
 Loose Leaf Paper Market | 2026-2036
Loose Leaf Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Loose Leaf Paper Market Analysis
North American integrated pulp-to-paper producers is broadening coated and specialty-grade output to serve premium loose leaf segments. Mead Products LLC leverages its long-standing brand equity and established distributor relationships across U.S. educational supply chains. Kokuyo Co., Ltd. anchors its competitive stance through precision manufacturing of graph and specialty formats for professional and technical users in East Asian markets. ACCO Brands Corporation sustains broad SKU coverage across ruled formats, competing through scale advantages in private-label and branded stationery.
Loose leaf paper denotes unbound sheets, typically manufactured in basis weights between 16 lb and 24 lb, with punched margins designed for ring binders or disc-bound systems; its primary commercial purpose centers on flexible, reconfigurable documentation across educational, professional, and creative workflows. College Ruled product types command the largest volume share due to standardized adoption in secondary and post-secondary institutions, while Graph formats generate disproportionate margin contribution from engineering and design professionals. Recycled material grades are gaining structural share as institutional procurement policies embed environmental criteria, though Virgin stock retains preference for high-ink applications where bleed-through resistance matters.
The EPA oversees emissions and effluent standards affecting U.S. mill operations, while the EU Timber Regulation and FSC chain-of-custody certification constrain fiber sourcing across European supply chains. China's GB standards and SAMR labeling requirements shape export compliance for Asian manufacturers supplying international markets. Stakeholders must monitor evolving extended producer responsibility frameworks and institutional purchasing mandates, as these mechanisms increasingly determine market access and contract eligibility across key demand clusters.
Market Dynamics
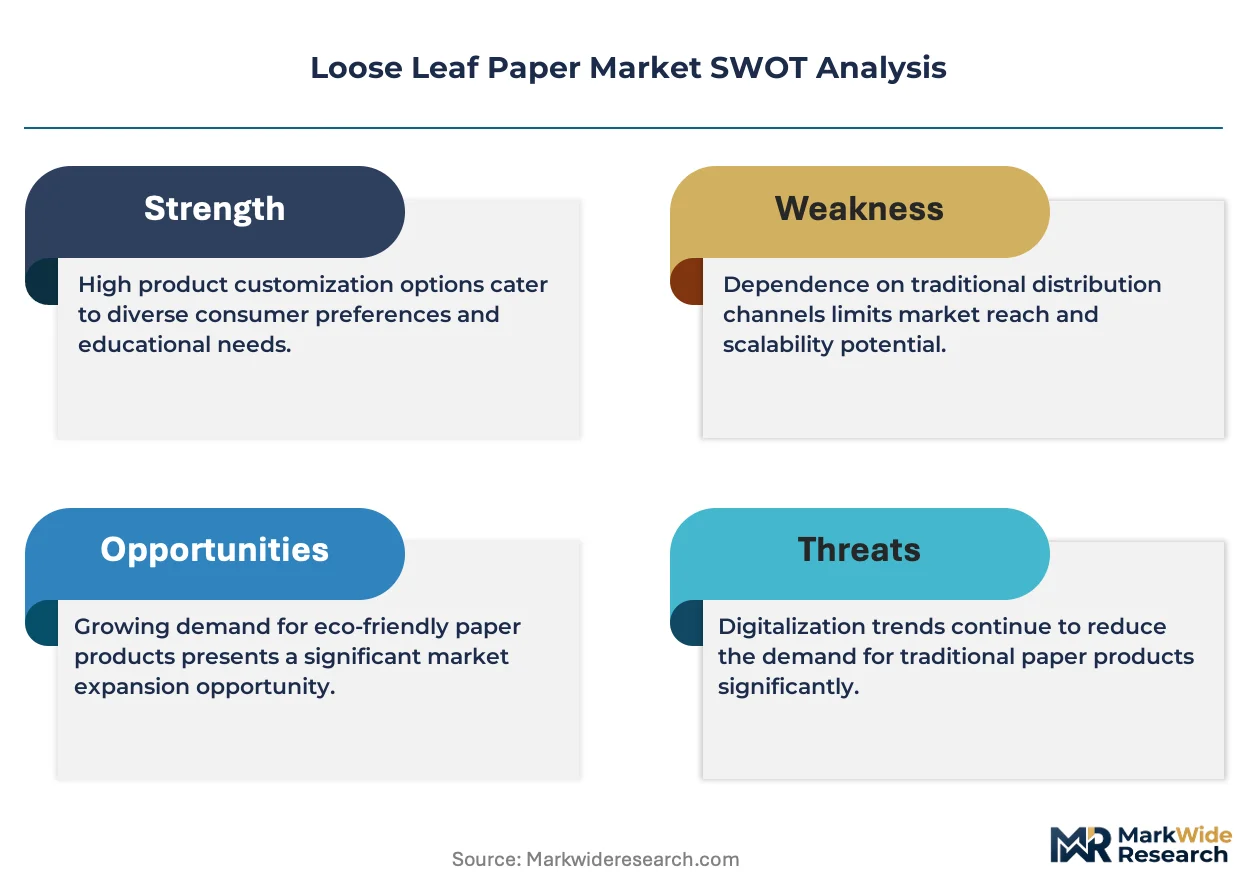
Institutional procurement mandates and certified fiber sourcing requirements are compressing margins for non-compliant mills while rewarding integrated producers with chain-of-custody credentials across U.S. and European educational supply chains.
Growth Catalysts
- FSC Chain-of-Custody Certification:European Union Timber Regulation enforcement is redirecting mill investment toward certified virgin and recycled fiber streams, unlocking contract eligibility with district-level purchasers.
- Back-to-School Seasonality:United States district bulk purchasing sustains volume throughput through predictable annual procurement cycles anchored in educational budgeting calendars.
- Recycled-Content Mandates:North American state-level environmental procurement policies are structurally elevating post-consumer waste grades in institutional tenders.
Market Restraints
- Pulp Cost Volatility:Hardwood and softwood fiber input prices fluctuate with weather-driven supply disruptions from Nordic and Canadian logging regions.
- Supply Concentration Risk:Integrated pulp-to-paper production clusters in the Southeastern United States create geographic vulnerability to hurricane-related downtime.
- Digital Substitution Pressure:Tablet and stylus-based note-taking platforms erode replacement demand among post-secondary students and professional users.
Strategic Opportunities
- Specialty Format Expansion:Engineering and design professionals in Germany and Japan generate disproportionate margin contribution for precision-manufactured graph and isometric sheet formats.
- Disc-Bound System Convergence:Hybrid binding technologies combining ring binder compatibility with lay-flat notebook mechanics are opening premium positioning in creative workflows.
- Extended Producer Responsibility Frameworks:Emerging EU-wide packaging and paper waste regulations will advantage producers with established take-back infrastructure.
Industry Challenges
- Retrofitting Legacy Equipment:Converting coated paper machines to uncoated freesheet production for loose leaf grades demands capital outlays that strain mid-cap mill balance sheets.
- Cross-Border Certification Complexity:Simultaneous compliance with EPA effluent standards, EU Timber Regulation, and China's GB labeling requirements fragments quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loose Leaf Paper Market |
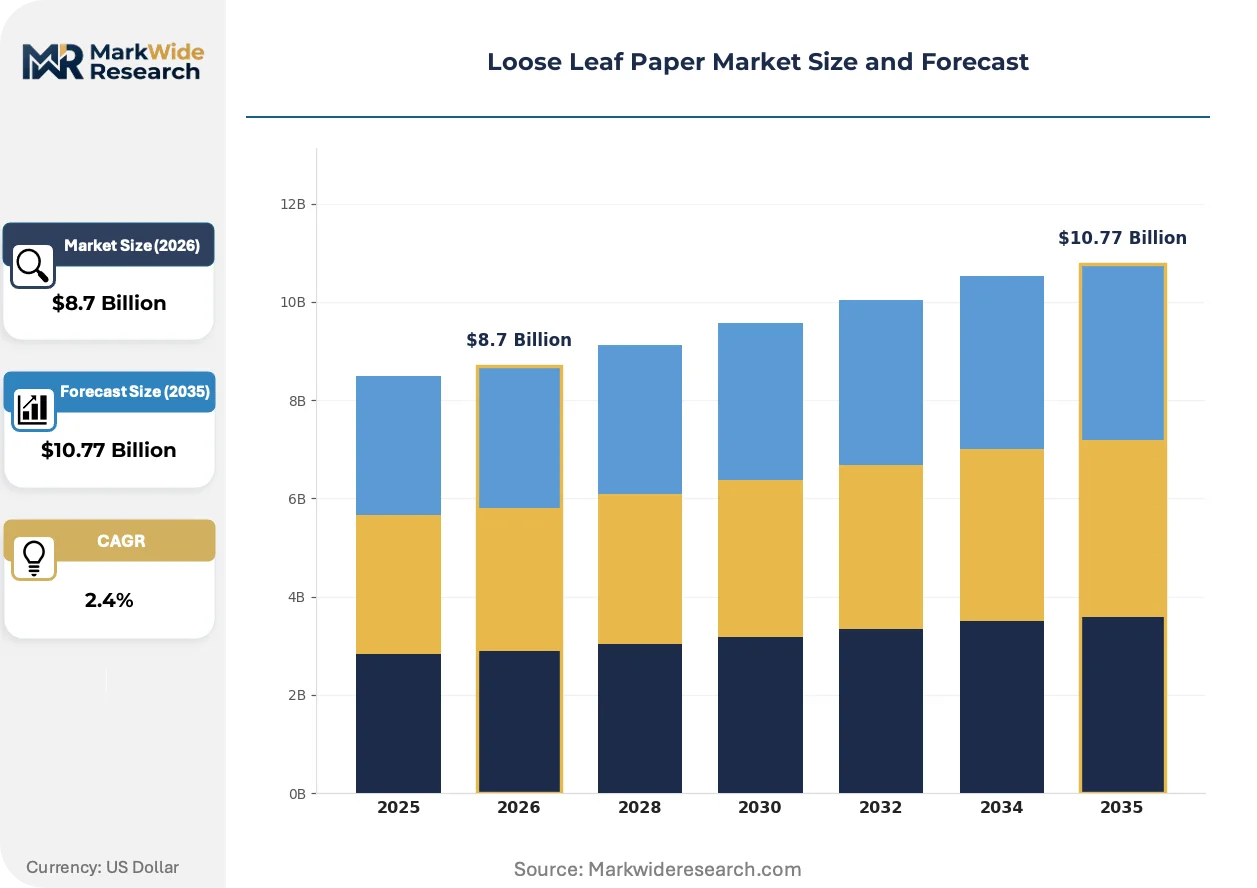
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $10.77 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: College Ruled, Wide Ruled, Graph, Blank End User: Students, Professionals, Artists, Schools Material: Recycled, Virgin, Specialty, Coated Distribution Channel: Online Retail, Supermarkets, Stationery Stores, Wholesale |
| Companies Covered | Staples, Inc., Roaring Spring Paper Products, ACCO Brands Corporation, Diamond Stationery Products, Bazic Products, Kokuyo Co., Ltd., Mead Products LLC, Esselte, Exacompta Clairefontaine S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loose Leaf Paper Market Emerging Trajectories
Sheet format standardization and binding system interoperability are reshaping how educational and professional users configure documentation workflows, compressing SKU proliferation while elevating premium specialty grades.
Disc-bound binding hardware is modularizing loose leaf consumption patterns by enabling users to remove, rearrange, and reinsert individual sheets without tearing or punching damage. Architecture and design studios in the United States and United Kingdom are adopting these systems at accelerating rates for project documentation portfolios. This format flexibility is modularizing the traditional notebook market by separating paper purchasing from binding hardware decisions.
EU Green Deal implementation is tightening carbon accounting requirements for paper products sold into European educational and government procurement channels. Industrial consequence falls heaviest on Asian exporters lacking verified supply chain emissions data. German and French institutional buyers are responding by privileging mills with ISO 14001 certification and Science Based Targets initiative commitments.
District-level cooperative purchasing alliances are consolidating buying power across U.S. state boundaries, compressing vendor counts and lengthening contract durations. Educational supply distributors face margin pressure as these alliances negotiate direct mill relationships. This concentration is most visible in Texas, California, and Florida, where statewide purchasing cooperatives now handle majority volume for K-12 loose leaf procurement.
Loose Leaf Paper Market Segmentation
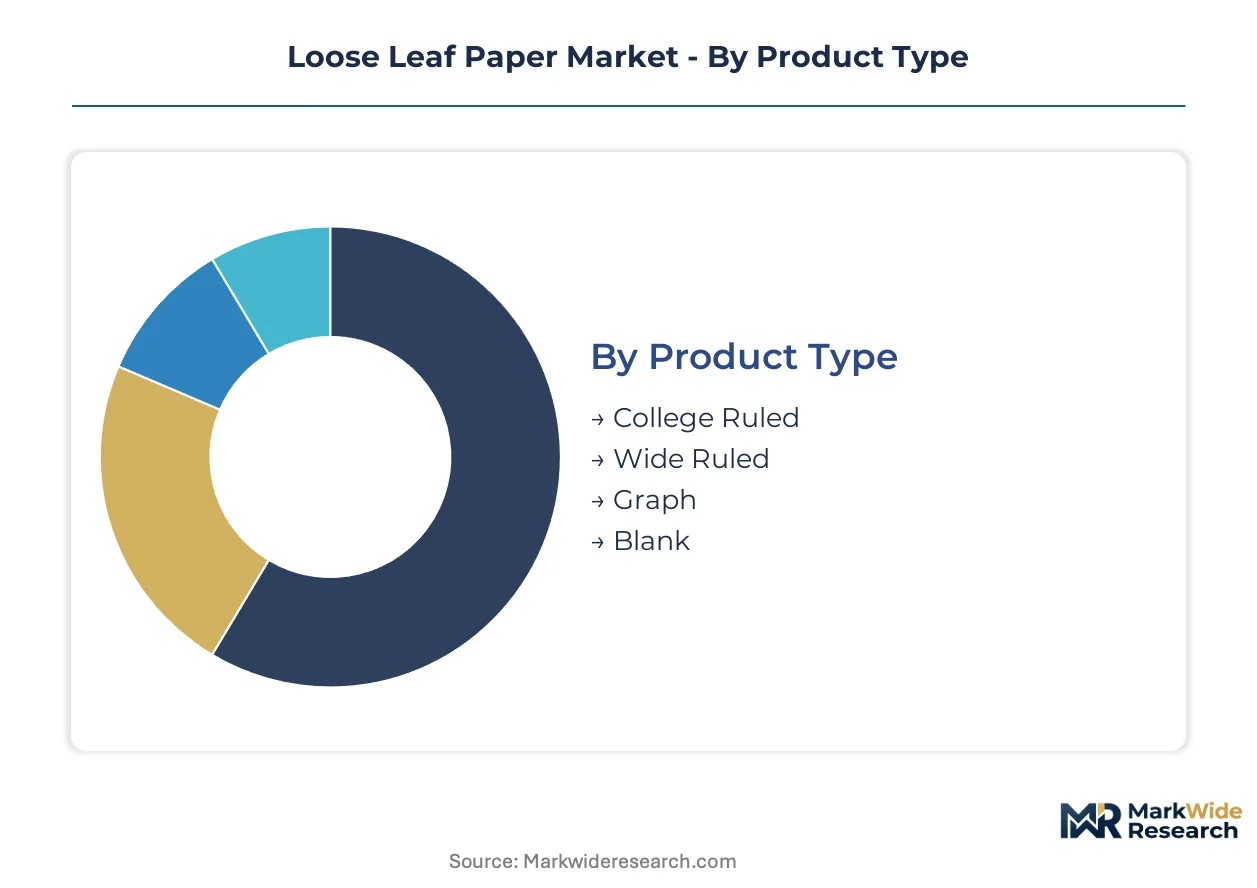
Loose leaf paper demand fragments across incompatible use cases requiring divergent sheet specifications, fiber grades, and margin structures. Procurement patterns in educational supply chains diverge sharply from technical and creative workflows, forcing producers to maintain parallel product architectures.
Product Type:
Line spacing and ruling geometry determine ink behavior, page yield per ream, and compatibility with standardized educational assessments.
- College Ruled:Narrow 7.1mm line spacing maximizes character density per page for dense note-taking in post-secondary lecture environments. United States secondary institutions specify this format for standardized testing preparation, locking in annual district-level procurement volumes that sustain baseline mill throughput.
- Graph:Precision-printed grid patterns at 5mm or 10mm intervals enable scaled technical drawings and mathematical plotting. Engineering consultancies in Germany and Japan specify ISO-grade graph paper with calibrated grid accuracy, generating premium pricing tolerance unavailable in commodity ruled formats.
- Wide Ruled:8.7mm spacing accommodates larger handwriting development in primary education settings. Early-grade handwriting curricula in Texas and Florida specify this format exclusively.
- Blank:Unruled sheets serve sketching, diagramming, and creative workflows where line constraints impede visual ideation. Architecture studios and industrial design firms specify heavier basis weights for marker and ink wash compatibility.
College Ruled leads on scale; Graph leads on momentum.
End User:
Volume concentration and purchasing authority diverge sharply between institutional buyers and individual consumers.
- Schools:District-level cooperative purchasing alliances aggregate demand across hundreds of individual buildings, negotiating direct mill relationships that bypass traditional distributor markups. California and Texas statewide cooperatives now handle majority K-12 loose leaf procurement.
- Students:Individual back-to-school purchasing concentrates in late summer retail windows, with brand loyalty shaped by prior institutional exposure and shelf placement proximity to binding accessories.
- Professionals:Engineering and legal workflows generate demand for archival-quality sheets with cotton fiber content and acid-free specifications for document longevity compliance.
- Artists:Specialized surface treatments including vellum finish and tooth texture command material premiums for dry media and light wash applications.
Schools concentrate procurement volume; Professionals expand most quickly.
Material:
Fiber sourcing and manufacturing process determine opacity, bleed resistance, and compliance eligibility for institutional tenders.
- Virgin:Long-fiber softwood pulp delivers superior tensile strength and ink holdout for high-density laser printing and fountain pen applications. EPA effluent standards constrain domestic mill production economics.
- Recycled:Post-consumer waste fiber streams satisfy North American state-level environmental procurement mandates, though shorter fiber length reduces sheet durability in high-handling workflows.
- Specialty:Cotton rag, linen, and synthetic fiber blends serve archival and technical documentation with century-scale stability requirements.
- Coated:Surface sizing and clay coatings enhance ink crispness for premium presentation and photographic reproduction applications.
Virgin dominates current institutional specification; Recycled gains share fastest.
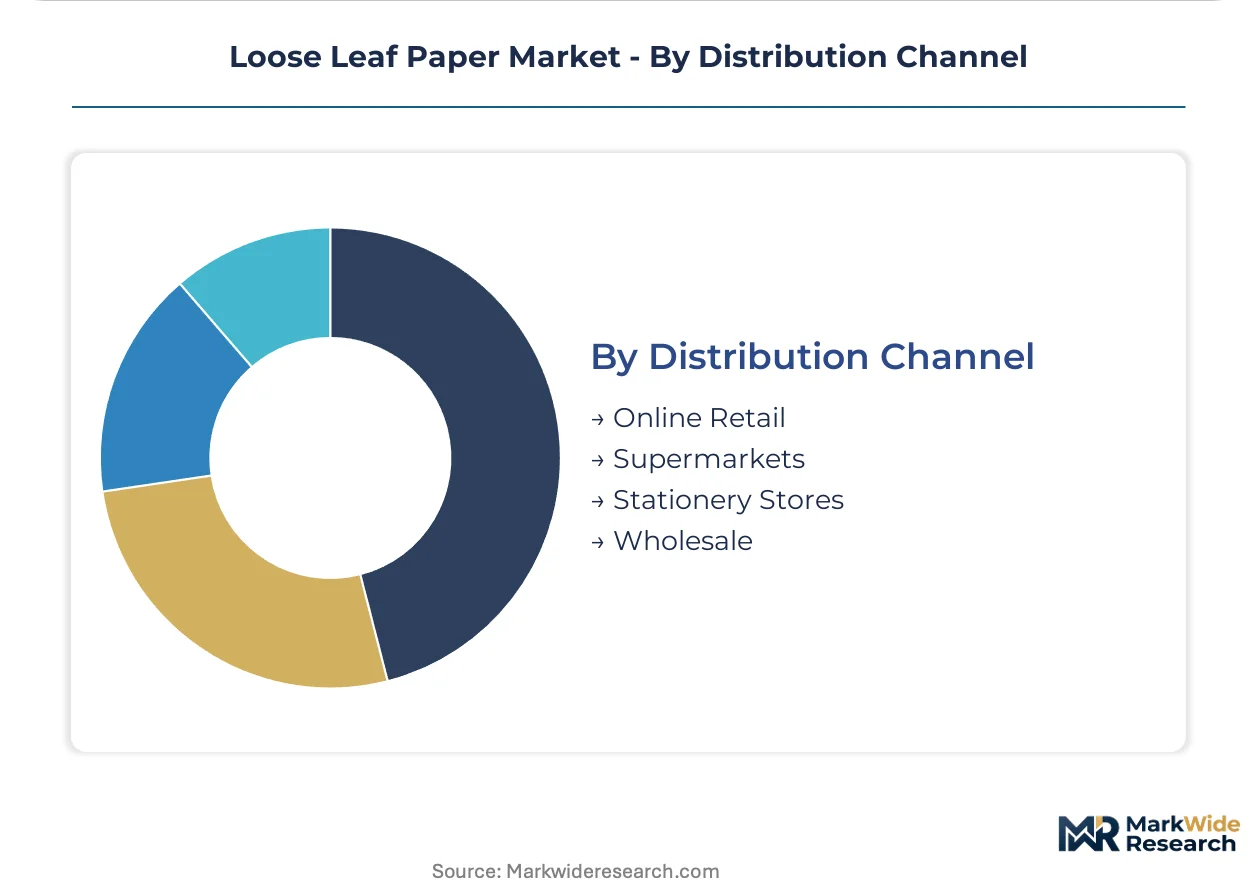
Distribution Channel:
Channel selection determines margin capture, inventory risk allocation, and access to procurement decision-makers.
- Wholesale:Educational supply distributors maintain established relationships with district purchasing officers, handling logistics aggregation across fragmented school building delivery requirements.
- Online Retail:Direct-to-consumer platforms enable specialty format access for dispersed professional and creative users outside major metropolitan supply footprints.
- Supermarkets:Seasonal back-to-school aisle placement captures impulse purchasing from household shoppers during concentrated August-September demand windows.
- Stationery Stores:Curated assortments and knowledgeable staff serve premium segment buyers seeking paper weight, finish, and ruling guidance unavailable in mass retail environments.
Wholesale anchors institutional volume; Online Retail climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States educational procurement volumes outpace Japanese technical-grade demand by an order of magnitude, yet German engineering specifications command pricing multiples unavailable in commodity ruled formats.
United States
District-level cooperative purchasing alliances in Texas, California, and Florida aggregate K-12 demand into direct mill contracts that bypass traditional distributor markups. EPA effluent standards constrain domestic production economics while privileging integrated pulp-to-paper operators with compliance infrastructure. The Southeast production corridor faces recurring hurricane-related downtime risks that disrupt supply continuity for institutional buyers.
Germany
Engineering consultancies and technical universities sustain premium demand for ISO-grade graph paper with calibrated grid accuracy. EU Timber Regulation enforcement redirects mill investment toward FSC-certified fiber streams, locking contract eligibility with government procurement channels. The Baden-Württemberg industrial cluster hosts precision manufacturing operations serving architectural and mechanical design workflows.
Japan
Professional and technical users in East Asian markets drive disproportionate margin contribution through specialty format requirements. METI industrial standards shape quality specifications for domestic consumption and regional export compliance. The Kansai manufacturing corridor concentrates precision paper finishing capabilities for professional documentation applications.
China
Export-oriented manufacturers supply international markets under GB standards and SAMR labeling requirements that fragment quality assurance resources. Domestic educational demand remains price-sensitive, constraining premium positioning opportunities for specialty grades. The Yangtze River Delta hosts integrated production capacity serving both domestic distribution and overseas contract manufacturing.
France
Government and educational procurement channels privilege mills with ISO 14001 certification and Science Based Targets initiative commitments under tightening EU Green Deal carbon accounting requirements. The Île-de-France region concentrates institutional purchasing decision-making for nationwide supply contracts. Clairefontaine's historical manufacturing base anchors premium positioning in archival and creative paper segments.
Loose Leaf Paper Market Vendor Landscape
North American integrated producers anchor the scale-driven tier; Japanese specialists hold premium positioning through precision manufacturing capabilities. The vendor base separates into three strategic archetypes: pulp-integrated giants with district-level contract access, format specialists commanding technical-grade premiums, and private-label operators competing on procurement efficiency. Capacity consolidation and certified fiber sourcing investments constitute the dominant competitive moves reshaping supplier eligibility.
Within the integrated producer tier, ACCO Brands Corporation and Mead Products LLC represent scale-driven positioning across U.S. educational supply chains, while Kokuyo Co., Ltd. exemplifies the precision-specialist archetype serving professional technical workflows. These three entities occupy distinct competitive vectors—ACCO through SKU breadth, Mead through distributor relationship depth, and Kokuyo through manufacturing precision—without direct confrontation in identical bid situations.
| Leading Market Players |
|---|
| Staples, Inc. |
| Roaring Spring Paper Products |
| ACCO Brands Corporation |
| Diamond Stationery Products |
| Bazic Products |
| Kokuyo Co., Ltd. |
| Mead Products LLC |
| Esselte |
| Exacompta Clairefontaine S.A. |
| Others |
Supply Flow & Price Mechanics
FSC chain-of-custody certification gates both qualified supply and premium-tier pricing access in the loose leaf paper market, as European Union Timber Regulation enforcement and North American recycled-content mandates bifurcate the supplier base into compliant and excluded tiers. Mills lacking verified fiber sourcing credentials face contract ineligibility with district-level educational purchasers, while certified operators capture pricing premiums through institutional procurement channels.
Pricing Analysis
Capacity additions in the Southeastern United States are reshaping price floors for commodity-grade loose leaf paper as integrated pulp-to-paper producers expand uncoated freesheet output. Three-tier pricing structure across premium, standard, and economy levels stratifies by fiber certification grade and basis weight precision, with FSC-certified virgin stock commanding the highest tier and uncertified recycled grades facing the steepest price compression. Pricing pressure stems from pulp cost volatility driven by Nordic and Canadian logging disruptions. District cooperative purchasing alliances exhibit the lowest price sensitivity, while individual back-to-school retail purchasers show the highest.
Supply Chain Analysis
Chain-of-custody certification requirements fragment quality assurance resources across the loose leaf paper supply chain, privileging integrated producers with in-house compliance infrastructure. Manufacturing concentrates in the United States, Germany, and Japan, with each hub serving distinct demand archetypes—educational bulk procurement, technical-grade precision formats, and professional specialty applications respectively. Raw material dependencies center on softwood and hardwood pulp streams, with post-consumer waste fiber gaining structural share under environmental procurement mandates. Supply chain risk manifests as geographic concentration vulnerability to hurricane-related downtime in the Southeastern United States production corridor. Distribution runs through educational supply wholesalers for institutional volume, with online retail channels expanding fastest for specialty formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The loose leaf paper market represents a late-cycle quality story as institutional procurement policies embed environmental criteria that favor certified fiber streams and premium specifications over commodity alternatives.
For Market Incumbents: Hedge against digital substitution pressure by deepening precision manufacturing capabilities for graph and isometric formats serving German and Japanese engineering workflows. Accelerate FSC certification coverage across remaining virgin pulp sourcing to defend contract eligibility with consolidating district purchasing alliances in Texas, California, and Florida. Prioritize disc-bound system compatibility investments to capture premium positioning in creative professional segments. For New Entrants and Emerging Players: EU Green Deal implementation in France and Germany opens a window for carbon-accounting-transparent producers to penetrate government procurement channels previously closed to Asian exporters lacking verified emissions data. Target the online retail specialty format segment with ISO-grade graph paper calibrated for architectural and mechanical design applications. Pursue direct mill relationships with emerging cooperative purchasing alliances bypassing established distributor networks. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap mills with legacy coated paper equipment requiring capital-intensive conversion to uncoated freesheet production. Long-term viability hinges on securing chain-of-custody credentials and positioning for extended producer responsibility framework advantages as EU-wide packaging and paper waste regulations mature. Watch for Science Based Targets initiative commitment announcements as an inflection indicator for premium-tier contract access.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Certification Investment | Unlocks contract eligibility with district-level educational purchasers under EU Timber Regulation enforcement. |
| Disc-Bound System Compatibility | Captures premium positioning in United States and United Kingdom architecture studio workflows. |
| Recycled-Content Capacity Expansion | Satisfies North American state-level environmental procurement mandates elevating post-consumer waste grades. |
| Precision Graph Format Manufacturing | Generates disproportionate margin contribution from German engineering consultancies and Japanese technical users. |
| Direct Mill Alliance Formation | Bypasses distributor markups as Texas and California statewide cooperatives consolidate K-12 procurement volume. |
Methodological Framework
Direct dialogue with mill operations managers, educational supply distributors, district procurement officers, and sustainability compliance leads grounded the qualitative foundation of this analysis. Secondary validation drew from EPA effluent standard filings, EU Timber Regulation enforcement notices, FSC chain-of-custody certification databases, and state-level environmental procurement policy documents. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, material grade, and distribution channel dimensions.
Bottom-up segment analysis anchored the forecast framework, with demand projections built from district-level purchasing data, back-to-school seasonality patterns, and professional workflow penetration rates across the projection horizon. Modeled dimensions included ruling format, fiber certification tier, institutional versus individual purchasing authority, and wholesale versus retail channel mix. CAGRs derived from historical volume trajectories adjusted for regulatory inflection points and substitution elasticity parameters. Pulp cost indices and certified fiber availability curves served as key industry-specific forecast inputs.
Revisions become necessary when EU Green Deal carbon accounting requirements accelerate, extended producer responsibility frameworks expand geographic coverage, or hurricane-related production disruptions exceed historical frequency baselines. Forecasts reflect documented assumptions regarding institutional procurement policy continuity and fiber certification adoption curves. A model refresh is warranted upon material change in district cooperative purchasing alliance consolidation rates or Science Based Targets initiative participation thresholds among competing mills.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Paper Making Machine Market
Paper Products
NCR Laser Paper Market
Paper Products
White Line Chipboard Market
Paper Products
Europe and MENA Pulp Market
Paper Products
Duplex Paper and Board Market
Paper Products
Global Electrical Insulation Paper Market
Paper Products
North America Specialty Paper Market
Paper Products
Industrial Paper Shredder Machine Market
Paper Products
North America Decor Paper Market
Paper Products
Europe Coated Paper Market
Paper Products
Paper Dry Strength Agents Market
Paper Products
Speciality Pulp and Paper Chemicals Market
Paper Products
Functional and Barrier Coatings for Paper Market
Paper Products
Greaseproof Paper Market
Paper Products
Medium Density Fiberboard Market
Paper Products
Medical Grade Paper Market