
 Pulp Market | 2026-2036
Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Pulp Market Outlook
Aftermarket fiber recovery and recycling services is rewriting margin allocation across the pulp value chain. Suzano leverages its integrated eucalyptus plantation network to control raw material costs from seedling to finished pulp. International Paper sustains manufacturing scale across North American and Brazilian mill complexes. Stora Enso differentiates through bioproduct diversification, extracting lignin and tall oil alongside traditional pulp streams.
Pulp consists of cellulose fibers extracted from wood, agricultural residues, or recycled paper through mechanical, chemical, or hybrid processes, typically achieving 85-99% alpha-cellulose content depending on grade and intended end-use. Kraft-processed bleached softwood pulp dominates printing and writing paper applications due to superior fiber length and tensile strength. Specialty pulp segments command premium positioning in medical-grade absorbent products and food-contact applications where purity certifications exceed standard commodity specifications. Recycled pulping technology is expanding fastest in packaging feedstocks as brand owners mandate post-consumer content minimums.
The EPA enforces effluent limitation guidelines for pulp and paper mills under the Clean Water Act, while the EU Green Deal and F-Gas Regulation constrain energy-intensive chemical recovery processes. Brazil's environmental licensing framework through IBAMA and state-level agencies shapes plantation expansion timelines and mill siting decisions. Stakeholders must monitor how carbon border adjustment mechanisms and emerging biomaterials substitution affect long-term fiber demand trajectories.
Market Dynamics
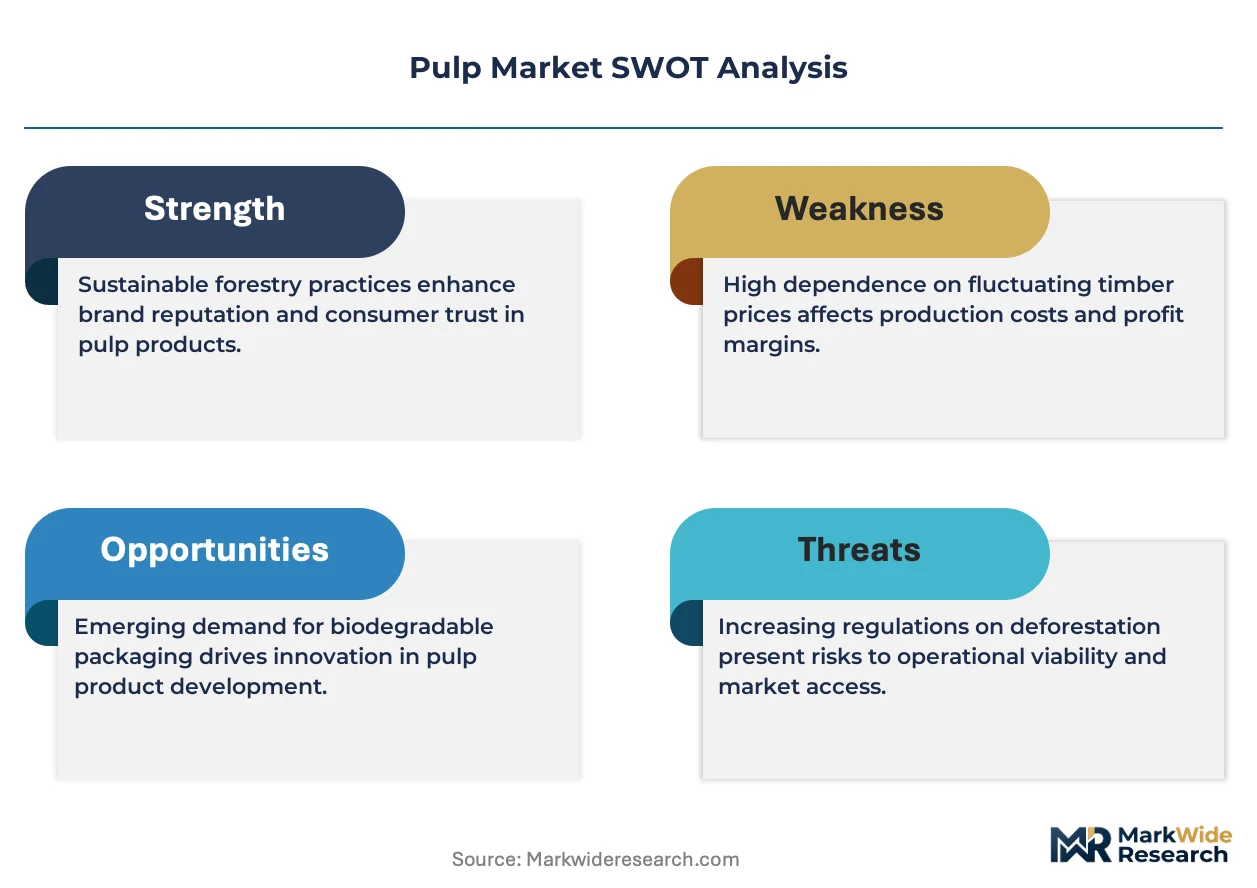
The EU Deforestation Regulation is compressing virgin fiber import timelines, forcing supply chain reconfiguration toward certified plantation sources while Brazil's eucalyptus plantation network absorbs displaced demand.
Growth Catalysts
- Packaging-grade hardwood pulp:E-commerce corrugated board producers are switching from recycled furnish to virgin hardwood for superior crush resistance in automated fulfillment centers.
- EU Deforestation Regulation:Mandatory geolocation traceability requirements are accelerating certified fiber premiums and rewarding compliant plantation operators.
- Fast-growing eucalyptus genetics:Brazilian breeding programs have shortened harvest cycles to seven years, compressing delivered fiber costs below temperate-zone softwood alternatives.
Market Restraints
- Energy cost volatility:Chemical recovery boilers in kraft mills consume 35-40% of operating expenditure; natural gas price spikes in Europe have idled marginal capacity.
- Single-hemisphere supply concentration:Brazil controls over 40% of seaborne hardwood pulp trade, creating freight rate leverage and currency exposure for Asian buyers.
- Textile fiber substitution:Man-made cellulosic producers are diverting dissolving pulp feedstock toward lyocell, tightening specialty pulp availability for traditional applications.
Strategic Opportunities
- India packaging conversion:Food-grade bleached bagasse pulp capacity expansion addresses domestic bans on single-use plastics and import substitution mandates.
- Lignin valorization:Biorefinery retrofits extract high-purity lignin for carbon fiber precursors and battery anodes, diversifying revenue beyond commodity pulp.
- Post-consumer fiber mandates:California's extended producer responsibility laws are creating guaranteed offtake agreements for recycled pulp mills at premium pricing tiers.
Industry Challenges
- Process control engineering talent:Kraft mill digitization requires expertise in model predictive control and digester automation that outpaces vocational pipeline output.
- Effluent treatment capex cycles:Zero liquid discharge compliance for Indian mills demands membrane bioreactor investments exceeding $50 million per installation.
- FSC chain-of-custody audit complexity:Multi-site certification across plantation, pulp mill, and paper converting stages extends compliance timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulp Market |
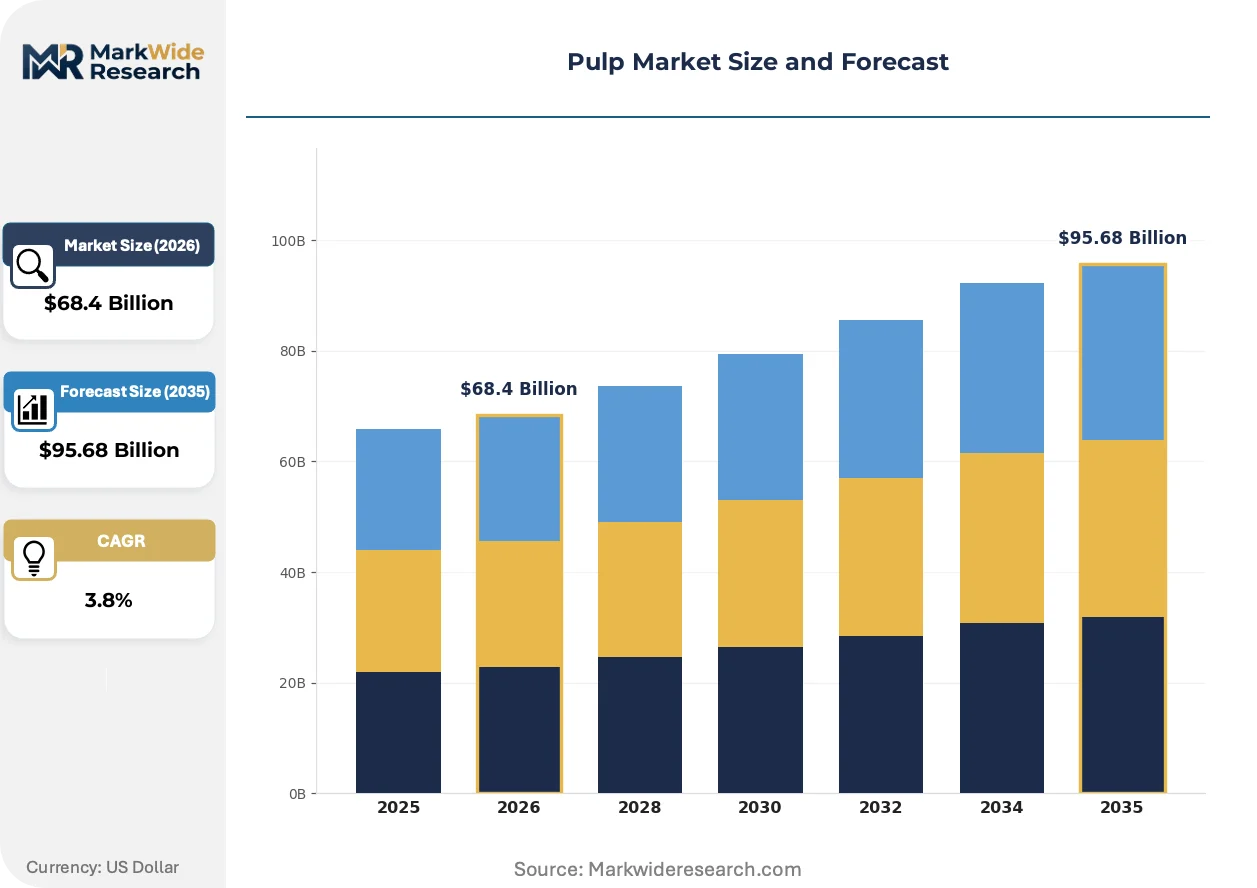
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $95.68 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bleached Softwood Pulp, Unbleached Softwood Pulp, Bleached Hardwood Pulp, Specialty Pulp End User: Packaging Industry, Printing Industry, Tissue Manufacturing, Writing Paper Producers Application: Food Packaging, Household Products, Industrial Applications, Medical Products Technology: Kraft Process, Sulfite Process, Recycled Pulping, Thermo-Mechanical Pulping |
| Companies Covered | International Paper, Suzano, Stora Enso, UPM, Oji Holdings, Nine Dragons Paper Holdings, Smurfit Westrock, Sappi Limited, Klabin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulp Market Strategic Shifts
Mechanical pulping technology is migrating from energy-intensive grinding toward thermomechanical processes, while regulatory traceability mandates and buyer sustainability scorecards are rewiring procurement specifications across the value chain.
Enzymatic bleaching sequences are migrating from elemental chlorine-free toward totally chlorine-free and ozone-based stages. Nordic mills have retrofitted existing lines to eliminate adsorbable organic halogen discharge. This migration from conventional chemistry is enabling closure of effluent treatment loops and access to premium tissue and food-contact markets previously blocked by chlorinated byproduct restrictions.
The EU Green Deal's F-Gas Regulation is phasing down hydrofluorocarbon use in lime kiln heat pumps and recovery boiler auxiliary systems. Mill operators are substituting ammonia absorption cycles and industrial heat pumps. Kraft pulp producers in Finland and Sweden face accelerated retrofit deadlines, compressing capital deployment windows through 2027.
Brand-owner sustainability scorecards are displacing spot-market purchasing for packaging feedstocks. Major beverage and personal care companies now mandate third-party certified fiber with mass-balance documentation. European corrugated converters are consolidating supplier panels to three approved pulp sources per grade, locking in volume commitments and compressing spot market liquidity for non-certified material.
Pulp Market Segmentation
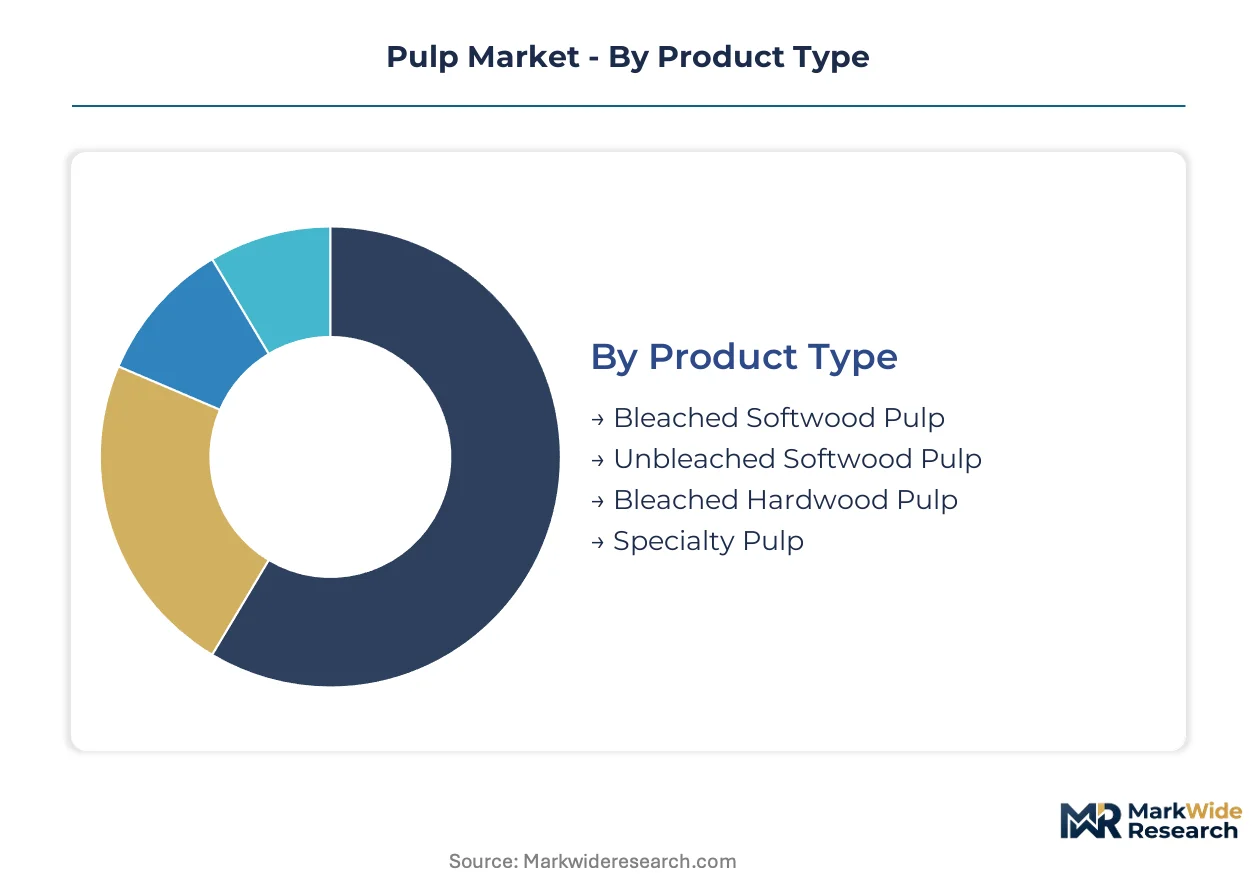
Pulp market segmentation reveals distinct performance tiers across fiber source, processing technology, and end-use specification. Manufacturers align capacity investments with grade-specific margin profiles and regulatory compliance requirements rather than treating pulp as a homogeneous commodity.
Product Type:
Mature commodity grades dominate volume flows, while emerging specialty segments capture disproportionate value through purity certifications and medical-grade specifications.
- Bleached Softwood Pulp:Long-fiber cellulose derived from coniferous species delivers superior tensile strength and tear resistance. Tissue and towel manufacturers in North American and Nordic markets specify this grade for premium absorbency applications where fiber integrity under wet stress determines product performance.
- Bleached Hardwood Pulp:Short-fiber eucalyptus and birch pulps provide smooth surface formation and excellent printability. E-commerce corrugated board producers across Asia-Pacific markets are substituting recycled furnish with virgin hardwood to achieve automated fulfillment center crush resistance standards.
- Unbleached Softwood Pulp:Retains lignin content for natural brown coloration and structural rigidity in linerboard and sack paper applications.
- Specialty Pulp:Ultra-high alpha-cellulose grades command stringent purity protocols for medical gauze, pharmaceutical filtration, and food-contact absorbent products.
Bleached softwood pulp retains volume leadership; specialty pulp holds the steepest expansion curve through medical and food-contact certification premiums.
End User:
Cost tier differentiation separates commodity packaging converters from premium tissue and specialty paper producers.
- Packaging Industry:Corrugated containerboard and folding carton manufacturers constitute the largest demand sink. Brazilian eucalyptus pulp integration supports cost-competitive boxboard production for Latin American export markets facing EU Deforestation Regulation compliance deadlines.
- Tissue Manufacturing:Premium bathroom tissue and facial towel producers specify low-contaminant bleached grades. North American integrated tissue-pulp operators leverage kraft mill chemical recovery systems to stabilize energy input costs against volatile natural gas benchmarks.
- Printing Industry:Magazine and catalog paper producers balance opacity requirements with postal weight restrictions.
- Writing Paper Producers:Fine paper mills targeting corporate stationery and premium notebooks demand superior formation uniformity.
Packaging industry consumption anchors absolute tonnage; tissue manufacturing delivers the most resilient pricing through brand-owner premium positioning.
Application:
Volume concentration favors high-throughput packaging segments, while margin accretion concentrates in regulated medical and food-contact categories.
- Food Packaging:Grease-resistant board and liquid packaging board require controlled extractives content. Indian bagasse pulp expansion targets domestic single-use plastic substitution mandates with bleached agricultural fiber capacity.
- Medical Products:Absorbent cotton, surgical gowns, and pharmaceutical-grade filters demand bioburden-controlled manufacturing environments. FDA and EMA device regulations enforce gamma-sterilization compatibility and endotoxin limits that exclude standard commodity pulp streams.
- Household Products:Disposable wipes and absorbent towels balance softness against wet strength through controlled fiber blending.
- Industrial Applications:Filter media, electrical insulation paper, and specialty composites utilize high-purity dissolving pulp derivatives.
Food packaging commands the widest volume base; medical products sustain the highest purity premiums and certification barriers.
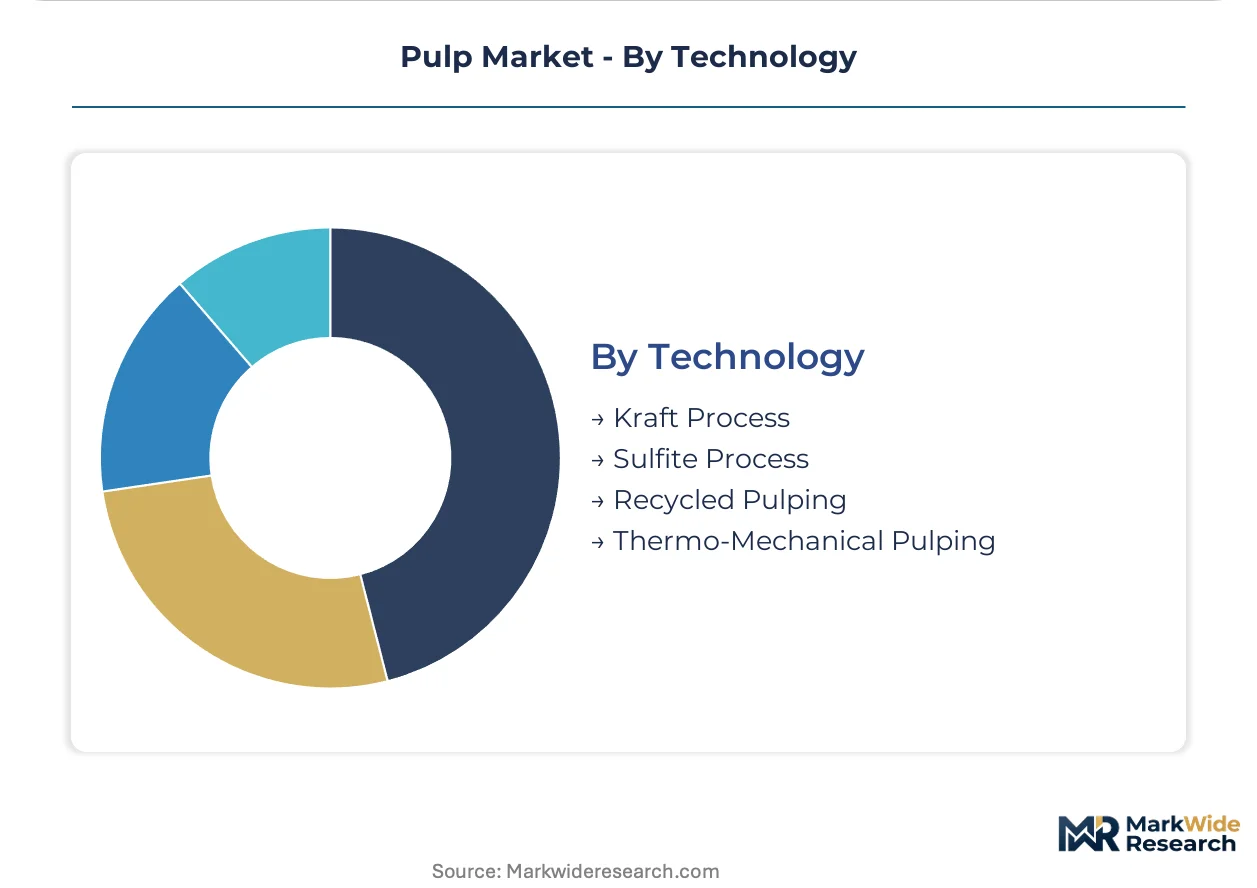
Technology:
Supply concentration clusters around kraft process dominance, with emerging thermo-mechanical and recycled streams reshaping environmental compliance economics.
- Kraft Process:Sulfate-based chemical pulping achieves highest cellulose preservation with recoverable lignin and tall oil byproducts. Finnish and Swedish mills face EU F-Gas Regulation deadlines for lime kiln heat pump retrofits through 2027, compressing capital deployment windows.
- Recycled Pulping:Post-consumer fiber recovery eliminates virgin wood dependency. California extended producer responsibility legislation creates guaranteed offtake agreements at premium pricing tiers for compliant deinking operations.
- Sulfite Process:Acid-based chemistry produces dissolving pulp for textile viscose and specialty cellulose derivatives.
- Thermo-Mechanical Pulping:Refiner mechanical action at elevated temperature reduces specific energy consumption versus stone grinding methods.
Kraft process capacity retains operational scale leadership; recycled pulping climbs the fastest through brand-owner post-consumer content mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: Brazilian mills feed eucalyptus pulp into export corrugated board, while Nordic producers extract bioproducts alongside kraft streams, and Indian bagasse operations target domestic plastic substitution mandates.
Brazil
Eucalyptus plantation networks in São Paulo and Minas Gerais deliver cost-competitive hardwood pulp to Asian packaging converters. IBAMA environmental licensing shapes mill siting timelines and expansion permits. The São Paulo state cluster hosts integrated pulp-to-board operations serving EU Deforestation Regulation-compliant export channels.
United States
Southeastern tissue and towel manufacturers specify low-contaminant bleached grades for premium absorbency applications. EPA effluent limitation guidelines under the Clean Water Act govern kraft mill discharge standards. The Pacific Northwest retains softwood pulp capacity serving specialty paper and export dissolving pulp markets.
Finland
Nordic biorefinery operators extract lignin and tall oil alongside traditional pulp production. EU F-Gas Regulation deadlines through 2027 compress capital deployment windows for lime kiln heat pump retrofits. The Kemi-Tornio industrial corridor hosts integrated chemical recovery systems stabilizing energy input costs.
China
Packaging converters blend imported hardwood pulp with domestic recycled furnish for e-commerce corrugated applications. MEE environmental standards constrain effluent discharge from deinking operations. The Yangtze River Delta concentration of board mills sources seaborne pulp through Shanghai and Ningbo port terminals.
India
Food-grade bleached bagasse pulp capacity expansion addresses domestic single-use plastic bans and import substitution mandates. State pollution control boards enforce zero liquid discharge compliance for agricultural fiber mills. Maharashtra and Gujarat host integrated sugar-to-pulp operations leveraging cane waste streams.
Pulp Market Competitive Environment
Capability concentration sits with plantation-integrated operators controlling fiber genetics and harvest cycles; scale advantage sits with multi-hemisphere mill networks balancing freight optimization against currency exposure. The vendor base stratifies across three archetypes: captive plantation operators, merchant market specialists, and integrated paperboard producers. Dominant competitive moves include biorefinery retrofits for lignin valorization and FSC chain-of-custody certification investments securing brand-owner offtake agreements.
Among Brazilian plantation-integrated operators, Suzano exemplifies upstream control over eucalyptus genetics from seedling through finished pulp. International Paper anchors multi-regional manufacturing scale across North American and Brazilian mill complexes. Stora Enso occupies a position within the Nordic biorefinery tier, extracting high-value bioproducts alongside commodity pulp streams.
| Leading Market Players |
|---|
| International Paper |
| Suzano |
| Stora Enso |
| UPM |
| Oji Holdings |
| Nine Dragons Paper Holdings |
| Smurfit Westrock |
| Sappi Limited |
| Klabin |
| Others |
Value Chain & Pricing Dynamics
Single-hemisphere supply concentration in Brazilian eucalyptus pulp creates freight rate leverage that compresses pricing tier spreads between certified and non-certified grades while simultaneously reshaping procurement geography toward Atlantic-facing ports. The EU Deforestation Regulation's geolocation traceability mandates are accelerating premium differentiation for compliant plantation operators, forcing Asian buyers to absorb currency exposure and logistics redundancy costs.
Pricing Analysis
Long-term offtake contracts dominate volume flows between Brazilian plantation-integrated producers and Asian corrugated board manufacturers, locking in quarterly price adjustments indexed to energy benchmarks and freight indices. Spot market liquidity concentrates in non-certified hardwood grades where price differentiation hinges on FSC chain-of-custody certification status and delivered fiber consistency metrics. Pricing pressure stems from energy cost volatility in European kraft mill operations, where natural gas spikes have idled marginal capacity and redirected spot demand toward Brazilian supply. Commodity packaging converters exhibit highest price sensitivity, while medical-grade specialty pulp buyers absorb certification premiums with limited volume elasticity.
Supply Chain Analysis
Tariff exposure between Brazil and Asian importing nations dominates supply chain risk calculus, compounded by currency volatility in Real-denominated export contracts. Raw material dependencies center on fast-growing eucalyptus genetics, sulfur and caustic soda chemical inputs, and lime kiln refractory maintenance cycles. Distribution runs through São Paulo state mill clusters feeding Santos port terminals, with secondary consolidation at Shanghai and Ningbo for Yangtze River Delta board mill consumption. Single-source vulnerability concentrates in seaborne hardwood pulp trade where Brazilian operators control over forty percent of export volume, creating leverage over Asian corrugated producers lacking alternative temperate-zone fiber economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pulp market sits at a regulatory inflection where EU Deforestation Regulation compliance deadlines are compressing procurement timelines and rewarding upstream plantation control, creating asymmetric advantage for operators with certified fiber traceability from seedling through finished pulp.
For Market Incumbents: Entrench position through biorefinery retrofits extracting lignin and tall oil alongside commodity pulp streams, diversifying revenue beyond cyclical packaging demand. Accelerate FSC chain-of-custody certification investments across multi-site plantation and mill operations to secure brand-owner offtake agreements before compliance deadlines eliminate non-certified spot market access. Prioritize backward integration into eucalyptus genetics programs to compress harvest cycles below temperate-zone competition. For New Entrants and Emerging Players: Pursue white-space opportunities in Indian food-grade bleached bagasse pulp capacity, where domestic single-use plastic bans and import substitution mandates create guaranteed demand anchors. Target Maharashtra and Gujarat sugar-to-pulp operations leveraging existing cane waste streams and state pollution control board licensing frameworks. Establish direct supply relationships with food packaging converters facing extended producer responsibility compliance requirements. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors plantation-integrated operators with multi-hemisphere mill networks balancing freight optimization against currency exposure. Long-term viability across the five-to-ten year window hinges on bioproduct diversification and carbon border adjustment preparedness. Acquisition target archetypes include Nordic biorefinery operators with lignin valorization capabilities and Brazilian eucalyptus plantation networks with IBAMA-compliant expansion permits. Monitor EU F-Gas Regulation retrofit deadlines as inflection indicator for European kraft mill capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Biorefinery Retrofit for Lignin Extraction | Finnish and Swedish mills access carbon fiber precursor markets through high-purity lignin streams. |
| FSC Chain-of-Custody Certification Investment | Multi-site audit completion secures beverage and personal care brand-owner volume commitments. |
| Eucalyptus Genetics Program Expansion | Brazilian breeding programs compress harvest cycles to seven years, undercutting temperate-zone delivered costs. |
| Zero Liquid Discharge Compliance Installation | Indian bagasse mills meet state pollution control board mandates through membrane bioreactor investments. |
| Long-term Offtake Agreement with E-commerce Corrugated Producers | Asian packaging converters lock in virgin hardwood supply for automated fulfillment center crush resistance standards. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of trade customs data, mill capacity registries, and environmental licensing disclosures through IBAMA and state-level Brazilian agencies. Primary interviews engaged pulp procurement directors at Asian corrugated converters, kraft mill operations managers in Finland and Sweden, and agricultural fiber processing executives in Maharashtra and Gujarat. Secondary validation drew from SEC 10-K filings of listed paperboard producers, EU Timber Regulation enforcement databases, and FSC certification audit summaries. Bottom-up capacity modeling triangulated against top-down trade flow analysis across the analysis window.
Forecast inputs incorporate grade-specific demand elasticity, energy cost pass-through coefficients, and regulatory compliance timeline acceleration. Segmentation dimensions span fiber source, processing technology, end-use specification, and regional production hub. CAGRs derive from volume trajectory modeling against macroeconomic consumption drivers and substitution elasticity parameters. Industry-specific inputs include eucalyptus plantation harvest cycle compression rates and EU carbon border adjustment mechanism implementation phasing.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-backed Chinese pulp producers or accelerated textile fiber substitution toward lyocell would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Organic Tissue Paper Market
Paper Products
Unbleached Kraft Pulp Market
Paper Products
Medical Grade Paper Market
Paper Products
Office Printing Papers Market
Paper Products
Veneer Sheets Market
Paper Products
Unbleached Hardwood Kraft Pulp Market
Paper Products
Global Kraft Paper Market
Paper Products
Global Pulp and Paper Machinery Market
Paper Products
Household Paper Market
Paper Products
Global Direct Thermal Ticket Paper Market
Paper Products
Carbonless Paper Market
Paper Products
Europe Tissue and Hygiene Paper Market
Paper Products
Decorative Plastic and Paper Laminates Market
Paper Products
Pp Synthetic Paper Market
Paper Products
Leatheroid Paper Market
Paper Products
Global Carpet Backing Material Market