
 Inkjet Papers and Films Market | 2026-2036
Inkjet Papers and Films Market Size, Share, and Industry Trends Forecast 2026-2036
Inkjet Papers and Films Market Foresight
Market Context
Buyer concentration among commercial print service providers is pivoting toward mid-sized digital shops that lack legacy offset infrastructure. Stora Enso leverages its integrated pulp-to-paper operations to secure cost advantages in coated substrates. Fujifilm dominates inkjet-receptive film formulations through sustained R&D investment in proprietary polymer layers. Sappi competes aggressively in North American fine-art segments where archival certification commands premium positioning.
Technical Definition and Structural Segments
Inkjet papers and films comprise engineered substrates with controlled porosity, surface chemistry, and caliper optimized for aqueous or solvent-based droplet absorption without feathering or coalescence. These materials serve commercial reproduction, photographic output, and variable-data packaging where image fidelity and drying speed determine operational throughput. Coated papers occupy the largest value pool due to universal compatibility across piezoelectric and thermal inkjet heads, while synthetic papers represent the fastest-expanding category as moisture-resistant labels and durable tags displace laminated alternatives. Films retain concentrated margins in photography and backlit display applications where optical clarity and dimensional stability justify unit premiums over paper stocks.
Regulatory Frame and Outlook
EPA rules under the Toxic Substances Control Act constrain solvent-based coating chemistries, while REACH registration requirements in Europe mandate disclosure of fluorinated additives used in stain-resistant synthetic papers. Japan's Ministry of Economy, Trade and Industry (METI) enforces JIS standards for recycled content claims that influence procurement by corporate print buyers. Stakeholders must monitor tightening per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as reformulation timelines for coating binders will determine which substrate suppliers retain access to regulated end markets.
Market Dynamics
Commercial print service providers are abandoning legacy offset infrastructure for digital short-run workflows, compressing substrate procurement cycles and forcing coating suppliers to reformulate for instant-drying aqueous chemistries.
Growth Catalysts
- Short-run packaging proliferation:E-commerce fulfillment centers in China and Germany now specify inkjet-compatible corrugated liners for variable-data cartons, eliminating pre-print plate costs.
- REACH fluorinated additive phase-out:European converters are accelerating migration to bio-based coating binders ahead of 2025 registration deadlines, opening formulation partnerships with specialty chemical suppliers.
- Piezoelectric head resolution advances:2400 dpi industrial printheads from Japanese equipment manufacturers now demand micro-porous coated papers with sub-micron surface roughness, upgrading specification thresholds across photo reproduction studios.
Market Restraints
- Pulp cost volatility:Northern bleached softwood kraft pulp prices fluctuate with Swedish and Finnish mill operating rates, squeezing margin predictability for coated paper specialists lacking long-term fiber contracts.
- Concentrated polymer supply:Inkjet-receptive layer formulations depend on acrylic emulsions manufactured at three German chemical complexes, creating single-source vulnerability for synthetic paper producers.
- Offset residual capacity:Commercial print shops in Italy and Spain retain depreciated Heidelberg presses, delaying full digital conversion and substrate specification upgrades.
Strategic Opportunities
- Indian packaging conversion:Mumbai and Ahmedabad flexographic converters are piloting aqueous inkjet for pharmaceutical leaflets, bypassing solvent-based regulatory constraints from India's Central Pollution Control Board.
- US IRA clean manufacturing credits:Coating facilities sourcing renewable energy for thermal drying processes qualify for production tax credits, subsidizing capital deployment in recycled-content substrate lines.
- RFID-integrated synthetic papers:Convergence of thermal transfer printing with UHF inlay embedding is creating durable smart label substrates for automotive parts traceability in South Korean assembly plants.
Industry Challenges
- Coating chemist scarcity:Formulation expertise in fluorine-free stain resistance resides with retiring specialists at Finnish and Japanese pulp mills, complicating REACH-compliant product pipeline execution.
- Archival certification timelines:ISO 18916 lightfastness testing requires 12-month exposure protocols, delaying premium fine-art paper launches and locking working capital in inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inkjet Papers and Films Market |
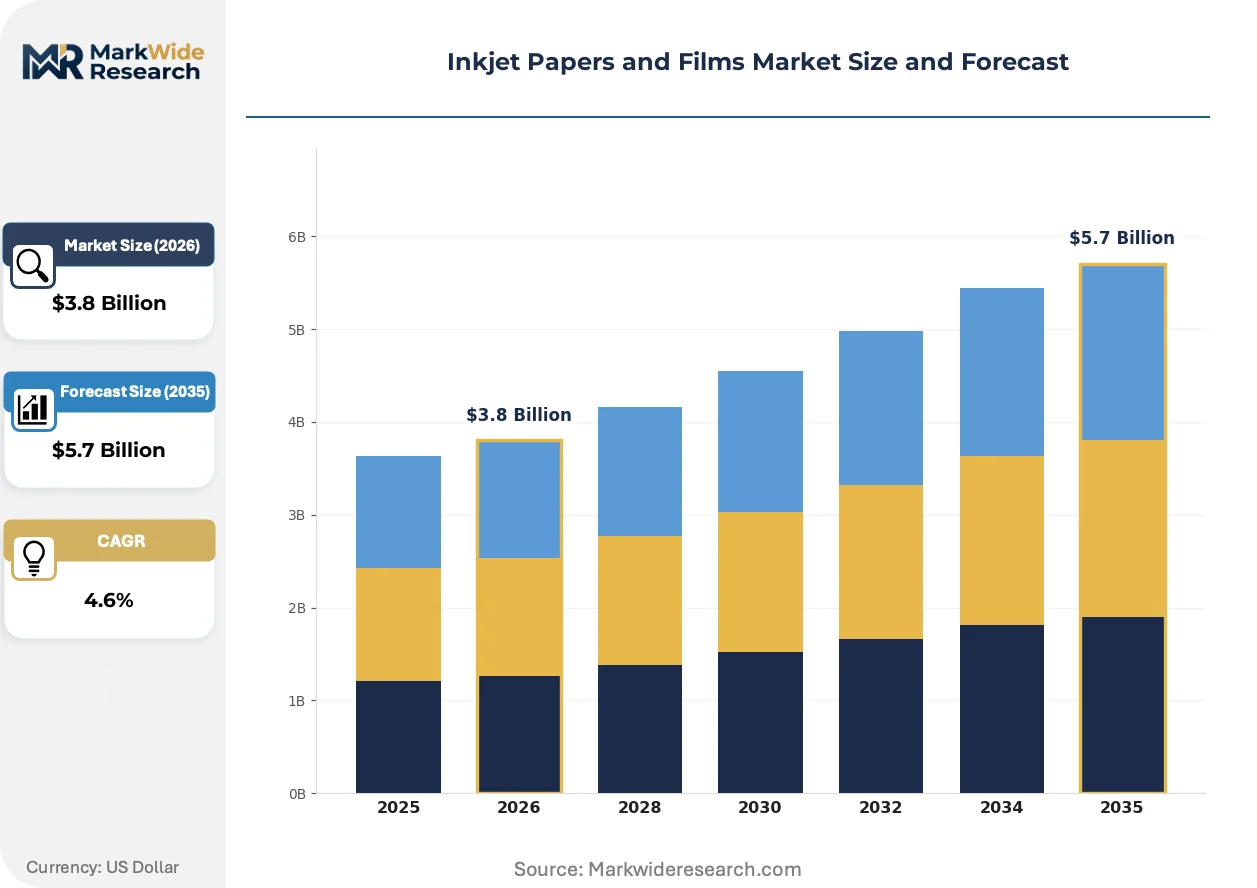
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Papers, Uncoated Papers, Films, Synthetic Papers End User: Commercial Printing, Photography, Fine Art, Labels Thickness: Standard, Heavyweight, Lightweight, Ultra-thin Application: Posters, Brochures, Business Cards, Packaging |
| Companies Covered | Stora Enso, Smurfit Kappa, International Paper, Nippon Paper, Sappi, Domtar Corporation, OJI, Fujifilm, UPM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inkjet Papers and Films Market Shifts & Advancements
Substrate engineering is converging with printhead physics and environmental compliance, forcing simultaneous optimization of surface chemistry, drying kinetics, and end-of-life recyclability.
Nano-cellular coating architectures are modularizing across high-volume commercial segments. These structures control droplet spread through engineered void networks rather than conventional pigment absorption. German packaging converters now specify nano-cellular boards for direct-to-corrugated beverage labeling, collapsing the traditional laminate-and-die-cut workflow into single-pass production.
EPA enforcement of per- and polyfluoroalkyl substance reporting under TSCA Section 8(a)(7) is compelling coating reformulation across North American synthetic paper lines. Manufacturers must disclose fluorinated additive volumes above 100 kilograms annually, triggering substitution programs for grease-resistant food service substrates. California's Safer Consumer Products program extends these obligations to backlit display films, accelerating silicone-based alternatives.
Consolidated procurement by multi-site print service providers is compressing supplier qualification cycles. Large commercial printers in Texas and Ontario now mandate single-source substrate contracts with guaranteed 48-hour fulfillment across 15+ SKUs. This behavior favors coating mills with integrated pulp supply and regional slitting operations, displacing fragmented distributor networks that previously managed inventory for independent shops.
Inkjet Papers and Films Market Segmentation
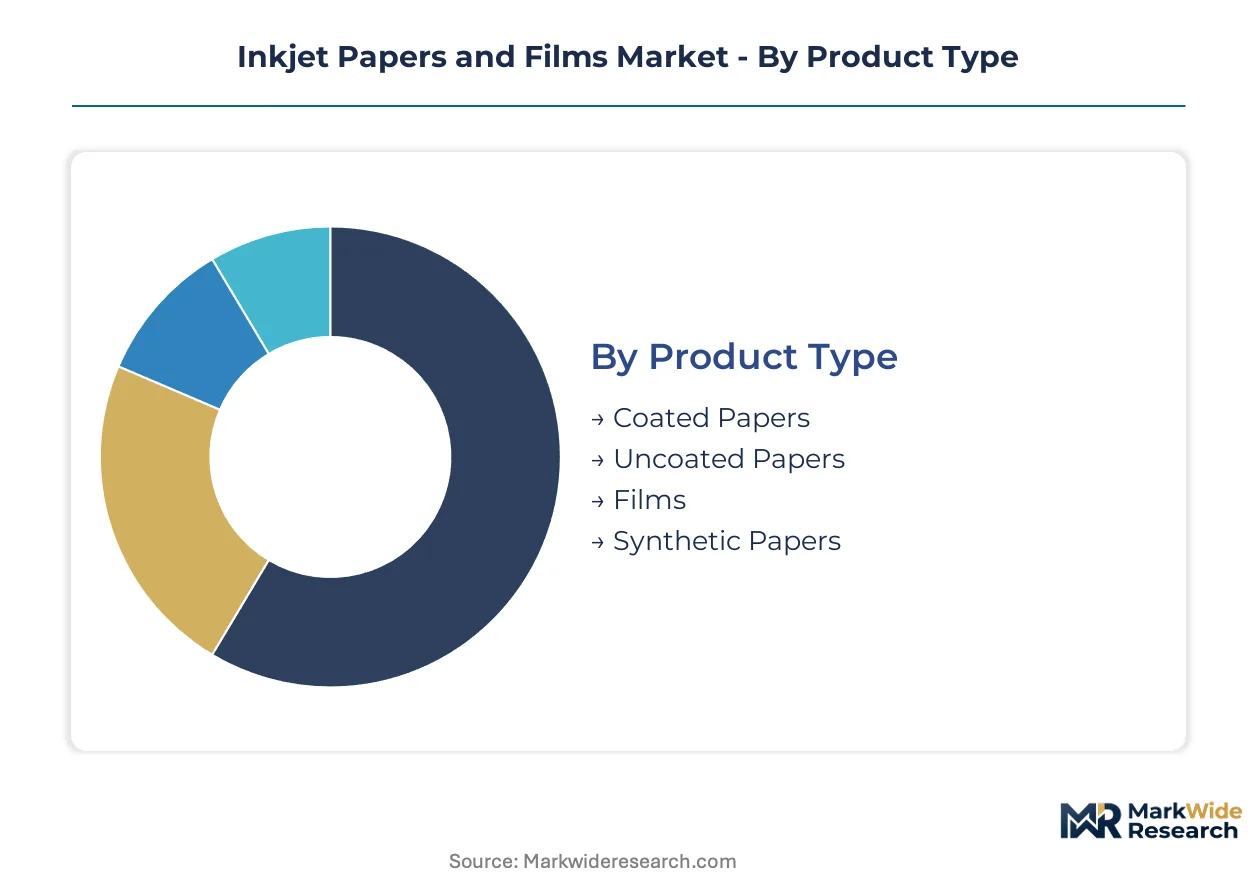
Substrate selection in inkjet printing hinges on reconciling image fidelity requirements with drying speed and end-use durability. Each segmentation dimension reflects a distinct trade-off between unit economics and performance specifications that converters must navigate.
Product Type:
Volume concentration favors established coated stocks, while premium positioning clusters around engineered synthetics and specialty films.
- Coated Papers:Micro-porous pigment layers bonded to wood-pulp bases control droplet spread through capillary absorption. Commercial print service providers in Germany and China specify these stocks for variable-data brochures where instant drying compresses job turnaround. Mature deployment sits with Coated Papers.
- Films:Polyester and polypropylene substrates carry proprietary polymer receptive layers optimized for aqueous dye and pigment inks. Backlit display manufacturers in South Korea and photographic studios in Japan drive specification for optical clarity and dimensional stability. Newer deployment is concentrated in Films.
- Uncoated Papers:Unsized cellulose sheets rely on fiber porosity alone for ink absorption, limiting use to draft output and internal documentation.
- Synthetic Papers:Polyolefin-based substrates resist moisture and tearing for durable tags, wristbands, and horticultural labels.
Coated Papers anchor high-volume commercial work. Films and Synthetic Papers are climbing the fastest as durability requirements displace laminated alternatives.
End User:
Customer type determines specification rigor, with archival and brand-critical applications commanding substrate premiums over transactional output.
- Commercial Printing:Mid-sized digital print shops purchase coated papers in pallet quantities for short-run marketing collateral. E-commerce fulfillment specifications in China and Germany now include inkjet-compatible corrugated liners.
- Fine Art:Museum-grade cotton rag and alpha-cellulose papers require ISO 18916 certification for lightfastness, locking inventory capital in 12-month testing protocols.
- Photography:Professional studios and minilabs specify resin-coated papers and transparency films for portrait and exhibition output.
- Labels:Pharmaceutical converters in Mumbai and Ahmedabad pilot aqueous inkjet for regulatory leaflets, bypassing solvent-based constraints from India's Central Pollution Control Board.
Commercial Printing dominates procurement tonnage. Fine Art and Labels represent the steepest expansion trajectory as certification requirements and regulatory shifts reshape substrate selection.
Thickness:
Caliper selection maps directly to equipment compatibility and handling durability across divergent end-use environments.
- Standard:90-120 gsm stocks balance feed reliability through desktop and light-production printers with sufficient opacity for double-sided output.
- Heavyweight:200-300 gsm boards serve greeting cards, packaging prototypes, and fine-art prints requiring rigidity without lamination.
- Lightweight:60-80 gsm papers reduce postage costs for direct-mail campaigns and high-volume transactional printing.
- Ultra-thin:Sub-50 gsm substrates enable compact folding for pharmaceutical inserts and airline ticket stock.
Standard caliper anchors equipment compatibility. Heavyweight grades are gaining share fastest as uncoated board alternatives displace laminated structures.
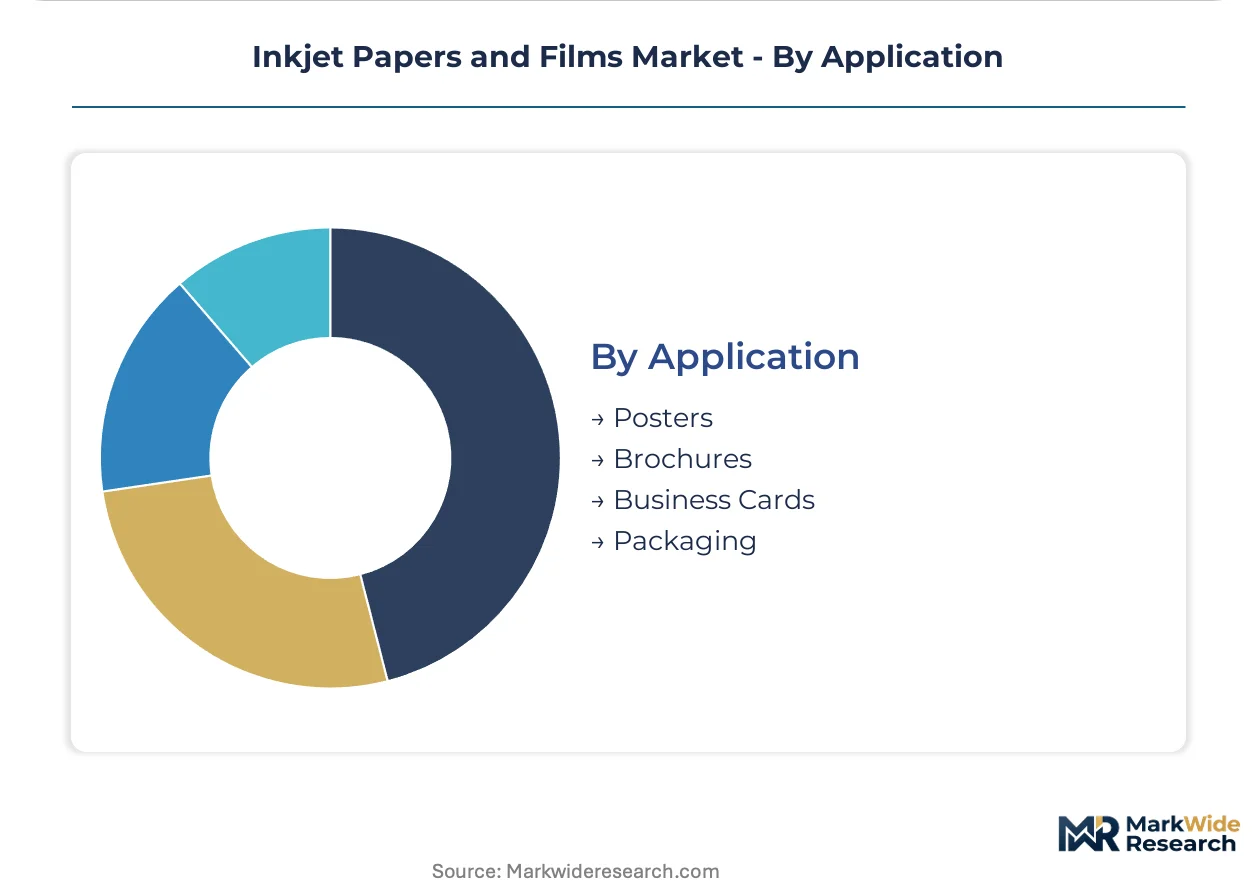
Application:
Use case determines surface finish, dimensional stability, and coating chemistry requirements across divergent display and handling conditions.
- Posters:Satin and gloss-coated papers with tear-resistant backings serve retail and transit advertising where short-term durability suffices.
- Packaging:Direct-to-corrugated inkjet liners with nano-cellular coatings collapse laminate-and-die-cut workflows into single-pass production for beverage labeling in German converter facilities.
- Brochures:Matte-coated stocks with enhanced ink holdout support high-resolution imagery for corporate and tourism marketing.
- Business Cards:Heavyweight coated or synthetic papers withstand repeated handling while supporting crisp typography and solid ink coverage.
Brochure and poster applications represent mature installed demand. Packaging is expanding most quickly as e-commerce variable-data requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial print service providers in China purchase the largest substrate volumes as packaging converters and photo studios displace offset workflows with digital short-run production.
China
E-commerce fulfillment centers in Shanghai and Shenzhen specify inkjet-compatible corrugated liners for variable-data cartons, eliminating pre-print plate costs. The Ministry of Ecology and Environment enforces dual carbon goals that constrain thermal drying energy intensity in coating facilities. Packaging converters in the Yangtze River Delta pilot nano-cellular coated boards for direct-to-corrugated beverage labeling.
Germany
Commercial print shops in Munich and Hamburg accelerate substrate procurement for short-run marketing collateral as legacy Heidelberg presses retire. ECHA administers REACH registration deadlines that mandate disclosure of fluorinated additives in stain-resistant synthetic papers. German packaging converters now specify nano-cellular architectures for single-pass beverage labeling workflows.
United States
Mid-sized digital print shops in Texas and Ontario mandate single-source substrate contracts with guaranteed 48-hour fulfillment across 15-plus SKUs. EPA enforcement of TSCA Section 8(a)(7) compels coating reformulation for grease-resistant food service substrates. Coating facilities sourcing renewable energy for thermal drying processes qualify for IRA clean manufacturing production tax credits.
Japan
Professional photography studios and minilabs in Tokyo and Osaka drive specification for resin-coated papers and transparency films requiring optical clarity. METI enforces JIS standards for recycled content claims that influence corporate print buyer procurement. Industrial printhead manufacturers in Nagoya now demand micro-porous coated papers with sub-micron surface roughness for 2400 dpi piezoelectric heads.
India
Flexographic converters in Mumbai and Ahmedabad pilot aqueous inkjet for pharmaceutical leaflets, bypassing solvent-based regulatory constraints. The Central Pollution Control Board maintains emissions standards that disadvantage solvent coating chemistries. Pharmaceutical packaging clusters in Gujarat test aqueous inkjet workflows for regulatory compliance.
Inkjet Papers and Films Market Competitive Landscape
Finnish and Swedish producers anchor one tier through integrated pulp-to-paper operations; Japanese and German specialists hold formulation advantages in proprietary polymer layers. The vendor base separates into three strategic archetypes: integrated forest products groups controlling fiber supply, coating technology specialists commanding receptive layer chemistry, and regional converters leveraging proximity to end-use clusters. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure coating chemist expertise and regional slitting operations.
Within the integrated pulp-to-paper tier, Stora Enso and UPM represent Nordic forest products groups with captive fiber supply. Sappi occupies a position among specialty coated paper producers with premium fine-art segment exposure. Fujifilm exemplifies the coating technology specialist archetype through sustained investment in proprietary polymer layer development. These three companies collectively illustrate how substrate competition separates between fiber-integrated cost positions and formulation-driven premium positioning.
| Leading Market Players |
|---|
| Stora Enso |
| Smurfit Kappa |
| International Paper |
| Nippon Paper |
| Sappi |
| Domtar Corporation |
| OJI |
| Fujifilm |
| UPM |
| Others |
Supply & Pricing Matrix
Nano-cellular coating architectures are compressing production economics for German packaging converters while simultaneously concentrating formulation expertise among three German chemical complexes that manufacture the acrylic emulsions powering inkjet-receptive layers. This technological transition rewards coating mills with integrated pulp supply and regional slitting operations, squeezing fragmented distributor networks that previously managed inventory for independent print shops.
Pricing Analysis
Volume concentration in coated papers trades margin for throughput, while premium positioning in synthetic papers and specialty films captures ISO-certified archival grades and optical-clarity specifications. Three-tier pricing structure across premium, standard, and economy levels separates museum-grade cotton rag from commercial coated stocks and draft-quality uncoated alternatives. Cost compression in mid-tier coated papers is intensifying because Finnish and Swedish pulp suppliers leverage captive fiber contracts against specialty mills lacking long-term supply agreements. Commercial print service providers in China and Germany exhibit the highest price sensitivity due to compressed job turnaround economics, whereas fine-art studios in Japan and museum procurement officers accept substantial premiums for certified lightfastness.
Supply Chain Analysis
ISO 18916 certification and REACH registration requirements gate supplier qualification, extending onboarding cycles for coating mills seeking access to European corporate print buyers and Japanese museum procurement channels. Geographic supply concentrates in Finland, Sweden, and Germany where integrated pulp-to-paper operations and chemical formulation clusters anchor production. Raw material dependencies center on northern bleached softwood kraft pulp, acrylic emulsions for receptive layers, and fluorine-free coating binders. Single-source vulnerability runs through the three German chemical complexes manufacturing acrylic emulsions for synthetic paper producers. Distribution runs through consolidated procurement contracts demanded by multi-site print service providers in Texas and Ontario, displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over coating chemist expertise and captive pulp supply determines margin sustainability. Players are pursuing backward integration into fiber supply and proprietary polymer layer development as the decisive upstream levers.
For Market Incumbents: Lock in coating chemist expertise through targeted retention programs and succession planning, as fluorine-free stain resistance formulation knowledge resides with retiring specialists at Finnish and Japanese pulp mills. Secure long-term fiber contracts with Swedish and Finnish suppliers to defend margin position against pulp cost volatility. Prioritize regional slitting operations in Texas and Ontario to meet 48-hour fulfillment mandates from consolidated multi-site print buyers. For New Entrants and Emerging Players: Capture the aqueous inkjet pharmaceutical leaflet segment in Mumbai and Ahmedabad, where India's Central Pollution Control Board emissions standards disadvantage incumbent solvent-based converters. Target RFID-integrated synthetic papers for automotive parts traceability in South Korean assembly plants, where durability requirements and smart-label convergence create specification gaps. Pursue formulation partnerships with specialty chemical suppliers accelerating bio-based coating binder migration ahead of European registration deadlines. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated forest products groups seeking coating technology capabilities, as Nordic pulp-to-paper operators and Japanese polymer specialists represent the most logical strategic buyers. Long-term viability favors substrate suppliers with demonstrated REACH-compliant product pipelines and established certification relationships with corporate print buyers. Watch for tightening per- and polyfluoroalkyl substance restrictions across multiple jurisdictions as the critical inflection signal determining which coating suppliers retain regulated end-market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Supply | Captive pulp contracts from Swedish and Finnish mills insulate margin predictability against spot price volatility. |
| Proprietary Polymer Layer Development | Fujifilm's sustained R&D investment in receptive layer chemistry commands premium positioning in photographic and display applications. |
| Regional Slitting Operations | Texas and Ontario fulfillment centers satisfy 48-hour SKU guarantees demanded by consolidated commercial print buyers. |
| REACH-Compliant Formulation Partnerships | Bio-based coating binder collaborations with German chemical suppliers accelerate European market access ahead of registration deadlines. |
| RFID-Integrated Synthetic Paper Lines | Convergence with UHF inlay embedding captures automotive traceability specifications in South Korean assembly plants. |
Research Methodology
Multi-period observation of pulp cost indices, coating formulation patent filings, and commercial print equipment installation rates anchored the trend analysis, supplemented by interviews with coating mill technical directors, commercial print shop procurement managers, pharmaceutical packaging converters, museum conservation officers, and specialty chemical supplier R&D leads. Secondary validation drew from customs and trade data tracking substrate imports, SEC filings of integrated forest products groups, EPA enforcement actions under TSCA Section 8(a)(7), and ECHA REACH registration disclosures. Bottom-up demand modeling across end-use segments triangulated against top-down pulp consumption and coating capacity estimates.
Segment-weighting approaches distributed value and volume across product type, end user, thickness, and application dimensions, with additional calibration for regional regulatory cluster effects. CAGRs were derived from fitted growth curves applied to historical shipment data and projected equipment replacement cycles. Industry-specific forecast inputs included piezoelectric printhead resolution advancement timelines, e-commerce corrugated liner specification adoption curves, and fluorinated additive phase-out implementation schedules across European and North American jurisdictions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pulp supply disruptions, coating chemist labor availability, and unanticipated regulatory acceleration on per- and polyfluoroalkyl substance restrictions. The analysis reflects documented assumptions regarding digital print adoption rates and substrate specification upgrade trajectories. A model refresh is warranted upon material change in REACH enforcement intensity or breakthrough advances in solvent-free coating curing technologies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Carbonless Paper Market
Paper Products
Clay Coated Paper Market
Paper Products
Solid Bleached Sulfate (SBS) Board Market
Paper Products
Printing Paper Market
Paper Products
Paper Glass Market
Paper Products
Pulp and Paper Chemicals Market
Paper Products
Unbleached Kraft Pulp Market
Paper Products
Stone Paper Market
Paper Products
Global Paperboard Market
Paper Products
Writing Paper Market
Paper Products
Europe Paper Market
Paper Products
Woodfree Paper Market
Paper Products
Decor Paper Market
Paper Products
Bleached Softwood Kraft Pulp Market
Paper Products
Bleached Hardwood Kraft Pulp Market
Paper Products
Hardwood Pulp Market