
 North America Thermal Paper Market | 2026-2036
North America Thermal Paper Market Size, Share, and Industry Trends Forecast 2026-2036
North America Thermal Paper Market Insights
Multi-sourcing strategies among label converters is recalibrating procurement patterns across the North America thermal paper supply base. Domtar Corporation leverages its integrated pulp-to-paper infrastructure to sustain cost advantages in high-volume receipt grades. Appvion Operations, Inc. differentiates through specialty coating capabilities that serve healthcare and logistics accounts requiring archival durability. Twin Rivers Paper Company anchors its position in lightweight thermal substrates optimized for portable printers and mobile point-of-sale terminals.
Thermal paper consists of a base paper stock coated with a color-developing layer containing leuco dye and developer chemicals, which react under controlled heat to produce visible marks without ink ribbons or toner cartridges; this chemistry enables instant, maintenance-free printing essential for high-transaction environments. Direct thermal dominates receipt printing applications across retail and banking channels where equipment simplicity and low operating cost outweigh fade sensitivity. Specialty coated grades command premium positioning in healthcare and logistics segments where barcode legibility and environmental resistance determine compliance outcomes. Thermal transfer technology extends label life in cold-chain logistics, creating a durable alternative where direct thermal image stability falls short.
EPA chemical review protocols and state-level bisphenol-A restrictions in California and New York are forcing coating reformulations across the supply chain, elevating compliance costs for phenol-free alternatives while opening technical differentiation opportunities. FDA regulations governing label permanence for pharmaceuticals and medical devices reinforce demand for archival-grade thermal substrates that maintain readability across temperature excursions. Stakeholders must monitor evolving chemical safety designations and digital receipt mandates at the municipal level to anticipate substitution risks and align R&D investments with compliance trajectories.
Market Dynamics
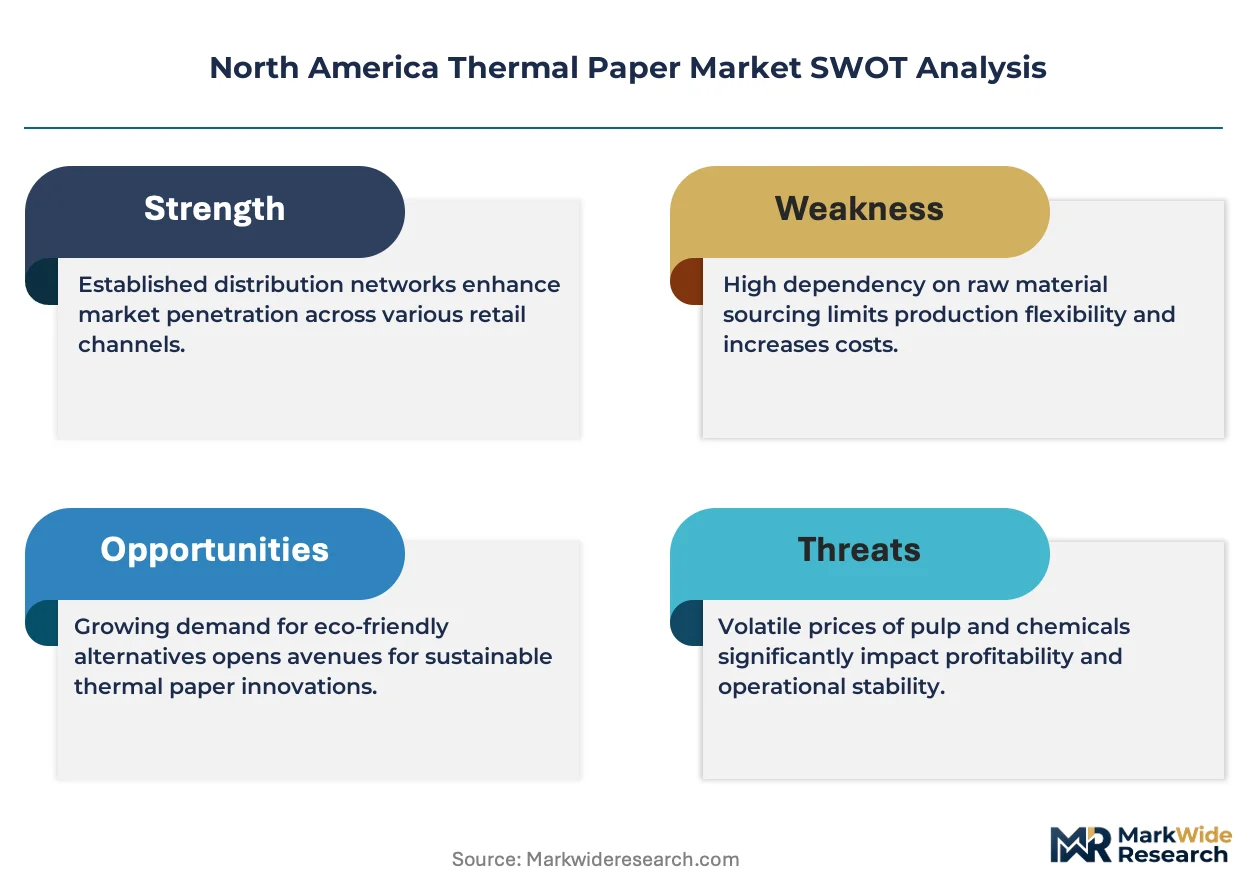
State-level chemical safety frameworks are forcing coating reformulations across the North America thermal paper supply chain, elevating compliance costs while creating technical differentiation opportunities for phenol-free alternatives.
Growth Catalysts
- Logistics label adoption:Last-mile tracking requirements are expanding thermal label consumption across e-commerce fulfillment networks clustered near Atlanta and Memphis distribution hubs.
- FDA archival permanence rules:Pharmaceutical and medical device labeling mandates are sustaining demand for thermal substrates that maintain barcode legibility across temperature excursions.
- Mobile POS terminal proliferation:Lightweight thermal substrates optimized for portable printers are capturing volume in retail and hospitality environments seeking equipment mobility.
Market Restraints
- Bisphenol-A input cost volatility:California and New York restrictions on phenol-based coatings are elevating reformulation expenses and compressing margins for non-specialty grades.
- Direct thermal image stability limitations:Fade sensitivity in receipt applications creates substitution pressure from thermal transfer technology in cold-chain logistics where durability determines compliance outcomes.
- Southeastern supply concentration:Distribution hub clustering in Georgia and Tennessee creates geographic vulnerability to regional logistics disruptions and weather events.
Strategic Opportunities
- Healthcare specialty coating expansion:Archival-grade thermal substrates for patient wristbands and prescription labels command premium positioning under FDA permanence requirements.
- Municipal digital receipt mandates:Select city-level paper reduction policies are accelerating development of hybrid digital-physical receipt systems that preserve thermal paper for essential compliance documentation.
- Thermal transfer convergence with RFID:Integration of durable thermal labels with track-and-trace electronics is opening cold-chain pharmaceutical applications where direct thermal chemistry falls short.
Industry Challenges
- Coating chemistry talent scarcity:Reformulation expertise for phenol-free leuco dye systems sits concentrated among legacy coating specialists, constraining rapid product line transitions.
- Multi-source certification timelines:Healthcare and logistics accounts require extended validation cycles for new thermal substrate suppliers, elongating customer acquisition timelines.
- Legacy POS equipment compatibility:Thermal paper specifications must maintain backward compatibility with installed base of stationary and mobile printers across fragmented equipment vintages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Thermal Paper Market |
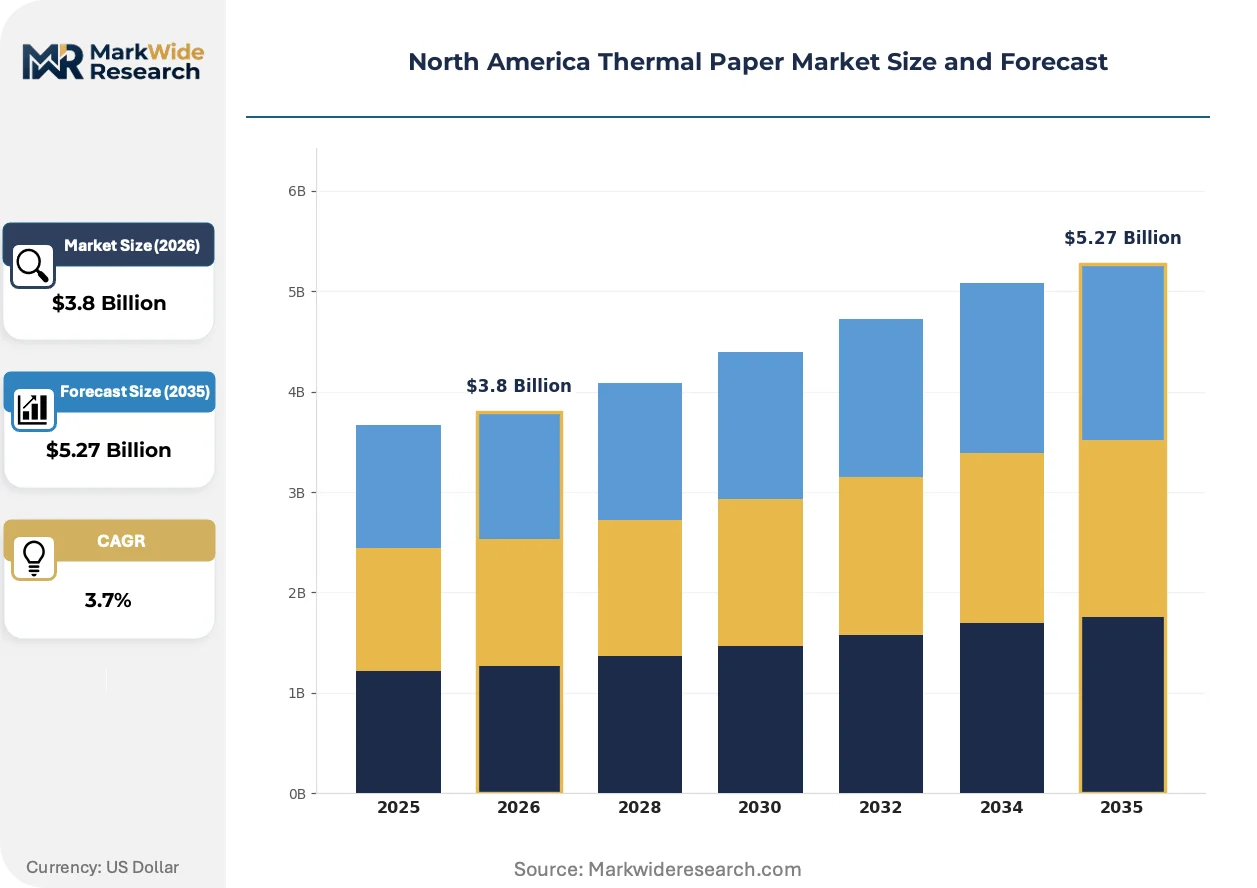
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.27 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Thermal, Thermal Transfer, Specialty Coated, Self-Adhesive End User: Retail, Banking, Healthcare, Logistics Application: Labeling, Receipt Printing, Barcode Printing, Ticketing Technology: Digital Printing, Offset Printing, Flexographic Printing, Inkjet Printing |
| Companies Covered | Appvion Operations, Inc., Domtar Corporation, Twin Rivers Paper Company, Iconex LLC, Nakagawa Manufacturing (USA), Inc., Kanzaki Specialty Papers, Inc., Telemark Diversified Graphics, POS Supply Solutions, Thermal Paper Direct, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Thermal Paper Market Trends and Innovations
Coating chemistry evolution and procurement model compression are restructuring competitive positioning across receipt and label segments. Technical differentiation is shifting from base paper quality toward environmental compliance and image durability specifications.
Phenol-free thermal coating chemistry is electrifying product development pipelines across the supply base. Leuco dye systems utilizing alternative developers are capturing healthcare and food-service accounts where bisphenol-A restrictions are most stringent. Coating specialists with in-house formulation capabilities are compressing commoditized receipt grades into price-driven procurement while securing multi-year contracts for archival-grade alternatives.
EPA chemical review protocols are amplifying state-level regulatory fragmentation across the United States. California's Safer Consumer Products framework and New York's emerging chemical restrictions are creating non-uniform compliance obligations that favor regional coating specialists over national distributors. Thermal paper converters are responding by segmenting product lines into state-specific SKUs, elevating inventory complexity and working capital requirements.
Buyer consolidation among national label converters is compressing supplier negotiation cycles and unbundling technical service from commodity volume contracts. Large logistics and retail accounts are consolidating thermal label procurement through centralized print management programs, displacing fragmented regional converter relationships. This concentration is most visible in the southeastern United States, where e-commerce fulfillment center expansion has created anchor customers with sufficient volume to demand custom coating specifications and dedicated production slots.
North America Thermal Paper Market Segmentation
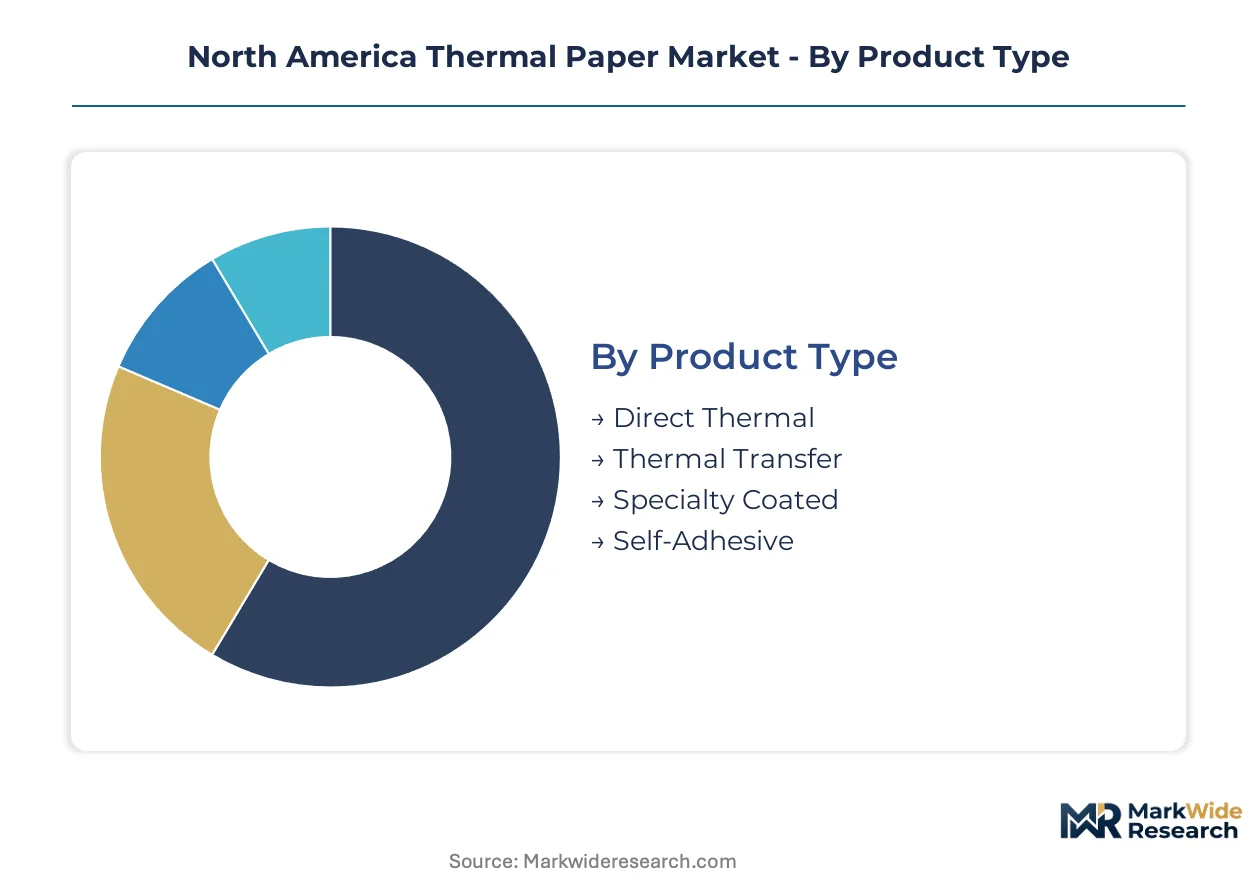
Thermal paper procurement patterns diverge sharply across product chemistry, end-use durability requirements, and printing infrastructure compatibility. Equipment replacement cycles and regulatory compliance timelines create asynchronous upgrade opportunities that reshape segment priorities across the North American supply base.
Product Type:
Printer fleet modernization and coating chemistry reformulations are recalibrating product specifications across receipt and label applications.
- Direct Thermal:Heat-sensitive coating containing leuco dye and developer reacts without ribbon or toner, enabling maintenance-free operation in high-transaction retail and banking environments. Demand clusters in southeastern distribution hubs where e-commerce receipt volume sustains high-throughput POS installations.
- Thermal Transfer:Wax or resin ribbon transfers image onto substrate, delivering archival durability for cold-chain pharmaceutical labels and multi-year logistics tracking. FDA permanence mandates for medical device labeling sustain premium positioning in healthcare accounts.
- Specialty Coated:Phenol-free formulations serve California and New York markets under state-level bisphenol-A restrictions.
- Self-Adhesive:Pre-coated adhesive layer eliminates secondary labeling steps in high-velocity fulfillment operations.
Volume placements concentrate in Direct Thermal; the faster expansion belongs to Specialty Coated.
End User:
Compliance intensity and transaction velocity create divergent specification requirements across customer categories.
- Retail:Point-of-sale receipt printing dominates volume, with mobile terminal proliferation driving lightweight substrate demand in hospitality and specialty store formats. Fade sensitivity limits archival applications, concentrating procurement on cost-optimized grades.
- Logistics:Last-mile tracking requirements expand thermal label consumption near Atlanta and Memphis distribution clusters, where barcode legibility determines compliance outcomes across temperature excursions.
- Banking:ATM receipt and transaction record applications sustain steady demand for standard direct thermal grades.
- Healthcare:Patient wristbands and prescription labels command premium positioning under FDA permanence rules.
Retail captures the largest shipment volumes; logistics is climbing the fastest.
Application:
Image durability requirements and environmental exposure conditions segment procurement across use cases.
- Labeling:Adhesive-backed thermal substrates serve package identification and inventory tracking across warehousing and transportation nodes. Cold-chain pharmaceutical applications favor thermal transfer durability where direct thermal chemistry degrades.
- Receipt Printing:Short-duration transaction records prioritize equipment simplicity and operating cost over image permanence in retail and hospitality channels.
- Barcode Printing:Scan reliability mandates precise coating uniformity for logistics compliance.
- Ticketing:Event and transportation applications require rapid printing with moderate environmental resistance.
Labeling dominates current procurement; barcode printing shows the steepest expansion trajectory.
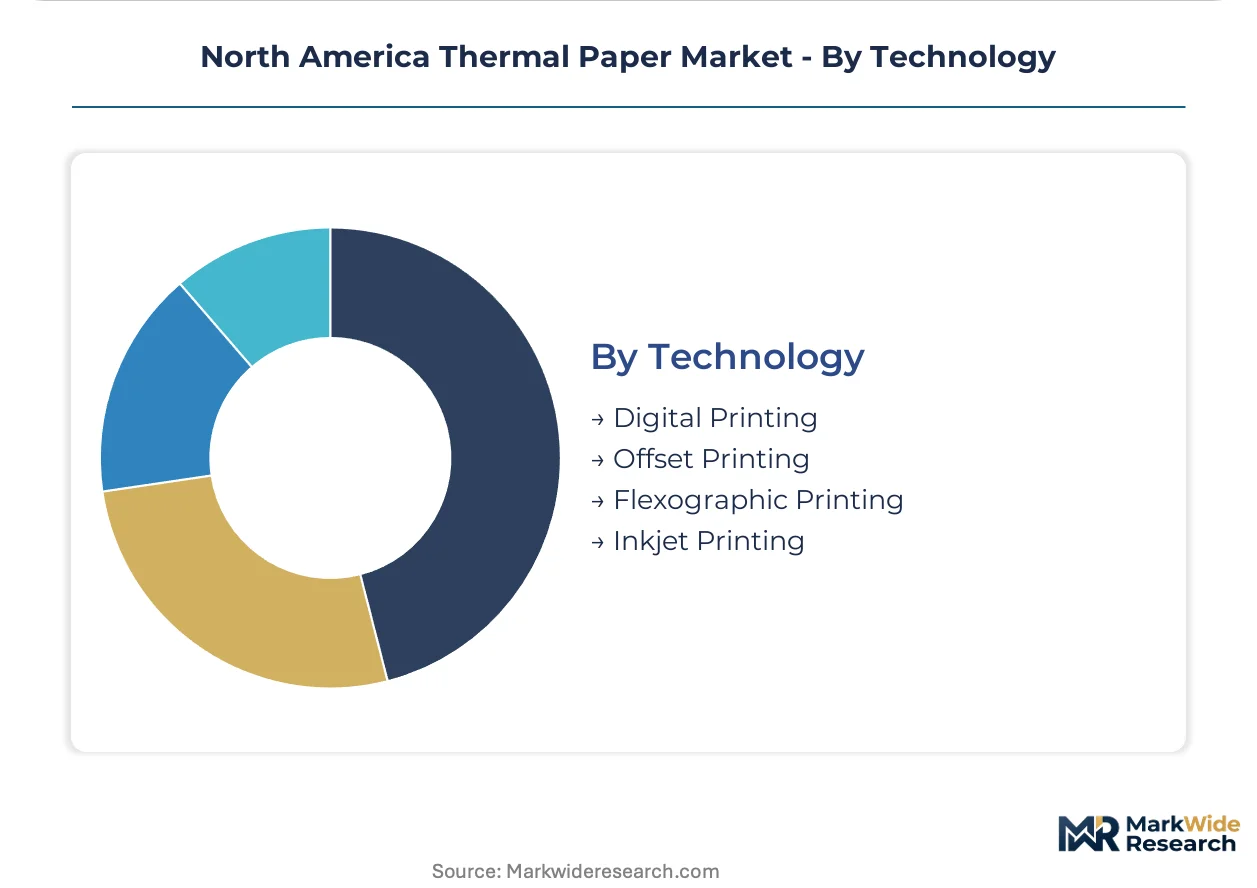
Technology:
Print method selection constrains substrate specification and coating compatibility across installed equipment bases.
- Digital Printing:Variable-data capability supports short-run customization for pharmaceutical serialization and personalized logistics labels. Equipment proliferation in healthcare accounts accelerates adoption of digitally optimized thermal substrates.
- Flexographic Printing:High-speed rotary operation dominates long-run label production for national retail and logistics accounts.
- Offset Printing:Limited thermal paper compatibility restricts application to specialized security and pre-printed formats.
- Inkjet Printing:Emerging compatibility with treated thermal surfaces creates hybrid application opportunities.
Flexographic placements lead in volume terms; digital printing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pulp mill locations in the southeastern United States anchor thermal paper production capacity, with integrated forest products infrastructure supplying base stock to coating operations across the region.
United States
Distribution hub clustering near Atlanta and Memphis sustains label demand from e-commerce fulfillment networks. FDA regulations governing pharmaceutical label permanence reinforce procurement of archival-grade substrates for medical device tracking. Georgia and Tennessee host the densest concentration of thermal paper converting capacity, serving last-mile logistics accounts with customized coating specifications.
Canada
Ontario and Quebec pulp producers supply bleached kraft base stock to North American coating operations. Health Canada chemical safety assessments influence phenol-free formulation trends that cross into US regulatory discussions. Vancouver-area logistics terminals generate thermal label consumption for trans-Pacific container tracking and cold-chain pharmaceutical exports.
Mexico
Manufacturing maquiladoras along the northern border states expand point-of-sale terminal installations in retail and hospitality channels. Mexico's national chemical regulator monitors bisphenol-A usage in food-contact applications, creating compliance alignment pressure with California frameworks. Monterrey and Tijuana industrial corridors concentrate thermal receipt demand from automotive and electronics assembly operations.
North America Thermal Paper Market Competitive Landscape
Global majors compete with regional champions across coating chemistry and distribution proximity. The North America thermal paper supply base organizes into three tiers: integrated pulp-to-paper producers with captive fiber supply, specialty coating specialists with formulation expertise, and regional converters focused on logistics and retail accounts. Strategic moves concentrate on phenol-free reformulation investments and multi-year supply contracts with e-commerce fulfillment anchor customers.
Within the integrated producer tier, Domtar Corporation exemplifies backward integration into pulp supply, while Appvion Operations, Inc. occupies a position as a coating chemistry specialist. Twin Rivers Paper Company anchors the lightweight substrate segment serving mobile point-of-sale applications.
| Leading Market Players |
|---|
| Appvion Operations, Inc. |
| Domtar Corporation |
| Twin Rivers Paper Company |
| Iconex LLC |
| Nakagawa Manufacturing (USA), Inc. |
| Kanzaki Specialty Papers, Inc. |
| Telemark Diversified Graphics |
| POS Supply Solutions |
| Thermal Paper Direct |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up label converters have compressed procurement cycles across the North America thermal paper supply base, tightening pricing discipline while fragmenting volume commitments across multiple coating specialists. This ownership pattern accelerates unbundling of technical service from commodity contracts, forcing suppliers to compete on state-specific compliance SKUs rather than national scale economies.
Pricing Analysis
Warranty and technical service bundling separates premium coating specialists from commodity receipt-grade suppliers in contract negotiations. Three-tier pricing structure across premium archival, standard direct thermal, and economy receipt grades reflects certification intensity and FDA permanence compliance. Pricing pressure stems from phenol-free reformulation costs under California and New York chemical safety frameworks. Logistics accounts with centralized print management programs exhibit lowest price sensitivity due to compliance-driven specification lock-in, while independent retail operators drive aggressive spot-market negotiation.
Supply Chain Analysis
Reverse-logistics flows for thermal label returns and printer equipment refurbishment remain underdeveloped, creating working capital inefficiencies for high-velocity e-commerce fulfillment accounts. Base paper production concentrates in Georgia, Tennessee, and South Carolina, drawing from regional pulp mills with integrated forest products infrastructure. Coating chemistry depends on leuco dye systems and developer formulations sourced from specialty chemical producers in the United States and Canada. Single-source vulnerability sits with phenol-free developer supply constrained by reformulation expertise concentration. Distribution runs through southeastern converting facilities to Atlanta and Memphis distribution hubs serving last-mile logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America thermal paper market sits in a technology-transition phase as phenol-free coating chemistry displaces legacy bisphenol-A formulations under state-level chemical safety mandates.
For Market Incumbents: Lock in multi-year supply contracts with e-commerce fulfillment anchor customers in the southeastern United States before phenol-free capacity expansion saturates premium pricing tiers. Deepen backward integration into leuco dye formulation capabilities to defend margin position against specialty chemical suppliers capturing coating value. Prioritize FDA archival-grade certification investments as thermal transfer substitution threatens direct thermal label applications in cold-chain pharmaceutical tracking. For New Entrants and Emerging Players: Begin with phenol-free specialty coating production targeting California and New York markets where regulatory restrictions have created geographic pricing premiums. Healthcare patient wristband and prescription label segments offer the most penetrable white-space due to extended validation timelines that deter incumbent product line transitions. Pursue co-development partnerships with regional label converters seeking state-specific SKU diversification without captive coating investment. For Investors and Strategic Acquirers: California Safer Consumer Products enforcement actions against non-compliant thermal paper importers are the leading indicator that phenol-free formulation capabilities will command acquisition premiums across the analysis window. Long-term viability favors coating specialists with in-house leuco dye chemistry expertise over pure-play converters dependent on external formulation supply. Monitor municipal digital receipt mandate adoption rates in major metropolitan areas as early signals of demand destruction velocity for commodity receipt grades.| Strategic Initiative | Industry Significance |
|---|---|
| Phenol-Free Coating Capacity Expansion | California and New York chemical safety frameworks elevate compliance-grade thermal paper premiums. |
| Backward Integration into Leuco Dye Chemistry | In-house formulation capabilities reduce dependency on specialty chemical suppliers amid input volatility. |
| Multi-Year Supply Contracts with E-Commerce Anchors | Atlanta and Memphis fulfillment hub concentration creates volume lock-in opportunities for coating specialists. |
| FDA Archival-Grade Certification Investment | Pharmaceutical label permanence mandates sustain premium positioning against thermal transfer substitution. |
| Hybrid Digital-Physical Receipt System Development | Municipal paper reduction policies accelerate preservation of thermal paper for essential compliance documentation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews conducted across coating plant managers, label converter procurement leads, healthcare GPO contracts managers, logistics fulfillment operations directors, and FDA regulatory affairs specialists. Secondary validation drew from EPA chemical review protocols, state-level bisphenol-A restriction filings, SEC 10-K disclosures from integrated forest products companies, and thermal printer equipment shipment databases. Bottom-up volume modeling triangulated against top-down market sizing across product chemistry, end-use durability requirements, and printing infrastructure compatibility dimensions.
Segment-level granularity modeled direct thermal, thermal transfer, specialty coated, and self-adhesive product types across retail, logistics, banking, and healthcare end users. Application-level forecasting incorporated labeling, receipt printing, barcode printing, and ticketing use cases with technology splits across digital, flexographic, offset, and inkjet printing methods. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory compliance timelines and equipment replacement cycles. Industry-specific inputs included FDA permanence rule implementation schedules, state chemical safety framework adoption patterns, and mobile POS terminal proliferation rates.
Reformulation cost volatility, digital receipt mandate acceleration, and cold-chain logistics technology substitution are the dominant revision risks to forecast assumptions. Practitioners should monitor California enforcement actions, municipal paper reduction policy adoption, and thermal transfer- RFID integration rates for early signals of demand trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Unbleached Kraft Pulp Market
Paper Products
Unbleached Softwood Kraft Pulp Market
Paper Products
Paper Making Machine Market
Paper Products
Pulp Market
Paper Products
High-Speed Production Inkjet Printer Paper Market
Paper Products
Tissue Paper Market
Paper Products
Acrylic Paper Market
Paper Products
Overlay Paper Market
Paper Products
Reprographic Paper Market
Paper Products
Europe Paper Market
Paper Products
Cheque Paper Market
Paper Products
Billing Paper Market
Paper Products
Decorative Plastic and Paper Laminates Market
Paper Products
Europe Decor Paper Market
Paper Products
Chemical Pulp Market
Paper Products
Global Molded Pulp Products Market