
 Pharma Grade Paper Market | 2026-2036
Pharma Grade Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Pharma Grade Paper Market Analytics
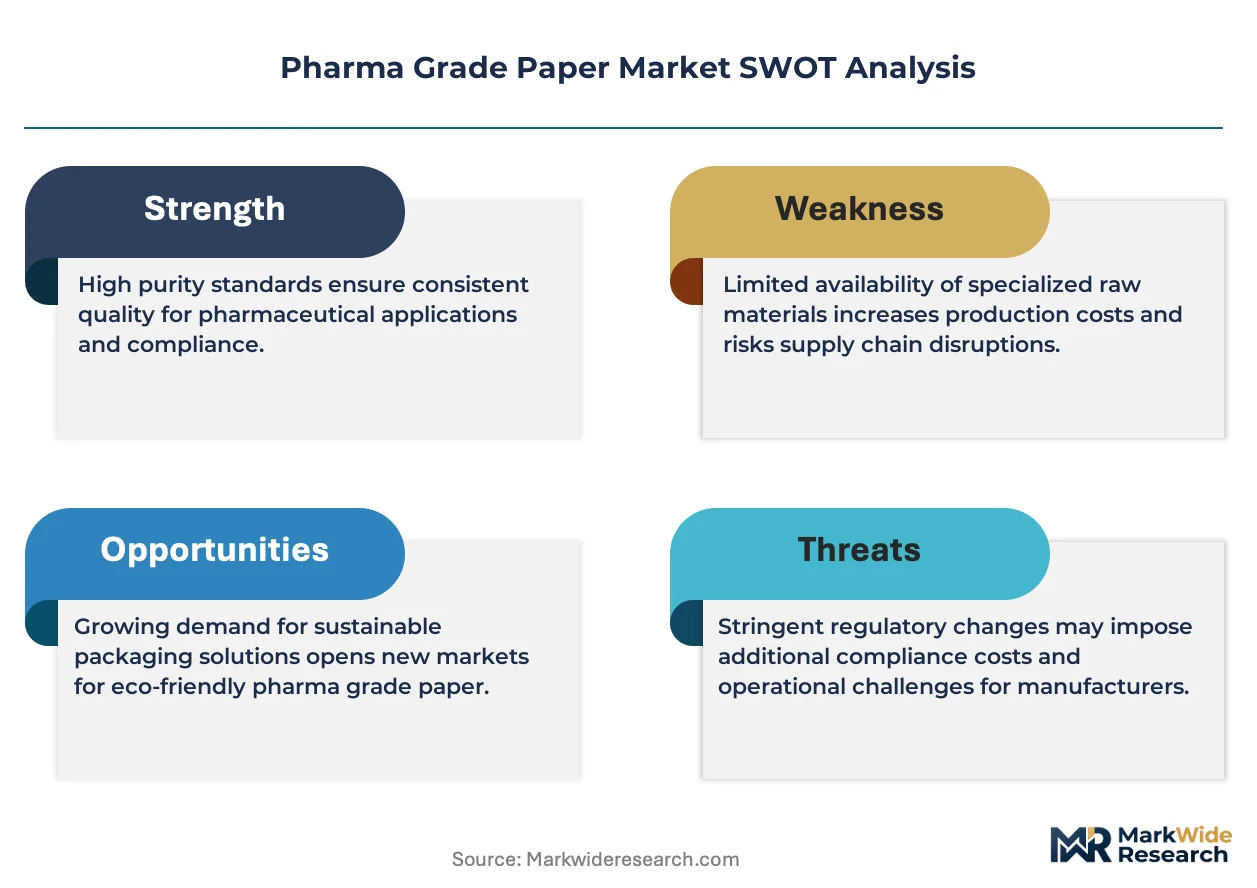
Multi-sourced pulp procurement is decoupling from traditional single-origin supply contracts as mills seek fiber security. Ahlstrom-Munksjö leverages its Nordic pulp integration to control specialty paper purity from forest to finished roll. Mondi Group anchors Central European production with integrated kraft pulp capacity serving pharmaceutical converters. Fedrigoni competes through premium coated grades tailored for high-resolution drug labeling across Mediterranean markets.
Pharma grade paper denotes cellulose-based substrates engineered to meet pharmacopoeial purity limits for extractables, microbial bioburden, and dimensional stability under variable humidity. Manufacturers produce these grades via controlled wet-end chemistry, alkaline sizing, and supercalendering to achieve specified air permeability and ink adhesion for variable-data printing. Specialty paper commands the widest margin pool due to custom barrier coatings and serialization-ready surfaces demanded by track-and-trace mandates. Uncoated paper leads volume in secondary packaging inserts where cost minimization dominates purchasing criteria. Coated paper sustains above-average growth in high-visibility patient information leaflets requiring pharmaceutical-grade print fidelity.
FDA enforces USP <661> container closure system guidelines that directly constrain paper composition for drug-contact applications, while EMA's MDR framework extends material traceability requirements to secondary packaging. ISO 15378 certifies quality management for medicinal product packaging, creating a de facto market-access threshold for European and Asian suppliers. Stakeholders must monitor evolving pharmacopoeial harmonization between FDA, EMA, and China's NMPA as divergence in extractables testing protocols threatens to fragment qualification requirements across supply chains.
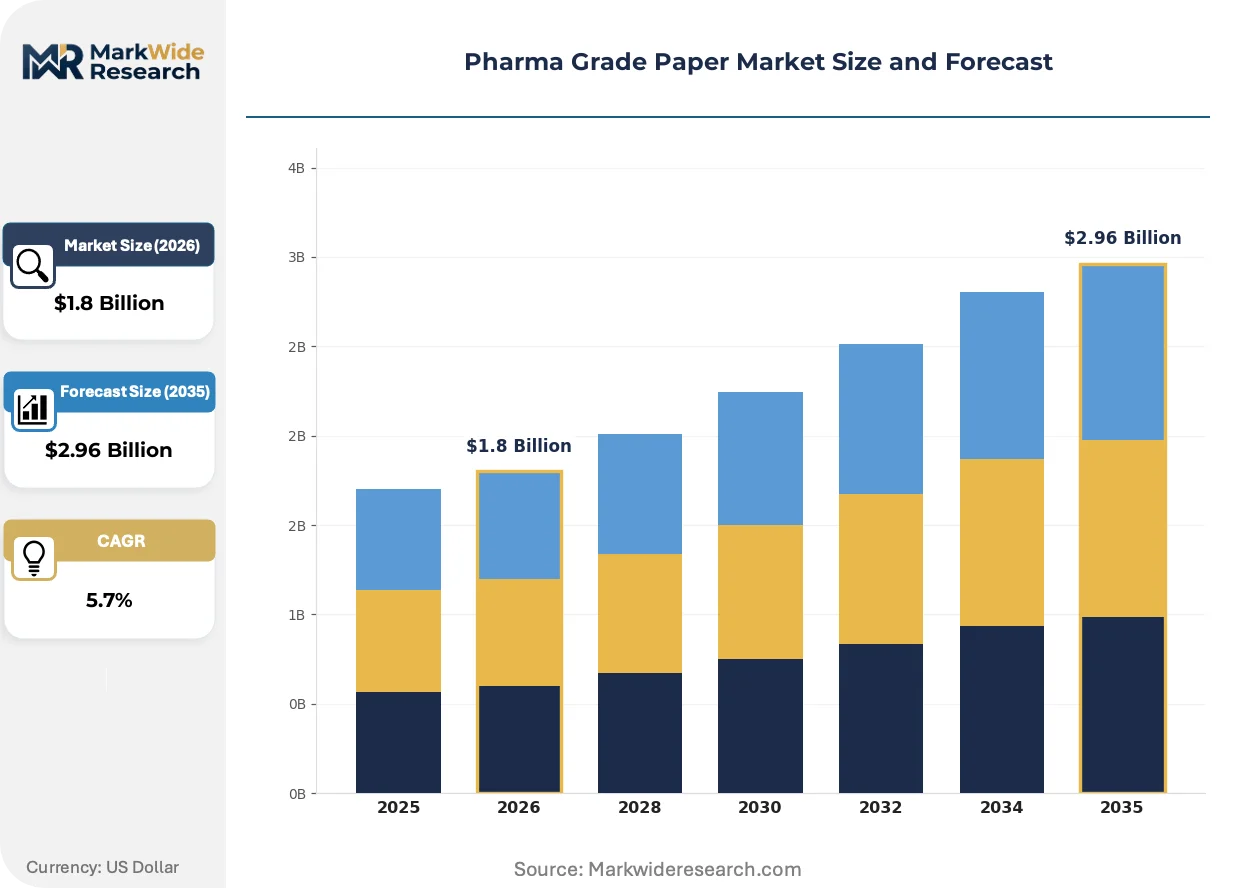
Market Dynamics
Pharmacopoeial harmonization pressures are fragmenting qualification protocols across FDA, EMA, and NMPA jurisdictions, forcing mills to maintain parallel certification tracks for the same substrate grades.
Growth Catalysts
- Track-and-trace serialization mandates:EU MDR and US DSCSA deadlines are accelerating demand for print-ready surfaces that accommodate 2D data matrices without compromising legibility.
- Biologics packaging expansion:Cold-chain requirements for monoclonal antibodies and mRNA therapies are driving specification upgrades for dimensional stability under thermal cycling.
- Germany's contract packaging concentration:Pan-European distribution hubs clustered around Frankfurt and Hamburg are consolidating purchasing power for compliant insert substrates.
Market Restraints
- Specialty pulp cost volatility:Dissolving-grade hardwood pulp prices fluctuate with viscose fiber demand, compressing margin predictability for alkaline-sized grades.
- Nordic supply concentration:Ahlstrom-Munksjö's captive pulp integration locks competitors out of equivalent fiber security, creating bottleneck risk for non-integrated converters.
- Extractables testing divergence:FDA USP <661> and EMA MDR employ incompatible analytical methods for leachable quantification, doubling qualification costs for dual-market suppliers.
Strategic Opportunities
- India's domestic pharma growth:CDSCO's tightening packaging material standards for export-compliant generics create upgrade demand among Mumbai and Hyderabad formulation clusters.
- Antimicrobial coating integration:Silver-ion and copper-based surface treatments are converging with base paper manufacturing to create single-step barrier grades for sterile packaging.
- Digital insert displacement:QR-code-linked electronic patient information leaflets are opening premium coated segments for high-visibility compliance graphics.
Industry Challenges
- ISO 15378 auditor scarcity:Qualified certification bodies for medicinal packaging quality management are backlogged 12-18 months in Asia-Pacific markets.
- Wet-end chemistry expertise gaps:Alkaline sizing and supercalendering process control requires specialized papermaking talent that retiring European mill workforces are not replacing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharma Grade Paper Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
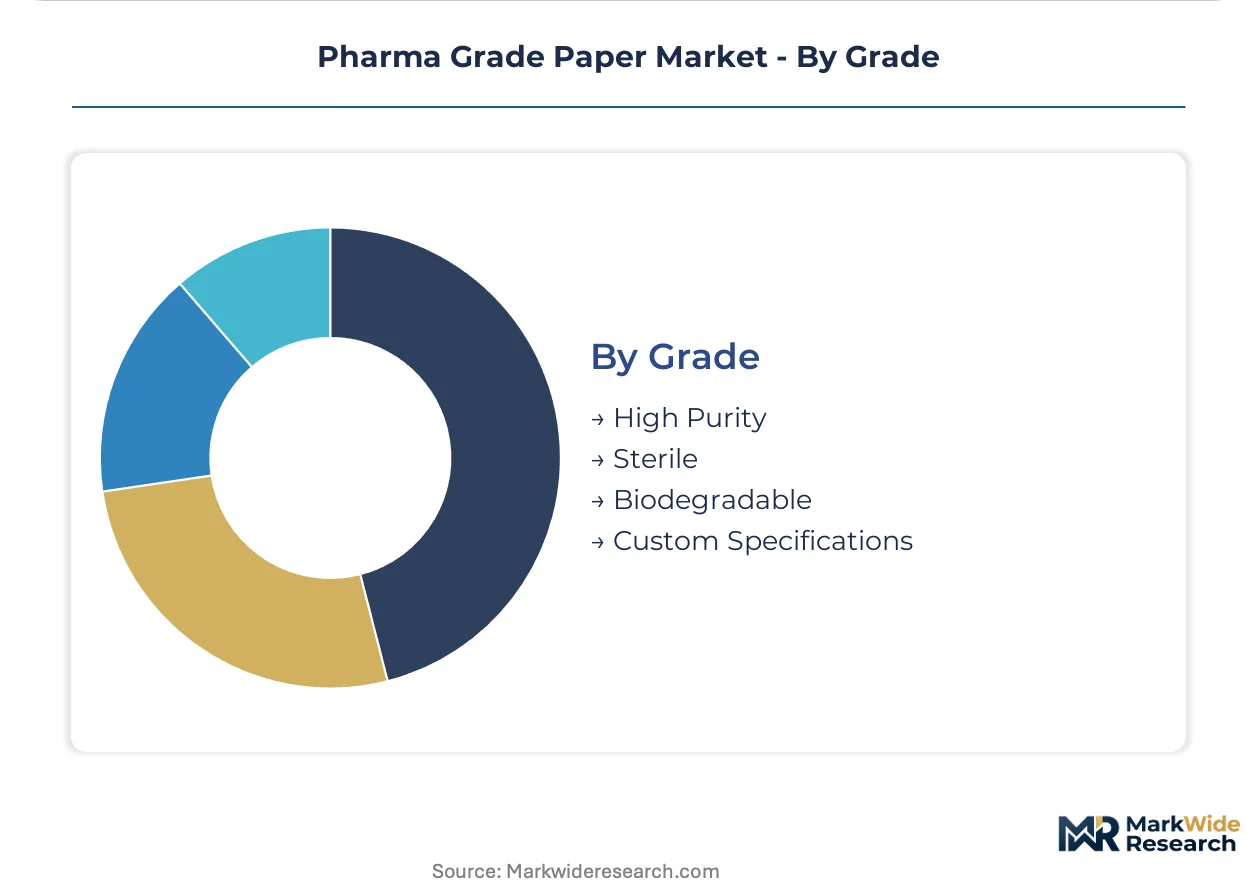
| Segmentation | Product Type: Coated Paper, Uncoated Paper, Specialty Paper, Label Stock Application: Pharmaceutical Packaging, Laboratory Use, Medical Forms, Sheets for Printing End User: Pharmaceutical Companies, Research Laboratories, Healthcare Institutions, Contract Manufacturers Grade: High Purity, Sterile, Biodegradable, Custom Specifications |
| Companies Covered | International Paper, Fedrigoni, Mondi Group, Georgia-Pacific, Stora Enso, Ahlstrom-Munksjö, BillerudKorsnäs, Smurfit Kappa, WestRock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharma Grade Paper Market Evolving Landscape
Active packaging functionality and regulatory data integrity requirements are converging to redefine substrate specifications beyond traditional purity metrics.
Barrier-coated pharma papers is consolidating multiple substrate functions into unified sheet structures. Blister pack lidding and cold-form foil replacements now integrate moisture vapor transmission control with print receptivity in single-pass coating operations. Major contract packaging organizations in Germany and Switzerland are qualifying these grades for high-value biologics, compressing the traditional multi-layer laminate supply chain into streamlined roll-fed formats.
EMA's MDR material traceability extensions are forcing batch-level genealogy documentation back to pulp harvest coordinates. Manufacturers must now map fiber provenance through every process stage to satisfy notified body audits. Secondary packaging suppliers serving European markets are responding by locking multi-year pulp contracts with certified sustainable forestry operations.
Serialization-ready surface specifications are reshaping converter procurement criteria. Variable-data inkjet and laser marking compatibility now ranks alongside pharmacopoeial purity in technical evaluations. Purchasing managers at pan-European drug distribution networks are consolidating supplier lists to favor mills with in-house coating and calendering control, eliminating toll-converted substrates from qualified vendor pools.
Pharma Grade Paper Market Segmentation
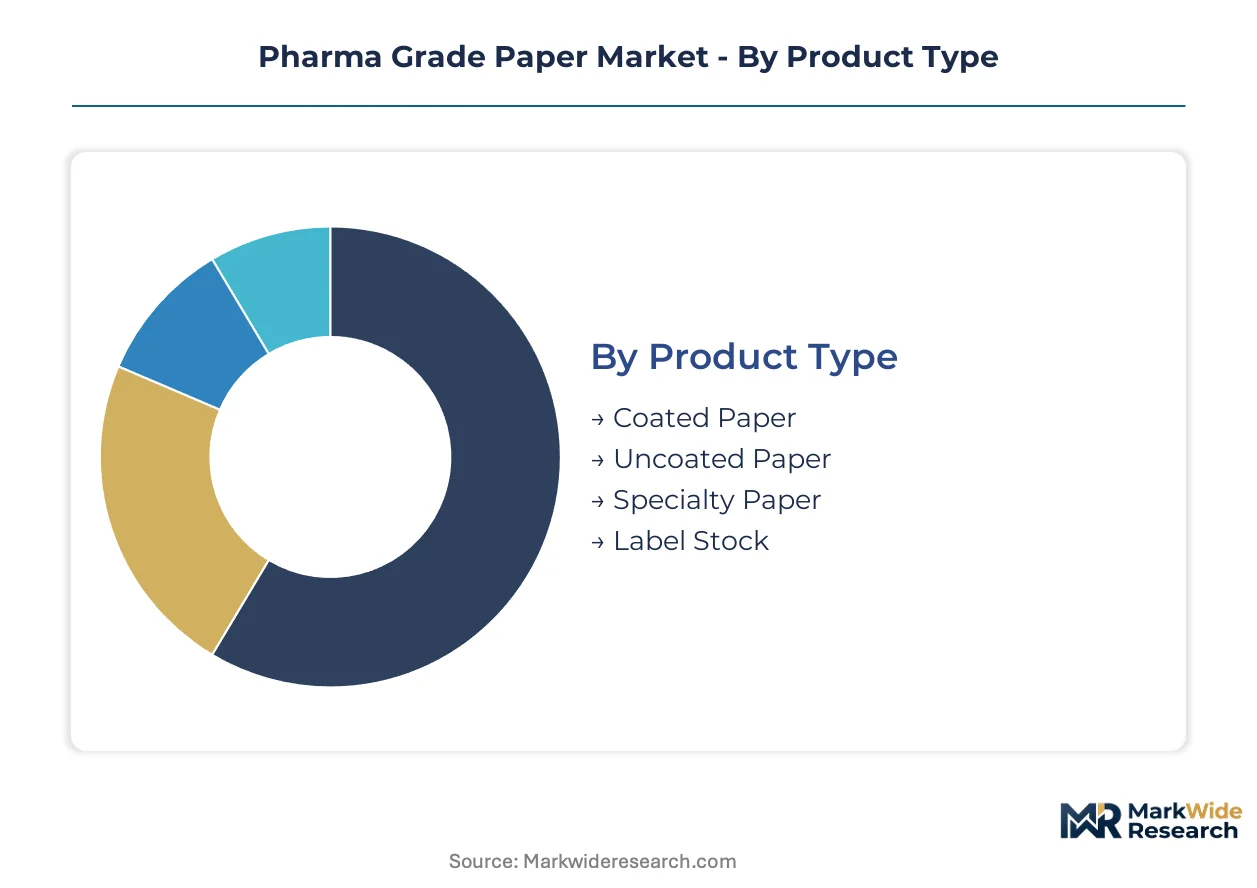
Pharma grade paper segmentation reflects divergent purity requirements across primary drug-contact surfaces and secondary packaging. Specification tiers separate blister pack lidding from insert substrates, while end-user consolidation in contract manufacturing reshapes procurement scale.
Product Type:
Upgrade cycles in pharmaceutical packaging are forcing converters to reassess substrate specifications against evolving pharmacopoeial standards.
- Specialty Paper:Engineered via controlled wet-end chemistry and supercalendering to achieve precise air permeability for serialization-ready surfaces. Demand concentrates in Germany's contract packaging clusters serving pan-European biologics distribution, driven by EU MDR track-and-trace mandates requiring 2D data matrix compatibility.
- Coated Paper:Premium grades receive barrier coatings and calendered finishes for high-resolution drug labeling. Mediterranean markets favor these substrates for patient information leaflets where pharmaceutical-grade print fidelity commands priority over cost minimization.
- Uncoated Paper:Alkaline-sized grades dominate secondary packaging inserts where extractables compliance meets budget constraints.
- Label Stock:Pressure-sensitive and wet-glue variants engineered for cold-chain adhesion under thermal cycling.
Uncoated paper sits at the top of the volume ranking, with specialty paper climbing the fastest.
Application:
Cost tier differentiation separates high-value biologics packaging from commoditized laboratory documentation.
- Pharmaceutical Packaging:Blister pack lidding, cold-form foil replacements, and insert substrates must satisfy FDA USP <661> extractables limits and EMA MDR material traceability. Frankfurt and Hamburg distribution hubs consolidate purchasing for compliant grades.
- Laboratory Use:Filter papers, chromatography sheets, and diagnostic substrates require low bioburden certification.
- Medical Forms:Prescription pads and patient records demand tamper-evident features and archival stability.
- Sheets for Printing:Variable-data inkjet compatibility now ranks alongside dimensional stability in technical evaluations.
Pharmaceutical packaging holds the dominant revenue share, with sheets for printing gaining share fastest.
End User:
Customer type concentration is shifting procurement power toward outsourced manufacturing networks.
- Contract Manufacturers:Pan-European packaging organizations in Germany and Switzerland qualify unified roll-fed substrates to compress multi-layer laminate supply chains. ISO 15378 certification requirements filter supplier pools to mills with in-house coating control.
- Pharmaceutical Companies:Multinationals maintain parallel qualification tracks for FDA, EMA, and NMPA jurisdictions.
- Research Laboratories:Academic and clinical trial sites prioritize batch-level genealogy documentation for audit trails.
- Healthcare Institutions:Hospital pharmacies and central fill operations source pre-printed compliance packaging.
Contract manufacturers command the steepest expansion trajectory, with pharmaceutical companies retaining the largest absolute spend.
Grade:
Margin stratification follows certification intensity from standard purity to sterile barrier specifications.
- High Purity:Dissolving-grade hardwood pulp substrates meet pharmacopoeial limits for extractables and leachables. Nordic integrated mills leverage captive fiber security to control specialty paper purity from forest to finished roll.
- Sterile:Gamma-irradiated or ethylene oxide-treated grades for aseptic filling lines require validated microbial bioburden documentation.
- Biodegradable:Cellulose-based alternatives to synthetic barriers respond to EU Green Deal packaging waste directives.
- Custom Specifications:Tailored alkaline sizing and barrier coatings for monoclonal antibody cold-chain requirements.
High purity grades anchor volume demand, with sterile specifications expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt and Hamburg anchor pan-European pharmaceutical packaging demand through contract manufacturing clusters serving biologics distribution networks across the continent.
Germany
Contract packaging organizations around Frankfurt and Hamburg consolidate purchasing power for FDA USP <661> and EMA MDR compliant insert substrates. EMA's MDR material traceability extensions force batch-level genealogy documentation back to pulp harvest coordinates. Mills serving these hubs maintain ISO 15378 certification and captive Nordic pulp integration to secure qualified supplier status.
United States
FDA enforces USP <661> container closure system guidelines that constrain paper composition for drug-contact blister pack lidding applications. The US DSCSA serialization deadlines accelerate demand for print-ready surfaces accommodating 2D data matrices. New Jersey and North Carolina formulation clusters drive specification upgrades for cold-chain biologics packaging.
India
CDSCO's tightening packaging material standards for export-compliant generics create upgrade demand among Mumbai and Hyderabad formulation clusters. Domestic pharma growth pushes converters toward pharmacopoeial-grade substrates previously imported from European mills. Karnataka and Telangana packaging hubs are qualifying local suppliers for ISO 15378 certification to reduce import dependency.
China
NMPA extractables testing protocols diverge from FDA and EMA methods, forcing parallel qualification tracks for dual-market suppliers. Shanghai and Jiangsu province biologics manufacturers drive demand for high-purity grades with validated microbial bioburden documentation. The country's national pharmaceutical regulator is tightening material traceability requirements for secondary packaging exports to European markets.
Switzerland
Swissmedic oversight of sterile packaging applications drives specification premiums for gamma-irradiated grades serving aseptic filling lines. Basel and Zurich contract packaging organizations qualify unified roll-fed substrates to compress multi-layer laminate supply chains. Mills with in-house coating and calendering control capture preferred vendor status for high-value monoclonal antibody packaging.
Pharma Grade Paper Market Competitive Landscape
Global majors compete with regional champions across certification intensity and fiber integration depth. The vendor base stratifies between Nordic integrated pulp producers and toll-dependent Central European converters. Three archetypes dominate: captive pulp specialists controlling purity from forest to finished roll, coating-integrated mills with serialization-ready surface capabilities, and regional converters leveraging geographic proximity to EMA-notified body clusters. Competitive moves concentrate on multi-year pulp contracting for certified sustainable forestry and in-house supercalendering investments to eliminate toll-converted substrates from qualified vendor pools.
Within the Nordic integrated tier, Ahlstrom-Munksjö and Stora Enso exemplify fiber security strategies that lock competitors out of equivalent supply chain control. Mondi Group anchors Central European production with integrated kraft pulp capacity serving pharmaceutical converters. These three occupy positions where pharmacopoeial compliance and process control capabilities converge to create de facto market-access thresholds.
| Leading Market Players |
|---|
| International Paper |
| Fedrigoni |
| Mondi Group |
| Georgia-Pacific |
| Stora Enso |
| Ahlstrom-Munksjö |
| BillerudKorsnäs |
| Smurfit Kappa |
| WestRock |
| Others |
Value Network & Pricing Analysis
Family-owned Nordic pulp producers anchor supply-side discipline through captive fiber integration, translating upstream cost control into stable pricing for pharmacopoeial-grade substrates while insulating contract manufacturers from dissolving-grade hardwood pulp volatility.
Pricing Analysis
Dissolving-grade hardwood pulp pass-through mechanics dominate cost structures for alkaline-sized grades, with specialty paper commanding widest margins through custom barrier coatings and serialization-ready surfaces. Price differentiation separates ISO 15378-certified mills with in-house supercalendering from toll-dependent converters facing qualification cost doubling. Pricing pressure stems from EMA-FDA extractables testing divergence compressing margins for dual-market suppliers. Contract manufacturers in Germany exhibit lowest price sensitivity due to consolidated purchasing power, while research laboratories prioritize cost minimization over certification premiums.
Supply Chain Analysis
Reverse-logistics flows for gamma-irradiated sterile grades require validated cold-chain documentation back to pulp harvest coordinates, complicating batch-level genealogy for secondary packaging exports. Supply concentrates in Finland, Sweden, and Germany through Ahlstrom-Munksjö's Nordic integration and Mondi's Central European kraft capacity. Raw material dependencies center on dissolving-grade hardwood pulp, certified sustainable softwood fiber, and specialty barrier coating chemistries. Single-source vulnerability from Nordic pulp concentration locks non-integrated converters out of equivalent fiber security. Distribution runs through Frankfurt and Hamburg contract packaging hubs serving pan-European biologics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate between India's CDSCO tightening for export-compliant generics and Europe's EMA MDR material traceability extensions, where cost differentials in qualification timelines reward early local supplier qualification in Mumbai and Hyderabad clusters.
For Market Incumbents: Deploy captive pulp integration as the primary defensive lever against specialty pulp cost volatility threatening margin predictability. Consolidate multi-year certified sustainable forestry contracts to preempt Nordic supply concentration risks from bottlenecking non-integrated competitors. Reinforce ISO 15378 certification depth to filter toll-converted substrates from qualified vendor pools at pan-European contract packaging organizations. For New Entrants and Emerging Players: CDSCO's tightening packaging material standards in India open a window for domestic mill qualification serving Mumbai and Hyderabad formulation clusters previously dependent on European imports. Target antimicrobial coating integration for sterile packaging applications where silver-ion surface treatments converge with base paper manufacturing. Pursue toll-converter partnerships with established Nordic pulp suppliers to bypass captive fiber integration barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among coating-integrated mills with serialization-ready surface capabilities but without full Nordic pulp integration. Five-to-ten-year viability hinges on pharmacopoeial harmonization between FDA, EMA, and NMPA jurisdictions resolving extractables testing divergence. Monitor CDSCO auditor backlog reduction in Asia-Pacific markets as inflection signal for qualification capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dissolving-Grade Pulp | Ahlstrom-Munksjö's Nordic fiber security locks competitors out of equivalent supply chain control. |
| ISO 15378 Certification Investment | EMA-notified body audits filter supplier pools to mills with validated quality management systems. |
| Antimicrobial Coating Convergence | Silver-ion surface treatments integrate with base paper manufacturing for sterile barrier grades. |
| Serialization-Ready Surface Development | EU MDR track-and-trace mandates demand 2D data matrix compatibility without legibility compromise. |
| Multi-Year Sustainable Forestry Contracting | Batch-level genealogy documentation requirements force pulp provenance mapping to harvest coordinates. |
Research Methodology
Direct dialogue with pharmaceutical packaging procurement managers, regulatory affairs leads at contract manufacturing organizations, mill technical directors, and EMA-notified body auditors grounded qualitative findings in operational reality. Secondary validation drew from FDA USP filings, EMA MDR submission databases, ISO certification registries, and customs trade data for dissolving-grade pulp flows. Bottom-up mill capacity modeling and top-down pharmaceutical packaging demand estimation were triangulated against contract manufacturer purchasing data.
Segmentation outputs across specialty, coated, and uncoated product types; pharmaceutical packaging, laboratory, and medical form applications; contract manufacturer and pharmaceutical company end users; and high-purity, sterile, and biodegradable grades were modeled across the projection horizon. CAGRs were derived from volume-weighted average growth rates calibrated to pharmacopoeial standard evolution timelines and biologics cold-chain packaging upgrade cycles. Forecast inputs incorporated EU MDR serialization deadline compliance curves and CDSCO packaging material standard tightening trajectories.
Revisions become necessary when pharmacopoeial harmonization between FDA, EMA, and NMPA materializes faster or slower than baseline assumptions, or when dissolving-grade hardwood pulp price volatility exceeds historical bands. Practitioners should monitor auditor availability at Asia-Pacific certification bodies and Nordic pulp integration expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Compressed Fiberboard Market
Paper Products
Global Paperboard Market
Paper Products
Abaca Pulp Market
Paper Products
Medical Grade Paper Market
Paper Products
Pp Synthetic Paper Market
Paper Products
Solar Paper Market
Paper Products
Thin Printing Paper Market
Paper Products
Global Paper Chemical Market
Paper Products
Paper Doilies Market
Paper Products
North America Decor Paper Market
Paper Products
Synthetic Paper Market
Paper Products
Global Kraft Paper Market
Paper Products
Paper Goods Market
Paper Products
Industrial Paper Shredder Machine Market
Paper Products
Coated Wood Free Papers Market
Paper Products
Wood Paper and Paperboard Recycling Market