
 Graphene Oxide (GO) Market | 2026-2036
Graphene Oxide (GO) Market Size, Share, and Industry Trends Forecast 2026-2036
Graphene Oxide (GO) Market Foresight
Software-defined coating formulations is hardening as a recurring revenue layer atop raw GO powder sales. Graphenea sustains European production leadership through specialized dispersion manufacturing. The Sixth Element Materials Technology Co., Ltd. dominates domestic supply chains in China with integrated powder-to-film operations. NanoXplore Inc. leverages Canadian graphite feedstock access to anchor North American dispersion quality.
Graphene oxide consists of a single-atom-thick carbon lattice functionalized with oxygen-containing groups, typically produced via modified Hummers oxidation of graphite with subsequent exfoliation; its hydrophilic surface and tunable bandgap enable conductive films, barrier coatings, and adsorbent membranes for industrial separation processes. Dispersion formulations command premium pricing due to batch consistency requirements from electronics buyers, while powder grades face margin compression from commoditization in composite filler applications. Energy storage applications represent the fastest-expanding demand pool as solid-state battery developers specify GO interlayers for dendrite suppression.
EPA drinking water standards and the EU REACH authorization framework constrain which GO chemistries enter commercial water treatment and consumer product channels. China's GB standards for nanomaterial classification add registration burdens for imported dispersions. BIS certification requirements in India create parallel compliance tracks for construction-grade GO additives. Stakeholders must monitor evolving toxicity dossiers from ECHA and EPA to anticipate which functionalization chemistries retain market access.
Market Dynamics
Software-defined coating formulations are hardening as a recurring revenue layer atop raw GO powder sales, compressing margins for undifferentiated suppliers while rewarding batch-consistent dispersion manufacturers with multi-year supply agreements.
Growth Catalysts
- EPA filtration mandates:Drinking water utilities in the United States face upgraded membrane procurement requirements under tightened filtration standards, accelerating GO membrane adoption for contaminant removal.
- Solid-state battery commercialization:Energy storage developers specify GO interlayers for dendrite suppression in next-generation cells, creating a high-specification demand channel.
- Shanghai-Shenzhen industrial clustering:China's integrated powder-to-film manufacturing corridors reduce logistics costs and enable rapid prototype-to-scale transitions for electronics buyers.
Market Restraints
- Graphite feedstock volatility:Spherical graphite price swings from Canadian and African mines compress dispersion margins unpredictably.
- ECHA authorization bottlenecks:REACH dossier requirements for novel functionalization chemistries delay market entry by 18-36 months.
- Reduced graphene oxide substitution:Thermal reduction processes yielding rGO compete for barrier coating applications at lower unit costs.
Strategic Opportunities
- Indian construction additives:BIS certification tracks for cement and concrete reinforcement applications remain underdeveloped relative to material performance potential.
- EU Green Deal procurement incentives:Public tender preferences for low-carbon membrane technologies favor GO-based filtration in municipal water projects.
- AI-assisted formulation design:Machine learning convergence with high-throughput characterization accelerates dispersion stability optimization for specialty electronics.
Industry Challenges
- Exfoliation technician scarcity:Modified Hummers process expertise concentrates in aging workforce cohorts across European and North American facilities.
- Batch-to-batch certification delays:Electronics buyers require six-month qualification cycles for each dispersion lot, freezing working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphene Oxide (GO) Market |
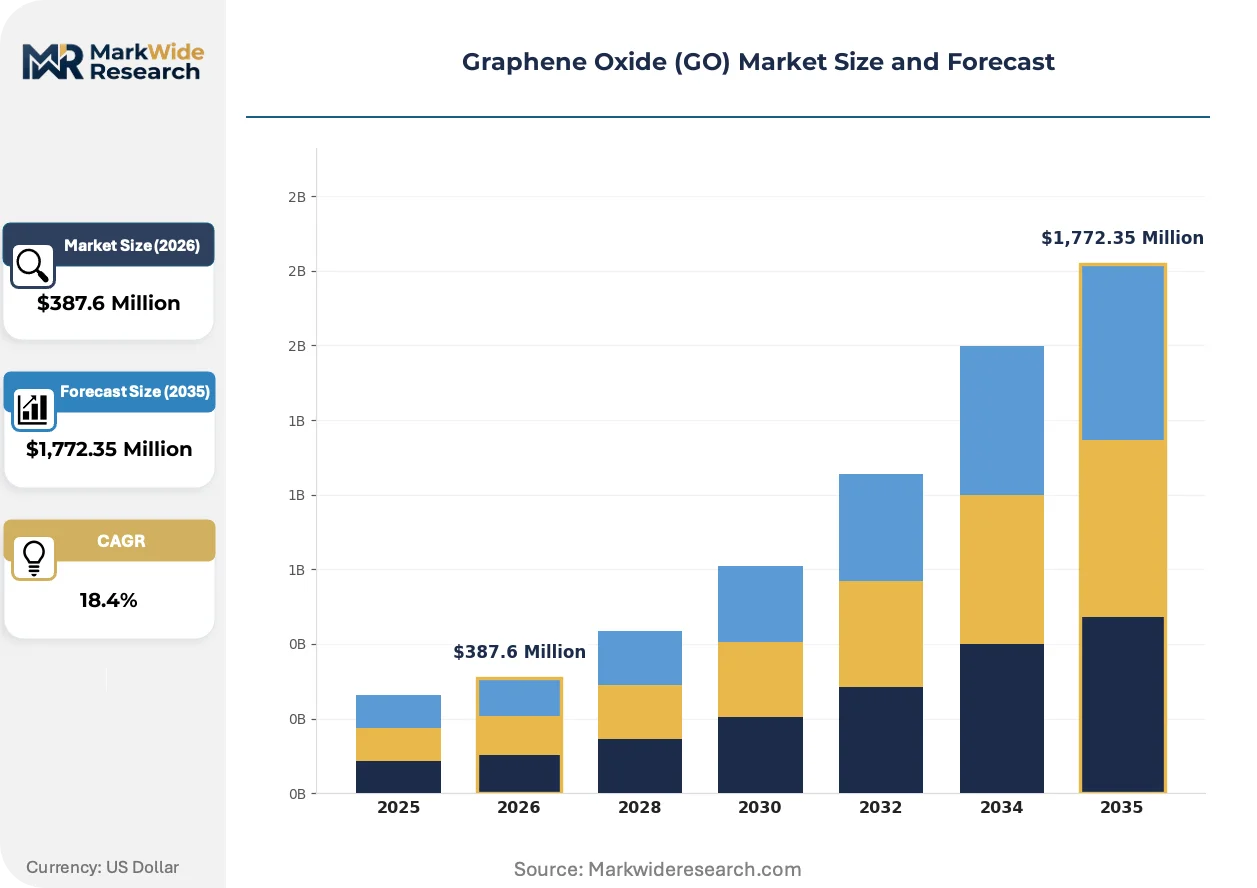
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dispersion, Powder, Film, Coating Application: Electronics, Energy Storage, Composites, Water Treatment End User: Aerospace, Automotive, Healthcare, Construction Distribution Channel: Direct Sales, Distributors, E-commerce, Retail |
| Companies Covered | Global Graphene Group, Graphenea, Abalonyx AS, The Sixth Element Materials Technology Co., Ltd., NanoXplore Inc., Haydale Graphene Industries plc, First Graphene Ltd., ACS Material, LLC, Garmor Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphene Oxide (GO) Market Shifts & Advancements
Active reformulation of GO products around software-defined specifications is compressing traditional sales cycles and forcing raw powder suppliers to develop service-layer capabilities or exit premium segments entirely.
Electrochemical exfoliation is modularizing production architectures for graphene oxide dispersions. Battery-grade manufacturers in South Korea and Japan adopt containerized, skid-mounted systems that reduce capital intensity for mid-volume producers. This technology is modularizing quality control protocols, enabling real-time conductivity adjustment that previously required centralized pilot facilities.
REACH authorization frameworks for nanomaterial classifications are tightening substance-by-substance scrutiny across the European Union. Industrial chemical registrations now require extended toxicity dossiers that delay new functionalization chemistries. Water treatment membrane suppliers respond by pre-certifying existing oxidation grades rather than pursuing novel surface modifications.
Specification-led procurement now dominates electronics and energy storage channels, displacing spot-market purchasing for GO dispersions. Buyers consolidate supplier lists to three qualified vendors per geography, demanding dedicated quality engineers and co-development agreements. This concentration is most visible in German automotive battery supply chains, where cell manufacturers enforce single-source dispersion partnerships with audit rights over production batches.
Graphene Oxide (GO) Market Segmentation
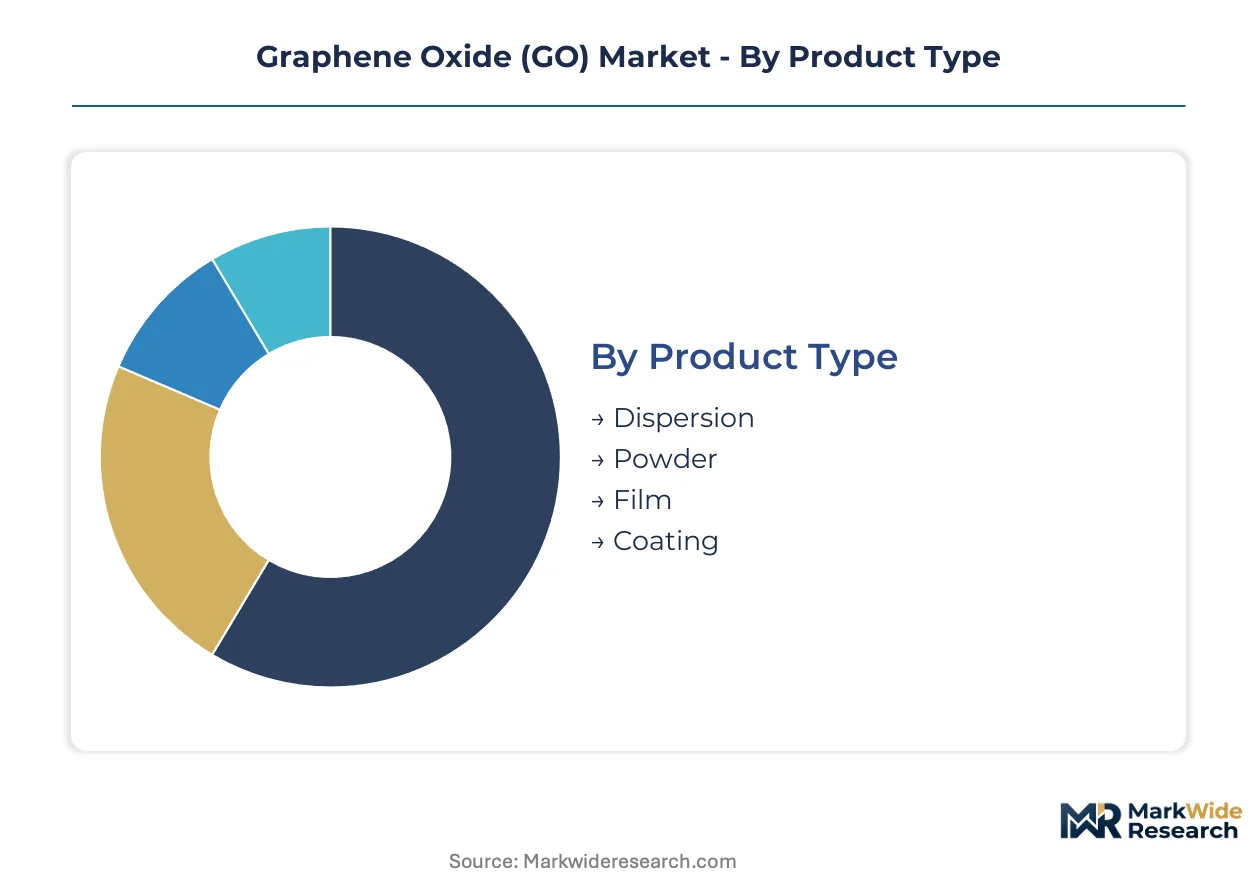
GO procurement patterns diverge sharply between specification-driven electronics channels and price-sensitive composite filler markets. Buyers in energy storage and water treatment impose distinct technical qualification protocols that reshape supplier economics across each segment tier.
Product Type:
Upgrade cycles in electronics manufacturing are compressing qualification timelines and favoring pre-certified dispersion suppliers over raw powder vendors.
- Dispersion:Liquid formulations with controlled flake size distribution and surface functionalization enable direct inkjet printing and slot-die coating without secondary processing. Battery cell manufacturers in South Korea and Japan specify these for dendrite-suppressing interlayers, locking in multi-year supply agreements with audit rights over batch records.
- Powder:Freeze-dried or spray-dried aggregates requiring redispersion before use dominate composite filler applications. Automotive Tier 1s in Germany purchase powder grades for thermoplastic masterbatching, though margin compression from Chinese commoditization is forcing European suppliers toward value-added surface treatments.
- Film:Cast or vacuum-filtered self-supporting membranes serve barrier and filtration applications. Water treatment utilities in California specify these for EPA-compliant contaminant removal systems.
- Coating:Pre-formulated liquid systems with binder chemistries tailored to substrate adhesion. Aerospace maintenance facilities in France apply these for corrosion protection on aluminum airframes.
Volume placements concentrate in Powder; the faster expansion belongs to Dispersion.
Application:
Cost tiering separates premium specification channels from bulk material procurement, with electronics and energy storage commanding 3-5x pricing multiples over composite fillers.
- Electronics:Transparent conductive films and printed circuit interconnects require sub-5nm thickness control and sheet resistance below 100 ohm/sq. Display manufacturers in Taiwan qualify dispersion lots through six-month certification cycles before production integration.
- Energy Storage:Solid-state battery developers specify GO interlayers for lithium dendrite suppression and electrolyte compatibility. Cell producers in Germany enforce single-source partnerships with dedicated quality engineers stationed at supplier facilities.
- Composites:Polymer matrix reinforcement for mechanical property enhancement at loadings of 0.1-1.0 wt%. Construction material suppliers in India pursue BIS certification for cement additive applications.
- Water Treatment:Membrane separation layers exploiting hydrophilic surface chemistry for organic contaminant adsorption. Municipal utilities in Texas procure these under tightened EPA filtration mandates.
Electronics commands premium pricing; Energy Storage is climbing the fastest.
End User:
Customer-type concentration in automotive and aerospace is consolidating supplier lists to three qualified vendors per geography with co-development agreement requirements.
- Aerospace:Lightweight structural composites and lightning strike protection for carbon fiber reinforced polymers. OEMs in Washington State specify GO-enhanced prepregs for next-generation narrowbody programs.
- Automotive:Battery pack thermal management films and body panel coatings. German cell manufacturers anchor European demand through integrated powder-to-film supply chains.
- Healthcare:Biosensor electrodes and antimicrobial surface treatments. FDA device clearance pathways constrain which oxidation grades enter diagnostic applications.
- Construction:Cement reinforcement and corrosion-resistant coatings for infrastructure. Indian contractors face BIS registration requirements for nanomaterial additives in public works.
Automotive absorbs the largest volume; Healthcare shows the steepest expansion trajectory.
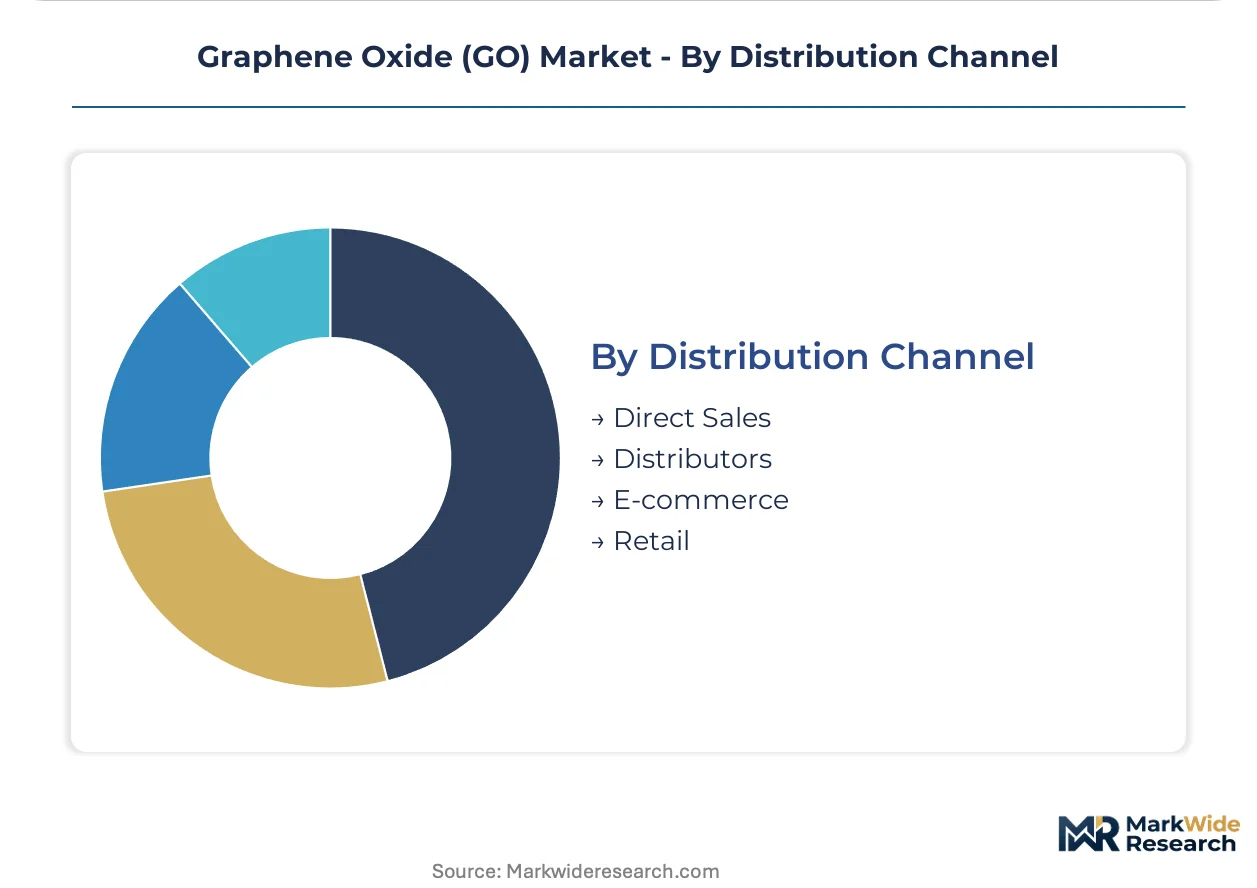
Distribution Channel:
Supply concentration in direct sales to qualified accounts is displacing spot-market purchasing as specification-led procurement dominates premium segments.
- Direct Sales:Technical field support and joint formulation development for qualified electronics and battery accounts. Graphenea maintains European leadership through specialized dispersion manufacturing with dedicated customer laboratories.
- Distributors:Regional inventory holding and local technical service for mid-volume composite and construction buyers. Channels in Brazil face ANVISA import registration requirements for nanomaterial classifications.
- E-commerce:Small-lot procurement for research institutions and prototype developers. Alibaba and specialty chemical platforms serve Chinese industrial clusters around Shanghai and Shenzhen.
- Retail:Consumer-grade coatings and hobbyist composites through hardware and specialty stores. This channel remains marginal due to REACH and EPA constraints on uncertified nanomaterial sales.
Direct Sales captures the value; E-commerce is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of graphene oxide powder feedstock, while consumption concentrates in German battery supply chains and US water treatment infrastructure. This geographic split creates logistics arbitrage for dispersion specialists with multi-regional formulation labs.
United States
EPA filtration mandates are accelerating GO membrane procurement by municipal utilities in Texas and California. The Safe Drinking Water Act enforcement timeline pressures treatment facilities toward advanced separation technologies. Industrial buyers in the Pacific Northwest qualify dispersion lots through extended certification cycles for electronics applications.
Germany
Automotive cell manufacturers enforce single-source dispersion partnerships with embedded quality engineers at supplier sites. ECHA REACH authorization requirements delay novel functionalization chemistries by 18-36 months. The Rhine-Ruhr industrial corridor anchors European demand through integrated powder-to-film supply chains serving battery pack producers.
China
Shanghai-Shenzhen manufacturing clusters reduce logistics costs for electronics buyers requiring rapid prototype-to-scale transitions. GB standards for nanomaterial classification impose registration burdens on imported dispersions. Domestic producers dominate through captive graphite feedstock access and backward integration into spherical graphite refining.
Japan
Solid-state battery developers specify GO interlayers for dendrite suppression in next-generation cell architectures. METI technology roadmaps prioritize domestic dispersion manufacturing to reduce import dependency. Kansai-based chemical conglomerates maintain qualification partnerships with South Korean electrolyte suppliers.
India
Construction material suppliers pursue BIS certification for cement additive applications in public infrastructure projects. The PLI scheme for advanced chemistry cell manufacturing creates downstream demand for battery-grade dispersions. Industrial clusters in Gujarat and Maharashtra experiment with GO-reinforced concrete for highway and bridge construction.
Graphene Oxide (GO) Market Competitive Landscape
Top-tier vendors anchor premium dispersion supply, while undifferentiated powder suppliers face margin compression from commoditization. The vendor base stratifies across three archetypes: integrated graphite-to-dispersion operators, specialized formulation laboratories, and regional composite filler distributors. Competitive positioning hardens through multi-year supply agreements with audit rights, while geographic expansion and technology licensing dominate mid-tier strategic moves.
Within the integrated manufacturing tier, The Sixth Element Materials Technology Co., Ltd. and NanoXplore Inc. exemplify feedstock-captive production models. Graphenea occupies a position representing specialized dispersion manufacturing with dedicated customer laboratory infrastructure. These three anchors illustrate how quality consistency and regulatory pre-certification separate premium-tier suppliers from commodity powder vendors competing on volume pricing.
| Leading Market Players |
|---|
| Global Graphene Group |
| Graphenea |
| Abalonyx AS |
| The Sixth Element Materials Technology Co., Ltd. |
| NanoXplore Inc. |
| Haydale Graphene Industries plc |
| First Graphene Ltd. |
| ACS Material, LLC |
| Garmor Inc. |
| Others |
Supply & Pricing Matrix
Electrochemical exfoliation modularization is compressing capital requirements for mid-volume producers while fragmenting supply concentration across containerized production sites. This technology shift enables real-time conductivity adjustment that previously demanded centralized pilot facilities, reshaping cost economics for dispersion manufacturers in South Korea and Japan while loosening geographic lock-in for battery-grade supply.
Pricing Analysis
Margin tightening in powder grades reflects Chinese commoditization pressure as integrated producers flood composite filler channels. Three-tier pricing structure across premium, standard, and economy levels separates batch-certified dispersions for electronics from construction-grade powders and research-scale samples. Cost-down pressure on standard grades accelerates because automotive Tier 1s in Germany consolidate supplier lists and demand audit rights. Composite buyers exhibit highest price sensitivity; energy storage cell manufacturers accept premium positioning for dendrite-suppressing interlayers.
Supply Chain Analysis
Dual-sourcing mandates from German automotive cell manufacturers require qualified dispersion suppliers in at least two geographies, typically pairing European formulation labs with Asian production sites. Feedstock draws from Chinese spherical graphite refining, Canadian flake graphite mining, and African vein graphite extraction. Single-source vulnerability concentrates in modified Hummers process expertise aging across European and North American facilities. Distribution runs through direct technical sales for qualified accounts, with regional distributors serving mid-volume composite buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization timelines and EPA toxicity dossier requirements erect compliance moats that reward pre-certified incumbents while delaying novel functionalization entrants by 18-36 months.
For Market Incumbents: Deploy captive feedstock integration to secure spherical graphite supply against African and Canadian mine volatility. Pre-certify existing oxidation grades for water treatment channels rather than pursuing novel surface modifications that trigger extended ECHA review. Consolidate dispersion manufacturing capacity in the Rhine-Ruhr corridor to serve German automotive single-source partnerships. For New Entrants and Emerging Players: Enter via Indian construction additive channels where BIS certification tracks remain underdeveloped relative to material performance potential. Target cement reinforcement applications in Gujarat and Maharashtra infrastructure projects. Pursue technical service partnerships with regional distributors rather than direct sales qualification cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated graphite-to-dispersion operators seeking formulation laboratory capabilities. Long-term viability hinges on regulatory pre-certification assets rather than raw production capacity. Watch for ECHA authorization bottlenecks easing as indicative signal for novel chemistry market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spherical Graphite | Captive feedstock secures margin against Canadian and African mine price swings. |
| REACH Pre-Certification Investment | Existing oxidation grades bypass 18-36 month ECHA authorization delays for water treatment channels. |
| Joint Venture with German Cell Manufacturers | Single-source partnerships with embedded quality engineers lock in multi-year dispersion supply agreements. |
| AI-Assisted Formulation Design | Machine learning convergence accelerates dispersion stability optimization for specialty electronics buyers. |
| Indian BIS Certification Track Development | First-mover advantage in cement additive registration captures public infrastructure procurement. |
Research Methodology
Multi-period observation of EPA filtration mandate implementation, ECHA authorization timelines, and solid-state battery commercialization milestones anchored the trend analysis, supplemented by interviews with dispersion manufacturing plant managers, procurement leads at German automotive Tier 1s, water treatment utility engineers, and technical R&D directors at South Korean cell producers. Secondary validation drew from EPA Safe Drinking Water Act enforcement records, ECHA REACH dossier databases, customs trade data for graphite feedstock flows, and SEC filings of listed graphene material suppliers. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, and end user dimensions.
Input-output matrix modeling connected spherical graphite feedstock pricing, electrochemical exfoliation capital costs, and dispersion formulation batch yields to downstream segment demand. Segmentation dimensions included product grade tier, end-use industry channel, functionalization chemistry type, and regional regulatory cluster. CAGRs were derived from fitted growth curves against observed procurement patterns. Industry-specific forecast inputs incorporated solid-state battery commercialization roadmaps and municipal water infrastructure replacement cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ECHA authorization suspensions or graphite export restriction scenarios. Model assumptions reflect documented regulatory timelines and technology readiness assessments. A model refresh is warranted upon material change in EPA filtration standard enforcement pace or solid-state battery dendrite suppression specification shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Europe Silicon Carbide Market
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Polymethylhydrosiloxane Market
Semiconductor Material
High Purity Germanium (Ge) Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Europium Market
Semiconductor Material
Organic Silicon Coating Market
Semiconductor Material
PV Module Encapsulant Film Market
Semiconductor Material
PP Capacitor Films Market
Semiconductor Material
United States Sapphire Glass Market
Semiconductor Material
Global Scintillator Market
Semiconductor Material
Terbium Oxide Market
Semiconductor Material
North America Semiconductor Materials Market
Semiconductor Material
Electronic Thermal Management Materials Market
Semiconductor Material
Acetylene Black Market
Semiconductor Material
Electronic-Grade Polysilicon Market