
 Platter Substrate Materials Market | 2026-2036
Platter Substrate Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Platter Substrate Materials Market Analysis
Hyperscale data center operators is reorganizing procurement priorities around archival-grade storage substrates, shifting volume away from consumer electronics buyers. SCHOTT AG leverages its glass-ceramic formulation expertise to dominate optical disc substrate supply for medical imaging archives. IBIDEN Co. Ltd. anchors the Asia-Pacific supply base through advanced alumina sintering capacity dedicated to hard disc drive applications. Showa Denko K.K. competes on silicon epitaxy integration, positioning its substrates for next-generation heat-assisted magnetic recording heads.
Platter substrate materials are precision-engineered wafers or discs—typically alumina, glass, silicon, or quartz composites manufactured to sub-micron flatness tolerances—that serve as mechanical and thermal foundations for magnetic or optical data recording layers. Sintered alumina substrates currently occupy the largest volume share in hard disc drive manufacturing due to cost-scalability and fracture toughness, while chemically strengthened glass variants are capturing margin pools in enterprise nearline storage where vibration resistance and thermal stability command premium positioning. Etching and coating process segments are expanding fastest as manufacturers pursue thinner substrates with enhanced surface topology control for areal density gains.
Japan's METI enforces JIS standards on substrate dimensional precision for domestic electronics supply chains, while the EU REACH regulation restricts hazardous substances in coating chemistries used for protective overcoats. The US EPA oversees emissions from sintering furnaces and machining operations at substrate fabrication facilities. Buyers must monitor evolving RoHS exemptions for lead-containing glass formulations and assess supplier readiness for EU CSRD supply chain disclosure requirements before committing to long-term substrate procurement contracts.
Market Dynamics
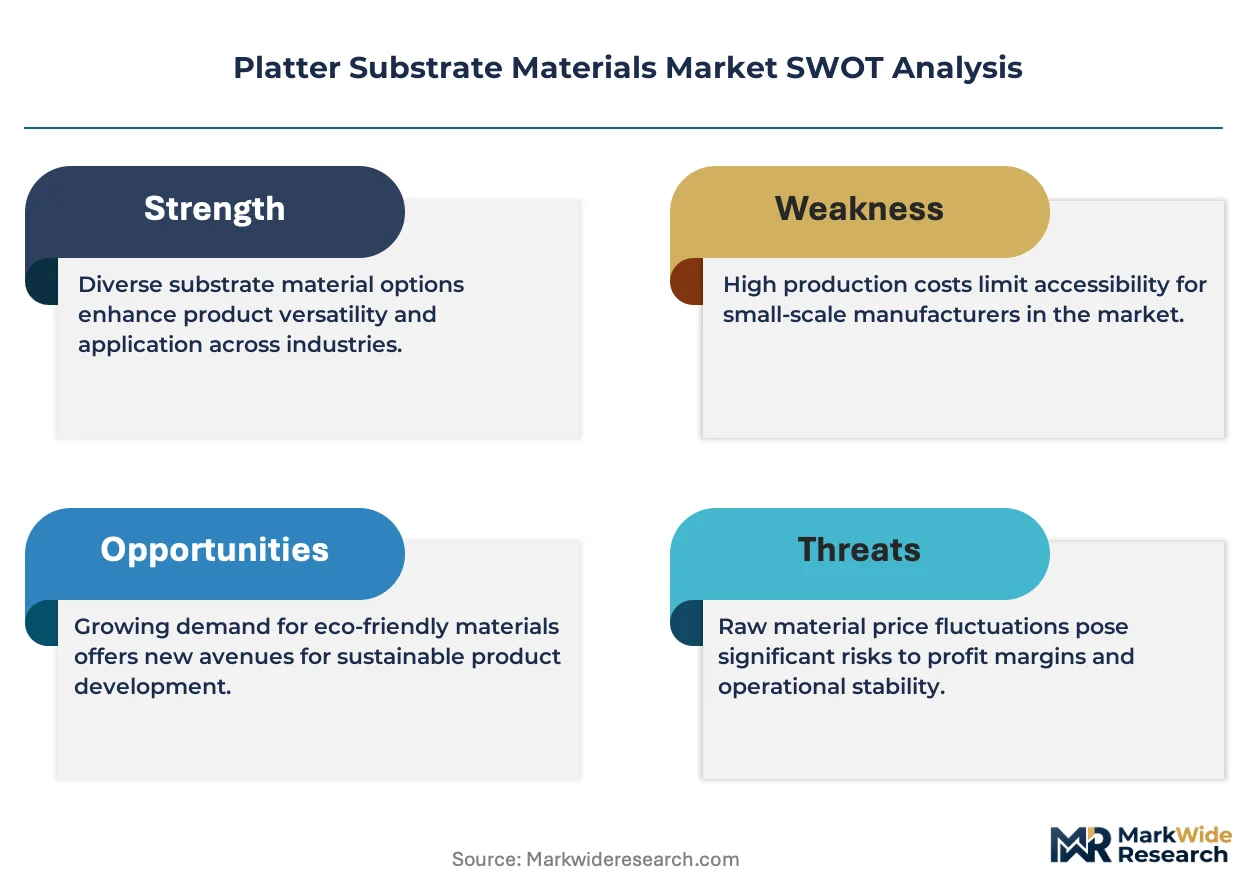
Heat-assisted magnetic recording (HAMR) technology deployment is compressing substrate flatness tolerances below 0.5 nanometers, forcing manufacturers to retool sintering and polishing lines for chemically strengthened glass-ceramic formulations that can withstand localized thermal spikes exceeding 450°C during write operations.
Growth Catalysts
- EU CSRD supply chain disclosure mandates:Large enterprise buyers now audit substrate suppliers for carbon intensity and chemical traceability, accelerating qualification of low-emission alumina sintering facilities in Taiwan and Japan.
- Hyperscale archival storage expansion:Cloud operators are commissioning dedicated nearline HDD farms for cold data tiers, pulling premium glass substrates into procurement portfolios previously dominated by consumer-grade aluminum.
- Heat-assisted magnetic recording (HAMR) substrate requirements:Next-generation recording heads demand thermally stable glass-ceramic foundations with near-zero thermal expansion coefficients, opening specification windows for advanced material suppliers.
Market Restraints
- High-purity alumina powder cost volatility:Feedstock prices fluctuate with bauxite refining capacity in China and energy costs for calcination, squeezing margin pools for sintered substrate manufacturers serving cost-sensitive client segments.
- Taiwan Science Park supply concentration:ASE Technology and IBIDEN anchor over 60% of precision substrate fabrication for Western HDD assemblers, creating single-source vulnerability amplified by seismic and geopolitical risk exposure.
- Silicon epitaxy thermal budget limitations:Silicon substrates face integration barriers with HAMR heads due to thermal conductivity mismatches that degrade signal-to-noise ratios at areal densities above 3 Tbit/in².
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Component-level incentives now extend to precision ceramic substrates, attracting fabrication joint ventures to serve emerging domestic data center and defense storage requirements.
- Medical imaging archive digitization:Healthcare systems are migrating film-based radiology to optical disc archives, pulling glass-ceramic substrates into diagnostic equipment supply chains previously isolated from data storage demand.
- Glass-ceramic and photonic integration convergence:Substrate suppliers with optical waveguide patterning capabilities can address emerging silicon photonics co-packaging requirements for AI training clusters.
Industry Challenges
- Sub-nanometer metrology talent scarcity:Proficiency in atomic force microscopy and white-light interferometry for substrate characterization concentrates in Japan and Taiwan, constraining facility expansion into lower-cost manufacturing geographies.
- Multi-year automotive qualification timelines:In-vehicle data recorder applications require AEC-Q100 stress testing and PPAP documentation cycles lasting 18-24 months, delaying revenue recognition for substrate suppliers targeting mobility segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platter Substrate Materials Market |
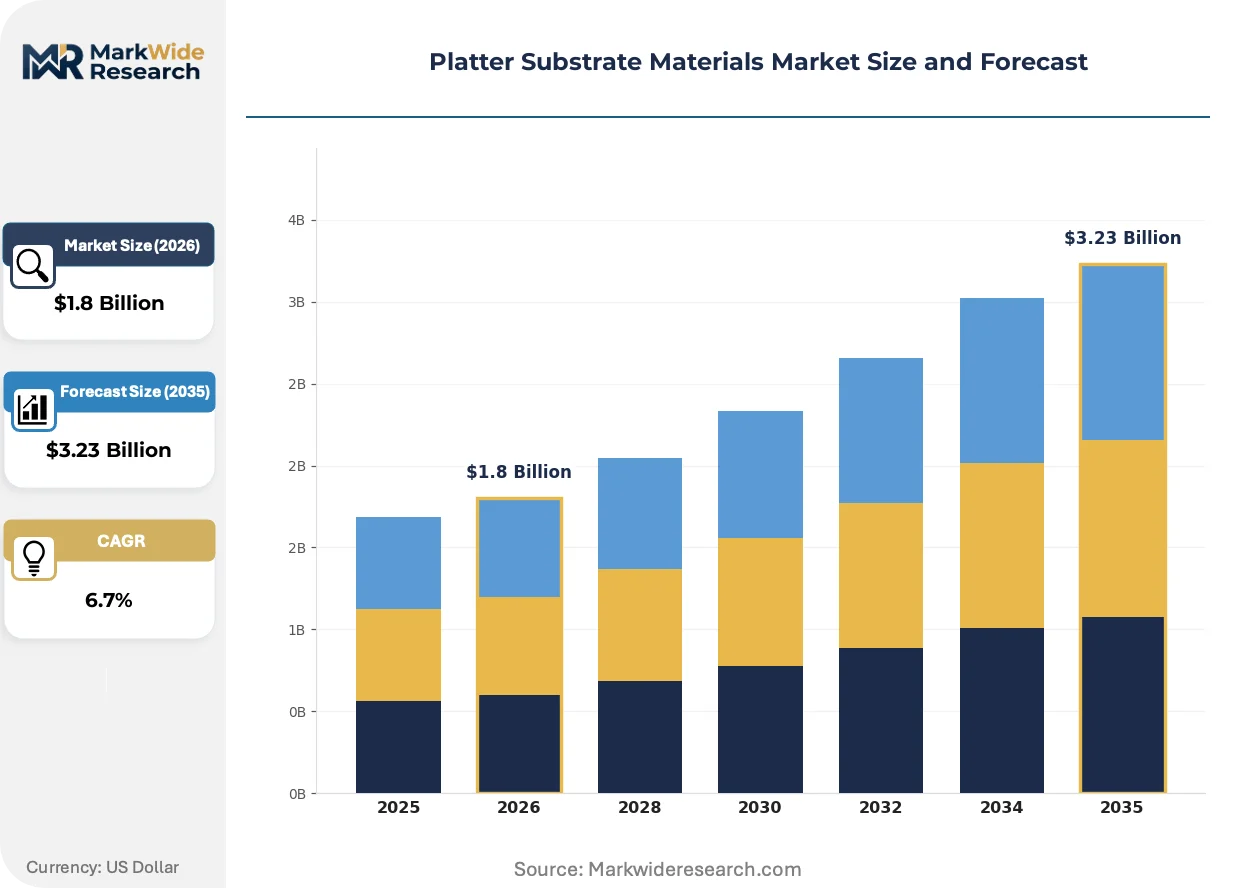
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Alumina, Glass, Silicon, Quartz Production Process: Sintering, Coating, Etching, Machining Application: Optical Discs, Hard Disc Drives, Medical Devices, Electronics End User Industry: Consumer Electronics, Healthcare, Automotive, Telecommunication |
| Companies Covered | Denka Company Limited, ASE Technology Holding Co., Ltd., SCHOTT AG, IBIDEN Co. Ltd., Showa Denko K.K., Seagate Technology Holdings plc, ALPS Electric Co., Ltd., FUJIFILM Holdings Corporation, Hoya Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platter Substrate Materials Market Emerging Trajectories
Substrate material selection is bifurcating along performance-versus-cost axes as recording head technologies diverge, with HAMR adoption accelerating specification fragmentation and coating chemistry innovation outpacing traditional alumina process optimization.
Chemically strengthened glass-ceramic substrates are fragmenting the established alumina-dominated supply base for enterprise nearline drives. Western Digital and Seagate procurement teams are dual-sourcing glass formulations from SCHOTT AG and AGC for 20TB+ capacity points, compressing lead times for sintered alumina suppliers who lack glass-melting furnace assets. This material transition is fragmenting equipment vendor relationships as glass substrate flatness requirements demand wholly different polishing and inspection toolchains.
EU REACH Annex XVII restrictions on perfluorinated compounds in protective overcoat formulations are forcing substrate suppliers to qualify fluorine-free diamond-like carbon deposition processes. ECHA substance evaluations have flagged PFAS precursors in traditional sputtering targets, compelling coating equipment retrofits at fabrication facilities serving European-headquartered drive assemblers. Japanese suppliers with advanced plasma-enhanced chemical vapor deposition capabilities are capturing qualification slots as REACH compliance timelines compress.
Hyperscale buyers are consolidating substrate procurement through direct long-term agreements with Tier-2 material processors, bypassing traditional HDD assembler intermediaries. Amazon Web Services and Microsoft Azure infrastructure teams now negotiate glass-ceramic volume commitments directly with IBIDEN and AGC, disintermediating legacy distribution through drive OEM supply chains. This channel restructuring is most visible in Taiwan's Hsinchu corridor where cloud operator technical teams co-locate with substrate fabrication facilities for specification alignment.
Platter Substrate Materials Market Segmentation
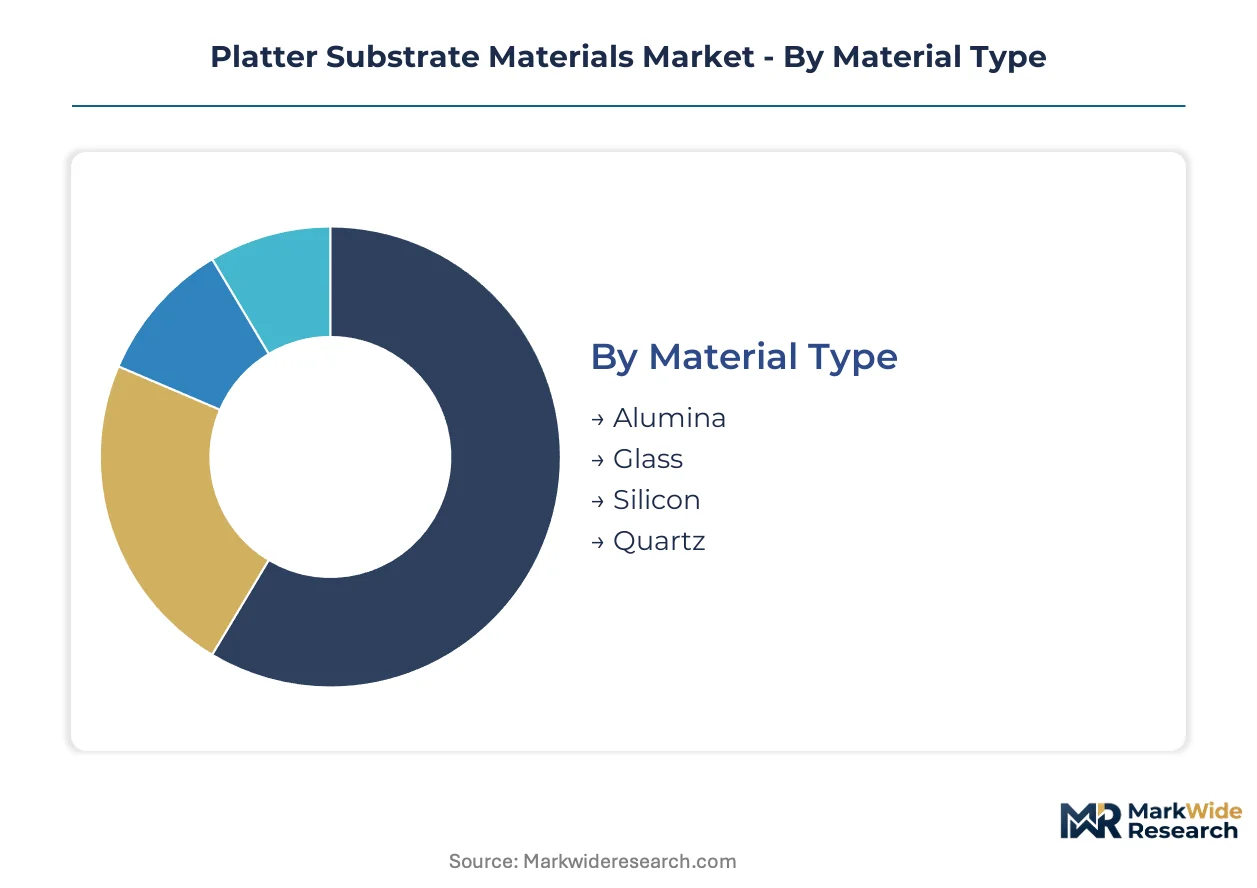
Substrate procurement channels diverge sharply by material grade and end-use performance requirements. Cloud operators negotiate direct supply agreements for glass-ceramic formulations, while consumer electronics assemblers rely on HDD OEM intermediaries for cost-optimized alumina volumes.
Material Type:
Channel mix varies dramatically across material categories, with hyperscale buyers dominating glass-ceramic procurement and OEM distributors controlling alumina flows to consumer markets.
- Alumina:Sintered aluminum oxide substrates deliver fracture toughness and cost scalability through established powder metallurgy routes. Volume concentrates in Taiwan's Science Park corridor where IBIDEN serves Seagate and Western Digital assembly lines, though high-purity feedstock cost volatility squeezes margin pools for cost-sensitive segments.
- Glass:Chemically strengthened glass-ceramic formulations withstand localized thermal spikes exceeding 450°C during HAMR write operations. Procurement is shifting toward direct agreements between cloud operators and SCHOTT AG or AGC, bypassing traditional HDD assembler intermediaries for enterprise nearline storage deployments.
- Silicon:Epitaxial silicon substrates integrate magnetic recording layers through semiconductor-compatible processes. Thermal conductivity mismatches with HAMR heads create integration barriers at areal densities above 3 Tbit/in², constraining adoption in next-generation drives.
- Quartz:Fused silica composites serve niche optical and precision measurement applications requiring ultra-low thermal expansion. Demand remains isolated from mainstream HDD procurement channels, flowing instead through specialized photonics equipment vendors.
By volume, alumina leads. By growth pace, glass-ceramic formulations are expanding most quickly.
Production Process:
Cost tier stratification separates capital-intensive coating operations from commodity machining, with etching processes capturing premium positioning for topology control.
- Sintering:High-temperature densification of alumina powders remains the dominant volume process, with furnace emissions regulated by the US EPA and Japan's METI standards constraining facility siting. Energy costs for calcination create margin pressure when natural gas prices spike.
- Coating:Diamond-like carbon and protective overcoat deposition commands premium pricing due to EU REACH restrictions on perfluorinated compounds. Japanese suppliers with plasma-enhanced chemical vapor deposition capabilities are capturing qualification slots as fluorine-free process timelines compress.
- Etching:Sub-micron surface topology control enables areal density gains for next-generation recording heads. Equipment vendors concentrate in Japan and Taiwan where atomic force microscopy proficiency constrains geographic expansion.
- Machining:Precision grinding and polishing operations achieve sub-nanometer flatness tolerances required for HAMR substrates. White-light interferometry characterization talent scarcity limits facility expansion into lower-cost manufacturing geographies.
By maturity, sintering dominates. By margin capture, coating processes are climbing the fastest.
Application:
Customer type fragmentation separates enterprise procurement teams from consumer electronics supply chains, with medical device applications emerging as a distinct channel.
- Hard Disc Drives:Magnetic storage substrates serve cloud archival and enterprise nearline tiers. HAMR technology deployment is compressing flatness tolerances below 0.5 nanometers, forcing retooling of fabrication lines for thermally stable glass-ceramic foundations.
- Optical Discs:Glass-ceramic substrates for medical imaging archives pull SCHOTT AG formulations into diagnostic equipment supply chains. Healthcare system digitization of film-based radiology is expanding addressable demand beyond traditional data storage markets.
- Medical Devices:Precision substrates support diagnostic and surgical equipment requiring thermal stability and biocompatibility. Qualification timelines extend 18-24 months for AEC-Q100 stress testing and PPAP documentation, delaying revenue recognition.
- Electronics:General-purpose substrate applications span sensors, MEMS, and passive components. Specification diversity fragments procurement volumes across multiple end-use channels with limited standardization.
By procurement scale, hard disc drives lead. By specification intensity, medical devices are gaining share fastest.
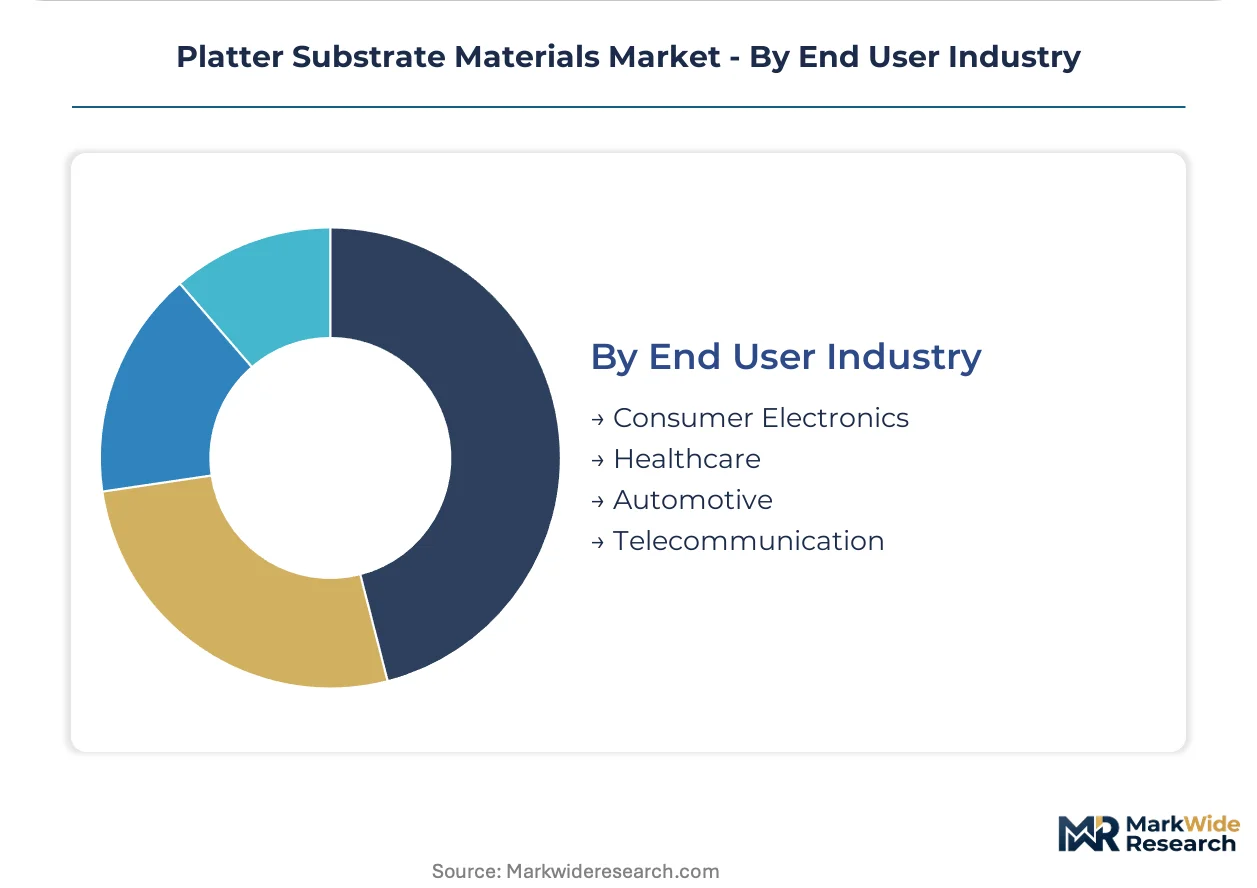
End User Industry:
Geography of demand concentration shapes supplier qualification pathways, with automotive and healthcare applications imposing distinct regulatory compliance burdens.
- Consumer Electronics:Personal computing and gaming device storage demands prioritize cost-optimized alumina substrates. Procurement flows through integrated HDD assembler supply chains rather than direct material supplier relationships.
- Healthcare:Diagnostic imaging and patient data archive requirements drive glass-ceramic substrate specifications. Japan's PMDA and the US FDA impose traceability standards on materials contacting sensitive equipment surfaces.
- Automotive:In-vehicle data recorders and autonomous driving sensor fusion create emerging substrate demand. Multi-year qualification timelines and AEC-Q100 stress testing requirements filter supplier participation.
- Telecommunication:Edge computing and 5G infrastructure storage deployments pull enterprise-grade substrates into network equipment supply chains. India's PLI scheme for electronics manufacturing is attracting fabrication joint ventures to serve domestic data center buildouts.
By current volume, consumer electronics leads. By procurement transformation, healthcare and automotive are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kaohsiung Port container terminal underwrites Taiwan's dominance in precision substrate logistics, moving alumina powders and finished glass-ceramic wafers to Seagate and Western Digital assembly lines. Japan's Yokohama port anchors METI-regulated export corridors for high-purity sintering equipment. India's Jawaharlal Nehru Port Trust is scaling capacity for electronics component imports under PLI scheme incentives.
Taiwan
ASE Technology and IBIDEN operate dedicated hard disc substrate fabrication clusters in Hsinchu Science Park, serving cloud operator procurement teams directly. The National Development Council enforces semiconductor supply chain security protocols affecting substrate inventory thresholds. Kaohsiung's precision materials corridor is expanding cleanroom capacity for chemically strengthened glass processing.
Japan
Showa Denko K.K. and SCHOTT AG's Japanese operations supply silicon epitaxy and glass-ceramic formulations for heat-assisted magnetic recording heads. METI's JIS standards enforce dimensional precision requirements on domestic substrate manufacturers. The Chubu region around Nagoya concentrates atomic force microscopy characterization talent for sub-nanometer metrology.
United States
Seagate Technology's Minnesota and California facilities drive substrate qualification demand for enterprise nearline storage deployments. The EPA regulates sintering furnace emissions at domestic fabrication sites under Clean Air Act provisions. Greater Phoenix anchors emerging cloud data center buildouts pulling premium glass substrates into Southwest procurement channels.
Germany
SCHOTT AG's Mainz headquarters controls glass-ceramic formulation IP for medical imaging archive applications. ECHA's REACH Annex XVII restrictions on perfluorinated compounds force coating chemistry retrofits at European-headquartered drive assemblers. The Rhine-Main logistics corridor distributes substrate materials to diagnostic equipment manufacturers across the EU.
India
PLI scheme incentives for electronics manufacturing are attracting precision ceramic substrate joint ventures to serve domestic data center requirements. The Ministry of Electronics and Information Technology mandates local value-add thresholds for component imports. Tamil Nadu's Sriperumbudur electronics cluster is emerging as a substrate fabrication location for defense storage applications.
Platter Substrate Materials Market Vendor Landscape
Listed leaders compete with private specialists across material formulation and fabrication process dimensions. The vendor base separates into consolidated glass-ceramic specialists, diversified electronics assemblers with captive substrate units, and pure-play alumina sintering operations. Three archetypes dominate: integrated materials-science conglomerates controlling feedstock-to-substrate value chains; precision fabrication contractors serving HDD OEM specification windows; and optical glass specialists pivoting into data storage applications. Competitive moves concentrate on dual-sourcing qualification partnerships and direct volume agreements with hyperscale cloud operators.
Among Japanese materials conglomerates, Showa Denko K.K. and Denka Company Limited exemplify the integrated feedstock-to-substrate archetype, while SCHOTT AG represents the optical glass specialist pivoting into archival storage substrates. Taiwan's ASE Technology Holding Co., Ltd. occupies the precision fabrication contractor position within this competitive map.
| Leading Market Players |
|---|
| Denka Company Limited |
| ASE Technology Holding Co., Ltd. |
| SCHOTT AG |
| IBIDEN Co. Ltd. |
| Showa Denko K.K. |
| Seagate Technology Holdings plc |
| ALPS Electric Co., Ltd. |
| FUJIFILM Holdings Corporation |
| Hoya Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between hyperscale cloud operators and Taiwanese glass-ceramic suppliers lock in five-year price visibility while securing dedicated furnace capacity. These contracts insulate premium substrate tiers from alumina powder cost volatility that squeezes sintered product margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates HAMR-grade glass-ceramic substrates from nearline enterprise alumina and consumer-grade sintered products. Price differentiation hinges on flatness certification grade and volume scale commitments exceeding ten thousand wafers annually. Cost compression in standard-tier alumina intensifies because Chinese bauxite refining capacity constraints feed raw material volatility. Consumer electronics assemblers exhibit highest price sensitivity, while cloud infrastructure teams absorb premium positioning for thermal stability guarantees.
Supply Chain Analysis
Kaohsiung Port container congestion on the transpacific lane elevates inbound logistics costs for Japanese sintering equipment and German glass-melting furnace components. Supply concentrates in Taiwan, Japan, and Germany, with fabrication clusters drawing from high-purity alumina powders, synthetic quartz crucibles, and fluorine-free sputtering targets. Single-source vulnerability runs through Taiwan's Science Park corridor where seismic exposure threatens sixty percent of precision substrate capacity. Distribution runs through direct technical partnerships between material processors and hyperscale buyer engineering teams, bypassing legacy HDD assembler intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in sub-nanometer metrology calibration and coating chemistry compliance auditing expand faster than hardware substrate sales. Recurring revenue from qualification maintenance contracts now exceeds equipment margins for fabrication facility operators.
For Market Incumbents: Compound defensive positioning through captive alumina powder calcination capacity and direct cloud operator technical service agreements. Silicon epitaxy integration faces displacement by glass-ceramic HAMR foundations; backward integration into synthetic quartz feedstock secures thermal expansion coefficient control. Certification investment in EU REACH fluorine-free deposition processes captures qualification slots as ECHA timelines compress. For New Entrants and Emerging Players: Differentiate on medical imaging archive substrate specifications where AEC-Q100 stress testing requirements filter incumbent participation. India's PLI scheme for electronics manufacturing offers the most penetrable geography, with Tamil Nadu's Sriperumbudur cluster attracting joint ventures for defense storage applications. Target diagnostic equipment OEMs through optical waveguide patterning capabilities that address silicon photonics co-packaging demand. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision fabrication contractors with captive metrology service arms and long-term hyperscale volume commitments. Five-to-ten year viability favors suppliers controlling glass-ceramic formulation IP and direct cloud procurement relationships. Watch for HAMR deployment inflection signals in Seagate and Western Digital enterprise nearline product roadmaps.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Quartz Feedstock | Hoya Corporation's crucible supply anchors thermal expansion control for HAMR-grade substrates. |
| Fluorine-Free Coating Chemistry Qualification | ECHA REACH Annex XVII compliance opens procurement slots at European-headquartered drive assemblers. |
| Direct Hyperscale Technical Partnership | Amazon Web Services infrastructure teams co-locate specification engineers with IBIDEN fabrication facilities. |
| Medical Imaging Archive Substrate Certification | Japan's PMDA traceability standards pull SCHOTT AG formulations into diagnostic equipment supply chains. |
| Sub-Nanometer Metrology Service Expansion | Atomic force microscopy proficiency scarcity in Japan and Taiwan supports premium calibration revenue streams. |
Methodological Framework
Operator-level perspectives from substrate fabrication plant managers, hyperscale data center procurement leads, HDD assembler supply chain directors, and coating equipment technical specialists anchored the qualitative base. Primary interview insights combined with secondary validation from Japan METI industrial statistics, EU ECHA substance evaluation databases, Taiwan customs export records, and SEC filings from listed HDD manufacturers. Bottom-up wafer volume estimates and top-down market sizing triangulated across material type and application dimensions.
Sensitivity analysis tested forecast robustness against alumina powder cost volatility scenarios and HAMR technology adoption pace variations across the projection horizon. Segmentation modeling incorporated material type, production process, application, and end-user industry dimensions with regional regulatory cluster differentiation. CAGRs derived from linear regression on historical volume trends adjusted for technology transition inflection points. Forecast inputs included cloud storage capex disclosures and medical imaging digitization policy timelines.
Forecasts assume regulatory continuity in EU REACH chemical controls and Japan's JIS substrate precision standards; material policy shifts would require re-modeling. Technology transition risk from HAMR deployment delays and seismic disruption scenarios in Taiwan's Science Park corridor could compress volume assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Silicon Germanium Material Market
Semiconductor Material
Semiconductor Silicon Material Market
Semiconductor Material
Sputtering Target Market
Semiconductor Material
Chalcocite-Digenite Group Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
Global Gallium Oxide Market
Semiconductor Material
Asia-Pacific Silicone Market
Semiconductor Material
Silicon Nitride Balls Market
Semiconductor Material
EV Capacitor Films Market
Semiconductor Material
Europium Market
Semiconductor Material
Metallurgical Grade Silicon Market
Semiconductor Material
Rhenium Market
Semiconductor Material
Yttrium Oxide Market
Semiconductor Material
Ultra High Purity Silicon Carbide Market
Semiconductor Material
Quartz Crucible Market