
 Global Machine Vision Lighting Market | 2026-2036
Global Machine Vision Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Machine Vision Lighting Market Outlook
Software-defined intensity control is broadening what machine vision lighting vendors actually monetize, shifting revenue from hardware-only sales to recurring calibration and spectral tuning subscriptions. Keyence Corporation leverages its integrated controller ecosystem to lock in multi-year service contracts alongside lamp heads. Cognex Corporation anchors its lighting portfolio to its VisionPro software suite, creating bundled renewal streams that sustain margin structure. CCS Inc specializes in application-specific optical design, competing on wavelength precision rather than unit volume.
Machine vision lighting comprises engineered photon sources—LED arrays, laser diodes, and gas-discharge lamps—packaged with collimating optics, thermal management substrates, and programmable drivers to deliver spectrally stable, geometrically precise illumination for automated imaging systems. Wavelength stability within ±2 nm and strobe repetition rates above 100 kHz determine inspection fidelity in high-speed electronics assembly. LED dominates installed base value given its efficiency and dimming granularity, though laser modules claim the fastest expansion as battery inspection demands structured pattern projection. Area scan technology still occupies the largest revenue pool, while line scan lighting is displacing older configurations in flat-panel and web inspection where continuous motion demands uniform line illumination.
FDA 21 CFR Part 11 and EU MDR compliance frameworks are reshaping pharmaceutical inspection lighting requirements, mandating documented spectral consistency and traceable calibration cycles that favor vendors with embedded sensor feedback. Japan's METI energy efficiency standards and China's GB certification for industrial equipment are filtering non-compliant halogen and fluorescent imports from East Asian supply chains. Stakeholders must monitor how IEC 62471 photobiological safety revisions and emerging EU AI Act conformity rules for automated decision systems will redefine liability and testing burdens for integrated vision-lighting packages.
Market Dynamics
Semiconductor fabs in Taiwan, South Korea, and China now mandate sub-micron defect detection at every process node, forcing lighting vendors to deliver wavelength stability within ±2 nm and thermal drift compensation that legacy halogen architectures cannot achieve.
Growth Catalysts
- Battery cell inspection surge:Gigafactories across China's Yangtze River Delta and Germany's Saxony region require structured laser projection for electrode coating verification, pulling demand for programmable multi-axis illumination systems.
- EU Machinery Directive compliance:CE marking mandates for industrial automation equipment are accelerating replacement of mercury-vapor and halogen sources with solid-state LED modules that integrate documented spectral calibration cycles.
- Stroboscopic LED maturation:Drivers achieving repetition rates above 100 kHz now enable line-scan inspection of continuously moving web materials in flat-panel and lithium-foil production, displacing older continuous-wave configurations.
Market Restraints
- Phosphor and rare-earth supply concentration:High-CRI LED phosphors and specialized optical substrates depend on processing capacity concentrated in China, exposing pricing volatility and export control risks.
- Laser module cost structure:Structured pattern projection systems for 3D inspection carry 4-6x unit cost premiums versus LED ring lights, limiting penetration outside high-value semiconductor and pharmaceutical applications.
- IEC 62471 photobiological testing burden:Revised safety classifications for high-intensity sources extend certification timelines and require third-party retesting for every spectral configuration variant.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Subsidized fab and assembly capacity buildout in Gujarat and Tamil Nadu creates first-mover advantage for lighting vendors establishing local calibration and service infrastructure.
- FDA 21 CFR Part 11 compliance services:Pharmaceutical inspection mandates for documented spectral consistency open recurring revenue streams in audit-trail software and traceable calibration subscriptions.
- Multi-spectral imaging convergence:Integration of SWIR, UV, and visible-band illumination into single programmable heads reduces footprint and wiring complexity for battery and display panel inspection lines.
Industry Challenges
- Embedded optics engineering talent scarcity:Design of collimating lenses and thermal management substrates for sub-micron uniformity requires rare cross-disciplinary expertise in photonics and precision mechanics.
- Legacy vision system integration friction:Brownfield semiconductor and automotive assembly lines run proprietary communication protocols that complicate retrofit of intelligent lighting controllers with feedback loops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Machine Vision Lighting Market |
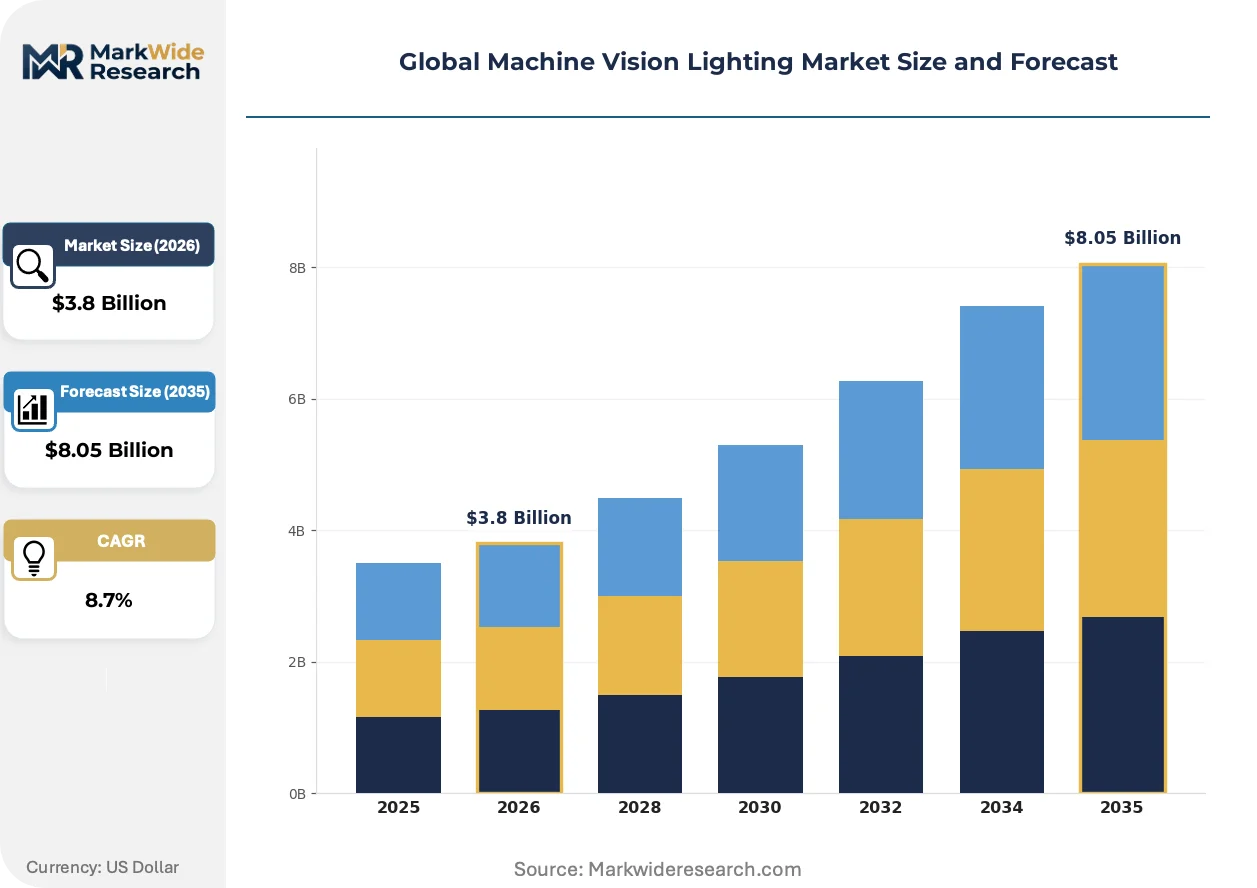
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Fluorescent, Laser Technology: Line Scan, Area Scan, Smart Cameras, Sensors End User: Manufacturing, Electronics, Food & Beverage, Pharmaceuticals Application: Quality Control, Inspection, Identification, Measurement |
| Companies Covered | Cognex Corporation, Keyence Corporation, Omron Corporation, Basler AG, CCS Inc, Smart Vision Lights, Spectrum Illumination, Advanced Illumination Inc., Banner Engineering Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Machine Vision Lighting Market Strategic Shifts
Machine vision lighting is transitioning from commodity hardware to intelligent, software-defined photon delivery systems where spectral tuning and thermal compensation happen in real time rather than at the fixture factory.
Multi-wavelength programmable heads are unifying previously separate UV, visible, and SWIR sources into single thermal-managed packages. Battery electrode inspection lines in South Korea and Germany now deploy these unified sources to switch between defect detection modes without mechanical changeover. The technology is unifying what were three distinct supplier relationships into single-vendor contracts with attached calibration service agreements.
Japan's METI energy efficiency standards and China's GB certification for industrial equipment are filtering non-compliant halogen and fluorescent imports from East Asian supply chains. Manufacturers must now embed power-factor correction and documented lumen-maintenance curves to maintain market access. Solid-state LED architectures with integrated power monitoring are capturing replacement cycles that fluorescent tube vendors cannot satisfy.
Automotive battery producers now specify outcome-based lighting performance contracts rather than unit hardware purchases. Tier-1 cell suppliers in Poland and Michigan negotiate payments tied to defect detection rates and uptime guarantees, transferring calibration and spectral drift liability upstream to lighting vendors. This model compresses procurement cycles and locks in multi-year service relationships that sustain margin structures independent of hardware replacement rates.
Global Machine Vision Lighting Market Segmentation
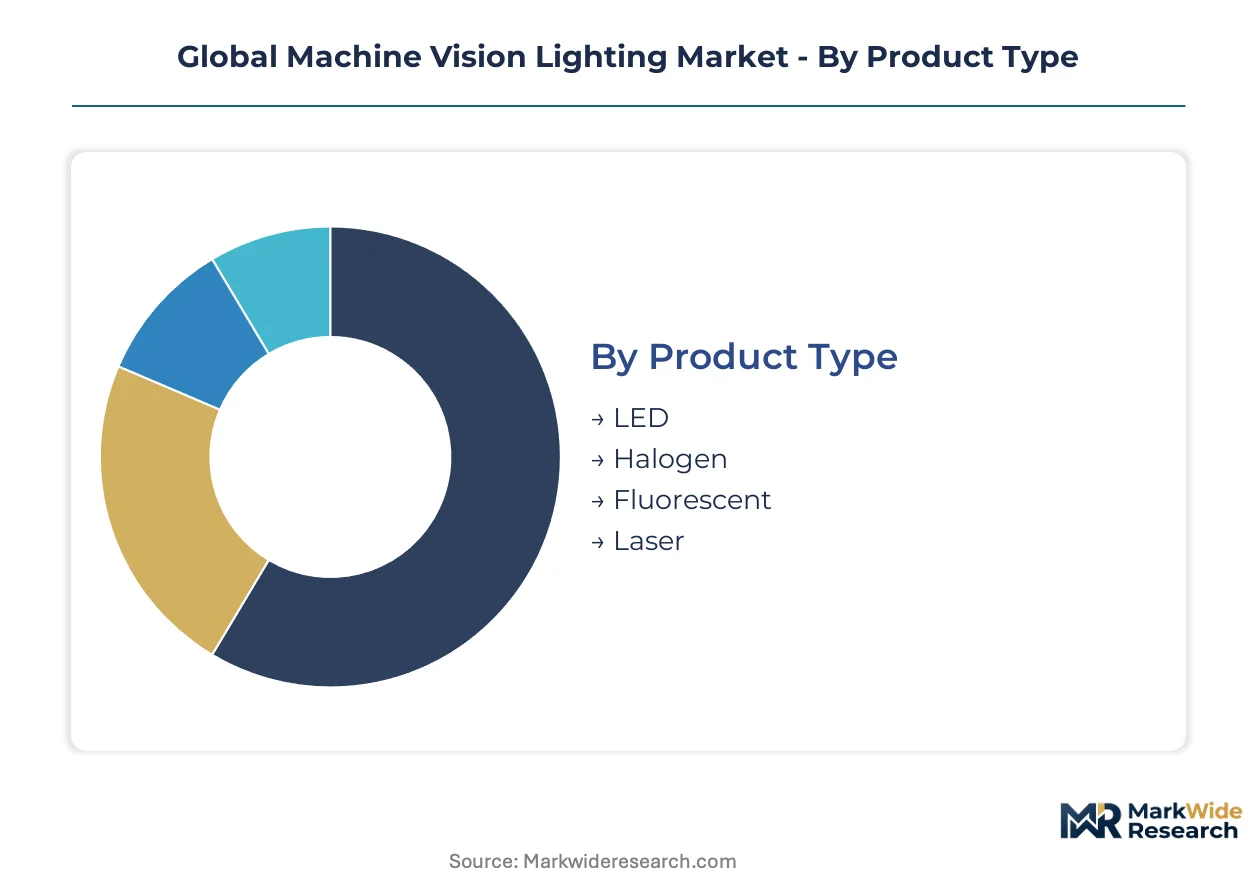
Machine vision lighting segmentation reveals how technical specifications map to inspection economics. Wavelength stability, strobe frequency, and thermal management requirements vary sharply across semiconductor fabs, battery plants, and pharmaceutical cleanrooms, forcing vendors to maintain parallel product architectures.
Product Type:
Customization intensity runs from fully configurable laser modules to commodity LED arrays, with cost premiums scaling directly with spectral precision requirements.
- LED:Solid-state arrays with programmable drivers deliver dimming granularity and thermal stability that halogen cannot match. Semiconductor fabrication lines in Taiwan and South Korea specify these for sub-micron defect detection where wavelength drift compromises yield. EU Machinery Directive CE marking mandates are accelerating replacement of legacy sources in German and Polish automotive assembly plants.
- Laser:Diode modules project structured patterns for 3D surface mapping and electrode coating verification. Gigafactories across China's Yangtze River Delta and Germany's Saxony region pull demand for multi-axis programmable systems despite 4-6x unit cost premiums over LED alternatives.
- Halogen:Legacy tungsten-filament sources persist in brownfield installations with proprietary control protocols.
- Fluorescent:Gas-discharge tubes face phased obsolescence under Japan's METI energy efficiency standards and China's GB certification requirements.
Leading the category by volume: LED. Expanding most quickly: Laser.
Technology:
Scan architecture determines how motion and illumination synchronize, with cost structures diverging between continuous web inspection and discrete part handling.
- Area Scan:Two-dimensional image sensors capture entire fields in single exposures. Electronics assembly lines in China's Pearl River Delta deploy these for PCB defect detection where part positioning varies. The technology commands the largest installed base value given flexibility across batch inspection workflows.
- Line Scan:Linear sensors build images from continuous motion, demanding stroboscopic LED drivers exceeding 100 kHz repetition rates. Flat-panel and lithium-foil production lines in South Korea and Japan specify these for uniform illumination across moving webs.
- Smart Cameras:Embedded processing reduces host controller dependency for edge inspection tasks.
- Sensors:Discrete photodetectors support simple presence-absence verification in cost-constrained applications.
Dominating current revenue: Area Scan. Gaining share fastest: Line Scan.
End User:
Regulatory stringency tiers separate pharmaceutical and food inspection from manufacturing and electronics, with compliance documentation requirements driving service attachment rates.
- Manufacturing:General industrial automation spans automotive, packaging, and materials handling with varying uniformity requirements. Tier-1 suppliers in Michigan and Poland now negotiate outcome-based contracts tied to defect detection rates rather than hardware unit purchases.
- Electronics:Semiconductor and display panel fabrication demands the tightest wavelength stability specifications. Taiwan's foundries and China's Yangtze River Delta memory plants embed vision-guided inspection at every process node.
- Pharmaceuticals:FDA 21 CFR Part 11 and EU MDR frameworks mandate documented spectral consistency and traceable calibration cycles.
- Food & Beverage:Sorting and foreign-object detection applications prioritize washdown-rated enclosure designs.
Highest service attachment: Pharmaceuticals. Largest unit volume: Manufacturing.
Application:
Inspection depth determines illumination complexity, with measurement tasks requiring geometric precision that quality control screening does not.
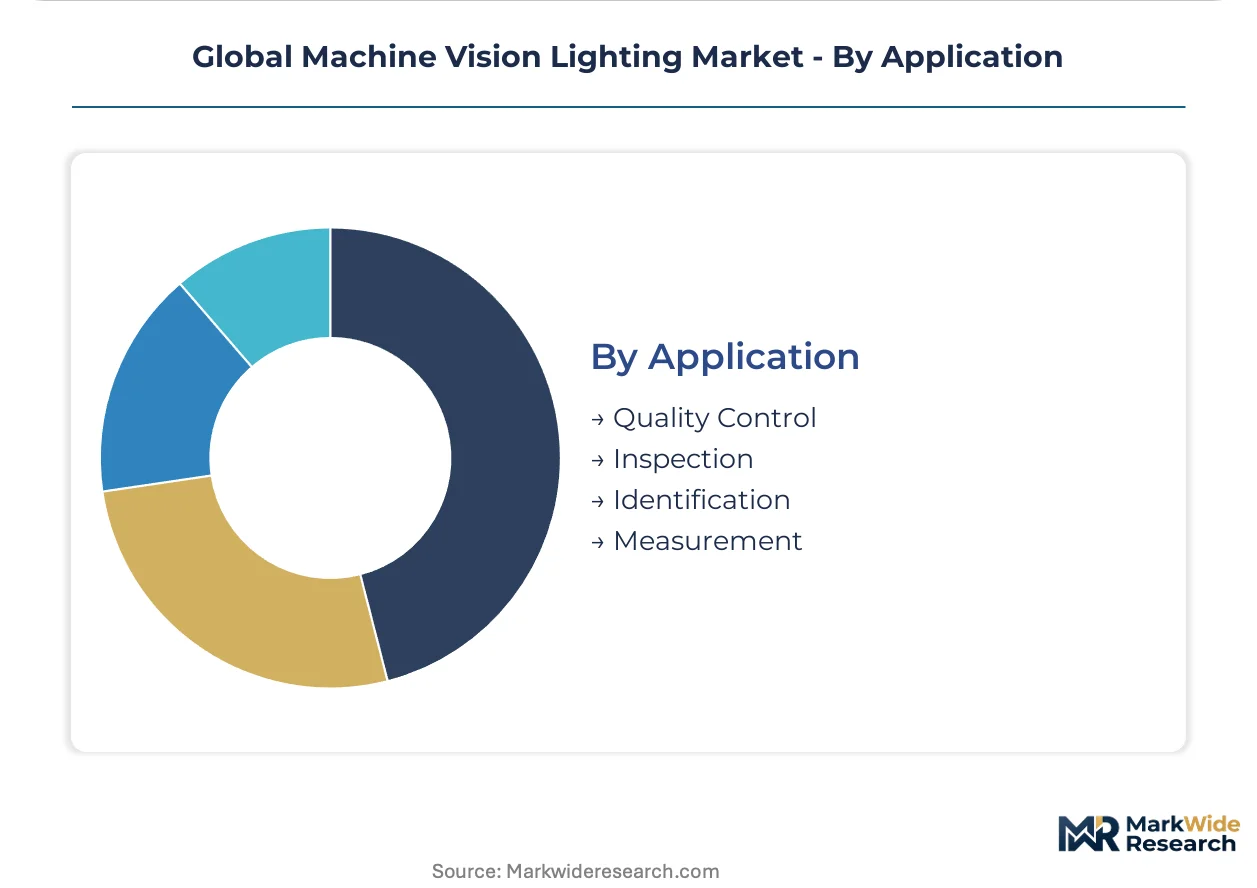
- Quality Control:Pass-fail sorting based on surface defects, dimensional tolerances, and assembly completeness. Battery cell plants in Germany and the United States deploy multi-spectral heads to switch between electrode coating verification and seal integrity modes without mechanical changeover.
- Inspection:Detailed defect characterization and classification for process feedback. Semiconductor fabs specify sub-micron resolution requiring thermal drift compensation and collimating optics engineered for uniformity.
- Identification:Barcode, QR code, and optical character recognition under variable contrast conditions.
- Measurement:Metrology-grade dimensional verification with structured light projection.
Broadest deployment: Quality Control. Steepest specification escalation: Inspection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asia manufactures the majority of machine vision lighting hardware while North American and European fabs consume the most advanced configurations. Taiwan, South Korea, and China dominate LED and laser module production. German and US battery plants drive premium specification demand.
China
MIIT industrial automation subsidies and GB certification requirements for industrial equipment are filtering non-compliant imports from domestic supply chains. Battery cell plants and display panel fabs in the Yangtze River Delta are scaling automated optical inspection capacity with multi-spectral programmable heads.
United States
FDA 21 CFR Part 11 compliance mandates for pharmaceutical inspection are reshaping procurement toward documented spectral consistency and traceable calibration cycles. Tier-1 automotive battery suppliers in Michigan negotiate outcome-based contracts tied to defect detection rates rather than hardware unit purchases.
Germany
EU Machinery Directive CE marking requirements are accelerating replacement of legacy halogen systems with certified solid-state LED modules. Gigafactories in Saxony deploy structured laser projection for electrode coating verification, pulling demand for programmable multi-axis illumination systems.
South Korea
METI-aligned energy efficiency standards and domestic fab automation roadmaps are concentrating demand for sub-micron defect detection lighting. Semiconductor fabrication lines embed vision-guided inspection at every process node, tightening reliance on high-uniformity LED ring lights with thermal drift compensation.
Japan
METI energy efficiency standards are filtering non-compliant halogen and fluorescent imports from domestic supply chains. Flat-panel and lithium-foil production lines specify stroboscopic LED drivers exceeding 100 kHz repetition rates for uniform illumination across moving webs.
Global Machine Vision Lighting Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the machine vision lighting landscape. Integrated vision system vendors with captive lighting portfolios hold pricing power through software bundling. Component specialists compete on wavelength precision and thermal engineering. The market structure favors three strategic archetypes: integrated platform vendors, optical component specialists, and programmable controller developers. Consolidation pressure runs through multi-spectral head convergence and service contract attachment.
Among integrated platform vendors, Cognex Corporation and Keyence Corporation exemplify the software-anchored model where lighting hardware attaches to vision system ecosystems. CCS Inc occupies a position within the optical specialization tier, competing on application-specific wavelength precision rather than unit volume scale. These three anchors illustrate how revenue is shifting from hardware-only sales toward recurring calibration and spectral tuning subscriptions.
| Leading Market Players |
|---|
| Cognex Corporation |
| Keyence Corporation |
| Omron Corporation |
| Basler AG |
| CCS Inc |
| Smart Vision Lights |
| Spectrum Illumination |
| Advanced Illumination Inc. |
| Banner Engineering Corp. |
| Others |
Value Chain & Pricing Dynamics
Outcome-based procurement contracts from Tier-1 battery suppliers in Michigan and Poland are forcing lighting vendors to absorb calibration and spectral drift liability, compressing hardware margins while elevating service attachment as the primary profit pool.
Pricing Analysis
Cost-down pressure on LED ring light assemblies accelerates because automotive battery producers now negotiate payments tied to defect detection rates rather than unit hardware purchases. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked solid-state modules with documented calibration cycles from uncertified commodity arrays. Price differentiation hinges on wavelength precision certification and thermal management substrate quality. Pharmaceutical inspection buyers demonstrate lowest price sensitivity given FDA 21 CFR Part 11 compliance mandates, while brownfield manufacturing retrofitters remain most cost-conscious.
Supply Chain Analysis
Dual-sourcing requirements from Taiwan's semiconductor foundries and Germany's automotive OEMs mandate qualified suppliers in both East Asia and Europe for critical LED phosphor and laser diode inputs. Manufacturing concentrates in China, Taiwan, and Japan for high-CRI LED phosphors, collimating optics, and precision thermal substrates. The chain draws from rare-earth processing capacity concentrated in China, exposing tariff and export control vulnerability. Distribution runs through vision system integrators and direct OEM contracts rather than open distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded optics engineering talent scarcity constrains rapid capacity expansion, propping pricing power for vendors with captive design expertise and multi-year service contract lock-in.
For Market Incumbents: Acquire calibration software platforms and spectral sensor feedback IP to defend against programmable controller startups eroding hardware attachment rates. Deepen backward integration into phosphor and thermal substrate supply through joint ventures with Japanese and Taiwanese materials specialists. Lock in multi-year outcome-based contracts with automotive battery producers before competitor service infrastructure matures. For New Entrants and Emerging Players: Direct-to-fab digital sales channels bypass established integrator relationships in India's Gujarat and Tamil Nadu electronics manufacturing corridors. Target pharmaceutical inspection lighting where FDA 21 CFR Part 11 documentation requirements create service revenue stickiness that offsets hardware margin compression. Lead with subscription-calibration bundles rather than unit sales to match incumbent contract structures. For Investors and Strategic Acquirers: The window for entry favors optical component specialists with wavelength precision IP and existing relationships with Taiwan's semiconductor foundries. Long-term viability centers on vendors controlling embedded sensor feedback technology that enables real-time thermal compensation. Watch for IEC 62471 photobiological safety reclassification as the signal that certification burden will consolidate vendor tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Spectral Head Convergence | Unifies UV, visible, and SWIR sources into single programmable packages for battery inspection lines. |
| Calibration Service Subscription Model | Transforms hardware vendors into recurring revenue platforms with pharmaceutical compliance lock-in. |
| Backward Integration into Phosphor Supply | Secures wavelength stability inputs from China-dependent rare-earth processing capacity. |
| India PLI Scheme Localization | Establishes qualified calibration infrastructure ahead of Gujarat and Tamil Nadu fab buildout. |
| Laser Module Cost Structure Reduction | Expands structured pattern projection beyond semiconductor into mid-tier electronics assembly. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with vision system integrators, semiconductor fab engineers, pharmaceutical quality directors, and automotive battery procurement leads. Bottom-up triangulation across product-type shipments and top-down validation against end-use capital expenditure patterns ensured cross-verification. Secondary sources included EU Machinery Directive implementation reports, FDA 21 CFR Part 11 guidance documents, METI energy efficiency filings, and MIIT industrial automation subsidy disclosures.
Product type, technology architecture, end-user industry, and application depth were modeled at the segment level across the analysis window. CAGRs were derived from slope analysis of historical shipment value trajectories projected against fab automation roadmaps and regulatory replacement cycle mandates. Industry-specific inputs incorporated stroboscopic LED driver maturation curves, laser module cost reduction trajectories, and multi-spectral convergence adoption rates from battery and display panel inspection lines.
Inputs from trade associations and regulatory bodies were available through the study window; gaps in real-time fab capital expenditure timing introduce uncertainty bands around near-term shipment forecasts. Deviation in China's rare-earth export policy or IEC 62471 reclassification timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Malaysia LED Lighting Controllers Market
Lighting
Global Headlight Control Module Market
Lighting
Directional Luminaire Market
Lighting
Bulb Market
Lighting
Connected (Smart) Street Lighting Market
Lighting
North America Street Lighting Market
Lighting
Photocell Market
Lighting
Solar Outdoor LED Lighting Market
Lighting
UAE Smart Lighting Market
Lighting
Cleanroom Lighting Market
Lighting
Street Lighting Market
Lighting
LED Eye Protection Lamp Market
Lighting
UV Lamps Market
Lighting
Smart Lighting Market
Lighting
Display Light Control Film Market
Lighting
Lighting Fixture Market