
 Global Ethernet Controller Market | 2026-2036
Global Ethernet Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ethernet Controller Market Foresight
The EU AI Act is rebalancing compliance costs for Ethernet controller suppliers serving European AI server deployments. NVIDIA leverages its data center silicon portfolio to sustain premium positioning in high-bandwidth networking segments. Intel anchors its position through in-house fabrication of controller die for enterprise server motherboards. Marvell Technology specializes in custom silicon for cloud-scale networking customers.
An Ethernet controller is a dedicated integrated circuit that manages frame encapsulation, MAC address filtering, and physical layer signaling between host processors and network infrastructure, typically supporting speeds from 10 Mbps to 400 Gbps depending on implementation. Its primary purpose is to offload packet processing from central CPUs while ensuring deterministic latency for real-time data transmission. Gigabit Ethernet and 10 Gigabit Ethernet controllers dominate volume shipments to enterprise IT & Networking deployments, where cost optimization governs procurement decisions. Multi-Gigabit Ethernet controllers represent the fastest-expanding product category, driven by 802.3bz standard adoption in Wi-Fi 6E access point backhaul and automotive Ethernet gateways. Power over Ethernet technology commands higher margin pools in building automation and smart surveillance endpoints where single-cable power-plus-data architectures reduce installation complexity.
The Federal Communications Commission in the United States governs electromagnetic emissions standards for Ethernet controllers deployed in telecommunications equipment, while the EU RoHS Directive restricts hazardous substance content in semiconductor packaging sold across European member states. China's Ministry of Industry and Information Technology enforces domestic GB standards for networking equipment procurement in government and state-owned enterprise tenders. Stakeholders must monitor divergence between regional certification regimes when planning controller platform roadmaps for multi-territory product families.
Market Dynamics
Data center rack density requirements in the United States are forcing Ethernet controller suppliers to prioritize 400G and 800G throughput capabilities while managing thermal envelope constraints. This density imperative is compressing product development cycles and redrawing competitive boundaries around signal integrity engineering.
Growth Catalysts
- EU AI Act traceability mandates:European networked infrastructure deployments now require chip-level provenance documentation, creating pull for controllers with embedded authentication features.
- Wi-Fi 6E access point backhaul:Enterprise wireless infrastructure refresh cycles are accelerating Multi-Gigabit Ethernet controller adoption for 2.5G and 5Gbps uplink capacity.
- Taiwan semiconductor foundry corridor:Concentrated advanced packaging capacity is enabling rapid prototyping of integrated controller-PHY solutions for cloud-scale customers.
Market Restraints
- Advanced node wafer costs:5nm and 3nm fabrication pricing for high-speed SerDes IP is compressing gross margins on 400G controller SKUs.
- Single-source photonics packaging:Co-packaged optical transceiver assembly capacity concentrates in a narrow supplier base, creating allocation risk for 800G roadmap execution.
- Copper reach limitations:Signal integrity degradation beyond 3 meters at 112G PAM4 is forcing premature optical transition in hyperscale server interconnects.
Strategic Opportunities
- Automotive Ethernet gateways:Zonal architecture adoption in electric vehicle platforms is opening 1Gbps and 10Gbps controller demand for sensor fusion backbones.
- India PLI scheme for networking equipment:Domestic manufacturing incentives are attracting controller assembly and test investments for government and telecom tenders.
- Power over Ethernet convergence:Building automation systems are unifying 90W power delivery with 10G data on single-cable infrastructure, expanding addressable controller attach rates.
Industry Challenges
- SerDes analog design talent scarcity:Experienced engineers capable of 112G and 224G signal conditioning are concentrated at a handful of incumbents, constraining new entrant ramp.
- Multi-territory certification timelines:Simultaneous FCC, CE marking, and MIIT GB standard compliance is extending product qualification cycles by 6-9 months for unified controller platforms.
- Legacy 1G/10G software stack entrenchment:Enterprise IT departments maintain substantial installed base dependencies that complicate 25G and faster controller migration planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ethernet Controller Market |
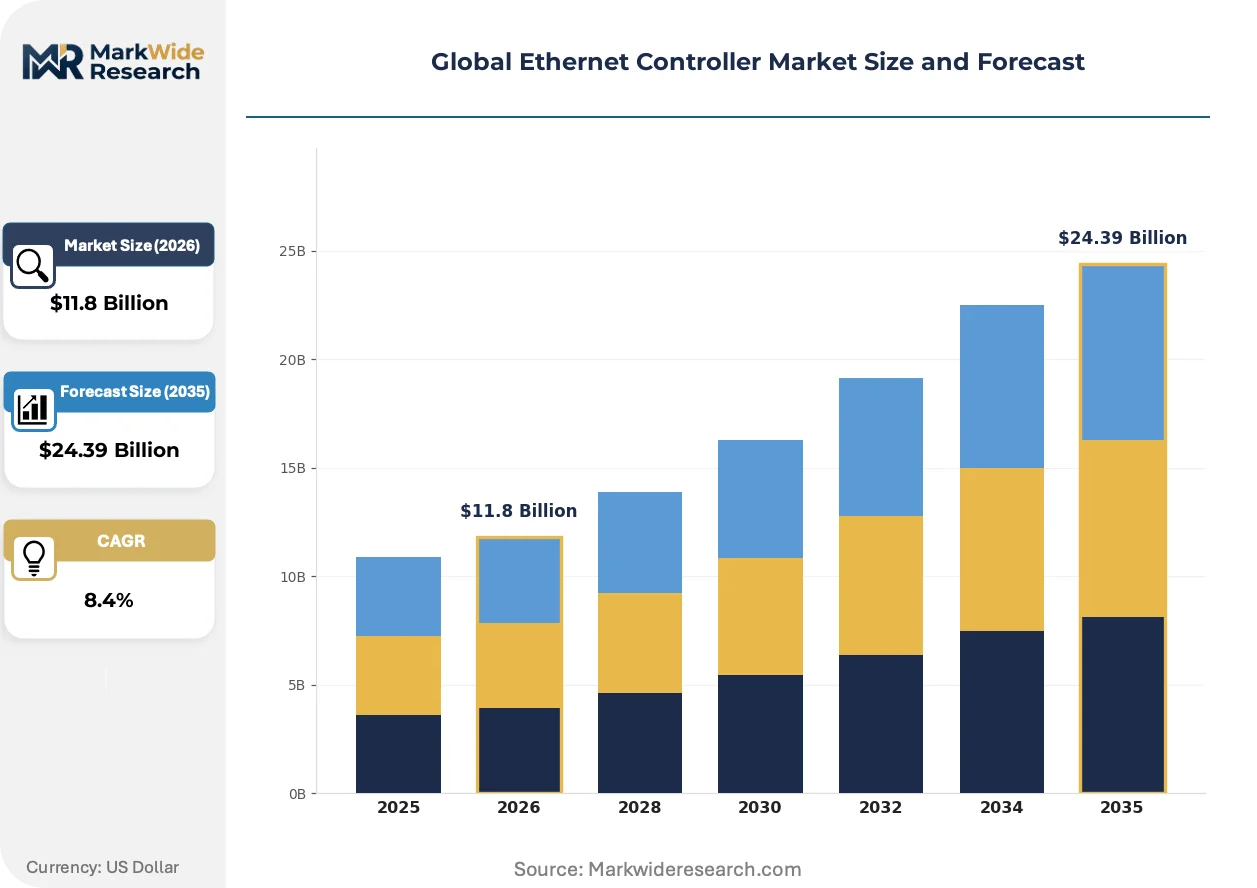
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gigabit Ethernet, Fast Ethernet, 10 Gigabit Ethernet, 100 Gigabit Ethernet, Multi-Gigabit Ethernet Technology: Wired Ethernet, Power over Ethernet, Automotive Ethernet, Industrial Ethernet, Ethernet Over Fiber Application: Data Centers, Telecommunications Equipment, Consumer Electronics, IT & Networking, Aerospace Systems End User: Original Equipment Manufacturers, Network Solutions Providers, System Integrators, Telecommunication Operators |
| Companies Covered | Realtek Semiconductor Corp., NVIDIA Corporation, Intel Corporation, Texas Instruments Incorporated, NXP Semiconductors N.V., Broadcom Inc., Microchip Technology Incorporated, Infineon Technologies AG, Marvell Technology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ethernet Controller Market Shifts & Advancements
Silicon photonics integration and software-defined networking abstraction are converging to redefine controller architecture trade-offs. Vendors must now optimize for co-packaged optical I/O while maintaining backward compatibility with established Ethernet software ecosystems.
SmartNIC and DPU silicon is consolidating network, storage, and security offload functions onto single-die or multi-chip modules. Hyperscale cloud operators are deploying these integrated controllers at rack scale to reduce CPU overhead for virtualization and encryption workloads. This functional consolidation is compressing the addressable market for standalone Ethernet controllers in high-performance computing environments.
REACH substance restrictions and RoHS hazardous material limits are tightening solder alloy and substrate material specifications for European-bound controller shipments. Semiconductor packaging houses are qualifying lead-free and halogen-free laminate alternatives to maintain CE marking eligibility. Automotive and industrial controller SKUs face the steepest reformulation costs due to extended temperature range reliability requirements.
Hyperscale buyers are consolidating procurement around vertically integrated networking stack vendors rather than discrete component suppliers. Cloud operators now specify end-to-end NIC-to-switch interoperability, reducing negotiation leverage for standalone controller merchants. This buyer concentration is most pronounced in the United States, where three operators account for the majority of 400G port deployment volume.
Global Ethernet Controller Market Segmentation
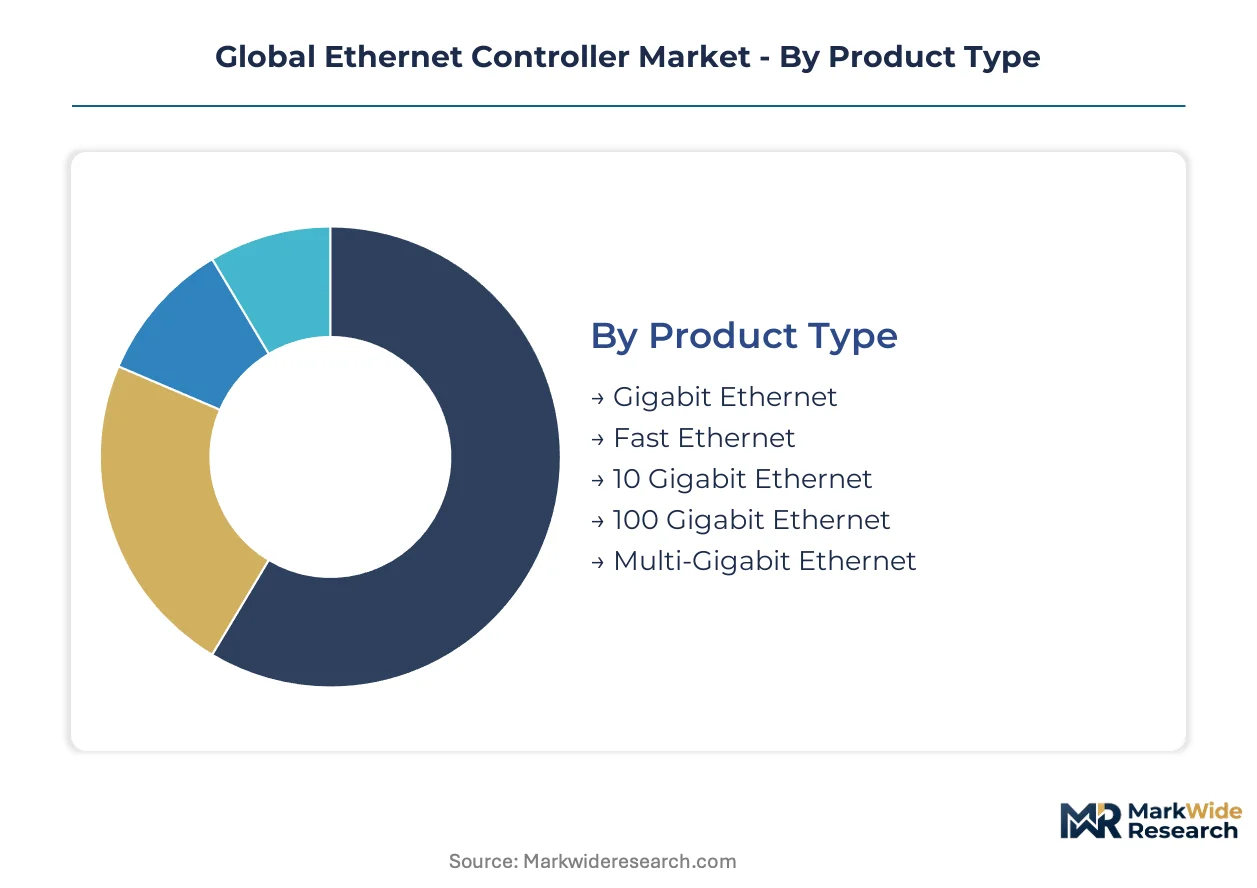
Ethernet controller segmentation reveals distinct engineering trade-offs between cost-optimized volume SKUs and precision-engineered custom silicon. Procurement patterns diverge sharply across these boundaries, with hyperscale buyers consolidating around integrated solutions while industrial customers retain appetite for discrete components.
Product Type:
Customization intensity spans from commodity off-the-shelf controllers to application-specific die configurations with proprietary SerDes tuning.
- Multi-Gigabit Ethernet:Controllers supporting 2.5G, 5G, and 10G non-standard rates integrate adaptive equalization for legacy copper infrastructure. Wi-Fi 6E access point backhaul deployments in Taiwan's manufacturing corridor are pulling volume for 2.5Gbps SKUs with extended temperature specifications.
- 100 Gigabit Ethernet:These devices incorporate PAM4 signaling and forward error correction for data center spine-leaf architectures. Rack density mandates from United States hyperscale operators are compressing development cycles for 400G-ready PHY integration.
- Gigabit Ethernet:Mature 1Gbps controllers dominate enterprise server motherboard attach with cost-optimized 28nm die shrinks.
- Fast Ethernet:Legacy 100Mbps implementations persist in building automation endpoints where bandwidth requirements remain minimal.
- 10 Gigabit Ethernet:SFP+ and BASE-T variants serve mid-range server connectivity with established software ecosystem compatibility.
Most installed capacity flows through Gigabit Ethernet. Expansion is steepest in Multi-Gigabit Ethernet.
Technology:
Margin profiles stratify sharply between standardized PHY integration and specialized power delivery or environmental hardening requirements.
- Power over Ethernet:These controllers integrate 802.3bt-compliant power sourcing equipment controllers delivering up to 90W alongside 10G data. Smart surveillance and LED lighting retrofits in European commercial real estate are demanding single-cable infrastructure with embedded authentication per EU AI Act traceability mandates.
- Automotive Ethernet:Controllers meet AEC-Q100 Grade 2 reliability with 100Mbps to 10Gbps rates for zonal E/E architectures. Electric vehicle platforms from Germany and South Korea are specifying 1Gbps controller counts per vehicle that exceed prior internal combustion configurations by 4-6x.
- Wired Ethernet:Standard copper PHY implementations without power delivery serve baseline enterprise connectivity.
- Industrial Ethernet:Hardened controllers with galvanic isolation and conformal coating target factory automation with deterministic latency requirements.
- Ethernet Over Fiber:These devices bridge electrical MAC interfaces to optical transceivers for extended reach beyond copper limitations.
Revenue concentration sits with Wired Ethernet. Steepest expansion trajectory belongs to Automotive Ethernet.
Application:
Deployment environments range from climate-controlled facilities to uncontrolled edge locations with divergent reliability specifications.
- Data Centers:Controllers prioritize 400G and 800G throughput with RDMA offload and congestion management for RoCEv2 fabrics. United States-based operators are specifying co-packaged optical I/O for 51.2T switch silicon, reallocating procurement toward vertically integrated networking stack vendors.
- IT & Networking:Enterprise refresh cycles favor 10G and 25G controllers with backward-compatible driver stacks. Legacy 1G software dependencies in United States and European IT departments are complicating migration timelines despite port cost convergence.
- Telecommunications Equipment:Controllers meet NEBS reliability with extended temperature ranges for central office deployments.
- Consumer Electronics:Cost-optimized 1G implementations serve gaming routers and high-end residential gateways.
- Aerospace Systems:Radiation-tolerant and DO-254 certifiable controllers target avionics databus replacement programs.
Volume leadership resides with IT & Networking. Gaining share fastest is Data Centers.
End User:
Technical specification authority concentrates differently across outsourced manufacturing versus in-house system design models.
- Original Equipment Manufacturers:Server and storage vendors specify controller die for captive motherboard designs with multi-year supply agreements. Taiwan-based ODMs are consolidating procurement around integrated NIC-DPU silicon to reduce bill-of-material complexity.
- Network Solutions Providers:These buyers specify interoperability requirements across NIC-to-switch boundaries, reducing negotiation leverage for discrete controller merchants.
- System Integrators:Value-added resellers configure controller subsystems for vertical-specific deployments with customized firmware loads.
- Telecommunication Operators:Carrier procurement departments enforce domestic certification requirements for government and state-owned enterprise tenders, particularly under China's MIIT GB standards.
Procurement volume concentrates with Original Equipment Manufacturers. Fastest growth is occurring among Network Solutions Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethernet controller manufacturing traces its industrial lineage to Silicon Valley's semiconductor ecosystem, where Fairchild Semiconductor and Intel pioneered integrated circuit production for networking applications. Taiwan's foundry corridor subsequently absorbed high-volume fabrication, while Germany's precision engineering base developed automotive-grade reliability standards. Contemporary demand now distributes across three continental manufacturing clusters with divergent regulatory and procurement specifications.
United States
Hyperscale data center operators in Virginia, Oregon, and Texas are specifying 400G and 800G controller capabilities for rack density expansion. The FCC governs electromagnetic emissions standards under Part 15 rules for telecommunications equipment deployment. Silicon Valley maintains design engineering concentration for SmartNIC and DPU architectures, though advanced node fabrication has migrated offshore.
Taiwan
Advanced packaging capacity in Hsinchu and Tainan Science Parks enables rapid prototyping of integrated controller-PHY solutions for cloud-scale customers. The National Development Council coordinates semiconductor supply chain resilience initiatives under the island's chip industry strategic framework. TSMC's foundry dominance concentrates 5nm and 3nm controller tape-outs within this corridor, creating allocation bottlenecks during demand surges.
Germany
Electric vehicle platforms from Munich and Stuttgart are specifying 1Gbps and 10Gbps automotive Ethernet controllers for zonal E/E architectures. The EU AI Act mandates chip-level provenance documentation for networked infrastructure deployed across member states. Bavaria's automotive electronics cluster coordinates AEC-Q100 qualification requirements with semiconductor suppliers.
China
Domestic server OEMs in Beijing and Shanghai are expanding procurement of indigenous controller designs for government and state-owned enterprise tenders. MIIT enforces GB standards for networking equipment certification in public sector deployments. Yangtze River Delta manufacturing bases assemble cost-optimized Gigabit Ethernet controllers for enterprise IT refresh cycles.
India
Telecom infrastructure tenders under the BharatNet program are stimulating demand for industrial-grade Ethernet controllers in rural connectivity deployments. The PLI scheme for networking equipment offers domestic manufacturing incentives for assembly and test investments. Karnataka's Electronics City and Tamil Nadu's Sriperumbudur corridor are attracting controller packaging operations from multinational suppliers.
Global Ethernet Controller Market Competitive Landscape
The competitive structure tilts toward vertically integrated semiconductor conglomerates with captive foundry relationships or advanced packaging partnerships. Tier-one suppliers command premium positioning through data center silicon portfolios, while mid-scale specialists concentrate on automotive and industrial qualification requirements. Strategic archetypes include: (1) full-stack networking vendors controlling NIC-to-switch interoperability specifications; (2) automotive-focused suppliers with AEC-Q100 Grade 2 reliability credentials; and (3) cost-optimized commodity controllers for enterprise motherboard attach. Dominant competitive moves encompass co-packaged optical I/O development partnerships and backward integration into SerDes IP design.
Among Taiwan-based semiconductor specialists, Realtek Semiconductor Corp. occupies a position exemplifying high-volume Gigabit Ethernet controller supply for consumer and enterprise motherboard segments. NVIDIA Corporation and Intel Corporation anchor the premium-tier vector for data center acceleration, representing the integrated SmartNIC-DPU convergence that is compressing standalone controller addressability in hyperscale environments. Marvell Technology, Inc. sits within the custom silicon specialization tier, serving cloud-scale networking customers with application-specific die configurations.
| Leading Market Players |
|---|
| Realtek Semiconductor Corp. |
| NVIDIA Corporation |
| Intel Corporation |
| Texas Instruments Incorporated |
| NXP Semiconductors N.V. |
| Broadcom Inc. |
| Microchip Technology Incorporated |
| Infineon Technologies AG |
| Marvell Technology, Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up packaging specialists in Taiwan and South Korea enforce disciplined allocation protocols for advanced controller die, translating wafer scarcity into sustained premium pricing for 400G and 800G SKUs while compressing margin pools for legacy Gigabit Ethernet merchants.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates co-packaged optical controllers from copper PHY variants from legacy Fast Ethernet implementations. Price differentiation hinges on SerDes performance tier and AEC-Q100 automotive certification grade. Cost compression in the standard tier is intensifying because 5nm wafer costs are outpacing die shrinks. Enterprise IT departments exhibit highest price sensitivity; hyperscale operators demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan's concentrated 3nm and 5nm foundry capacity for high-speed SerDes IP. Controller assembly draws from Taiwan, South Korea, and China's Yangtze River Delta for substrate and packaging inputs. Raw material dependencies include ABF substrates, high-purity copper for traces, and specialized lead-free solder alloys. Tariff exposure on semiconductor equipment imports threatens cost structures. Distribution runs through Taiwan-based ODMs and direct hyperscale procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where hyperscale demand for 800G co-packaged optical controllers is displacing commodity merchant silicon.
For Market Incumbents: Lock in captive foundry allocation for 3nm tape-outs before capacity tightens further. Secure AEC-Q100 Grade 2 qualification pipelines for automotive Ethernet controllers as electric vehicle platforms quadruple per-vehicle controller counts. Threat substitution from SmartNIC-DPU consolidation demands defensive R&D in offload acceleration IP. For New Entrants and Emerging Players: Taiwan-based ODMs represent the most penetrable channel partner type for controller-PHY integration partnerships. White-space targets include India's PLI-subsidized assembly corridors and European building automation endpoints requiring EU AI Act-compliant authentication features. Go-to-market leverage rests on 90W Power over Ethernet single-cable solutions for smart surveillance retrofits. For Investors and Strategic Acquirers: Valuations sit cheapest among automotive-qualified controller specialists with AEC-Q100 credentials and zonal E/E architecture design wins. Long-term viability over the next decade hinges on co-packaged optical I/O roadmaps and backward compatibility with hyperscale software stacks. Watch for MIIT GB standard enforcement tightening as a signal for indigenous Chinese controller substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Co-packaged Optical I/O Partnership | TSMC's 3nm packaging capacity enables 51.2T switch silicon integration for hyperscale operators. |
| Automotive Ethernet Qualification | AEC-Q100 Grade 2 certification opens 1Gbps and 10Gbps demand from German electric vehicle platforms. |
| India PLI Manufacturing Investment | Karnataka and Tamil Nadu assembly corridors attract controller test operations for BharatNet tenders. |
| EU AI Act Compliance Integration | Embedded authentication features address chip-level provenance mandates for European networked infrastructure. |
| SerDes IP Backward Integration | In-house 112G and 224G signal conditioning design reduces dependence on concentrated analog engineering talent pools. |
Research Methodology
Coverage spans the United States, Taiwan, Germany, China, and India, with primary inputs from each combining interviews with data center procurement officers, semiconductor packaging engineers, automotive platform architects, and networking equipment ODM sourcing managers. Secondary validation draws from FCC Part 15 filings, EU AI Act regulatory texts, MIIT GB standard publications, and hyperscaler capex disclosures. Bottom-up controller shipment modeling and top-down semiconductor industry triangulation anchor volume estimates.
Rate-of-change decomposition across the analysis window segments by product type, technology, application, and end-user vertical. Modeled dimensions include SerDes performance tier, power delivery integration, and regional certification cluster. CAGRs derive from historical shipment trajectories, foundry capacity expansion schedules, and electric vehicle platform controller content per vehicle assumptions. Forecast inputs incorporate Taiwan foundry allocation data and EU RoHS REACH substance restriction timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to 3nm wafer pricing volatility and co-packaged optical transceiver assembly capacity constraints. Assumptions reflect current regulatory trajectories and hyperscale procurement consolidation patterns. Specific risks include single-source photonics packaging bottlenecks and divergence between FCC, CE marking, and MIIT GB certification timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Audio Power Amplifier Market
Electronic Components
Surface Mountable Laser Direct Structuring Antenna (LDS) Market
Electronic Components
Electronic Shelf Label Market
Electronic Components
Metal Composite Power Inductor Market
Electronic Components
Encoder Market
Electronic Components
Bluetooth Adapter Market
Electronic Components
Digital Potentiometer Market
Electronic Components
Plastics in Consumer Electronics Market
Electronic Components
Stretchable Conductors in Electronics Market
Electronic Components
Electrolytic Capacitor Market
Electronic Components
Ceramic Capacitors Market
Electronic Components
Global Waveguide Components and Assemblies Market
Electronic Components
Multilayer Transparent Conductors Market
Electronic Components
Flexible Heater Market
Electronic Components
Switch Diode Market
Electronic Components
Intel Motherboards Market