
 Single Board Computer Market | 2026-2036
Single Board Computer Market Size, Share, and Industry Trends Forecast 2026-2036
Single Board Computer Market Analysis
Taiwan's semiconductor packaging ecosystem is reshaping supply availability for compact compute modules. Advantech Co Ltd leverages vertical integration across board design and thermal management to sustain pricing power in ruggedized deployments. Aaeon Technology Inc anchors its position through specialized form factors for industrial gateways. Kontron AG competes on certification depth for railway and medical segments.
A single board computer integrates processor, memory, storage, and I/O interfaces onto one printed circuit board, typically measuring under 170mm by 170mm and operating on 5V to 24V DC input. ARM-based designs dominate processing power categories for power-constrained IoT endpoints, while x86 variants command premium positioning in vision-inspection and kiosk applications. Raspberry Pi units anchor education and prototyping volumes through community-supported software ecosystems. Industrial automation end users generate the highest absolute revenue within connectivity-enabled Ethernet configurations.
FCC Part 15 emissions rules in the United States constrain wireless-enabled board designs, while REACH and RoHS compliance in Europe restricts substrate and solder material choices. The EU AI Act's risk-classification framework will soon extend to embedded inference engines on edge-deployed boards. Stakeholders must monitor how cybersecurity certification mandates proliferate across national procurement standards before committing to long hardware refresh cycles.
Market Dynamics
The EU's Cyber Resilience Act is compressing hardware refresh cycles as industrial buyers pre-certify designs against mandatory baseline security standards before the enforcement window closes.
Growth Catalysts
- Industrie 4.0 corridors:Germany's automotive assembly networks are deploying edge computing nodes at scale, creating concentrated demand for Ethernet-enabled ruggedized boards in predictive maintenance applications.
- EU AI Act risk classification:Embedded inference engines on edge-deployed boards face new compliance tiers, driving replacement demand for boards with hardware security modules and trusted execution environments.
- ARM ecosystem maturation:Power-constrained IoT endpoints in smart agriculture and remote monitoring are shifting from x86 to ARM-based designs, opening volume opportunities in battery-operated field deployments.
Market Restraints
- Substrate material restrictions:REACH and RoHS compliance in Europe limits solder alloy choices and PCB substrate formulations, raising qualification costs for boards targeting EU industrial buyers.
- Taiwan packaging concentration:Compact compute module supply hinges on a narrow geographic base of advanced semiconductor packaging facilities, exposing buyers to single-source disruption risk.
- x86 power floor:Vision-inspection and kiosk applications requiring x86 compatibility face thermal design constraints that ARM alternatives bypass, limiting deployment flexibility in fanless enclosures.
Strategic Opportunities
- Railway certification depth:EN 50155 and EN 50121 compliance for rolling stock applications remains underserved, rewarding vendors who pre-validate boards against transit agency procurement standards.
- Medical device integration:IEC 60601-1 isolation requirements for patient-contact equipment create a protected niche for boards with reinforced galvanic isolation and documented risk management files.
- Edge-to-cloud orchestration:Kubernetes-native board firmware is converging with containerized workloads, enabling new service revenue streams through over-the-air update subscriptions.
Industry Challenges
- Embedded Linux talent scarcity:Board vendors struggle to hire kernel engineers capable of maintaining long-term support branches for decade-long industrial deployment horizons.
- Multi-certification stacking:Simultaneous pursuit of FCC Part 15, CE marking, and railway medical approvals stretches engineering bandwidth and delays product launch timelines.
- Legacy fieldbus integration:PROFINET and EtherCAT protocol stacks require specialized silicon support that newer ARM SoCs omit, forcing bridge chip additions that consume board real estate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Board Computer Market |
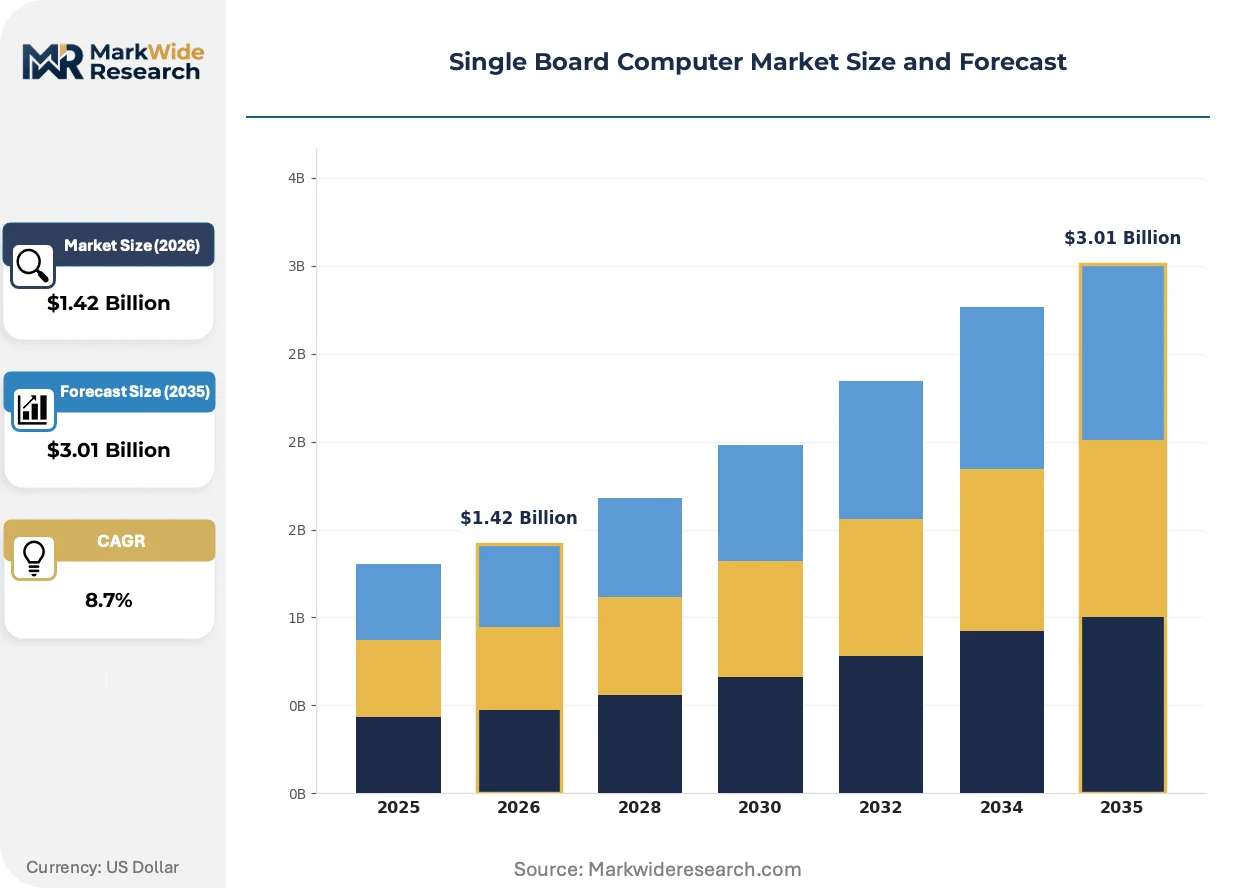
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raspberry Pi, Arduino, BeagleBone, Assimilators End User: Education, Industrial Automation, Robotics, Prototyping Connectivity: Wi-Fi, Bluetooth, Ethernet, USB Processing Power: ARM, x86, MIPS, PowerPC |
| Companies Covered | Advantech Co Ltd, Aaeon Technology Inc, Adlink Technology Inc, Mercury Systems Inc, Intel Corporation, Texas Instruments Incorporated, Qualcomm Incorporated, Raspberry Pi Foundation, Kontron AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Board Computer Market Emerging Trajectories
Virtualization of compute workloads at the edge is collapsing the distinction between dedicated controllers and general-purpose SBCs, enabling software-defined automation architectures that reduce hardware SKU proliferation.
Hardware-based trusted execution environments are virtualizing security-sensitive workloads onto shared SBC platforms. Automotive tier-one suppliers are adopting these designs for gateway consolidation, replacing discrete security modules with partitioned firmware domains. This compression of physical security boundaries is virtualizing what previously required separate hardware stacks.
REACH substance restrictions are tightening solder alloy compositions and flame-retardant specifications for boards entering European industrial supply chains. The ECHA authorization list now captures several legacy PCB laminates, forcing substrate transitions that ripple through qualification timelines. Medical and railway segments in Germany and France are absorbing these compliance costs fastest due to their certification documentation requirements.
Buyer preference is hardening around pre-certified board families that collapse procurement risk. Industrial automation purchasing departments in Stuttgart and Munich are shifting from component-level sourcing to qualified vendor lists with locked firmware configurations. This behavioral pivot is most pronounced in German automotive supply chains, where Cyber Resilience Act readiness now precedes technical evaluation in RFP scoring.
Single Board Computer Market Segmentation
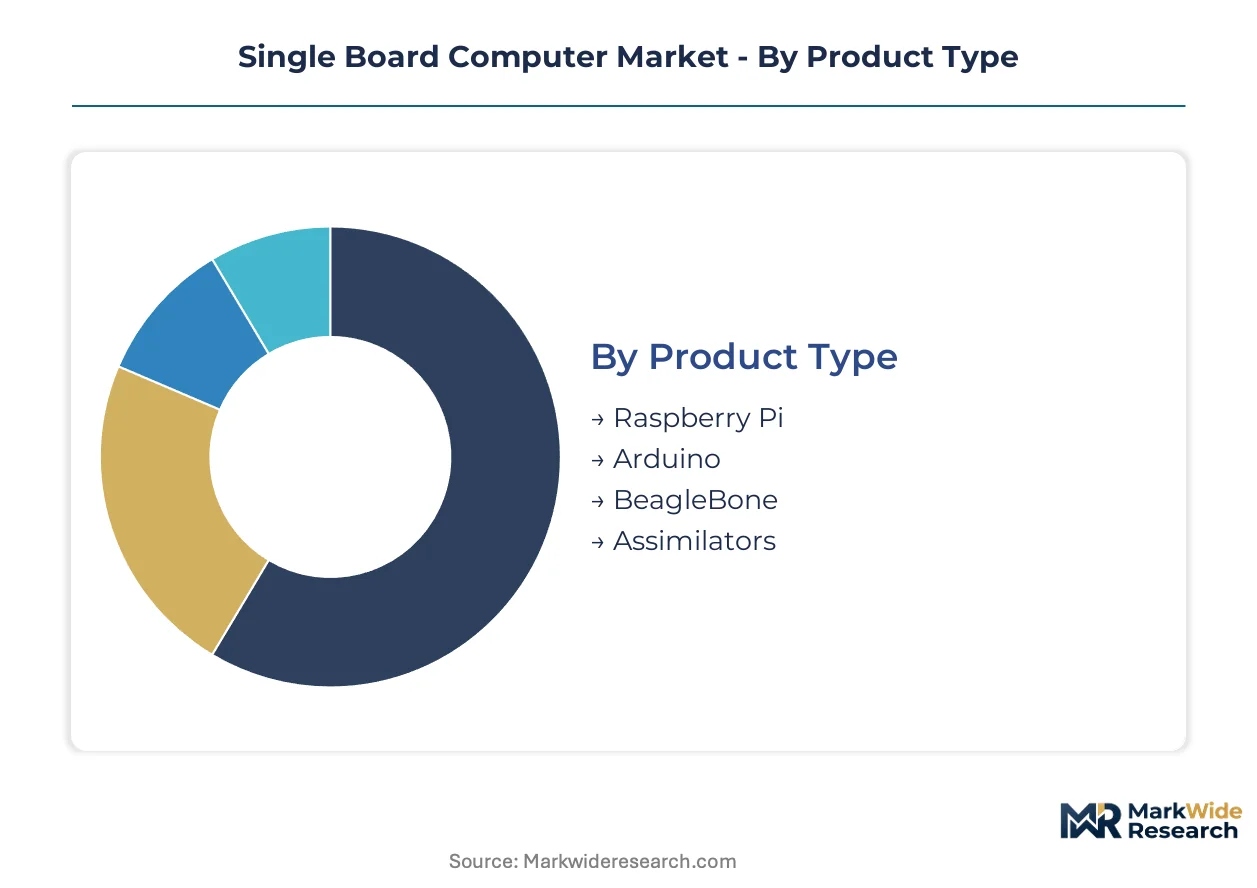
Segmentation in the single board computer market reveals distinct procurement patterns across education budgets, industrial certification requirements, and connectivity specifications. Buyers select architectures based on thermal constraints, software ecosystem maturity, and long-term support horizons rather than unit cost alone.
Product Type:
Mature education platforms anchor volume shipments while emerging industrial-grade assimilators capture premium positioning in ruggedized deployments.
- Raspberry Pi:The BCM2711 quad-core ARM Cortex-A72 powers this credit-card form factor with 40-pin GPIO header and dual micro-HDMI outputs. Education ministries in India and Brazil standardize procurement around this ecosystem due to curriculum-aligned training resources and decade-long software support commitments.
- Arduino:ATmega328P microcontroller units emphasize real-time I/O control over application processing. Italian design origins sustain maker community density, though industrial buyers in Germany's Industrie 4.0 corridors increasingly bypass this segment for Ethernet-native alternatives.
- BeagleBone:Texas Instruments AM335x Sitara processors enable PRU-ICSS programmable real-time units for deterministic control loops.
- Assimilators:Custom carrier-board designs integrating COM Express modules target railway EN 50155 and medical IEC 60601-1 certification stacks.
Raspberry Pi retains volume leadership; assimilators hold the steepest expansion curve.
End User:
Cost tiers separate hobbyist education budgets from industrial automation procurement cycles that amortize hardware across seven-to-ten-year operational lifespans.
- Education:Volume purchases by national curriculum authorities emphasize sub-$35 unit pricing and GPIO accessibility for introductory programming courses. India's CBSE board mandates Raspberry Pi units for Class 11-12 computer science practical examinations.
- Industrial Automation:Predictive maintenance nodes in automotive assembly lines demand -40°C to +85°C operating ranges with locked firmware configurations. Stuttgart and Munich purchasing departments pre-qualify vendor lists against EU Cyber Resilience Act baselines.
- Robotics:ROS 2-native boards with hardware-accelerated kinematics processing command mobility platform integration.
- Prototyping:Rapid validation cycles prioritize community library density over thermal specifications.
Industrial automation commands absolute revenue concentration; robotics demonstrates the steepest expansion trajectory.
Connectivity:
Application requirements dictate interface selection, with vision-inspection systems demanding deterministic Ethernet while agricultural sensors prioritize low-power wireless.
- Ethernet:IEEE 1588 Precision Time Protocol support enables microsecond-synchronized motion control in multi-axis machinery. Germany's automotive tier-one suppliers specify gigabit Ethernet with TSN (Time-Sensitive Networking) for assembly line coordination.
- Wi-Fi:FCC Part 15 emissions certification constrains antenna integration and RF shielding designs for US market entry.
- Bluetooth:BLE 5.2 mesh networking supports battery-operated sensor arrays in smart agriculture deployments.
- USB:USB 3.0 vision camera interfaces dominate quality inspection stations requiring high-bandwidth image pipelines.
Ethernet retains revenue leadership; Wi-Fi climbs fastest in remote monitoring applications.
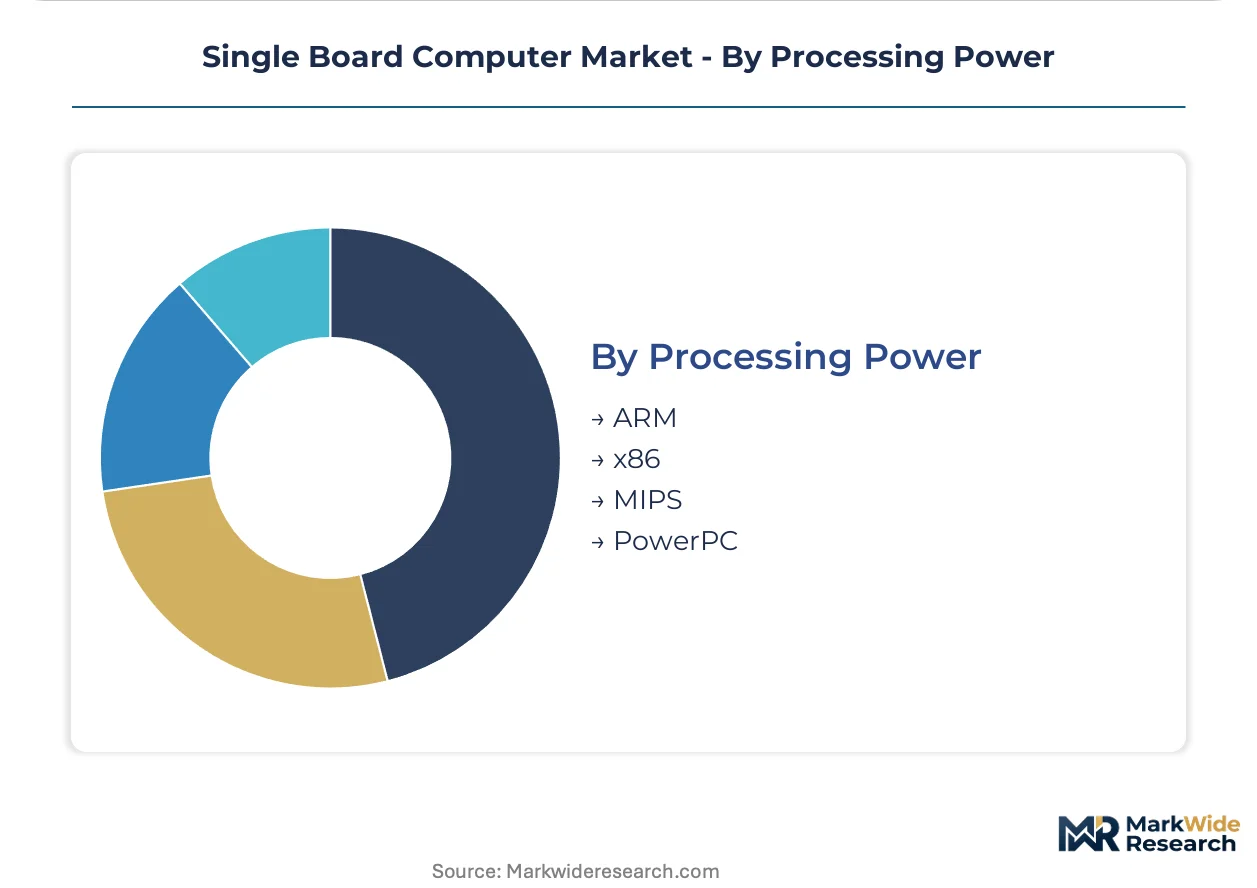
Processing Power:
Architecture selection hinges on software ecosystem lock-in versus thermal design power constraints in fanless enclosures.
- ARM:Cortex-A78AE automotive-grade cores with functional safety certification target gateway consolidation in vehicle architectures. Power consumption below 15W TDP enables battery-operated field instrumentation across Nordic remote monitoring networks.
- x86:Intel Elkhart Lake and AMD Ryzen Embedded R-series sustain legacy Windows application compatibility for kiosk and HMI terminals. Thermal dissipation requirements limit deployment in sealed IP67 enclosures without active cooling.
- MIPS:Legacy router and network appliance designs maintain maintenance-phase procurement.
- PowerPC:NXP QorIQ communications processors persist in telecommunications infrastructure refresh cycles.
x86 holds revenue concentration in premium vision applications; ARM gains share fastest in power-constrained edge nodes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Industrie 4.0 manufacturing corridors anchor European demand, while REACH and RoHS compliance from ECHA tightens material specifications across the continent. Buyers in Stuttgart and Munich procurement departments now pre-qualify vendor lists against EU Cyber Resilience Act baselines before technical evaluation.
Germany
Automotive assembly networks in Stuttgart and Munich deploy edge computing nodes at scale for predictive maintenance applications. The EU Cyber Resilience Act mandates baseline security standards for connected embedded systems, compressing hardware refresh cycles. Bavaria's automotive tier-one suppliers specify gigabit Ethernet with Time-Sensitive Networking for assembly line coordination.
United States
Vision-inspection systems and kiosk applications sustain demand for x86-compatible boards with legacy Windows support. FCC Part 15 emissions rules constrain wireless-enabled board designs, particularly affecting antenna integration and RF shielding. California's industrial automation buyers absorb these certification costs while deploying edge nodes in semiconductor fabrication facilities.
China
Smart agriculture and remote monitoring deployments drive volume demand for power-constrained ARM-based designs in battery-operated field instrumentation. MIIT standards govern telecommunications infrastructure refresh cycles affecting board specifications. The Yangtze River Delta concentration of electronics manufacturing clusters shapes procurement patterns for compact compute modules.
Japan
Industrial gateway applications and robotics integration command premium positioning for boards with deterministic control capabilities. METI industrial policy supports edge-to-cloud orchestration architectures in manufacturing modernization programs. The Nagoya automotive manufacturing corridor generates concentrated demand for Ethernet-enabled ruggedized boards.
India
National curriculum authorities standardize education ministry procurement around sub-dollar unit pricing for introductory programming platforms. The CBSE board mandates specific single board computer units for Class 11-12 computer science practical examinations. Karnataka's technology corridor hosts assembly operations serving domestic education and prototyping segments.
Single Board Computer Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base separates into industrial certification specialists, community-supported education platforms, and semiconductor originators with captive board portfolios. Two archetypes dominate: vertically integrated thermal management specialists and form-factor innovators targeting gateway consolidation. Competitive moves center on pre-certification against railway and medical standards, plus locked firmware configurations for industrial procurement.
Within the industrial certification tier, Advantech Co Ltd and Kontron AG exemplify positioning around regulatory depth. Aaeon Technology Inc occupies a position among form-factor specialists. These three represent divergent strategic anchors: vertical integration across board design and thermal management, certification stacking for transit agency procurement standards, and specialized carrier configurations for industrial gateways.
| Leading Market Players |
|---|
| Advantech Co Ltd |
| Aaeon Technology Inc |
| Adlink Technology Inc |
| Mercury Systems Inc |
| Intel Corporation |
| Texas Instruments Incorporated |
| Qualcomm Incorporated |
| Raspberry Pi Foundation |
| Kontron AG |
| Others |
Supply Flow & Price Mechanics
The Kaohsiung-to-Long Beach freight corridor carries substrate-laden containers whose spot-rate volatility feeds directly into board-level cost structures. Taiwan's packaging concentration compresses margin buffers for EU-bound shipments facing REACH compliance surcharges, while German automotive buyers absorb premium freight costs to secure pre-certified industrial-grade units.
Pricing Analysis
Geographic price spreads between Stuttgart procurement offices and Shenzhen distribution hubs exceed certification-grade differentials. Three-tier pricing structure across industrial-certified, commercial-grade, and education-volume levels dominates, with EN 50155 railway compliance and IEC 60601-1 medical isolation driving premium positioning. Cost compression in education-tier Raspberry Pi volumes intensifies as India's CBSE mandates standardize procurement around sub-dollar targets. Industrial automation buyers demonstrate lowest price sensitivity, amortizing hardware across decade-long deployment horizons.
Supply Chain Analysis
Upstream feedstock for ARM SoC substrates draws from Taiwan's advanced packaging foundries, South Korea's memory fabrication clusters, and Japan's high-reliability laminate suppliers. ABF substrate, DDR4 memory modules, and automotive-grade passive components constitute critical input dependencies. Single-source vulnerability around Taiwan's CoWoS packaging capacity exposes buyers to allocation rationing during demand spikes. Distribution runs through authorized industrial distributors in Stuttgart and direct-to-education channels in Bangalore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
System-on-module consolidation threatens discrete SBC architectures as automotive tier-one suppliers virtualize gateway functions. Incumbents must defend against this substitution through certification depth and firmware lock-in.
For Market Incumbents: Harden position against SoC module encroachment by deepening EN 50155 and IEC 60601-1 certification stacks that system-in-package alternatives cannot replicate. Secure backward integration into thermal management substrates to defend margin structures against Taiwan packaging cost volatility. Prioritize locked firmware configurations that embed Cyber Resilience Act readiness into procurement scoring.
For New Entrants and Emerging Players: Build out presence in smart agriculture edge nodes across Nordic remote monitoring networks, where battery-operated ARM designs face limited incumbent saturation. Target railway signaling retrofits in Eastern European markets where EN 50121 compliance documentation remains sparse. Pursue Kubernetes-native firmware subscriptions as a service revenue wedge.
For Investors and Strategic Acquirers: Carve-out targets emerge from semiconductor conglomerates' captive board portfolios that lack standalone industrial certification depth. Long-term viability hinges on cybersecurity mandate proliferation across national procurement standards. Watch for EU AI Act enforcement windows that trigger replacement demand for boards with hardware security modules.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Validation | EN 50155 railway compliance collapses procurement cycles for Stuttgart automotive suppliers. |
| Firmware Lock-In Programs | Locked configurations embed Cyber Resilience Act readiness into Munich purchasing department scoring. |
| Backward Integration | In-house thermal substrate production defends margins against Taiwan packaging cost volatility. |
| Edge-to-Cloud Orchestration | Kubernetes-native firmware enables recurring revenue through over-the-air update subscriptions. |
| Medical Isolation Specialization | IEC 60601-1 galvanic isolation creates protected niche against system-on-module substitution. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with industrial automation procurement directors, embedded systems engineers, railway certification specialists, and education ministry technology officers; and secondary validation against ECHA substance restriction databases, FCC Part 15 filing records, and SEC disclosures from semiconductor packaging firms. Bottom-up volume estimates triangulated with top-down spend analysis across German Industrie 4.0 corridors.
Forecast inputs span processing architecture migration rates, EU regulatory enforcement timelines, and Taiwan packaging capacity utilization trajectories across the analysis window. Segmentation dimensions include product form factor, end-use certification tier, connectivity protocol, and regional procurement cluster. CAGRs derive from elasticity modeling against industrial automation capex cycles and education ministry budget trajectories. SoC integration pace and embedded Linux talent scarcity index as industry-specific modifiers.
Practitioners should monitor Taiwan packaging allocation announcements and EU AI Act delegated act publications for early signals of supply constraint or compliance timeline acceleration. Cross-checking against IHS Markit industrial automation equipment forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IT Hardware
PC Case Market
IT Hardware
Industrial Motherboards Market
IT Hardware
Global IT Hardware Market
IT Hardware
Asia Pacific IT Device Market
IT Hardware
Cloud IT Infrastructure Hardware Market
IT Hardware
Tablet PC Market
IT Hardware
Global 4K Set Top Box (STB) Market
IT Hardware
India IT Hardware Market
IT Hardware
Three-Proof Laptop Market
IT Hardware
Europe IT Device Market
IT Hardware
Middle East and Africa IT Device Market
IT Hardware
Server Chassis Market
IT Hardware
USB 3.0 Market