
 Power Amplifier Modules Market | 2026-2036
Power Amplifier Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Power Amplifier Modules Market Analytics
Asset-light foundry partnerships and contract manufacturing arrangements is fragmenting competitive tiers across the Power Amplifier Modules landscape. Skyworks Solutions leverages captive GaAs fabrication to sustain margin control in mobile handset segments. Qorvo anchors its position through vertical integration into BAW filter and GaN process technology. Infineon Technologies dominates automotive-qualified LDMOS supply for radar and telematics applications.
Power amplifier modules integrate active semiconductor devices, impedance matching networks, and thermal management substrates into hermetic or overmolded packages designed to boost signal power across frequencies from sub-GHz to millimeter-wave bands, with output power ranging from milliwatts in mobile devices to kilowatts in broadcast transmitters. Solid-state architectures based on GaN and LDMOS now lead wireless infrastructure deployments due to superior power-added efficiency and linearity compared to legacy vacuum tube alternatives. GaN technology captures the fastest expansion trajectory as defense contractors and space agencies specify wideband, high-temperature operation for next-generation radar and satellite payloads.
FCC spectrum auctions and NTIA frequency coordination in the United States, EU Radio Equipment Directive harmonization across member states, and China's MIIT 5G base station certification regime collectively tighten efficiency, spurious emission, and thermal compliance thresholds. EAR and ITAR export controls further segment accessible technology tiers between allied and restricted defense markets. Stakeholders must weigh foundry access constraints against captive process development costs when committing to GaN or SiC technology roadmaps.
Market Dynamics
GaN-on-SiC technology transitions are compressing thermal budgets and forcing foundry capacity reallocation across defense and wireless infrastructure supply chains, with procurement patterns fragmenting between captive fabrication and outsourced module assembly.
Growth Catalysts
- 5G base station densification:Telecom operators in China, the United States, and Germany are expanding macro and small-cell deployments. MIIT certification requirements and FCC spectrum auctions accelerate module refresh cycles.
- REACH and RoHS compliance harmonization:EU directives on hazardous substance restrictions and energy efficiency standards tighten spurious emission thresholds. Module suppliers redesign thermal substrates to meet CE marking requirements.
- Defense radar modernization:ITAR-controlled programs specify wideband GaN operation for next-generation electronic warfare and satellite payloads. Thermal management specifications now exceed legacy LDMOS capabilities.
Market Restraints
- SiC substrate supply concentration:Wolfspeed, Coherent, and II-VI dominate 6-inch and 8-inch SiC wafer supply. Foundry access constraints limit second-source qualification for defense contractors.
- EAR export licensing friction:Commerce Department restrictions on GaN process technology create tiered market access between allied and restricted defense markets. Chinese module suppliers face foundry equipment procurement delays.
- Vacuum tube substitution ceiling:Legacy traveling-wave tubes retain cost advantages in ultra-high-power broadcast transmitters above 10 kW. Solid-state architectures face power-combining complexity at these thresholds.
Strategic Opportunities
- Automotive radar module qualification:Infineon and NXP are expanding LDMOS and SiGe capacity for 77-81 GHz frequency-modulated continuous-wave radar. AEC-Q100 and AEC-Q101 certification creates barrier to entry for commodity suppliers.
- LEO satellite constellation buildouts:SpaceX Starlink and Amazon Kuiper specify GaN solid-state power amplifiers for phased-array user terminals. Thermal cycling requirements differ from terrestrial base station specifications.
- India PLI scheme for telecom equipment:Production-linked incentives for 5G radio access network manufacturing attract module assembly investments. BIS certification requirements favor local testing infrastructure development.
Industry Challenges
- Compound semiconductor process engineering talent scarcity:GaN HEMT and SiC MOSFET fabrication requires specialized epitaxy and defect engineering expertise. Foundries compete for limited pools of experienced device physicists.
- Multi-physics simulation complexity:Electromagnetic-thermal-mechanical co-design for millimeter-wave modules demands integrated ANSYS and Cadence workflows. Design cycle compression conflicts with first-pass yield targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Amplifier Modules Market |
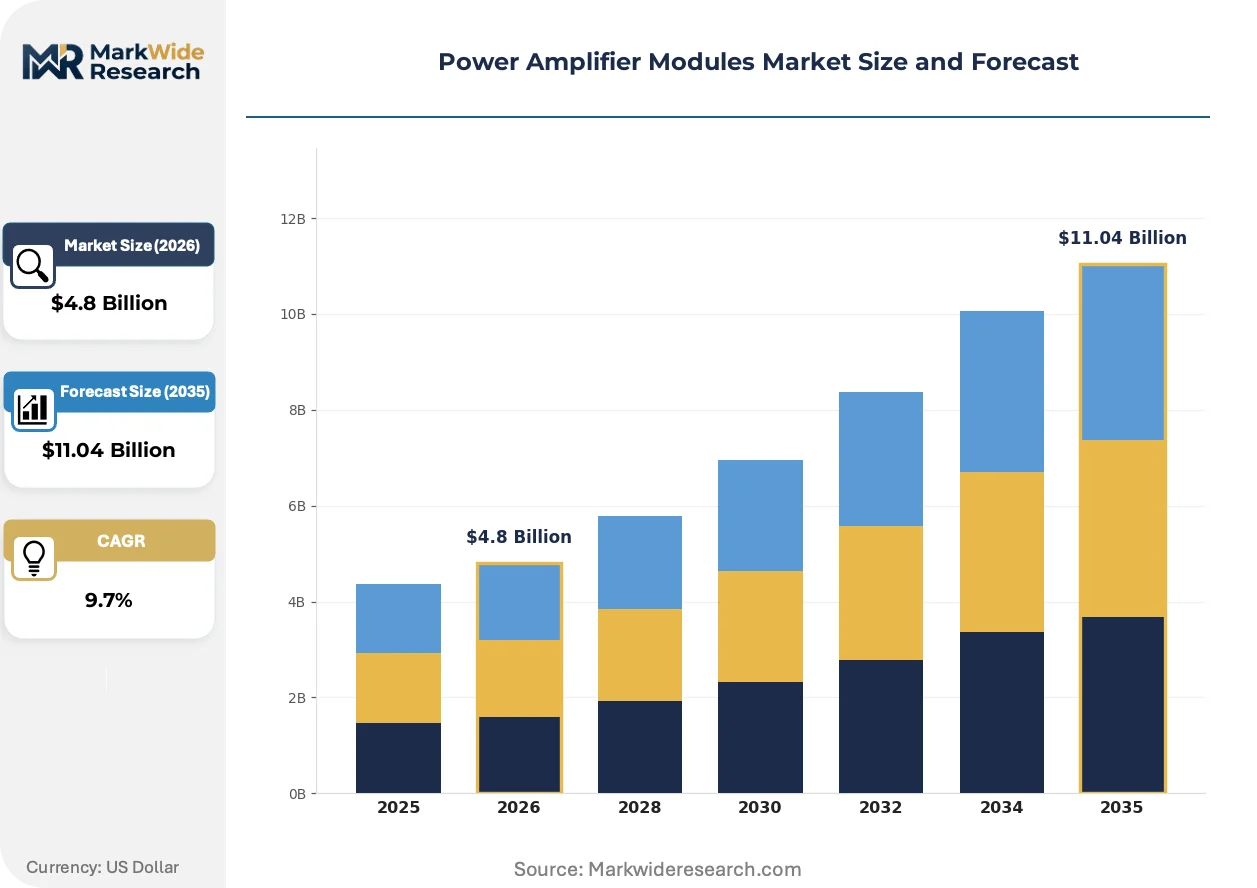
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid State, Traveling Wave Tube, Hybrid, Vacuum Tube Technology: GaN, LDMOS, GaAs, SiC Application: Wireless Infrastructure, Radar Systems, Satellite Communication, Broadcast Transmitters End User: Telecom Operators, Defense Contractors, Space Agencies, Broadcasting Companies |
| Companies Covered | Skyworks Solutions, Qorvo, Broadcom, Infineon Technologies, NXP Semiconductors, Analog Devices, Texas Instruments, STMicroelectronics, Murata Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Amplifier Modules Market Evolving Landscape
Digital predistortion and envelope tracking algorithms are displacing analog linearization techniques, compressing module bill-of-materials while tightening adjacent channel leakage ratio specifications across base station and handset applications.
Envelope tracking power supply integration is virtualizing the boundary between RF front-end and power management subsystems. Smartphone original equipment manufacturers specify co-packaged GaAs power amplifiers with DC-DC converters to extend battery endurance during high-data-rate transmission. This convergence is virtualizing traditional discrete component procurement categories and forcing module suppliers to acquire power semiconductor design capabilities.
FCC Part 27 and NTIA frequency coordination orders in the United States mandate stricter out-of-band emission limits for C-band and 3.5 GHz CBRS deployments. Module manufacturers redesign harmonic termination networks and invest in high-volume automated tuning equipment. Base station original equipment manufacturers in North America now specify third-order intermodulation distortion performance 3 dB tighter than 3GPP minimum requirements.
Defense procurement offices are consolidating vendor qualification lists and mandating domestic foundry sourcing for strategic programs. Tier-1 contractors respond by acquiring captive GaN fabrication or executing long-term supply agreements with qualified foundries. This concentration is most visible in Pentagon radar and electronic warfare programs where ITAR compliance and supply chain traceability requirements exclude non-domestic module sources.
Power Amplifier Modules Market Segmentation
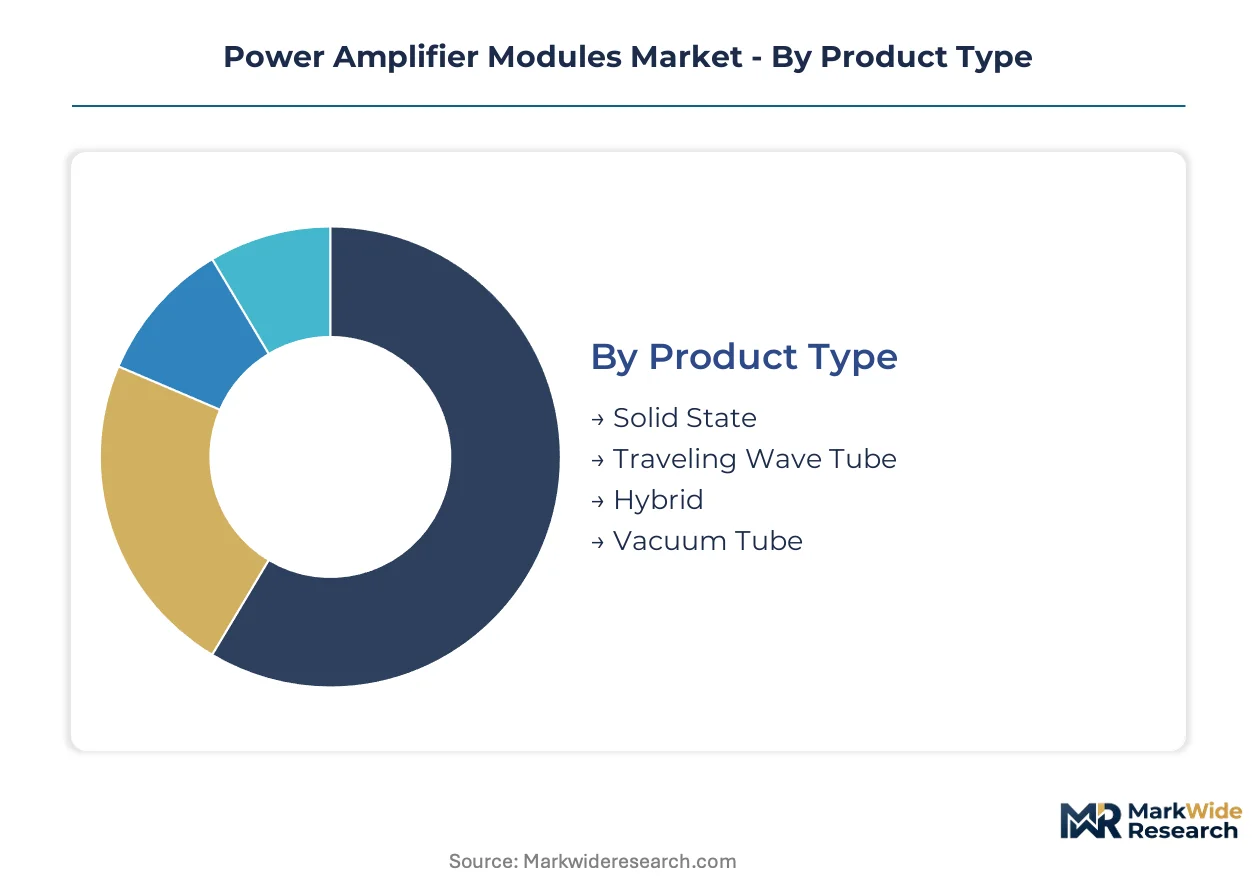
Power amplifier modules exhibit distinct service intensity profiles across technology generations, with GaN-on-SiC devices demanding specialized thermal recalibration protocols while legacy LDMOS installations rely on standardized field replacement programs. Segmentation reveals how procurement patterns fragment between captive maintenance networks and third-party service providers.
Product Type:
After-sales service intensity varies dramatically across architectures, with solid-state modules requiring predictive thermal monitoring while vacuum tube systems depend on filament replacement schedules and specialized handling protocols.
- Solid State:Semiconductor-based architectures integrate GaN HEMT or LDMOS transistors with impedance matching networks in hermetic packages. Telecom operators in China and the United States specify these for 5G macro base stations, driven by FCC efficiency mandates and MIIT certification requirements that obsolete legacy alternatives.
- Traveling Wave Tube:Vacuum electron devices amplify signals through interaction between electron beams and slow-wave structures, achieving kilowatt-level output at millimeter-wave frequencies. Defense contractors specify these for electronic warfare transmitters where solid-state power combining remains economically prohibitive above 10 kW thresholds.
- Hybrid:Combines solid-state driver stages with vacuum tube power sections to balance linearity and efficiency in broadcast applications.
- Vacuum Tube:Legacy triode and tetrode architectures persist in ultra-high-power AM broadcast transmitters where replacement cycles extend beyond fifteen years.
Solid State holds the largest share; momentum sits with Hybrid configurations bridging power and efficiency requirements.
Technology:
Cost tier stratification separates premium GaN-on-SiC modules from commodity LDMOS alternatives, with price differentials reflecting substrate scarcity and epitaxial process complexity rather than assembly economics alone.
- GaN:Gallium nitride HEMT devices on SiC substrates deliver wideband operation above 100 GHz with power-added efficiency exceeding 70 percent. Space agencies in the United States and Germany specify these for LEO satellite phased arrays, constrained by Wolfspeed and Coherent wafer supply allocation and ITAR export licensing friction.
- LDMOS:Laterally-diffused metal-oxide-semiconductor technology dominates sub-6 GHz wireless infrastructure through mature 8-inch silicon fabrication. Infineon anchors automotive radar supply with AEC-Q101-qualified devices, while telecom operators in Germany leverage these for cost-optimized rural 5G deployments.
- GaAs:Gallium arsenide pHEMT devices capture handset power amplifier sockets through Skyworks captive foundry supply.
- SiC:Silicon carbide substrates serve as thermal management platforms for GaN epitaxy rather than active RF devices in this market.
LDMOS retains volume leadership; GaN claims the steepest expansion trajectory across defense and space applications.
Application:
Customer type concentration distinguishes volume-driven wireless infrastructure procurement from project-based defense and space contracting, with qualification timelines and technical documentation requirements shaping supplier relationships.
- Wireless Infrastructure:Macro and small-cell base stations integrate multi-band power amplifier modules with digital predistortion linearization. China MIIT certification and FCC Part 27 mandates accelerate refresh cycles as operators densify 5G networks.
- Radar Systems:Active electronically scanned arrays demand wideband GaN modules with instantaneous bandwidth exceeding 500 MHz. Pentagon programs specify domestic foundry sourcing with ITAR compliance and full supply chain traceability.
- Satellite Communication:Geostationary and LEO payloads require radiation-hardened amplifiers with thermal cycling tolerance across orbital temperature extremes.
- Broadcast Transmitters:Terrestrial television and radio infrastructure specifies either solid-state or tube-based architectures depending on channel count and geographic coverage requirements.
Wireless Infrastructure commands the largest share; Satellite Communication is expanding most quickly through constellation deployment schedules.
End User:
Geographic procurement concentration centers module demand in China, the United States, and Germany, with each market imposing distinct certification regimes and domestic content requirements.
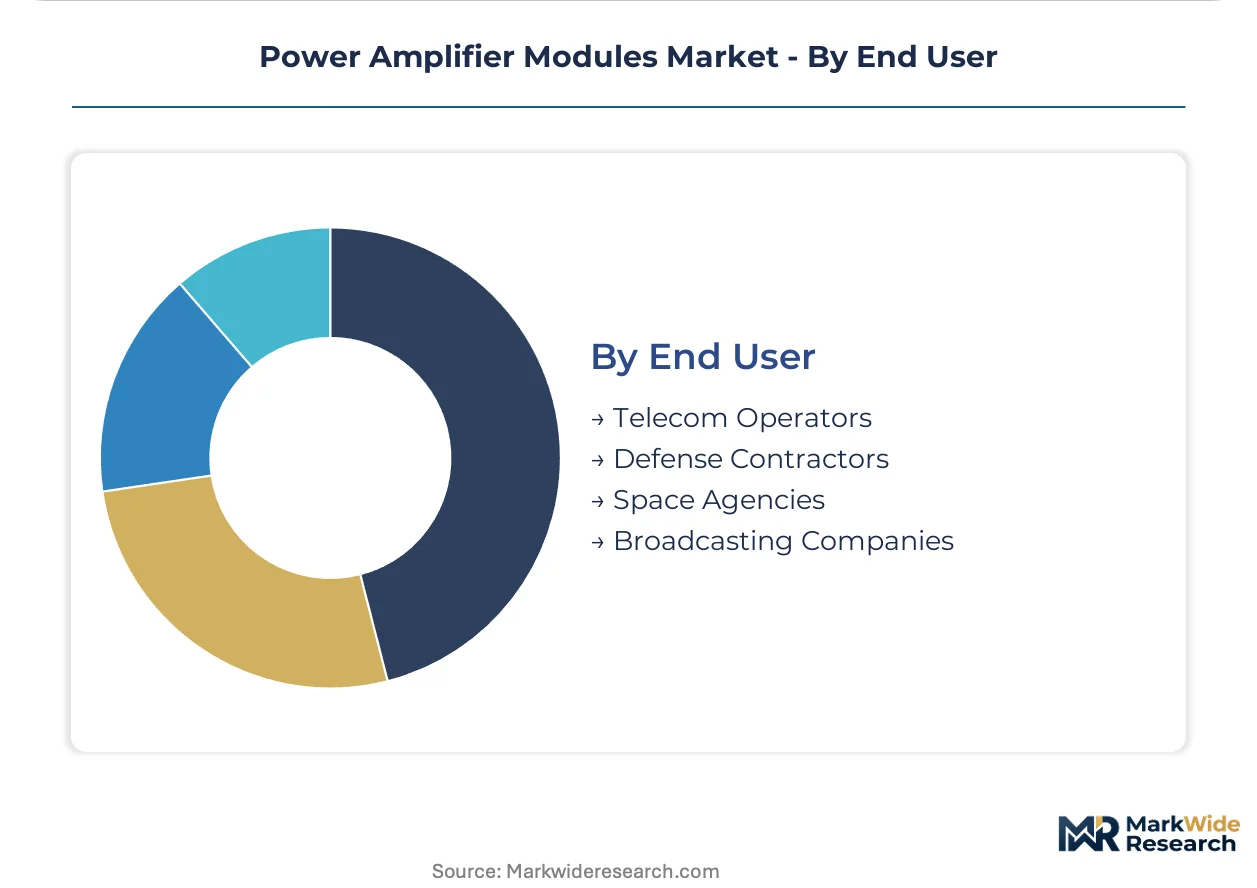
- Telecom Operators:China Mobile, Verizon, and Deutsche Telekom drive volume procurement through RFP specifications that tighten efficiency and spurious emission thresholds beyond 3GPP minima. India PLI scheme incentives are redirecting assembly investments toward domestic BIS certification pathways.
- Defense Contractors:Raytheon, Lockheed Martin, and BAE Systems consolidate vendor qualification lists and mandate captive or domestic foundry sourcing for strategic radar programs.
- Space Agencies:NASA, ESA, and national programs specify radiation-hardened GaN modules with qualification protocols extending across thermal vacuum and vibration testing.
- Broadcasting Companies:Regional network operators maintain legacy tube-based transmitters through specialized maintenance contracts while transitioning new installations to solid-state architectures.
Telecom Operators hold the largest share; Defense Contractors are gaining share fastest through modernization program acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentives and spectrum auction regimes are redrawing procurement geography across the Power Amplifier Modules landscape. National certification requirements and domestic content mandates now shape where module assembly and foundry investments concentrate.
United States
Pentagon radar modernization programs and FCC Part 27 spectrum mandates drive GaN module procurement. ITAR compliance requirements and NTIA frequency coordination orders restrict foundry sourcing to domestic qualified suppliers. Defense contractors in Massachusetts and California anchor electronic warfare and satellite payload development clusters.
China
MIIT 5G base station certification accelerates module refresh cycles for macro and small-cell densification. National dual carbon goals tighten energy efficiency thresholds for telecom infrastructure procurement. Module assembly investments cluster in the Yangtze River Delta and Pearl River Delta manufacturing corridors.
Germany
Automotive radar module demand from Infineon and NXP supply chains concentrates LDMOS procurement for 77-81 GHz applications. EU Radio Equipment Directive harmonization and REACH compliance tighten spurious emission standards. Bavaria and Baden-Württemberg host automotive-qualified foundry and testing infrastructure.
India
PLI scheme incentives for 5G radio access network manufacturing attract module assembly investments from telecom operators. BIS certification requirements and TRAI spectrum allocation orders favor local testing infrastructure development. Karnataka and Maharashtra emerge as assembly and qualification hubs for export-oriented production.
South Korea
MFDS regulatory coordination and national 5G spectrum policies sustain base station module demand from domestic telecom operators. Samsung and LG supply chain proximity drives GaAs handset amplifier procurement. Seoul Capital Area and Busan-Ulsan regions concentrate RF front-end module packaging and test capacity.
Power Amplifier Modules Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Captive foundry operators maintain margin control through backward integration into GaAs and GaN process technology. Three archetypes dominate: integrated IDMs with captive fabrication, fabless designers relying on outsourced assembly, and defense-focused suppliers with ITAR-qualified domestic sourcing. Competitive moves concentrate on long-term supply agreements with SiC substrate vendors and acquisition of power semiconductor design capabilities.
Among US-based RF specialists, Skyworks Solutions, Qorvo, and Broadcom exemplify contrasting strategic positions. Skyworks occupies a captive-foundry archetype with in-house GaAs fabrication for mobile handset segments. Qorvo represents vertical integration into BAW filter and compound semiconductor process technology. Broadcom sits within the scale-driven diversified semiconductor tier, leveraging module expertise across wireless and wired infrastructure applications.
| Leading Market Players |
|---|
| Skyworks Solutions |
| Qorvo |
| Broadcom |
| Infineon Technologies |
| NXP Semiconductors |
| Analog Devices |
| Texas Instruments |
| STMicroelectronics |
| Murata Manufacturing |
| Others |
Value Network & Pricing Analysis
Undercapacity in 6-inch and 8-inch SiC wafer fabrication at Wolfspeed and Coherent facilities concentrates pricing power among substrate vendors while forcing module suppliers into long-term offtake commitments that lock in cost structures across multi-year defense and telecom procurement cycles.
Pricing Analysis
Certification level (ITAR-compliant vs. commercial-grade) creates the primary spread between premium GaN-on-SiC modules and commodity LDMOS alternatives. Three-tier pricing structure across ITAR-restricted, automotive-qualified, and commercial-grade tiers reflects foundry access constraints and qualification timeline differentials. Cost compression in commercial wireless infrastructure segments intensifies as Chinese module suppliers expand domestic GaN capacity. Telecom operators exhibit highest price sensitivity due to volume procurement and multi-vendor RFP processes, while defense contractors accept premium pricing for domestic foundry sourcing and supply chain traceability.
Supply Chain Analysis
SiC substrate supply concentrates in the United States, Japan, and Germany through Wolfspeed, Coherent, and II-VI manufacturing footprints. GaN epitaxy equipment and specialty gases draw from concentrated chemical processing hubs in Germany and Japan. Single-source vulnerability in 6-inch SiC wafer supply creates qualification bottlenecks for second-source defense contractors. Distribution runs through tiered channels: direct foundry relationships for defense primes, contract manufacturers for telecom OEMs, and specialized distributors for aftermarket replacement modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among tier-1 defense contractors and national telecom operators shifts bargaining power toward buyers capable of mandating captive foundry sourcing and multi-year supply agreements.
For Market Incumbents: Build process-technology moats through backward integration into GaN HEMT fabrication or exclusive SiC substrate offtake agreements. Acquire power semiconductor design capabilities to capture envelope tracking integration opportunities in smartphone RF front-ends. Lockheed Martin and Raytheon vendor consolidation threatens margin compression for non-qualified suppliers. Capacity addition in domestic ITAR-compliant foundries represents the critical defensive lever. For New Entrants and Emerging Players: India's PLI scheme for 5G radio access network manufacturing represents the most penetrable entry point for module assembly investments without legacy foundry infrastructure. LEO satellite constellation suppliers offer project-based contracting with less stringent qualification barriers than Pentagon radar programs. Partner with domestic testing laboratories for BIS certification to accelerate market access before incumbent localization investments mature. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among defense-focused suppliers with multi-year program-of-record contracts and ITAR-compliant domestic sourcing. Long-term viability hinges on compound semiconductor process engineering talent retention and SiC substrate supply security. Acquisition target archetype: fabless designers with BAW filter integration capabilities and existing telecom OEM relationships. Monitor Pentagon vendor qualification list consolidation as inflection indicator for strategic sourcing shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term SiC Substrate Supply Agreement | Secures wafer allocation from Wolfspeed or Coherent for defense qualification programs. |
| GaN Process Technology Acquisition | Adds captive HEMT fabrication capability to meet ITAR domestic sourcing mandates. |
| Envelope Tracking Integration Development | Captures smartphone power management convergence through DC-DC co-packaging expertise. |
| India PLI Scheme Localization Investment | Positions for BIS-certified assembly capacity serving domestic 5G infrastructure procurement. |
| Automotive Radar Module Qualification | Opens AEC-Q101-certified supply to Infineon and NXP automotive tier-1 channels. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC spectrum auction records, MIIT certification filings, Pentagon budget justification documents, and SEC 10-K disclosures from compound semiconductor suppliers. Primary interviews engaged RF front-end procurement managers at telecom operators, GaN process engineering directors at foundries, defense contractor supplier qualification leads, and satellite payload systems engineers. Bottom-up module shipment estimates triangulate against top-down infrastructure capex allocations across 5G, radar, and space applications.
Forecast inputs include technology transition timelines for GaN-on-SiC versus LDMOS, foundry capacity expansion announcements, and regulatory certification requirement changes. Segmentation dimensions span product architecture, semiconductor technology, application vertical, and end-user procurement type. CAGRs derive from installed base replacement cycles, spectrum auction schedules, and constellation deployment timelines across the projection horizon. Defense modernization program acceleration and LEO satellite manufacturing ramp rates constitute primary demand-side variables.
Practitioners should monitor SiC substrate capacity utilization, ITAR licensing queue lengths, and India PLI scheme disbursement rates for early signals of supply constraint easing or procurement geography shifts. Forecasts reflect assumptions regarding foundry yield improvements and defense budget continuity that material revision of SiC wafer supply agreements or Pentagon program cancellations could alter. Cross-checking against NTIA frequency coordination orders and MIIT base station certification statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
String Inverter Market
Power Systems
Power Supply and Charger Market
Power Systems
Automotive Power Electronics Market
Power Systems
Global Data Center Transformer Market
Power Systems
Batteries for Semiconductor Market
Power Systems
Asia-Pacific Electric Vehicle Power Inverter Market
Power Systems
MCR Based Static VAR Compensator Market
Power Systems
Global Uninterruptible Power Supply (UPS) Market
Power Systems
Embedded Power Generation Market
Power Systems
Global Plasma Generators Market
Power Systems
Asia-Pacific Shunt Reactors Market
Power Systems
Voltage Stabilizer System Market
Power Systems
Three-Phase String Inverter Market
Power Systems
Power Electronics Market
Power Systems
DC-DC Converter Market
Power Systems
Solid State Power Controller Market