
 Global Power Discrete and Modules Market | 2026-2036
Global Power Discrete and Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Global Power Discrete and Modules Market Outlook
AEC-Q101 qualification for automotive-grade discrete semiconductors is bifurcating the supplier landscape into qualified and non-qualified tiers. Infineon Technologies AG leverages its vertically integrated SiC substrate capacity to anchor premium module supply for traction inverters. STMicroelectronics sustains broad silicon MOSFET portfolios that dominate industrial motor drive sockets. onsemi specializes in intelligent power modules that integrate gate drivers and protection circuitry for appliance and automotive clients.
Power discrete devices and modules comprise individual semiconductor switches and multi-die assemblies engineered for voltage ratings from tens to thousands of volts and current handling from milliamps to kiloamperes, fabricated through epitaxial growth, ion implantation, and trench etch processes to achieve low on-resistance and fast switching speeds for energy conversion and motion control. Silicon carbide technology captures the fastest expansion trajectory as electric vehicle platforms above 800 volts demand reduced switching losses and higher thermal budgets, while silicon MOSFETs and IGBTs retain volume leadership in cost-sensitive industrial variable frequency drives and uninterruptible power supplies. Gallium nitride transistors carve a distinct niche in sub-10-kW power supplies where megahertz switching enables compact magnetics.
FDA device regulations indirectly shape medical power supply specifications, while EPA efficiency standards and NHTSA electrification mandates in the United States tighten converter loss budgets across automotive and industrial end uses. The EU Green Deal's embedded carbon requirements and REACH substance restrictions are altering material selection and foundry location decisions for European-bound modules. Stakeholders must monitor how China's MIIT dual carbon enforcement and GB standard updates for EV charging infrastructure redirect domestic capacity allocation and export availability.
Market Dynamics
The 800-volt electric vehicle platform migration is compressing silicon IGBT dominance while expanding silicon carbide module procurement volumes across automotive inverter supply chains.
Growth Catalysts
- EU Ecodesign Directive:Efficiency mandates for motor drives and power supplies are accelerating replacement cycles in European industrial automation corridors.
- Silicon carbide substrate availability:Captive SiC crystal growth capacity at major suppliers is reducing module cost premiums for traction inverter applications.
- China's dual carbon enforcement:MIIT carbon intensity targets are redirecting domestic semiconductor capacity toward EV charging infrastructure and renewable energy converters.
Market Restraints
- Epitaxial wafer supply concentration:SiC epitaxy capacity concentrates among Japanese and US substrate specialists, creating allocation bottlenecks during demand surges.
- Copper and rare earth magnet cost volatility:Power module packaging and motor integration expose supply chains to commodity price swings in thermal interface materials.
- Silicon MOSFET technical ceiling:Junction temperature and switching frequency limitations prevent silicon devices from serving 800-volt automotive platforms without excessive cooling overhead.
Strategic Opportunities
- India's PLI scheme for semiconductors:Domestic assembly incentives are attracting power module packaging investments for appliance and automotive export markets.
- GaN-SiC hybrid integration:Combining gallium nitride high-frequency capability with silicon carbide high-voltage tolerance enables next-generation onboard chargers.
- Direct OEM procurement channels:Tier-1 automotive suppliers are bypassing traditional distribution to secure allocated SiC module supply through multi-year contracts.
Industry Challenges
- AEC-Q101 certification timelines:Automotive qualification protocols extend product development cycles and strain engineering resources at mid-tier suppliers.
- Legacy IGBT inventory rationalization:Industrial customers face write-down risks as they transition variable frequency drive fleets to SiC-based alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Power Discrete and Modules Market |
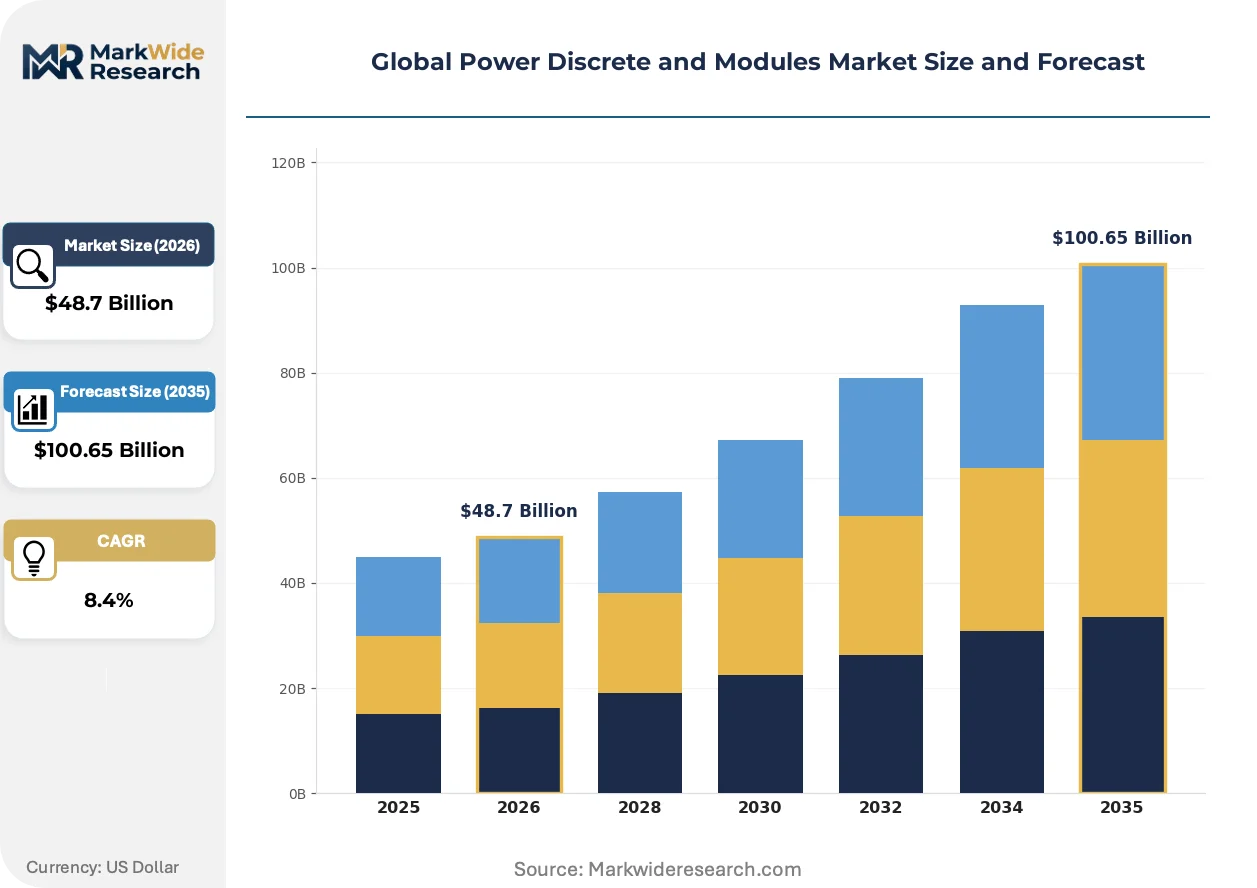
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transistors, Diodes, Thyristors, Modules Technology: Silicon, Silicon Carbide, Gallium Nitride, Others End User: Consumer Electronics, Automotive, Industrial, Renewable Energy Application: Power Supply, Inverter, Motor Drives, LED Lighting |
| Companies Covered | Infineon Technologies AG, STMicroelectronics, onsemi, Mitsubishi Electric Corporation, Toshiba Corporation, ROHM Semiconductor, NXP Semiconductors, Texas Instruments, Fuji Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Power Discrete and Modules Market Strategic Shifts
Power semiconductor technology is bifurcating across voltage tiers, with material innovations and regulatory efficiency mandates compressing traditional silicon device lifecycles.
Silicon carbide MOSFET technology is fragmenting the high-voltage power device landscape by enabling 800-volt traction inverters with reduced cooling requirements. Automotive OEMs in Germany and China are adopting SiC modules for premium electric vehicle platforms at accelerating procurement volumes. This material transition is compressing IGBT market share in automotive applications while expanding addressable thermal budgets for compact inverter designs.
The EU Green Deal's embedded carbon requirements are altering foundry location decisions for European-bound power modules. REACH substance restrictions on lead-based solders and halogenated flame retardants are forcing packaging material substitutions across industrial and automotive segments. Module suppliers are responding by qualifying copper wire bonding and sintered die-attach processes for automotive qualification tiers.
Buyer consolidation among tier-1 automotive inverter suppliers is compressing supplier negotiation leverage and lengthening contract durations. Direct sourcing agreements are displacing traditional distribution channels for silicon carbide modules in high-volume electric vehicle programs. This channel shift is most visible in Japan's automotive semiconductor supply chain, where captive foundry relationships anchor strategic procurement decisions.
Global Power Discrete and Modules Market Segmentation
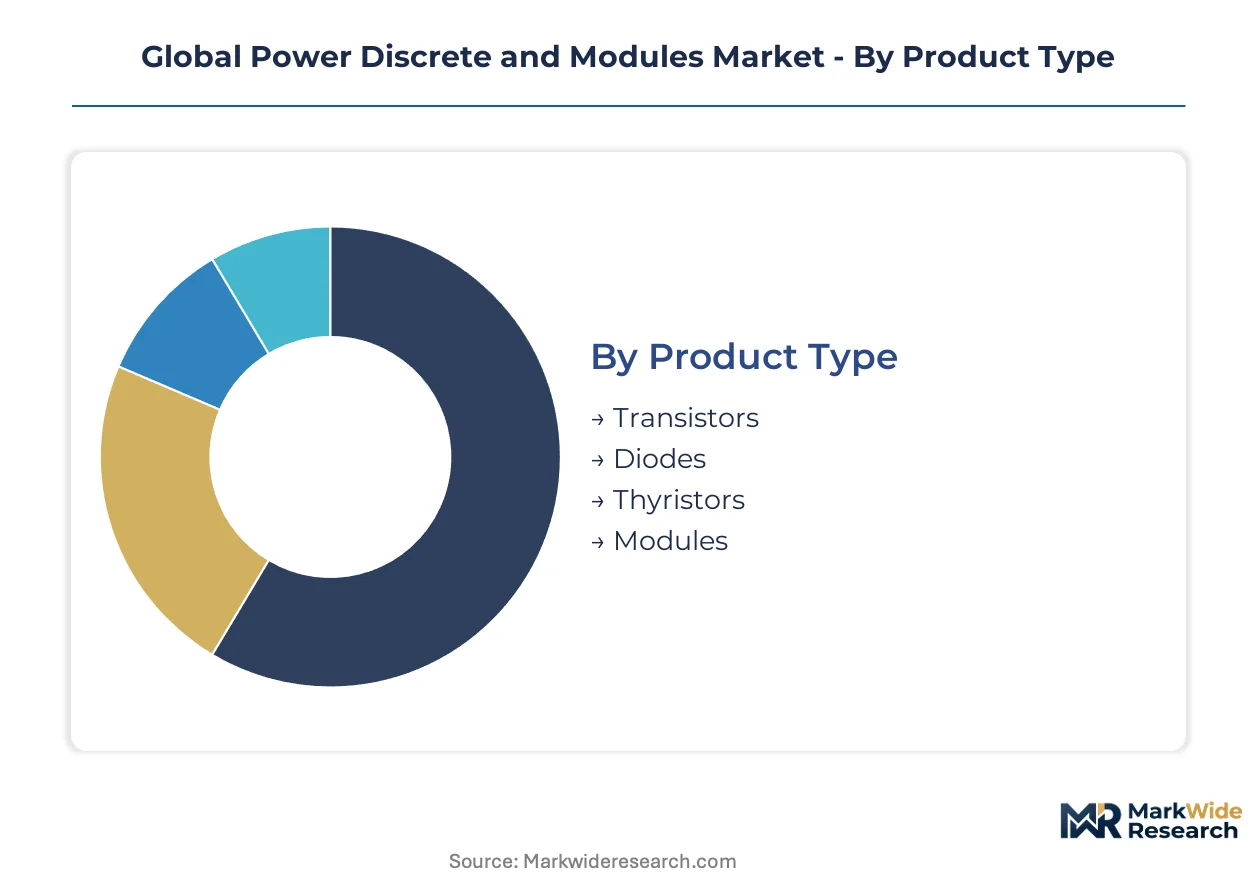
Power semiconductor segmentation reveals how material transitions and voltage requirements are fragmenting procurement patterns across automotive and industrial supply chains. Discrete devices and module assemblies now compete as substitutable solutions depending on thermal budgets and switching frequency demands.
Product Type:
Substitution pressure intensifies as integrated modules displace discrete component assemblies in high-power applications requiring reduced parasitic inductance.
- Transistors:Individual switching devices including MOSFETs and IGBTs fabricated through trench etch processes achieve on-resistance below 10 milliohms for low-voltage motor control. Silicon carbide MOSFET transistors for 800-volt traction inverters concentrate procurement among German and Chinese automotive OEMs accelerating electrification roadmaps.
- Modules:Multi-die assemblies with integrated thermal management and electrical isolation enable kiloampere current handling in compact footprints. Demand clusters in Japan's automotive semiconductor supply chain where tier-1 inverter suppliers secure allocated capacity through direct sourcing agreements.
- Diodes:Rectification devices spanning Schottky, fast-recovery, and Zener configurations serve freewheeling and protection functions across power conversion stages.
- Thyristors:Phase-controlled switches retain dominance in high-voltage DC transmission and industrial soft-start applications where silicon IGBTs remain cost-prohibitive.
Modules retain volume leadership; transistors hold the steepest expansion curve as discrete SiC devices penetrate onboard charger and DC-DC converter sockets.
Technology:
Cost tier stratification separates premium wide-bandgap materials from commodity silicon across voltage and frequency application boundaries.
- Silicon Carbide:Wide-bandgap substrates enable 1,200-volt operation with switching losses below 20% of equivalent silicon IGBTs. Tesla and BYD procurement volumes for traction inverters are compressing module cost premiums as captive crystal growth capacity expands.
- Silicon:Mature epitaxial processes deliver cost-optimized MOSFETs and IGBTs for industrial motor drives below 600 volts. STMicroelectronics and Infineon sustain broad portfolios dominating variable frequency drive sockets in Germany's industrial automation corridor.
- Gallium Nitride:HEMT structures achieve megahertz switching in sub-650-volt applications enabling compact magnetics for consumer power adapters.
- Others:Emerging materials including gallium oxide and diamond substrates address specialized ultra-high-voltage and thermal management requirements.
Silicon dominates unit shipments; silicon carbide climbs the fastest as 800-volt platforms proliferate.
End User:
Application maturity varies sharply across customer segments, with automotive electrification forcing the most rapid technology transitions.
- Automotive:Traction inverters, onboard chargers, and DC-DC converters demand AEC-Q101 qualified devices with junction temperatures exceeding 175°C. EU Ecodesign Directive efficiency mandates and China's MIIT dual carbon enforcement are redirecting capacity toward EV powertrain electrification.
- Industrial:Variable frequency drives and uninterruptible power supplies sustain silicon IGBT and MOSFET procurement at scale. Replacement cycles in European automation corridors are accelerating as efficiency regulations tighten converter loss budgets.
- Renewable Energy:Solar inverters and wind turbine converters require high-reliability modules with 25-year operational lifespans.
- Consumer Electronics:Smartphone and laptop adapters drive GaN transistor adoption for compact, high-frequency power supplies.
Industrial applications retain volume leadership; automotive holds the steepest expansion trajectory as electrification penetrates mass-market vehicle platforms.
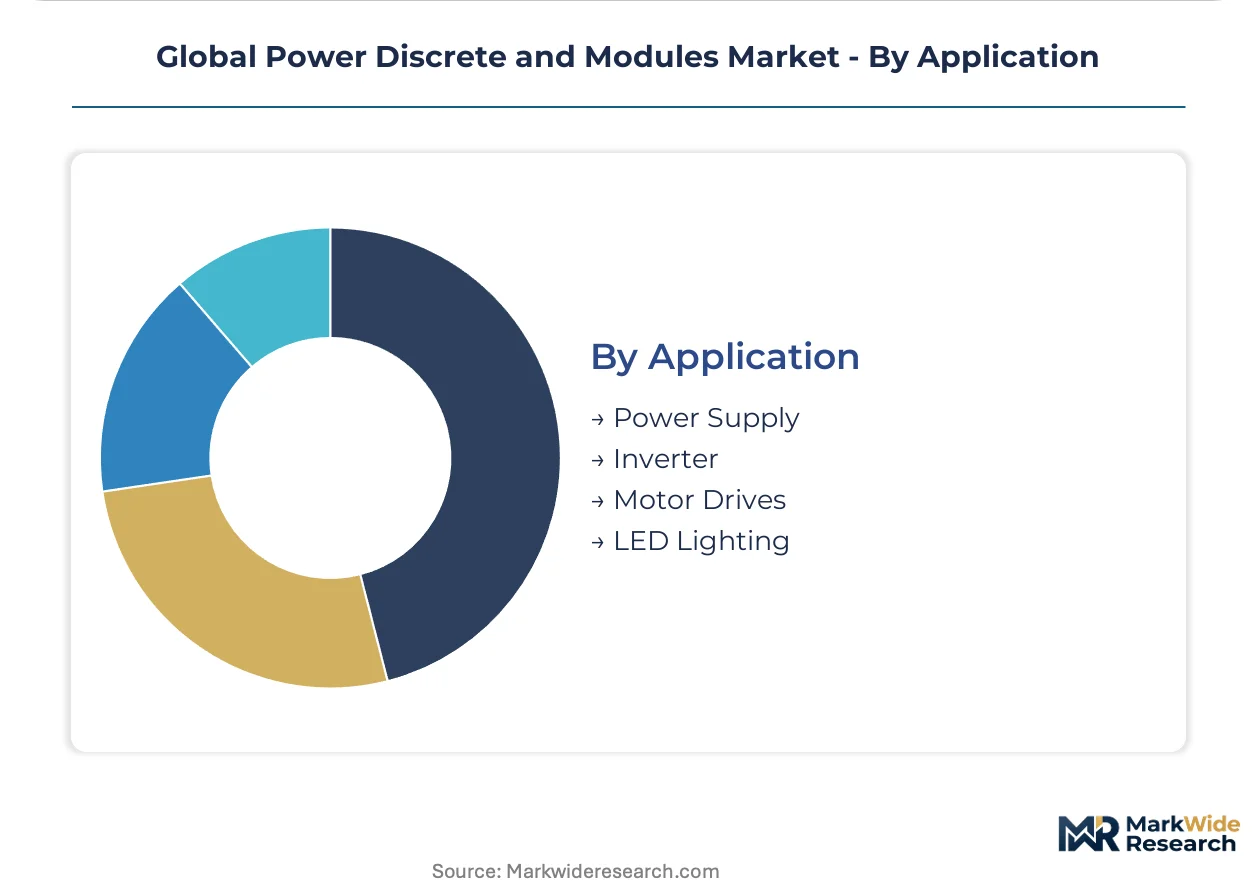
Application:
Customer type differentiation separates OEM-direct procurement from distribution-channel purchasing across voltage and reliability tiers.
- Inverter:DC-AC conversion stages for solar, motor drive, and traction applications demand highest-efficiency switching to minimize thermal management overhead. 800-volt automotive platforms are compressing silicon IGBT dominance while expanding SiC module procurement.
- Power Supply:AC-DC and DC-DC conversion spans adapter, server, and telecom rectifier applications with varying isolation and holdup requirements. Gallium nitride transistors carve distinct share in sub-10-kW segments where megahertz switching enables compact magnetics.
- Motor Drives:Variable frequency control for industrial automation and appliance motors sustains silicon MOSFET and IGBT procurement at highest unit volumes.
- LED Lighting:Solid-state driver circuits require cost-optimized discrete components for residential and commercial luminaire applications.
Motor drives retain volume leadership; inverters gain share fastest as renewable energy and electrification expand addressable demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government electrification mandates and industrial efficiency programs are redrawing procurement geography across power semiconductor supply chains. Subsidy regimes in automotive manufacturing hubs and renewable energy deployment zones concentrate module demand in specific national markets.
China
MIIT dual carbon enforcement redirects domestic foundry capacity toward EV charging infrastructure and traction inverter production. GB standard updates for high-voltage charging protocols accelerate silicon carbide module qualification timelines. BYD and CATL procurement clusters in Shenzhen and Ningbo compress supplier delivery schedules for 800-volt platform components.
Germany
The EU Ecodesign Directive tightens converter loss budgets across industrial motor drive replacement cycles. KBA vehicle-type approval requirements for electrified powertrains expand SiC module sourcing from domestic tier-1 inverter suppliers. Stuttgart and Munich automotive corridors anchor captive foundry relationships for premium EV platform supply.
United States
NHTSA electrification mandates and EPA efficiency standards tighten automotive converter specifications while IRA production credits attract module packaging investments. FDA device regulations indirectly shape medical power supply discrete procurement. Texas and Arizona fabrication clusters expand epitaxial wafer capacity for wide-bandgap device production.
Japan
METI energy efficiency targets for industrial equipment accelerate silicon MOSFET replacement with advanced IGBT and SiC alternatives. JIS standards for automotive power devices enforce reliability testing protocols that extend supplier qualification periods. Nagoya and Kyoto semiconductor corridors concentrate substrate specialist capacity for epitaxial wafer supply.
India
The PLI scheme for semiconductors attracts power module packaging investments targeting appliance and automotive export markets. CEA grid modernization directives expand procurement for renewable energy inverters and EV charging infrastructure. Gujarat and Tamil Nadu electronics manufacturing clusters host assembly operations for industrial motor drive modules.
Global Power Discrete and Modules Market Competitive Environment
Player mix skews toward vertically integrated European and Japanese conglomerates with captive substrate capacity, alongside fabless specialists sourcing epitaxial wafers from concentrated Japanese and US suppliers. Tier-1 automotive inverter suppliers bypass distribution channels through multi-year direct contracts, compressing negotiation leverage for mid-tier module vendors. Strategic archetypes include substrate-integrated module houses, silicon-dominant portfolio diversifiers, and intelligent power module specialists. Competitive moves center on backward integration into SiC crystal growth and geographic expansion into Indian packaging corridors.
Among European-integrated suppliers, Infineon Technologies AG anchors the premium module tier through in-house SiC substrate production. STMicroelectronics occupies a position exemplifying broad silicon MOSFET portfolio diversification across industrial sockets. onsemi represents the intelligent power module specialization vector with integrated gate driver and protection circuitry offerings.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| STMicroelectronics |
| onsemi |
| Mitsubishi Electric Corporation |
| Toshiba Corporation |
| ROHM Semiconductor |
| NXP Semiconductors |
| Texas Instruments |
| Fuji Electric |
| Others |
Value Chain & Pricing Dynamics
Captive silicon carbide crystal growth capacity at Infineon and STMicroelectronics anchors price floors for automotive-grade modules while compressing margins for fabless competitors sourcing substrates from Japanese specialists. Scale economies in 200mm SiC wafer production concentrate pricing power among vertically integrated European suppliers serving Germany's automotive OEM direct procurement channels.
Pricing Analysis
Certification level creates the primary spread between AEC-Q101 qualified automotive modules and industrial-grade alternatives. Pricing stratifies across premium, standard, and economy tiers based on junction temperature ratings and substrate quality grades. Cost compression in silicon MOSFET segments intensifies as Chinese suppliers expand 600-volt industrial device capacity. Tier-1 automotive inverter suppliers exhibit lowest price sensitivity due to multi-year allocation contracts, while appliance OEMs drive hardest bargain on intelligent power modules.
Supply Chain Analysis
Inventory cycles for SiC epitaxial wafers extend 26-32 weeks during demand surges, constraining module output at packaging houses in Malaysia and the Philippines. Supply concentrates in Japan for substrate crystal growth, Germany for automotive module assembly, and China for industrial discrete packaging. Raw material dependencies encompass high-purity silicon carbide powder, copper lead frames, and silver sinter pastes. Single-source vulnerability in 150mm SiC substrate supply from Japanese specialists threatens allocation stability. Distribution runs through direct OEM contracts for automotive tiers and authorized distributors for industrial sockets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power discrete and modules markets sit in early-cycle expansion as 800-volt EV platform penetration accelerates silicon carbide substitution beyond premium vehicle segments into mass-market architectures.
For Market Incumbents: Fortify captive substrate positions through backward integration into SiC crystal growth or long-term wafer supply agreements with Japanese specialists. Defend module share by accelerating AEC-Q101 qualification timelines ahead of mid-tier competitors. Prioritize direct contracting with German and Chinese automotive OEMs to lock allocation through 2030 platform cycles. For New Entrants and Emerging Players: Lead with GaN transistor specialization in sub-10-kW onboard charger sockets where megahertz switching enables compact magnetics differentiation. Target India's PLI scheme incentives for power module packaging investments serving appliance export markets. Pursue fabless model sourcing epitaxial wafers from US substrate specialists to avoid Japanese supply queue. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among intelligent power module suppliers with integrated gate driver software and multi-year appliance platform contracts. Five-to-ten year viability favors substrate-integrated module houses over pure-play silicon portfolio holders facing technical ceiling pressures. Watch SiC module pricing convergence with silicon IGBT benchmarks as the inflection signal for mass-market EV adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Production | Captive crystal growth capacity secures allocation priority with Tesla and BYD procurement teams. |
| AEC-Q101 Certification Acceleration | Automotive qualification compresses supplier tiers into qualified and non-qualified segments. |
| Direct OEM Contracting Expansion | Multi-year supply agreements with tier-1 inverter suppliers displace traditional distribution channels. |
| GaN-SiC Hybrid Module Development | Combining high-frequency and high-voltage tolerance enables next-generation onboard charger platforms. |
| India PLI Packaging Investment | Domestic assembly incentives attract module operations targeting appliance and automotive exports. |
Study Parameters
Operator-level perspectives from tier-1 automotive inverter procurement managers, industrial motor drive OEMs, power module packaging engineers, and SiC substrate specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, MIIT capacity utilization disclosures, and EU Ecodesign Directive implementation tracking. Bottom-up unit demand modeling triangulated against top-down semiconductor revenue aggregates.
Sensitivity analysis tested forecast outputs against variable EV platform penetration rates and SiC substrate capacity expansion scenarios. Segmentation dimensions modeled encompass product type, material technology, voltage rating tier, end-user industry, and regional production cluster. CAGRs derived from slope-interpolation across annual demand build-ups incorporating vehicle electrification roadmaps and industrial efficiency replacement cycles. Specific inputs included OEM platform content-per-vehicle assumptions and foundry utilization rates at major substrate suppliers.
Forecasts assume regulatory continuity in EU Ecodesign enforcement, China's MIIT dual carbon targets, and US NHTSA electrification mandates; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Battery Cyclers Market
Power Systems
Piezoelectric Energy Harvesting System Market
Power Systems
Asia-Pacific DC Distribution Networks Market
Power Systems
Voltage Regulators Market
Power Systems
Grid Tie Inverter Market
Power Systems
USB Power Adapters Market
Power Systems
Asia-Pacific Shunt Reactors Market
Power Systems
Thyristor Market
Power Systems
North America Telecom Power Systems Market
Power Systems
Grid Forming Inverters Market
Power Systems
Modular Uninterrupted Power Supplies (UPS) Market
Power Systems
Three-Phase String Inverter Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Power Electronics Equipment Cooling System Market
Power Systems
Battery Pack High-Voltage Wiring System Components Market
Power Systems
Superconducting Magnet Systems Market