
 Asia-Pacific Shunt Reactors Market | 2026-2036
Asia-Pacific Shunt Reactors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Shunt Reactors Market Outlook
Utility procurement channels across Southeast Asia and South Asia are reshaping vendor relationships as state-owned grid operators consolidate supplier panels. Siemens AG leverages its localized manufacturing footprint to sustain long-term service contracts with Indian transmission utilities. CG Power and Industrial Solutions Limited anchors its position through domestic transformer and reactor production capabilities. Mitsubishi Electric Corporation differentiates through advanced insulation systems designed for tropical humidity conditions.
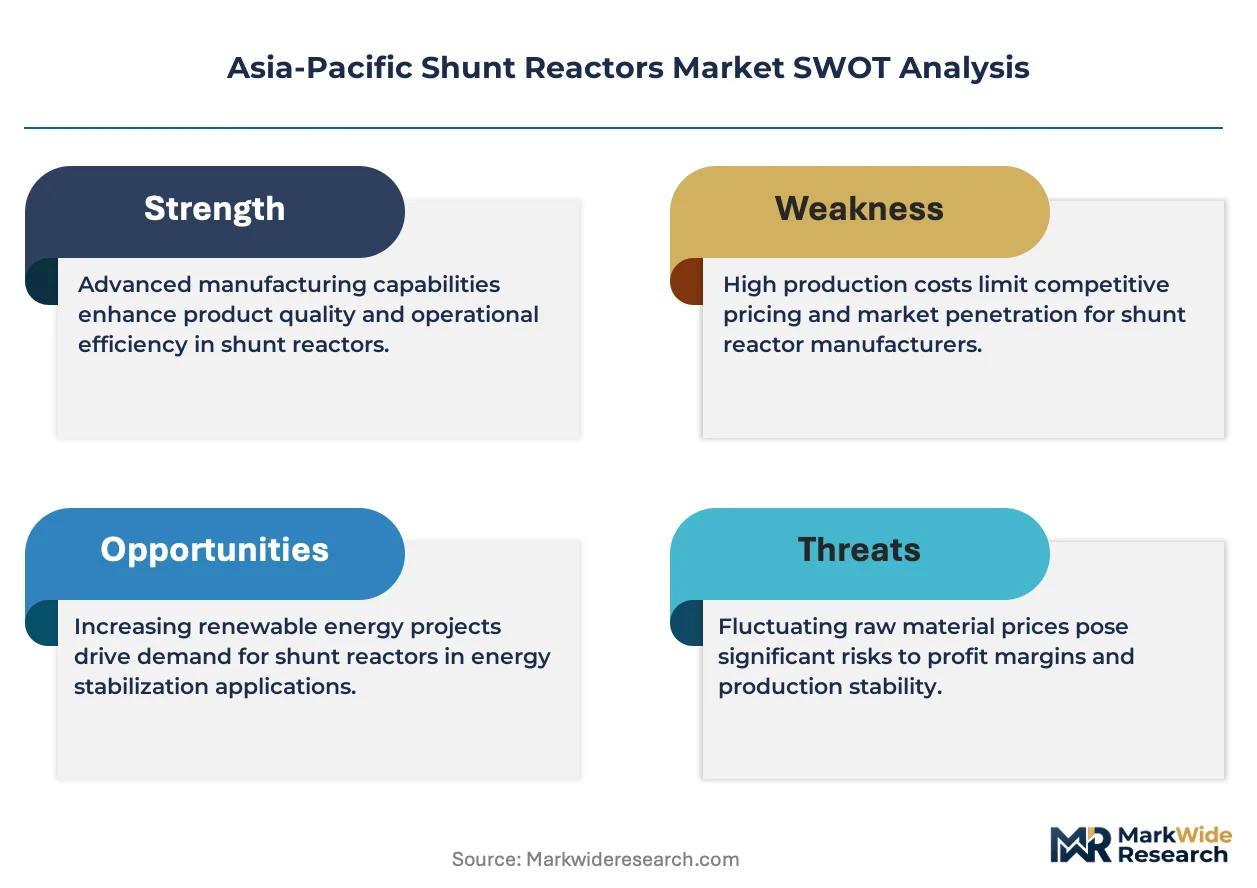
Asia-Pacific shunt reactors are inductive devices installed in parallel with transmission lines to absorb excess reactive power and maintain voltage stability within ±5% of nominal levels. Oil-cooled designs dominate existing installed bases due to proven thermal management in high-load corridors, while air-core units are gaining share in coastal substations where fire safety and environmental containment requirements have tightened. Among end users, renewable energy developers represent the fastest-expanding customer category as wind and solar farms require dynamic VAR support to meet grid code compliance. Control systems technology commands premium positioning because digital monitoring interfaces reduce outage response times and enable predictive maintenance protocols.
India's Central Electricity Authority mandates shunt reactor deployment on 400 kV and above lines to limit Ferranti rise, while China's GB standards and MEE environmental directives enforce noise and thermal emission thresholds for substation equipment. Japan's METI grid modernization framework incentivizes replacement of aged oil-cooled units with hybrid designs. Stakeholders must weigh localization requirements against technology transfer costs as procurement rules tighten across the region's major markets.
Market Dynamics
State-owned transmission utilities across Asia-Pacific are consolidating supplier panels and mandating stricter localization thresholds, forcing equipment vendors to reconfigure manufacturing footprints and service architectures around national procurement rules rather than regional economies of scale.
Growth Catalysts
- China's dual carbon goals:Beijing's 2030 carbon peak and 2060 neutrality targets compel grid operators to install reactive power compensation equipment that stabilizes voltage swings from intermittent renewable injections.
- 400 kV and above line mandates:India's Central Electricity Authority requires shunt reactor deployment on extra-high-voltage corridors to suppress Ferranti rise, creating automatic demand pull as transmission networks expand.
- Hybrid reactor designs:Advanced insulation systems combining oil-cooled thermal management with air-core fire safety characteristics are capturing retrofit contracts in Japan's coastal substations.
Market Restraints
- Grain-oriented electrical steel concentration:Supply of high-permeability core laminates concentrates among Japanese and South Korean metallurgical suppliers, exposing reactor manufacturers to input cost volatility and allocation risk.
- Extended type-testing protocols:China's GB standards and India's BIS certification require multi-month thermal and seismic validation cycles that delay project commissioning and compress vendor cash conversion.
- Air-core substitution in greenfield coastal sites:Fire-safety-conscious developers in Southeast Asian offshore wind zones are specifying magnetically shielded air-core reactors that bypass traditional oil-cooled equipment categories entirely.
Strategic Opportunities
- Vietnam's 500 kV backbone expansion:State utility EVN is tendering reactive power equipment for north-south transmission corridors where renewable generation clusters in the central highlands create voltage stability gaps.
- Digital twin integration:Convergence of finite-element thermal modeling with real-time dissolved gas analysis enables predictive maintenance contracts that extend equipment lifecycle revenue beyond initial sale.
- India's PLI scheme for power infrastructure:Production-linked incentives for domestic manufacturing of high-voltage equipment reduce landed cost disadvantages for local reactor assembly operations.
Industry Challenges
- High-voltage insulation engineering talent scarcity:Specialized expertise in epoxy-impregnated winding design and partial discharge testing concentrates among aging technical workforces in Japan and Germany, constraining knowledge transfer to emerging manufacturing hubs.
- Legacy SCADA integration complexity:New digital monitoring interfaces must communicate with decades-old substation automation protocols deployed across China's provincial grids, extending commissioning timelines and requiring custom protocol gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Shunt Reactors Market |
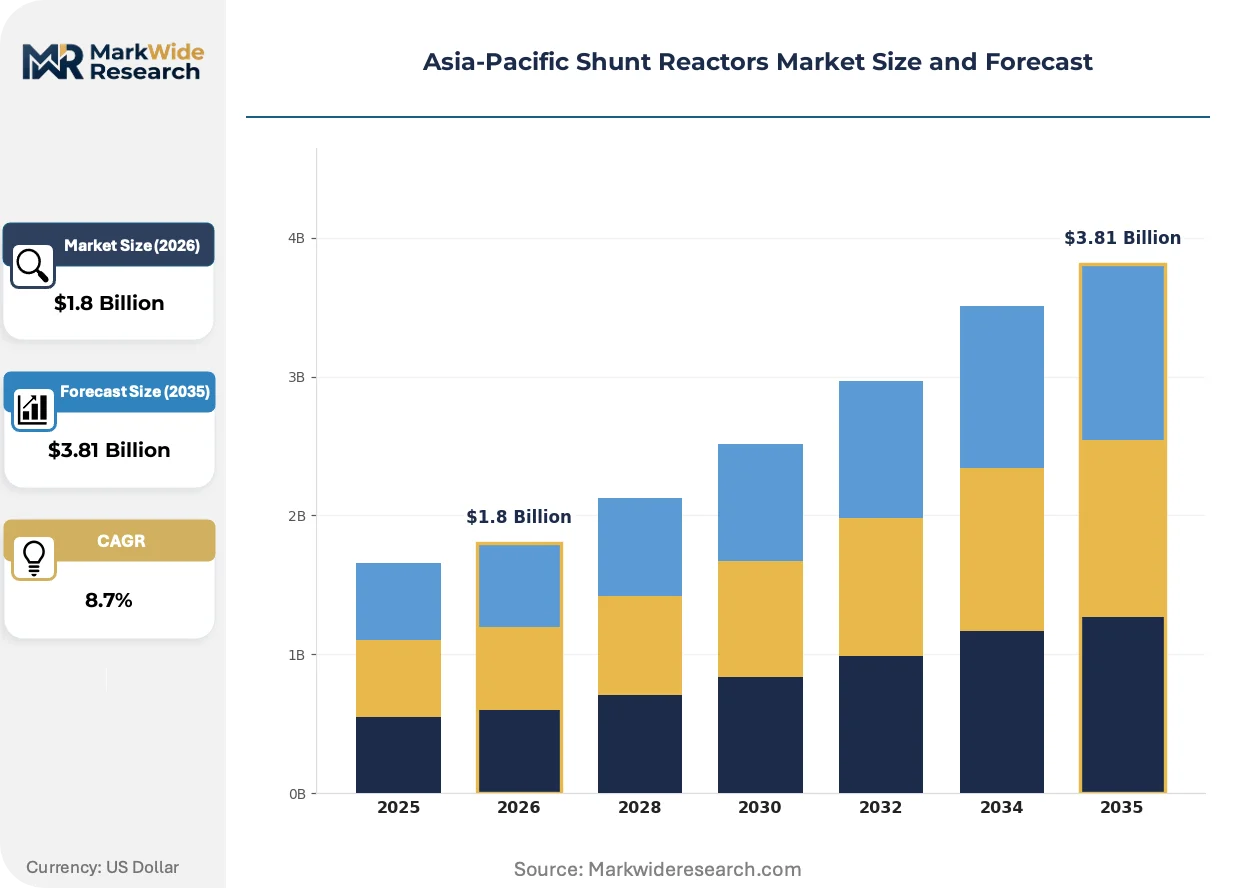
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Core, Oil-Cooled, Resin-Bonded, Hybrid Technology: Voltage Source, Current Source, Reactive Power Compensation, Control Systems End User: Utilities, Industrial Plants, Renewable Energy, Commercial Buildings Installation: Indoor, Outdoor, Substation, Mobile |
| Companies Covered | Siemens AG, CG Power and Industrial Solutions Limited, Mitsubishi Electric Corporation, Fuji Electric Co., TBEA Co. Ltd, General Electric, Toshiba Corporation, Hitachi Energy Ltd., Hyosung Heavy Industries Corp., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Shunt Reactors Market Strategic Shifts
Reactive power equipment is transitioning from passive grid components to intelligent nodes capable of dynamic VAR modulation, with control system architecture becoming the primary axis of vendor differentiation and procurement evaluation.
Integrated power-electronic controllers with embedded fiber-optic sensing is digitizing shunt reactor operations by enabling millisecond-scale reactive power adjustment. Wind farm developers in India's Rajasthan and Gujarat corridors are specifying these units to meet grid code ride-through requirements. The technology is compressing traditional electromechanical switchgear replacement cycles by embedding switching intelligence directly within reactor control enclosures.
China's MEE environmental directives now enforce noise emission thresholds below 65 dB at substation perimeter fences, compelling redesign of magnetic core joint geometries and tank vibration damping systems. Reactor manufacturers are responding with computational acoustic modeling that optimizes core stacking patterns before physical prototyping. Japanese utilities facing similar METI guidelines are importing these simulation methodologies for aged equipment replacement programs.
Long-term service contracts unbundled from initial equipment supply are displacing transactional procurement models among Southeast Asian state grids. Thai and Indonesian transmission operators now separate reactor purchase from decade-long maintenance and spare parts agreements, allowing specialized service firms to compete independently of manufacturing parent companies. This restructuring is most visible in procurement panels where Indian and Chinese vendors without local service infrastructure lose eligibility despite competitive equipment pricing.
Asia-Pacific Shunt Reactors Market Segmentation
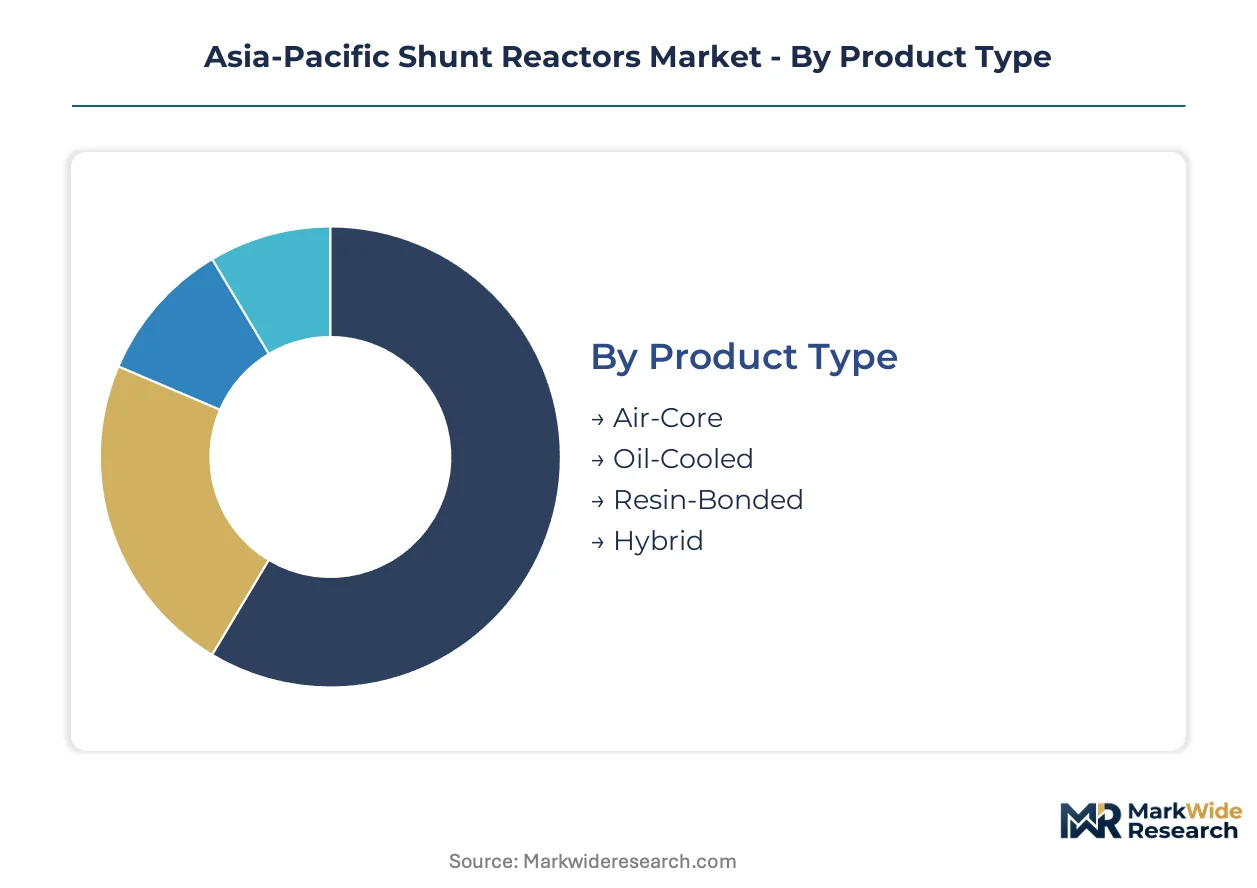
Segmentation in the Asia-Pacific shunt reactors market reveals how voltage stability requirements diverge across grid architectures, coastal versus inland substations, and renewable integration intensity. Procurement patterns vary sharply between state transmission utilities seeking bulk reactive power absorption and wind farm developers requiring dynamic VAR modulation.
Product Type:
Cooling architecture and fire safety specifications split demand across coastal substations, urban corridors, and high-load transmission corridors where thermal management priorities differ.
- Air-Core:Magnetically shielded designs eliminate oil containment risks in Southeast Asian offshore wind zones and coastal substations where fire safety regulations have tightened. EVN's 500 kV Vietnam backbone tenders specify these units for central highland renewable clusters.
- Oil-Cooled:Proven thermal management in high-load corridors dominates existing installed bases across China and India's 400 kV networks, though Japan's METI framework now incentivizes replacement with hybrid alternatives.
- Resin-Bonded:Epoxy-impregnated winding systems serve compact urban substations where space constraints and leak prevention outweigh thermal efficiency priorities.
- Hybrid:Advanced insulation combining oil-cooled thermal capacity with air-core safety characteristics captures retrofit contracts in Japan's coastal facilities and greenfield sites facing dual performance mandates.
The dominant share belongs to Oil-Cooled, while Hybrid is closing the gap fastest as coastal fire-safety mandates proliferate.
Technology:
Control sophistication determines procurement premiums, with digital interfaces commanding price multiples over passive electromechanical alternatives.
- Control Systems:Embedded fiber-optic sensing and millisecond-scale VAR adjustment enable grid code compliance for Rajasthan and Gujarat wind developers. Digital monitoring interfaces reduce outage response times and unlock predictive maintenance revenue streams.
- Reactive Power Compensation:Core inductive functionality absorbs excess reactive power on long transmission lines, with China's dual carbon goals accelerating deployment to stabilize voltage swings from intermittent renewable injections.
- Voltage Source:Converter-based architectures integrate with power-electronic switchgear for dynamic voltage support in weak grid zones.
- Current Source:Thyristor-controlled designs serve legacy substation automation protocols across China's provincial grids where SCADA integration complexity extends commissioning timelines.
Control Systems captures the steepest expansion trajectory, while Reactive Power Compensation maintains volume leadership through transmission utility mandates.
End User:
Customer type dictates specification priorities, from bulk procurement standardization among state grids to customized dynamic response for renewable developers.
- Utilities:State-owned transmission operators across China, India, and Southeast Asia consolidate supplier panels and mandate localization thresholds, creating automatic demand pull through 400 kV and above line deployment rules.
- Renewable Energy:Wind and solar farm developers represent the fastest-expanding customer category, requiring VAR support to meet ride-through requirements as generation clusters concentrate in India's western corridors and Vietnam's central highlands.
- Industrial Plants:Steel and cement facilities install shunt reactors for power factor correction and voltage flicker mitigation on captive high-voltage connections.
- Commercial Buildings:Large-scale data centers and metro infrastructure deploy compact units for harmonic filtering and voltage regulation on medium-voltage distribution networks.
Utilities retain the largest procurement volumes, though Renewable Energy is gaining share fastest as capacity addition targets escalate across the region.
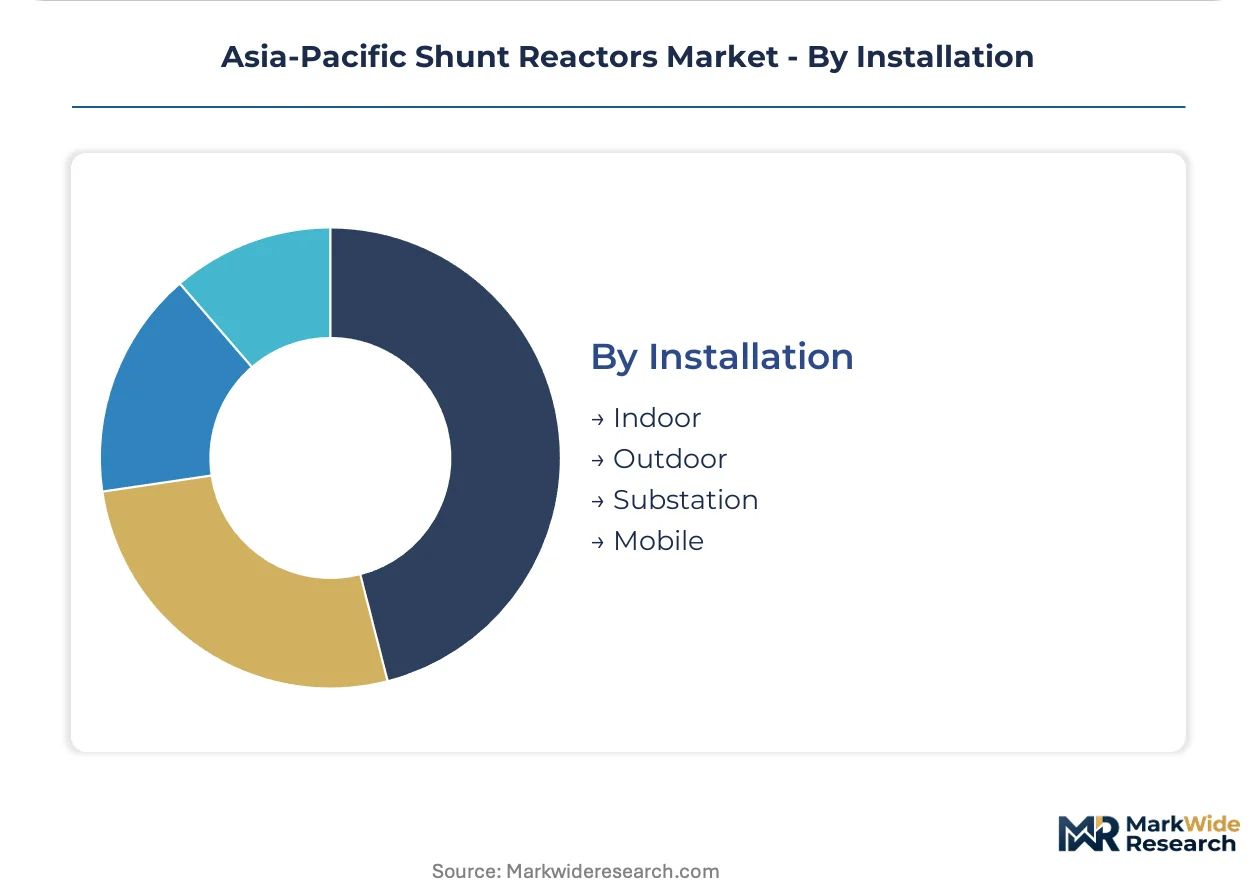
Installation:
Physical deployment mode reflects land availability, climate exposure, and operational mobility requirements across diverse grid topographies.
- Substation:Fixed installations dominate high-voltage transmission corridors where permanent reactive power absorption addresses Ferranti rise on 400 kV and above lines per India's CEA mandates.
- Outdoor:Open-air configurations prevail across tropical climates, with noise emission thresholds below 65 dB now enforced by China's MEE directives compelling acoustic redesign of tank and core geometries.
- Indoor:Climate-controlled housings protect sensitive insulation systems in coastal humidity zones and urban substations where space constraints favor compact resin-bonded designs.
- Mobile:Trailer-mounted units serve emergency grid restoration and temporary renewable interconnection projects requiring rapid deployment without permanent civil works.
Substation installations command the dominant position, while Mobile units are expanding most quickly for contingency and interim grid reinforcement applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ultra-high-voltage backbone spanning China's western renewable bases to eastern load centers underwrites the region's centrality to shunt reactor deployment. This 800 kV and above corridor network absorbs voltage swings from intermittent generation while creating procurement scale unmatched elsewhere in Asia-Pacific.
China
State Grid Corporation's 800 kV UHVDC lines from Gansu and Qinghai wind-solar clusters to coastal demand centers mandate reactive power compensation at every converter station. MEE environmental directives enforce noise thresholds below 65 dB at substation perimeters, compelling core geometry redesigns. Manufacturing concentration in Xi'an and Shenyang supplies domestic demand while exporting to Belt and Road grid projects.
India
Power Grid Corporation's 765 kV and 400 kV greenfield corridors through Rajasthan and Gujarat renewable zones create automatic reactor demand under CEA mandates. The PLI scheme for power infrastructure reduces landed cost disadvantages for domestic assembly operations. Manufacturing clusters in Vadodara and Bhopal anchor transformer and reactor production for western transmission expansion.
Japan
Tokyo Electric Power's grid modernization program targets replacement of 1970s-era oil-cooled units with hybrid designs at coastal substations. METI incentives for equipment renewal compress replacement cycles in the Kanto and Kansai load centers. Yokohama-based engineering consultancies specialize in seismic qualification protocols that extend to regional export markets.
Vietnam
EVN's 500 kV north-south backbone expansion through the central highlands requires reactive power equipment where renewable generation clusters create voltage stability gaps. National power development plans prioritize grid reinforcement over generation capacity. Da Nang and Ho Chi Minh City serve as procurement coordination hubs for transmission infrastructure tenders.
South Korea
KEPCO's Jeju Island HVDC interconnection and mainland renewable integration drive demand for dynamic VAR support equipment. Domestic suppliers leverage grain-oriented electrical steel production from Pohang metallurgical complexes to secure input material access. Busan-Ulsan industrial corridor hosts high-voltage equipment testing facilities serving regional export markets.
Asia-Pacific Shunt Reactors Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on materials and insulation engineering. The Asia-Pacific shunt reactor market structures around three distinct competitive tiers: global electrical equipment conglomerates with localized manufacturing footprints, domestic champions anchored in national procurement rules, and specialized reactor engineering houses with proprietary insulation system IP. Consolidation pressure intensifies as state utilities consolidate supplier panels and mandate localization thresholds. Dominant competitive moves include backward integration into core laminate supply and long-term service contract unbundling from initial equipment sales.
Among diversified industrial conglomerates, Siemens AG and Mitsubishi Electric Corporation exemplify platform-tier positioning through integrated power system offerings. CG Power and Industrial Solutions Limited occupies a specialist-tier position within India's domestic procurement ecosystem. These three anchors illustrate how vendor strategies diverge between global scale economies and national compliance architectures.
| Leading Market Players |
|---|
| Siemens AG |
| CG Power and Industrial Solutions Limited |
| Mitsubishi Electric Corporation |
| Fuji Electric Co. |
| TBEA Co. Ltd |
| General Electric |
| Toshiba Corporation |
| Hitachi Energy Ltd. |
| Hyosung Heavy Industries Corp. |
| Others |
Value Chain & Pricing Dynamics
Japanese and South Korean metallurgical suppliers dominate grain-oriented electrical steel output, concentrating margin capture upstream while reactor manufacturers face input cost volatility and allocation risk downstream.
Pricing Analysis
Volume-discount tiering structures separate premium-tier hybrid designs with embedded fiber-optic sensing from standard oil-cooled units and economy-grade air-core alternatives. Price differentiation hinges on certification grade for seismic qualification and after-sales service bundling. Cost compression in the standard tier is intensifying because state utilities consolidate supplier panels and mandate localization thresholds. Renewable energy developers exhibit highest price sensitivity due to project finance constraints, while Japanese utilities show lowest sensitivity given METI equipment renewal incentives.
Supply Chain Analysis
Contract manufacturing concentrates among transformer and reactor specialists in Xi'an, Shenyang, Vadodara, and Bhopal with captive winding and core assembly capacity. Raw material dependencies center on grain-oriented electrical steel laminates, epoxy resin systems for insulation, and copper winding conductors. Single-source vulnerability in high-permeability core steel from Pohang and Japanese metallurgical complexes exposes manufacturers to allocation risk. Distribution runs through state-owned transmission utility procurement panels with long-term service contracts unbundled from initial equipment supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in epoxy-impregnated winding design and partial discharge testing concentrates among aging technical workforces, constraining knowledge transfer to emerging manufacturing hubs and creating durable capability gaps for late entrants.
For Market Incumbents: Build switching-cost moats through digital twin integration that embeds predictive maintenance contracts and extends lifecycle revenue beyond initial sale. Deepen backward integration into grain-oriented electrical steel supply through offtake agreements with Pohang metallurgical complexes to secure input material access against allocation risk. Capture retrofit contracts in Japan's coastal substations by accelerating hybrid design certification under METI guidelines before replacement cycles peak. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's 500 kV backbone expansion where EVN tenders reactive power equipment for central highland renewable clusters with less consolidated supplier panels than China or India. Target mobile reactor units for emergency grid restoration and temporary renewable interconnection projects requiring rapid deployment without permanent civil works. Lead with localized service infrastructure in Thailand and Indonesia where procurement rules now separate equipment purchase from decade-long maintenance agreements. For Investors and Strategic Acquirers: Capital is best deployed toward reactor engineering houses with proprietary insulation system IP and established seismic qualification protocols that can extend to regional export markets. Long-term viability favors specialists with demonstrated GB standards and BIS certification track records as procurement rules tighten across Asia-Pacific. Watch for inflection in EVN tender awards for central highland transmission corridors as signal of Vietnam demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Steel Supply | Secures grain-oriented electrical steel access against Japanese and South Korean supplier allocation risk. |
| Hybrid Design Certification Investment | Captures METI-incentivized replacement cycles in Japan's coastal substations before competitors. |
| Digital Twin Platform Development | Enables predictive maintenance contracts that extend revenue lifecycle beyond initial equipment sale. |
| Localized Service Infrastructure Buildout | Qualifies for Thai and Indonesian procurement panels separating equipment from maintenance agreements. |
| Seismic Qualification Protocol Export | Leverages Yokohama-based engineering expertise for regional retrofit and greenfield project eligibility. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and equipment procurement databases. Utility planning officers, IPP project developers, EPC contractors, and grid operators provided demand-side perspectives on reactive power equipment specifications and procurement timelines. Secondary validation drew from Central Electricity Authority mandates, GB standards documentation, METI grid modernization frameworks, and MEE environmental directives. Bottom-up unit deployment estimates triangulate against top-down transmission network expansion forecasts.
Forecast inputs span reactor cooling architecture adoption curves, renewable integration intensity by grid zone, and localization threshold evolution across national procurement rules. Segmentation dimensions modeled include product type, control technology sophistication, end-user category, and installation mode across the projection horizon. CAGRs derive from fitted growth curves anchored to announced transmission corridor investments and equipment replacement cycles. Industry-specific inputs incorporate 400 kV and above line mandates and dual carbon goal implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in capital cost of renewable projects or transmission utility budget allocations would shift the trajectory. Forecasts reflect assumptions on regulatory enforcement consistency for noise and thermal emission thresholds. Quarterly review of EVN tender announcements, Power Grid Corporation capital expenditure disclosures, and State Grid UHVDC commissioning schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Europe Variable Frequency Drive Market
Power Systems
Battery Cyclers Market
Power Systems
North America Micro Inverter Market
Power Systems
Charge Pumps Market
Power Systems
PV Inverter Market
Power Systems
Battery Equalizer Market
Power Systems
Battery Racks Market
Power Systems
Smart Power Strips Market
Power Systems
Medium Voltage Drives Market
Power Systems
Asia Pacific Transformer Monitoring System Market
Power Systems
Asia-Pacific DC Distribution Networks Market
Power Systems
Global Battery Thermal Management System Market
Power Systems
Thermoelectric Assemblies Market
Power Systems
Three Phase Micro Inverters Market
Power Systems
Battery Balancer Market
Power Systems
Low Voltage Drives Market