
 Acetylated Distarch Adipate Market | 2026-2036
Acetylated Distarch Adipate Market Size, Share, and Industry Trends Forecast 2026-2036
Acetylated Distarch Adipate Market Analysis
Modular ingredient bundling is recalibrating how food manufacturers procure modified starches. Ingredion Incorporated leverages its integrated formulation labs to anchor North American supply relationships. Tate & Lyle PLC differentiates through specialty texturant portfolios that extend beyond commodity starches. Roquette Frères S.A dominates European pea and potato starch upstream streams, sustaining backward integration into modified derivatives.
Acetylated distarch adipate is a cross-linked and esterified starch derivative produced by treating native starch with adipic anhydride and acetic anhydride, yielding improved freeze-thaw stability, acid resistance, and viscosity retention under shear. It serves primarily as a texture-modifying additive in processed foods, personal care emulsions, and pharmaceutical binders where thermal and pH stability prove critical. The thickening agents category leads volume offtake as sauce and soup manufacturers prioritize process tolerance over cost minimization. Stabilizers represent the fastest-expanding functional class, driven by clean-label dairy alternatives requiring extended shelf stability without gelatin. Food manufacturers occupy the deepest margin pools among end users, while cosmetic companies and pharmaceutical firms concentrate procurement on pharmacopeia-compliant and halal-certified grades.
FDA food additive regulations under 21 CFR 172.892 govern acetylated distarch adipate purity and usage limits in the United States, while EFSA and REACH in Europe impose migration thresholds and chemical registration burdens that filter smaller suppliers from commercial participation. The EU Green Deal and F-Gas Regulation indirectly shape demand by pressuring manufacturers to lower processing temperatures and solvent use during starch modification. Stakeholders must monitor evolving EFSA re-evaluations of modified starch acceptable daily intakes and calibrate formulation pipelines accordingly.
Market Dynamics
Clean-label reformulation mandates from EFSA and the EU Green Deal are compressing acceptable additive portfolios, forcing dairy and frozen dessert manufacturers to validate modified starches through stricter purity benchmarks and carbon footprint audits.
Growth Catalysts
- EFSA Re-evaluation Protocols:Tightening acceptable daily intake reviews for modified starches are filtering out non-compliant suppliers, concentrating procurement among certified manufacturers in Germany and France.
- Industrial Bakery Expansion:Automated bread and pastry production lines in Northern Europe require starches with freeze-thaw stability and shear resistance, pulling acetylated distarch adipate into high-volume dough conditioning applications.
- Pea Starch Feedstock Diversification:Roquette Frères S.A's backward integration into European pea protein streams is securing non-GMO, allergen-free raw material bases for modified starch derivatives.
Market Restraints
- Adipic Anhydride Price Volatility:Petrochemical feedstock fluctuations for cross-linking agents compress margins for mid-tier starch modifiers lacking long-term supply contracts.
- REACH Registration Burdens:ECHA chemical substance dossier requirements and toxicity testing protocols impose six-figure compliance costs that exclude smaller European compounders from food-grade participation.
- Native Starch Substitution:Unmodified tapioca and rice starches with simpler processing profiles threaten commodity applications where process tolerance requirements are relaxed.
Strategic Opportunities
- Plant-Based Dairy Alternatives:Oat and almond milk manufacturers in the Netherlands and Denmark require halal-certified stabilizers with extended shelf stability, opening formulation partnerships beyond traditional gelatin replacement.
- Pharmaceutical Binder Grades:USP-NF and EP pharmacopeia compliance for tablet disintegration and binding properties creates premium pricing tiers for GMP-certified production facilities.
- Low-Temperature Modification:EU F-Gas Regulation pressure to reduce solvent use and thermal processing energy is accelerating enzymatic and physical modification methods that lower carbon intensity scores.
Industry Challenges
- Food-Pharma Cross-Training Gaps:Formulation chemists with dual competency in food-grade texture engineering and pharmaceutical excipient validation command salary premiums that strain mid-cap R&D budgets.
- Halal Certification Timelines:Multi-audit cycles through Islamic Food and Nutrition Council of America or Halal Control EU extend product launch schedules by eight to fourteen months for cosmetic and pharmaceutical grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetylated Distarch Adipate Market |
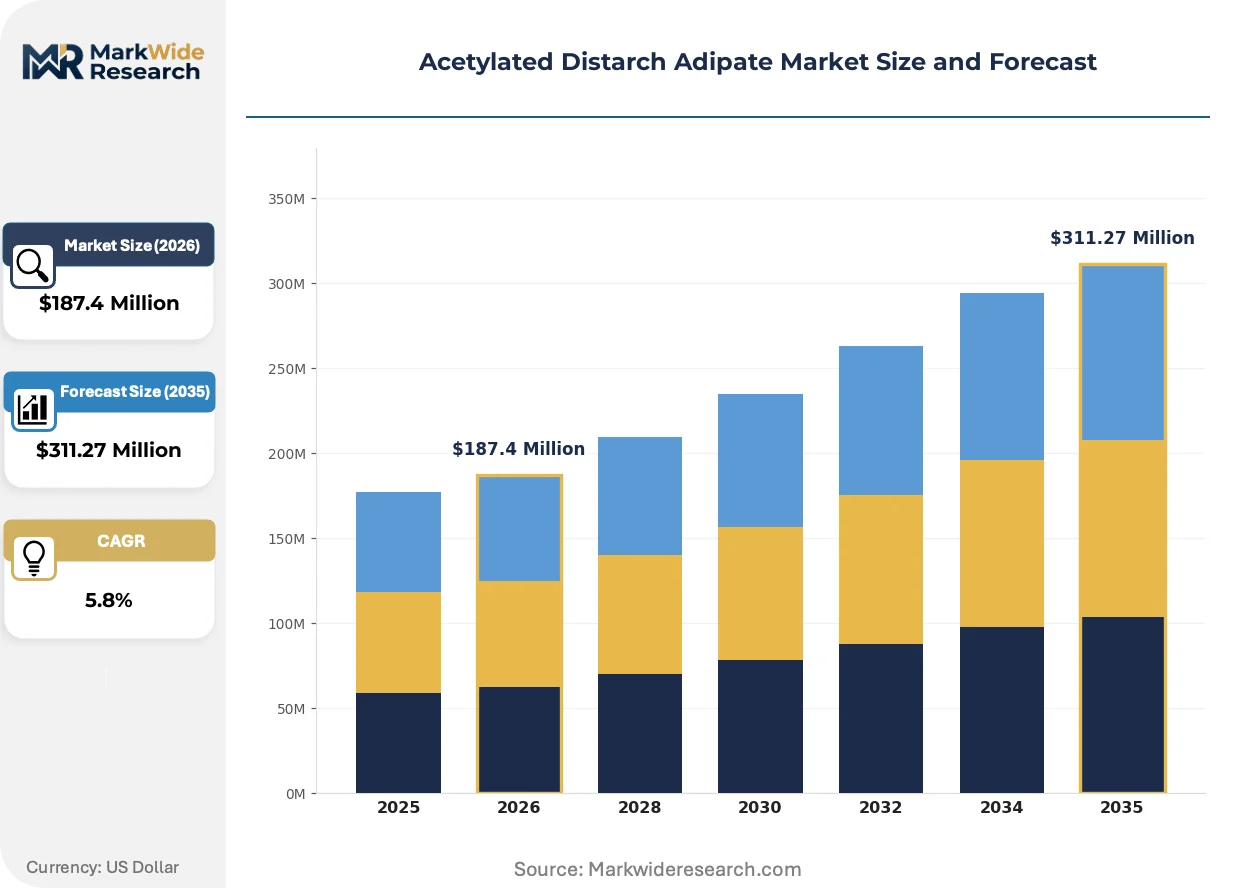
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thickening Agents, Stabilizers, Emulsifiers, Binders Application: Food & Beverage, Personal Care, Pharmaceuticals, Coatings End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Paint Producers Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | AGRANA Beteiligungs-AG, SÜDSTÄRKE GMBH, Ingredion Incorporated, N. B. ENTERPRISE, Venus Starch Suppliers, Tate & Lyle PLC, Roquette Frères S.A, Hasal Tarim Urunleri Sanayi Ve Ticaret Limited Sirketi, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetylated Distarch Adipate Market Emerging Trajectories
Physical modification technologies and enzymatic cross-linking methods are displacing conventional chemical esterification, driven by carbon accounting pressures and clean-label positioning requirements across European processed food channels.
Enzymatic phosphorylation and transglutaminase cross-linking is consolidating as the preferred low-temperature modification pathway for freeze-thaw stable starches. Dairy alternative manufacturers in Denmark and Sweden are adopting these methods at pilot scale. The technology is consolidating supplier bases around biotech-enabled compounders with in-house enzyme production.
EU Green Deal carbon border adjustment mechanisms and REACH SVHC candidate list expansions are forcing starch modifiers to document full supply chain chemical footprints. Industrial bakeries in Germany now require Scope 3 emissions declarations from additive suppliers. The policy pressure is concentrating procurement on vertically integrated manufacturers with captive agriculture partnerships.
Direct supplier-manufacturer formulation partnerships are replacing distributor-mediated starch procurement. Sauce and soup compounders in France and Belgium are embedding technical service agreements into multi-year supply contracts. The behavioral shift is most visible in private-label frozen dessert manufacturing, where co-development clauses lock in exclusive modified starch grades.
Acetylated Distarch Adipate Market Segmentation
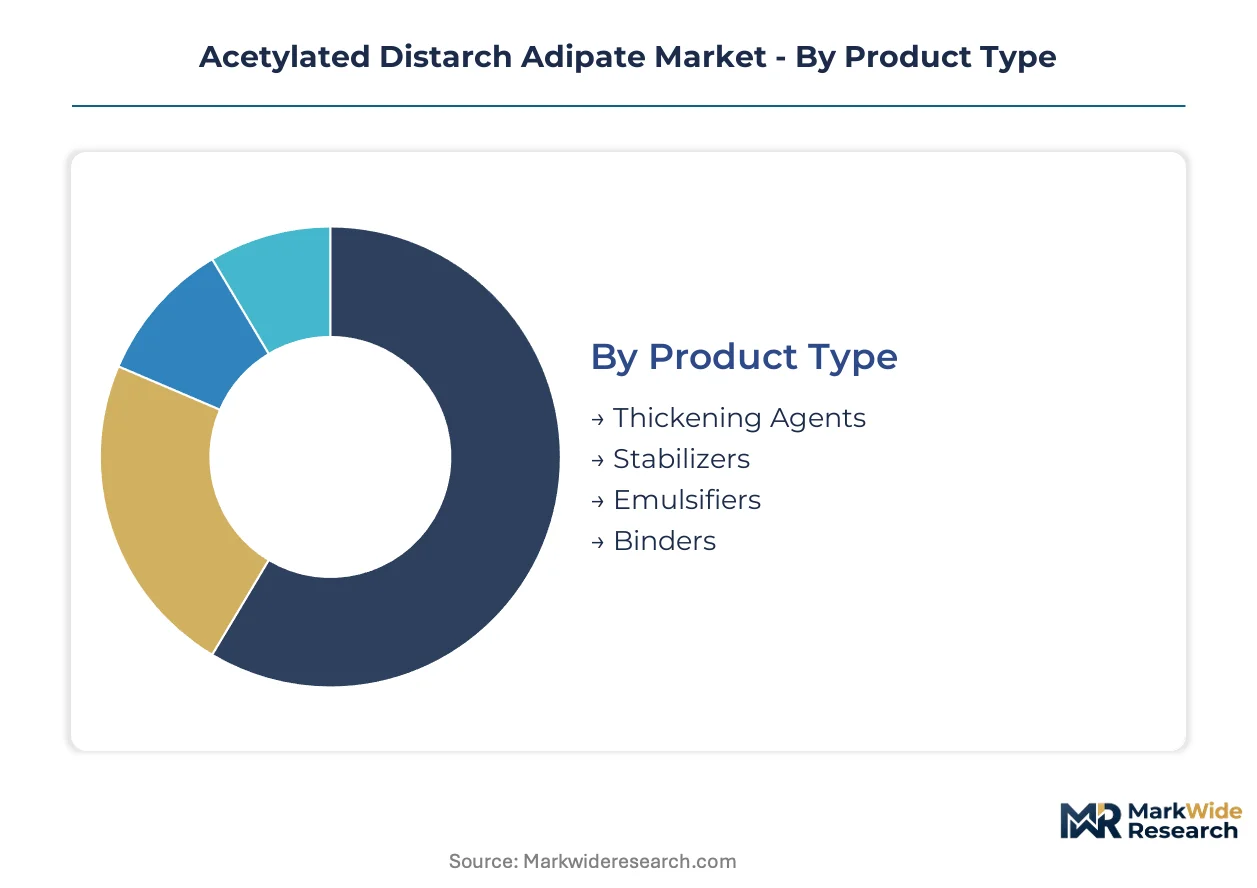
Acetylated distarch adipate procurement splits sharply between high-volume commodity grades and premium-certified variants. Food manufacturers drive baseline demand through thickening applications, while pharmaceutical and clean-label dairy segments extract premium pricing through pharmacopeia and halal certifications.
Product Type:
Volume concentration clusters in commodity texturants, while premium pricing accrues to functional additives with regulatory certifications.
- Thickening Agents:These derivatives deliver viscosity retention under thermal and shear stress through cross-linked amylopectin networks. Sauce and soup manufacturers in Germany and France anchor European offtake, prioritizing process tolerance over cost minimization in automated production environments.
- Stabilizers:Freeze-thaw stability and extended shelf-life performance define this segment's technical specification. Plant-based dairy alternatives in Denmark and the Netherlands are pulling demand upward as gelatin replacement accelerates in clean-label oat and almond milk formulations.
- Emulsifiers:Surface-active modified starches stabilize oil-water interfaces in personal care emulsions.
- Binders:Tablet disintegration and granulation properties serve pharmaceutical compounding requirements.
Mature deployment sits with Thickening Agents. Newer deployment is concentrated in Stabilizers.
Application:
End-use diversification reflects divergent purity benchmarks across regulated industries.
- Food & Beverage:Processed food applications dominate tonnage, spanning sauces, soups, frozen desserts, and bakery conditioning. Industrial bakeries in Northern Europe require freeze-thaw stable grades for automated dough production lines.
- Pharmaceuticals:USP-NF and EP pharmacopeia compliance creates premium pricing tiers for GMP-certified manufacturing facilities with validated excipient production.
- Personal Care:Emulsion stability in creams and lotions drives cosmetic-grade demand.
- Coatings:Film-forming properties serve paint and paper surface treatment applications.
Established demand centers on Food & Beverage. Steepest expansion trajectory belongs to Pharmaceuticals.
End User:
Procurement sophistication varies sharply between price-sensitive commodity buyers and specification-driven premium purchasers.
- Food Manufacturers:Deep margin pools and high-volume contracts characterize this segment. Sauce compounders in Belgium and frozen dessert producers in France are embedding technical service agreements into multi-year supply relationships.
- Pharmaceutical Firms:Pharmacopeia compliance, GMP certification, and halal validation create entry barriers that filter non-specialized suppliers from participation.
- Cosmetic Companies:Halal-certified and dermatologically tested grades command formulation partnerships.
- Paint Producers:Cost-driven procurement for industrial coating applications.
Volume leadership rests with Food Manufacturers. Premium pricing concentrates with Pharmaceutical Firms.
Distribution Channel:
Channel selection tracks customer scale and technical service requirements.
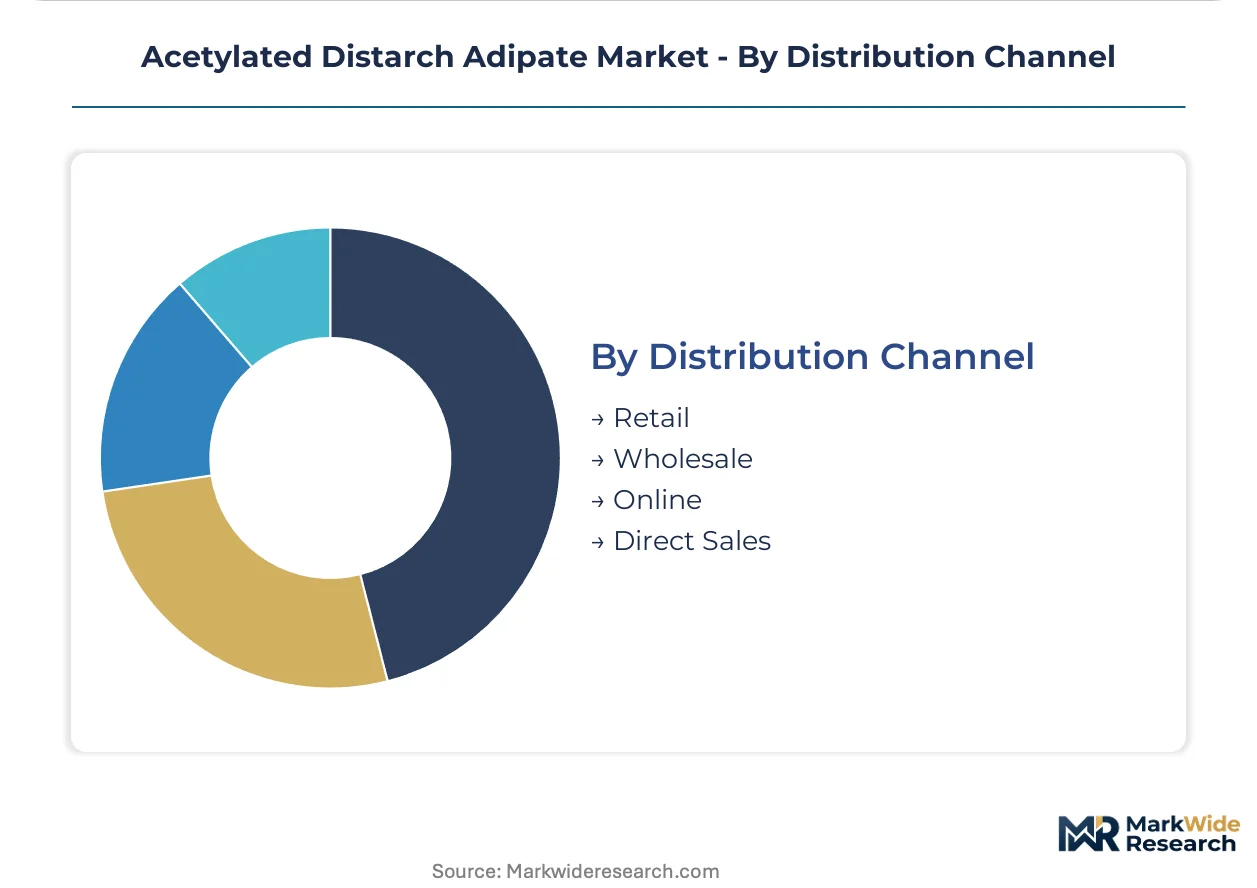
- Direct Sales:Large-scale food and pharmaceutical manufacturers negotiate exclusive supply agreements with integrated technical support. Direct supplier-manufacturer formulation partnerships are displacing distributor-mediated procurement in French and Belgian sauce compounding.
- Wholesale:Regional distributors serve mid-tier processors with standardized grade portfolios.
- Online:E-procurement platforms facilitate spot purchasing for small-batch and specialty grades.
- Retail:Limited to pilot-scale and research-grade quantities.
Contracted volume flows through Direct Sales. Emerging channel development centers on Online platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in the Netherlands and industrial clusters across Northern Europe concentrate modified starch production capacity through targeted tax incentives and REACH compliance infrastructure.
Germany
Industrial bakeries in North Rhine-Westphalia drive thickening agent demand for automated dough production lines. EFSA purity benchmarks and EU Green Deal carbon audits filter supplier participation. Cologne and Düsseldorf anchor formulation partnerships between starch modifiers and sauce compounders.
France
Frozen dessert manufacturers in Île-de-France prioritize stabilizers with extended freeze-thaw stability for clean-label reformulation. REACH registration requirements impose six-figure compliance costs on smaller compounders. Lyon and Paris host technical service agreements embedding modified starch specifications into multi-year supply contracts.
Netherlands
Plant-based dairy alternatives in Randstad require halal-certified stabilizers for oat and almond milk formulations. F-Gas Regulation pressure accelerates low-temperature enzymatic modification methods. Rotterdam and Amsterdam concentrate pilot-scale adoption of carbon-accounted starch derivatives.
Denmark
Dairy alternative manufacturers in Copenhagen prioritize gelatin replacement through modified starch stabilizers. EU Green Deal Scope 3 emissions declarations now condition supplier qualification. The Øresund region anchors Nordic clean-label formulation partnerships.
United States
Pharmaceutical binder demand concentrates in New Jersey and Massachusetts around USP-NF compliance requirements. FDA 21 CFR 172.892 governs food-grade purity specifications. Chicago and Minneapolis host integrated formulation labs serving North American processed food manufacturers.
Acetylated Distarch Adipate Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply relationships. Market structure concentrates procurement among vertically integrated manufacturers with captive agriculture partnerships and GMP-certified pharmaceutical facilities. Three archetypes dominate: multinational ingredient platforms with integrated formulation labs, regional starch processors with backward integration into pea and potato feedstocks, and specialty compounders serving pharmacopeia-compliant grades. Competitive moves center on direct supplier-manufacturer technical partnerships and enzymatic modification technology licensing.
Among European integrated processors, AGRANA Beteiligungs-AG and SÜDSTÄRKE GMBH exemplify the regional specialist archetype with upstream control over Central European starch streams. Ingredion Incorporated occupies a position representing North American multinational scale with formulation laboratory infrastructure. Tate & Lyle PLC and Roquette Frères S.A sit within the specialty texturant tier, with the latter anchoring non-GMO pea starch backward integration. These named entities represent competitive positioning patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| AGRANA Beteiligungs-AG |
| SÜDSTÄRKE GMBH |
| Ingredion Incorporated |
| N. B. ENTERPRISE |
| Venus Starch Suppliers |
| Tate & Lyle PLC |
| Roquette Frères S.A |
| Hasal Tarim Urunleri Sanayi Ve Ticaret Limited Sirketi |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
Formulation chemists with dual food-pharma competency in Germany and France command salary premiums that compress mid-tier R&D budgets, widening spreads between premium-certified grades and commodity texturants as labor-cost differentials filter through to customer-facing price tiers.
Pricing Analysis
Short lead-time premiums for halal-certified pharmaceutical grades command significant markups over spot-market commodity texturants with standard certification timelines. Three-tier pricing structure across premium pharmacopeia-compliant, standard food-grade, and economy industrial-coating levels separates contract-based long-term offtake from transactional spot purchasing. Price differentiation hinges on GMP certification status and REACH registration completeness. Cost compression in mid-tier food-grade segments is intensifying because adipic anhydride feedstock volatility passes through to compounders lacking captive petrochemical supply.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Antwerp anchor hub-and-spoke patterns serving industrial bakeries and sauce compounders across Northern Europe. Manufacturing concentrates in Germany, France, and the Netherlands where REACH compliance infrastructure and EFSA-aligned testing facilities cluster. Raw material flows draw from European pea and potato starch streams, adipic anhydride petrochemical feedstocks, and acetic anhydride acetylation agents. Single-source vulnerability around enzymatic modification technology providers creates concentration risk as enzymatic cross-linking displaces conventional chemical esterification. Distribution runs through direct technical partnerships for large-scale food and pharmaceutical manufacturers, with wholesale channels serving regional mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acetylated distarch adipate supply is constrained by REACH registration bottlenecks that filter smaller compounders from food-grade participation, propping pricing power among certified manufacturers with completed ECHA dossiers.
For Market Incumbents: Cement formulation partnerships with plant-based dairy manufacturers in Denmark and the Netherlands through embedded technical service agreements. Deepen backward integration into pea starch feedstocks to secure non-GMO, allergen-free raw material bases against Roquette Frères S.A's upstream control. Lock in multi-year supply contracts with industrial bakeries in Germany before enzymatic modification technology licensing reshapes competitive positioning. For New Entrants and Emerging Players: E-procurement platforms for specialty halal-certified pharmaceutical grades offer the most penetrable entry vector. Target USP-NF and EP pharmacopeia-compliant binder segments where GMP certification barriers filter commodity producers. Pursue co-development clauses with private-label frozen dessert manufacturers in France seeking exclusive modified starch specifications. For Investors and Strategic Acquirers: Re-rating potential sits with biotech-enabled compounders with in-house enzyme production given EU F-Gas Regulation acceleration of low-temperature modification methods. Long-term viability favors facilities with dual food-pharma competency and validated excipient production capabilities. Watch EFSA re-evaluation timelines for modified starch acceptable daily intakes as the inflection indicator for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Starch Feedstocks | Roquette Frères S.A's upstream control secures non-GMO, allergen-free raw material bases for European compounders. |
| Enzymatic Modification Technology Licensing | EU F-Gas Regulation pressure accelerates low-temperature processing methods that lower carbon intensity scores. |
| Halal Certification Investment | Islamic Food and Nutrition Council of America multi-audit cycles extend launch schedules but unlock premium pharmaceutical pricing tiers. |
| Direct Technical Partnership Expansion | French and Belgian sauce compounders embed co-development clauses into multi-year supply contracts. |
| Pharmacopeia Compliance Capacity Buildout | USP-NF and EP validation creates entry barriers that filter non-specialized suppliers from premium binder segments. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with plant managers at starch modification facilities, procurement leads at industrial bakeries and sauce manufacturers, technical R&D directors at ingredient compounders, and distribution channel partners serving Northern European markets. EFSA re-evaluation documents, ECHA REACH registration databases, FDA 21 CFR 172.892 specifications, and EU Green Deal implementation guidelines provided regulatory boundary conditions. Bottom-up volume estimates from end-use consumption patterns triangulated against top-down production capacity assessments across identified manufacturing clusters.
Data-stream reconciliation across supply-side capacity, demand-side offtake, and trade-flow validation informed the analytical framework. Segmentation dimensions modeled include functional grade tier, end-use industry application, certification status, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized growth trajectories. Industry-specific forecast inputs incorporated EFSA purity benchmark evolution, enzymatic modification technology adoption curves, and plant-based dairy alternative formulation partnership velocity.
The model holds under stable REACH registration timelines and sustained EU Green Deal carbon accounting pressure; deviation in EFSA acceptable daily intake re-evaluations or adipic anhydride feedstock disruption would shift volume and value trajectories. Forecasts reflect documented assumptions regarding certification timeline stickiness and enzymatic technology scale-up rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Integrated Food Ingredient Market
Food Additives and Ingredients
Emulsifiers Market
Food Additives and Ingredients
Nutraceutical Excipients Market
Food Additives and Ingredients
Sri Lanka Starch and Starch Derivative Market
Food Additives and Ingredients
Neohesperidine DC Market
Food Additives and Ingredients
South America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Beta Agonist Feed Additive Market
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
Beverage Stabilizer Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
Food Antimicrobial Additives Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Anti-Caking Market
Food Additives and Ingredients
Acetylated Distarch Phosphate Market
Food Additives and Ingredients
DATEM Replacement Market