
 United Kingdom Food Preservatives Market | 2026-2036
United Kingdom Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Food Preservatives Market Analytics
Clean-label specification tiers is collapsing the traditional synthetic preservative hierarchy as British consumers reject E-number additives. Corbion N.V. leverages its fermentation-derived portfolio to occupy the natural acidulants segment. Tate & Lyle PLC sustains its position through deep reformulation partnerships with UK bakery chains. Kerry Group plc differentiates via integrated taste-preservation systems that reduce sodium while extending shelf life.
Food preservatives encompass chemical substances added to food matrices to inhibit microbial spoilage, enzymatic browning, and oxidative rancidity, typically functioning through pH reduction, membrane disruption, or free-radical scavenging at concentrations between 0.01% and 0.3% by weight. Their primary commercial purpose centers on enabling extended distribution cycles for packaged goods while maintaining organoleptic safety thresholds. Sorbates dominates the synthetic product type category due to its broad pH efficacy and established cost position in beverage applications. Natural formulation types represent the fastest-expanding margin pool as FSA labeling scrutiny and retailer clean-list requirements intensify. Benzoates faces structural pressure in carbonated drinks as potassium sorbate displaces legacy systems.
The Food Standards Agency enforces maximum permitted levels for nitrites and benzoates through retained EU regulation 1333/2008, directly constraining formulation flexibility and accelerating clean-label R&D expenditure. EFSA scientific opinions on additive safety trigger downward revisions in acceptable daily intake values, forcing manufacturers to preemptively reformulate ahead of regulatory ratification. Stakeholders must monitor emerging FSA consultations on novel preservation technologies including bacteriocins and high-pressure processing to anticipate compliance pathways and capital allocation priorities.
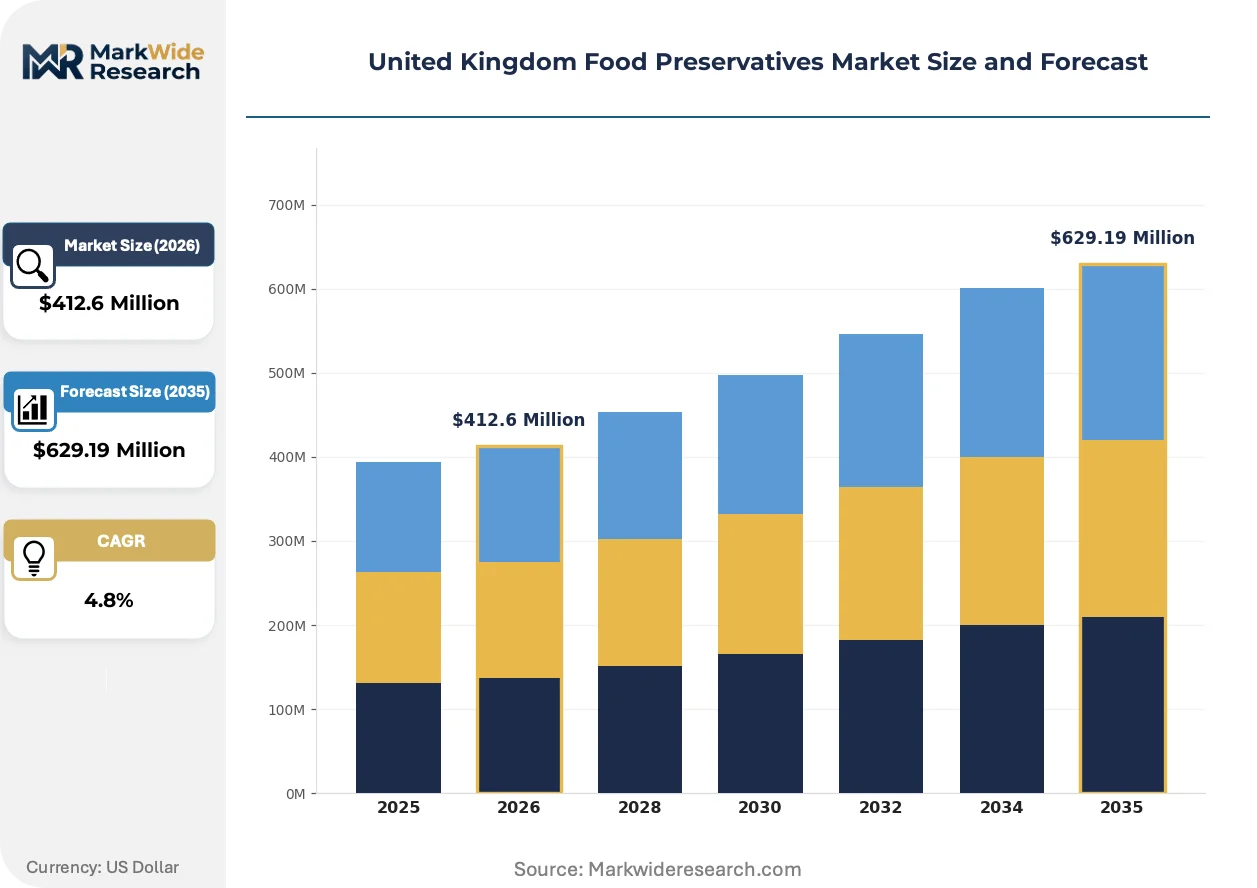
Market Dynamics
Clean-label reformulation mandates from the Food Standards Agency are compressing synthetic preservative demand while fermentation-derived alternatives capture margin pools across British bakery and meat processing corridors.
Growth Catalysts
- FSA Sodium Nitrite Threshold Reductions:Processed meat manufacturers are accelerating plant-derived alternative adoption as the regulator enforces stricter maximum permitted levels under retained EU regulation 1333/2008.
- Ready-to-Eat Meal Manufacturing:Greater London's food manufacturing corridor is driving concentrated demand for natural preservation systems as clean-label specifications tighten across premium convenience food operations.
- Fermentation-Derived Acidulants:Advances in bioprocess engineering are expanding production capacity for natural pH-modifying agents that match synthetic efficacy in beverage applications.
Market Restraints
- Natural Extract Input Volatility:Rosemary and green tea extract supply chains face agricultural yield fluctuations that compress formulator margins and constrain batch-to-batch consistency.
- Technical Efficacy Gaps:Plant-derived antimicrobials demonstrate narrower pH efficacy windows than sorbates, forcing complex multi-hurdle systems that increase R&D cycle duration.
- Clean-Label Cost Premium:Natural preservation systems command 40-60% higher unit costs than synthetic equivalents, limiting penetration in private-label and economy-tier product lines.
Strategic Opportunities
- Bacteriocin Commercialization Pathways:Emerging FSA consultations on novel preservation technologies are creating regulatory headroom for antimicrobial peptide applications in chilled dairy.
- High-Pressure Processing Integration:Non-thermal pasteurization technology convergence with minimal preservative formulations is opening clean-label shelf-life extension in premium ready meals.
- Scotland's Specialty Dairy Corridor:Underpenetrated artisan cheese and cultured product manufacturers present white space for tailored bioprotective cultures that deliver both fermentation and preservation functions.
Industry Challenges
- Reformulation Timeline Compression:EFSA scientific opinion cycles are accelerating acceptable daily intake revisions, forcing manufacturers to complete multi-year reformulation projects within 18-month retailer compliance windows.
- Clean-Label Certification Complexity:Divergent retailer clean-list specifications across Tesco, Sainsbury's, and Waitrose are fragmenting formulation standards and multiplying SKU validation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Food Preservatives Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbates, Benzoates, Nitrites, Propionates Application: Packaged Foods, Beverages, Dairy Products, Baked Goods End User: Food Manufacturers, Retailers, Food Service, Households Formulation Type: Natural, Synthetic, Organic, Artificial |
| Companies Covered | Corbion N.V., Kemin Industries, Tate & Lyle PLC, BASF SE, Archer Daniels Midland Company, Kerry Group plc, Koninklijke DSM N.V., Galactic S.A., Cargill Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Food Preservatives Market Evolving Landscape
Fermentation biotechnology and non-thermal processing are converging to reshape British food preservation, displacing legacy chemical additive systems across multiple end-use verticals.
Bioprotective cultures derived from lactic acid bacteria are displacing synthetic antimicrobials in chilled dairy applications. Yorkshire and Lancashire cheese manufacturers are adopting these live cultures at accelerated rates to achieve extended shelf life without E-number declarations. This displacement is compressing demand for potassium sorbate in premium dairy segments while creating captive supply relationships between culture houses and processor cooperatives.
Retained EU regulation 1333/2008 continues to constrain maximum benzoate levels in carbonated beverages, forcing reformulation toward potassium sorbate or natural acidulant systems. The Food Standards Agency's enforcement posture is tightening ahead of anticipated EFSA opinions on additive safety, compressing formulation flexibility for mid-tier soft drink manufacturers. England's beverage bottling corridor is responding through accelerated partnerships with fermentation-derived acidulant suppliers.
Retailer clean-list procurement is consolidating supplier relationships around integrated taste-preservation system vendors. British bakery chains are displacing single-ingredient preservative purchasing with bundled solutions that combine shelf-life extension with sodium reduction and flavor modulation. This consolidation is most visible across Greater London and Manchester metropolitan manufacturing zones where procurement teams prioritize technical service depth over commodity ingredient pricing.
United Kingdom Food Preservatives Market Segmentation
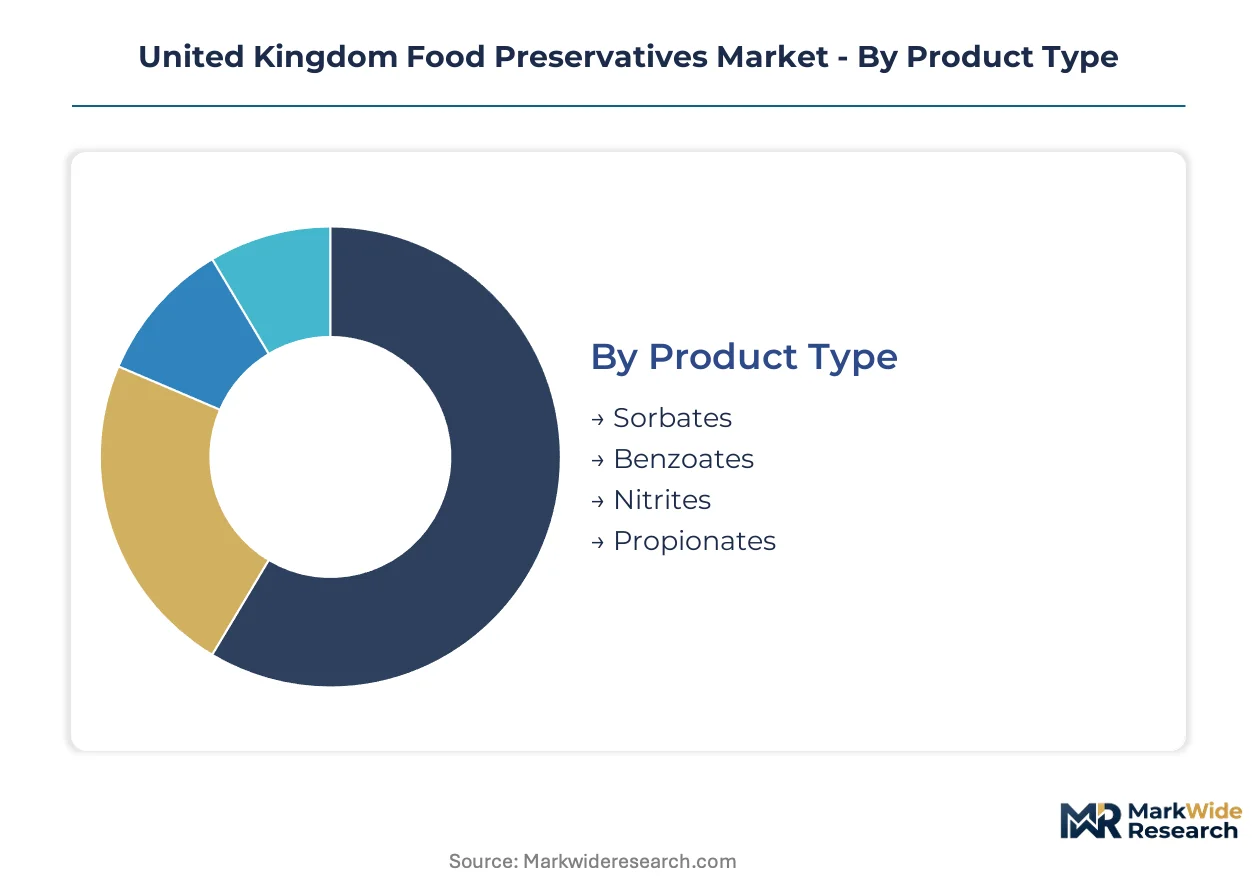
Preservative segmentation in the United Kingdom reveals divergent margin trajectories across synthetic legacy systems and fermentation-derived alternatives. Formulation type and application verticals determine pricing power, while product chemistry governs regulatory exposure and reformulation urgency.
Product Type:
Margin pools concentrate in pH-flexible synthetic chemistries and plant-derived alternatives displacing legacy nitrite systems.
- Sorbates:Potassium and sodium salts deliver broad antimicrobial efficacy across acidic to neutral pH ranges. Beverage bottlers in England's manufacturing corridor specify sorbates for carbonated and still drinks, though EFSA scrutiny on acceptable daily intakes is compressing formulation flexibility.
- Nitrites:Sodium and potassium nitrites function as curing agents and botulism inhibitors in processed meats. FSA threshold reductions under retained EU regulation 1333/2008 are forcing Greater London meat processors toward celery powder and fermented plant extracts.
- Benzoates:Sodium and potassium benzoates provide cost-effective yeast and mold inhibition in acidic foods. Regulatory pressure from EFSA scientific opinions is accelerating displacement by sorbates in soft drink applications.
- Propionates:Calcium and sodium propionates inhibit rope-forming bacteria in bread and baked goods. Manchester and Birmingham bakery chains specify propionates for extended distribution cycles in wrapped bread categories.
Sorbates holds installed capacity. Nitrites is rotating up the share rankings as natural alternatives gain technical parity.
Application:
Volume concentration follows packaged food manufacturing gravity in England's metropolitan production zones.
- Packaged Foods:Ready-to-eat meals, processed meats, and shelf-stable convenience products dominate preservative absorption. Greater London's food manufacturing corridor drives concentrated demand for clean-label preservation systems as retailer specifications tighten.
- Beverages:Carbonated soft drinks, juices, and functional waters require pH-specific antimicrobial protection. England's bottling corridor is reformulating legacy benzoate systems toward potassium sorbate and fermentation-derived acidulants.
- Dairy Products:Yogurt, cheese, and chilled desserts utilize bioprotective cultures and synthetic antimicrobials. Yorkshire and Lancashire cheese manufacturers are displacing potassium sorbate with live culture systems to eliminate E-number declarations.
- Baked Goods:Industrial bread, cakes, and pastries demand mold inhibition and anti-staling agents. British bakery chains are consolidating procurement around integrated taste-preservation bundles combining shelf-life extension with sodium reduction.
Packaged Foods commands current volume share. Dairy Products is climbing the fastest as bioprotective culture adoption accelerates.
End User:
Procurement sophistication tiers separate large-scale manufacturers from fragmented service and retail channels.
- Food Manufacturers:Industrial processors specify preservatives through technical service partnerships with ingredient houses. Reformulation timelines compress as EFSA opinion cycles accelerate and retailer compliance windows narrow.
- Retailers:Tesco, Sainsbury's, and Waitrose enforce divergent clean-list specifications that fragment formulation standards. Private-label procurement teams prioritize cost position over technical service depth.
- Food Service:Contract caterers and restaurant chains utilize preservatives in pre-prepared ingredient streams. Supply relationships concentrate through national distribution agreements with limited SKU flexibility.
- Households:Consumer-packaged preservation products represent minimal volume in direct retail channels. Domestic use concentrates in home canning and specialty baking applications.
Food Manufacturers retain technical specification authority. Retailers is gaining procurement influence through clean-list mandates.
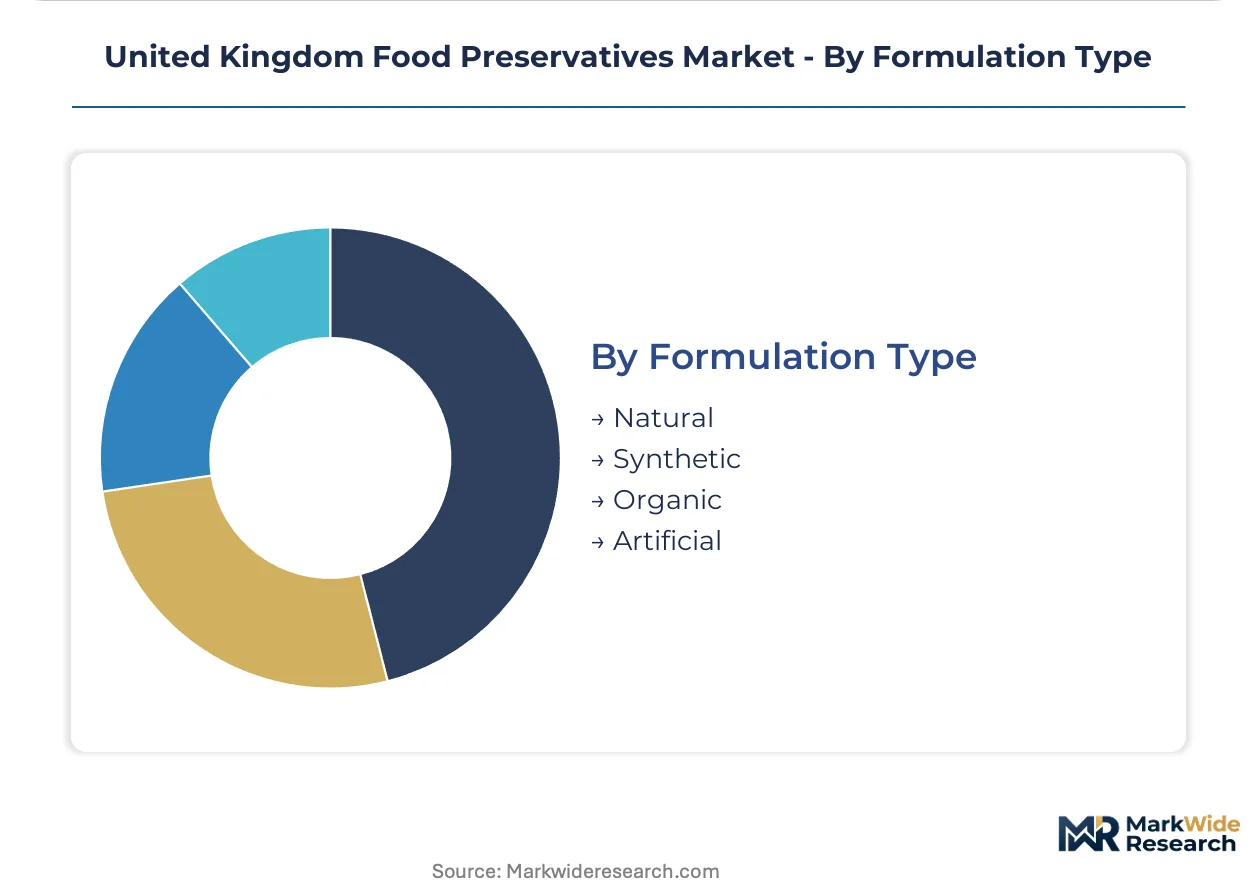
Formulation Type:
Cost structure stratification creates three-tier pricing architecture across certification grades.
- Natural:Fermentation-derived acidulants, plant extracts, and bioprotective cultures command 40-60% premiums over synthetic equivalents. Rosemary and green tea extract supply chains face agricultural yield volatility that constrains batch consistency.
- Synthetic:Petrochemical-derived sorbates, benzoates, and nitrites maintain cost leadership in private-label and economy-tier lines. Regulatory compression from FSA and EFSA is eroding long-term demand visibility.
- Organic:Certified organic preservatives meet Soil Association standards for limited synthetic residue. Supply scarcity and input certification costs restrict penetration to premium positioned product lines.
- Artificial:Chemically synthesized additives without natural derivation claims occupy declining share in E-number conscious formulations. Reformulation away from artificial classifications is accelerating across all application verticals.
Synthetic maintains volume dominance. Natural is expanding most quickly as clean-label specifications harden across British retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient manufacturing concentrates in England's metropolitan food production zones, with formulation R&D clustering around Greater London and the Midlands. Scotland and Wales present expansion vectors for specialty dairy and meat preservation applications.
Greater London and Southeast England
Premium ready-to-eat meal manufacturers and beverage bottlers drive concentrated demand for clean-label preservation systems. The Food Standards Agency enforces retained EU regulation 1333/2008 from its London headquarters, directly shaping national formulation standards. Slough and Reading host major fermentation-derived acidulant production facilities serving carbonated drink reformulation programs.
Midlands Manufacturing Corridor
Industrial bread and baked goods producers specify propionate-based mold inhibitors for extended distribution cycles. EFSA scientific opinion cycles trigger preemptive reformulation across Birmingham and Coventry bakery operations. Nottingham's food science research parks anchor collaborative partnerships between ingredient houses and regional processors.
Yorkshire and Lancashire
Artisan cheese manufacturers displace synthetic antimicrobials with bioprotective lactic acid bacteria cultures. The Soil Association's organic certification requirements constrain synthetic residue thresholds in specialty dairy. Leeds and Bradford culture houses build captive supply relationships with processor cooperatives.
Scotland
Underpenetrated specialty dairy and smoked salmon processors present white space for tailored bioprotective formulations. Food Standards Scotland coordinates with the FSA on additive safety assessments while maintaining distinct enforcement priorities. Aberdeen and Edinburgh food manufacturing zones adopt minimal-preservative systems for premium export positioning.
Wales
Traditional meat processing and emerging plant-based alternative manufacturers create bifurcated demand profiles. Welsh Government food innovation programs support natural preservation R&D in Cardiff and Newport enterprise zones. The region's agrifood cluster experiments with fermented plant extracts as nitrite alternatives in cured meat applications.
United Kingdom Food Preservatives Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the United Kingdom food preservatives market. The supplier base organizes into three functional tiers: fermentation biotechnology specialists, integrated taste-modification houses, and commodity chemical distributors. Dutch and Irish ingredient conglomerates anchor the premium natural segment through proprietary culture collections. Competitive dynamics center on reformulation service depth and clean-label certification speed rather than unit pricing alone.
Within the fermentation-derived acidulant tier, Corbion N.V. and Galactic S.A. occupy positions exemplifying biotechnology-led preservation strategies. Tate & Lyle PLC represents the integrated reformulation partnership model sustaining relationships with British bakery chains. Kerry Group plc anchors the taste-preservation convergence archetype bundling shelf-life extension with sodium reduction capabilities. These three player types illustrate how competitive positioning separates around technical service intensity rather than manufacturing scale.
| Leading Market Players |
|---|
| Corbion N.V. |
| Kemin Industries |
| Tate & Lyle PLC |
| BASF SE |
| Archer Daniels Midland Company |
| Kerry Group plc |
| Koninklijke DSM N.V. |
| Galactic S.A. |
| Cargill Incorporated |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between fermentation-derived acidulant suppliers and Greater London beverage manufacturers lock in supply access while anchoring price visibility against agricultural input volatility. Retained EU regulation 1333/2008 compliance costs cascade through formulation tiers, compressing margins for synthetic preservative distributors unable to secure captive supply relationships.
Pricing Analysis
Retained EU regulation 1333/2008 dictates the pricing tier structure across the United Kingdom food preservatives market, forcing a three-tier pricing structure across premium, standard, and economy levels. Certification grade under Soil Association organic standards and volume scale separate natural fermentation-derived products from commodity synthetic alternatives. Cost compression in the synthetic tier is intensifying because EFSA scientific opinion cycles accelerate reformulation mandates ahead of retailer compliance windows. Private-label procurement teams at economy-tier retailers exhibit highest price sensitivity, while premium ready-to-eat meal manufacturers prioritize technical service depth over unit cost.
Supply Chain Analysis
Inventory buffers for rosemary and green tea extracts extend lead times beyond synthetic chemical replenishment cycles, constraining batch-to-batch consistency for natural formulators. Supply concentrates in the Netherlands for fermentation biotechnology, China for benzoate and sorbate precursors, and India for botanical extract inputs. Raw material dependencies include corn-derived dextrose for fermentation substrates, petrochemical feedstocks for synthetic acidulants, and agricultural harvests for plant-derived antimicrobials. Single-source vulnerability in fermentation capacity creates supply chain risk during bioprocess engineering scale-up phases. Distribution runs through ingredient houses maintaining technical service partnerships with food manufacturers across England's metropolitan production corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
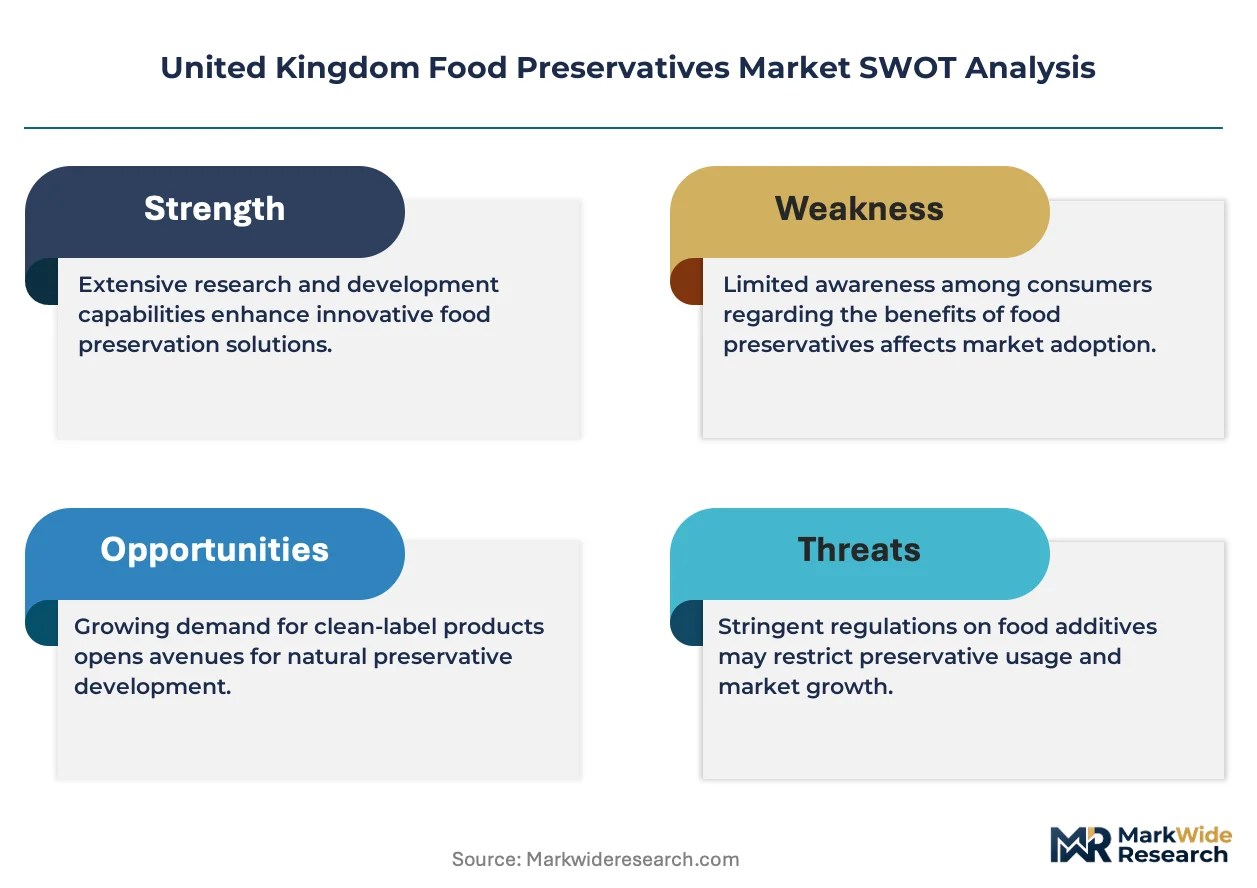
The United Kingdom food preservatives market represents a high-growth disruption as clean-label mandates from the Food Standards Agency compress synthetic demand while fermentation biotechnology captures formulation share.
For Market Incumbents: Consolidate around captive supply relationships with Yorkshire and Lancashire dairy cooperatives to defend against bioprotective culture displacement. Deepen backward integration into fermentation substrate sourcing to secure margin position against agricultural input volatility. Prioritize certification investment for Soil Association organic tiers to capture premium pricing pools. For New Entrants and Emerging Players: Differentiate on bacteriocin commercialization pathways targeting Scotland's underpenetrated specialty dairy corridor. White-space opportunities concentrate in Welsh cured meat applications seeking fermented plant extract nitrite alternatives. Go-to-market execution should anchor on technical partnership models with regional processor cooperatives rather than commodity ingredient distribution. For Investors and Strategic Acquirers: Fermentation biotechnology specialists with proprietary culture collections present the strongest acquisition target archetype for long-term viability across the 5-10 year projection horizon. Signal to watch: emerging Food Standards Agency consultations on novel preservation technologies including high-pressure processing integration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Substrates | Corn-derived dextrose supply security anchors natural acidulant production economics against agricultural volatility. |
| Bioprotective Culture Commercialization | Lactic acid bacteria applications in Yorkshire cheese manufacturing displace potassium sorbate with clean-label live culture systems. |
| High-Pressure Processing Partnership | Non-thermal pasteurization convergence with minimal preservative formulations opens premium ready-meal shelf-life extension. |
| Soil Association Certification Investment | Organic tier accreditation unlocks 40-60% pricing premiums across Waitrose and Sainsbury's clean-list procurement. |
| Scotland Dairy Corridor Expansion | Underpenetrated artisan cheese and cultured product manufacturers present white space for tailored bioprotective formulations. |
Research Methodology
A spread of perspectives from formulation R&D directors at ingredient houses, procurement leads at British bakery chains, regulatory affairs specialists navigating FSA compliance, and technical service managers at fermentation biotechnology firms converged on the working assumptions. Primary interview intelligence combined with secondary validation from retained EU regulation 1333/2008 filings, EFSA scientific opinion databases, Soil Association certification records, and customs trade data for preservative chemical imports. Bottom-up volume modeling across product type, application vertical, and formulation tier triangulated against top-down market sizing from manufacturing capacity assessments.
Segmentation dimensions modeled include synthetic versus natural versus organic formulation type, packaged foods versus beverages versus dairy versus baked goods application vertical, and England versus Scotland versus Wales regional production cluster. CAGRs were derived from elasticity-adjusted demand projections across the analysis window, incorporating EFSA opinion cycle frequency and retailer clean-list adoption curves as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued FSA enforcement posture and stable agricultural input supply; material deviation in regulatory timelines or fermentation capacity expansion would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
Seitan Powder Market
Food Additives and Ingredients
Potassium Lactate Market
Food Additives and Ingredients
Japan Food Enzymes Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
Oxidized Starch Market
Food Additives and Ingredients
United States Anti-Caking Market
Food Additives and Ingredients
Food Grade Calcium Hydroxide Market
Food Additives and Ingredients
Food Glazing Agents Market
Food Additives and Ingredients
Brazil Feed Additives Market
Food Additives and Ingredients
Food Grade Acetic Acid Market
Food Additives and Ingredients
Russia Food Preservatives Market
Food Additives and Ingredients
South Africa Food Emulsifiers Market
Food Additives and Ingredients
Europe Feed Anti-Caking Agents Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Potassium Polymetaphosphate Food Additives Market