
 United States Feed Additives Market | 2026-2036
United States Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
United States Feed Additives Market Intelligence
Modular premix bundling is expanding as a configuration pattern across the United States feed additives landscape, allowing nutritionists to swap individual micronutrient modules without reformulating entire rations. Cargill leverages its captive grain origination network to anchor supply security for amino acid and vitamin premix production. DSM-Firmenich specializes in precision-delivery vitamin technologies that differentiate its offering in ruminant applications. Alltech competes through yeast-based additive platforms that occupy a distinct position in gut health modulation.
Feed additives comprise biologically active substances—including enzymes, amino acids, vitamins, and acidifiers—formulated at parts-per-million to percent-level inclusion rates to modify nutritional uptake, metabolic efficiency, or pathogen resistance in animals raised for food production. Their primary commercial purpose centers on compressing feed conversion ratios and reducing mortality losses in confined animal feeding operations. Amino acid formulations command the deepest margin pools among product types due to their irreplaceable role in least-cost ration optimization. Poultry end-user demand leads absolute volume consumption, while aquaculture represents the fastest-expanding application frontier as marine and freshwater species diets intensify. Powder and liquid forms dominate current formulation preferences, though granular concentrates are gaining share in automated feed mill systems where dust control and flowability determine handling economics.
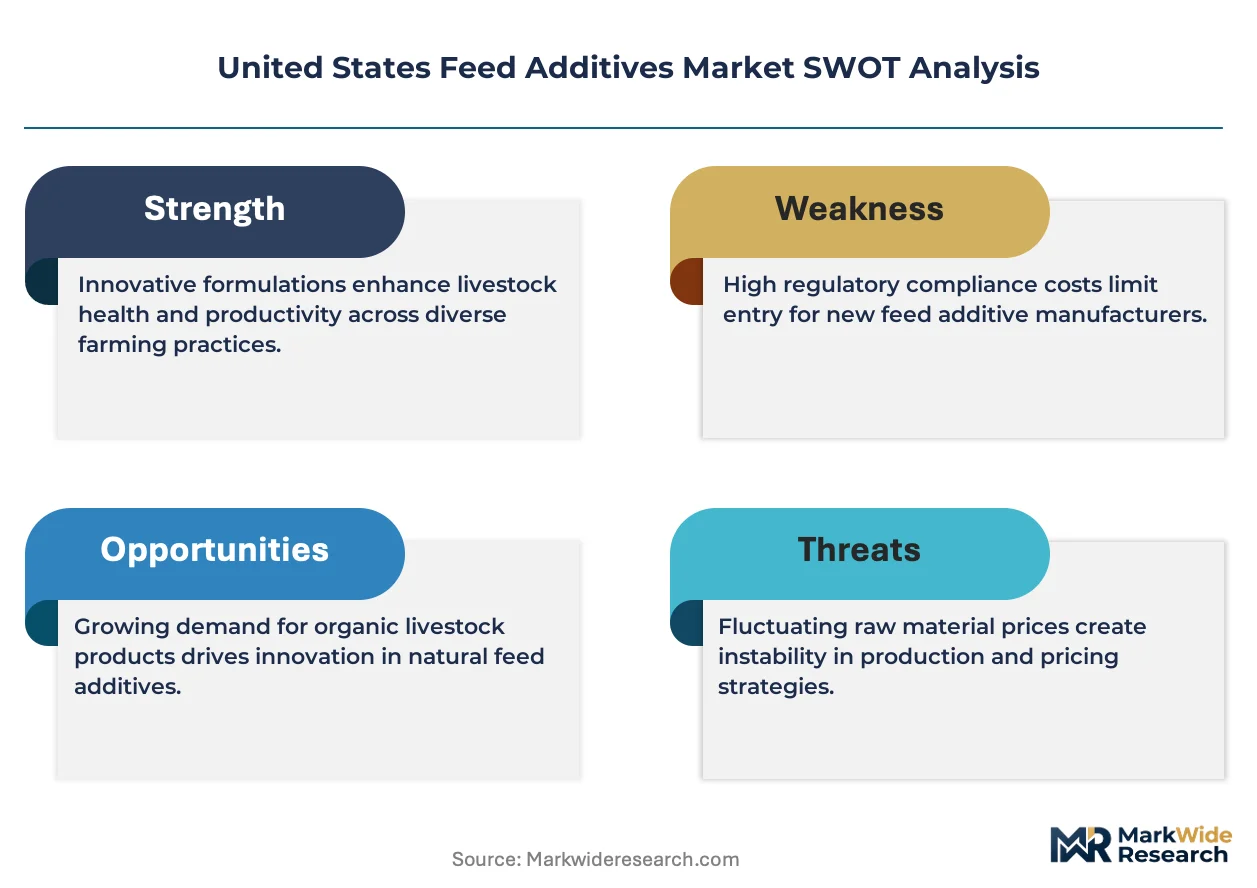
The FDA Veterinary Feed Directive and USDA Organic standards jointly constrain antibiotic growth promoter access while creating compliant alternative pathways for probiotic and phytogenic additives. EPA discharge permits and state-level nutrient management plans further shape formulation choices by restricting nitrogen and phosphorus excretion rates from livestock operations. Stakeholders must monitor emerging state ballot initiatives on animal confinement practices, as these regulatory mechanisms will determine which additive categories retain formulary access across major production geographies.
Market Dynamics
The FDA's Veterinary Feed Directive has compressed antibiotic growth promoter usage by mandating veterinary oversight, forcing feed mills to reconfigure formulation protocols around enzyme and probiotic alternatives. Poultry integrators now specify non-antibiotic performance additives in procurement contracts, redrawing competitive boundaries between legacy pharmaceutical suppliers and microbial fermentation specialists.
Growth Catalysts
- Enzyme formulation advances:Xylanase and phytase cocktails now achieve 8-12% feed conversion improvements in broiler operations, justifying premium pricing through measurable performance metrics.
- Iowa-Illinois feed milling clusters:Proximity to corn and soybean processing infrastructure enables just-in-time amino acid premix delivery, reducing working capital requirements for integrators.
- USDA Organic certification expansion:Livestock operations pursuing organic status must eliminate synthetic growth promoters, creating compliant additive demand for phytogenics and organic acidifiers.
Market Restraints
- Vitamin E and D3 input volatility:Feed-grade vitamin synthesis depends on petrochemical and lanolin feedstocks subject to energy price swings, compressing premix margin predictability.
- Chinese amino acid supply dominance:Lysine and threonine production concentrates in Shandong and Hebei provinces, exposing US formulators to tariff and logistics risk.
- Ruminant bypass technology limitations:Protected amino acids and fats suffer from inconsistent rumen release profiles, limiting adoption in dairy nutrition despite theoretical benefits.
Strategic Opportunities
- Texas Panhandle cattle feeding expansion:Large-scale beef operations in Deaf Smith and Parmer counties lack specialized ruminant additive technical service coverage.
- Precision fermentation-derived proteins:Microbial biomass from gas fermentation offers novel amino acid profiles for aquaculture diets, bypassing agricultural commodity cycles.
- California Proposition 12 compliance pathways:Sow housing restrictions create demand for stress-mitigating additives that maintain productivity under confinement constraints.
Industry Challenges
- Feed mill microbiome contamination control:Salmonella and E. coli suppression in pelleting operations requires validated additive protocols that integrate with HACCP systems.
- Phytogenic standardization gaps:Botanical additive potency varies by harvest geography and extraction method, complicating nutritionist confidence in dose-response relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Feed Additives Market |
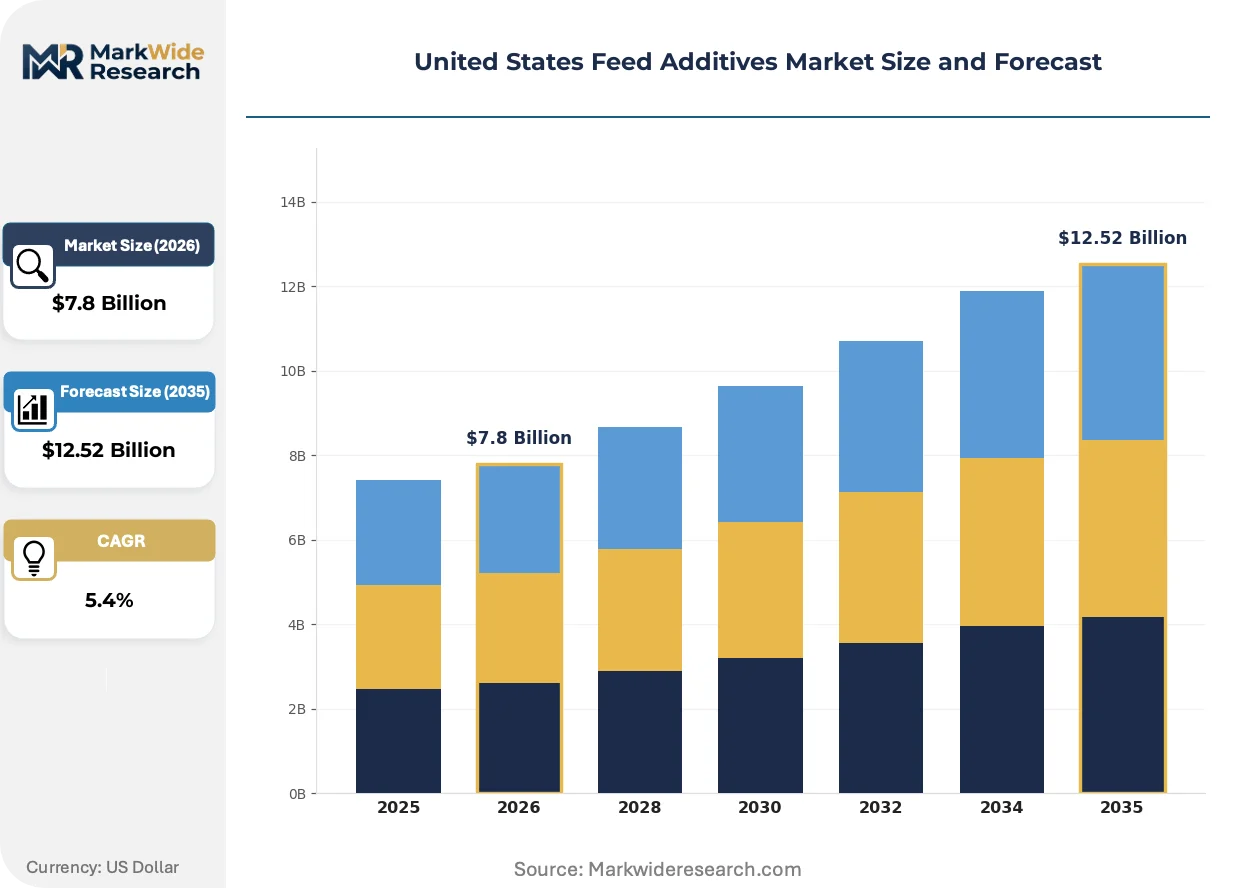
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Vitamins, Amino Acids, Enzymes End User: Poultry, Swine, Ruminants, Aquaculture Application: Growth Promotion, Nutritional Health, Digestive Health, Weight Gain Form: Powder, Liquid, Granular, Concentrate |
| Companies Covered | Cargill, Archer Daniels Midland, Adisseo, DSM-Firmenich, Evonik Industries, BASF, Alltech, Kemin Industries, Land O'Lakes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Feed Additives Market Strategic Shifts & Innovations
Formulation science is migrating from fixed-nutrient matrices toward dynamic modeling that adjusts micronutrient loading based on real-time ingredient composition analysis. This shift demands new additive delivery formats and analytical partnerships between premix suppliers and mill operators.
Microencapsulated butyrate and tributyrin formulations are absorbing intestinal health positioning previously held by antibiotic growth promoters. Broiler integrators in the Southeast are adopting these products at trial-to-contract conversion rates exceeding conventional acidifiers. The technology is absorbing margin pools from legacy coccidiostat categories as performance data accumulates across multiple grow-out cycles.
EPA nutrient management permits in Chesapeake Bay and Ohio River watersheds are tightening phosphorus discharge limits for swine and poultry operations. Formulators must document excretion reductions from phytase superdosing and low-protein amino acid balancing. Operations in Maryland and Virginia face the most stringent enforcement timelines, accelerating additive specification changes ahead of permit renewal cycles.
Large integrators are consolidating premix procurement under multi-year supply agreements with indexed amino acid pricing. Independent feed mills respond through cooperative purchasing arrangements that aggregate volume for vitamin and trace mineral negotiations. This bifurcation is most pronounced in the Carolinas, where Smithfield and Mountaire vertical integration contrasts with remaining independent mill capacity serving smaller hog finishers.
United States Feed Additives Market Segmentation
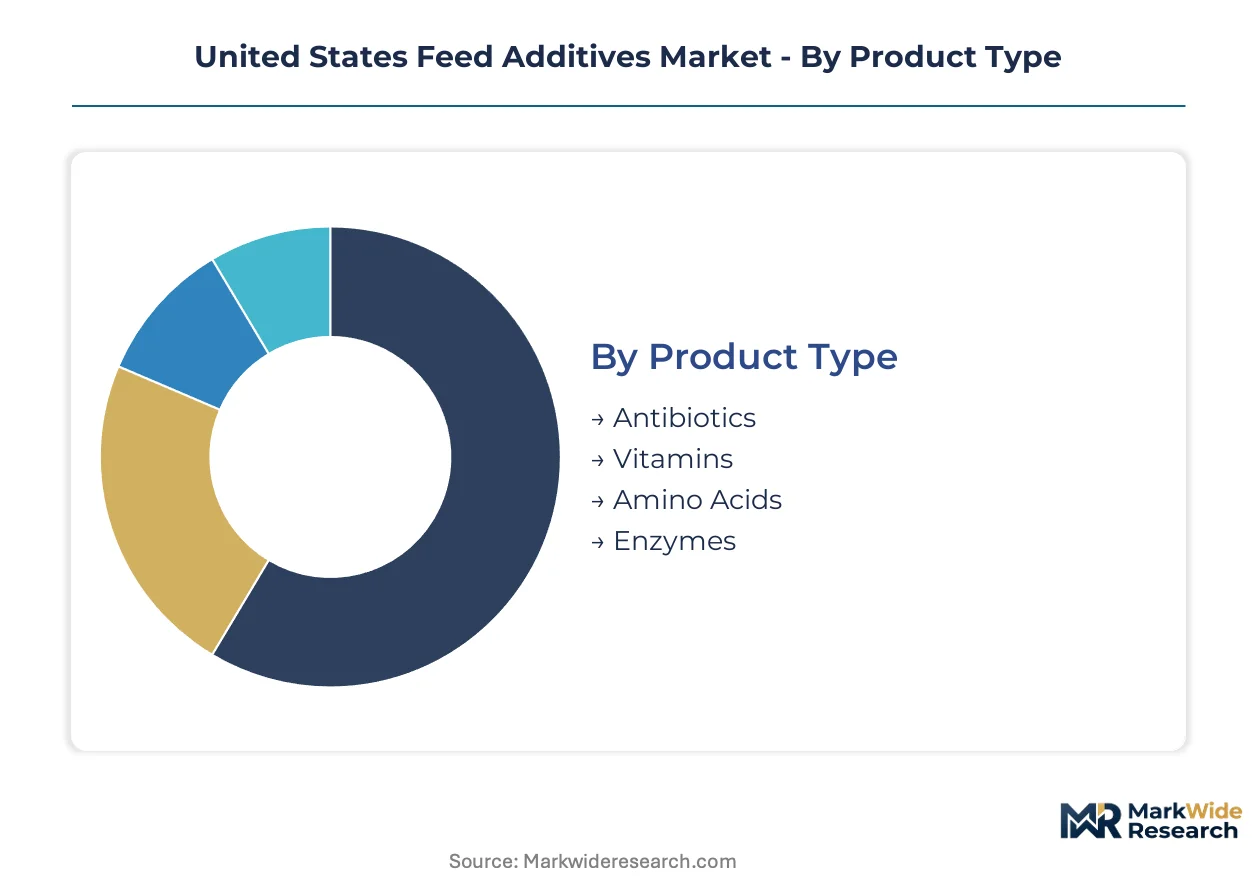
Feed additive segmentation in the United States reflects the divergent biological requirements of livestock species and the regulatory constraints shaping permissible ingredients. Formulation choices cascade from end-user procurement specifications through to manufacturing equipment requirements at the mill level.
Product Type:
Amino acid and enzyme production concentrates near Corn Belt processing infrastructure where captive grain supply secures fermentation feedstock access.
- Amino Acids:Lysine, methionine, threonine, and tryptophan formulations enable least-cost ration optimization by replacing crude protein with precise synthetic supplementation. Demand concentrates in Iowa and Illinois integrator operations where large-scale premix facilities achieve just-in-time delivery economics. The category commands the deepest margin pools due to irreplaceable nutritional functionality and scale-dependent manufacturing barriers.
- Enzymes:Xylanase, phytase, and protease cocktails modify feed substrate digestibility through targeted hydrolysis of anti-nutritional factors. Poultry integrators in the Southeast specify these formulations at contract rates exceeding conventional acidifiers as FDA Veterinary Feed Directive compliance displaces antibiotic growth promoters. Phytase superdosing specifically addresses Chesapeake Bay watershed phosphorus discharge limits.
- Vitamins:Fat-soluble and water-soluble micronutrient premixes stabilize metabolic function across stress periods. Feed-grade synthesis depends on petrochemical and lanolin feedstocks subject to energy price volatility.
- Antibiotics:Therapeutic and sub-therapeutic formulations now require veterinary oversight under FDA Veterinary Feed Directive mandates. Usage patterns have compressed to treatment protocols from historical growth promotion applications.
Amino acids absorb the bulk of installed capacity; enzymes are expanding most quickly.
End User:
Species-specific digestive physiology determines additive bioavailability requirements and dosing precision standards.
- Poultry:Broiler and layer operations consume the largest absolute additive volumes due to intensified production density and compressed grow-out cycles. Enzyme cocktails and acidifiers dominate Southeastern integrator procurement as non-antibiotic performance protocols harden into contract specifications.
- Swine:Nursery and finishing phases require amino acid balancing to optimize lean tissue deposition while managing nitrogen excretion under EPA discharge permits. California Proposition 12 sow housing restrictions create demand for stress-mitigating additives.
- Ruminants:Dairy and beef operations present formulation complexity due to rumen microbial interference with nutrient absorption. Bypass-protected amino acids suffer from inconsistent release profiles limiting adoption despite theoretical benefits.
- Aquaculture:Marine and freshwater species diets represent the steepest expansion trajectory as domestic intensification reduces wild fishmeal dependence. Precision fermentation-derived proteins offer novel amino acid profiles bypassing agricultural commodity cycles.
Poultry commands the largest share of current volume; aquaculture is climbing the fastest.
Application:
Functional positioning of additives aligns with measurable performance outcomes that justify procurement premiums.
- Nutritional Health:Vitamin and trace mineral supplementation prevents deficiency syndromes during metabolic stress periods. USDA Organic certification expansion restricts synthetic options, redirecting demand toward compliant natural alternatives.
- Digestive Health:Probiotic, prebiotic, and acidifier formulations modulate gut microbiome composition to suppress pathogen colonization. Microencapsulated butyrate absorbs positioning previously held by antibiotic growth promoters.
- Growth Promotion:Enzyme and amino acid interventions compress feed conversion ratios through enhanced nutrient uptake. Poultry integrators specify these outcomes in procurement contracts with indexed pricing.
- Weight Gain:Metabolic efficiency additives optimize tissue deposition rates in finishing phases. Texas Panhandle cattle feeding operations lack specialized technical service coverage for ruminant-specific formulations.
Nutritional health captures the broadest installed base; digestive health is gaining share fastest.
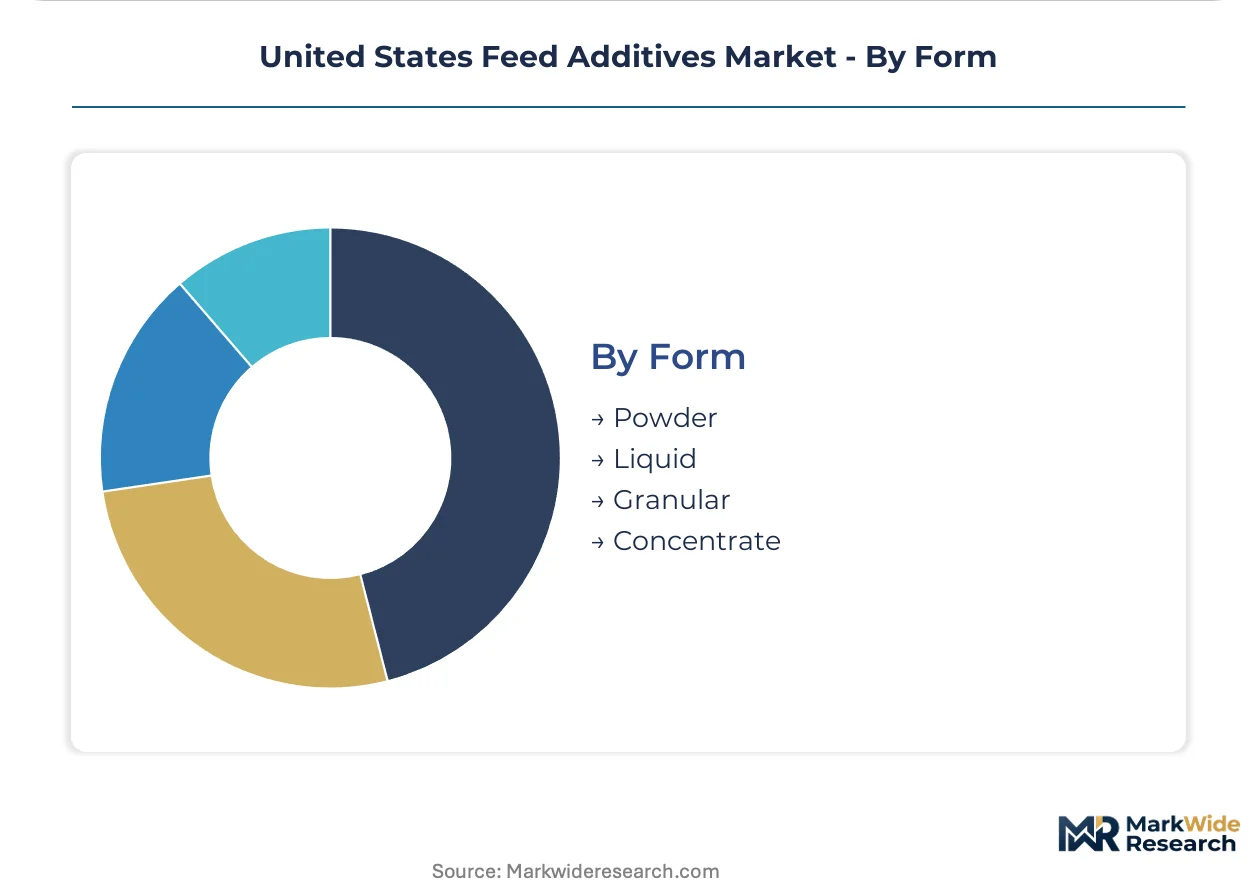
Form:
Physical formulation determines handling economics and dosing precision in automated mill systems.
- Powder:Fine-ground additives enable homogeneous distribution in mash feeds at low inclusion rates. Dust control requirements increasingly favor alternative formats in large-scale operations.
- Liquid:Pumpable formulations integrate into fat coating and spray application systems for post-pelleting nutrient addition. Flowability advantages support just-in-time manufacturing at high-throughput mills.
- Granular:Agglomerated particles reduce dust generation and improve flow characteristics in pneumatic handling systems. Automated feed mill adoption is driving share expansion.
- Concentrate:High-potency premixes minimize transport and storage costs for micronutrients used at parts-per-million rates. Precision-delivery technologies differentiate supplier positioning in ruminant applications.
Powder retains the largest installed base; granular is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Corn Belt states generate the bulk of domestic feed additive consumption while coastal aquaculture clusters drive emerging demand. Production capacity concentrates near grain origination infrastructure to minimize fermentation feedstock logistics. Regulatory fragmentation across watersheds and state ballot initiatives shapes regional formulation preferences.
Midwest Corn Belt
Iowa and Illinois integrators consume the largest absolute additive volumes due to dense poultry and swine operations. EPA nutrient management plans in the Ohio River watershed tighten phosphorus discharge limits, accelerating phytase superdosing adoption. Des Moines and Cedar Rapids anchor amino acid premix manufacturing clusters with just-in-time delivery to feed mills.
Southeast Poultry Belt
Georgia and Alabama broiler integrators specify enzyme cocktails and acidifiers under non-antibiotic performance contracts. FDA Veterinary Feed Directive enforcement has compressed legacy antibiotic growth promoter usage to therapeutic protocols. The Dalton-Rome corridor in northwest Georgia clusters specialized technical service operations for poultry nutrition.
Texas Panhandle
Deaf Smith and Parmer counties host expanding large-scale cattle feeding operations with unmet demand for ruminant-specific additive technical coverage. State-level water discharge permits constrain nitrogen excretion, creating openings for amino acid balancing formulations. Amarillo serves as the regional distribution node for bypass-protected nutrient technologies.
Chesapeake Bay Watershed
Maryland and Virginia poultry and swine operations face the most stringent EPA phosphorus discharge timelines ahead of permit renewals. Operations must document excretion reductions through low-protein amino acid balancing and enhanced phytase loading. The Delmarva Peninsula concentrates contract grow-out density requiring intensive additive protocol validation.
California Central Valley
Proposition 12 sow housing restrictions generate demand for stress-mitigating additives maintaining productivity under confinement constraints. USDA Organic certification expansion in the state redirects procurement toward compliant phytogenic and organic acidifier alternatives. Fresno and Modesto integrate dairy nutrition consulting with precision-delivery vitamin technologies.
United States Feed Additives Market Key Industry Players
The competitive structure tilts toward diversified agricultural conglomerates with captive grain supply chains. Cargill and Archer Daniels Midland leverage origination infrastructure to anchor amino acid and vitamin premix security. Three archetypes dominate: integrated grain-processors with fermentation capacity, precision-nutrition specialists with delivery technologies, and microbial-platform innovators in gut health. Consolidation pressures intensify through multi-year supply agreements with indexed amino acid pricing, while independent mills respond via cooperative purchasing arrangements.
Among diversified agricultural processors, Cargill and Archer Daniels Midland exemplify the grain-anchored archetype with backward integration into fermentation feedstocks. DSM-Firmenich occupies a position in precision-delivery vitamin technologies for ruminant applications. Alltech represents the microbial-platform vector through yeast-based additive positioning in gut health modulation. These three companies illustrate the strategic bifurcation between scale-driven supply security and technology-driven formulation differentiation.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| Adisseo |
| DSM-Firmenich |
| Evonik Industries |
| BASF |
| Alltech |
| Kemin Industries |
| Land O'Lakes |
| Others |
Cost & Logistics Intelligence
Poultry integrator procurement consolidation in the Southeast and Corn Belt tilts pricing power toward volume-scale buyers demanding multi-year supply agreements with indexed amino acid clauses. This buyer concentration forces premix suppliers to absorb input volatility through formula pricing rather than spot market exposure.
Pricing Analysis
Margin tightening in vitamin premix tiers reflects petrochemical and lanolin feedstock energy price swings that compress predictability. Three-tier pricing structure across premium, standard, and economy levels separates precision-delivery technologies from commodity micronutrient blends. Cost-down pressure on standard-grade amino acid formulations accelerates because Chinese lysine and threonine supply dominance exposes US formulators to tariff risk. Independent feed mills exhibit highest price sensitivity due to working capital constraints, while integrated poultry operations leverage contract scale for locked-in rates.
Supply Chain Analysis
Direct-to-feed-mill channels handle large integrator demand through just-in-time amino acid premix delivery from Iowa and Illinois manufacturing clusters. Geographic supply concentration centers on China for fermentation-derived lysine and threonine, with domestic Corn Belt production for grain-based ethanol co-products. Raw material dependencies include corn steep liquor, molasses, and petrochemical precursors for vitamin synthesis. Single-source vulnerability in Shandong and Hebei province amino acid capacity creates tariff and logistics risk exposure. Distribution runs through cooperative purchasing arrangements for independent mills and captive supply networks for integrated processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States feed additives market functions as a cost-of-compliance arena where FDA Veterinary Feed Directive mandates erect formulation protocol barriers that favor established players with veterinary oversight infrastructure.
For Market Incumbents: Deploy indexed amino acid pricing mechanisms to lock multi-year integrator contracts before Chinese tariff exposure escalates. Deepen captive grain origination control to secure fermentation feedstock access against commodity cycle volatility. Consolidate technical service coverage in underserved Texas Panhandle cattle feeding zones before regional competitors establish ruminant bypass technology beachheads. For New Entrants and Emerging Players: Direct-to-aquaculture digital channels offer the most penetrable route for precision fermentation-derived protein platforms bypassing agricultural commodity cycles. Target California Central Valley organic certification pathways where USDA compliance creates demand for phytogenic and organic acidifier alternatives. White-space exists in Chesapeake Bay watershed phosphorus discharge documentation services bundled with phytase superdosing protocols. For Investors and Strategic Acquirers: The window for entry favors microbial-platform innovators with validated gut health modulation data displacing legacy antibiotic growth promoter positioning. Long-term viability hinges on acquisition targets possessing EPA nutrient management permit compliance documentation capabilities. Watch California Proposition 12 enforcement timelines as the inflection signal for stress-mitigating additive demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Delivery Technology Investment | DSM-Firmenich's ruminant vitamin platforms demonstrate premium capture through bioavailability differentiation. |
| Backward Integration into Fermentation Feedstocks | Cargill's captive corn origination secures amino acid premix supply security against Chinese import volatility. |
| Multi-Year Supply Agreement Structuring | Indexed pricing clauses transfer commodity risk to suppliers while locking integrator volume commitments. |
| Organic Certification Compliance Pathway | USDA Organic standards redirect procurement toward phytogenic alternatives, creating compliant additive demand. |
| Regional Technical Service Expansion | Texas Panhandle cattle feeding operations lack specialized ruminant additive coverage, creating service gaps. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with feed mill procurement managers, poultry integrator nutritionists, veterinary oversight officers, and amino acid fermentation specialists combined with FDA Veterinary Feed Directive enforcement documentation, EPA nutrient management permit databases, and USDA Organic certification registries. Bottom-up volume triangulation across product type and end-user segments reconciled with top-down value estimates from premix manufacturing capacity assessments.
Data-stream reconciliation employed cross-segment validation across amino acid, enzyme, vitamin, and probiotic categories. Modeled dimensions included livestock species, functional application, physical formulation, and regional regulatory cluster. CAGRs derived from trend extrapolation of FDA compliance-driven formulation shifts and integrator contract specification changes. Industry-specific inputs encompassed phytase superdosing adoption curves in Chesapeake Bay watersheds and precision fermentation protein commercialization timelines.
The model holds under stable FDA enforcement intensity and Chinese amino acid supply continuity; deviation in tariff regimes or veterinary oversight mandate expansion would shift volume trajectories. Forecasts reflect documented assumptions regarding enzyme cocktail adoption rates and organic certification growth curves. Periodic stress-testing of base assumptions is recommended given state ballot initiative volatility on animal confinement practices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Acidulants Market
Food Additives and Ingredients
Acrylamide Reduction Market
Food Additives and Ingredients
Australia Food Acidulants Market
Food Additives and Ingredients
North America Food Coating Ingredients Market
Food Additives and Ingredients
Protective Cultures Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
Global Food Grade Calcium Chloride Market
Food Additives and Ingredients
Beverage Stabilizer Market
Food Additives and Ingredients
Global Fatty Acids Market
Food Additives and Ingredients
Instant Fat Powder Market
Food Additives and Ingredients
France Adjuvants Market
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
UK Food Enzymes Market
Food Additives and Ingredients
Natural Food Additives Market
Food Additives and Ingredients
Monk Fruit Ingredient Market
Food Additives and Ingredients
Africa Food Acidulants Market