
 Distilled Monoglycerides Market | 2026-2036
Distilled Monoglycerides Market Size, Share, and Industry Trends Forecast 2026-2036
Distilled Monoglycerides Market Outlook
Multi-source procurement for vegetable-derived feedstocks is broadening across the distilled monoglycerides value chain. Corbion leverages microbial fermentation expertise to secure non-GMO supply lines. Wilmar International anchors Southeast Asian palm oil access through integrated crushing and refining assets. BASF SE differentiates via pharmaceutical-grade monoglyceride portfolios for regulated drug-delivery applications.
Distilled monoglycerides are glycerol esters of fatty acids refined to minimum 90% monoester content through molecular distillation, functioning primarily as emulsifiers that stabilize water-oil interfaces in processed foods and topical formulations. Glycerol monostearate dominates commercial volumes due to its crystallization stability and widespread bakery deployment. Glycerol monolaurate represents the fastest-expanding product type, driven by antimicrobial properties in clean-label preservation systems. Food and beverage applications command the largest value pool, while pharmaceutical-grade segments capture premium margin tiers through compendial compliance requirements.
FDA food additive regulations under 21 CFR 184.1505 govern U.S. market access, while EFSA evaluates novel emulsifier safety under updated food additive reauthorization cycles. China's NMPA and SAMR enforce GB standards for pharmaceutical excipient grades, tightening import documentation for foreign suppliers. Stakeholders must monitor evolving purity thresholds across FDA, EFSA, and NMPA jurisdictions to preempt reformulation costs and secure multi-regional product registrations.
Market Dynamics
Clean-label reformulation mandates under EU REACH and EFSA frameworks are forcing distilled monoglyceride producers to eliminate synthetic additives and demonstrate traceable vegetable-derived supply chains. This regulatory compression is redrawing competitive boundaries between palm-oil-dependent and microbial-fermentation-based supply models.
Growth Catalysts
- EFSA Food Additive Reauthorization:The updated safety evaluation cycle is accelerating clean-label emulsifier adoption across European bakery and confectionery manufacturing, creating compulsion for distilled monoglyceride substitution of synthetic alternatives.
- Antimicrobial Preservation Systems:Glycerol monolaurate's natural antimicrobial properties are displacing chemical preservatives in refrigerated dough and clean-label sauces, opening formulation partnerships with premium sauce manufacturers.
- China:SAMR enforcement of GB standards for pharmaceutical excipients is tightening import documentation requirements, advantaging domestic producers with established NMPA compliance infrastructure.
Market Restraints
- Palm Oil Price Volatility:Feedstock cost swings in Malaysian and Indonesian crude palm oil markets transmit directly to glycerol monostearate production economics, compressing margin predictability for non-integrated processors.
- Regulatory Friction:Divergent purity thresholds between FDA 21 CFR 184.1505 and EFSA specifications force dual-registration investments, raising fixed costs for multi-regional suppliers.
- Enzymatic Ester Substitutes:Lipase-catalyzed emulsifier production is emerging as a processing alternative with lower energy intensity, threatening molecular distillation's cost position in commodity applications.
Strategic Opportunities
- India:FSSAI's evolving standards for processed bakery goods present first-mover positioning for distilled monoglyceride suppliers establishing local technical service capabilities ahead of formal clean-label mandates.
- Pharmaceutical-Grade Excipients:Compendial compliance for drug-delivery applications commands premium pricing tiers unavailable in food-grade commoditized segments, rewarding USP-NF investment.
- Microbial Fermentation Convergence:Integration of precision fermentation with lipid biochemistry is enabling non-GMO, non-palm supply lines that satisfy EU Deforestation Regulation due diligence requirements.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Molecular distillation optimization and monoester purity verification require specialized chromatography expertise that competes with broader pharmaceutical quality control hiring pools.
- Multi-Jurisdictional Registration Timelines:Sequential FDA, EFSA, and NMPA approval processes extend product commercialization cycles, delaying revenue recognition for novel glyceride compositions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distilled Monoglycerides Market |
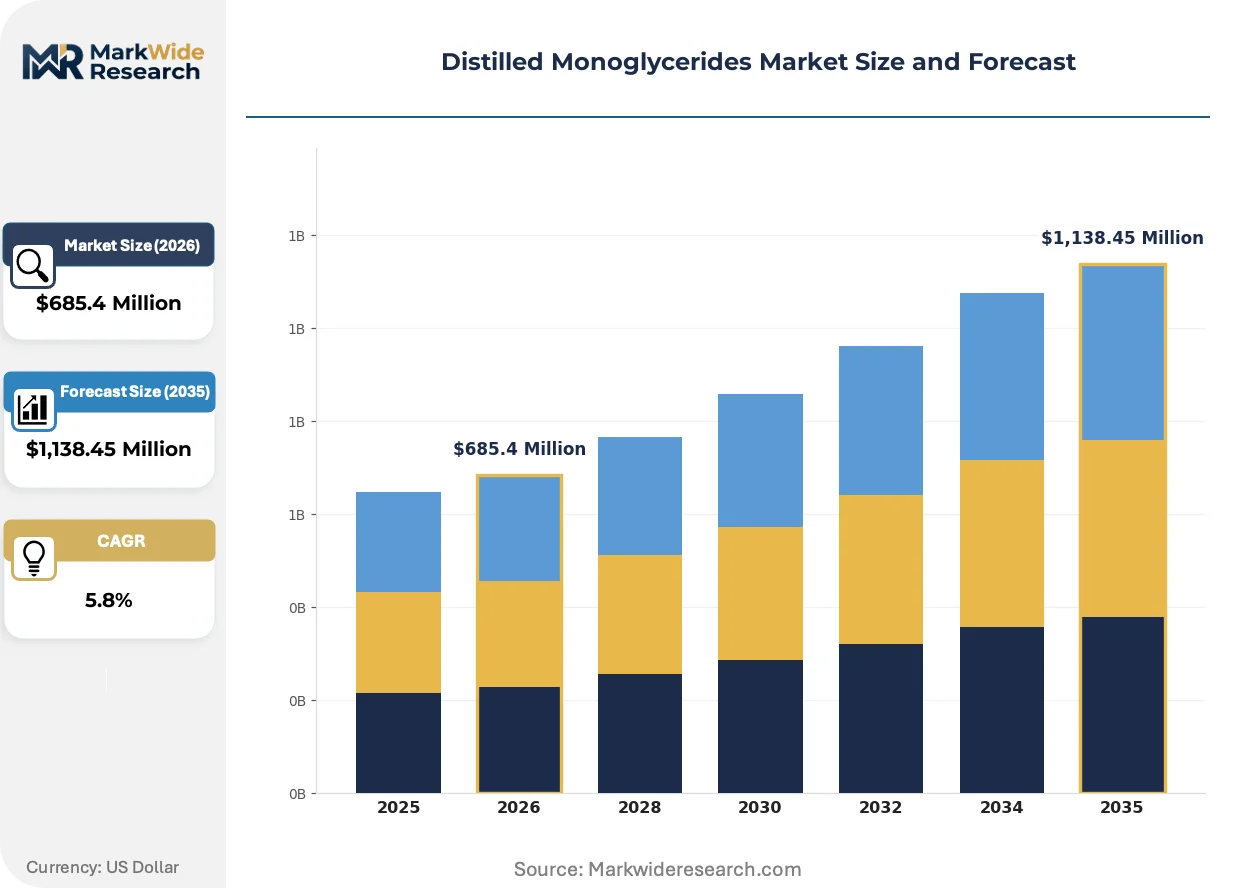
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glycerol Monostearate, Glycerol Monooleate, Glycerol Monododecanoate, Glycerol Monolaurate Application: Food & Beverage, Cosmetics, Pharmaceuticals, Animal Feed End User: Food Manufacturers, Cosmetic Brands, Pharmaceutical Companies, Livestock Producers Distribution Channel: Online Retail, Direct Sales, Wholesale, Distributors |
| Companies Covered | DuPont de Nemours, Inc., Corbion, Cargill, Incorporated, Archer Daniels Midland Company, Wilmar International, BASF SE, Palsgaard A/S, Riken Vitamin Co., Ltd., Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distilled Monoglycerides Market Strategic Shifts
Processing technology convergence and regulatory transparency mandates are compressing traditional supply advantages while opening formulation partnerships across pharmaceutical and food-grade boundaries. Innovation vectors center on feedstock diversification and analytical verification capabilities.
Enzymatic glycerolysis systems are expanding into commercial-scale distilled monoglyceride production, replacing energy-intensive molecular distillation with lipase-catalyzed esterification at moderate temperatures. Mid-sized bakery ingredient suppliers in Germany and the Netherlands are piloting these systems to secure EU Green Deal-aligned carbon footprint credentials. The technology is expanding into commodity emulsifier segments previously dominated by thermochemical processing, compressing capital barriers for new market entrants.
EFSA's updated food additive reauthorization framework is mandating extended toxicological datasets for emulsifiers, including distilled monoglycerides previously grandfathered under older safety evaluations. Manufacturers must commission new in vitro and dietary exposure studies to maintain authorized status, raising fixed compliance costs disproportionately for smaller producers. The pharmaceutical-grade segment is responding fastest, leveraging existing pharmacopeial documentation to bridge regulatory gaps.
Brand-owner direct sourcing from certified sustainable palm operations is consolidating procurement relationships, bypassing traditional multi-tier distributor networks. Large bakery conglomerates in the United States and France are implementing mass-balance certification requirements that trace monoglyceride fractions to specific crushing mill origins. This verification-driven preference shift is most visible in premium private-label confectionery, where clean-label claims require documentary evidence rather than ingredient list disclosure alone.
Distilled Monoglycerides Market Segmentation

Distilled monoglycerides serve divergent performance requirements across food emulsification, pharmaceutical solubilization, and antimicrobial preservation. Segmentation reveals where standalone commodity grades suffice versus where embedded compendial specifications command premium positioning.
Product Type:
Integration depth varies sharply: glycerol monostearate dominates as a standalone bakery emulsifier, while glycerol monolaurate embeds into complex clean-label preservation systems requiring multi-ingredient synergy.
- Glycerol Monostearate:This 90%+ purity monoester crystallizes reliably at water-oil interfaces, stabilizing margarine and bread dough formulations. Demand concentrates in German industrial bakeries and U.S. frozen dough operations where EFSA clean-label mandates are displacing synthetic emulsifiers.
- Glycerol Monolaurate:Possessing documented antimicrobial efficacy against Gram-positive bacteria, this C12 monoester integrates into refrigerated sauce and clean-label meat preservation systems. Expansion concentrates in French premium sauce manufacturing and Chinese chilled prepared foods where SAMR documentation requirements favor domestic microbial-fermentation supply lines.
- Glycerol Monooleate:This unsaturated C18 monoester delivers fluidity at reduced temperatures for topical pharmaceutical applications.
- Glycerol Monododecanoate:A saturated C12 variant finding niche use in specialized cosmetic emulsion systems.
Volume placements concentrate in glycerol monostearate; the faster expansion belongs to glycerol monolaurate.
Application:
Cost tier stratification separates commodity food-grade volumes from pharmaceutical-grade premiums where compendial compliance investments create margin insulation.
- Food & Beverage:Emulsification in bakery, confectionery, and dairy applications constitutes the foundational demand pool. FDA 21 CFR 184.1505 grandfathered status sustains broad formulation access, though EFSA reauthorization cycles are forcing toxicological dataset renewals.
- Pharmaceuticals:USP-NF compliant grades serve as solubilizers and stabilizers in oral and topical drug delivery. NMPA GB standards enforcement in China is tightening import documentation, advantaging producers with established pharmacopeial infrastructure.
- Cosmetics:Topical emulsion stabilization for skin and hair care formulations drives moderate-volume demand.
- Animal Feed:Nutritional emulsification and pellet binding applications support livestock production economics.
Revenue concentration sits in food and beverage; pharmaceutical-grade segments capture the steepest margin expansion trajectory.
End User:
Customer type determines procurement sophistication, with pharmaceutical companies demanding batch-level certificates of analysis that food manufacturers rarely require.
- Food Manufacturers:Industrial bakery and confectionery operations in Germany, China, and the United States anchor procurement volumes. Direct sourcing from mass-balance certified palm operations is consolidating supplier relationships away from distributor tiers.
- Pharmaceutical Companies:Drug developers and contract manufacturers require compendial-grade monoglycerides with validated impurity profiles. Multi-jurisdictional FDA, EFSA, and NMPA registration timelines extend commercialization cycles for novel glyceride compositions.
- Cosmetic Brands:Formulators of premium skin care and color cosmetics specify cosmetic-grade monoesters for sensory and stability performance.
- Livestock Producers:Feed compounders integrate nutritional emulsifiers into rations for improved fat digestibility and pellet durability.
Procurement scale concentrates in food manufacturers; pharmaceutical companies deliver the highest per-kilogram value realization.
Distribution Channel:
Supply concentration patterns favor direct relationships for volume accounts, while fragmented regional demand routes through intermediaries.
- Direct Sales:Large bakery conglomerates and pharmaceutical manufacturers negotiate frame contracts with producers for glycerol monostearate and compendial grades. Mass-balance certification requirements in France and the United States mandate documentary traceability that direct relationships facilitate.
- Distributors:Regional chemical and ingredient distributors serve mid-sized cosmetic brands and animal feed compounders with lower volume requirements and broader formulation portfolios.
- Wholesale:Commodity glycerol monostearate volumes for standard bakery applications flow through food ingredient wholesalers with established logistics networks.
- Online Retail:Small-scale cosmetic formulators and specialty food producers access packaged quantities through digital channels.
Transaction volume concentrates in direct sales; distributor channels retain importance for geographic market development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian and Indonesian crude palm oil supplies anchor production economics for glycerol monostearate manufacturing. Distilled monoglyceride demand concentrates in industrial bakery clusters across Germany, China, and the United States where clean-label reformulation accelerates.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia drive glycerol monostearate consumption for frozen dough stabilization. EFSA food additive reauthorization mandates toxicological dataset renewals that favor established suppliers with pharmacopeial documentation. Cologne-based ingredient formulators are consolidating direct sourcing relationships with mass-balance certified palm operations.
China
SAMR enforcement of GB standards for pharmaceutical excipients tightens import documentation for foreign monoglyceride suppliers. Yangtze River Delta pharmaceutical manufacturers demand compendial-grade glycerol monostearate with validated impurity profiles. Domestic microbial-fermentation producers in Jiangsu province are capturing market share through NMPA compliance infrastructure.
United States
FDA 21 CFR 184.1505 grandfathered status sustains broad formulation access for distilled monoglycerides in industrial bakery applications. Frozen dough operations in the Midwest and Southeast are displacing synthetic emulsifiers under clean-label pressure from retail brand owners. Chicago-area ingredient distributors are implementing documentary traceability systems for mass-balance certification.
France
Premium sauce manufacturers in the Île-de-France region integrate glycerol monolaurate into refrigerated clean-label preservation systems. EU REACH frameworks compel elimination of synthetic additives from emulsifier formulations. Lyon-based food ingredient clusters are piloting enzymatic glycerolysis systems to secure EU Green Deal-aligned carbon credentials.
India
FSSAI's evolving standards for processed bakery goods present positioning opportunities for distilled monoglyceride suppliers establishing local technical capabilities. Maharashtra and Gujarat industrial bakeries are expanding capacity ahead of anticipated clean-label mandates. Mumbai-based procurement teams are evaluating direct sourcing models to bypass traditional distributor tiers.
Distilled Monoglycerides Market Competitive Environment
Global majors compete with regional champions across feedstock access and regulatory compliance capabilities. Market structure shows moderate concentration with integrated palm oil processors holding supply advantages and specialized fermentation-based producers gaining share in premium segments. Three archetypes dominate: integrated agribusiness conglomerates with captive crushing assets, precision fermentation specialists with non-GMO supply lines, and pharmaceutical-grade refiners with pharmacopeial infrastructure. Competitive moves center on backward integration into sustainable palm certification and technology licensing for enzymatic production methods.
Among integrated agribusiness players, Wilmar International and Cargill, Incorporated exemplify the palm-oil-dependent archetype with Southeast Asian supply chain control. BASF SE occupies a position within the pharmaceutical-grade tier, leveraging compendial compliance investments to capture premium pricing unavailable in commoditized food-grade segments. Corbion represents the microbial-fermentation convergence model, enabling non-palm supply lines that satisfy EU Deforestation Regulation due diligence requirements.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Corbion |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Wilmar International |
| BASF SE |
| Palsgaard A/S |
| Riken Vitamin Co., Ltd. |
| Kerry Group |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in German and Dutch bakery ingredient manufacturing anchor pricing discipline through long-term frame contracts with industrial bakers. Their ownership structure limits speculative inventory plays, tethering glycerol monostearate quotations to Malaysian crude palm oil futures with predictable lag structures.
Pricing Analysis
Technical service bundling separates pharmaceutical-grade glycerol monostearate from unbundled food-grade commodity transactions. Three-tier pricing structure across USP-NF certified, food-grade mass-balance, and standard bakery grades reflects documentation burden and impurity verification depth. Pricing pressure stems from enzymatic glycerolysis entrants capturing carbon-conscious buyers in EU Green Deal jurisdictions. Food manufacturers exhibit highest price sensitivity, while pharmaceutical companies absorb premiums for validated batch certificates.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Singapore consolidate molecular distillation outputs for re-export to formulation plants. Malaysian and Indonesian palm oil estates feed glycerol monostearate production; Jiangsu province microbial-fermentation facilities supply glycerol monolaurate. Single-source vulnerability concentrates in Southeast Asian crude palm oil logistics. Distribution runs through direct sales for volume accounts and chemical distributors for fragmented cosmetic and feed demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over certified sustainable palm or microbial-fermentation capacity determines margin capture. Players are pursuing backward integration into feedstock origination to escape commodity pricing cycles.
For Market Incumbents: Extend pharmacopeial documentation investments to bridge EFSA reauthorization gaps before smaller competitors exhaust compliance budgets. Lock in mass-balance certified palm supply through equity stakes in Indonesian crushing assets. Enzymatic glycerolysis threatens molecular distillation's cost position in commodity tiers. For New Entrants and Emerging Players: Precision fermentation platforms for non-GMO glycerol monolaurate production unlock white-space positioning in EU Deforestation Regulation-compliant supply lines. Target Indian industrial bakeries ahead of FSSAI clean-label formalization. Lead with technical service partnerships rather than price undercutting. For Investors and Strategic Acquirers: Distressed-cycle entries favor pharmaceutical-grade refiners with dormant USP-NF infrastructure in Yangtze River Delta manufacturing zones. Long-term viability hinges on regulatory compliance scalability across FDA, EFSA, and NMPA jurisdictions. Monitor EFSA food additive reauthorization timelines as margin compression inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Palm | Mass-balance traceability satisfies EU Deforestation Regulation due diligence for French bakery conglomerates. |
| Enzymatic Glycerolysis Scale-Up | Lipase-catalyzed production secures EU Green Deal carbon credentials for German mid-cap ingredient suppliers. |
| Pharmaceutical-Grade Certification | USP-NF compliance unlocks premium pricing tiers unavailable in commoditized food-grade segments. |
| Microbial Fermentation Convergence | Non-palm supply lines bypass Malaysian crude palm oil volatility for clean-label preservation systems. |
| Direct Sourcing Relationships | Frame contracts with industrial bakers disintermediate distributor tiers and capture documentary traceability value. |
Study Parameters
Independent corroboration across molecular distillation plant managers, procurement leads at German industrial bakeries, pharmaceutical excipient regulatory affairs directors, and Southeast Asian palm oil trading desks underwrites the qualitative findings. Secondary validation draws from EFSA food additive reauthorization documentation, SAMR GB standard filings, customs trade data for glycerol ester flows, and SEC disclosures from integrated agribusiness conglomerates. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Rate-of-change decomposition separates feedstock price transmission, regulatory compliance cost inflation, and substitution elasticity across the projection horizon. Segmentation dimensions include product type (glycerol monostearate, glycerol monolaurate, glycerol monooleate), application grade (food-grade, pharmaceutical-grade, cosmetic-grade), and end-user procurement sophistication. CAGRs derive from elasticity-adjusted volume projections and price trajectory assumptions anchored to crude palm oil futures curves and enzymatic process cost learning rates.
Several conditions sit outside the modeled scope, including abrupt EFSA safety reclassification of distilled monoglycerides, Indonesian export duty regime shifts, and breakthrough lipase catalyst cost reductions. Forecasts reflect documented assumptions about regulatory timelines and feedstock supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Coconut Fatty Acids Market
Food Additives and Ingredients
Fruit Ripening Agents Market
Food Additives and Ingredients
Ammonium Chloride Food Grade Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Africa Food Enzymes Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Europe Food Enzymes Market
Food Additives and Ingredients
Japan Food Preservatives Market
Food Additives and Ingredients
Germany Food Enzymes Market
Food Additives and Ingredients
Hydrocolloid Carrier Market
Food Additives and Ingredients
North America Microencapsulation Market
Food Additives and Ingredients
Noodles Preservatives Market
Food Additives and Ingredients
Brazil Food Additives Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
South America Anti Caking Market
Food Additives and Ingredients
Nanoencapsulated Food Additives Market