
 China Food Emulsifiers Market | 2026-2036
China Food Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
China Food Emulsifiers Market Outlook
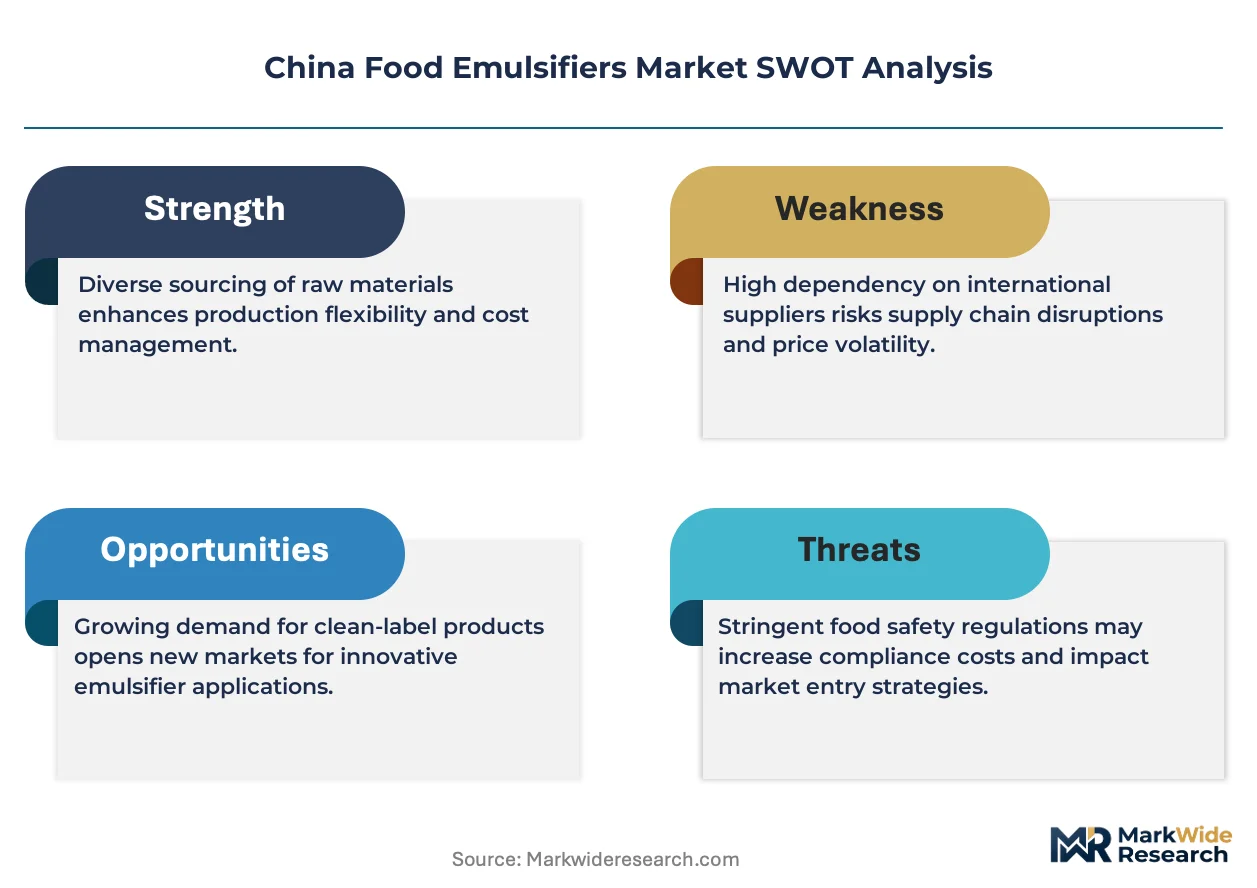
Asset-light leasing arrangements for emulsifier blending equipment is fragmenting competitive barriers across China's food ingredient sector. Cargill, Incorporated leverages its integrated oilseed processing network to secure lecithin supply advantages. Henan Eastar Chem & Tech Co Ltd anchors regional distribution through proximity to central China's wheat milling belt. BASF SE competes on synthetic emulsifier purity grades that meet stringent export specifications.
Food emulsifiers are surface-active compounds, typically spanning HLB values from 3 to 16, that reduce interfacial tension between immiscible phases such as oil and water in processed foods. Lecithin dominates volume flows due to cost positioning and clean-label alignment, while monoglycerides and diglycerides capture margin pools in premium bakery applications requiring extended shelf stability. Sorbitan esters occupy niche but high-value territory in confectionery fat crystallization control.
SAMR enforces GB 2760 food additive usage limits that directly constrain emulsifier dosage levels in sauces and beverages. The country's dual carbon goals from MEE are pressuring manufacturers toward enzymatic esterification routes with lower thermal energy profiles. BIS-referenced import testing protocols for lecithin create compliance checkpoints for foreign suppliers. Stakeholders must weigh backward integration into phospholipid extraction against specialist procurement from established refiners as formulation complexity escalates.
Market Dynamics
China's food emulsifier sector is compressing around dual carbon compliance timelines and enzymatic process conversion, as MEE energy-intensity benchmarks force manufacturers to retire thermal esterification assets ahead of depreciation cycles.
Growth Catalysts
- GB 2760 reformulation mandates:SAMR tightening of additive dosage limits in sauces and beverages compels processors to source higher-purity emulsifier grades, expanding technical service contracts.
- Bakery chain consolidation:National expansion of centralized dough production facilities concentrates procurement volumes with suppliers offering integrated shelf-life solutions.
- Instant noodle premiumization:Texture innovation in high-end noodle segments pulls specialized monoglyceride blends for oil retention and mouthfeel engineering.
Market Restraints
- Soybean lecithin input volatility:Crush margin compression at oilseed processors transmits directly to phospholipid raw material pricing, squeezing blender margins.
- Jiangsu-Shandong supply concentration:Coastal infrastructure clustering creates single-region exposure to port logistics disruptions and environmental compliance shutdowns.
- Enzymatic route capex barriers:Lipase-based esterification requires stainless-steel bioreactor investment that mid-scale compounders cannot amortize against batch volumes.
Strategic Opportunities
- Central China wheat belt proximity:Henan and Hubei flour milling expansion creates geographic white space for emulsifier blending facilities with 24-hour delivery radius.
- Clean-label lecithin certification:Non-GMO and organic phospholipid segments command price premiums in infant formula and clinical nutrition channels.
- Carbon accounting integration:Dual carbon goals from MEE incentivize suppliers offering verified Scope 3 emission reductions to multinational food manufacturers.
Industry Challenges
- Biocatalysis talent scarcity:Enzyme engineering and fermentation process control expertise concentrates at agricultural universities, constraining plant-level technical staffing.
- GB standard transition timelines:SAMR notification-comment periods for revised food additive specifications compress reformulation windows for legacy product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Food Emulsifiers Market |
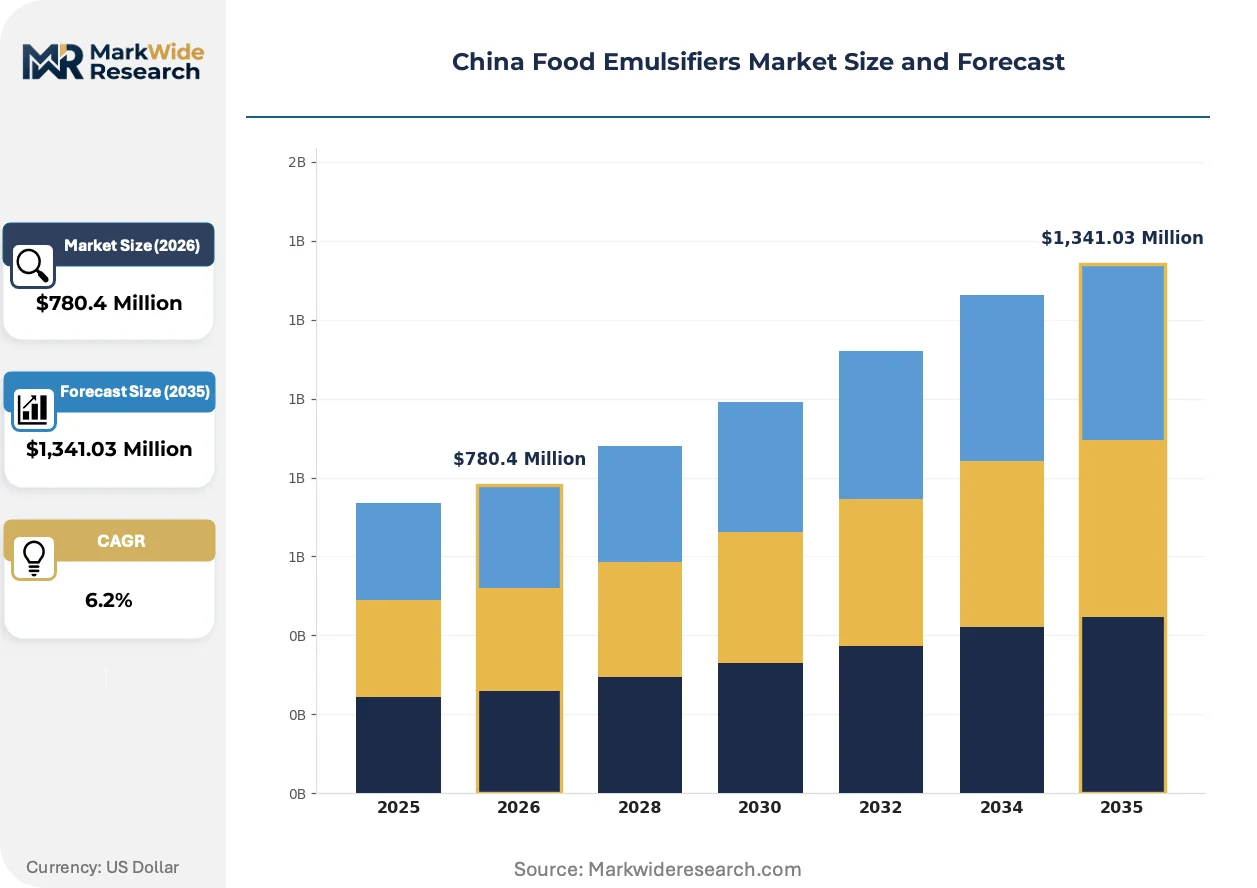
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,341.03 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbitan Esters, Lecithin, Monoglycerides, Diglycerides End User: Bakery, Dairy, Snack Foods, Dressings Application: Food Processing, Confectionery, Sauces, Beverages Form: Liquid, Powder, Granular, Semi-solid |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, DuPont de Nemours, Inc, Kerry Group plc, Corbion NV, BASF SE, Palsgaard A/S, Henan Eastar Chem & Tech Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Food Emulsifiers Market Strategic Shifts
Process chemistry and procurement architecture are diverging from conventional thermal routes, with enzymatic platforms and equipment-leasing models fragmenting established competitive barriers.
Enzyme-catalyzed esterification is hybridizing traditional emulsifier manufacturing by substituting lipase biocatalysts for high-temperature processing. Bakery ingredient divisions at major food manufacturers are piloting these routes for monoglyceride production to meet internal carbon reduction targets. The technology is hybridizing capital allocation patterns, as asset-light tolling arrangements displace in-house reactor investment for mid-scale compounders.
MEE dual carbon enforcement is tightening thermal process permits for emulsifier plants in Shandong and Jiangsu provinces. Manufacturers face retrofit deadlines or production caps that favor greenfield enzymatic facilities with lower emission profiles. Coastal processors with existing carbon-intensive assets are responding by contracting toll manufacturing to inland biotech specialists with certified low-carbon routes.
Equipment leasing is displacing ownership models for emulsifier blending and spray-drying assets. Instant noodle manufacturers and regional bakery chains are adopting pay-per-batch arrangements to avoid balance-sheet loading. This shift is most visible in Jiangsu, where third-party toll operators aggregate demand from multiple mid-sized processors to achieve enzyme-route scale economics.
China Food Emulsifiers Market Segmentation
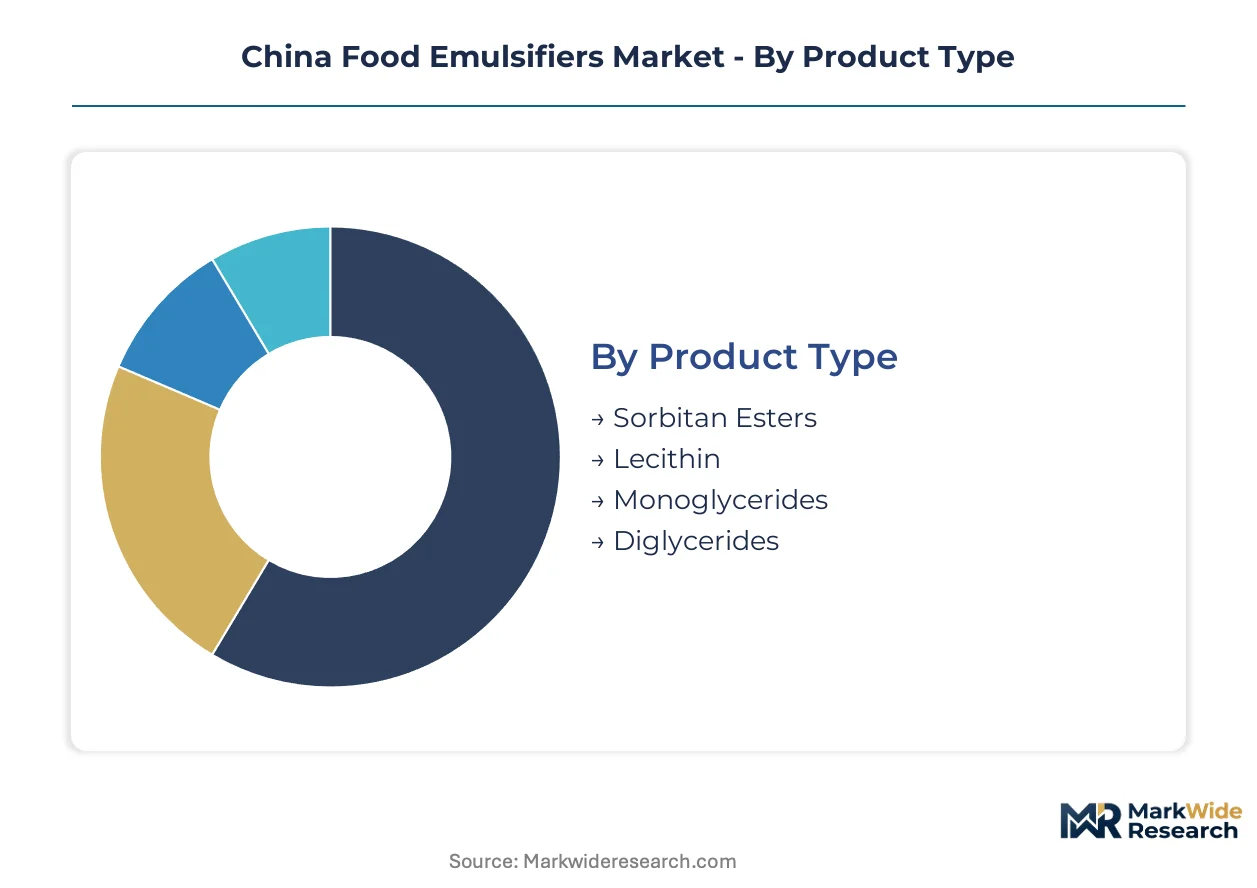
Emulsifier procurement patterns in China diverge sharply across product chemistry, end-use processing intensity, and physical form requirements. SAMR dosage regulations and MEE carbon enforcement reshape how manufacturers prioritize segment exposure.
Product Type:
Cost tier positioning determines raw material sourcing strategies and margin capture across phospholipid and synthetic routes.
- Lecithin:Phospholipid mixtures extracted from soybean or sunflower oilseeds dominate volume flows through cost positioning and clean-label alignment. Jiangsu and Shandong coastal processors concentrate procurement for instant noodle oil retention and chocolate viscosity control, though soybean input volatility transmits directly to blender margins.
- Monoglycerides:Single fatty acid esters of glycerol command premium positioning in extended-shelf-life bakery applications. Henan flour milling belt expansion pulls specialized distilled grades for dough conditioning, with enzymatic esterification routes gaining traction under MEE dual carbon timelines.
- Diglycerides:Partial glycerol esters function as co-emulsifiers in margarine and spread formulations.
- Sorbitan Esters:Sorbitol-derived surfactants occupy high-value niches in confectionery fat crystallization control.
Lecithin commands the established base. The steepest expansion runs through monoglycerides as bakery chain consolidation accelerates.
End User:
Application maturity and formulation complexity separate volume-driven commodity buyers from technical service-dependent processors.
- Bakery:Centralized dough production facilities at national chains concentrate procurement with suppliers offering integrated shelf-life solutions. GB 2760 reformulation mandates compel sourcing of higher-purity emulsifier grades with expanded technical service contracts.
- Dairy:UHT milk and recombined cream applications demand HLB-balanced systems for fat globule stabilization. SAMR tightening of additive dosage limits in flavored milk products constrains formulation flexibility.
- Snack Foods:Extruded and fried product segments utilize emulsifiers for oil uptake control and texture modification.
- Dressings:Mayonnaise and sauce manufacturers navigate strict emulsifier dosage ceilings under revised GB standards.
Bakery anchors volume concentration. Dairy offers the most rapid climb as premium UHT and recombined cream segments expand.
Application:
Processing temperature and shear requirements dictate emulsifier HLB selection and physical form preferences.
- Food Processing:Industrial-scale meat and plant-protein systems utilize emulsifiers for fat binding and water retention. Shandong protein processing clusters drive regional demand concentration.
- Confectionery:Chocolate and coating applications require precise fat polymorphism control. Sorbitan esters and lecithin blends dominate this technically demanding segment.
- Sauces:Cold-process emulsions face GB 2760 dosage constraints that favor high-efficiency emulsifier grades.
- Beverages:Clouding agents and flavor emulsions in soft drinks operate under strict SAMR usage limits.
Food processing holds the volume base. Confectionery delivers the sharpest gain as premium chocolate consumption rises.
Form:
Logistics economics and dosing precision requirements separate bulk liquid handlers from specialized dry blenders.
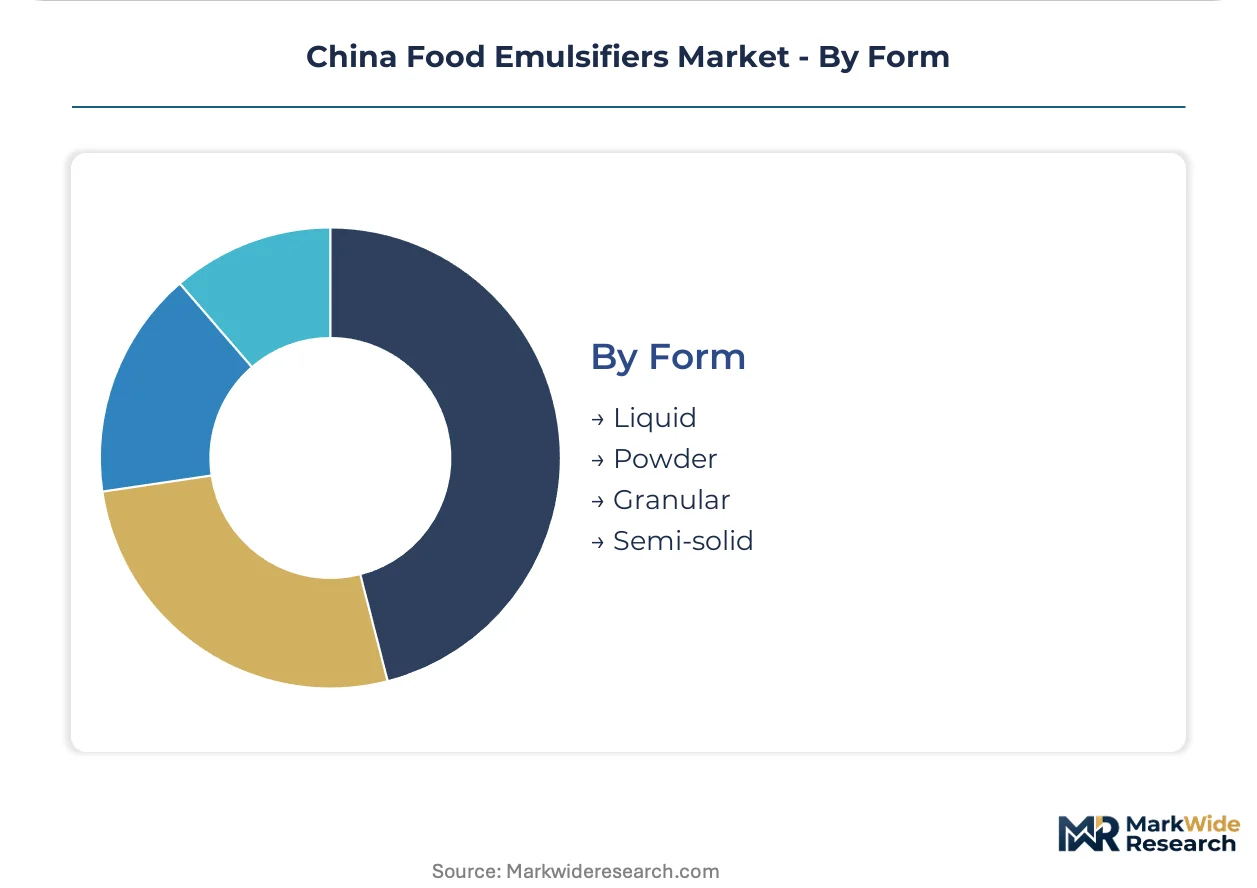
- Liquid:Fluid lecithin and monoglyceride suspensions dominate high-volume bakery and margarine channels. Coastal manufacturing zones favor tanker delivery for cost efficiency.
- Powder:Spray-dried emulsifiers enable precise dry-blending in instant noodle seasoning and bakery premixes. Asset-light tolling arrangements proliferate in Jiangsu for mid-scale processors.
- Granular:Free-flowing agglomerated forms suit automated dosing in large-scale confectionery operations.
- Semi-solid:Plastic-range products target artisan bakery and specialty margarine applications.
Liquid forms retain the dominant share. Powder formats are climbing fastest as premix and toll-manufacturing adoption spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB 2760 reformulation mandates and MEE dual carbon enforcement are redistributing emulsifier procurement across China's manufacturing belt. Provincial environmental compliance timelines now determine where new blending capacity can locate.
Jiangsu Province
Instant noodle manufacturers and confectionery processors drive concentrated demand along the Yangtze River Delta. MEE thermal process permits are tightening fastest here, pushing coastal plants toward enzymatic retrofit or tolling arrangements. Nanjing and Suzhou host the densest clusters of third-party blending facilities serving bakery chains.
Shandong Province
Oilseed crushing infrastructure anchors lecithin supply for margarine and chocolate applications. GB 2760 dosage ceilings for sauces directly constrain Qingdao-based dressing manufacturers. Yantai and Weihai protein processing clusters generate specialized demand for meat-system emulsifiers.
Henan Province
Central China's wheat milling expansion creates geographic white space for 24-hour delivery radius coverage. Zhengzhou flour milling belt growth pulls monoglyceride procurement away from coastal suppliers. SAMR additive compliance costs favor regional blending facilities over long-haul liquid tanker logistics.
Guangdong Province
Pearl River Delta beverage and dairy processors navigate strict SAMR usage limits for clouding agents and UHT applications. Shenzhen and Guangzhou confectionery operations demand high-purity sorbitan esters for premium chocolate fat control. MEE carbon accounting favors suppliers with verified Scope 3 documentation.
Sichuan-Chongqing Region
Western China's snack food and hotpot seasoning sectors represent underpenetrated demand for oil-uptake control emulsifiers. Chongqing's instant noodle innovation hubs test specialized monoglyceride blends for texture engineering. Provincial environmental enforcement lags coastal timelines, preserving thermal process economics temporarily.
China Food Emulsifiers Market Competitive Environment
On the supply side, the industry is compressing around dual carbon compliance capabilities and enzymatic process access. Mid-scale compounders face displacement as asset-light tolling models fragment traditional equipment ownership barriers. Three archetypes dominate: integrated oilseed processors with captive lecithin streams, multinational specialists on synthetic purity grades, and regional distributors anchoring proximity to flour milling belts. Competitive moves concentrate on enzymatic route licensing partnerships and carbon-verified supply chain certification.
Within the multinational tier, Cargill, Incorporated and BASF SE exemplify divergent sourcing strategies—one leveraging integrated oilseed networks, the other competing on synthetic emulsifier specifications. Henan Eastar Chem & Tech Co Ltd anchors the regional specialist archetype through central China distribution proximity. These three represent the spectrum from global scale to geographic specialization now reshaping procurement relationships.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| DuPont de Nemours, Inc |
| Kerry Group plc |
| Corbion NV |
| BASF SE |
| Palsgaard A/S |
| Henan Eastar Chem & Tech Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Jiangsu and Shandong enzymatic blending facilities is compressing tolling rates and forcing coastal suppliers into aggressive contract renegotiations with instant noodle manufacturers. This utilization squeeze transmits directly into pricing power erosion for mid-scale compounders while concentrating margin capture with integrated oilseed processors holding captive lecithin streams.
Pricing Analysis
Certification level creates the primary spread across China's emulsifier procurement landscape. SAMR GB 2760 compliance tiers separate premium enzymatic grades from legacy thermal products, with clean-label organic and non-GMO lecithin commanding substantial premiums in infant formula channels. Pricing pressure stems from soybean crush margin volatility transmitting through phospholipid raw material costs. National bakery chains exhibit lowest price sensitivity due to shelf-life solution bundling, while regional dressing manufacturers face acute margin compression under dosage ceiling constraints.
Supply Chain Analysis
Tariff exposure between Argentina and China dominates soybean lecithin input volatility, with crush margin compression at oilseed processors transmitting directly to blender procurement costs. Supply concentrates in Jiangsu and Shandong coastal zones, with Henan emerging as a secondary hub for central China flour milling proximity. Raw material dependencies center on soybean and sunflower phospholipids, glycerol feedstocks, and lipase biocatalysts. Single-region exposure to MEE environmental compliance shutdowns represents the structural vulnerability. Distribution runs through third-party toll operators aggregating mid-scale processor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated national bakery chains and instant noodle manufacturers, whose centralized procurement volumes fragment supplier pricing leverage. This concentration compels emulsifier vendors to embed technical service capabilities and carbon-verified supply chains into contract structures.
For Market Incumbents: Entrench enzymatic process capabilities through licensing partnerships with agricultural universities, securing biocatalysis talent pipelines before regional competitors. Invest in Scope 3 carbon accounting certification to defend contract renewals against multinational food manufacturers' dual carbon procurement mandates. Expand tolling capacity in Henan to intercept wheat belt demand migrating from coastal suppliers.
For New Entrants and Emerging Players: Establish a beachhead in Sichuan-Chongqing snack food emulsifiers, where provincial environmental enforcement lags coastal timelines and thermal process economics remain viable. Target hotpot seasoning manufacturers with specialized oil-uptake control formulations. Pursue asset-light equipment leasing arrangements to bypass enzymatic bioreactor capex barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across enzymatic toll-manufacturing sub-segments, favoring acquisition of regional blending facilities with certified low-carbon routes and established SAMR compliance track records. Monitor MEE permit issuance velocity in Jiangsu as the inflection signal for coastal capacity rationalization timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Licensing | Lipase biocatalyst partnerships with agricultural universities secure biocatalysis talent pipelines for MEE compliance. |
| Backward Integration into Phospholipid Extraction | Captive soybean lecithin supply insulates margins from crush volatility at oilseed processors. |
| Carbon-Verified Supply Chain Certification | Scope 3 documentation meets multinational food manufacturers' dual carbon procurement requirements. |
| Regional Blending Facility Expansion | Henan proximity to central China wheat milling belt intercepts demand migrating from coastal suppliers. |
| Asset-Light Tolling Arrangements | Pay-per-batch models aggregate mid-scale processor demand to achieve enzymatic route scale economics. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across China's food emulsifier value chain. Primary interviews captured perspectives from bakery chain procurement directors, instant noodle manufacturer R&D heads, oilseed processing plant managers, and SAMR regulatory compliance officers. Secondary validation drew from customs trade data, GB standards documentation, MEE environmental permit filings, and SEC disclosures from multinational ingredient suppliers. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Calibration anchored on historical consumption patterns and announced capacity expansions without year-specific assumptions. Segmentation dimensions spanned product chemistry, end-use processing intensity, physical form requirements, and provincial regulatory cluster. CAGRs derived from trend extrapolation moderated by enforcement timeline uncertainty for MEE dual carbon targets. Forecast inputs incorporated enzymatic route adoption curves and bakery chain consolidation trajectories.
Sensitivities concentrate around MEE permit issuance velocity, SAMR GB 2760 reformulation timelines, and soybean crush margin volatility. Forecasts reflect documented assumptions on technology substitution rates and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Africa Food Additives Market
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
Fruit and Vegetable Processing Enzymes Market
Food Additives and Ingredients
Food Preservatives Market
Food Additives and Ingredients
Transglutaminase Market
Food Additives and Ingredients
Acetylated Distarch Phosphate Market
Food Additives and Ingredients
Pyranose Oxidase Market
Food Additives and Ingredients
South America Food Enzymes Market
Food Additives and Ingredients
Nutraceutical Excipients Market
Food Additives and Ingredients
Trans Fatty Acids Market
Food Additives and Ingredients
Lake Food Colors Market
Food Additives and Ingredients
Canada Food Colorants Market
Food Additives and Ingredients
Egg Wash Substitute Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
North America Food Anti Caking Agents Market
Food Additives and Ingredients
Bakery Release Agents Market