
 Erythorbic Acid Market | 2026-2036
Erythorbic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Erythorbic Acid Market Analytics
The gap between pharmaceutical-grade erythorbic acid and commodity food-grade material is broadening as purity specifications diverge. DSM leverages its fermentation technology leadership to command premium positions in regulated pharmaceutical channels. Huayuan Bioengineering anchors China's export-oriented supply base through integrated starch-to-acid production. Foodchem competes aggressively on standardized food-grade volumes across Southeast Asian markets.
Erythorbic acid, the stereoisomer of ascorbic acid produced by microbial fermentation of glucose or sorbitol, functions primarily as an oxygen scavenger and reducing agent in food systems, with antioxidant efficacy at lower dosage levels than its vitamin C counterpart. The powdered form dominates current volume given its ease of dispersion in meat curing and beverage applications, while pharmaceutical-grade crystals capture disproportionate margin pools due to sterility and impurity thresholds. Food preservation anchors absolute demand, though cosmetic applications for oxidative stability in emulsions represent the fastest-expanding segment as formulators seek alternatives to BHA and BHT under tightening regulatory scrutiny.
The FDA governs erythorbic acid under GRAS status for food applications, while the European Food Safety Authority enforces purity benchmarks through Regulation 231/2012 that restrict residual solvent levels. China's National Health Commission maintains separate additive standards that influence export qualification protocols for domestic producers. Stakeholders must monitor evolving EFSA re-evaluations of antioxidant safety profiles and corresponding reformulation timelines across European processed meat categories.
Market Dynamics
Fermentation capacity concentration in Shandong province and diverging purity specifications between food and pharmaceutical grades are compressing margin structures and forcing specialization strategies across the value chain.
Growth Catalysts
- GB Standards Alignment:China's National Health Commission additive standards for erythorbic acid are accelerating export qualification investments among domestic producers seeking overseas market access.
- Processed Meat Preservation:Curing applications across Southeast Asian meat processing are absorbing rising erythorbic acid volumes as manufacturers phase out nitrite-heavy formulations under consumer pressure.
- Fermentation Yield Improvements:Microbial strain optimization and glucose-to-acid conversion efficiency gains are lowering unit production costs at integrated starch-based facilities.
Market Restraints
- Corn Starch Price Volatility:Feedstock cost swings tied to agricultural commodity cycles constrain margin predictability for fermentation-based producers lacking upstream grain processing control.
- Shandong Supply Concentration:Geographic clustering of fermentation capacity in a single Chinese province creates systemic disruption exposure from localized environmental enforcement actions or energy rationing.
- Ascorbic Acid Substitution:Vitamin C price competitiveness in low-specification food applications limits erythorbic acid penetration where label differentiation carries minimal commercial value.
Strategic Opportunities
- Cosmetic Antioxidant Formulations:BHA and BHT displacement in European Union personal care products under EFSA re-evaluation timelines is opening specification-grade demand for oxidative stability agents.
- Pharmaceutical-Grade Crystallization:Sterility and impurity threshold compliance for injectable applications commands pricing multiples that reward dedicated production line investments.
- Carbon-Neutral Fermentation:Dual carbon goals implementation in China is incentivizing energy-efficient bioprocess retrofits that qualify producers for preferential export financing and green procurement channels.
Industry Challenges
- Pharmaceutical GMP Certification Timelines:Sterile manufacturing validation and impurity profiling documentation requirements extend qualification cycles for producers crossing from food-grade into regulated pharmaceutical supply chains.
- Residual Solvent Compliance:EFSA Regulation 231/2012 purity benchmarks and evolving maximum residue limits demand continuous analytical capability upgrades at export-oriented facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Erythorbic Acid Market |
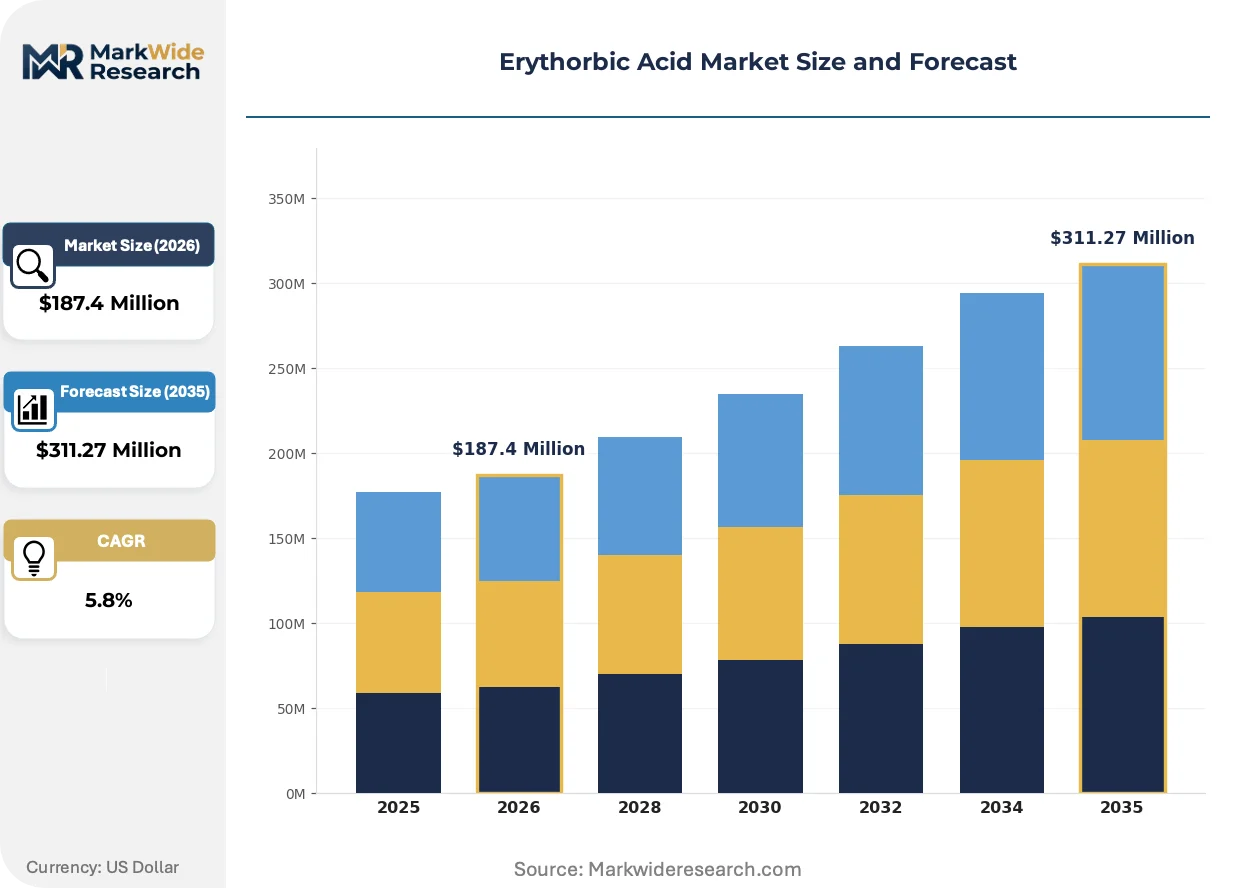
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered, Granules, Crystals, Tablets Application: Food Preservation, Cosmetics, Pharmaceuticals, Agriculture End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Agricultural Sector Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | DSM, Foodchem, Huayuan Bioengineering, HuameiHuli Biochem, Morimura Bros, American International Foods, IFPC, Archer Daniels Midland, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Erythorbic Acid Market Evolving Landscape
Continuous fermentation monitoring and downstream crystallization control systems are compressing batch-to-batch variability while regulatory re-evaluations of legacy antioxidants are rewriting formulation specifications across end-use categories.
Continuous glucose monitoring integrated with fermentation bioreactor control systems is rewriting process economics for erythorbic acid manufacturers. Real-time metabolite tracking enables dynamic nutrient feeding that lifts conversion yields above batch benchmarks. Pharmaceutical-grade producers in regulated channels are capturing the margin premiums this precision enables.
EFSA's scheduled re-evaluation of BHA, BHT, and propyl gallate safety profiles is accelerating antioxidant substitution timelines across European processed meat categories. Reformulation deadlines are compressing procurement cycles as manufacturers pre-empt regulatory restrictions. Clean-label positioning is displacing traditional synthetic preservation claims in retail-facing product lines.
Direct contracting between Shandong fermentation clusters and Southeast Asian meat processors is shortening traditional distributor channels. Volume commitments with technical service attachments are replacing spot-market transactions for standardized food-grade material. Indonesian and Vietnamese curing facilities are consolidating supplier relationships to secure qualification documentation for export-bound processed meat shipments.
Erythorbic Acid Market Segmentation
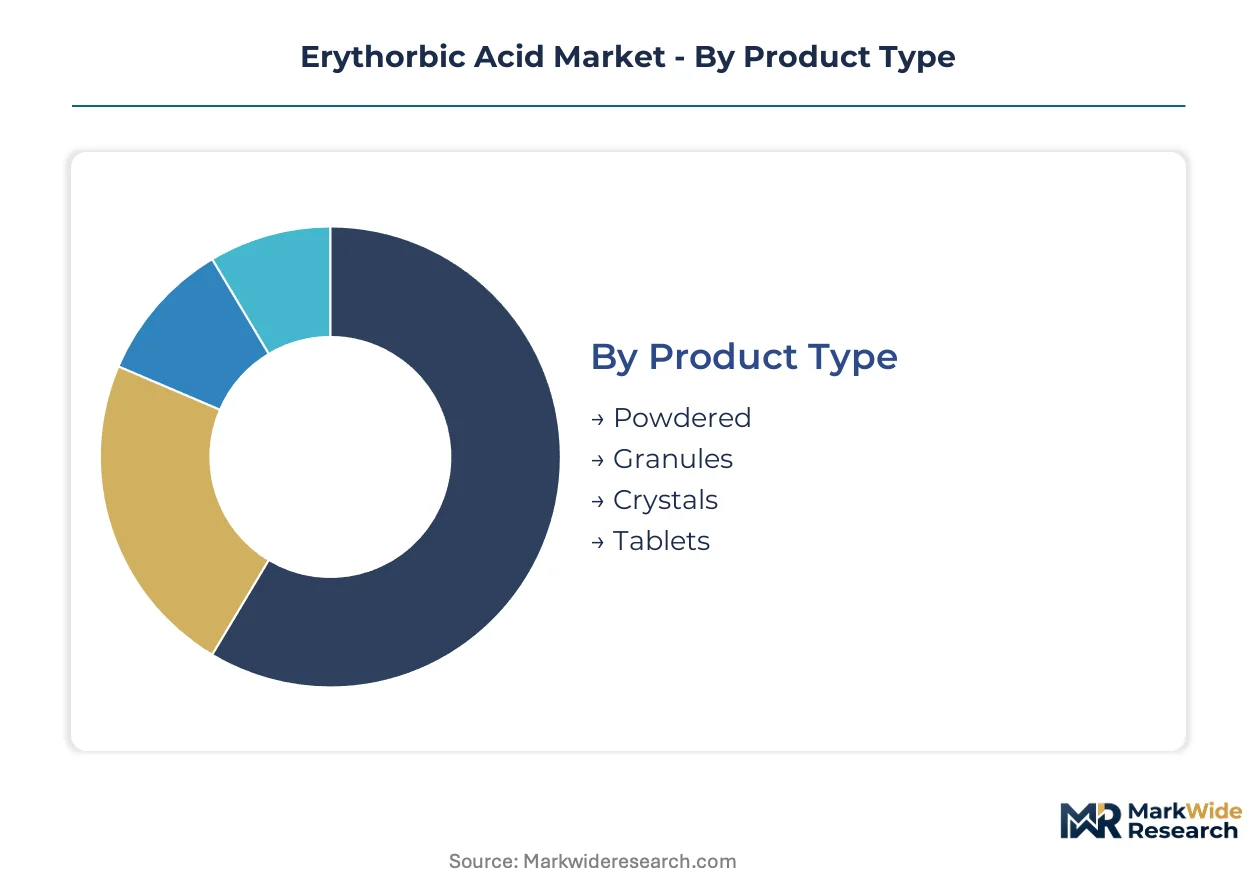
Erythorbic acid's value chain fragments across purity grades and formulation formats that dictate manufacturing investment thresholds. Segmentation reveals where fermentation capacity earns sustainable returns versus commodity pressure.
Product Type:
Capital intensity escalates sharply from bulk powder production to sterile crystallization lines requiring dedicated GMP facilities.
- Powdered:Spray-dried material dominates meat curing and beverage applications where rapid dispersion matters. Southeast Asian processors absorb the bulk of standardized food-grade volumes as nitrite reduction accelerates.
- Crystals:Pharmaceutical-grade crystallization demands sterile manufacturing validation and impurity profiling documentation. Injectable applications command pricing multiples that reward dedicated production line investments.
- Granules:Intermediate particle size suits controlled-release formulations in agricultural applications.
- Tablets:Direct compression grades serve niche dietary supplement channels requiring precise dosing.
Most installed capacity flows through Powdered. Expansion is steepest in Crystals.
Application:
Margin profiles diverge between regulated pharmaceutical channels and price-sensitive food preservation bulk demand.
- Food Preservation:Oxygen scavenging in processed meat curing anchors absolute volume. Chinese Shandong fermentation clusters supply standardized material direct to Indonesian and Vietnamese curing facilities.
- Cosmetics:Oxidative stability in emulsions is gaining share fastest as formulators displace BHA and BHT under EFSA re-evaluation timelines.
- Pharmaceuticals:Reducing agent applications in injectable formulations require sterility compliance that filters out commodity producers.
- Agriculture:Crop treatment formulations absorb technical-grade material with lower purity thresholds.
Food Preservation retains the largest revenue pool. Cosmetics shows the steepest margin expansion trajectory.
End User:
Procurement sophistication separates pharmaceutical qualification systems from spot-market food-grade purchasing.
- Food Manufacturers:Processed meat processors across Southeast Asia consolidate supplier relationships to secure export documentation.
- Cosmetic Companies:European Union formulators drive specification-grade demand for clean-label antioxidant positioning.
- Pharmaceutical Firms:Injectable drug producers enforce sterility and impurity thresholds that extend supplier validation cycles.
- Agricultural Sector:Fertilizer and crop protection blenders purchase technical-grade material on volume contracts.
Food Manufacturers absorb the highest tonnage. Pharmaceutical Firms generate the highest per-kilogram returns.
Distribution Channel:
Channel economics shift as direct contracting shortens traditional distributor layers for standardized material.
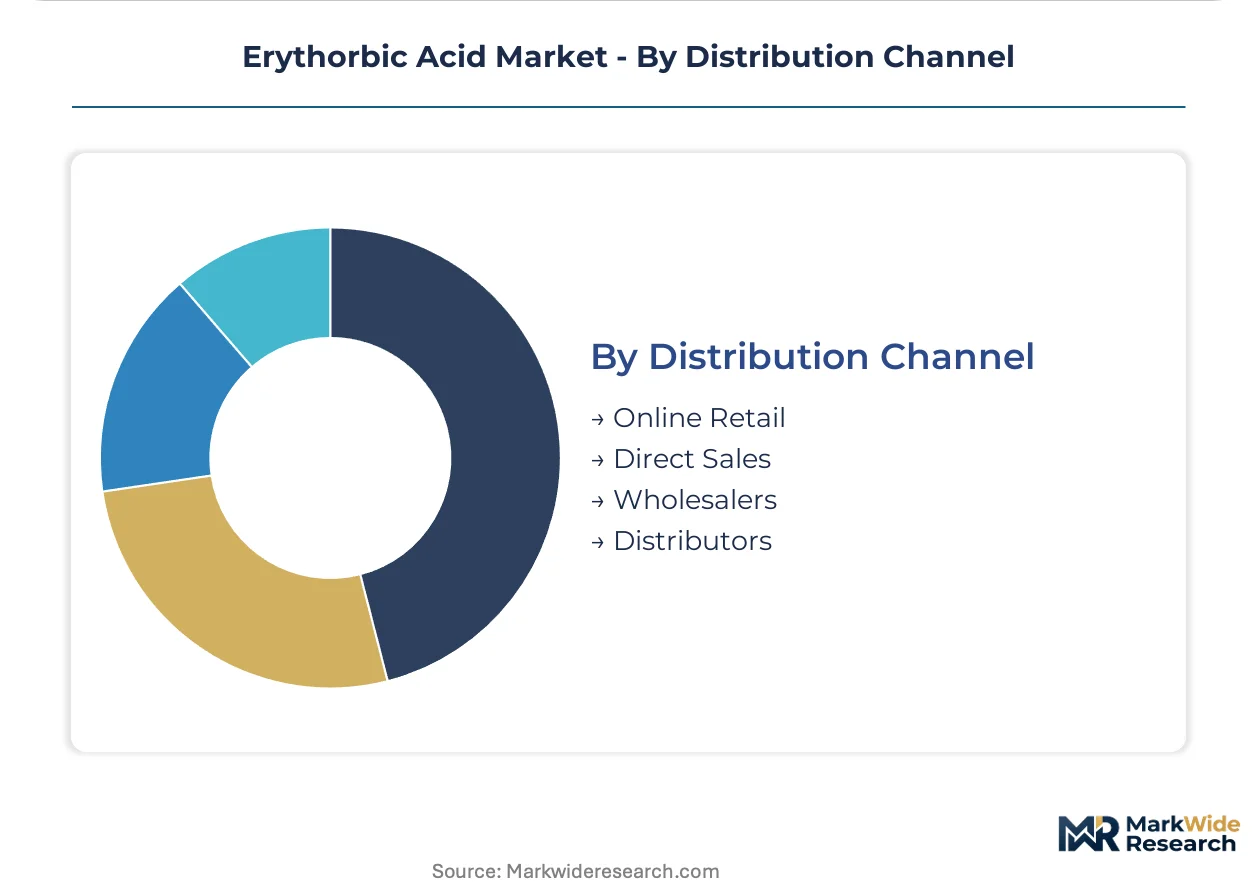
- Direct Sales:Volume commitments with technical service attachments replace spot-market transactions for Shandong-to-Southeast Asia supply.
- Distributors:Regional chemical distributors maintain inventory positions for qualified food-grade material serving mid-tier processors.
- Wholesalers:Bulk handlers aggregate agricultural-grade shipments for crop treatment blenders.
- Online Retail:E-commerce platforms serve small-scale cosmetic formulators and research laboratories requiring gram-scale quantities.
Direct Sales captures the largest value flow. Online Retail expands most quickly for specialty-grade access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Shandong province concentrates fermentation capacity for erythorbic acid, while the United States maintains pharmaceutical-grade demand through FDA-regulated channels. European formulators drive substitution trends as EFSA re-evaluates legacy antioxidants. Southeast Asian meat processors absorb standardized food-grade volumes through direct contracting.
China
Shandong province hosts the dominant fermentation clusters converting starch to erythorbic acid through microbial processing. The National Health Commission's GB standards for food additives shape export qualification protocols for domestic producers. Qingdao and Jinan manufacturing bases supply standardized material direct to Indonesian and Vietnamese curing facilities under volume commitments.
United States
FDA GRAS status governs food preservation applications while pharmaceutical channels enforce sterility thresholds for injectable formulations. The agency's purity benchmarks filter out commodity producers seeking regulated supply chain entry. New Jersey and Illinois distribution hubs consolidate qualified material for meat processing and cosmetic formulators.
Germany
EFSA Regulation 231/2012 residual solvent limits constrain import qualification for Chinese-manufactured erythorbic acid. The agency's scheduled re-evaluations of BHA and BHT accelerate antioxidant substitution timelines across processed meat categories. Hamburg chemical distributors maintain inventory positions for specification-grade material serving EU cosmetic manufacturers.
Indonesia
Processed meat curing facilities absorb rising erythorbic acid volumes as manufacturers phase out nitrite-heavy formulations under consumer pressure. Direct contracting with Shandong fermentation clusters shortens traditional distributor channels for export-bound shipments. Jakarta and Surabaya processing plants consolidate supplier relationships to secure documentation for EU-bound product lines.
Vietnam
Meat processors leverage erythorbic acid oxygen-scavenging properties in curing applications for domestic consumption and export markets. Ho Chi Minh City and Hanoi facilities source standardized food-grade material through technical service attachments replacing spot-market transactions. Procurement sophistication is rising as manufacturers seek qualification documentation for regulated destination markets.
Erythorbic Acid Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade crystallization, while commodity food-grade producers compete on fermentation yield and starch feedstock access. The vendor base stratifies across purity grades with sterile manufacturing validation separating regulated channels from bulk supply. Three archetypes dominate: integrated starch-to-acid fermentation specialists, pharmaceutical-grade crystallization houses, and regional food-grade distributors. Capacity expansion in Shandong and GMP certification investments represent the dominant competitive moves.
Among fermentation-based producers, DSM and Huayuan Bioengineering occupy positions reflecting divergent specialization strategies. DSM exemplifies the pharmaceutical-grade tier through regulated channel access. Huayuan Bioengineering anchors China's export-oriented supply base. Foodchem sits within the standardized food-grade distribution tier competing across Southeast Asian markets.
| Leading Market Players |
|---|
| DSM |
| Foodchem |
| Huayuan Bioengineering |
| HuameiHuli Biochem |
| Morimura Bros |
| American International Foods |
| IFPC |
| Archer Daniels Midland |
| Cargill |
| Others |
Value Network & Pricing Analysis
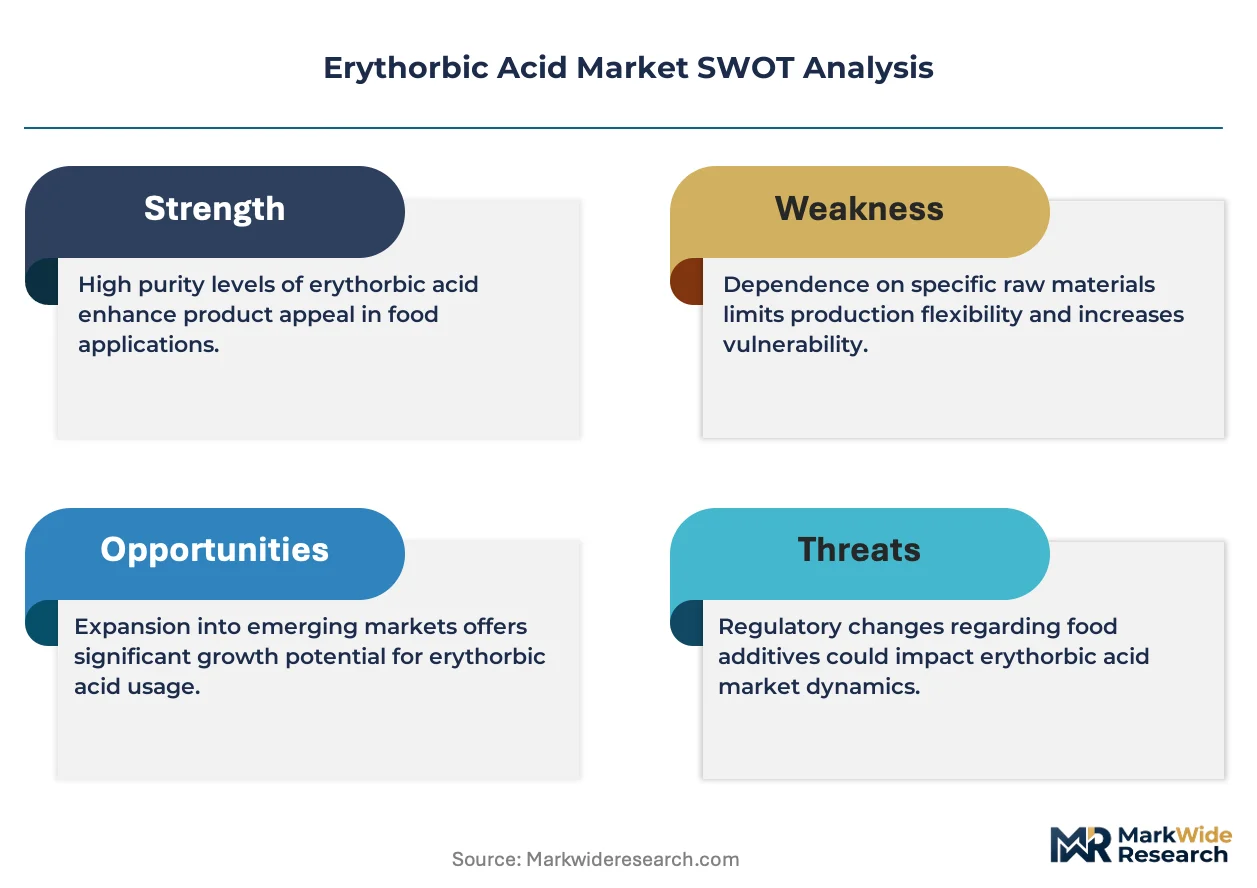
China's dual carbon goals implementation gates qualified supply and premium-tier pricing access for erythorbic acid producers, as energy-efficient bioprocess retrofits separate green-financing-eligible exporters from commodity suppliers locked into carbon-intensive fermentation.
Pricing Analysis
Capacity additions in Shandong province are reshaping price floors for standardized food-grade material while pharmaceutical-grade crystallization maintains insulation. Three-tier pricing structure across pharmaceutical, food-grade, and technical tiers reflects sterility certification and impurity profiling investments. Cost compression in food-grade powder runs through corn starch feedstock volatility and ascorbic acid substitution pressure. Southeast Asian meat processors show highest price sensitivity, while injectable drug producers accept premiums for GMP-validated supply.
Supply Chain Analysis
Direct-to-processor channels handle volume commitments from Shandong fermentation clusters to Indonesian and Vietnamese curing facilities. Geographic supply concentrates in China, with secondary fermentation capacity in Japan and distribution hubs in Germany and the United States. Raw material flows draw from corn starch processors, glucose refiners, and microbial strain suppliers. Single-province concentration creates systemic disruption exposure from environmental enforcement actions. Distribution runs through direct sales with technical service attachments for qualified material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Erythorbic acid offers margin expansion through fermentation yield improvements and pharmaceutical-grade tier shift, as real-time bioreactor control systems lower unit costs while sterility compliance commands pricing multiples.
For Market Incumbents: Deploy continuous fermentation monitoring systems to compress batch-to-batch variability and capture pharmaceutical-grade premiums. Defensive moves require GMP certification investments for injectable applications and backward integration into starch processing to hedge feedstock volatility. Ascorbic acid price competitiveness in low-specification food applications threatens commodity tier positioning. For New Entrants and Emerging Players: The premium-to-economy price-point gap in pharmaceutical-grade crystallization opens entry corridors for sterile manufacturing specialists. White-space targets include European cosmetic formulators displacing BHA and BHT under EFSA re-evaluation timelines, and carbon-neutral fermentation qualifications for green procurement channels. Go-to-market positioning should anchor on residual solvent compliance documentation for EU-bound shipments. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap fermentation specialists with GMP certification pathways because pharmaceutical-grade demand concentration rewards scale players with validated sterile lines. Long-term viability favors producers with dual food-pharma grade flexibility and upstream starch control. Watch EFSA re-evaluation implementation timelines as inflection indicators for antioxidant substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade GMP Certification | Sterile manufacturing validation unlocks injectable drug pricing multiples for qualified producers. |
| Backward Integration into Starch Processing | Captive corn supply hedges agricultural commodity cycles constraining fermentation margins. |
| Continuous Fermentation Monitoring Deployment | Real-time metabolite tracking lifts glucose-to-acid conversion yields above batch benchmarks. |
| Carbon-Neutral Bioprocess Retrofit | Dual carbon goals compliance qualifies producers for preferential export financing and green procurement. |
| Direct Contracting with Southeast Asian Processors | Volume commitments with technical service attachments replace spot-market distributor layers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation plant managers, procurement leads at meat processing facilities, cosmetic formulators, pharmaceutical quality directors, and Shandong-based export coordinators with secondary validation. Sources included Chinese customs export data, EFSA additive safety evaluations, FDA GRAS notifications, National Health Commission GB standards filings, and SEC disclosures from listed chemical producers. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Historical reference periods established baseline fermentation yields and pricing spreads across purity grades, with projections extending across the analysis window through segmented modeling. Dimensions included product type, application end-use, and regulatory qualification tier. CAGRs derived from weighted average of capacity expansion timelines, substitution elasticity estimates for antioxidant displacement, and pharmaceutical-grade demand ramp assumptions. Forecast inputs incorporated EFSA re-evaluation implementation schedules and China's dual carbon policy enforcement intensity.
Caveats apply where EFSA maximum residue limit revisions or Shandong environmental enforcement actions could materially shift the outlook. Forecasts reflect assumptions on fermentation yield improvement trajectories and pharmaceutical channel qualification success rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
Food Preservatives Market
Food Additives and Ingredients
Oleic Acid Market
Food Additives and Ingredients
Mediterranean Sourdough Starter Cultures Market
Food Additives and Ingredients
Italy Food Additives Market
Food Additives and Ingredients
Egypt Feed Additives Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Food Grade Glue Market
Food Additives and Ingredients
Brazil Food Acidulants Market
Food Additives and Ingredients
Ascorbyl Palmitate Market
Food Additives and Ingredients
Carob Bean Gum Market
Food Additives and Ingredients
Isodecanol Market
Food Additives and Ingredients
Egg Stabilizer Market
Food Additives and Ingredients
Global Food Grade Calcium Chloride Market
Food Additives and Ingredients
Food Clarifiers Market
Food Additives and Ingredients
Chymosine Market