
 Anti-Caking Agents Market | 2026-2036
Anti-Caking Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Caking Agents Market Analysis
A shift from single-source mineral supply contracts toward multi-source procurement with regional blending partners is realigning how food-grade anti-caking agents reach formulation houses. Solvay SA leverages its integrated soda ash operations to anchor sodium bicarbonate supply security for European processors. Evonik Industries AG specializes in precipitated silica technologies that differentiate its offerings for pharmaceutical tableting applications. Brenntag AG controls extensive distribution networks across North America, competing on logistics speed rather than manufacturing scale.
Anti-caking agents are hygroscopicity-modifying additives, typically composed of silicates, carbonates, or phosphates, that physically separate particles to prevent clumping under moisture exposure; food-grade silicon dioxide must achieve specific surface area thresholds measured in square meters per gram to meet flowability standards. The food industry application segment dominates volume demand due to widespread use in salt, sugar, and powdered beverage formulations where caking destroys consumer usability. Spray drying technology leads processing methods for heat-sensitive pharmaceutical and cosmetic grades, while granulation occupies the margin pool for high-purity mineral carbonates used in effervescent tablet manufacturing.
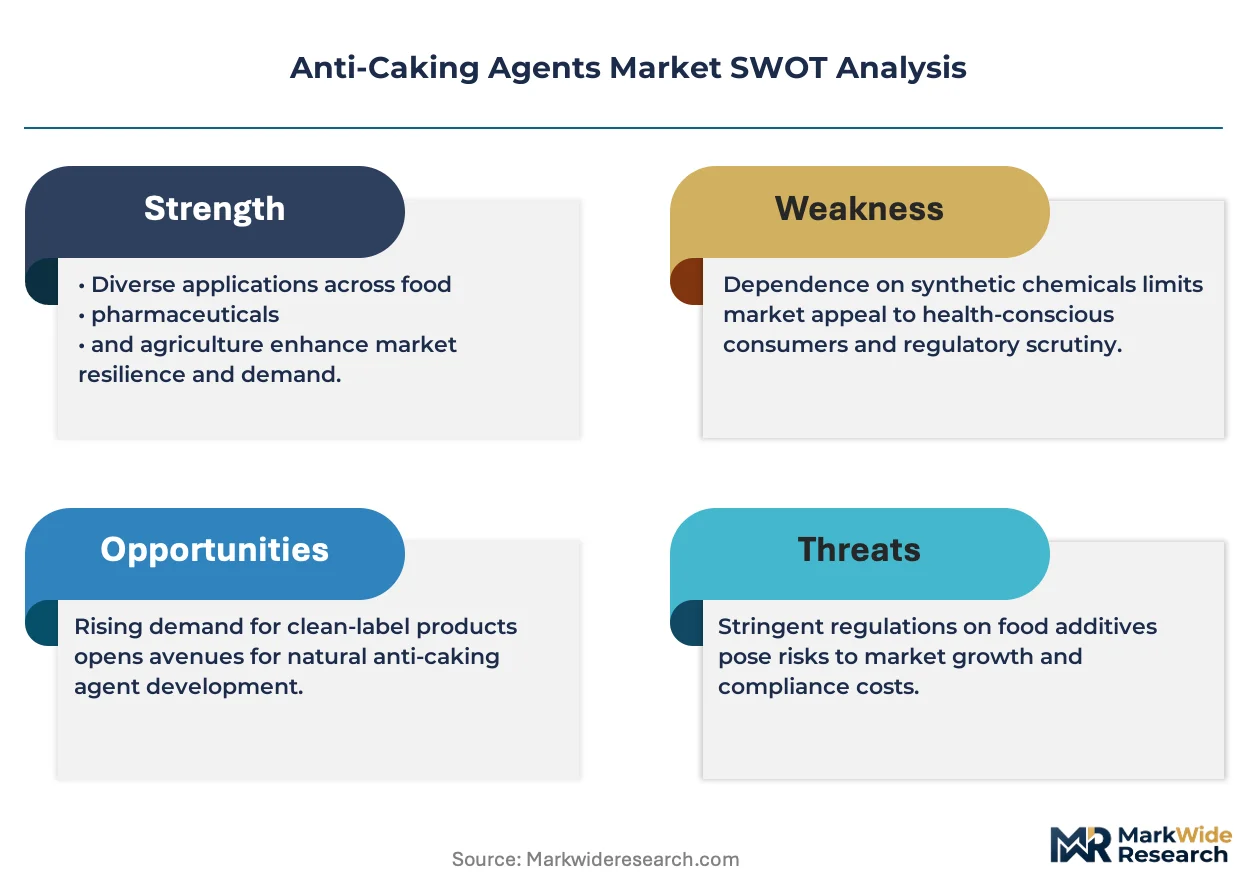
FDA food additive regulations and EU REACH restrictions on synthetic amorphous silica purity are forcing reformulation investments among suppliers seeking dual-continent market access. EFSA evaluations of calcium carbonate and magnesium carbonate food safety thresholds shape product development pipelines for European-labeled goods. Stakeholders must monitor evolving BIS standards in India and emerging GB food additive classifications in China, as these frameworks will determine which mineral grades gain access to the fastest-expanding processed food manufacturing bases.
Market Dynamics
Multi-source procurement strategies are restructuring supply relationships as processors abandon single-mineral contracts in favor of regional blending partnerships that reduce humidity-driven flowability risks.
Growth Catalysts
- REACH purity benchmarks:Tightened ECHA thresholds for synthetic amorphous silica are compelling reformulation investments that upgrade technical capabilities across European supply chains.
- Processed food manufacturing:Bakery and dairy clusters in Germany and France are expanding additive volumes to maintain salt, sugar, and powdered beverage usability under humid storage.
- Spray drying adoption:Pharmaceutical and cosmetic formulators are converting heat-sensitive grades to this processing method, expanding addressable applications beyond mineral carbonates.
Market Restraints
- Input cost volatility:Soda ash and sodium bicarbonate feedstock prices fluctuate with energy-intensive Solvay process economics, compressing margin stability for carbonate-grade suppliers.
- Supply concentration risk:Precipitated silica manufacturing clusters in Germany and Belgium create geographic chokepoints for pharmaceutical tableting grades.
- Regulatory friction:Divergent FDA food additive classifications and EU REACH substance evaluations force dual-certification investments for cross-Atlantic market access.
Strategic Opportunities
- Indian processing expansion:Emerging BIS standards for food-grade mineral additives create first-mover positioning as domestic processed food manufacturing scales.
- Effervescent tablet demand:High-purity magnesium carbonate applications in pharmaceutical manufacturing represent an underdeveloped specification tier.
- Logistics-speed competition:North American distributors can capture margin pools by compressing delivery timelines rather than competing on manufacturing scale.
Industry Challenges
- Surface area certification complexity:Food-grade silicon dioxide testing protocols require square-meters-per-gram precision that strains quality control infrastructure.
- Legacy formulation integration:Salt and sugar processors face technical friction when retrofitting established production lines for multi-additive blending systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Caking Agents Market |
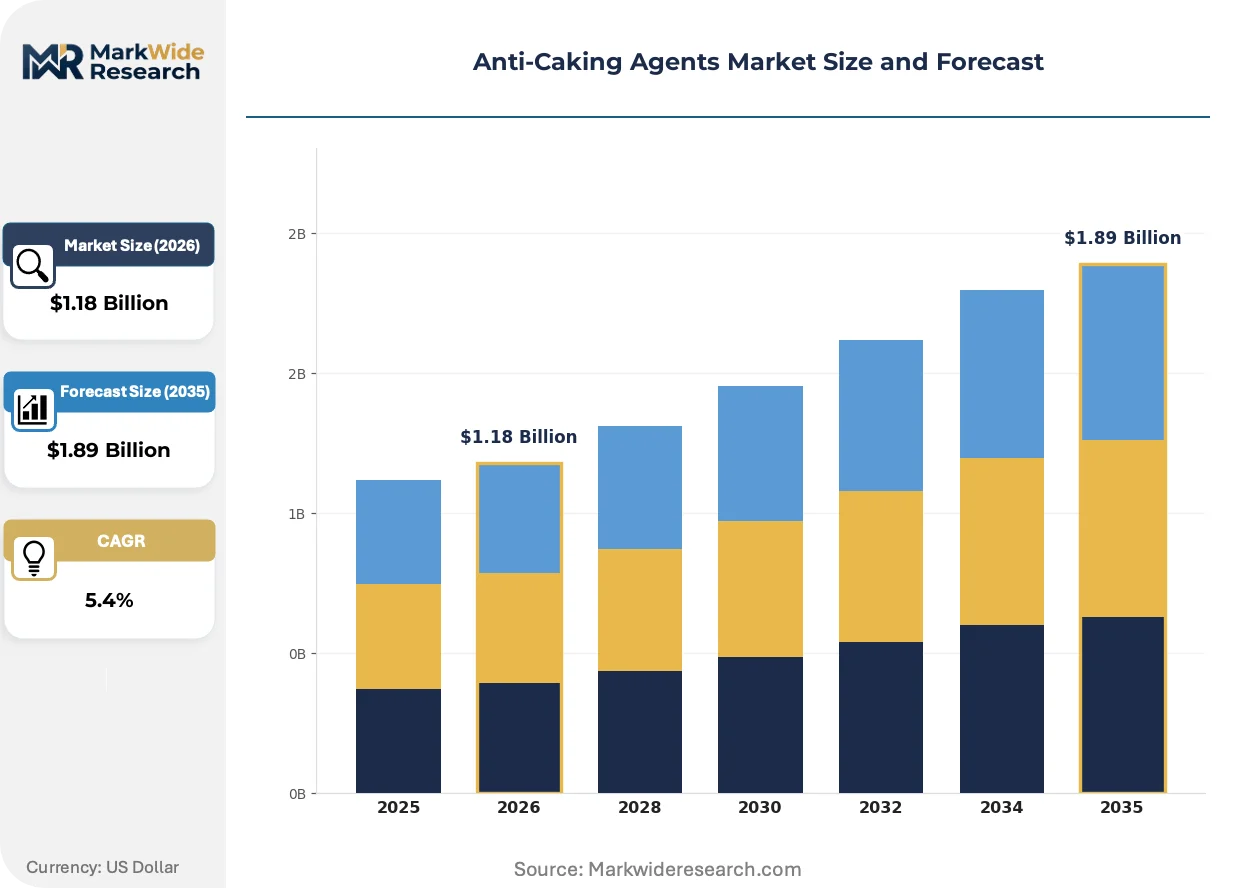
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $1.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Bicarbonate, Calcium Carbonate, Magnesium Carbonate, Silicon Dioxide Application: Food Industry, Animal Feed, Pharmaceuticals, Cosmetics Form: Powder, Granular, Liquid, Gel Technology: Granulation, Spray Drying, Coating, Blending |
| Companies Covered | Solvay SA, Brenntag AG, Evonik Industries AG, Huber Engineered Materials, Agropur Ingredients, BASF SE, PPG Industries, Inc., Univar Solutions Inc., Cabot Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Caking Agents Market Emerging Trajectories
Flowability engineering is migrating from commodity mineral sourcing toward precision surface-modification technologies that match additive specifications to exact humidity exposure profiles.
Nano-structured precipitated silica is consolidating its position as the dominant flowability solution for moisture-sensitive pharmaceutical actives. Tablet manufacturers in Switzerland and Germany are converting from conventional mineral grades to surface-engineered variants that achieve sub-5% moisture absorption thresholds. This specification compression is consolidating procurement decisions around technical performance rather than bulk mineral pricing.
EFSA evaluations of calcium carbonate and magnesium carbonate food safety thresholds are reshaping European-labeled product development pipelines. Manufacturers must demonstrate compliance with evolving maximum daily intake benchmarks before market authorization. Dairy and bakery segments in France and Italy are reformulating ahead of anticipated threshold reductions to avoid distribution interruptions.
Formulation houses are unbundling after-sales technical support from bulk additive contracts, creating standalone advisory revenue streams. Salt processors in Poland and the Netherlands now purchase flowability diagnostics separately from mineral supply agreements. This service separation is most visible in Central European markets where humidity variability demands customized additive blending ratios.
Anti-Caking Agents Market Segmentation
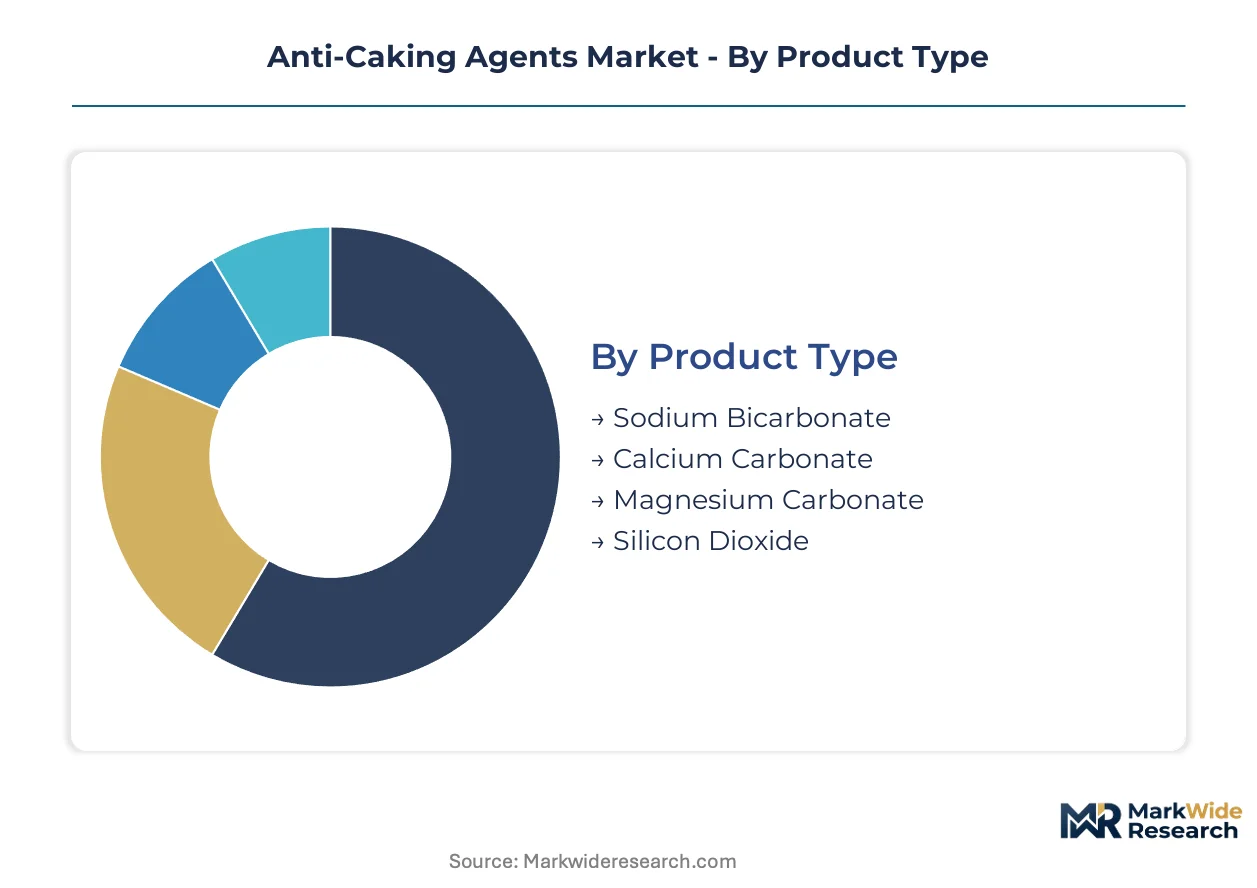
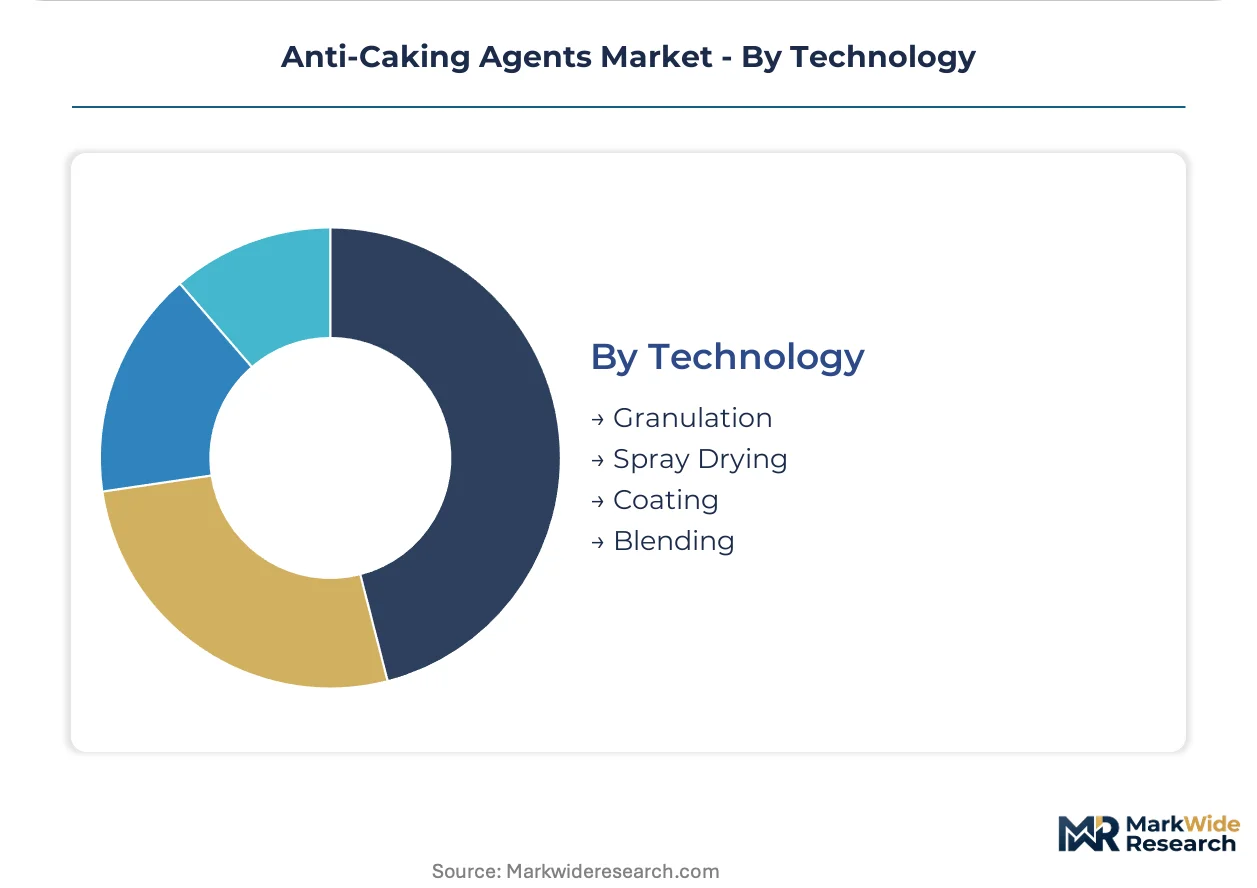
Anti-caking agent procurement decisions hinge on precise matching between mineral chemistry, processing method, and end-use regulatory requirements. Formulators select product types based on humidity exposure profiles, while technology choices determine surface area specifications critical for flowability performance.
Product Type:
Standardization dominates commodity mineral grades, yet pharmaceutical and food applications demand customized purity certifications and particle size distributions that fragment procurement across specification tiers.
- Sodium Bicarbonate:Alkaline salt produced via Solvay process chemistry serves effervescent tablet and baking powder applications where controlled CO₂ release properties matter. German and French dairy processors specify food-grade variants with tight heavy metal limits under EFSA thresholds. Growing fastest: pharmaceutical effervescent formulations.
- Silicon Dioxide:Synthetic amorphous silica achieves surface areas of 150-300 square meters per gram, creating physical barriers between hygroscopic particles. REACH-compliant grades for European food labeling command specification premiums over technical mineral variants. Leading the category by volume: salt and sugar flowability applications.
- Calcium Carbonate:Ground and precipitated grades serve dual roles as anti-caking agent and calcium fortification source in bakery premixes.
- Magnesium Carbonate:Light and heavy variants differentiate by bulk density for pharmaceutical tableting and athletic chalk formulations.
Volume leadership: Silicon Dioxide. Steepest expansion trajectory: Sodium Bicarbonate in pharmaceutical effervescents.
Application:
Margin structures diverge sharply between mass-volume food commodity sales and specification-intensive pharmaceutical contracts.
- Food Industry:Salt, sugar, and powdered beverage manufacturers consume standardized mineral grades where cost-per-kilogram drives supplier selection. Humidity-induced caking destroys consumer usability, forcing continuous additive inclusion across distribution channels in Germany, France, and Poland. Dominant volume position: table salt processing.
- Pharmaceuticals:Tablet manufacturers in Switzerland and Germany source surface-engineered precipitated silica with sub-5% moisture absorption thresholds. FDA and EMA dual-certification requirements compress viable supplier pools to integrated chemical producers with validated quality systems. Most rapid specification escalation: moisture-sensitive active pharmaceutical ingredients.
- Animal Feed:Mineral premix producers incorporate carbonate grades for flowability in vitamin and trace element blends.
- Cosmetics:Talc-free formulations drive substitution toward silica-based flow agents in powder makeup products.
Highest volume concentration: Food Industry. Fastest margin expansion: Pharmaceuticals.
Form:
Physical state selection traces directly to blending equipment compatibility and dissolution rate requirements in target formulations.
- Powder:Finely milled mineral grades below 50 microns integrate uniformly into dry mixes but generate dust exposure concerns during handling. Salt processors in the Netherlands and Poland specify powder grades for high-speed packaging lines where instantaneous dispersion prevents equipment fouling. Category volume leader: dry food premix applications.
- Granular:Controlled particle sizes between 100-500 microns reduce dusting while maintaining flowability in humid storage. Pharmaceutical tableting operations in Germany prefer granular silicon dioxide for direct compression compatibility with high-speed rotary presses. Fastest technology conversion: effervescent tablet manufacturing.
- Liquid:Suspension concentrates serve specialized coating applications where dry blending is impractical.
- Gel:Thixotropic formulations occupy niche cosmetic and pharmaceutical coating segments.
Granular formats gain share in pharmaceutical processing; powder retains food industry dominance.
Technology:
Processing method selection locks in surface area, porosity, and thermal stability characteristics that downstream formulators cannot modify.
- Spray Drying:Atomization of silica sols or carbonate slurries produces spherical particles with controlled porosity for moisture-sensitive actives. Heat-sensitive pharmaceutical and cosmetic grades require this method to preserve bioactive integrity during manufacture. Fastest adoption trajectory: moisture-sensitive pharmaceutical actives.
- Granulation:Agglomeration of fine powders into larger, free-flowing particles serves high-purity mineral carbonates in effervescent tablet manufacturing where dissolution kinetics determine product performance. Swiss and German pharmaceutical clusters specify granulation for magnesium carbonate grades. Volume concentration: effervescent tablet production.
- Coating:Surface modification technologies apply functional layers to base mineral particles.
- Blending:Physical mixing of multiple anti-caking agents creates customized flowability profiles for specific humidity conditions.
Spray Drying leads pharmaceutical specification trends; Granulation anchors effervescent tablet supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soda ash deposits in Wyoming's Green River Basin anchor North American supply security for sodium bicarbonate derivatives. German precipitated silica clusters and Belgian carbonation facilities concentrate European pharmaceutical-grade manufacturing. Chinese mineral processing expansion reshapes Asia-Pacific procurement patterns for food-grade silicates.
United States
Processed food manufacturers in the Midwest and Southeast expand silicon dioxide procurement for salt and sugar flowability under humid distribution conditions. FDA food additive regulations tighten purity documentation requirements for synthetic amorphous silica grades entering interstate commerce. Houston and Chicago distribution hubs consolidate multi-source blending operations to compress delivery timelines for regional formulation houses.
Germany
Bakery and dairy processing clusters in Bavaria and North Rhine-Westphalia drive carbonate-grade demand for powdered premix applications. ECHA REACH compliance mandates upgraded technical capabilities for precipitated silica suppliers seeking retained market access. Frankfurt and Mannheim pharmaceutical tableting operations source surface-engineered variants with sub-5% moisture absorption thresholds.
China
Domestic processed food manufacturing scales in Shandong and Jiangsu provinces, expanding mineral additive consumption for seasoning and beverage formulations. GB food additive classifications under SAMR authority determine which silicon dioxide grades achieve market authorization for packaged goods. Yangtze River Delta chemical processors invest in spray drying capacity to serve pharmaceutical contract manufacturing demand.
India
Emerging BIS standards for food-grade mineral additives create compliance thresholds for imported carbonate and silicate grades. FSSAI oversight of additive safety evaluations shapes product development pipelines for domestic-labeled goods. Maharashtra and Gujarat dairy cooperatives reformulate milk powder and cheese salt premixes to address humidity-driven caking in monsoon distribution cycles.
France
EFSA evaluations of calcium carbonate maximum daily intake benchmarks drive preemptive reformulation in Île-de-France bakery operations. Dairy processors in Brittany and Normandy specify heavy metal-tested grades for infant nutrition and cheese salt applications. Lyon and Marseille formulation houses unbundle technical advisory services from bulk supply contracts to capture standalone revenue streams.
Anti-Caking Agents Market Vendor Landscape
Global majors compete with regional champions across certification depth and logistics velocity. The vendor base stratifies between integrated chemical producers with validated quality systems and distribution specialists competing on delivery compression rather than manufacturing scale. Three archetypes dominate: soda ash-integrated carbonate suppliers, precipitated silica technology specialists, and network-heavy regional blenders. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure feedstock positions and regional blending capabilities.
Within the integrated chemical tier, Solvay SA and Evonik Industries AG exemplify divergent specialization paths—one anchored in soda ash process economics, the other in precipitated silica surface engineering. Among distribution-focused operators, Brenntag AG occupies a position emphasizing logistics speed over captive production. These three entities represent the structural spectrum from upstream integration through technical differentiation to network-based service models.
| Leading Market Players |
|---|
| Solvay SA |
| Brenntag AG |
| Evonik Industries AG |
| Huber Engineered Materials |
| Agropur Ingredients |
| BASF SE |
| PPG Industries, Inc. |
| Univar Solutions Inc. |
| Cabot Corporation |
| Others |
Supply Flow & Price Mechanics
Multi-source procurement mandates from German and French bakery processors are forcing carbonate-grade suppliers to reconfigure blending partnerships, compressing margin pools for single-mineral contract holders while rewarding regional logistics networks with pricing power.
Pricing Analysis
Technical advisory unbundling now separates flowability diagnostics from bulk mineral supply agreements, creating standalone service revenue streams alongside commodity sales. Three-tier pricing structure across REACH-certified premium, food-grade standard, and technical mineral economy levels reflects certification investment differentials. Price differentiation hinges on EFSA compliance documentation and heavy metal testing thresholds. Margins are tightening for sodium bicarbonate suppliers exposed to Solvay process energy economics, while pharmaceutical-grade silicon dioxide commands premium stability. Salt processors in Poland and the Netherlands exhibit highest price sensitivity; Swiss tablet manufacturers show least elasticity due to specification rigidity.
Supply Chain Analysis
Return flows of expired pharmaceutical inventory and off-specification mineral grades feed into reprocessing streams for lower-tier technical applications, creating circular material pathways that supplement virgin feedstock economics. Supply concentrates in Germany, Belgium, and Wyoming's Green River Basin, with soda ash deposits anchoring North American carbonate security. Raw material dependencies rest on trona ore, sodium sulfate, and silica sand feedstocks. Single-source vulnerability clusters around Belgian carbonation facilities for high-purity magnesium carbonate. Distribution runs through Houston and Chicago blending hubs serving Midwest and Southeast formulation houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spray-dried precipitated silica is displacing conventional mineral grades in moisture-sensitive pharmaceutical applications, compressing addressable volume for legacy granulation-based suppliers and rewarding surface-engineering capabilities.
For Market Incumbents: Acquire regional blending capabilities in Central European humidity corridors to anchor multi-source procurement relationships against logistics-speed competitors. Invest in EFSA pre-compliance certification for calcium carbonate grades ahead of anticipated maximum daily intake threshold reductions. Defensive consolidation around validated quality systems preserves dual-continent market access as FDA and REACH divergence intensifies. For New Entrants and Emerging Players: Nano-structured surface modification expertise offers entry into Swiss and German pharmaceutical tableting clusters where sub-5% moisture absorption specifications filter out commodity suppliers. White-space targets include effervescent tablet magnesium carbonate grades and Indian BIS-compliant mineral additive imports. Direct technical advisory sales to Maharashtra dairy cooperatives bypasses established distribution layers. For Investors and Strategic Acquirers: The window for entry favors integrated chemical producers with captive soda ash positions and validated pharmaceutical quality systems over pure-play distribution assets. Long-term viability rests on backward integration into energy-intensive process feedstocks and regulatory certification depth. Monitor EFSA calcium carbonate safety re-evaluations and Indian BIS implementation timelines for demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soda Ash Feedstock | Wyoming trona deposits anchor margin stability for sodium bicarbonate derivatives against energy volatility. |
| REACH Certification Investment | ECHA-compliant synthetic amorphous silica grades command specification premiums in European food labeling. |
| Regional Blending Partnership Expansion | Central European humidity variability rewards customized additive ratio capabilities near German dairy clusters. |
| Spray Drying Capacity Addition | Heat-sensitive pharmaceutical actives require atomized particle porosity that granulation cannot replicate. |
| Technical Advisory Service Unbundling | Polish salt processors now purchase flowability diagnostics separately from mineral supply contracts. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant managers at carbonate processing facilities, procurement leads at German bakery premix houses, distribution channel partners in North American blending hubs, and technical R&D directors at precipitated silica manufacturers. Bottom-up volume modeling triangulated against top-down value estimates derived from EFSA additive safety evaluations and FDA food additive classification updates.
Data-stream reconciliation across import-export statistics, Solvay process economics disclosures, and pharmaceutical excipient procurement databases informed the analytical framework. Segmentation dimensions spanned mineral chemistry grade, end-use industry application, processing technology method, and regional regulatory cluster. CAGRs were derived from trend extrapolation of spray drying adoption curves and effervescent tablet formulation growth, cross-referenced with humidity exposure modeling for salt and sugar distribution channels.
Several conditions sit outside the modeled scope, including sudden EFSA threshold revisions, energy price shocks affecting Solvay process economics, and trade restriction implementations on Chinese mineral processing exports. Practitioners should monitor BIS standard finalization in India, EFSA calcium carbonate safety re-evaluation timelines, and pharmaceutical contract manufacturing migration patterns toward Yangtze River Delta facilities for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Fermented Ingredient Market
Food Additives and Ingredients
Soft Drink Ingredients Market
Food Additives and Ingredients
Africa Feed Additives Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
Spain Food Preservatives Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
Firming Agents Market
Food Additives and Ingredients
Carrageenan Market
Food Additives and Ingredients
Food Enzymes Market
Food Additives and Ingredients
Lactose Monohydrate Market
Food Additives and Ingredients
Lake Food Colors Market
Food Additives and Ingredients
Food Grade Calcium Lactate Market
Food Additives and Ingredients
Oxidized Starch Market
Food Additives and Ingredients
Monoglyceride Market
Food Additives and Ingredients
Annatto Food Colors Market
Food Additives and Ingredients
Germany Food Additives Market