
 Global Food Bulking Agents Market | 2026-2036
Global Food Bulking Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Bulking Agents Market Analysis
ISO 22000 certification is reorganizing supplier tiers in the Global Food Bulking Agents Market, filtering out uncertified hydrocolloid traders from Western retail supply chains. Cargill, Incorporated leverages its corn wet-milling infrastructure to anchor bulk dextrose supply for North American contract manufacturers. Roquette Frères sustains pea starch differentiation through backward integration into European protein crop networks. Tate & Lyle PLC competes on clean-label positioning with its non-GMO tapioca-derived maltodextrin portfolio.
Food bulking agents are carbohydrate-based or hydrocolloid substances added to food matrices to increase volume, improve texture, and replace caloric components without altering sensory profiles; typical specifications include water-holding capacities of 3–15 grams per gram of dry material and particle sizes calibrated between 80–200 mesh for uniform dispersion. Their primary commercial purpose centers on enabling reduced-calorie and reduced-sugar reformulations while maintaining structural integrity in processed foods. Starch and pectin dominate volume flows in baked goods and dairy applications where gelatinization and gelling properties prove essential to mouthfeel replication. Guar gum occupies faster-growing niches in gluten-free bakery and clean-label sauce systems where cold-water solubility reduces processing energy. Psyllium remains a premium-positioned fiber source in functional snack bars, commanding higher margin pools despite smaller throughput.
The FDA's GRAS notification pathway and the EFSA's food additive re-evaluation program jointly determine which novel bulking agents achieve commercial scale in transatlantic markets. China's SAMR enforces GB standards on hydrocolloid purity that diverge from Codex Alimentarius thresholds, creating dual-compliance burdens for multinational ingredient suppliers. India's FSSAI has tightened labeling requirements for plant-based bulking claims, redirecting formulation R&D toward domestically sourced tamarind and cassava derivatives. Stakeholders must monitor pending EFSA opinions on modified starch digestibility classifications, as downgraded nutritional designations would force rapid reformulation across European convenience food portfolios.
Market Dynamics
Clean-label reformulation mandates from major retailers are compressing formulation cycles for bulking agents, forcing ingredient houses to pre-certify hydrocolloid grades against multiple regulatory frameworks before contract bidding begins.
Growth Catalysts
- EU Food Additives Regulation tightening:Purity thresholds for hydrocolloid imports are accelerating supplier consolidation toward ISO 22000-certified producers with captive refining capacity.
- Soluble fiber adoption in artisan baking:German industrial bakers are pulling clean-label bulking agents into reduced-sugar product lines to meet retail reformulation contracts.
- Gluten-free bakery expansion:Cold-water soluble hydrocolloids are penetrating sauce and bakery applications where energy-intensive processing previously limited uptake.
Market Restraints
- Pea protein crop volatility:European starch processors face margin compression from weather-driven protein crop yield fluctuations affecting backward-integrated supply security.
- Dual-compliance burdens in China:SAMR's GB standards on hydrocolloid purity diverge from Codex Alimentarius thresholds, forcing redundant testing protocols for multinational suppliers.
- Modified starch digestibility reclassification risk:Pending EFSA opinions threaten downgraded nutritional designations that would force rapid reformulation across European convenience food portfolios.
Strategic Opportunities
- India FSSAI labeling redirection:Tightened plant-based bulking claims are opening formulation R&D lanes for domestically sourced tamarind and cassava derivatives.
- Psyllium premium positioning:Functional snack bar manufacturers are capturing higher margin pools through fiber-specific health claims despite smaller throughput volumes.
- Non-GMO tapioca maltodextrin:Clean-label positioning is creating differentiation corridors in North American contract manufacturing where corn-derived alternatives face consumer skepticism.
Industry Challenges
- GRAS notification timeline compression:FDA pathway delays for novel bulking agents are extending commercialization cycles beyond typical food ingredient development windows.
- Mesh calibration standardization gaps:Particle size specifications between 80-200 mesh lack harmonized testing protocols, creating dispersion quality disputes between suppliers and formulators.
- Water-holding capacity verification:Laboratory capacity constraints for 3-15 grams per gram dry material testing are bottlenecking supplier qualification programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Bulking Agents Market |
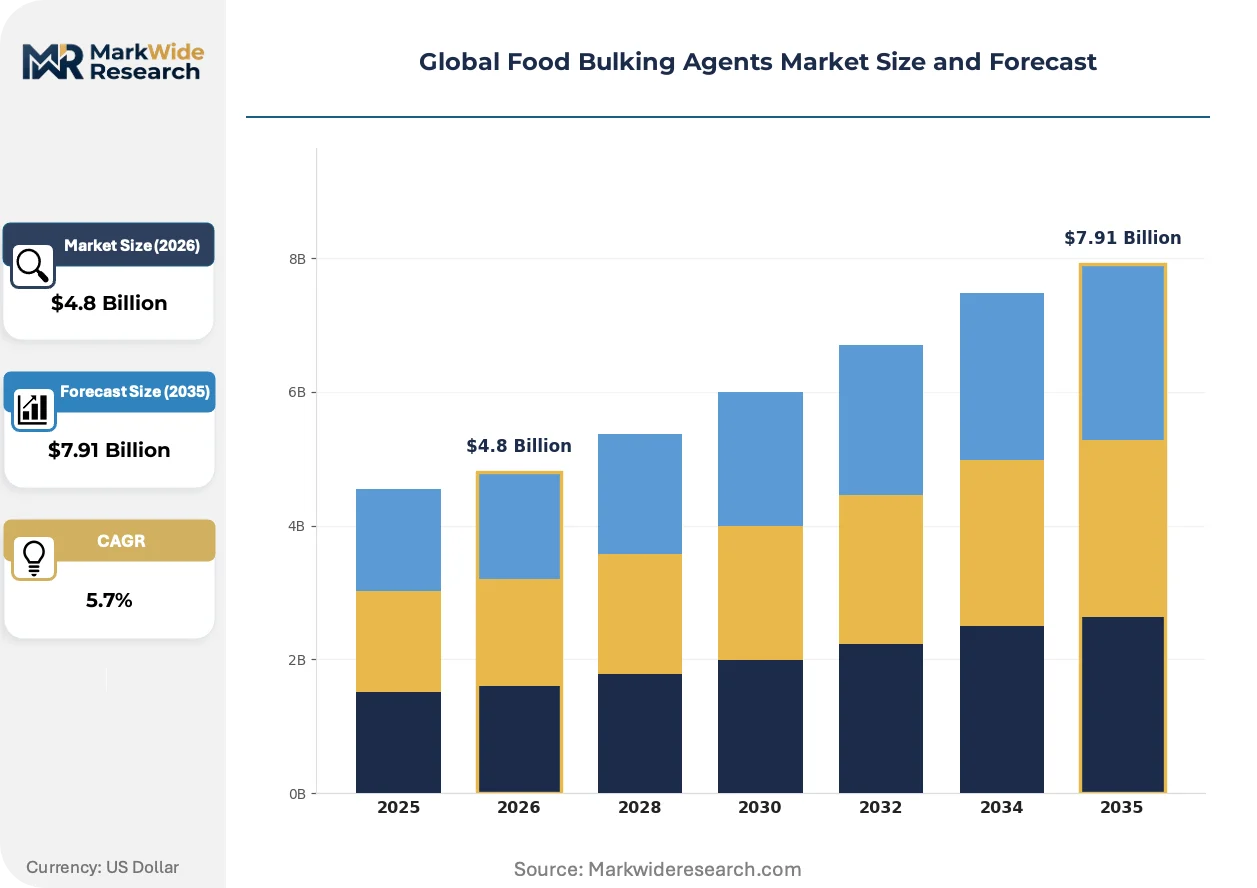
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch, Psyllium, Guar Gum, Pectin Application: Baked Goods, Sauces, Dairy Products, Snacks Source: Plant-based, Synthetic, Animal-derived, Mineral-based End User: Food Manufacturers, Restaurants, Retail, Catering Services |
| Companies Covered | Roquette Frères, DuPont Nutrition & Biosciences, Ingredion Incorporated, Olam Group, Tate & Lyle PLC, Cargill, Incorporated, Kerry Group plc, CP Kelco, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Bulking Agents Market Emerging Trajectories
Bioprocessed fiber ingredients are actively restructuring competitive positioning in bulking agent supply chains, creating new entry points for fermentation-derived alternatives alongside traditional extraction-based hydrocolloids.
Precision fermentation-derived cellulose is supplanting conventional wood-pulp microcrystalline cellulose in clean-label bakery applications. North American reduced-calorie bread manufacturers are adopting these ingredients at pilot scale ahead of full commercial rollout. This technology is compressing the addressable market for chemically processed texturizers while opening premium pricing tiers for fermentation-verified supply.
REACH-compliant hydrocolloid purity certifications are becoming mandatory gatekeeping criteria for EU retail supply chain entry. The ECHA enforcement framework is disqualifying uncertified traders from Western European distribution channels. Modified starch and pectin suppliers with pre-validated dossiers are capturing reformulation contracts from competitors facing registration gaps.
Buyer concentration among contract manufacturers is shortening ingredient qualification cycles from 18 months to 9 months. Large North American bakery and dairy processors are unbundling R&D partnerships from volume supply agreements. Germany and the Netherlands show the most pronounced compression, where ingredient houses must now deliver certified samples within 90 days of brief receipt to remain competitive.
Global Food Bulking Agents Market Segmentation
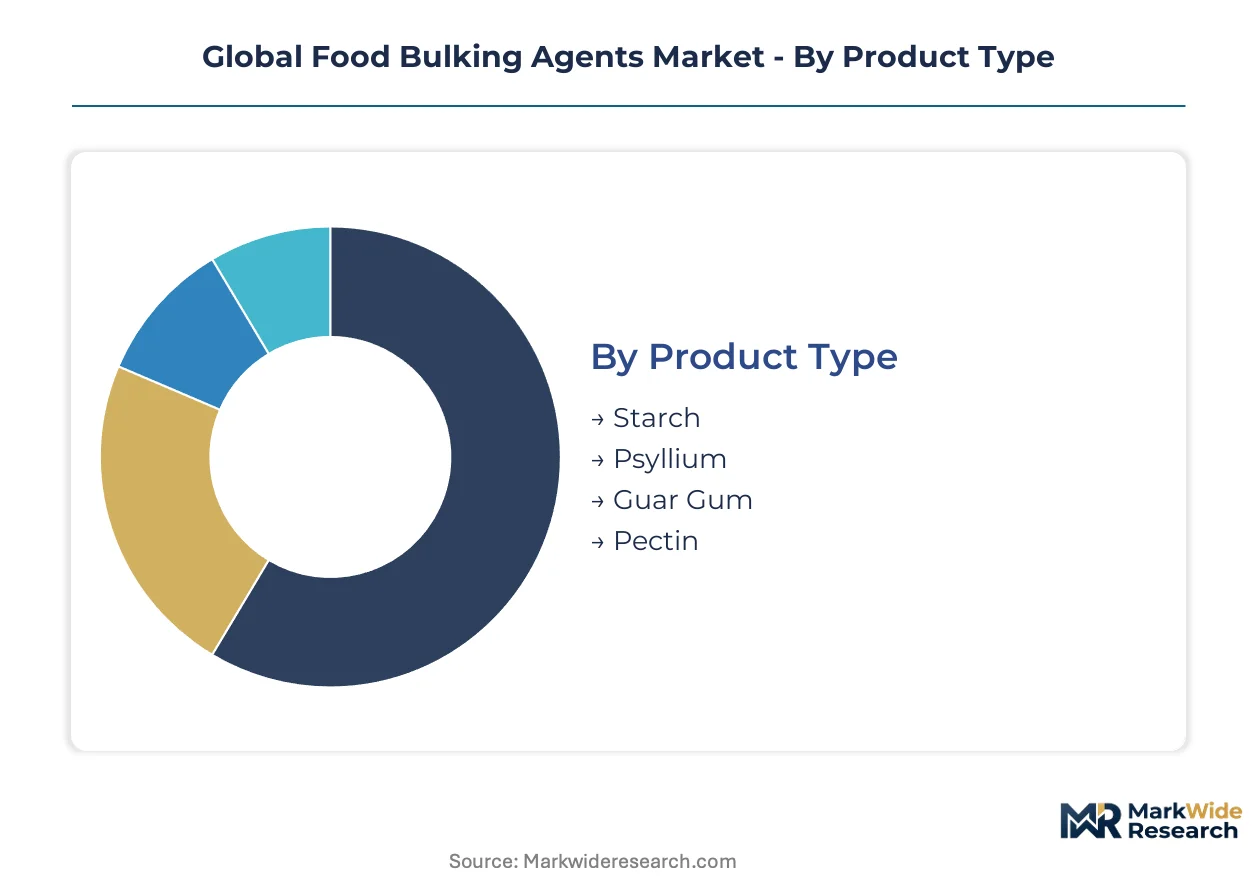
Segmentation in food bulking agents reflects divergent regulatory pathways and technical specifications that reshape procurement priorities. Formulators select grades based on water-holding capacity thresholds and certification requirements that vary sharply across end-use categories.
Product Type:
Regulatory frameworks distinguish bulking agents by extraction method and purity thresholds, with EFSA and FDA maintaining separate dossier requirements for hydrocolloids versus modified starches.
- Starch:Corn, potato, and tapioca derivatives dominate volume flows with gelatinization temperatures between 60–70°C enabling thermal processing stability. German industrial bakers specify native and modified grades for reduced-sugar bread formulations under tightened EU Food Additives Regulation compliance windows.
- Psyllium:Husk fiber from Plantago ovata delivers water-holding capacities at the upper range of bulking agent specifications, creating dense matrices in functional snack bars. US and European manufacturers command premium positioning through fiber-specific health claims despite constrained raw material availability from Indian cultivation zones.
- Guar Gum:Cold-water soluble galactomannan from Cyamopsis tetragonoloba seed endosperm reduces energy-intensive processing steps in gluten-free bakery systems.
- Pectin:Citrus and apple-derived polyuronide requires precise degree of esterification control for gelation in reduced-sugar dairy applications.
Starch handles the majority of throughput; psyllium is gaining share fastest through functional positioning in health-forward snack categories.
Application:
End-use processing conditions dictate particle size calibration and hydration kinetics, with thermal stability requirements varying across baking versus cold-fill manufacturing lines.
- Baked Goods:Bread, cake, and pastry matrices demand bulking agents with controlled swelling behavior and moisture retention across freeze-thaw cycles. Artisan and industrial bakers in Germany and the Netherlands specify 80–120 mesh particle sizes for uniform crumb structure in clean-label reduced-sugar lines.
- Sauces:Viscosity-building hydrocolloids require rapid hydration without lumping in high-shear processing environments. Cold-water soluble guar and tapioca derivatives penetrate this segment where energy reduction targets favor lower-temperature manufacturing.
- Dairy Products:Pectin and starch blends stabilize protein matrices in yogurt and dairy alternatives through controlled syneresis prevention.
- Snacks:Extruded and puffed formats utilize resistant starch and fiber bulking agents for texture modification and caloric reduction claims.
Baked goods anchor current volume absorption; sauces are expanding most quickly as clean-label reformulation compresses processing energy requirements.
Source:
Raw material provenance determines regulatory classification speed and label claim permissibility, with plant-derived options facing shorter GRAS notification timelines than novel synthetic alternatives.
- Plant-based:Corn, cassava, tamarind, and legume derivatives constitute the primary commercial volume, with non-GMO and organic certifications commanding price premiums in North American retail channels. India's FSSAI labeling redirection favors domestically sourced tamarind and cassava for regional formulation R&D.
- Synthetic:Chemically modified cellulose and polymer-based bulking agents serve industrial applications where cost minimization outweighs clean-label positioning.
- Animal-derived:Limited to gelatin and collagen peptides in specialized confectionery and dairy texturizing applications.
- Mineral-based:Microcrystalline cellulose from wood pulp and fermentation-derived alternatives compete on purity and sustainability credentials.
Plant-based sources command the dominant share position; mineral-based alternatives are climbing the fastest through bioprocessing technology substitution.
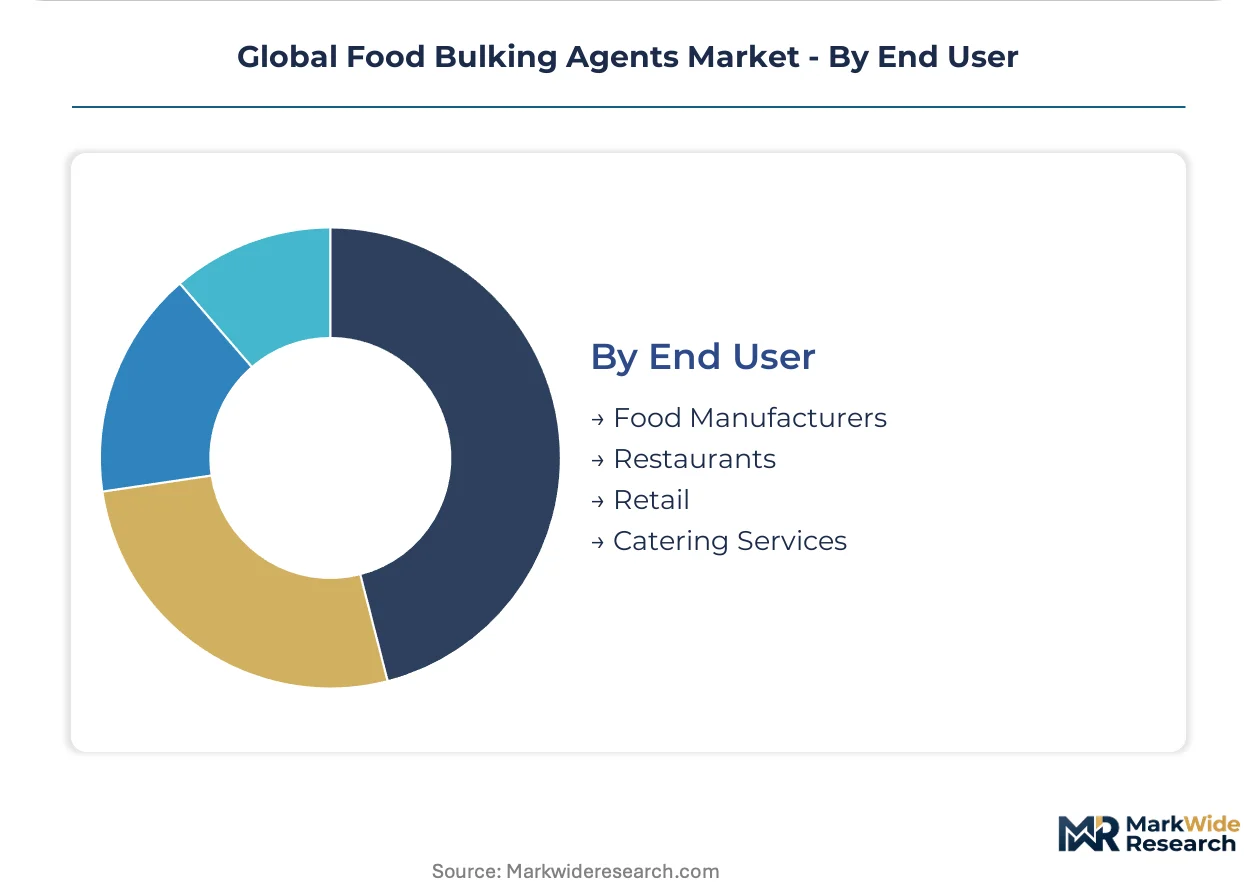
End User:
Procurement scale and technical service requirements fragment the customer base, with large contract manufacturers compressing supplier qualification cycles against smaller operators prioritizing formulation flexibility.
- Food Manufacturers:Industrial bakery, dairy, and sauce processors specify bulk volumes with ISO 22000-certified supply chains and documented water-holding capacity verification. Buyer concentration among North American contract manufacturers has shortened ingredient qualification from 18 months to 9 months.
- Restaurants:Limited penetration due to batch-scale preparation methods and minimal reformulation R&D capacity.
- Retail:Private-label product development teams specify clean-label bulking agents for reduced-calorie and reduced-sugar product lines under retailer reformulation mandates.
- Catering Services:Minimal direct procurement; indirect exposure through prepared ingredient specifications from upstream food manufacturers.
Food manufacturers absorb the preponderance of volume flows; retail private-label development shows the steepest expansion trajectory as supermarket reformulation deadlines accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturers and ingredient houses concentrate procurement authority across Germany, the United States, China, and India, with each market presenting distinct regulatory compliance burdens and formulation service requirements that reshape supplier access.
Germany
Industrial bakers in the Rhine-Ruhr and Bavarian clusters drive soluble fiber uptake for reduced-sugar bread lines under retailer reformulation mandates. EFSA's pending modified starch digestibility opinions threaten downgraded nutritional classifications that would force rapid portfolio adjustments. Ingredient houses in Hamburg and Frankfurt maintain ISO 22000-certified supply chains to serve pan-European contract manufacturing networks.
United States
North American bakery and dairy processors compress ingredient qualification cycles from eighteen months to nine months, unbundling R&D partnerships from volume agreements. FDA GRAS notification delays extend commercialization timelines for novel bulking agents beyond typical development windows. Corn wet-milling infrastructure in the Midwest anchors bulk dextrose supply for contract manufacturers serving clean-label reformulation demand.
China
SAMR enforces GB standards on hydrocolloid purity that diverge from Codex Alimentarius thresholds, creating dual-compliance testing burdens for multinational suppliers. Yangtze River Delta ingredient traders face disqualification from Western retail channels without REACH-compliant purity certifications. Domestic tapioca and cassava processors capture reformulation contracts as FSSAI-style labeling pressures redirect R&D toward plant-derived alternatives.
India
FSSAI tightened plant-based bulking claims redirect formulation R&D toward domestically sourced tamarind and cassava derivatives in Maharashtra and Gujarat processing clusters. Psyllium husk from Rajasthan cultivation zones commands premium positioning in functional snack bar exports despite constrained raw material throughput. Mumbai and Ahmedabad ingredient houses serve regional reformulation contracts ahead of Western qualification timelines.
Netherlands
Rotterdam and Amsterdam distribution hubs filter uncertified hydrocolloid traders from EU retail supply chains under ECHA enforcement frameworks. Buyer concentration among Dutch dairy and sauce processors demands certified sample delivery within ninety days of brief receipt. Pea starch backward integration into European protein crop networks sustains differentiation for Netherlands-based ingredient specialists serving German industrial bakeries.
Global Food Bulking Agents Market Vendor Landscape
Player mix skews toward diversified agribusiness conglomerates with captive refining capacity and specialized hydrocolloid purifiers with ISO 22000 pre-certification. The vendor base separates into three strategic archetypes: corn wet-millers leveraging infrastructure scale, pea protein integrators controlling crop networks, and clean-label specialists differentiating through non-GMO verification. Competitive moves concentrate on backward integration into raw material supply and rapid certification against multiple regulatory frameworks ahead of contract bidding.
Within the diversified agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven positioning anchored in North American grain processing infrastructure. Roquette Frères occupies a specialist position representing European pea-derived ingredient integration. Tate & Lyle PLC sits within the clean-label verification vector, illustrating non-GMO positioning strategies in tapioca-derived portfolios. These three anchors demonstrate how geographic processing concentration and certification pre-positioning determine contract access in compressed qualification environments.
| Leading Market Players |
|---|
| Roquette Frères |
| DuPont Nutrition & Biosciences |
| Ingredion Incorporated |
| Olam Group |
| Tate & Lyle PLC |
| Cargill, Incorporated |
| Kerry Group plc |
| CP Kelco |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
Ninety-day sample delivery windows now function as the primary sorting mechanism between certified and uncertified suppliers, compressing pricing power toward ISO 22000-accredited hydrocolloid refiners with captive European refining capacity while disqualifying spot-market traders from reformulation contract access.
Pricing Analysis
Cost-plus contracts indexed to corn and tapioca starch futures dominate North American volume agreements, with Tate & Lyle PLC and Cargill, Incorporated leveraging captive wet-milling infrastructure to stabilize input pass-through. Three-tier pricing structure across premium, standard, and economy levels separates fermentation-verified cellulose grades from chemically processed microcrystalline cellulose and unmodified native starches. Pricing pressure stems from buyer concentration among contract manufacturers demanding 90-day qualification compression without price premiums. Food manufacturers show highest price sensitivity on commodity starch grades; functional snack bar producers accept premium positioning for psyllium and fermentation-derived fiber claims.
Supply Chain Analysis
Inventory buffers of 45-60 days for Indian psyllium husk and European pea starch reflect agricultural harvest cyclicality and protein crop yield volatility. Supply concentrates in Germany, the United States, and India, with Rotterdam and Hamburg distribution hubs filtering uncertified traders from EU retail channels. Raw material flows draw from Rajasthan psyllium cultivation zones, Midwest corn belt processing clusters, and Maharashtra tapioca refining operations. Single-source vulnerability runs through Indian monsoon-dependent fiber crops. Distribution runs through ingredient houses serving pan-European contract manufacturing networks with documented water-holding capacity verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label certification interoperability is restructuring supplier-platform economics, as REACH-compliant hydrocolloid dossiers become mandatory gatekeeping criteria for EU retail supply chain entry and compress qualification cycles toward pre-certified ingredient houses.
For Market Incumbents: Consolidate backward integration into European protein crop networks and captive pea starch refining capacity to defend margin position against fermentation-derived cellulose substitution. Accelerate ISO 22000 pre-certification against multiple regulatory frameworks ahead of EFSA modified starch digestibility opinions. Lock in 18-24 month supply agreements with German industrial bakers to anchor volume through retailer reformulation mandate windows. For New Entrants and Emerging Players: Anchor in India's FSSAI-compliant tamarind and cassava derivative segments, where tightened plant-based bulking claims redirect formulation R&D toward domestically sourced alternatives ahead of Western qualification timelines. Target functional snack bar manufacturers with psyllium-premium positioning and fiber-specific health claim support. Pursue rapid-sample certification partnerships with Mumbai and Ahmedabad processing clusters to compress 90-day delivery benchmarks. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because regulatory divergence between FDA GRAS pathways, EFSA re-evaluation programs, and SAMR GB standards creates persistent compliance premiums for multi-certified suppliers. Acquisition targets should demonstrate pre-validated REACH dossiers and backward-integrated raw material security. Watch for EFSA modified starch digestibility reclassification as the signal triggering rapid European portfolio restructuring and consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Protein Crop Networks | Roquette Frères sustains pea starch differentiation through European cultivation zone control. |
| Multi-Framework Pre-Certification Investment | ISO 22000 accreditation against FDA, EFSA, and SAMR standards compresses contract bidding timelines. |
| Fermentation-Derived Cellulose Scale-Up | Bioprocessed alternatives displace chemically processed microcrystalline cellulose in clean-label bakery. |
| Regional Formulation R&D Partnerships | Mumbai and Ahmedabad ingredient houses capture FSSAI-redirected tamarind and cassava development. |
| REACH-Compliant Purity Certification | ECHA enforcement disqualifies uncertified traders from Western European distribution channels. |
Methodological Framework
A standing panel of ingredient procurement directors at North American contract manufacturers, EFSA regulatory affairs specialists, hydrocolloid quality verification laboratory managers, and German industrial bakery reformulation leads provided ongoing calibration against secondary validation from FDA GRAS notification databases, EFSA food additive re-evaluation opinions, SAMR GB standard publications, and customs trade flow records. Bottom-up volume estimates from starch, psyllium, guar gum, and pectin grade specifications were cross-checked against top-down market sizing from agribusiness segment disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window, with segmentation modeling across product type, application, source, and end-user dimensions plus regulatory pathway clustering by FDA, EFSA, SAMR, and FSSAI jurisdiction. CAGRs were derived from trend-line fitting to historical volume flows and forward projection of clean-label reformulation mandate penetration. Forecast inputs included retailer reformulation deadline schedules, pending EFSA opinion release timelines, and protein crop yield volatility patterns.
Material uncertainties — regulatory reclassification of modified starch digestibility, Indian monsoon-driven psyllium crop failures, and GRAS notification pathway delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification adoption rates and buyer concentration trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Ph Adjuster Market
Food Additives and Ingredients
Food Grade Glycerin Market
Food Additives and Ingredients
Beverage Clarifier and Stabilizer Market
Food Additives and Ingredients
Food Enzymes Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
Argentina Food Additives Market
Food Additives and Ingredients
Food Grade Sodium Citrate Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Tapioca Starch Market
Food Additives and Ingredients
Egypt Feed Additives Market
Food Additives and Ingredients
Spain Food Enzymes Market
Food Additives and Ingredients
Nutraceutical Excipients Market
Food Additives and Ingredients
Antistaling Agent Market
Food Additives and Ingredients
Europe Clean Label Ingredient Market