
 Neohesperidin Market | 2026-2036
Neohesperidin Market Size, Share, and Industry Trends Forecast 2026-2036
Neohesperidin Market Analytics
Pharmaceutical companies is reorganizing neohesperidin procurement away from generalist ingredient traders toward qualified botanical extract suppliers with documented supply chain traceability. Nutrafur S.A. anchors European demand through its specialized citrus-derived ingredient portfolio and backward integration into Spanish orange processing. Golden Health Technology Co., Ltd. dominates domestic Chinese supply through captive orchards and in-house extraction infrastructure. Merck KGaA competes in high-purity reference standards and analytical-grade neohesperidin for pharmaceutical validation protocols.
Neohesperidin is a flavanone glycoside extracted primarily from bitter orange (Citrus aurantium) peel, characterized by a molecular weight of 610.56 g/mol and solubility in polar organic solvents; manufacturers employ solvent extraction followed by chromatographic purification to achieve pharmaceutical-grade specifications above 98% purity for drug formulation applications. Natural neohesperidin commands premium positioning in nutraceutical and pharmaceutical channels where clean-label certification drives procurement decisions, while neohesperidin dihydrochalcone concentrates in high-intensity sweetener applications for beverage brands seeking sugar reduction without artificial additive labeling. Synthetic neohesperidin occupies cost-sensitive industrial segments where functional performance outweighs botanical provenance requirements.
China's NMPA and SAMR enforce evolving GB standards for botanical extract purity and heavy metal limits, compelling domestic producers to upgrade filtration and testing infrastructure or forfeit pharmaceutical channel access. The FDA's GRAS notification pathway and EFSA's novel food assessment framework shape export market entry for Chinese and European suppliers respectively. Stakeholders must monitor regulatory divergence between pharmacopeial-grade specifications and food-additive purity thresholds, as dual-track compliance investments will separate viable long-term suppliers from regional commodity players.
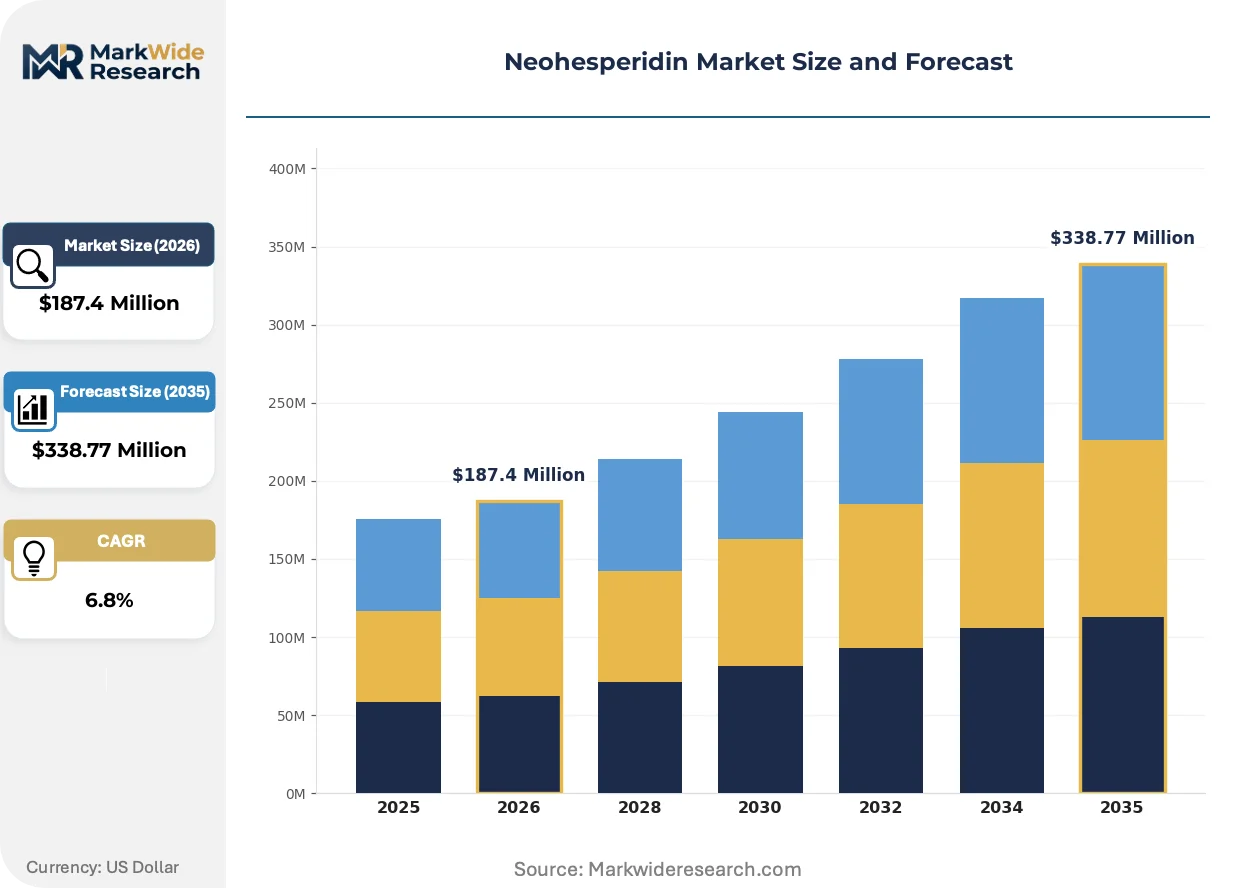
Market Dynamics
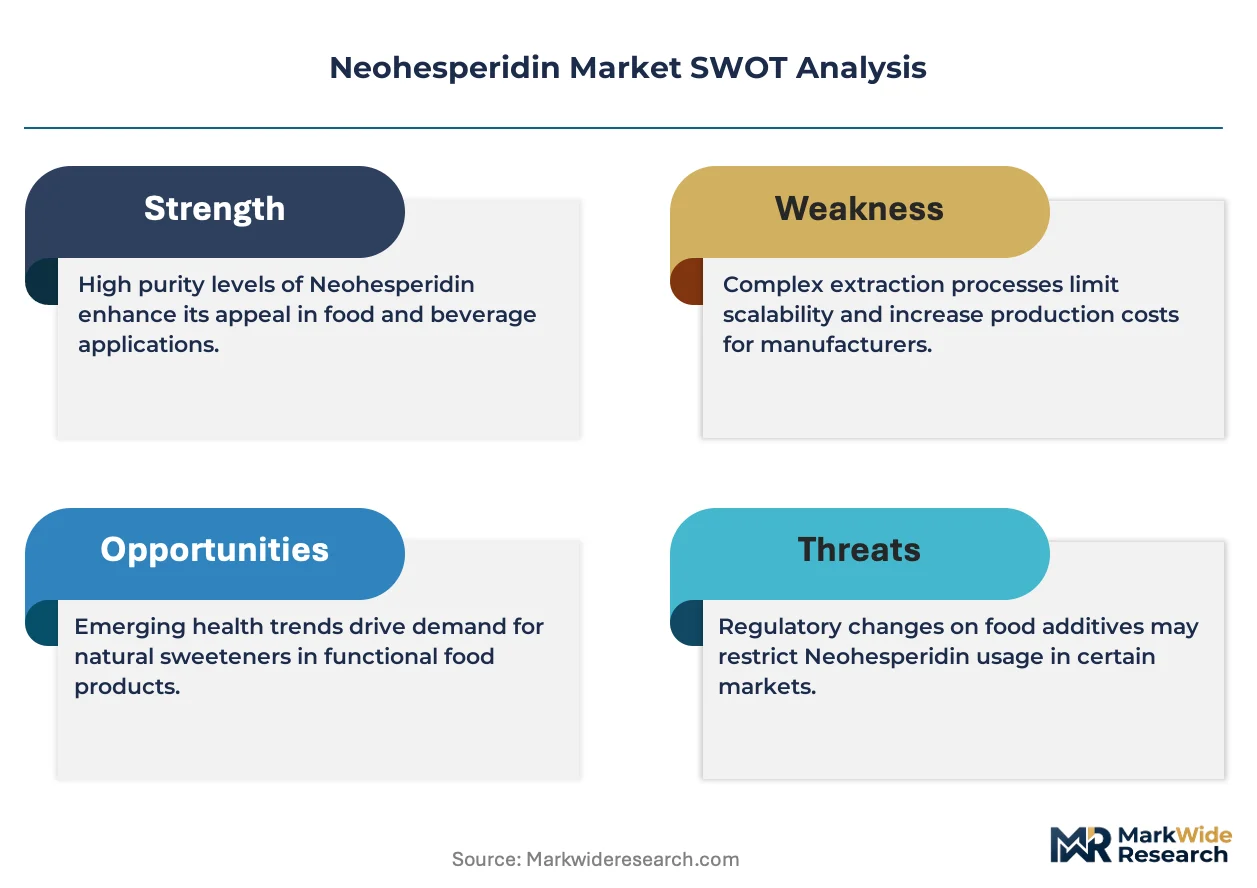
Pharmaceutical-grade purity mandates from China's NMPA and SAMR are compressing supplier margins while concentrating procurement among vertically integrated extractors with captive citrus orchards and in-house chromatographic purification infrastructure.
Growth Catalysts
- Flavonoid-based drug pipelines:Pharmaceutical formulators are expanding neohesperidin procurement for cardiovascular and metabolic disorder research programs, pulling volume through qualified botanical extract channels.
- China's GB standard upgrades:Evolving national standards for botanical extract purity and heavy metal limits are redirecting pharmaceutical channel access toward certified domestic producers with documented supply chain traceability.
- Bitter orange processing clusters:Concentrated raw material feedstock in Sichuan and Hunan provinces is enabling economies of scale for regional extractors serving both domestic and export markets.
Market Restraints
- Raw material concentration risk:Dependence on Citrus aurantium peel from specific Chinese citrus belts exposes processors to climate volatility and regional supply disruptions.
- Purification cost escalation:Achieving pharmaceutical-grade specifications above 98% purity requires capital-intensive chromatographic infrastructure that excludes smaller regional commodity traders.
- Stevia and monk fruit substitution:Natural high-intensity sweeteners are capturing beverage formulation share from neohesperidin dihydrochalcone in cost-sensitive sugar reduction applications.
Strategic Opportunities
- EFSA novel food pathway:European suppliers can capture premium positioning by navigating the novel food assessment framework for expanded food-additive applications beyond current use cases.
- Clean-label pharmaceutical certification:Documented supply chain traceability and botanical provenance verification is opening differentiated pricing tiers for nutraceutical and pharmaceutical channels.
- Dual-track compliance infrastructure:Investments spanning pharmacopeial-grade specifications and food-additive purity thresholds are separating viable long-term suppliers from regional commodity players.
Industry Challenges
- Chromatographic purification expertise:Scarcity of skilled technicians capable of operating high-performance liquid chromatography systems at pharmaceutical-grade throughput is constraining capacity expansion.
- Dual regulatory certification timelines:Simultaneous compliance with China's NMPA drug master file requirements and FDA GRAS notification pathways is extending market entry cycles for export-oriented producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neohesperidin Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Neohesperidin, Synthetic Neohesperidin, Neohesperidin Dihydrochalcone, Neohesperidin Powder Application: Food & Beverages, Pharmaceuticals, Nutraceuticals, Cosmetics End User: Food Manufacturers, Beverage Brands, Pharmaceutical Companies, Cosmetic Brands Distribution Channel: Online Retailers, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Nutrafur S.A., Golden Health Technology Co., Ltd., Sichuan New Hawk Biotechnology Co., Ltd., MORRE-TEC Industries, Chengdu Mansite Biotechnology Co., Ltd., Merck KGaA, Changsha Sunnycare Inc., Layn Corp., Kang Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neohesperidin Market Evolving Landscape
Continuous processing technology and advanced separation science are compressing batch cycle times while enabling real-time purity monitoring, fundamentally altering capital efficiency benchmarks for neohesperidin extraction operations.
Supercritical fluid extraction systems are replacing conventional solvent-based methods in premium-grade production. European botanical extract specialists are adopting these platforms to meet EFSA novel food purity thresholds. The technology is miniaturizing extraction footprints while eliminating residual solvent contamination risks that plague traditional hexane-based processes.
China's SAMR is tightening heavy metal limits under revised GB standards for botanical extracts. Domestic producers face mandatory filtration infrastructure upgrades or forfeiture of pharmaceutical channel access. Sichuan-based extractors are responding by integrating inductively coupled plasma mass spectrometry testing into quality control protocols.
Formulation houses are consolidating supplier relationships around qualified botanical extract specialists with documented provenance. Beverage brands seeking sugar reduction are bypassing generalist ingredient traders to source directly from Spanish and Chinese processors with captive orchard networks. This consolidation is most visible in European nutraceutical channels where clean-label certification drives procurement decisions.
Neohesperidin Market Segmentation
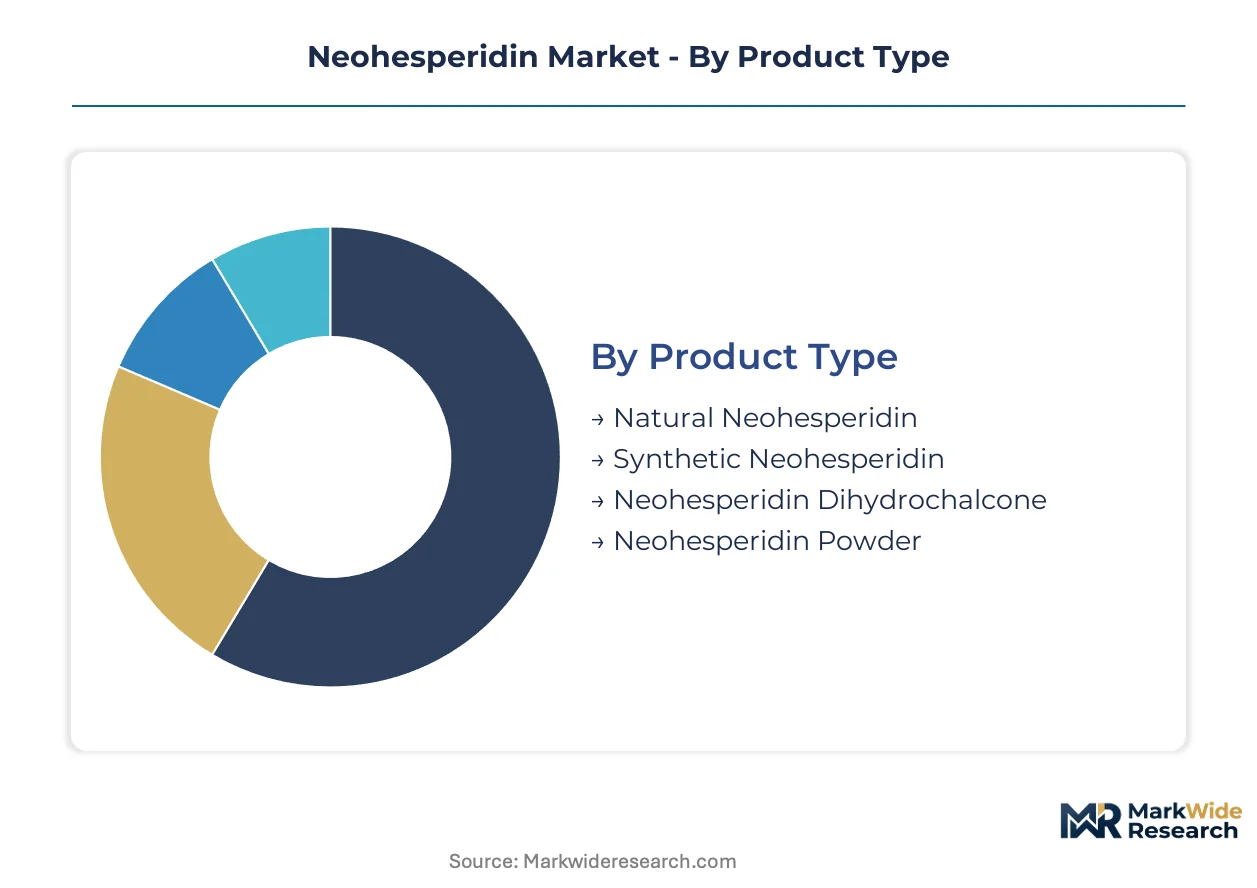
Neohesperidin procurement channels diverge sharply by purity grade and end-use certification requirements. Pharmaceutical formulators, beverage brands, and cosmetic houses each access distinct supply tiers with incompatible specification thresholds.
Product Type:
Channel-mix patterns separate botanical-certified grades from industrial synthetics, with pharmaceutical and nutraceutical buyers paying premiums for documented Citrus aurantium provenance while food additive buyers prioritize cost efficiency.
- Natural Neohesperidin:Extracted from bitter orange peel through solvent extraction and chromatographic purification, this grade achieves pharmaceutical specifications above 98% purity. Demand concentrates in European nutraceutical channels where EFSA novel food frameworks and clean-label certification command pricing premiums from documented Spanish and Chinese suppliers.
- Neohesperidin Dihydrochalcone:A hydrogenated derivative delivering high-intensity sweetness approximately 1500-1800 times sucrose potency, this segment serves beverage brands pursuing sugar reduction without artificial additive labeling. Procurement is shifting toward direct relationships with Chinese processors in Sichuan and Hunan provinces that control captive orchard networks.
- Synthetic Neohesperidin:Manufactured through chemical synthesis routes, this grade occupies cost-sensitive industrial applications where functional performance outweighs botanical provenance requirements.
- Neohesperidin Powder:Standardized dry formulations with defined particle size distributions for formulation convenience in supplement and cosmetic manufacturing.
By volume, Neohesperidin Dihydrochalcone leads. By growth pace, Natural Neohesperidin is expanding most quickly.
Application:
Margin structures across applications reflect regulatory burden divergence, with pharmaceutical validation protocols demanding pharmacopeial-grade investments that food additive channels cannot amortize.
- Pharmaceuticals:Flavonoid-based drug pipelines for cardiovascular and metabolic disorder research are pulling volume through qualified botanical extract channels with NMPA drug master file documentation. China's GB standard upgrades for heavy metal limits and purity benchmarks are redirecting procurement toward certified domestic producers with inductively coupled plasma mass spectrometry testing capabilities.
- Food & Beverages:Sugar reduction formulations in beverage categories drive volume procurement of neohesperidin dihydrochalcone, though stevia and monk fruit substitution is compressing share in cost-sensitive applications.
- Nutraceuticals:Clean-label certification and supply chain traceability verification open differentiated pricing tiers for European and North American channels.
- Cosmetics:Antioxidant and skin-brightening applications in premium skincare formulations.
Pharmaceuticals capture the highest margin tier. Food & Beverages dominates absolute volume throughput.
End User:
Customer scale determines sourcing modality, with multinational beverage brands and pharmaceutical formulators disintermediating generalist traders to secure supply continuity.
- Pharmaceutical Companies:These buyers enforce the most stringent supplier qualification protocols, requiring documented chromatographic purification infrastructure and dual regulatory compliance across NMPA and FDA pathways.
- Beverage Brands:Direct procurement relationships with Spanish and Chinese processors are consolidating around suppliers with captive orchard networks and backward integration into citrus processing.
- Food Manufacturers:Industrial-scale buyers prioritizing cost efficiency and consistent specification delivery.
- Cosmetic Brands:Premium positioning buyers seeking antioxidant claims with botanical ingredient narratives.
Pharmaceutical Companies impose the most demanding qualification burden. Beverage Brands are driving the steepest channel consolidation.
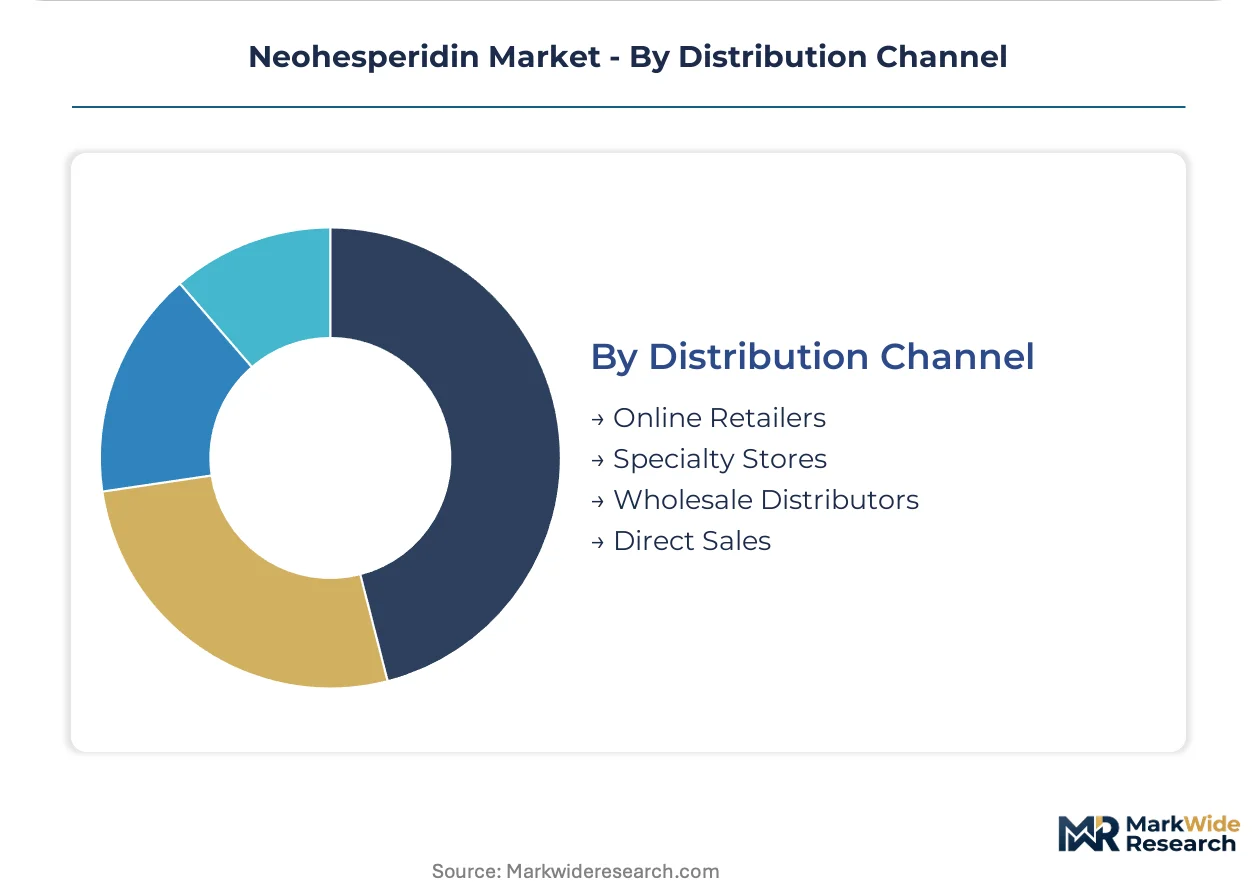
Distribution Channel:
Channel selection correlates with buyer sophistication and volume scale, with qualified extractors increasingly bypassing intermediaries for strategic accounts.
- Direct Sales:Dominates pharmaceutical and large beverage accounts where multi-year supply agreements and technical collaboration justify relationship investment.
- Wholesale Distributors:Serves mid-tier nutraceutical and cosmetic manufacturers lacking scale for direct supplier negotiation.
- Specialty Stores:Small-volume channels for research institutions and boutique formulators.
- Online Retailers:Emerging for analytical-grade reference standards and small-batch procurement.
Direct Sales commands the highest value per transaction. Wholesale Distributors still handle the broadest customer count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical formulators and beverage brands concentrate procurement in jurisdictions with established citrus processing infrastructure and evolving botanical extract regulations. Buyer archetypes prioritize supply chain traceability and dual regulatory compliance capabilities.
China
Pharmaceutical-grade neohesperidin demand from cardiovascular drug pipelines pulls volume through Sichuan and Hunan citrus belts. SAMR's revised GB standards for heavy metal limits and purity benchmarks compel filtration infrastructure upgrades among domestic extractors. Chengdu and Changsha processing clusters consolidate around vertically integrated producers with captive orchard networks and in-house chromatographic purification.
Spain
European nutraceutical channels drive premium positioning for documented Citrus aurantium provenance. EFSA's novel food assessment framework shapes market entry pathways for expanded food-additive applications. Valencia and Murcia bitter orange processing regions anchor supply through specialized citrus-derived ingredient portfolios with backward integration into regional orange cultivation.
United States
Beverage brands pursuing sugar reduction formulations source neohesperidin dihydrochalcone for clean-label positioning. FDA's GRAS notification pathway governs food-additive approvals while pharmacopeial-grade specifications apply to pharmaceutical validation protocols. California and Florida formulation houses consolidate supplier relationships around qualified botanical extract specialists with documented supply chain traceability.
Germany
High-purity reference standards and analytical-grade neohesperidin serve pharmaceutical validation protocols across European drug development pipelines. EMA pharmacopeial requirements intersect with REACH chemical safety regulations for botanical extract imports. Frankfurt and Munich distribution nodes channel certified grades to formulators requiring dual regulatory documentation.
India
Emerging nutraceutical manufacturing expands procurement of natural neohesperidin for antioxidant and metabolic health formulations. CDSCO's evolving drug master file requirements for botanical extracts redirect supplier qualification toward certified producers. Maharashtra and Gujarat processing hubs develop extraction capacity to serve domestic pharmaceutical and export-oriented functional ingredient demand.
Neohesperidin Market Competitive Landscape
Player mix skews toward vertically integrated citrus processors with captive orchard assets and specialized botanical extract houses with chromatographic purification infrastructure. Market structure concentrates procurement access among qualified suppliers with documented NMPA drug master files and FDA GRAS notifications. Strategic archetypes include backward-integrated Chinese processors controlling Sichuan-Hunan raw material belts, European citrus specialists with EFSA novel food certifications, and diversified chemical suppliers offering analytical-grade reference standards. Dominant competitive moves encompass filtration infrastructure upgrades to meet SAMR heavy metal limits and direct sales relationship consolidation with multinational beverage brands.
Within the backward-integrated processor tier, Golden Health Technology Co., Ltd. and Sichuan New Hawk Biotechnology Co., Ltd. represent Chinese archetypes with upstream control over citrus cultivation and extraction infrastructure. Nutrafur S.A. occupies a position exemplifying European specialization in citrus-derived ingredient portfolios with regional orchard network integration. Merck KGaA anchors the analytical-grade and reference standards segment serving pharmaceutical validation protocols across multiple regulatory jurisdictions.
| Leading Market Players |
|---|
| Nutrafur S.A. |
| Golden Health Technology Co., Ltd. |
| Sichuan New Hawk Biotechnology Co., Ltd. |
| MORRE-TEC Industries |
| Chengdu Mansite Biotechnology Co., Ltd. |
| Merck KGaA |
| Changsha Sunnycare Inc. |
| Layn Corp. |
| Kang Biotech |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day inventory cycles for pharmaceutical-grade neohesperidin concentrate pricing power among Sichuan and Hunan processors with captive orchard networks, while beverage brands face compressed margins from stevia substitution in high-intensity sweetener applications. China's SAMR-mandated filtration upgrades and EFSA novel food certification costs are bifurcating supplier tiers between qualified extractors and regional commodity traders.
Pricing Analysis
Solvent-extraction pricing gaps separate supercritical fluid platforms from conventional hexane methods, with European specialists commanding premiums for residual-solvent-free grades. Three-tier pricing structure across pharmaceutical-certified, food-additive, and industrial synthetic levels reflects divergence in chromatographic purification investment and NMPA drug master file documentation. Cost compression in food-grade dihydrochalcone intensifies because stevia and monk fruit capture beverage formulation share. Pharmaceutical companies exhibit least price sensitivity due to validation protocol requirements, while industrial buyers prioritize functional performance over provenance verification.
Supply Chain Analysis
Sichuan-Hunan citrus belt concentration exposes processors to climate volatility and regional supply disruptions from typhoon patterns and temperature anomalies. Raw material dependence draws from Citrus aurantium peel, high-purity solvents, and chromatographic resins as critical inputs. Single-source vulnerability runs through China's dominance of bitter orange cultivation clusters and in-house extraction infrastructure. Distribution runs through direct sales relationships with multinational pharmaceutical formulators and beverage brands, bypassing generalist ingredient traders for qualified botanical extract specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neohesperidin procurement cycles track pharmaceutical R&D pipeline expansion, positioning the market for cyclical recovery as flavonoid-based cardiovascular drug programs advance through clinical validation stages.
For Market Incumbents: Compound defensive positioning through backward integration into Spanish and Chinese citrus cultivation assets, while accelerating NMPA-FDA dual-track certification investments to exclude regional commodity competitors. Chromatographic technician scarcity and SAMR heavy metal compliance timelines threaten margin stability for under-invested processors. For New Entrants and Emerging Players: Analytical-grade reference standard supply gaps where Merck KGaA dominates offer white-space entry through pharmaceutical validation protocol partnerships. Target India's emerging nutraceutical manufacturing hubs and CDSCO-certified extraction capacity buildout. Pursue EFSA novel food pathway navigation as differentiated service-layer positioning against incumbent commodity traders. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with under-monetized botanical extract divisions lacking pharmaceutical channel access. Five-to-ten-year viability hinges on dual regulatory compliance infrastructure amortization across NMPA and FDA pathways. Monitor SAMR enforcement intensity against GB standard violators as inflection indicator for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical Fluid Extraction Adoption | Eliminates residual solvent risks for EFSA novel food certification in European nutraceutical channels. |
| NMPA Drug Master File Investment | Secures pharmaceutical channel access as China's SAMR tightens botanical extract purity benchmarks. |
| Captive Orchard Network Expansion | Controls Citrus aurantium feedstock quality and traceability for clean-label certification requirements. |
| Inductively Coupled Plasma Testing Integration | Enables GB standard heavy metal compliance verification for domestic and export market qualification. |
| Direct Sales Relationship Consolidation | Bypasses wholesale distributors to secure multi-year supply agreements with multinational beverage brands. |
Research Methodology
The analysis maps natural neohesperidin, dihydrochalcone derivatives, synthetic grades, and powder formulations, each validated through extraction facility managers, pharmaceutical procurement directors, beverage brand formulators, and regulatory affairs specialists across primary interviews. Secondary sources encompass NMPA drug master file registries, FDA GRAS notification databases, EFSA novel food assessment records, and customs trade data for citrus-derived ingredient flows. Bottom-up capacity modeling and top-down demand triangulation from cardiovascular drug pipeline disclosures cross-validate volume estimates.
Consistency checks against external benchmarks validated analytical outputs across the projection horizon through comparison with pharmacopeial-grade specification adoption rates and high-intensity sweetener substitution patterns. Segmentation dimensions span purity grade, application end-use, and regulatory certification tier alongside captive versus merchant supply sourcing. CAGRs derive from year-over-year capacity utilization trends and pharmaceutical R&D expenditure trajectories. Forecast inputs incorporate SAMR enforcement intensity projections and EFSA novel food approval velocity assumptions.
Underlying assumptions cover NMPA-FDA regulatory convergence pace and citrus yield stability, with deviation risk concentrated in climate volatility across Sichuan-Hunan growing regions and stevia cost-performance improvements. Practitioners should keep alternative scenarios live as SAMR GB standard implementation timelines and EFSA assessment backlogs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Transglutaminase Market
Food Additives and Ingredients
Beverage Clarifier and Stabilizer Market
Food Additives and Ingredients
Mexico Food Enzymes Market
Food Additives and Ingredients
Egypt Food Enzymes Market
Food Additives and Ingredients
Modified Milk Ingredients Market
Food Additives and Ingredients
United Kingdom Food Acidulants Market
Food Additives and Ingredients
Canada Food Preservatives Market
Food Additives and Ingredients
Australia Food Acidulants Market
Food Additives and Ingredients
Food Grade Sodium Citrate Market
Food Additives and Ingredients
Hydrocolloid Carrier Market
Food Additives and Ingredients
China Food Acidulants Market
Food Additives and Ingredients
Italy Food Enzymes Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Food Binders Market
Food Additives and Ingredients
Japan Food Acidulants Market
Food Additives and Ingredients
North America Feed Additives Market