
 Dairy Stabilizer Market | 2026-2036
Dairy Stabilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Stabilizer Market Analytics
Subscription-based formulation support is rebalancing how dairy stabilizer suppliers monetize technical relationships. Palsgaard leverages its integrated emulsifier-stabilizer portfolio to anchor long-term contracts with European dairy processors. Cargill competes through backward integration into guar and tara gum supply chains in South Asia and South America.
Dairy stabilizers encompass hydrocolloid and gum-based additives that control viscosity, prevent syneresis, and maintain suspension in processed milk products, typically functioning at concentrations between 0.1% and 2.0% by weight. These ingredients serve the essential commercial purpose of extending shelf stability and textural consistency in temperature-stressed distribution networks. Pectin and gellan gum command premium positioning within the product type architecture, as beverage and spoonable yogurt makers prioritize thermal-reversible gelation and clean-label declaration compatibility. The application dimension shows yogurt and dairy desserts absorbing the bulk of formulation innovation, while cheese applications remain comparatively mature with slower ingredient turnover cycles.
The FDA GRAS notification pathway and USDA organic certification requirements govern market access for new hydrocolloid entrants in the United States, while EFSA novel food assessments and EU organic regulation shape European product qualification timelines. Compliance with these frameworks directly determines which stabilizer chemistries achieve commercial scale in each jurisdiction. Stakeholders must track evolving clean-label definitions and biobased feedstock verification standards as these criteria increasingly filter procurement decisions across dairy processor R&D programs.
Market Dynamics
Clean-label reformulation mandates from the EU F-Gas Regulation and REACH compliance are compressing synthetic hydrocolloid availability while pulling investment toward plant-derived alternatives with verified biobased feedstocks.
Growth Catalysts
- EU F-Gas Regulation phase-down:Synthetic refrigerant restrictions are forcing dairy processors to reformulate for ambient-stable distribution, expanding demand for thermal-reversible gelling agents that maintain texture without cold-chain integrity.
- Spoonable yogurt clean-label migration:Beverage and yogurt makers are eliminating modified starches in favor of pectin and gellan gum declarations that satisfy retailer scoring algorithms and consumer scan behavior.
- South Asian guar cluster expansion:Backward integration into Rajasthan and Gujarat guar gum supply chains is securing volume commitments for European dairy processors facing locust bean gum shortages.
Market Restraints
- Locust bean gum supply concentration:Eighty percent of global carob cultivation clusters in Spain, Portugal, and Morocco, creating weather-driven price volatility that destabilizes formulation costing models.
- EFSA novel food assessment timelines:New hydrocolloid entrants face eighteen-to-thirty-six month qualification periods that freeze chemistry innovation and entrench incumbent supplier relationships.
- Native starch functional limitations:Clean-label starches lack the process tolerance of modified alternatives, forcing processors to absorb yield losses or invest in capital-intensive high-pressure processing equipment.
Strategic Opportunities
- Fermentation-derived hydrocolloids:Precision fermentation platforms in Denmark and the Netherlands are producing gellan gum and curdlan equivalents with certified non-GMO status and supply security independent of agricultural harvests.
- Plant-based dairy analogues:Oat, almond, and pea protein beverage makers require stabilizer systems that suspend insoluble fiber and prevent phase separation, opening formulation service contracts beyond traditional dairy.
- EU organic regulation expansion:The 2024 update to EU organic processing standards is mandating stricter additive restrictions, creating first-mover advantage for suppliers with certified organic hydrocolloid portfolios.
Industry Challenges
- Food technologist formulation expertise gaps:The shift from single-hydrocolloid to synergistic multi-component systems demands rheology and protein interaction knowledge that outpaces university curriculum updates and internal training programs.
- Clean-label certification audit complexity:Biobased feedstock verification through mass balance accounting requires supply chain documentation systems that smaller stabilizer suppliers lack capital to implement.
- Legacy dairy equipment compatibility:Existing pasteurization and homogenization lines operate at shear rates and temperature profiles optimized for conventional stabilizers, complicating clean-label transitions without equipment retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Stabilizer Market |
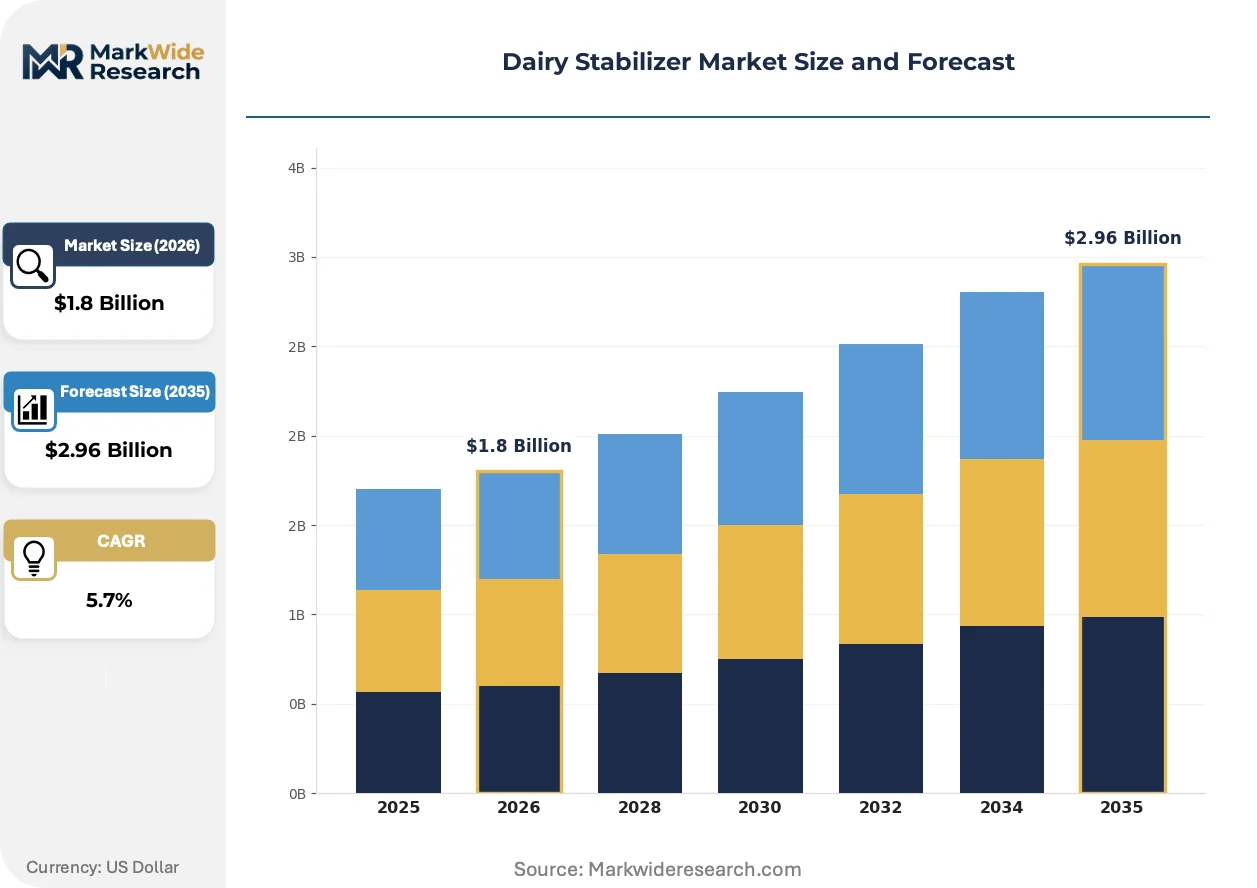
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gellan Gum, Agar Agar, Pectin, Xanthan Gum Application: Dairy Desserts, Sour Cream, Yogurt, Cheese End User: Food Manufacturers, Dairy Processors, Retailers, Restaurants Functionality: Thickening Agent, Emulsifier, Stabilizer, Gelling Agent |
| Companies Covered | Corbion, Musim Mas, Palsgaard, ICL Food Specialties, Silvateam, Clariant AG, IFPC, National Stabilizers, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Stabilizer Market Evolving Landscape
Digital formulation platforms and precision fermentation are compressing development cycles while regulatory chemistry restrictions are redirecting R&D investment toward bio-derived alternatives with supply chain traceability.
Enzymatic hydrocolloid modification is automating the production of tailored molecular weight distributions that match specific dairy application requirements. Mid-sized yogurt manufacturers are adopting these enzymatically optimized pectins to reduce dosage rates by fifteen to twenty percent while maintaining identical mouthfeel profiles. This technology is automating the transition from empirical formulation to predictive rheology modeling, compressing the supplier-customer technical service relationship into software-driven specification matching.
REACH substance restriction proposals are accelerating substitution planning for carrageenan and alginates derived from non-EU seaweed harvesting regions. The European Chemicals Agency's 2025 roadmap for polymer registration is forcing importers to document supply chain environmental footprints and heavy metal contamination controls. Dairy dessert and ice cream segments are responding fastest, reformulating toward land-based hydrocolloids with established EU cultivation or fermentation origins.
Subscription-based technical service contracts are displacing traditional spot procurement of stabilizer ingredients. Dairy processors in Germany, France, and Italy are locking multi-year formulation support agreements that bundle regulatory documentation, sensory panel access, and emergency supply guarantees. This model concentrates purchasing authority within technical directors rather than procurement functions, rewarding suppliers with integrated application laboratories and rapid sample turnaround capabilities.
Dairy Stabilizer Market Segmentation
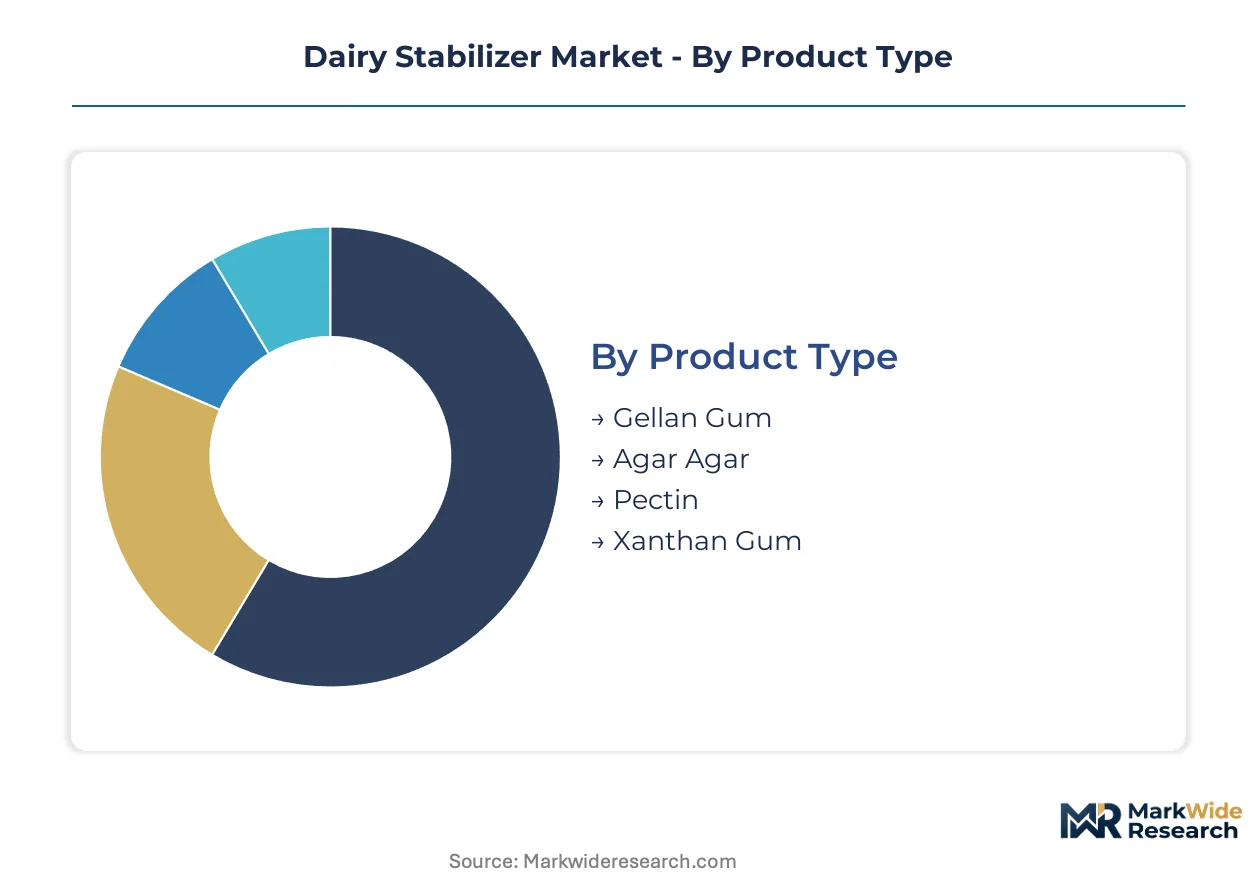
Dairy stabilizer procurement decisions split between commodity-grade specifications for high-volume yogurt production and tailored rheology packages for premium dessert lines. Formulation complexity determines supplier relationship intensity and contract duration across each segment boundary.
Product Type:
Customization intensity spans from off-the-shelf xanthan gum to project-specific pectin molecular weight engineering for clean-label declarations.
- Pectin:Citrus and apple-derived pectins with varying degrees of methoxylation enable thermal-reversible gelation in ambient-stable yogurt beverages. German and French dairy processors specify low-methoxyl grades for calcium-set spoonable applications, paying formulation service premiums to secure EFSA-compliant organic certification documentation.
- Gellan Gum:Fermentation-derived high-acyl and low-acyl variants suspend insoluble minerals and create fluid gels in fortified dairy beverages. Demand clusters with beverage makers in the Netherlands and Denmark seeking non-GMO supply security independent of agricultural harvest volatility.
- Xanthan Gum:Standardized fermentation polysaccharide provides shear-thinning viscosity in cost-optimized sour cream and processed cheese applications.
- Agar Agar:Seaweed-extracted gelling agent serves niche halal and kosher dairy dessert segments with restrictive gelatin substitution requirements.
Most installed capacity flows through pectin. Expansion is steepest in gellan gum.
Application:
Volume concentration versus margin capture varies sharply across temperature-stressed distribution requirements and clean-label reformulation cycles.
- Yogurt:Drinkable and spoonable yogurt formats absorb the majority of hydrocolloid innovation investment, with pectin-gellan gum synergies replacing modified starches in ambient-stable lines. Italian and German processors drive specification changes to meet retailer clean-label scoring algorithms.
- Dairy Desserts:Custards, mousses, and chilled puddings demand precise gel strength control and freeze-thaw stability, pulling customized hydrocolloid blends with documented EFSA novel food status.
- Cheese:Processed and analog cheese applications rely on established carrageenan and locust bean gum systems with slower ingredient turnover due to legacy equipment compatibility constraints.
- Sour Cream:Viscosity maintenance through temperature fluctuations dominates functional requirements, with xanthan-guar gum combinations serving commodity volume segments.
Cheese commands the largest volume throughput. Dairy desserts are gaining share fastest.
End User:
Technical service intensity scales inversely with customer scale, as mid-sized processors lack in-house formulation expertise.
- Dairy Processors:Integrated yogurt and cheese manufacturers in Germany, France, and Italy negotiate multi-year formulation support contracts bundling regulatory documentation, sensory panel access, and emergency supply guarantees.
- Food Manufacturers:CPG companies with dairy-adjacent portfolios require stabilizer systems compatible with co-manufacturing networks and private-label specification portability.
- Restaurants:Foodservice distributors prioritize cost-optimized, high-tolerance stabilizer blends for prepared dessert and sauce applications with minimal technical support requirements.
- Retailers:Private-label dairy program managers specify clean-label compliant hydrocolloid declarations to match national brand positioning at price-tier discounts.
Dairy processors anchor current revenue. Food manufacturers show the steepest contract expansion trajectory.
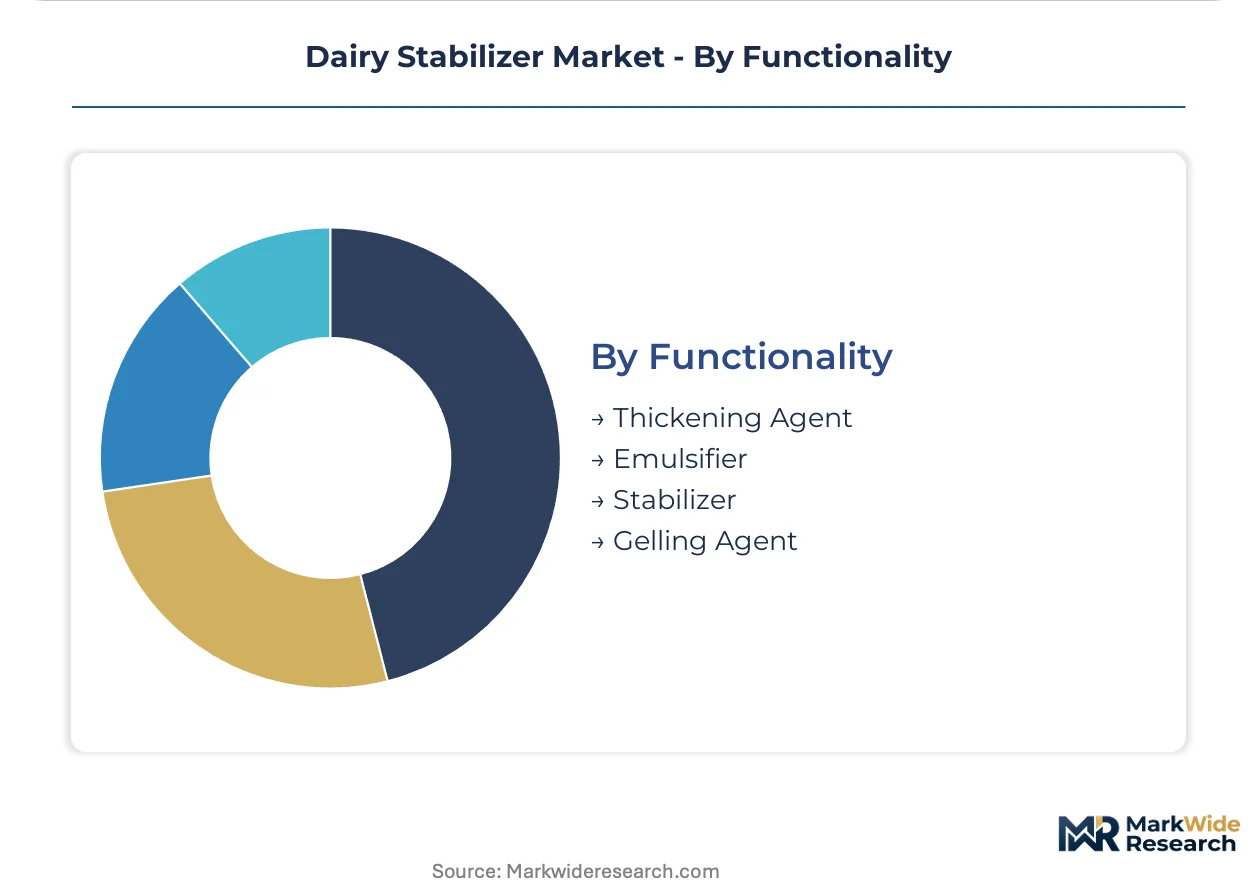
Functionality:
Single-function commoditization confronts multi-functional premium positioning as equipment compatibility and clean-label constraints reshape procurement priorities.
- Thickening Agent:Viscosity control in pourable dairy beverages and spoonable yogurt relies on xanthan gum and native starch combinations, with enzymatic modification reducing dosage rates in cost-sensitive applications.
- Gelling Agent:Thermal-reversible gelation for ambient-stable desserts and set yogurt demands pectin and gellan gum with precise calcium reactivity profiles, commanding specification premiums from processors reformulating for EU F-Gas Regulation compliance.
- Stabilizer:Syneresis prevention and phase separation control in long-shelf-life products combines multiple hydrocolloid functionalities, requiring supplier technical service investment.
- Emulsifier:Fat stabilization and mouthfeel modification in reduced-fat dairy lines integrates hydrocolloid and emulsifier-stabilizer portfolios, with Palsgaard and similar suppliers bundling integrated ingredient systems.
Thickening agent specifications dominate current volume. Gelling agent applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting dairy stabilizer production toward jurisdictions with streamlined biobased feedstock certification. The EU F-Gas Regulation and REACH compliance costs in Europe are pushing processors to evaluate manufacturing footprints in markets with lower qualification timelines.
Germany
Spoonable yogurt clean-label migration and ambient-stable beverage expansion drive hydrocolloid procurement from processors in Bavaria and North Rhine-Westphalia. EFSA novel food assessments and EU organic regulation compliance shape formulation timelines for pectin and gellan gum suppliers. The Munich-Stuttgart corridor concentrates precision fermentation R&D for fermentation-derived hydrocolloids.
France
Dairy dessert innovation and premium yogurt positioning pull customized pectin specifications from processors in Île-de-France and Auvergne-Rhône-Alpes. REACH substance restriction proposals accelerate substitution planning for seaweed-derived stabilizers. The Lyon-Grenoble cluster hosts application laboratories serving pan-European formulation support contracts.
Italy
Traditional cheese applications and emerging plant-based analogues create dual demand streams for hydrocolloid suppliers in Lombardy and Emilia-Romagna. EU organic regulation expansion mandates stricter additive restrictions for export-certified production. The Parma-Reggio Emilia dairy processing belt anchors long-term stabilizer supply agreements.
Netherlands
Fortified dairy beverages and fluid gel applications concentrate gellan gum demand among processors in Randstad and Brabant. EFSA-compliant documentation requirements filter procurement toward suppliers with established EU cultivation or fermentation origins. The Wageningen food technology cluster drives enzymatic hydrocolloid modification adoption.
United States
Clean-label reformulation in drinkable yogurt and reduced-fat sour cream segments expands pectin and gellan gum specification changes. FDA GRAS notification pathways and USDA organic certification govern market access timelines for new hydrocolloid entrants. The Midwest dairy processing corridor evaluates backward integration into South Asian guar supply chains.
Dairy Stabilizer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation-intensive yogurt and dessert applications favoring integrated technical service providers while commodity cheese and sour cream lines tolerate spot procurement. The vendor base concentrates around three strategic archetypes: fermentation-derived hydrocolloid specialists with precision platforms, plant-extraction houses with backward-integrated agricultural supply chains, and emulsifier-stabilizer integrators bundling multi-functional systems. Dominant competitive moves include multi-year formulation support contract expansion and upstream control over biobased feedstock verification systems.
Among integrated emulsifier-stabilizer providers, Palsgaard occupies a position exemplifying the bundled-ingredient-system archetype, while Cargill represents the agricultural-commodity-backward-integration model with upstream presence in South Asian and South American supply chains. Within the fermentation-specialist tier, Corbion anchors European precision-derived hydrocolloid supply security independent of harvest volatility.
| Leading Market Players |
|---|
| Corbion |
| Musim Mas |
| Palsgaard |
| ICL Food Specialties |
| Silvateam |
| Clariant AG |
| IFPC |
| National Stabilizers |
| Cargill |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation phase-down mandates gate qualified supply access and premium-tier pricing power by restricting synthetic refrigerant-dependent distribution networks, forcing dairy processors toward certified biobased hydrocolloids with documented REACH compliance. Formulation service premiums concentrate with suppliers possessing EFSA-compliant organic certification and precision fermentation platforms.
Pricing Analysis
Capacity additions in Denmark and the Netherlands are reshaping price floors for fermentation-derived gellan gum as precision platforms expand supply security independent of agricultural harvests. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified organic pectin from conventional grades and commodity xanthan gum. Cost compression in commodity xanthan-guar combinations is intensifying because South Asian guar cluster expansion feeds volume competition. Small-scale Italian yogurt processors show highest price sensitivity; German dairy dessert makers prioritize specification premiums over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns for hydrocolloid consolidation before final-mile delivery to Bavarian and Lombardy processing belts. Manufacturing gravity centers on Spain, Portugal, and Morocco for locust bean gum, with Denmark and the Netherlands hosting fermentation-derived alternatives. Raw material flows draw from Rajasthan guar clusters, citrus peel processors in Mexico and Brazil, and North Atlantic seaweed harvesting regions. Single-source vulnerability in Iberian carob cultivation creates weather-driven price volatility. Distribution runs through integrated emulsifier-stabilizer bundlers with captive application laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dairy stabilizer procurement operates as a geographic-arbitrage play between EU REACH compliance costs and South Asian backward integration economics, with formulation service intensity determining margin capture.
For Market Incumbents: Lock in multi-year technical service contracts with German and French dairy processors before EFSA novel food assessment timelines freeze substitution windows. Deepen upstream control over biobased feedstock verification systems to defend margin position against South Asian guar cluster expansion. Precision fermentation capacity additions in Denmark represent the priority defensive lever against agricultural supply volatility. For New Entrants and Emerging Players: Launch via subscription-based formulation support models targeting mid-sized Italian yogurt manufacturers lacking in-house rheology expertise. Plant-based dairy analogues for oat and pea protein beverages present the most penetrable white space beyond traditional dairy. White-label enzymatic hydrocolloid modification services offer a direct go-to-market angle against incumbent application laboratories. For Investors and Strategic Acquirers: Roll-up economics work for fermentation-derived hydrocolloid specialists because EFSA qualification timelines entrench supplier relationships and compress competitive entry. Five-to-ten year viability hinges on precision platform scale and organic certification portfolio breadth. Acquisition targets should show integrated emulsifier-stabilizer bundling capability. The signal to watch is EU organic regulation enforcement intensity driving specification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Guar Supply Chains | Cargill's Rajasthan cluster presence secures volume commitments against Iberian locust bean shortages. |
| Precision Fermentation Platform Expansion | Corbion's Danish facilities produce gellan gum with certified non-GMO status independent of harvest cycles. |
| Subscription-Based Formulation Support | Palsgaard's multi-year contracts bundle regulatory documentation with emergency supply guarantees. |
| Enzymatic Hydrocolloid Modification | Wageningen cluster adoption reduces pectin dosage rates while maintaining identical mouthfeel profiles. |
| EU Organic Certification Investment | 2024 regulation updates mandate stricter additive restrictions, creating first-mover specification advantages. |
Research Methodology
Coverage spans Germany, France, Italy, the Netherlands, and the United States, with primary inputs from each market's dairy processing belt. The research combines interviews with formulation directors at integrated yogurt manufacturers, procurement leads at CPG companies, technical service heads at stabilizer suppliers, and regulatory affairs specialists navigating EFSA and FDA pathways. Secondary validation draws from EFSA novel food registers, FDA GRAS notifications, EU organic certification databases, and customs trade data for guar and locust bean gum flows. Bottom-up volume modeling and top-down value triangulation cross-check segment estimates.
Granularity extends to individual hydrocolloid chemistries by methoxylation grade and acyl content, with application-level modeling across yogurt, dairy dessert, cheese, and plant-based analogue segments. CAGRs derive from shipment volume analysis, capacity expansion announcements, and substitution elasticity estimates for clean-label reformulation cycles. Forecast inputs include EU F-Gas Regulation phase-down schedules, REACH substance restriction proposals, and precision fermentation platform commissioning timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under locust bean harvest failures or accelerated EFSA novel food restrictions. Outputs reflect documented assumptions about clean-label definition evolution and biobased feedstock verification adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
South Africa Food Additives Market
Food Additives and Ingredients
Wheat & Rice Flour Substitute-Resistant Starch Market
Food Additives and Ingredients
Acrylamide Reduction Market
Food Additives and Ingredients
Global Lutein and Lutein Esters Market
Food Additives and Ingredients
Olestra Market
Food Additives and Ingredients
Europe Food Acidulants Market
Food Additives and Ingredients
Gelatin Films Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
China Anti-Caking Market
Food Additives and Ingredients
Sugar Reduction Technology Market
Food Additives and Ingredients
Argentina Sodium Reduction Ingredient Market
Food Additives and Ingredients
Fruit and Vegetable Processing Enzymes Market
Food Additives and Ingredients
Carob Gum Market
Food Additives and Ingredients
Scrambled Egg Mix Market
Food Additives and Ingredients
Erythorbic Acid Market
Food Additives and Ingredients
North America Food Acidulants Market