
 Food Protein Ingredient Market | 2026-2036
Food Protein Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Food Protein Ingredient Market Analysis
Modular protein bundling—combining isolates, hydrolysates, and flavor masking systems into single-ingredient platforms—is hardening buyer expectations for turnkey solutions. Cargill, Incorporated leverages its oilseed processing network to secure non-GMO soy protein supply chains across North America. Kerry Group competes through taste and texture expertise that reduces reformulation cycles for beverage clients. Glanbia Nutritionals anchors its position in sports nutrition through backward integration into Irish and US dairy fractionation.
Food protein ingredients comprise concentrated or isolated protein fractions extracted from animal, plant, microbial, or insect biomass, typically standardized to 80–90% protein content by dry weight and functionalized for solubility, emulsification, or gelation in processed foods. Their primary commercial purpose is to fortify nutritional profiles, replace traditional protein sources, and enable texture engineering in formulated consumer products. Animal-based proteins still dominate value pools in dairy and infant nutrition, while plant-based sources represent the fastest-growing margin corridor as beverage brands reformulate for flexitarian consumers. Application-led demand in meal replacements concentrates purchasing power among contract manufacturers serving weight-management and clinical nutrition channels.
FDA nutrition labeling requirements, EFSA health claim protocols, and China's GB standards for plant protein beverages collectively elevate analytical rigor around protein quality scoring and amino acid completeness. These frameworks compel ingredient suppliers to invest in digestibility-corrected amino acid scoring and region-specific dossier preparation. Stakeholders must monitor evolving regulatory definitions of protein quality as jurisdictions adopt divergent measurement methodologies that could fragment formulation strategies and complicate cross-border product registration.
Market Dynamics
Modular protein bundling is hardening buyer expectations for turnkey ingredient platforms that combine isolates, hydrolysates, and flavor masking systems into single-procurement solutions, compressing supplier margins and rewarding integrated formulation capabilities.
Growth Catalysts
- Digestibility-Corrected Amino Acid Scoring:FDA's updated nutrition labeling rules for protein quality are forcing reformulation investments that favor suppliers with advanced analytical capabilities and complete amino acid profiling.
- Flexitarian beverage reformulation:Plant-based dairy alternatives in the United States are accelerating procurement of pea and oat protein isolates as major brands retool production lines for hybrid protein systems.
- Sports nutrition contract manufacturing:Meal replacement and weight-management channels are concentrating purchasing power among toll manufacturers serving clinical nutrition and athletic performance end-uses.
Market Restraints
- Input cost volatility in dairy fractionation:Whey protein concentrate and isolate production faces margin pressure from fluid milk price swings and energy-intensive ultrafiltration operations.
- Supply concentration in North American oilseed processing:Non-GMO soy protein isolates depend on a limited number of crushing facilities with identity-preserved handling infrastructure.
- Regulatory fragmentation in protein quality measurement:Divergent methodologies between FDA, EFSA, and China's GB standards complicate cross-border product registration and dossier preparation costs.
Strategic Opportunities
- Precision fermentation proteins:Microbial biomass platforms using single-cell organisms are opening novel ingredient categories with complete amino acid profiles and minimal agricultural land use.
- Clinical nutrition channel expansion:Medical foods and enteral nutrition applications represent underpenetrated demand for hydrolyzed protein systems with documented digestibility data.
- EU Green Deal sustainable protein incentives:Farm-to-fork strategy funding and carbon labeling requirements are creating procurement preference for regionally sourced legume proteins with verified lifecycle data.
Industry Challenges
- Flavor masking R&D talent scarcity:Formulation chemists capable of integrating bitter-blocking technologies with protein systems command premium compensation and limited availability.
- Dual certification timeline compression:Simultaneous pursuit of organic certification and non-GMO verification extends supplier qualification cycles by 12-18 months.
- Legacy dairy equipment retrofit costs:Fractionation facilities require substantial capital expenditure to pivot between whey and emerging plant protein processing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Protein Ingredient Market |
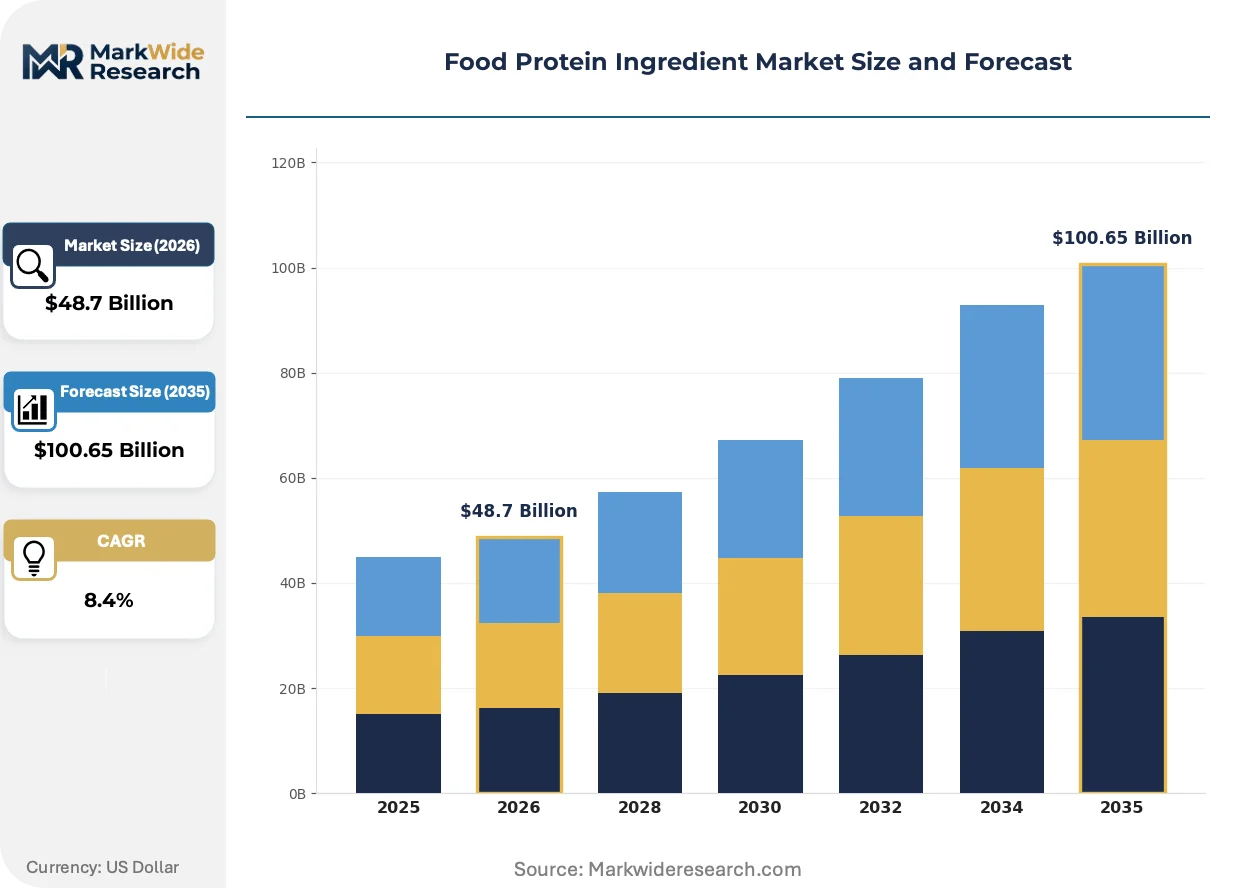
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Soy Protein, Casein Protein, Pea Protein Application: Beverages, Snacks, Dairy Products, Meal Replacements Source: Animal-Based, Plant-Based, Microbial, Insect-Based Form: Powder, Isolate, Concentrate, Hydrolysate |
| Companies Covered | Archer Daniels Midland, Cargill, Incorporated, Roquette Frères, Glanbia Nutritionals, Kerry Group, Fonterra Co-operative Group, Ingredion Incorporated, DuPont de Nemours, Inc., Kewpie Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Protein Ingredient Market Emerging Trajectories
Protein ingredient markets are experiencing simultaneous pressure from regulatory precision requirements, biological production platform advances, and procurement consolidation among contract manufacturers serving branded consumer goods companies.
Precision fermentation-derived proteins are absorbing investment from ingredient suppliers seeking to bypass agricultural commodity cycles entirely. Startups and established players alike are commissioning pilot facilities for fungal and bacterial biomass production. This technology is absorbing capital that previously flowed into conventional extraction capacity, reshaping long-term supply assumptions.
EFSA health claim protocols and China's GB standards for plant protein beverages are elevating analytical rigor around amino acid completeness and digestibility scoring. Ingredient suppliers must now maintain region-specific dossiers and invest in clinical validation studies. Sports nutrition and infant formula categories face the steepest compliance burdens as they operate under the strictest quality thresholds.
Contract manufacturers serving weight-management and clinical nutrition channels are consolidating procurement decisions and demanding integrated formulation support rather than commodity protein supply. Direct relationships between ingredient platforms and finished goods brands are displacing traditional distributor networks. This concentration is most visible in the United States, where clean-label product launches accelerate ingredient co-development partnerships.
Food Protein Ingredient Market Segmentation
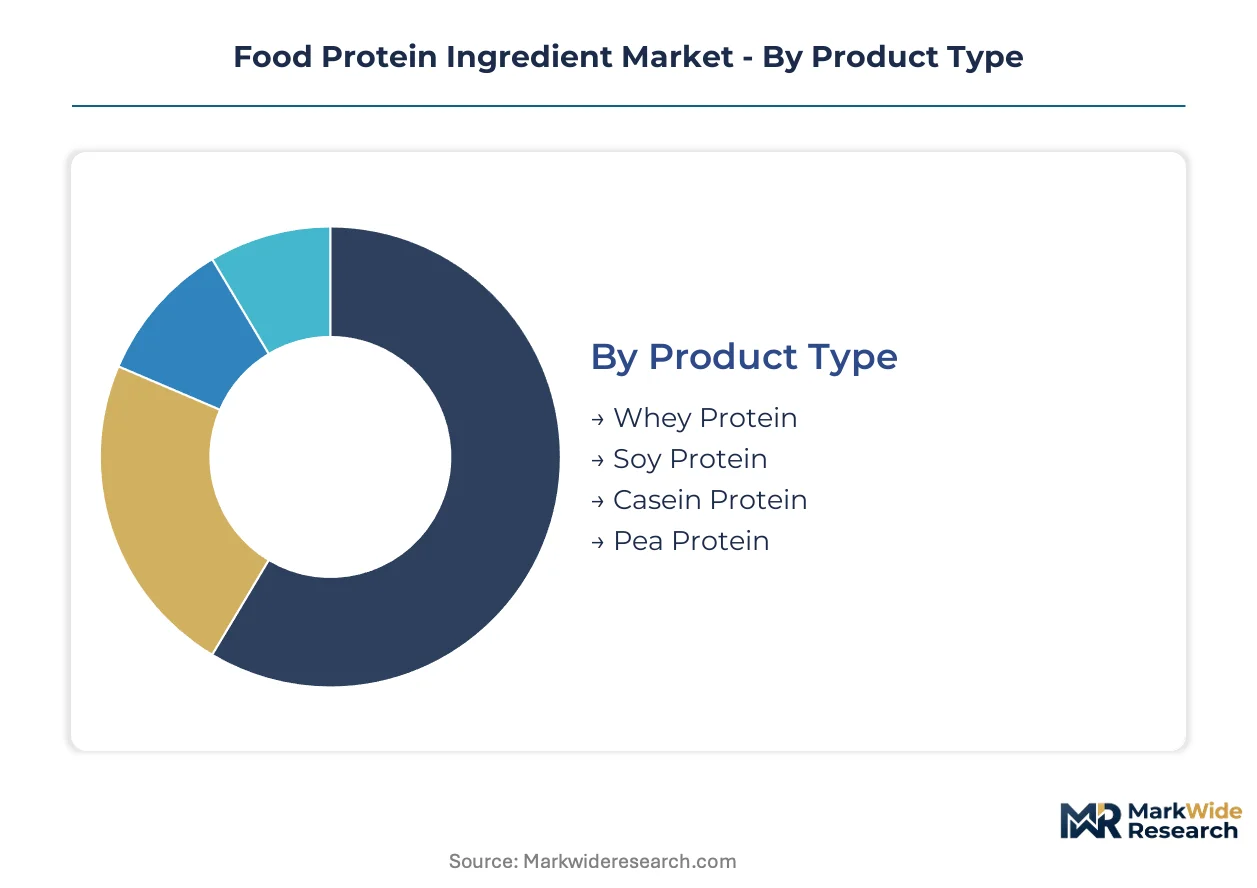
Protein ingredient procurement splits sharply between standalone commodity supply and embedded formulation partnerships, with contract manufacturers consolidating purchasing across multiple segment dimensions simultaneously. Understanding where each segment sits on this integration spectrum determines supplier strategy and margin capture potential.
Product Type:
Standalone protein commodities dominate spot purchasing, while hydrolyzed and isolate grades increasingly move through embedded formulation contracts with integrated masking systems.
- Whey Protein:Fractionated dairy proteins standardized to 80-90% protein content with established solubility profiles for sports nutrition. Demand concentrates among US contract manufacturers serving meal replacement brands facing FDA protein quality scoring requirements that favor complete amino acid profiles.
- Pea Protein:Legume isolates from yellow split peas with neutral pH solubility and emulsification properties engineered for plant-based dairy alternatives. Beverage brands in the United States are accelerating procurement as production lines retool for hybrid protein systems combining multiple plant sources.
- Soy Protein:Oilseed isolates and concentrates from identity-preserved non-GMO supply chains with functional gelation properties for meat analogues.
- Casein Protein:Slow-digesting micellar fractions from skim milk with sustained amino acid release profiles for overnight recovery formulations.
Whey protein leads volumes today; pea protein is gaining share fastest.
Application:
Cost tier stratification separates premium clinical nutrition channels from mass-market beverage applications, with procurement concentration highest where formulation complexity demands technical partnership.
- Meal Replacements:Complete nutrition systems requiring precise macronutrient balancing and documented digestibility data for weight-management and clinical channels. Toll manufacturers serving these end-uses are consolidating purchasing power and demanding integrated formulation support rather than commodity supply.
- Beverages:Ready-to-drink and powder formats with stringent solubility and flavor masking requirements driving co-development partnerships between ingredient platforms and finished goods brands.
- Snacks:Extruded and baked applications where protein fortification must balance texture engineering with shelf stability requirements.
- Dairy Products:Traditional yoghurt and cheese systems where protein ingredients enable standardization and functional modification of native milk proteins.
Meal replacements command premium pricing tiers; beverages show steepest expansion trajectory.
Source:
Supply concentration varies dramatically by biomass origin, with animal-based proteins anchored in established dairy fractionation infrastructure and novel sources requiring entirely new production platforms.
- Animal-Based:Dairy and egg protein fractions with complete amino acid profiles and established digestibility credentials dominating infant formula and sports nutrition value pools.
- Plant-Based:Legume, cereal, and oilseed proteins representing the fastest-growing margin corridor as flexitarian consumers drive beverage reformulation across North American and European markets.
- Microbial:Precision fermentation platforms using fungal and bacterial biomass to bypass agricultural commodity cycles entirely, with pilot facilities absorbing capital previously directed toward conventional extraction capacity.
- Insect-Based:Larval and cricket flour proteins with favorable feed conversion ratios still awaiting regulatory clarity in major Western markets.
Animal-based proteins anchor current revenue; microbial sources are climbing the fastest.
Form:
Processing intensity determines functional properties and procurement integration depth, with hydrolysates and isolates commanding formulation partnerships while powders flow through commodity channels.
- Isolate:Highly refined fractions exceeding 90% protein content with minimal carbohydrate and lipid contamination, essential for ketogenic and clinical nutrition applications requiring precise macronutrient control.
- Hydrolysate:Enzymatically pre-digested proteins with reduced allergenicity and accelerated gastric emptying, capturing premium positioning in medical foods and enteral nutrition where documented digestibility data is mandatory.
- Concentrate:Intermediate purification grades retaining some native functionality while offering cost advantages for mass-market fortification.
- Powder:Bulk commodity formats with standardised particle size and flow properties for industrial-scale blending operations.
Isolates dominate premium procurement; hydrolysates are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy fractionation infrastructure first scaled in the United States and Europe during the 1970s whey protein boom, establishing processing know-how that now diffuses into plant protein and microbial platforms across multiple continents.
United States
Sports nutrition contract manufacturers and flexitarian beverage brands drive procurement of whey isolates and pea protein systems. FDA nutrition labeling rules for protein quality scoring compel suppliers to invest in digestibility-corrected amino acid profiling. Chicago and Minneapolis-St. Paul anchor dairy fractionation clusters where toll manufacturers consolidate purchasing for meal replacement channels.
China
Domestic brands reformulate plant-based dairy alternatives using soy and pea protein isolates for urban flexitarian consumers. GB standards for plant protein beverages mandate amino acid completeness testing that elevates analytical requirements for ingredient imports. Yangtze River Delta processing hubs near Shanghai concentrate oilseed crushing capacity with identity-preserved handling infrastructure.
Germany
EU Green Deal farm-to-fork strategy funding accelerates regional legume protein sourcing with verified lifecycle data for carbon labeling compliance. EFSA health claim protocols demand clinical validation studies that extend supplier qualification timelines. Bavaria and North Rhine-Westphalia host precision fermentation pilot facilities absorbing capital previously directed toward conventional extraction.
India
Domestic dairy cooperatives expand whey fractionation capacity to serve emerging sports nutrition and clinical nutrition demand. FSSAI standards for protein fortification in processed foods tighten quality thresholds for imported isolates. Gujarat and Maharashtra concentrate oilseed processing infrastructure with growing non-GMO soy protein output for regional beverage manufacturers.
Brazil
Meat analogue startups procure soy protein concentrates from domestic oilseed crushers with established gelation expertise for textured vegetable protein applications. ANVISA regulations for novel protein ingredients in functional foods create compliance pathways for emerging microbial biomass platforms. São Paulo state anchors formulation partnerships between ingredient suppliers and multinational consumer goods brands.
Food Protein Ingredient Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation integration depth, with turnkey solution providers capturing value that basic isolate suppliers forfeit. The vendor base clusters around three strategic archetypes: diversified agribusiness conglomerates with oilseed processing networks, dairy cooperatives with backward integration into fractionation, and specialized taste-texture houses with flavor masking intellectual property. Dominant competitive moves include portfolio diversification into hybrid protein systems and geographic expansion through toll manufacturing partnerships in high-growth beverage markets.
Within the diversified agribusiness tier, Cargill, Incorporated and Archer Daniels Midland exemplify players leveraging North American oilseed crushing infrastructure to secure non-GMO supply chains. Glanbia Nutritionals anchors the dairy cooperative archetype with Irish and US fractionation assets. Kerry Group occupies a position among taste-texture specialists competing through integrated formulation support that compresses client reformulation cycles.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Cargill, Incorporated |
| Roquette Frères |
| Glanbia Nutritionals |
| Kerry Group |
| Fonterra Co-operative Group |
| Ingredion Incorporated |
| DuPont de Nemours, Inc. |
| Kewpie Corporation |
| Others |
Supply Flow & Price Mechanics
EU Green Deal farm-to-fork carbon labeling requirements gate qualified supply for premium-tier protein ingredients, compressing margins for suppliers lacking verified lifecycle data while rewarding North American and European processors with identity-preserved handling infrastructure. Buyers face bifurcated procurement economics where sustainability credentials command pricing power in contract manufacturing channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates hydrolyzed isolates with clinical validation from commodity concentrates and bulk powders. Certification grade and volume scale drive price differentiation, with FDA-compliant amino acid profiling and organic-non-GMO dual certification commanding substantial premia. Cost compression in standard-tier whey concentrates is intensifying because fluid milk price volatility feeds directly into fractionation economics. Contract manufacturers serving meal replacement channels show least price sensitivity, while mass-market beverage blenders prioritize economy-tier procurement.
Supply Chain Analysis
Dual certification timelines for organic and non-GMO verification extend supplier qualification cycles, concentrating qualified supply among established North American and European processors with dedicated identity-preserved infrastructure. Raw material flows draw from fluid milk cooperatives in the United States and Ireland, yellow split pea processors in Canada and France, and non-GMO soy crushing facilities in the United States and Brazil. Single-source vulnerability in North American oilseed processing creates structural exposure to capacity constraints at identity-preserved handling sites. Distribution runs through toll manufacturing partnerships that consolidate procurement decisions for branded consumer goods companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food protein ingredient markets function as a geographic-arbitrage play where EU carbon labeling compliance costs and FDA amino acid profiling requirements create divergent cost structures between European and North American supply bases.
For Market Incumbents: Anticipate precision fermentation platforms eroding agricultural commodity exposure by commissioning pilot facilities for microbial biomass production before capital allocation shifts decisively. Deepen backward integration into Irish and US dairy fractionation to defend whey protein margins against fluid milk price volatility. Secure non-GMO soy supply chains through long-term crushing partnerships with identity-preserved handling infrastructure.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in hydrolyzed protein systems creates entry space for clinical nutrition specialists with documented digestibility data. Target medical foods and enteral nutrition applications where EFSA health claim protocols have thinned incumbent presence. Pursue co-development partnerships with contract manufacturers rather than commodity supply relationships to bypass entrenched distributor networks.
For Investors and Strategic Acquirers: Roll-up economics work for taste-texture specialists with flavor masking intellectual property because formulation integration demands are consolidating procurement decisions among toll manufacturers. Five-to-ten year viability favors platforms with hybrid protein system capabilities spanning animal, plant, and microbial sources. Watch FDA protein quality scoring adoption rates as the inflection indicator for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial biomass platforms bypass agricultural commodity cycles entirely. |
| Dual Certification Investment | Organic and non-GMO verification opens premium contract manufacturing channels. |
| Clinical Validation Studies | Documented digestibility data satisfies EFSA health claim protocol requirements. |
| Regional Legume Sourcing Partnerships | EU Green Deal funding rewards verified lifecycle carbon data. |
| Flavor Masking R&D Expansion | Bitter-blocking technology integration compresses client reformulation cycles. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ingredient procurement directors at contract manufacturers, formulation scientists at taste-texture houses, regulatory affairs leads at dairy cooperatives, and plant managers at oilseed crushing facilities with secondary validation against FDA nutrition labeling guidance documents, EFSA health claim registers, Chinese GB standards filings, and customs trade data for protein isolate imports. Bottom-up segment sizing and top-down market triangulation cross-checked volume assumptions.
Historical reference periods anchored the projection framework to established whey protein demand cycles and plant-based beverage reformulation trajectories across the analysis window. Segmentation modeling incorporated product type, application channel, biomass source, and processing form dimensions. CAGRs derived from elasticity-adjusted demand curves for sports nutrition, clinical nutrition, and flexitarian beverage end-uses, with input sensitivity around precision fermentation capacity buildout assumptions and regulatory adoption timelines for protein quality scoring methodologies.
Caveats apply where FDA amino acid profiling enforcement intensity, EU carbon labeling scope expansion, or precision fermentation regulatory clearance delays could materially shift the outlook. Deviation in contract manufacturer consolidation patterns would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Fermented Ingredient Market
Food Additives and Ingredients
Acetylated Monoglycerides (AMG) Market
Food Additives and Ingredients
North America Food Micronized Salt Market
Food Additives and Ingredients
Australia Food Additives Market
Food Additives and Ingredients
Argentina Food Preservatives Market
Food Additives and Ingredients
Lime Oil Market
Food Additives and Ingredients
Curcumin Food Color Market
Food Additives and Ingredients
Spain Food Acidulants Market
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
United Kingdom Food Acidulants Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
Carmine Alternatives Market
Food Additives and Ingredients
Sucroglycerides Market
Food Additives and Ingredients
Pet Food Emulsifier Market
Food Additives and Ingredients
United States Anti-Caking Market
Food Additives and Ingredients
Clean Label Emulsifiers Market