
 Planter Market | 2026-2036
Planter Market Size, Share, and Industry Trends Forecast 2026-2036
Planter Market Analysis
Residential landscaping is rebalancing toward container gardening and balcony farming as urban density rises and outdoor space shrinks. Deere & Company leverages its precision agriculture heritage to compete in smart planter systems for controlled-environment farming. AGCO Corporation anchors its position through ruggedized commercial-grade containers built for greenhouse operators. Kinze Manufacturing differentiates via specialized large-capacity planters engineered for industrial hydroponic facilities.
A planter is a horticultural container, typically constructed from terracotta, plastic, ceramic, or wood, designed to hold soil or growth media and support plant root systems in controlled or semi-controlled environments. Wall thickness, drainage porosity, and UV stabilization ratings determine performance lifespan and suitability for indoor versus outdoor deployment. Plastic dominates volume manufacturing due to injection-molding scalability and cost efficiency, though ceramic commands premium positioning in design-centric retail channels. Hydroponic usage represents the fastest-expanding structural segment as soilless cultivation systems penetrate commercial agriculture and consumer markets simultaneously.
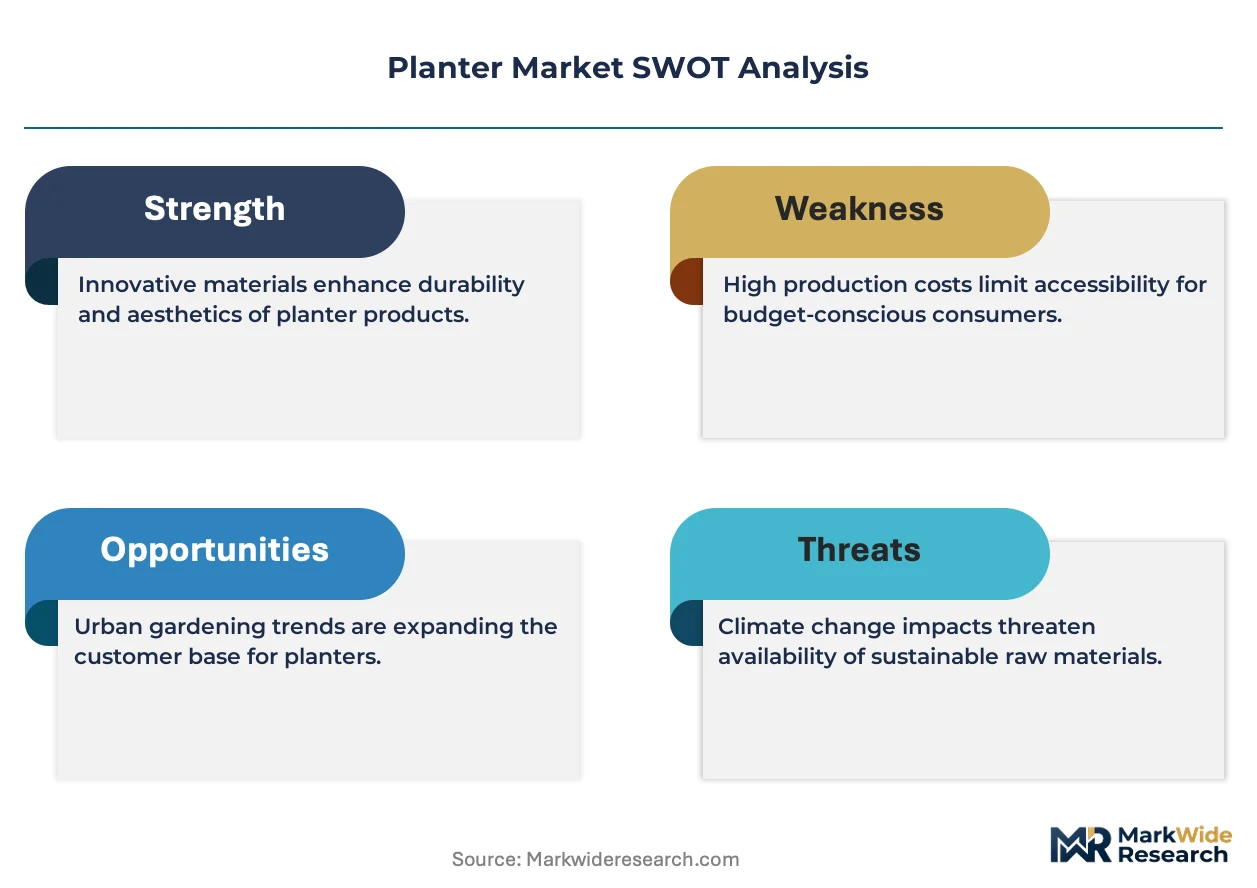
EPA guidelines on water runoff and irrigation efficiency shape planter design standards in the United States, while REACH chemical restrictions in Europe limit certain plasticizers and coatings in consumer-facing products. BIS certification requirements in India govern load-bearing specifications for vertical mounting systems used in urban greening programs. Stakeholders must monitor evolving material compliance thresholds and irrigation integration standards as municipalities tighten building-integrated vegetation mandates.
Market Dynamics
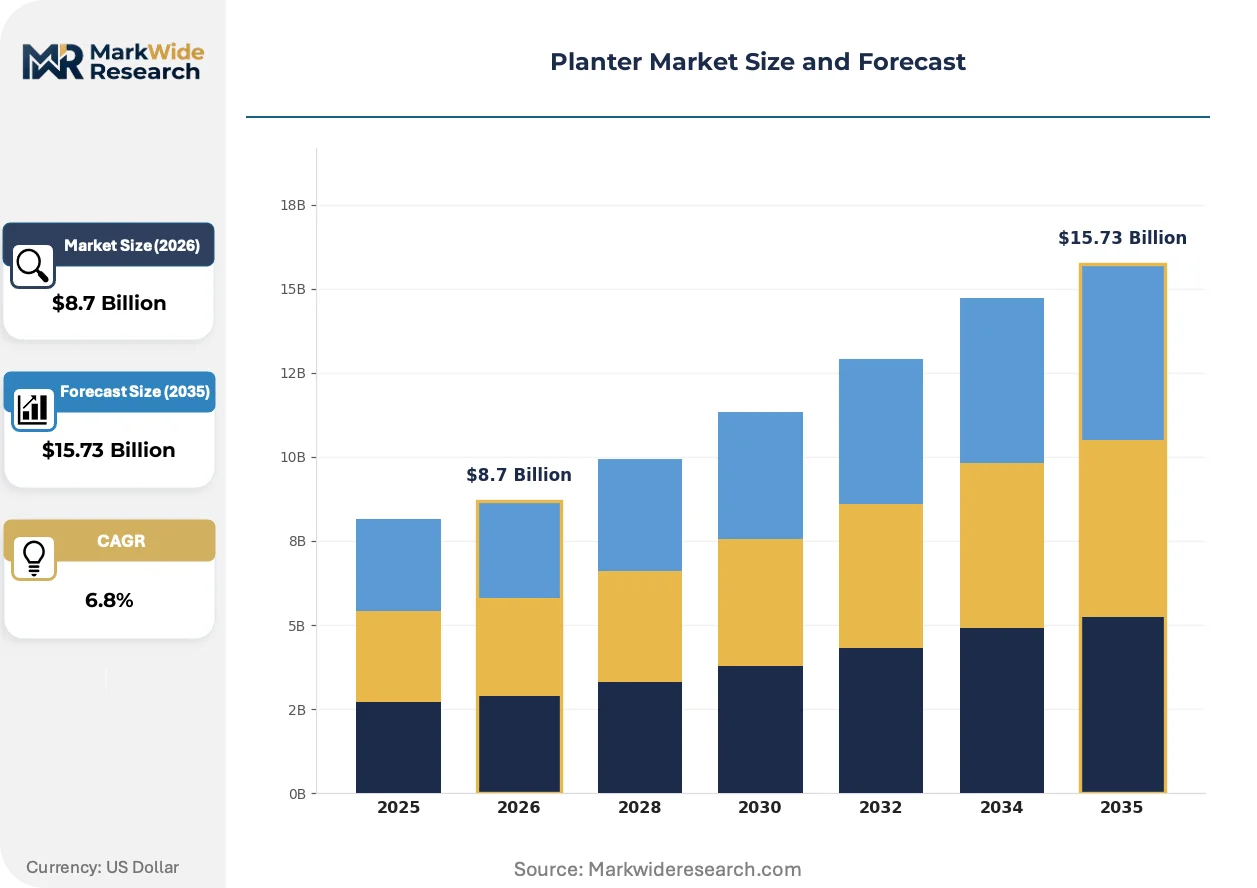
Container gardening is rebalancing residential demand as urban density compresses outdoor space availability, while regulatory pressure on water efficiency and material safety tightens design specifications across manufacturing bases.
Growth Catalysts
- EPA Water-Use Guidelines:United States irrigation efficiency mandates are accelerating adoption of self-watering and sub-irrigation planter systems in drought-prone municipalities.
- Hydroponic Cultivation:Soilless growing systems are penetrating commercial agriculture and consumer markets simultaneously, expanding addressable demand for specialized containers.
- China's Commercial Green Infrastructure:Urban greening mandates in tier-one cities are driving bulk procurement of large-format planters for building-integrated vegetation projects.
Market Restraints
- Petrochemical Input Volatility:Polypropylene and polyethylene resin prices fluctuate with crude oil indices, compressing margins for injection-molded plastic planter manufacturers.
- REACH Chemical Restrictions:European ECHA limitations on phthalate plasticizers and heavy-metal coatings force reformulation costs and supplier qualification delays.
- Clay and Terracotta Substitution:Premium ceramic containers face displacement from fiber-reinforced polymer alternatives offering comparable aesthetics at lower weight and breakage rates.
Strategic Opportunities
- Germany's Urban Horticulture Sector:Berlin and Hamburg balcony farming cooperatives present underpenetrated demand for modular vertical mounting systems.
- IoT-Integrated Irrigation Convergence:Sensor-enabled moisture monitoring and automated watering are creating premium product tiers in controlled-environment farming.
- India's BIS Certification Tailwind:Load-bearing specifications for vertical greening programs in Delhi and Mumbai are standardizing procurement criteria for engineered mounting hardware.
Industry Challenges
- Multi-Material Certification Timelines:Composite planters combining recycled plastics with natural fibers face extended testing protocols for UV stabilization and leachate safety.
- Hydroponic System Integration Complexity:Container manufacturers must coordinate nutrient delivery specifications with equipment suppliers lacking standardized connection interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Planter Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Terracotta, Plastic, Ceramic, Wooden Design Style: Modern, Rustic, Vintage, Minimalist Capacity: Small, Medium, Large, Extra Large Usage: Indoor, Outdoor, Vertical, Hydroponic |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial, Kinze Manufacturing, Bracke Group, Dawn Equipment Company, East Jordan Plastics, HC Companies, Mahindra and Mahindra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Planter Market Emerging Trajectories
Smart irrigation integration and sustainable material substitution are compressing traditional product lifecycles while opening premium positioning for technology-enabled containers.
Recycled ocean-bound polyethylene is unifying sustainability credentials with cost parity in injection-molding operations. Retail garden centers and municipal procurement offices are qualifying these materials at accelerated pace. This shift is unifying environmental marketing claims with actual supply chain traceability, compressing greenwashing tolerance among institutional buyers.
REACH chemical restrictions in Europe are forcing reformulation of UV stabilizers and colorants across the supplier base. Manufacturers serving EU markets must now qualify alternative additive packages or exit the geography. Decorative ceramic and premium plastic segments face the steepest compliance cost escalation as coating and pigmentation requirements tighten.
Direct-to-consumer subscription models for seasonal container rotations are disrupting traditional retail garden center channels. Urban apartment dwellers in dense North American and European cities are replacing one-time purchases with rental-and-refresh services. This pattern is most visible in London, New York, and Toronto, where space constraints favor turnkey solutions over ownership.
Planter Market Segmentation
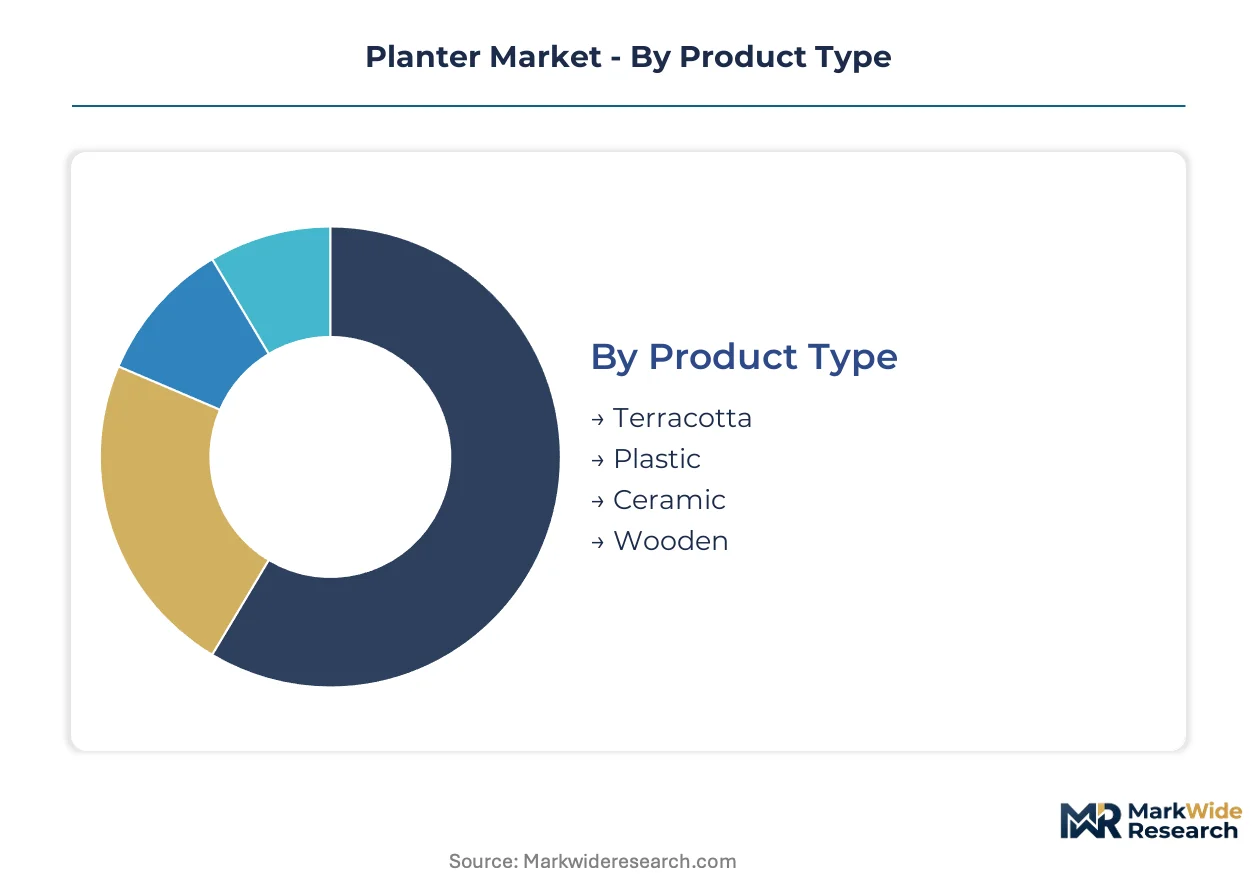
Planter segmentation reveals divergent manufacturing economics and compliance burdens across material classes and deployment contexts. Product type determines resin feedstock exposure versus kiln-energy intensity, while usage segmentation separates commodity residential volumes from precision-engineered commercial systems.
Product Type:
Customization intensity spans from standardized injection-molded commodity units to artisan-crafted ceramic vessels with batch-variable glazing.
- Plastic:Polypropylene and polyethylene homopolymer formulations dominate mass-market production through high-speed injection molding. Demand concentrates in United States big-box retail and German discount garden chains where REACH compliance costs are absorbed through volume scale. Margins compress when petrochemical indices spike.
- Terracotta:Fired clay construction delivers superior moisture wicking and root aeration for Mediterranean-climate horticulture. Italian and Spanish manufacturers anchor European supply, while Indian Rajasthani kilns serve price-sensitive Asian markets. ECHA heavy-metal limits on lead-based glazes force reformulation investments.
- Ceramic:Vitreous porcelain and stoneware variants command premium positioning in design-forward retail channels.
- Wooden:Cedar and teak planters serve aesthetic-driven outdoor landscaping with natural weathering characteristics.
Most installed capacity flows through Plastic. Expansion is steepest in Ceramic as sustainability credentials displace lower-tier alternatives.
Design Style:
Margin structures stratify sharply between mass-produced contemporary lines and craft-intensive heritage aesthetics.
- Modern:Clean geometric profiles in matte finishes align with urban apartment aesthetics and commercial building-integrated vegetation. Scandinavian and Japanese design houses drive specification in Berlin, Copenhagen, and Tokyo balcony farming projects. OEM partnerships with furniture retailers expand distribution.
- Minimalist:Reduced-form vessels emphasize negative space and monochromatic surfaces for gallery and hospitality settings.
- Rustic:Distressed woodgrain textures and irregular hand-finished surfaces target cottage and farmhouse exterior themes.
- Vintage:Reproduction patinas and classical ornamentation serve heritage property restoration and themed hospitality.
Production gravity sits with Modern. Fastest share gains accrue to Minimalist as luxury residential towers specify coordinated interior-exterior planting systems.
Capacity:
Logistics costs and last-mile handling constraints reconfigure competitive advantage across dimensional tiers.
- Large:Containers exceeding 50-liter soil volume require reinforced sidewall engineering for tree and shrub installation. Municipal greening contracts in Shanghai, Shenzhen, and Chengdu specify these formats for streetscape tree pits. Flat-pack knockdown designs reduce shipping cube.
- Extra Large:Custom-engineered planters for commercial atriums and rooftop gardens demand structural load certification.
- Small:Desktop and windowsill formats prioritize retail impulse placement and e-commerce parcel compliance.
- Medium:Balcony rail and patio formats balance portability with sufficient root zone for perennial displays.
Volume throughput peaks in Medium. Steepest expansion trajectory belongs to Large as urban greening mandates proliferate.
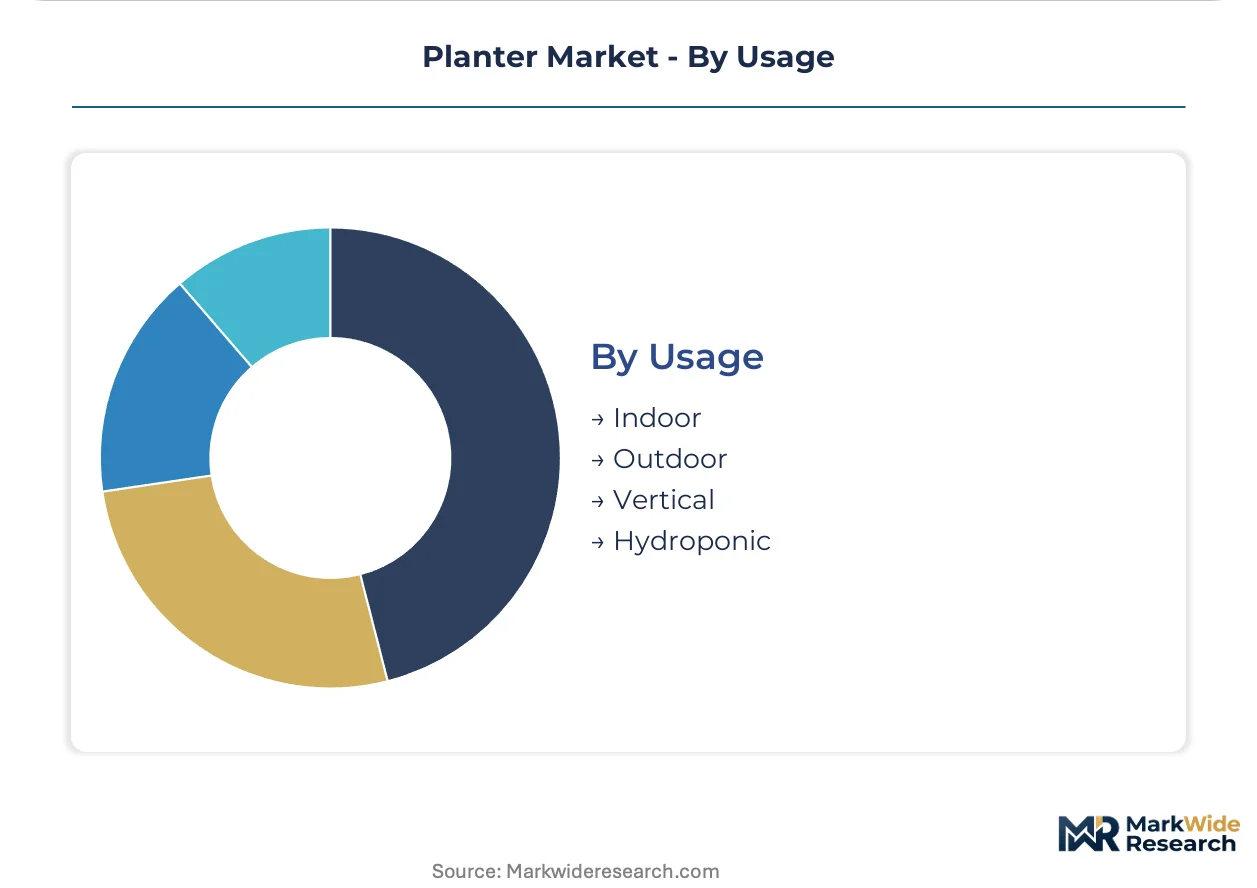
Usage:
Performance specifications diverge between passive soil containers and active hydroponic systems with integrated irrigation.
- Hydroponic:Soilless cultivation vessels incorporate nutrient film technique channels, aeroponic misting manifolds, or deep-water culture reservoirs. Netherlands greenhouse operators and Chinese plant factory ventures drive specification for food-grade polymer construction with UV stabilization. SAMR food-contact approvals govern import eligibility.
- Vertical:Modular stacking and wall-mounting systems maximize planting density in constrained urban footprints. BIS load-bearing certification for Delhi and Mumbai vertical greening programs standardizes mounting hardware procurement. Fiber-reinforced polymer substitutes displace terracotta weight penalties.
- Indoor:Leak-proof saucers and furniture-friendly finishes prioritize residential living room and office deployment.
- Outdoor:Frost-thaw cycling resistance and drainage porosity dominate material selection for temperate climate exposure.
Current installation base concentrates in Outdoor. Technology-enabled formats in Hydroponic are climbing the fastest as controlled-environment agriculture scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as REACH compliance costs in Europe and EPA water-efficiency mandates in North America create divergent cost-of-compliance gaps. Producers are migrating capacity toward jurisdictions with lighter chemical restrictions while maintaining export-qualified product lines for regulated markets.
United States
EPA irrigation-efficiency guidelines are accelerating self-watering planter adoption in drought-prone municipalities across California and Arizona. The agency's water-use mandates are tightening specifications for residential and commercial outdoor containers. Dallas and Phoenix municipal procurement offices are specifying sub-irrigation systems for streetscape greening contracts.
Germany
Urban horticulture cooperatives in Berlin and Hamburg are driving modular vertical mounting demand for balcony farming applications. ECHA REACH restrictions on phthalate plasticizers are forcing reformulation investments among injection-molded suppliers. The Ruhr industrial corridor hosts concentrated manufacturing capacity serving discount garden chains across the EU.
China
SAMR food-contact approvals are governing import eligibility for hydroponic cultivation vessels in controlled-environment agriculture. Urban greening mandates in Shanghai, Shenzhen, and Chengdu are driving bulk procurement of large-format planters for building-integrated vegetation. The Yangtze River Delta cluster dominates export-oriented ceramic and engineered polymer production.
India
BIS load-bearing certification requirements are standardizing procurement criteria for vertical greening programs in Delhi and Mumbai. Rajasthani kiln operations supply price-sensitive terracotta demand across Asian markets. Maharashtra and Gujarat industrial zones are scaling fiber-reinforced polymer substitutes to displace ceramic weight penalties in urban mounting systems.
Netherlands
Greenhouse operators in the Westland region are specifying food-grade polymer construction with UV stabilization for nutrient film technique applications. The country's national environmental regulator enforces strict leachate testing for containers used in commercial food production. Rotterdam port logistics facilitate re-export of hydroponic system components to European plant factory ventures.
Planter Market Vendor Landscape
Strategic partnerships dominate the current landscape as fabricators align with irrigation technology providers and furniture retailers to capture specification in building-integrated vegetation projects. The vendor base stratifies across three tiers: precision-agriculture heritage players with smart-system capabilities, commodity injection-molders serving big-box retail, and artisan ceramic houses targeting design-forward channels. Two competitive vectors define positioning: backward integration into resin compounding to manage petrochemical input volatility, and geographic expansion into municipal procurement offices in tier-one Chinese cities.
Among heritage agricultural equipment manufacturers, Deere & Company and AGCO Corporation exemplify the precision-system archetype, leveraging controlled-environment farming expertise to compete in sensor-enabled container segments. Kinze Manufacturing occupies a position within the specialized large-capacity tier, while CNH Industrial anchors the diversified industrial portfolio archetype. These named entities represent strategic positioning patterns rather than specific market share claims.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial |
| Kinze Manufacturing |
| Bracke Group |
| Dawn Equipment Company |
| East Jordan Plastics |
| HC Companies |
| Mahindra and Mahindra |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between REACH-compliant EU-qualified lines and non-certified commodity production splits pricing power and sourcing geography simultaneously. Premium ceramic and engineered polymer planters command 40-60% distributor markups through design-forward retail channels, while injection-molded polypropylene units move through high-volume discount chains with compressed margins.
Pricing Analysis
Distributor margin layers absorb the steepest cost differentials between premium and commodity tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, UV stabilization grade, and IoT integration depth. Cost compression in standard-grade plastic planters is intensifying because petrochemical index volatility erodes manufacturer margins. Municipal procurement offices in drought-prone US states exhibit lowest price sensitivity due to EPA mandate compliance requirements, while German discount garden chains drive hardest bargain on volume commitments.
Supply Chain Analysis
Single-source vulnerability sits with Yangtze River Delta ceramic clusters and Ruhr corridor injection-molding capacity for EU-qualified production. Manufacturing draws from Italian and Spanish terracotta kilns, Indian Rajasthani clay operations, and Chinese polymer compounding facilities. Raw material dependencies span polypropylene resin, kaolin clay, and cobalt-based colorants. Tariff exposure on Chinese ceramic imports into the United States threatens cost structures for design-forward retailers. Distribution runs through big-box retail consolidation in North America, specialized garden center networks in Europe, and direct municipal procurement in Chinese tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Europe and EPA water-efficiency mandates in the United States create divergent cost-of-compliance gaps against lighter-regulated Asian manufacturing bases.
For Market Incumbents: Hedge petrochemical input exposure through backward integration into resin compounding or long-term offtake agreements with Middle Eastern feedstock suppliers. Defend against fiber-reinforced polymer substitution in premium ceramic segments by accelerating SAMR food-contact certification for hydroponic vessel exports to Chinese plant factory ventures. Prioritize capacity addition in Gujarat and Maharashtra industrial zones to capture BIS-certified vertical mounting demand in Indian urban greening programs. For New Entrants and Emerging Players: Capture modular vertical mounting white space in Berlin and Hamburg balcony farming cooperatives where incumbent coverage remains thin. Target India's BIS certification tailwind in Delhi and Mumbai vertical greening procurement as the most penetrable regulatory-driven demand pocket. Lead with direct-to-consumer subscription models for seasonal container rotations in London, New York, and Toronto dense apartment markets. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH reformulation costs and petrochemical margin compression simultaneously stress mid-tier injection-molders without scale or premium positioning. Long-term viability favors asset-light subscription service operators and precision-agriculture heritage players with IoT integration capabilities over commodity ceramic fabricators facing clay substitution. Watch Chinese urban greening mandate acceleration in Shenzhen and Chengdu as the signal indicating inflection in large-format planter demand.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation Investment | ECHA chemical restrictions force additive package qualification or EU market exit. |
| IoT-Integrated Irrigation Convergence | Sensor-enabled moisture monitoring creates premium tiers in controlled-environment farming. |
| Recycled Ocean-Bound Polyethylene Adoption | Sustainability credentials unify with cost parity in injection-molding operations. |
| Direct-to-Consumer Subscription Launch | Seasonal container rotations disrupt traditional retail garden center channels. |
| BIS Certification Pathway Completion | Load-bearing specifications standardize procurement for Indian vertical greening programs. |
Methodological Framework
Direct dialogue with injection-molding plant managers, ceramic kiln operators, municipal procurement officers, and greenhouse system integrators grounded qualitative findings in operational reality. Secondary validation drew from EPA water-use guideline filings, ECHA REACH restriction updates, SAMR food-contact approval databases, and BIS certification registries. Bottom-up demand modeling across product type, design style, capacity tier, and usage segmentation triangulated against top-down macroeconomic indicators.
Bottom-up volume builds aggregated individual segment trajectories across plastic, terracotta, ceramic, and wooden material classes, while top-down cross-checks validated aggregate market scale against petrochemical consumption patterns and kiln energy intensity benchmarks. Segmentation dimensions spanned product type, design style, capacity tier, and usage context including hydroponic, vertical, indoor, and outdoor deployment. CAGRs were derived from regression analysis of historical volume trends against regulatory mandate implementation timelines and urban density projections. Industry-specific forecast inputs incorporated REACH compliance cost curves and Chinese urban greening mandate procurement schedules.
Petrochemical index volatility, ECHA chemical restriction scope expansion, and Chinese municipal procurement budget allocation shifts are the dominant revision risks to modeled trajectories. Forecasts reflect documented assumptions regarding regulatory implementation pace and substitution elasticity between material classes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Sheep Shearing Equipment Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Cotton Picker Market
Agricultural Equipment
North America Electric Zero Turn Mower Market
Agricultural Equipment
Heavy Tooth Drag Harrows Market
Agricultural Equipment
Harrows Market
Agricultural Equipment
Agriculture Seeder Market
Agricultural Equipment
Gardening Tools Market
Agricultural Equipment
Agricultural Rake Market
Agricultural Equipment
Solar Fruit Dryer Market
Agricultural Equipment
Billhook Market
Agricultural Equipment
Wet Fertilizer Spreaders Market
Agricultural Equipment
Wheelbarrow Market
Agricultural Equipment
Battery Powered Sprayer Market
Agricultural Equipment
Commercial Vegetable Chopper Market