
 North America Brewing Enzymes Market | 2026-2036
North America Brewing Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Brewing Enzymes Market Analytics
The gap between premium craft formulations and commodity lager production is broadening across North American brewing operations. Novozymes A/S dominates microbial enzyme supply for large-scale breweries seeking process standardization. DuPont de Nemours, Inc. leverages its biotechnology portfolio to serve craft producers demanding specialized amylase blends. Kerry Group anchors liquid enzyme distribution through its North American food ingredient infrastructure.
Brewing enzymes comprise protein catalysts—primarily amylases, proteases, and cellulases—derived from microbial fermentation that accelerate starch conversion, protein modification, and cell wall degradation during malting and mashing. These biocatalysts operate at specific temperature and pH ranges to optimize extract yield, filtration speed, and fermentation efficiency in beer manufacturing. Amylase formulations command the largest product share due to their essential role in converting grain starches to fermentable sugars, while liquid enzyme preparations lead the form category because of easier dosing integration and storage stability in commercial brewhouses. Craft breweries represent the fastest-growing end-user segment as smaller batch sizes and experimental recipes drive demand for flexible, high-activity enzyme systems.
The FDA oversees enzyme safety through GRAS notifications and food additive regulations, while the Alcohol and Tobacco Tax and Trade Bureau enforces labeling and production standards that influence enzyme disclosure requirements. Health Canada and PMRA maintain parallel approval pathways for enzymes used in Canadian brewing facilities, creating a dual-compliance environment for cross-border suppliers. Stakeholders must monitor evolving enzyme classification protocols and brewing innovation tax incentives at the federal and provincial levels to anticipate procurement cost shifts and formulation flexibility.
Market Dynamics
Craft brewery proliferation across the United States and Canada is compressing enzyme procurement cycles, forcing suppliers to deliver smaller-batch formulations with faster technical support turnaround than traditional lager operations require.
Growth Catalysts
- FDA GRAS Pathway:The FDA's streamlined GRAS notification process for food-grade enzymes accelerates new product introductions by reducing pre-market approval timelines for North American brewers.
- Gluten-Reduced Formulation Demand:Consumer preference for gluten-reduced beer variants drives protease enzyme adoption across craft and mid-size facilities seeking expanded product portfolios.
- Great Lakes Brewing Cluster:Concentrated brewing infrastructure in Michigan and Wisconsin generates sustained bulk enzyme demand that justifies regional distribution center investments.
Market Restraints
- Input Cost Volatility:Fermentation-derived enzyme production faces feedstock price swings in corn steep liquor and soybean meal used for microbial cultivation.
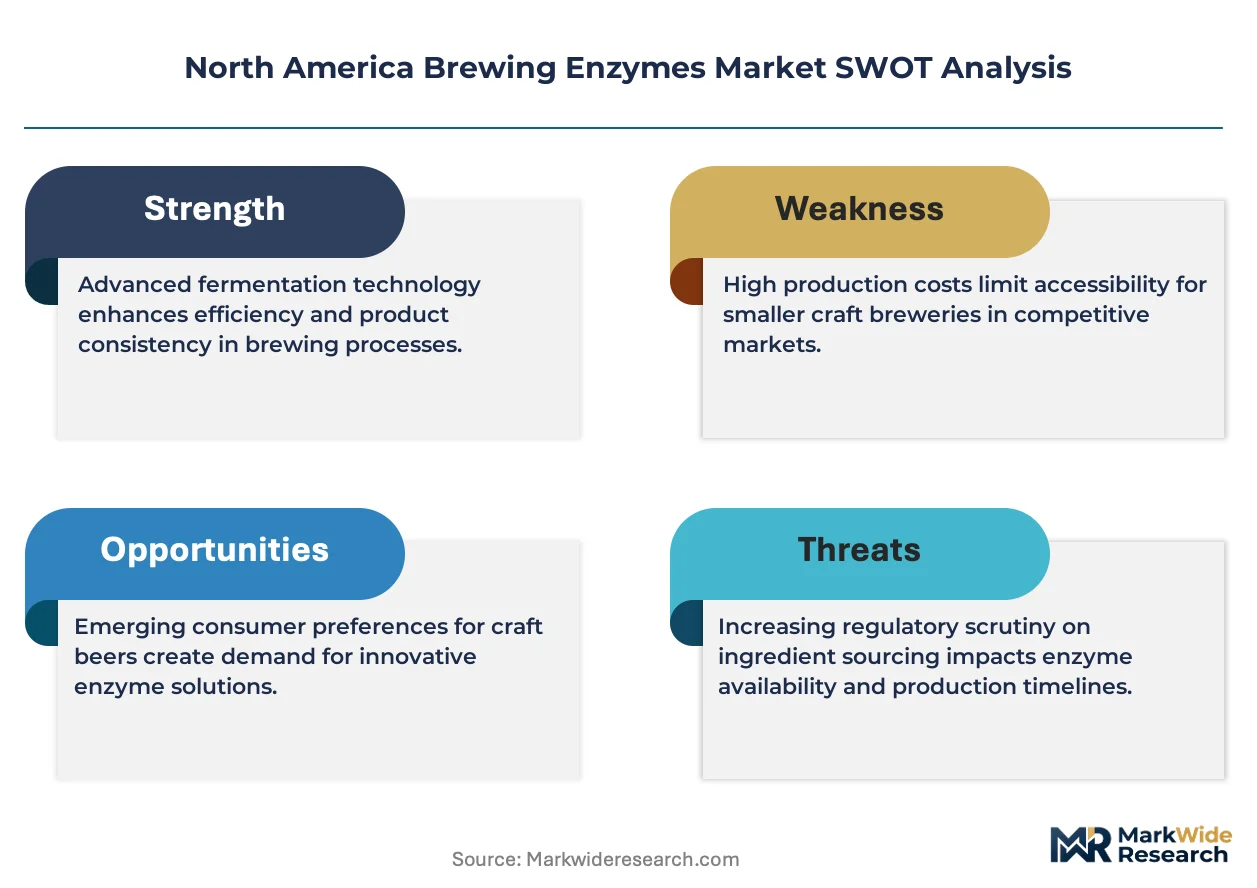
- Supplier Concentration Risk:Microbial strain IP and large-scale fermentation capacity concentrate among a handful of biotechnology suppliers, limiting buyer negotiating leverage.
- Technical Substitution Limits:Traditional malting processes in heritage-style breweries resist full enzyme substitution due to flavor profile requirements and operational inertia.
Strategic Opportunities
- Canadian Prairie Expansion:Saskatchewan and Alberta malt barley production growth creates localized enzyme blending opportunities serving prairie-based brewing facilities.
- Health Canada Streamlined Approvals:PMRA alignment initiatives with FDA enzyme safety assessments promise faster cross-border product registration for suppliers.
- Liquid Enzyme Cold-Chain Innovation:Refrigerated logistics partnerships with North American food ingredient distributors extend liquid enzyme shelf stability into remote brewing markets.
Industry Challenges
- Brewing Biochemist Talent Scarcity:Craft facilities lack in-house enzyme optimization expertise, creating dependency on supplier technical service teams for mash protocol design.
- Dual-Compliance Certification Burden:Parallel FDA and Health Canada enzyme documentation requirements extend product launch timelines for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Brewing Enzymes Market |
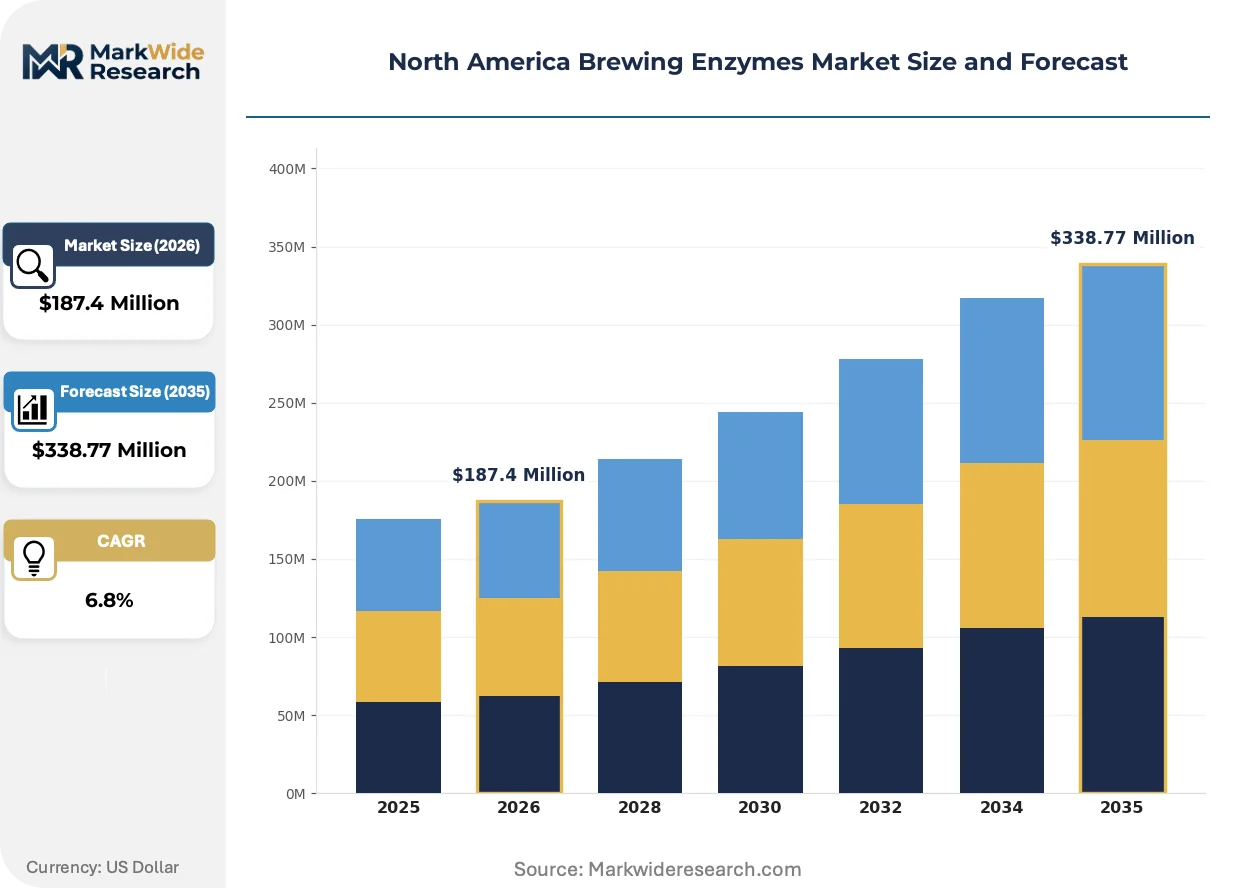
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Protease, Glucose Isomerase, Cellulase Application: Beer Production, Wort Filtration, Mashing, Fermentation End User: Craft Breweries, Large Scale Breweries, Microbreweries, Contract Breweries Form: Liquid, Powder, Granular, Tablet |
| Companies Covered | The Soufflet Group, Koninklijke DSM N.V., DuPont de Nemours, Inc., Merck KGaA, Novozymes A/S, Amano Enzyme Inc., Enzyme Development Corporation, AB Enzymes, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Brewing Enzymes Market Evolving Landscape
Enzyme engineering and regulatory harmonization are compressing product development cycles while craft brewery procurement sophistication is redrawing supplier relationship expectations across North America.
High-activity amylase concentrates are absorbing the dosing volume requirements of smaller brewhouses. These ultra-concentrated liquid formulations permit precise micro-dosing in 10-30 barrel systems without volumetric measurement errors. Craft breweries in Colorado and Oregon are adopting these concentrates fastest, enabling enzyme use in experimental small batches previously considered economically unviable.
Health Canada and FDA are converging enzyme safety assessment frameworks. The PMRA's adoption of FDA GRAS determinations for brewing enzymes reduces redundant toxicology studies for suppliers seeking dual-market approval. Canadian craft breweries in Ontario and British Columbia benefit first from accelerated access to novel enzyme blends previously delayed by parallel review processes.
Direct supplier relationships are displacing traditional distributor intermediaries in craft segment enzyme procurement. Mid-size breweries in California and New York now contract enzyme technical service agreements directly with biotechnology firms, bypassing ingredient brokers. This channel compression demands suppliers maintain regional application laboratories and rapid-response technical teams previously handled by distribution partners.
North America Brewing Enzymes Market Segmentation
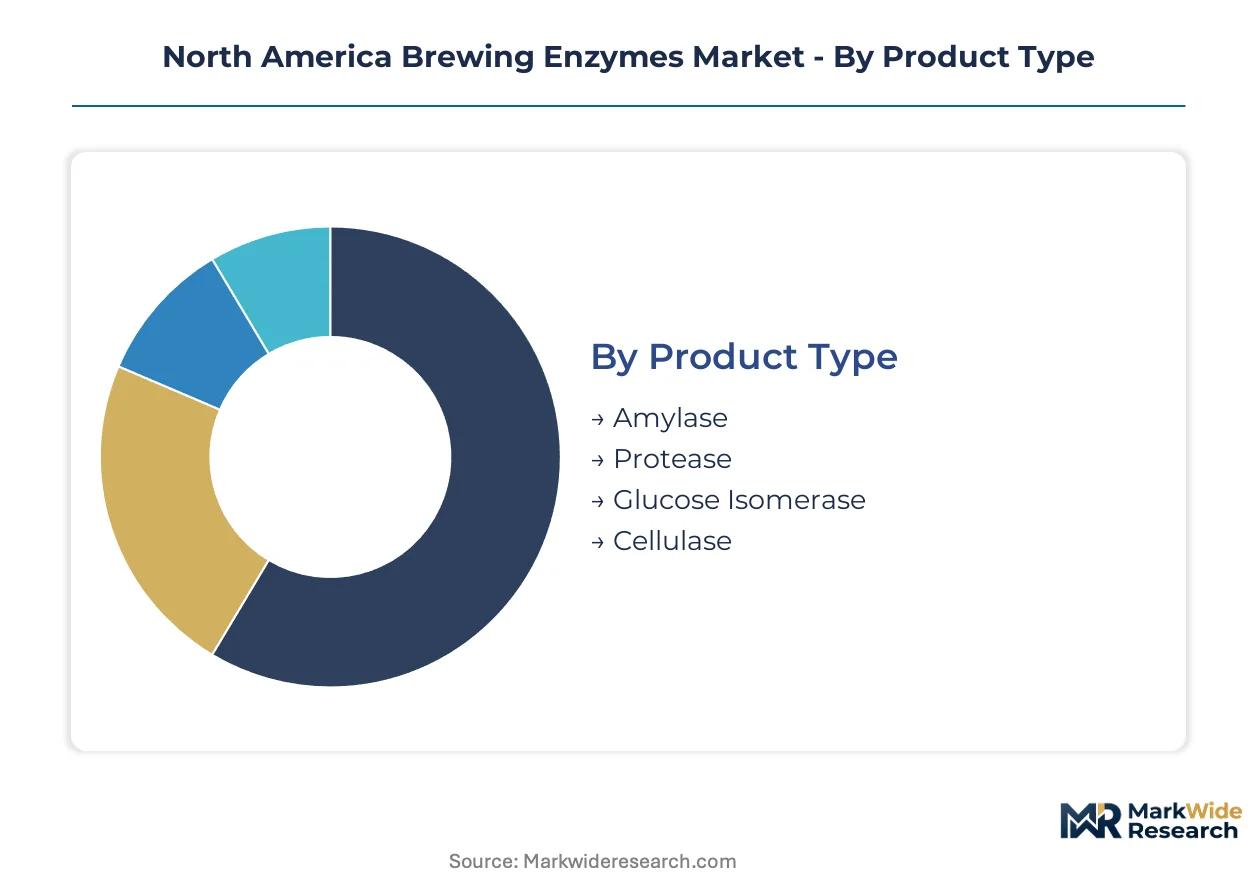
Brewing enzyme procurement patterns diverge sharply across facility scale and process stage, requiring suppliers to maintain parallel formulation portfolios. Segmentation reveals where capital deployment concentrates and which technical specifications command premium positioning.
Product Type:
Capital intensity peaks with specialized protease engineering, while commodity amylase production spreads fixed costs across volume.
- Amylase:Starch-converting biocatalysts hydrolyze alpha-1,4 glycosidic bonds to release fermentable sugars from malted grains. Demand clusters in Michigan and Wisconsin brewing corridors where large-scale facilities prioritize extract yield maximization and mash cycle acceleration.
- Protease:Protein-modifying enzymes cleave peptide bonds to reduce haze formation and enable gluten-reduced beer formulations. Craft breweries across Colorado and Oregon drive adoption as experimental portfolios expand into specialty dietetic segments.
- Glucose Isomerase:Catalytic isomerization of glucose to fructose supports adjunct sugar stream optimization in high-gravity brewing systems.
- Cellulase:Cell wall-degrading enzymes improve lautering efficiency and wort runoff rates in facilities processing unmalted adjuncts.
Amylase absorbs the bulk of installed capacity; protease is expanding most quickly.
Application:
Process stage determines enzyme stability requirements and temperature tolerance specifications.
- Beer Production:Encompasses full-process enzyme deployment from mashing through fermentation, requiring multi-enzyme compatibility and pH range flexibility. Large-scale breweries in the U.S. Great Lakes region standardize on integrated enzyme protocols to maintain batch-to-batch consistency across multi-million barrel annual outputs.
- Wort Filtration:Viscosity-reducing enzyme applications accelerate lautering and improve extract recovery. Facilities processing high-adjunct mashes in Canadian prairie provinces prioritize cellulase and beta-glucanase blends to prevent stuck sparges.
- Mashing:Starch gelatinization and conversion stage applications demand thermostable amylase formulations active at 62-72°C.
- Fermentation:Supplementary enzyme additions support attenuation control and diacetyl management in extended fermentation protocols.
Beer production commands the largest enzyme volume; wort filtration is gaining share fastest.
End User:
Facility scale dictates technical service intensity and formulation customization depth.
- Craft Breweries:Small-batch producers under 15,000 barrels annually require flexible dosing systems and rapid technical support for experimental recipes. California and New York facilities lead direct supplier contracting, bypassing traditional ingredient brokers to secure application-specific enzyme blends.
- Large Scale Breweries:Multi-million barrel facilities standardize on validated enzyme protocols with automated dosing integration and centralized procurement.
- Microbreweries:Sub-1,000 barrel operations concentrate in urban clusters where space constraints favor concentrated liquid enzyme formats.
- Contract Breweries:Third-party production facilities serving multiple brands demand enzyme versatility across divergent client specifications.
Large scale breweries absorb the bulk of installed capacity; craft breweries are climbing the fastest.
Form:
Physical state determines storage infrastructure, dosing precision, and supply chain complexity.
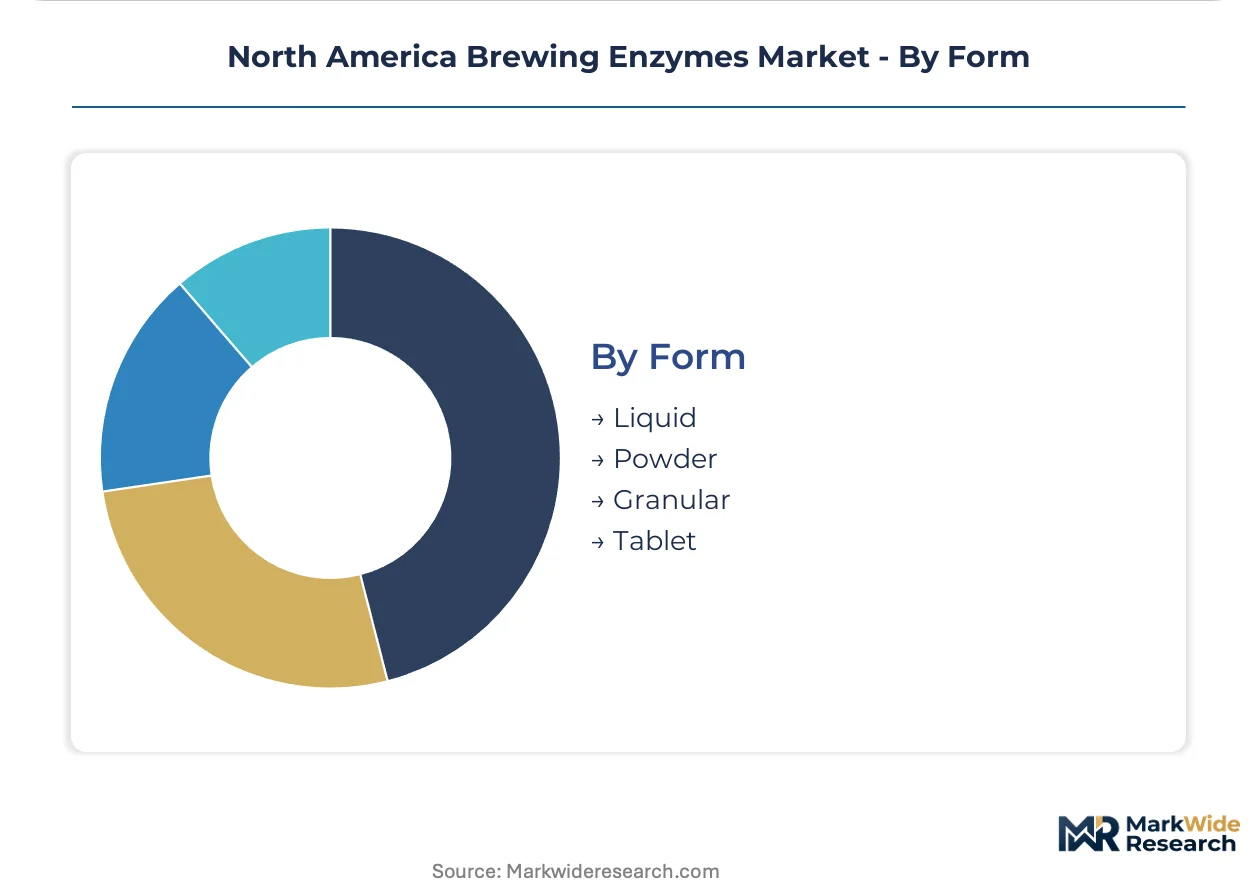
- Liquid:Aqueous enzyme preparations enable precise volumetric dosing and rapid tank integration. Cold-chain distribution partnerships extend shelf-stable delivery to remote brewing markets across Saskatchewan and Alberta.
- Powder:Lyophilized formulations reduce shipping weight and eliminate refrigeration requirements for facilities with limited cold storage.
- Granular:Free-flowing particulate forms facilitate automated handling systems in high-throughput production environments.
- Tablet:Unit-dosed solid formats simplify inventory management for small-batch operations with infrequent enzyme requirements.
Liquid absorbs the bulk of installed capacity; tablet is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes brewing corridor stretching through Michigan and Wisconsin anchors North American enzyme demand, with concentrated malt processing infrastructure generating sustained bulk procurement volumes from large-scale facilities.
United States
Craft brewery proliferation across Colorado and Oregon drives specialized protease adoption for gluten-reduced formulations. The FDA's GRAS notification pathway accelerates new enzyme introductions by reducing pre-market approval timelines. California facilities in San Diego and Los Angeles lead direct supplier contracting, bypassing traditional ingredient brokers to secure application-specific technical service agreements.
Canada
Prairie malt barley production growth in Saskatchewan and Alberta creates localized enzyme blending opportunities for regional brewing facilities. Health Canada and PMRA maintain parallel approval pathways that create dual-compliance requirements for cross-border suppliers. Ontario craft breweries in Toronto and Hamilton benefit first from accelerated access to novel enzyme blends through PMRA alignment with FDA safety assessments.
Mexico
Large-scale lager operations in Mexico City and Monterrey standardize on validated amylase protocols with automated dosing integration. The country's national food safety regulator oversees enzyme safety through established food additive frameworks. Baja California brewing clusters near Tijuana leverage cross-border logistics partnerships to access U.S.-distributed liquid enzyme cold-chain infrastructure.
North America Brewing Enzymes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation customization depth, with specialized protease engineering commanding price multiples over standard amylase commodities. The supplier base concentrates around microbial strain IP holders and large-scale fermentation capacity operators, creating tiered access to technical service intensity. Three archetypes dominate: integrated biotechnology conglomerates with diversified enzyme portfolios, specialized brewing ingredient suppliers with dedicated application laboratories, and regional distributors with cold-chain logistics capabilities. Competitive moves center on direct technical service agreements with mid-size craft facilities and refrigerated distribution partnerships extending into remote prairie markets.
Among European-anchored biotechnology groups, Novozymes A/S and Koninklijke DSM N.V. exemplify the integrated conglomerate archetype with diversified microbial enzyme portfolios spanning industrial applications. DuPont de Nemours, Inc. occupies a position representing U.S.-based biotechnology leverage into specialized amylase blends for craft producers. Kerry Group anchors the distribution-centric tier through its North American food ingredient infrastructure, sitting within the liquid enzyme logistics specialization that extends shelf-stable delivery into Saskatchewan and Alberta brewing markets.
| Leading Market Players |
|---|
| The Soufflet Group |
| Koninklijke DSM N.V. |
| DuPont de Nemours, Inc. |
| Merck KGaA |
| Novozymes A/S |
| Amano Enzyme Inc. |
| Enzyme Development Corporation |
| AB Enzymes |
| Kerry Group |
| Others |
Value Network & Pricing Analysis
Specialized protease engineering for gluten-reduced formulations commands price multiples over commodity amylase blends, with this performance divergence manifesting in both value-based pricing tiers and supply chain configurations that concentrate high-margin biocatalyst production near Great Lakes brewing clusters while dispersing standard enzyme distribution through regional food ingredient networks.
Pricing Analysis
Yield-linked pricing anchors value capture for high-activity amylase concentrates, with suppliers tying contract terms to measurable mash efficiency gains and fermentation throughput improvements. Pricing stratifies across premium, standard, and economy tiers based on enzyme activity certification, formulation customization depth, and bundled technical service intensity. Cost compression in commodity amylase segments is intensifying because craft brewery procurement sophistication drives competitive bidding for standard formulations. Large-scale facilities in Michigan and Wisconsin exhibit lowest price sensitivity due to volume-anchored supplier relationships, while microbreweries in urban clusters face highest per-unit cost exposure.
Supply Chain Analysis
Direct-to-craft-brewery channels handle specialized protease demand through biotechnology firm technical service agreements, bypassing traditional ingredient brokers. Microbial strain production concentrates in Denmark, the Netherlands, and the United States, with fermentation capacity anchored near pharmaceutical-grade biomanufacturing infrastructure. Raw material inputs draw from corn steep liquor suppliers in the U.S. Midwest and soybean meal processors in Canadian prairie provinces. Single-source vulnerability runs through proprietary microbial strain IP held by consolidated biotechnology suppliers. Distribution runs through Kerry Group's North American food ingredient infrastructure for liquid enzyme cold-chain delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive control over microbial strain development and fermentation capacity to secure supply security and margin capture in high-growth protease segments.
For Market Incumbents: Deploy regional application laboratories to defend against direct supplier relationships displacing distributor intermediaries. Incumbents should consolidate technical service teams in Colorado and Oregon craft brewing clusters where experimental recipe demand creates sticky supplier relationships. Capacity addition in Saskatchewan and Alberta anchors prairie malt barley supply security. FDA-Health Canada regulatory harmonization threatens to accelerate new entrant access, requiring incumbents to front-load dual-compliance certification investments.
For New Entrants and Emerging Players: Launch via liquid enzyme cold-chain partnerships with North American food ingredient distributors to access remote prairie brewing markets without capital-intensive logistics buildout. White-space targets concentrate in gluten-reduced formulation technical service gaps and microbrewery tablet-format enzyme demand. The most penetrable segment is mid-size craft facilities in California and New York seeking direct biotechnology firm relationships. Go-to-market positioning should emphasize rapid-response mash protocol design support where incumbent technical service teams create dependency friction.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized protease engineering specialists given Health Canada PMRA alignment with FDA safety assessments accelerating cross-border product registration. Long-term viability favors biotechnology firms with captive microbial strain IP and regional fermentation capacity serving craft segment growth. Acquisition target archetypes include dedicated brewing application laboratories and refrigerated logistics operators extending into Saskatchewan and Alberta. The signal to watch is direct contracting penetration rates among mid-size craft facilities as inflection indicator for distributor displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Application Laboratory Expansion | Direct technical service agreements with Colorado and Oregon craft breweries displace distributor intermediaries. |
| Microbial Strain IP Acquisition | Captive fermentation capacity in Denmark and the Netherlands secures supply security for high-activity concentrates. |
| Liquid Enzyme Cold-Chain Partnership | Kerry Group infrastructure extends shelf-stable delivery into Saskatchewan and Alberta prairie markets. |
| Dual-Compliance Certification Investment | Parallel FDA and Health Canada documentation accelerates cross-border product launch timelines. |
| Gluten-Reduced Formulation Technical Service | Protease optimization expertise captures premium pricing in Colorado and Oregon experimental portfolios. |
Research Methodology
Independent corroboration across primary interviews with brewing biochemists, craft brewery operations managers, and biotechnology firm technical service directors, alongside secondary validation through FDA GRAS notification filings, Health Canada PMRA submission databases, and American Society of Brewing Chemists technical protocols, underwrites the qualitative findings. Bottom-up triangulation across facility-scale enzyme procurement patterns and top-down validation against malt barley production statistics and brewing capacity databases ensures segmentation integrity.
Rate-of-change decomposition across the analysis window separates volume expansion from price-mix effects in craft versus large-scale facility segments. The modeling framework incorporates enzyme activity tier, formulation physical state, process stage application, and regional regulatory cluster as segmentation dimensions. CAGRs derive from regression analysis against malted barley consumption trends and brewing capacity utilization rates, with craft brewery proliferation velocity and gluten-reduced product portfolio expansion serving as industry-specific forecast inputs.
Regulatory reclassification, microbial feedstock price volatility, and craft brewery consolidation failure are the dominant revision risks to projection assumptions. Forecasts reflect documented base-case assumptions regarding FDA-Health Canada harmonization velocity and prairie malt barley production growth trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Diastatic Malt Market
Ingredients
Europe Amino Acid Market
Ingredients
Glucomannan Market
Ingredients
Wheat Germ Oil Market
Ingredients
Africa Fats and Oil Market
Ingredients
Organic Virgin Coconut Oil Market
Ingredients
Biotech Ingredients Market
Ingredients
Bulk Food Ingredients Market
Ingredients
Black Cumin Seed Oil Market
Ingredients
Olive Oil Market
Ingredients
Bleached Flour Market
Ingredients
Farnesene Market
Ingredients
Notoginseng Root Extract Market
Ingredients
Chickpea Fiber Market
Ingredients
Meat Extract Market
Ingredients
Baobab Powder Market