
 Canada Sodium Reduction Ingredients Market | 2026-2036
Canada Sodium Reduction Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Sodium Reduction Ingredients Market Outlook
Potassium chloride is hardening as the primary sodium replacement in Canadian processed meat and bakery formulations, cutting sodium content by up to 40% without compromising taste profiles. Cargill Incorporated leverages its integrated salt-alternative supply chain to dominate bulk ingredient contracts with national food manufacturers. Kerry Group plc sustains competitive advantage through its taste modulation technology portfolio, which masks metallic off-notes in potassium-based systems. Tate & Lyle PLC anchors its position in the bakery segment with specialized mineral salt blends engineered for dough stability and shelf-life extension.
Sodium reduction ingredients comprise functional additives and reformulation systems designed to replicate or enhance the sensory properties of sodium chloride in food matrices, typically employing potassium salts, yeast extracts, amino acids, and flavor potentiators at concentrations calibrated to specific application requirements. Their primary commercial purpose is enabling food manufacturers to achieve regulatory-compliant sodium targets while preserving consumer acceptance and processing functionality. Mineral salts command the largest product type share due to established efficacy and cost predictability in high-volume applications, while flavor enhancers represent the fastest-expanding category as clean-label demands intensify and yeast-derived umami systems gain traction among premium positioned brands. Within applications, processed foods absorb the greatest ingredient volume, though sauces exhibit superior margin capture owing to complex flavor-reconstruction requirements and shorter development cycles.
Health Canada sets mandatory sodium reduction targets through its voluntary-mandatory framework, while the Canadian Food Inspection Agency enforces labeling standards that expose sodium content to consumer scrutiny. These regulatory pressures directly expand demand for certified low-sodium ingredient systems and reformulation advisory services. The CFIA's evolving front-of-package nutrition symbol regulations further tighten compliance windows for food manufacturers. Stakeholders must monitor Health Canada's transition from voluntary targets to potential mandatory limits, as this policy inflection would compress reformulation timelines and reshape supplier qualification criteria across the Canadian food production base.
Market Dynamics
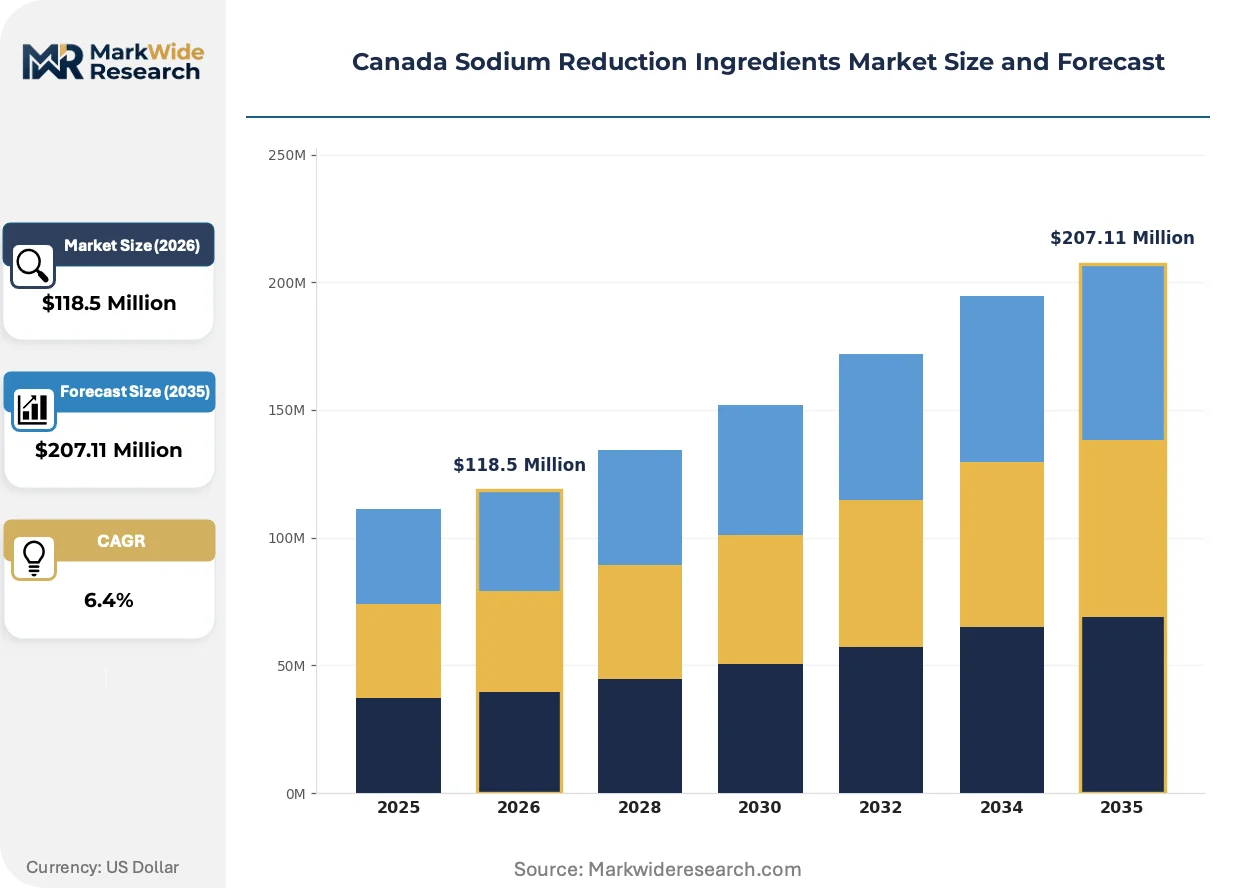
Health Canada's transition toward mandatory sodium limits is compressing reformulation timelines for processed food manufacturers, forcing rapid supplier qualification and accelerating demand for certified low-sodium ingredient systems across Ontario and Quebec production clusters.
Growth Catalysts
- Health Canada Sodium Reduction Framework:The voluntary-mandatory hybrid structure pressures packaged food producers to preemptively reformulate, expanding procurement of potassium chloride and yeast extract blends before binding limits take effect.
- Clean-label yeast extract systems:Premium positioned brands in the bakery and snack segments are replacing artificial flavor enhancers with fermented umami ingredients to meet consumer transparency expectations.
- Ontario-Quebec production concentration:Large-scale meat processing and baked goods manufacturing facilities in these provinces generate concentrated demand for bulk mineral salt alternatives and technical reformulation support.
Market Restraints
- Potassium chloride supply concentration:Domestic production capacity for food-grade potassium salts remains limited, creating import dependency on North American chemical suppliers and price volatility exposure.
- Metallic off-note technical barrier:Potassium-based sodium replacers introduce bitter aftertastes that require expensive taste modulation systems to mask, elevating formulation costs for mid-tier manufacturers.
- CFIA labeling compliance friction:Evolving front-of-package nutrition symbol regulations force repeated label redesigns and reformulation iterations, extending product development cycles.
Strategic Opportunities
- Western Canada geographic white space:Alberta and British Columbia processed food sectors remain underpenetrated by specialized sodium reduction ingredient suppliers, offering first-mover expansion potential.
- Sauce and condiment application expansion:Complex flavor reconstruction requirements in these categories command premium margins and shorter development cycles compared to bulk processed foods.
- Health Canada mandatory limit anticipation:Early positioning against impending binding sodium caps allows ingredient suppliers to lock in long-term reformulation advisory contracts with national manufacturers.
Industry Challenges
- Food formulation chemist talent scarcity:Specialized expertise in salt-replacement matrix optimization and sensory science remains concentrated among a small pool of technical consultants, constraining manufacturer reformulation velocity.
- Legacy equipment recalibration requirements:Existing processing lines designed for sodium chloride functionality require capital-intensive modifications to handle hygroscopic potassium salt blends without caking or flow disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Sodium Reduction Ingredients Market |
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $207.11 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavor Enhancers, Salt Substitutes, Mineral Salts, Nutrient Additives Application: Processed Foods, Snacks, Sauces, Bakery End User: Food Manufacturers, Restaurants, Institutions, Retailers Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | Cargill Incorporated, Kerry Group plc, Tate & Lyle PLC, Givaudan SA, Archer Daniels Midland (ADM), DuPont de Nemours Inc., Innophos Holdings Inc., Advanced Food Systems Inc., Sensient Technologies Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Sodium Reduction Ingredients Market Strategic Shifts
Digital formulation platforms and AI-driven sensory prediction tools are compressing product development cycles, while regulatory pressure intensifies clean-label demands and procurement patterns shift toward integrated reformulation partnerships.
Machine learning-based flavor matching software is automating the optimization of potassium chloride and yeast extract ratios in processed meat matrices. National sausage and deli meat manufacturers in Ontario are deploying these platforms to cut reformulation trial cycles from months to weeks. This compression of sensory validation timelines is automating supplier selection decisions around technical service capabilities rather than commodity pricing.
Health Canada's proposed mandatory front-of-package sodium warning labels are accelerating label redesign investments across the bakery segment. The Canadian Food Inspection Agency's enforcement of these standards forces manufacturers to either reformulate or accept visibility penalties in retail environments. Processed bread and cracker producers in Quebec are responding by consolidating supplier relationships with firms offering integrated regulatory compliance documentation.
Ingredient procurement is consolidating around full-service reformulation partnerships rather than transactional mineral salt purchases. Mid-sized snack manufacturers are replacing multiple specialty chemical vendors with single-source suppliers providing technical advisory, sensory testing, and regulatory submission support. This bundling trend is most pronounced in Ontario, where bakery and meat processing clusters face compressed compliance deadlines.
Canada Sodium Reduction Ingredients Market Segmentation
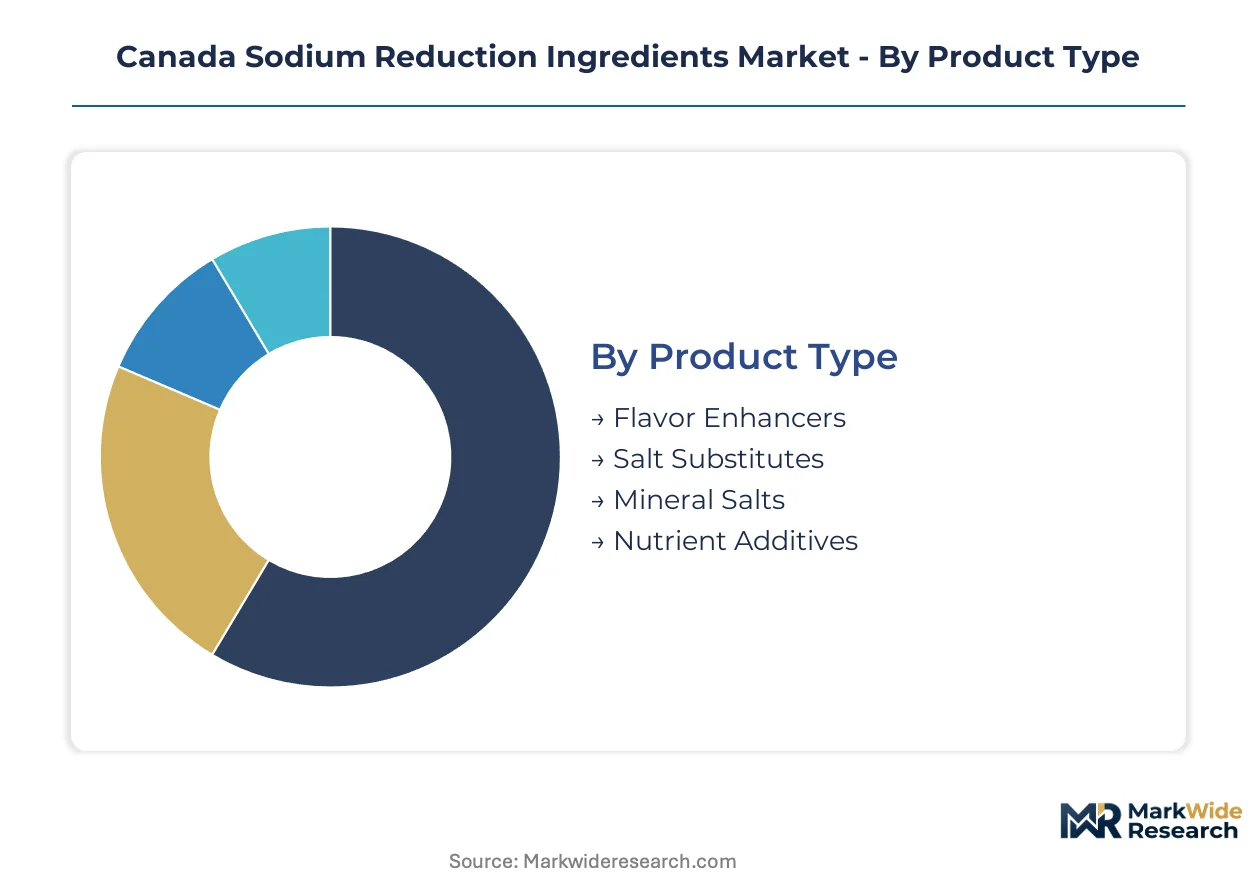
Sodium reduction ingredient procurement in Canada diverges sharply across product categories and customer types. Health Canada's compliance windows and Ontario-Quebec manufacturing concentration reshape how suppliers structure their segment portfolios.
Product Type:
Formulation chemists select ingredients based on sodium replacement efficacy, off-note masking requirements, and clean-label positioning against Health Canada disclosure standards.
- Mineral Salts:Potassium chloride and potassium-based blends constitute the workhorse category for high-volume reformulation. Ontario meat processors and Quebec bakeries absorb the bulk of food-grade mineral salt contracts as they race to meet sodium targets.
- Flavor Enhancers:Yeast extracts, amino acids, and nucleotide-based systems rebuild umami profiles stripped out by sodium removal. Premium snack brands in Toronto and Montreal manufacturing clusters are switching to fermented flavor systems to satisfy consumer transparency demands.
- Salt Substitutes:Commercial blends combining mineral salts with masking agents deliver turnkey sodium reduction for mid-tier manufacturers lacking in-house formulation expertise.
- Nutrient Additives:Magnesium and calcium fortification compounds address the nutritional gap created when potassium displaces sodium in reformulated matrices.
Mineral salts lead on scale; flavor enhancers lead on momentum.
Application:
Reformulation complexity and margin structure vary dramatically across food matrices, with liquid and emulsion systems commanding technical premiums over dry applications.
- Processed Foods:Deli meats, sausages, and cured products in Ontario processing plants represent the highest absolute ingredient volume. Potassium chloride integration here demands precise control over water-binding and texture preservation.
- Sauces:Complex flavor reconstruction in liquid matrices generates superior margins and accelerates development cycles. Montreal condiment manufacturers are consolidating supplier relationships around integrated reformulation partnerships.
- Bakery:Dough stability and shelf-life extension requirements drive demand for specialized mineral salt blends engineered to maintain gluten network integrity without sodium's structural role.
- Snacks:Seasoning surface applications permit simpler sodium replacement strategies, though clean-label positioning is pushing brands toward yeast-derived flavor systems.
Processed foods anchor volume absorption; sauces capture margin premiums.
End User:
Procurement sophistication and technical service requirements stratify sharply between industrial-scale manufacturers and fragmented foodservice operators.
- Food Manufacturers:National packaged food producers in Ontario and Quebec drive bulk mineral salt demand and command dedicated technical advisory resources from ingredient suppliers.
- Restaurants:Chain operators face Health Canada menu labeling pressures but lack reformulation infrastructure, creating demand for pre-blended sodium reduction systems.
- Institutions:Healthcare and education foodservice contracts are adopting sodium targets ahead of regulatory mandates, though procurement remains price-sensitive and fragmented.
- Retailers:Private-label development teams at major grocery chains are building in-house reformulation capabilities, shifting from commodity purchasing toward strategic ingredient partnerships.
Food manufacturers dominate procurement scale; retailers are gaining strategic leverage fastest.
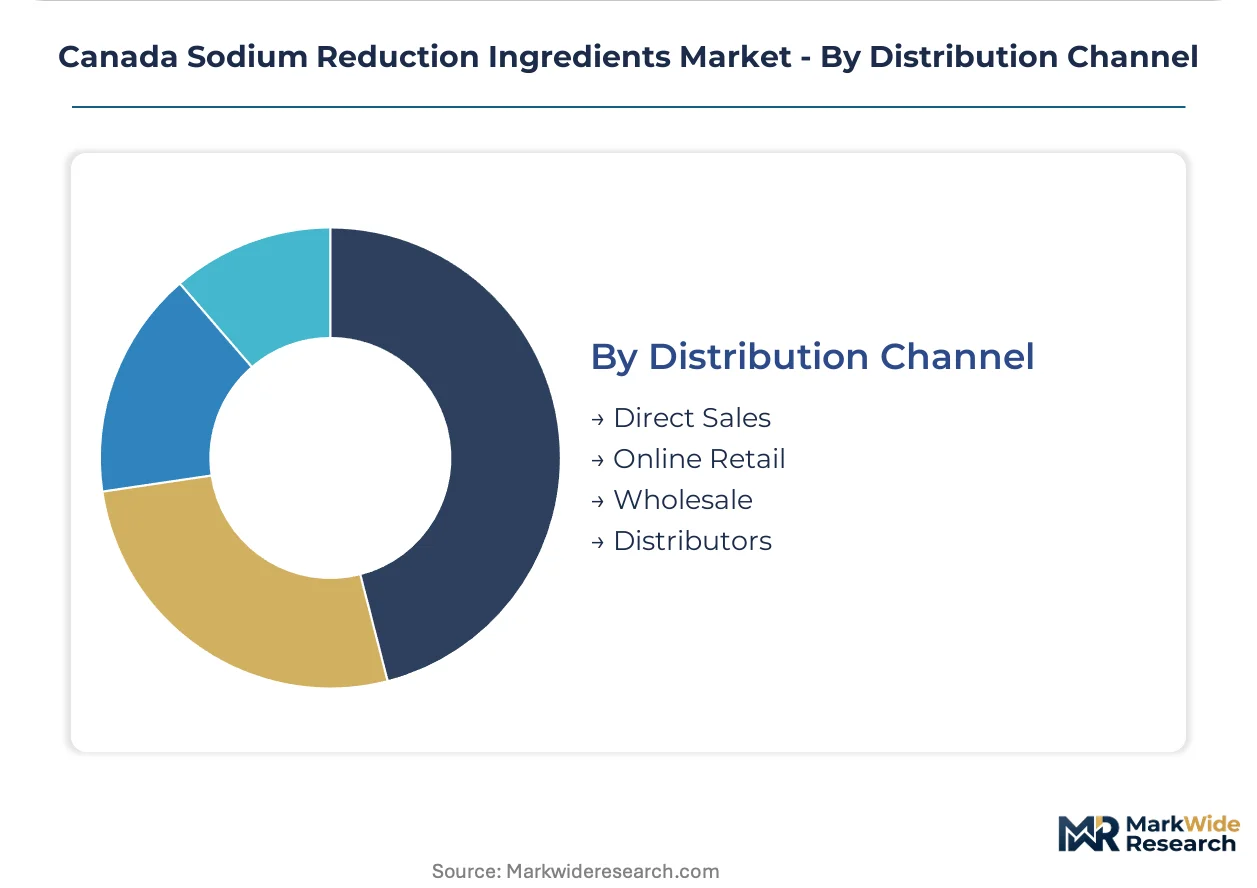
Distribution Channel:
Supply chain configuration determines technical service intensity and compliance documentation access for sodium reduction ingredient buyers.
- Direct Sales:Large-volume contracts with national meat and bakery processors bypass intermediaries to secure dedicated formulation support and regulatory submission assistance from suppliers like Cargill and Kerry.
- Distributors:Regional chemical and ingredient distributors serve mid-tier manufacturers across Ontario and Quebec with stocked mineral salts and basic technical literature.
- Wholesale:Bulk purchasing cooperatives aggregate demand from smaller processors, though they sacrifice customized reformulation advisory.
- Online Retail:Emerging channel for specialty yeast extracts and clean-label flavor systems targeting artisan producers and startup brands in Vancouver and Calgary.
Direct sales command the largest contract values; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario and Quebec production clusters generate the dominant share of sodium reduction ingredient demand in Canada. Health Canada's regulatory pressure compresses reformulation timelines across provincial manufacturing bases. The analysis examines five sub-regional markets where processed food concentration and compliance urgency intersect.
Ontario
Large-scale meat processing facilities in Hamilton and Toronto drive bulk potassium chloride procurement for deli meat and sausage reformulation. Health Canada's voluntary sodium targets for processed meats accelerate supplier qualification cycles among Ontario processors. The Golden Horseshoe manufacturing corridor concentrates national contract volumes with integrated ingredient suppliers.
Quebec
Montreal-area bakeries and snack manufacturers absorb specialized mineral salt blends engineered for dough stability. The Canadian Food Inspection Agency's front-of-package labeling enforcement triggers label redesign investments across Quebec's baked goods sector. Laval and Longueuil production clusters consolidate supplier relationships around full-service reformulation partnerships.
Alberta
Calgary and Edmonton food processors represent underpenetrated demand for sodium reduction technical services. Provincial health authorities in Alberta are advancing institutional sodium targets ahead of federal mandates. Meat packing facilities in the Calgary-Edmonton corridor lack dedicated reformulation advisory infrastructure available in Ontario.
British Columbia
Vancouver's premium positioned food brands prioritize clean-label yeast extract systems for consumer transparency. Health Canada disclosure standards influence packaging decisions among British Columbia's natural and organic product manufacturers. The Lower Mainland hosts emerging demand for online-retail specialty ingredients targeting artisan producers.
Atlantic Canada
Halifax and Moncton seafood processors face sodium reduction pressure in cured and smoked fish categories. Regional institutional foodservice contracts adopt sodium targets without the technical support infrastructure present in central Canada. Atlantic Canada's fragmented manufacturing base relies on distributor intermediaries rather than direct supplier relationships.
Canada Sodium Reduction Ingredients Market Competitive Environment
Global majors compete with regional champions across technical service capabilities and supply chain integration. The vendor base stratifies between bulk mineral salt suppliers and specialized taste modulation technology providers. Three archetypes dominate: integrated agricultural conglomerates with captive salt-alternative production, flavor science specialists with masking technology portfolios, and regional chemical distributors serving mid-tier manufacturers. Competitive positioning hardens around M&A activity consolidating reformulation advisory capabilities and strategic partnerships locking in long-term supply contracts with national food manufacturers.
Within the integrated agricultural tier, Cargill Incorporated anchors bulk ingredient supply relationships through its North American salt-alternative production network. Kerry Group plc exemplifies the flavor science specialist archetype with taste modulation systems addressing potassium chloride off-notes. Tate & Lyle PLC occupies a position among ingredient technology providers targeting bakery-specific mineral salt formulations. These three companies represent distinct competitive vectors: scale-driven commodity supply, sensory science differentiation, and application-specific technical service.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Kerry Group plc |
| Tate & Lyle PLC |
| Givaudan SA |
| Archer Daniels Midland (ADM) |
| DuPont de Nemours Inc. |
| Innophos Holdings Inc. |
| Advanced Food Systems Inc. |
| Sensient Technologies Corporation |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap mineral salt processors in Saskatchewan and Manitoba anchor domestic potassium chloride production, translating captive brine extraction rights into pricing discipline that resists volatility from North American chemical import markets. Their concentrated ownership structures enable long-term contract pricing with Ontario meat processors that insulates reformulation budgets from spot-market swings.
Pricing Analysis
Input-cost pass-through from food-grade potassium chloride feedstock governs contract structures across the Canadian market. Three-tier pricing structure across premium, standard, and economy levels separates certified clean-label yeast extract systems from commodity mineral salt blends and unmasked potassium chloride base grades. Price differentiation hinges on Health Canada compliance documentation depth and technical advisory bundling. Pricing pressure stems from metallic off-note masking requirements that elevate formulation service costs. Mid-tier snack manufacturers exhibit highest price sensitivity; national bakery chains with dedicated R&D facilities demonstrate lowest.
Supply Chain Analysis
Domestic-content thresholds in Health Canada procurement guidelines for institutional foodservice contracts reshape sourcing toward Saskatchewan and Manitoba potash producers. Geographic supply concentration centers on Canada, the United States, and Chile for food-grade potassium salts. Raw material dependencies include potash ore, fermentation feedstocks for yeast extracts, and amino acid precursors. Single-source vulnerability runs through Saskatchewan's Allan mine complex as the dominant North American food-grade potassium chloride origin. Distribution runs through direct sales contracts with national manufacturers and regional chemical distributors serving Quebec and Ontario mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
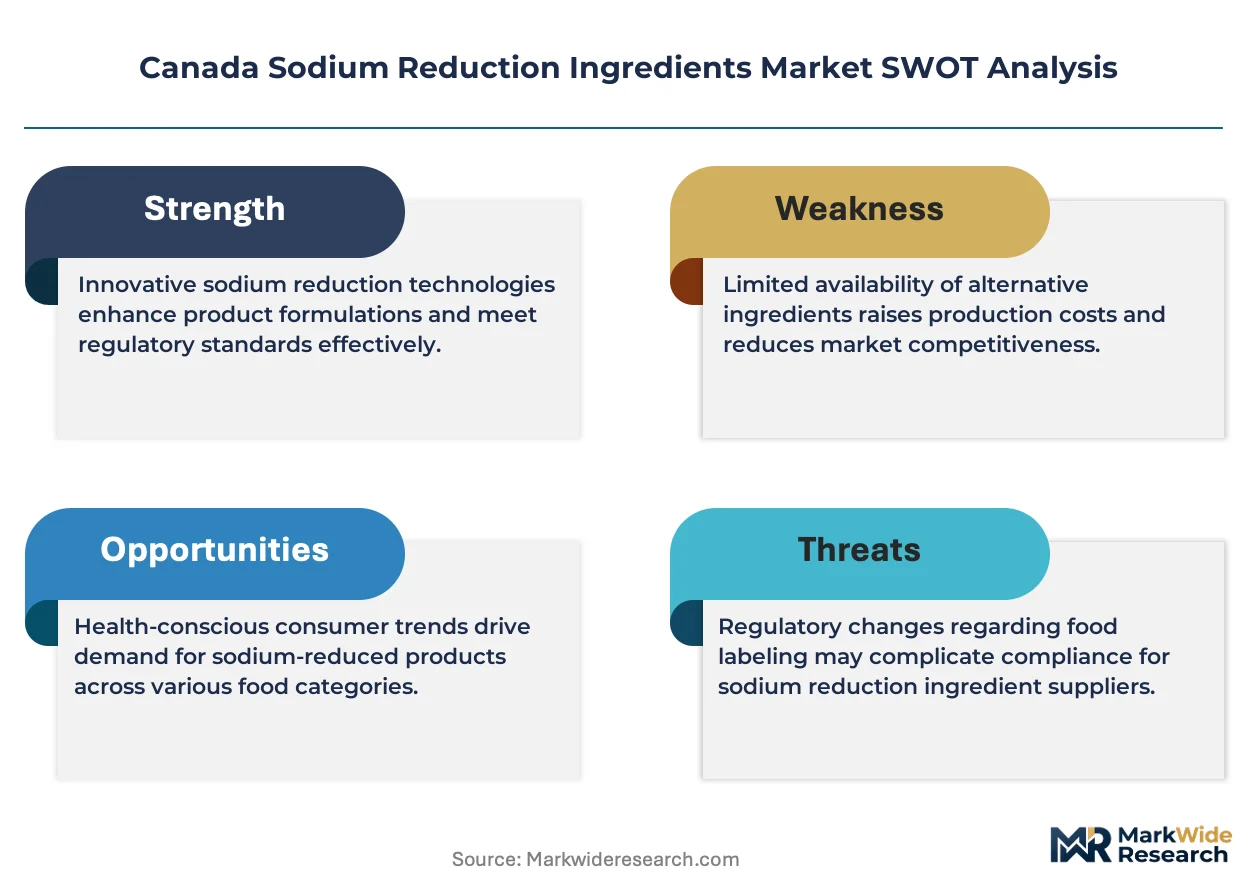
The Canada sodium reduction ingredients market represents a late-cycle quality story as Health Canada's transition toward mandatory sodium limits concentrates procurement among suppliers with integrated reformulation capabilities and certified compliance documentation. Demand is shifting toward premium specifications as private-label grocery chains build in-house sensory science teams.
For Market Incumbents: To counter emerging AI-driven flavor matching platforms from technology entrants, Cargill and Kerry should deepen captive supply of taste modulation compounds and lock in exclusive reformulation advisory contracts with Quebec bakery clusters before compliance deadlines compress. Certification investment in Health Canada pre-approved ingredient systems is the critical lever. For New Entrants and Emerging Players: Launch via online retail channels targeting British Columbia artisan producers and Alberta meat processors lacking technical advisory infrastructure. Western Canada geographic white space offers the most penetrable expansion corridor. Specialty yeast extract systems for clean-label positioning provide the strongest go-to-market angle against established mineral salt incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among regional chemical distributors with reformulation advisory capabilities but limited brand recognition. Long-term viability over the five-to-ten year horizon rests on Health Canada's mandatory sodium limit implementation timeline. Acquisition targets should display integrated regulatory submission support and sensory testing laboratories. The signal to watch is CFIA front-of-package labeling enforcement intensity as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Potash Extraction | Cargill's captive Saskatchewan brine rights secure cost predictability for Ontario meat processor contracts. |
| AI-Driven Flavor Matching Platform Launch | Machine learning deployment by Ontario sausage manufacturers compresses sensory validation from months to weeks. |
| Clean-Label Yeast Extract Certification | Kerry's fermented umami systems meet Health Canada disclosure standards for Toronto premium snack brands. |
| Western Canada Distribution Expansion | First-mover technical advisory presence in Alberta addresses meat packing facility reformulation gaps. |
| Regulatory Submission Support Bundling | Integrated compliance documentation locks in long-term supplier relationships with Quebec bakery clusters. |
Study Parameters
Direct dialogue with food formulation chemists, procurement directors at national meat processors, Health Canada regulatory affairs specialists, and Quebec bakery technical service managers grounded qualitative insights. Secondary validation drew from CFIA labeling guidance documents, Health Canada sodium reduction framework publications, Canadian Food Inspection Agency enforcement bulletins, and customs trade data on potassium chloride imports. Bottom-up and top-down triangulation cross-referenced ingredient volume estimates against processed food production statistics.
Bottom-up modeling built category-level projections from individual application segments and end-user procurement patterns across the analysis window. Segmentation dimensions included product type, application matrix complexity, end-user technical sophistication, and distribution channel service intensity. CAGRs were derived from slope analysis of year-over-year growth trajectories adjusted for regulatory inflection points. Forecast inputs incorporated Health Canada compliance timeline assumptions and Ontario-Quebec manufacturing cluster expansion plans.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated mandatory sodium limit implementation or potassium chloride supply disruption scenarios. Forecasts reflect documented assumptions regarding regulatory transition timing and manufacturer reformulation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
Egg Yolk Lecithin Market
Ingredients
Citrus Fiber Market
Ingredients
Collagen Casings Market
Ingredients
Rooster Comb Extract Market
Ingredients
Edible Halal Gelatin Market
Ingredients
Carica Papaya Seed Oil Market
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Egg Membrane Powder Market
Ingredients
Whey Permeate Market
Ingredients
Avocado Oil Market
Ingredients
Astragalus Root Extract Market
Ingredients
Protein Ingredients Market
Ingredients
Tomato Concentrate Market
Ingredients
North America Rice Bran Oil Market
Ingredients
Volatile Fatty Acids Market