
 Sea Salt Market | 2026-2036
Sea Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Sea Salt Market Analysis
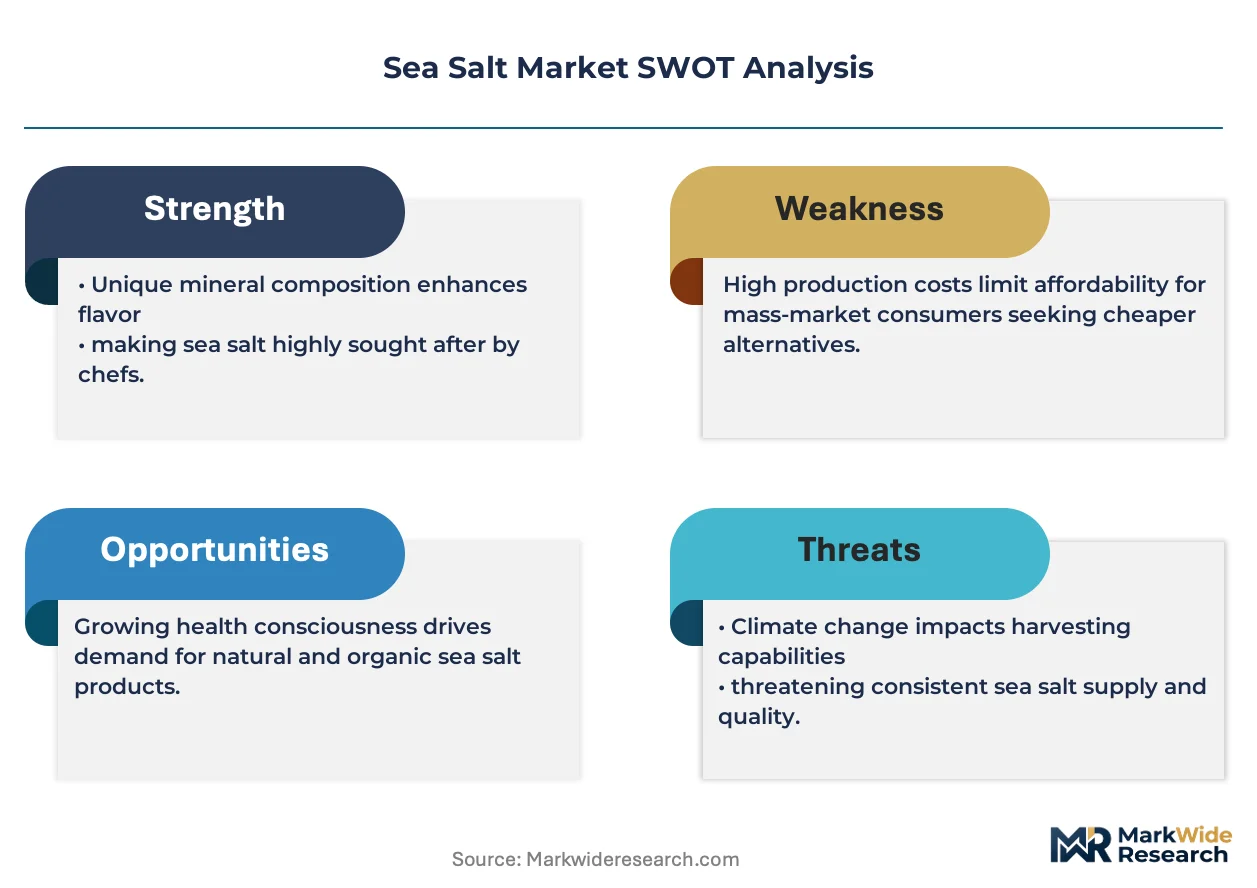
ISO 22000 certification is collapsing the competitive field into a narrower set of qualified suppliers. Maldon Salt Company Limited leverages its Essex coastal heritage to sustain premium positioning in fine sea salt grades. Cargill, Incorporated anchors North American bulk supply through extensive evaporative infrastructure. K+S Aktiengesellschaft competes across European food-grade and de-icing segments with integrated mine-to-distribution control.
Sea salt denotes sodium chloride crystals harvested through solar evaporation of seawater in shallow ponds, typically retaining trace minerals such as magnesium, potassium, and calcium that distinguish it from refined vacuum-evaporated table salt. Its primary commercial purpose centers on flavor enhancement, food preservation, and texture modification across culinary and industrial food processing applications. Fine sea salt dominates household and food industry procurement volumes, while flavored sea salt captures expanding margin pools in gourmet retail channels. Coarse sea salt maintains steady demand in cosmetics exfoliation and pharmaceutical buffer applications where crystalline structure matters.
EU REACH compliance and FDA food-contact substance regulations shape permissible mineral content thresholds and labeling requirements for cross-border sea salt trade. EFSA evaluations of dietary sodium intake influence reformulation pressures on food manufacturers sourcing sea salt as a perceived healthier alternative. ISO standards for food safety management systems increasingly gate market access for smaller Mediterranean and Asian producers. Stakeholders must monitor evolving carbon-border adjustment mechanisms that could reprice energy-intensive salt transport routes against localized solar evaporation investments.
Market Dynamics
The EU's F-Gas Regulation is forcing evaporative salt producers to abandon conventional fuel-powered harvesting in favor of solar evaporation infrastructure, reshaping capital allocation across Mediterranean coastal operations.
Growth Catalysts
- Gourmet food manufacturing expansion:Specialty sea salt integration into premium packaged goods lines is pulling volume through certified channels. EFSA dietary sodium evaluations are accelerating reformulation demand from food processors seeking perceived healthier positioning.
- REACH compliance concentration:ISO 22000 certification requirements are collapsing supplier fields, advantaging qualified Mediterranean and coastal European producers with established food safety management systems.
- Solar evaporation technology:Decarbonization mandates across EU member states are subsidizing pond infrastructure upgrades, reducing operational carbon intensity for traditional salt flat operators in Sicily and the Algarve.
Market Restraints
- Energy input cost volatility:Natural gas price fluctuations directly impact producers still running hybrid thermal-solar operations, compressing margins during winter harvest cycles.
- Supply geography concentration:Premium brand premiums cluster around specific Mediterranean coastal zones, creating vulnerability to localized climate disruption or coastal development restrictions.
- Refined vacuum-evaporated substitution:Industrial food processors in price-sensitive segments can switch to purified table salt without functional loss, capping sea salt penetration in bulk ingredient markets.
Strategic Opportunities
- Cosmetics exfoliation applications:Coarse crystalline sea salt is capturing share from synthetic microbeads in European personal care formulations, driven by ingredient transparency preferences.
- Carbon border adjustment positioning:Localized solar evaporation investments in Portugal and Spain will qualify for preferential treatment under emerging EU carbon-border mechanisms, repricing import competition.
- Pharmaceutical buffer-grade supply:Crystalline structure requirements in pharmaceutical manufacturing create a technical moat for producers with documented mineral trace consistency.
Industry Challenges
- ISO 22000 certification timeline:Smaller traditional salt flat operators face 18-24 month compliance windows, risking market exclusion during transition periods.
- Seasonal production-workforce mismatch:Solar-dependent harvesting concentrates labor demand in summer months, complicating retention in remote coastal locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sea Salt Market |
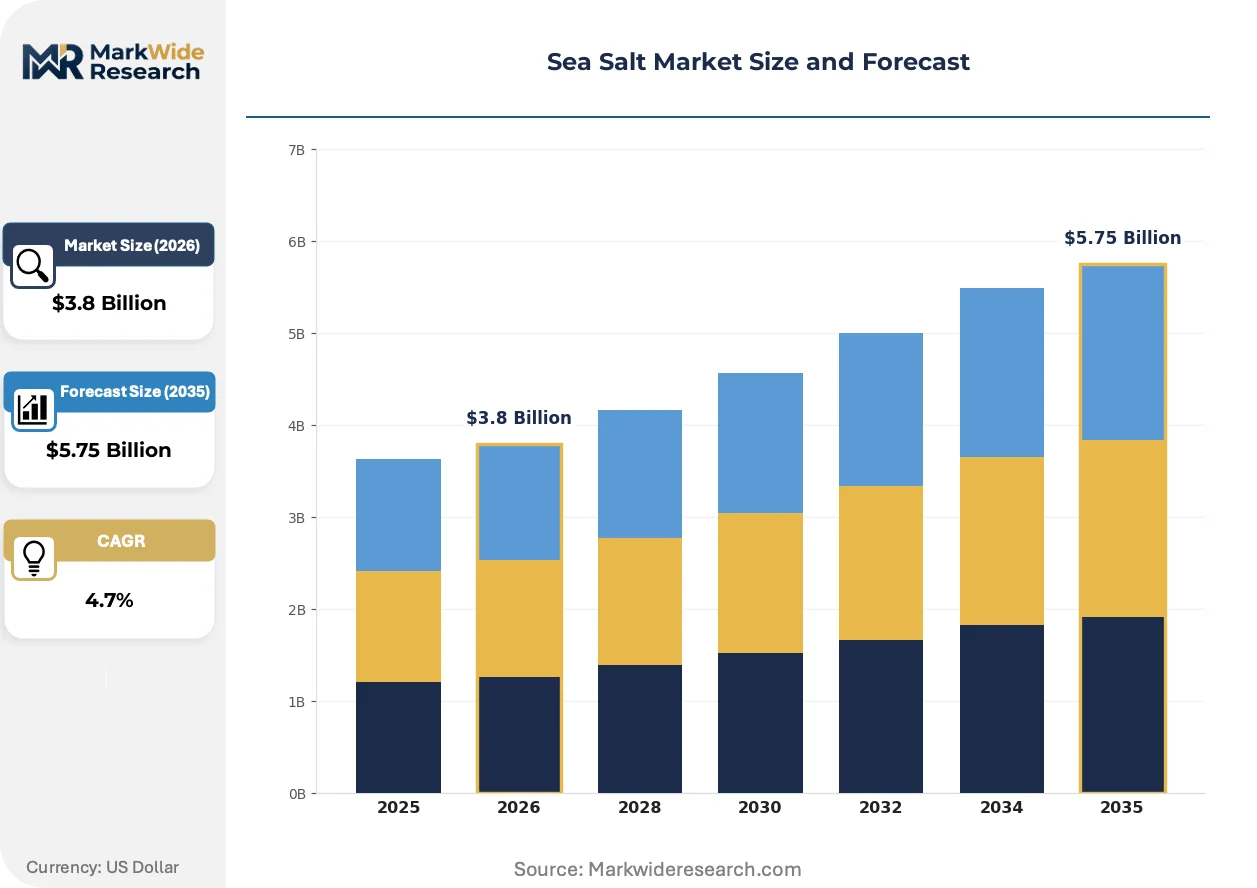
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fine Sea Salt, Coarse Sea Salt, Flavored Sea Salt, Himalayan Sea Salt End User: Food Industry, Cosmetics Industry, Pharmaceutical Industry, Household Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Packaging Type: Bottles, Sachets, Bulk Packaging, Jars |
| Companies Covered | Maldon Salt Company Limited, Jacobsen Salt Co., LLC, Cargill, Incorporated, Tata Chemicals Limited, Redmond Real Salt, LLC, Morton Salt, Inc., SaltWorks, Inc., Société des Salins du Midi et des Salines de l'Est, K+S Aktiengesellschaft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sea Salt Market Emerging Trajectories
Active innovation across this market centers on production decarbonization, regulatory compliance automation, and channel restructuring that bypasses traditional ingredient distribution layers.
Automated salinity monitoring and AI-driven pond management is fragmenting the historical advantage of multi-generational harvester expertise. Mid-scale Sicilian and Algarve operations are adopting sensor networks faster than legacy family-run flats, compressing the premium positioning window for heritage-dependent brands. This technology diffusion is enabling new entrants to achieve mineral consistency benchmarks without decades of accumulated tacit knowledge.
EU F-Gas Regulation phase-down schedules are accelerating capital redeployment toward fully solar evaporation infrastructure. Producers in Spain, Portugal, and Italy face 2030 deadlines for refrigerant-dependent process equipment, forcing premature depreciation of hybrid thermal systems. Food-grade segment players with integrated mine-to-distribution control are absorbing these transition costs more efficiently than standalone evaporative operators.
Direct-to-manufacturer contracting is displacing layered ingredient distribution for certified specialty grades. Gourmet food manufacturers in France and Italy are establishing captive supply relationships with specific salt flat operations, bypassing wholesale intermediaries. This channel compression is most visible in fine sea salt procurement for premium packaged goods, where provenance documentation requirements favor bilateral agreements over spot-market purchasing.
Sea Salt Market Segmentation
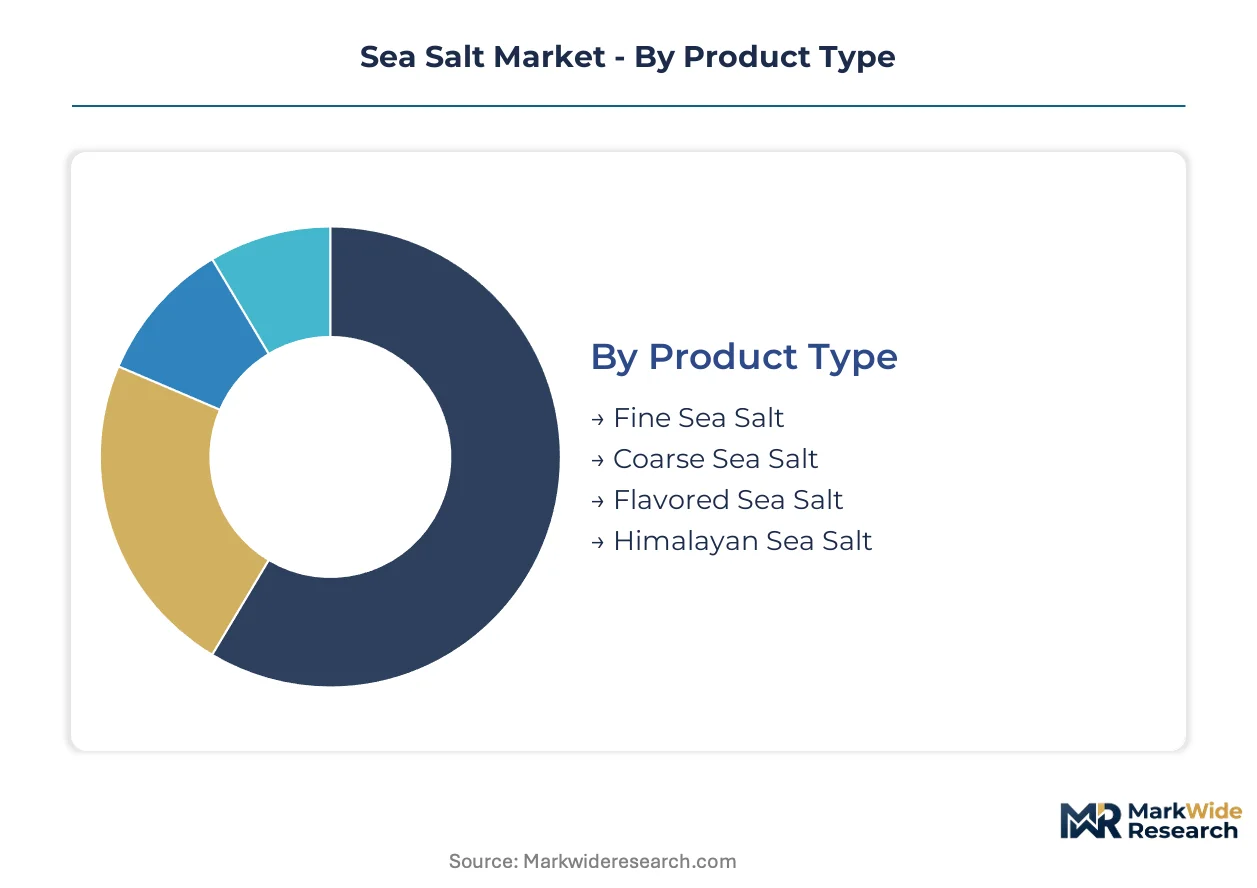
Sea salt procurement patterns diverge sharply across product grades, end-use specifications, and channel structures. Regulatory thresholds for mineral content and food safety certification reshape which segments capture margin versus volume.
Product Type:
EU REACH compliance thresholds and FDA food-contact substance regulations differentiate permissible mineral content across crystalline grades, determining cross-border trade eligibility.
- Fine Sea Salt:Small-crystal sodium chloride with retained trace minerals of magnesium and calcium serves as the default input for industrial food processing and household cooking. Procurement concentrates in Mediterranean coastal zones—particularly Sicily and the Algarve—where ISO 22000-certified operations supply gourmet food manufacturers seeking provenance documentation for premium packaged goods lines.
- Coarse Sea Salt:Large-crystal structures harvested through extended solar evaporation cycles provide the crystalline integrity required for cosmetics exfoliation and pharmaceutical buffer applications. Demand clusters in European personal care formulations where ingredient transparency preferences displace synthetic microbeads, and in pharmaceutical manufacturing where documented mineral trace consistency creates technical qualification barriers.
- Flavored Sea Salt:Infused variants carrying smoke, herb, or spice signatures capture expanding margin pools in gourmet retail channels through direct-to-manufacturer contracting that bypasses wholesale intermediaries.
- Himalayan Sea Salt:Pink-hued crystalline deposits marketed on mineral diversity claims serve wellness-positioned retail segments despite lacking marine evaporation provenance.
Established volume favors Fine Sea Salt; emerging adoption favors Coarse Sea Salt.
End User:
Application-specific purity requirements and certification burdens segment procurement economics across industrial buyers.
- Food Industry:Industrial processors and gourmet manufacturers drive the largest procurement volumes, with EFSA dietary sodium evaluations accelerating reformulation demand for perceived healthier positioning. REACH-compliant Mediterranean suppliers with integrated mine-to-distribution control absorb decarbonization transition costs more efficiently than standalone evaporative operators.
- Cosmetics Industry:European personal care formulators source coarse crystalline grades to replace synthetic microbeads, with mineral consistency documentation requirements favoring bilateral supply agreements over spot-market purchasing.
- Pharmaceutical Industry:Buffer-grade applications demand crystalline structure precision and batch-to-batch mineral trace consistency that technical specifications gate to qualified suppliers.
- Household:Consumer-packaged volumes concentrate in fine grades through supermarket and online channels, with premium positioning sustained by coastal heritage branding.
Food Industry procurement anchors current volume; Cosmetics Industry applications are climbing the fastest.
Distribution Channel:
Channel selection determines certification documentation depth and margin capture for producers.
- Online Retail:Direct-to-consumer platforms enable provenance storytelling and heritage brand premiums for specialty grades, particularly flavored and coarse crystalline variants.
- Supermarkets:Mass-market fine sea salt volumes concentrate here, with private-label substitution pressure capping price realization.
- Specialty Stores:Gourmet retail channels capture the highest margins for documented-origin Mediterranean salts, with shelf placement contingent on ISO 22000 certification.
- Wholesale:Industrial food processors and cosmetics manufacturers increasingly bypass this layer through captive supply relationships with specific salt flat operations.
Wholesale retains food industry bulk flow; specialty stores are gaining share fastest in premium segments.
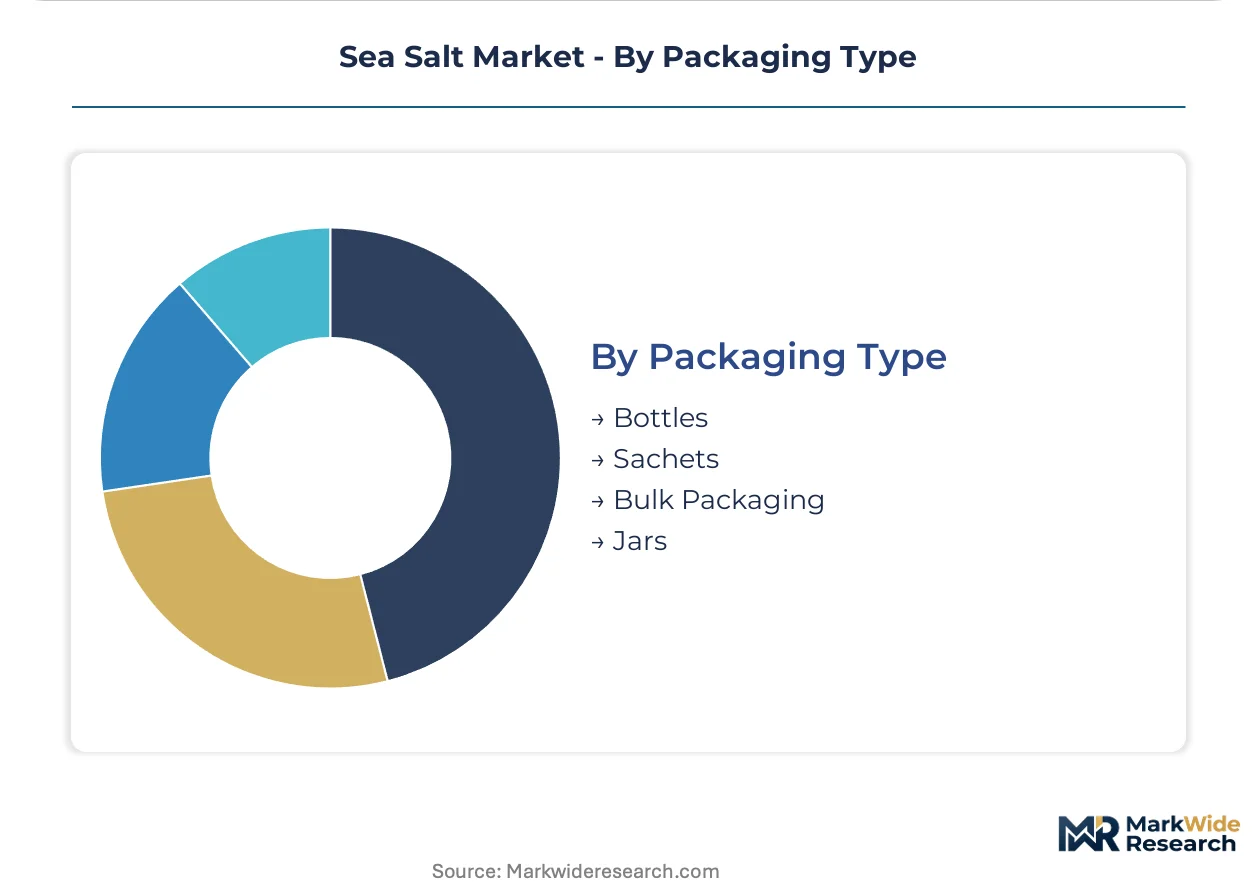
Packaging Type:
Packaging economics align with volume scale and end-use handling requirements.
- Bottles:Precision-dispensing formats serve household cooking applications where moisture resistance preserves crystalline integrity.
- Sachets:Single-serve portions dominate foodservice and airline catering procurement, with cost minimization favoring refined vacuum-evaporated substitution.
- Bulk Packaging:Industrial food processors and cosmetics manufacturers source certified grades in unbranded bulk to enable private-label positioning or downstream formulation integration.
- Jars:Wide-mouth formats suit coarse and flavored grades where visual crystalline structure supports premium retail positioning.
Bulk Packaging commands industrial volume; Jars sustain the steepest expansion trajectory in gourmet retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation subsidies are accelerating solar evaporation infrastructure across Mediterranean coastal zones. France, Italy, Spain, and Portugal dominate premium sea salt production. Germany and the United Kingdom anchor industrial processing and distribution.
France
Gourmet food manufacturers in Provence-Alpes-Côte d'Azur source coarse crystalline grades for cosmetics and pharmaceutical buffer applications. ANSM documentation requirements for mineral trace consistency favor established Salins du Midi operations. Camargue salt flats near Arles concentrate heritage-brand premium positioning through direct-to-manufacturer contracting.
Italy
Sicilian coastal operations command brand premiums for fine sea salt in premium packaged goods lines. EFSA dietary sodium evaluations are accelerating reformulation demand from pasta and cured meat processors. Trapani salt flats deploy automated salinity monitoring to compress traditional harvester expertise advantages.
Spain
Andalusian producers face 2030 deadlines for refrigerant-dependent process equipment under EU F-Gas phase-down schedules. Cádiz and Huelva salt flats absorb transition costs through integrated mine-to-distribution control. Solar evaporation investments in these zones qualify for preferential treatment under emerging carbon-border mechanisms.
Portugal
Algarve traditional salt flat operations leverage ISO 22000 certification to supply certified specialty channels. The country's national food safety authority enforces REACH-compliant mineral content thresholds for cross-border trade. Tavira and Olhão clusters concentrate solar-dependent harvesting with seasonal workforce retention challenges in remote coastal locations.
Germany
KBA industrial standards influence pharmaceutical buffer-grade specifications for crystalline structure precision. North Rhine-Westphalia and Lower Saxony host integrated evaporative infrastructure serving food-grade and de-icing segments. German distributors anchor North European bulk supply flows through extensive logistics networks.
Sea Salt Market Vendor Landscape
Player mix skews toward heritage-positioned Mediterranean specialists and integrated North American bulk suppliers. The field collapses around two dominant tiers: ISO 22000-certified coastal operators capturing gourmet premiums, and scale-driven evaporative infrastructure players serving industrial food processors. Strategic archetypes include provenance-dependent heritage brands, integrated mine-to-distribution conglomerates, and mid-scale technology-adopting regionalists. Competitive moves concentrate on captive supply relationship formation and solar evaporation capacity redeployment.
Among heritage-positioned specialists, Maldon Salt Company Limited and Jacobsen Salt Co., LLC exemplify coastal-origin premium positioning archetypes. Cargill, Incorporated occupies a position representing integrated bulk supply scale. These three anchors illustrate the structural tension between documented-provenance certification premiums and volume-driven industrial procurement economics.
| Leading Market Players |
|---|
| Maldon Salt Company Limited |
| Jacobsen Salt Co., LLC |
| Cargill, Incorporated |
| Tata Chemicals Limited |
| Redmond Real Salt, LLC |
| Morton Salt, Inc. |
| SaltWorks, Inc. |
| Société des Salins du Midi et des Salines de l'Est |
| K+S Aktiengesellschaft |
| Others |
Supply Flow & Price Mechanics
Scale economies in solar evaporation infrastructure concentrate supply among Mediterranean coastal operators with depreciated pond networks, compressing price floors for new entrants while amplifying margin capture for established Sicilian and Algarve producers with ISO 22000 certification.
Pricing Analysis
Certification level creates the primary spread between premium and commodity tiers. Three-tier pricing structure across heritage-positioned, certified-standard, and bulk-economy levels governs procurement economics, with ISO 22000 documentation commanding 15-25% premiums in gourmet channels. Cost compression in industrial fine grades is intensifying because refined vacuum-evaporated salt offers functional substitution without provenance premiums. Food processors exhibit highest price sensitivity, while cosmetics formulators prioritize mineral consistency documentation over unit cost.
Supply Chain Analysis
Strategic stockpiling dominates procurement behavior among industrial food processors facing seasonal solar harvest cycles, while gourmet manufacturers prefer just-in-time bilateral contracts with named salt flat operations. Supply concentrates in Italy, Spain, and Portugal, with Sicilian and Algarve clusters anchoring premium heritage positioning. Production draws from seawater feedstock, polyethylene packaging, and logistics fuel as primary inputs. Single-source vulnerability intensifies around specific coastal zones exposed to climate disruption. Distribution runs through direct-to-manufacturer contracting for certified grades, displacing traditional wholesale layering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sea salt sits in early-cycle expansion as decarbonization subsidies accelerate solar infrastructure deployment and EFSA sodium evaluations pull reformulation demand toward perceived healthier positioning.
For Market Incumbents: Consolidate around captive supply relationships with gourmet food manufacturers seeking provenance documentation, while accelerating solar evaporation capacity redeployment ahead of EU F-Gas 2030 deadlines. Absorb transition costs through integrated mine-to-distribution control to outlast standalone evaporative operators facing margin compression from natural gas volatility. Certification investment in ISO 22000 and REACH compliance creates defensive moats against emerging mid-scale technology adopters. For New Entrants and Emerging Players: Differentiate on mineral trace consistency documentation for pharmaceutical buffer applications, where technical specifications gate qualified supply. Cosmetics exfoliation segments offer lowest penetration barriers as European personal care formulators displace synthetic microbeads. Direct-to-manufacturer contracting with provenance storytelling bypasses wholesale margin capture and builds brand equity faster than supermarket private-label competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among heritage-positioned Mediterranean specialists with established direct relationships to gourmet packaged goods manufacturers. Long-term viability favors integrated operators with solar evaporation infrastructure and documented coastal origin rights. Watch carbon-border adjustment mechanism implementation as inflection indicator for repricing import competition against localized production.| Strategic Initiative | Industry Significance |
|---|---|
| Solar Evaporation Capacity Expansion | EU F-Gas Regulation subsidies reduce operational carbon intensity for Sicilian and Algarve operators. |
| ISO 22000 Certification Investment | Food safety management documentation gates access to premium gourmet retail and direct-to-manufacturer channels. |
| Backward Integration into Packaging | In-house jar and bulk container production secures supply continuity for moisture-sensitive coarse crystalline grades. |
| Direct-to-Manufacturer Contracting | Bilateral agreements with French and Italian gourmet processors bypass wholesale intermediaries and capture provenance premiums. |
| Pharmaceutical Buffer-Grade Qualification | Documented mineral trace consistency meets ANSM and KBA specifications for high-margin technical applications. |
Methodological Framework
A spread of perspectives from salt flat operations managers, gourmet food manufacturer procurement leads, cosmetics formulation chemists, and pharmaceutical quality assurance directors converged on the working assumptions underlying supply and demand trajectories. Primary field engagement combined with secondary validation from customs trade data, EFSA dietary evaluation records, EU F-Gas Regulation implementation filings, and SEC disclosures from integrated salt producers. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across Mediterranean production zones.
Segmentation dimensions modeled include product grade tier, end-use industry application, distribution channel structure, and regional regulatory cluster. CAGRs were derived through growth rate convergence analysis applied to volume and value outputs across the projection horizon. Industry-specific forecast inputs incorporated solar evaporation capacity buildout schedules and EFSA sodium intake guidance revision timelines.
Material uncertainties — regulatory enforcement intensity, climate disruption frequency, and natural gas price volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions about subsidy continuity and certification adoption curves. Revision becomes warranted when carbon-border adjustment mechanism implementation crosses thresholds that reprice import competition.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market
Ingredients
Plant Protein Ingredients Market
Ingredients
Roasted Grain Ingredients Market
Ingredients
Distiller's Dried Grains with Solubles (DDGS) Feed Market
Ingredients
Asia-Pacific Yeast and Yeast Extract Market
Ingredients
Amaranth Seed Oil Market
Ingredients
Potato Peel Powder Market
Ingredients
Europe Corn Glucose Market
Ingredients
Dill Seed Oil Market
Ingredients
South America Soy Protein Ingredients Market
Ingredients
Avocado Powder Market
Ingredients
Gluten-Free Flour Market
Ingredients
Rennet Market
Ingredients
Hydrolyzed Egg Market
Ingredients
China Cane Sugar Market
Ingredients
Safflower Oil Market