
 Hydrolyzed Corn Protein Market | 2026-2036
Hydrolyzed Corn Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrolyzed Corn Protein Market Foresight
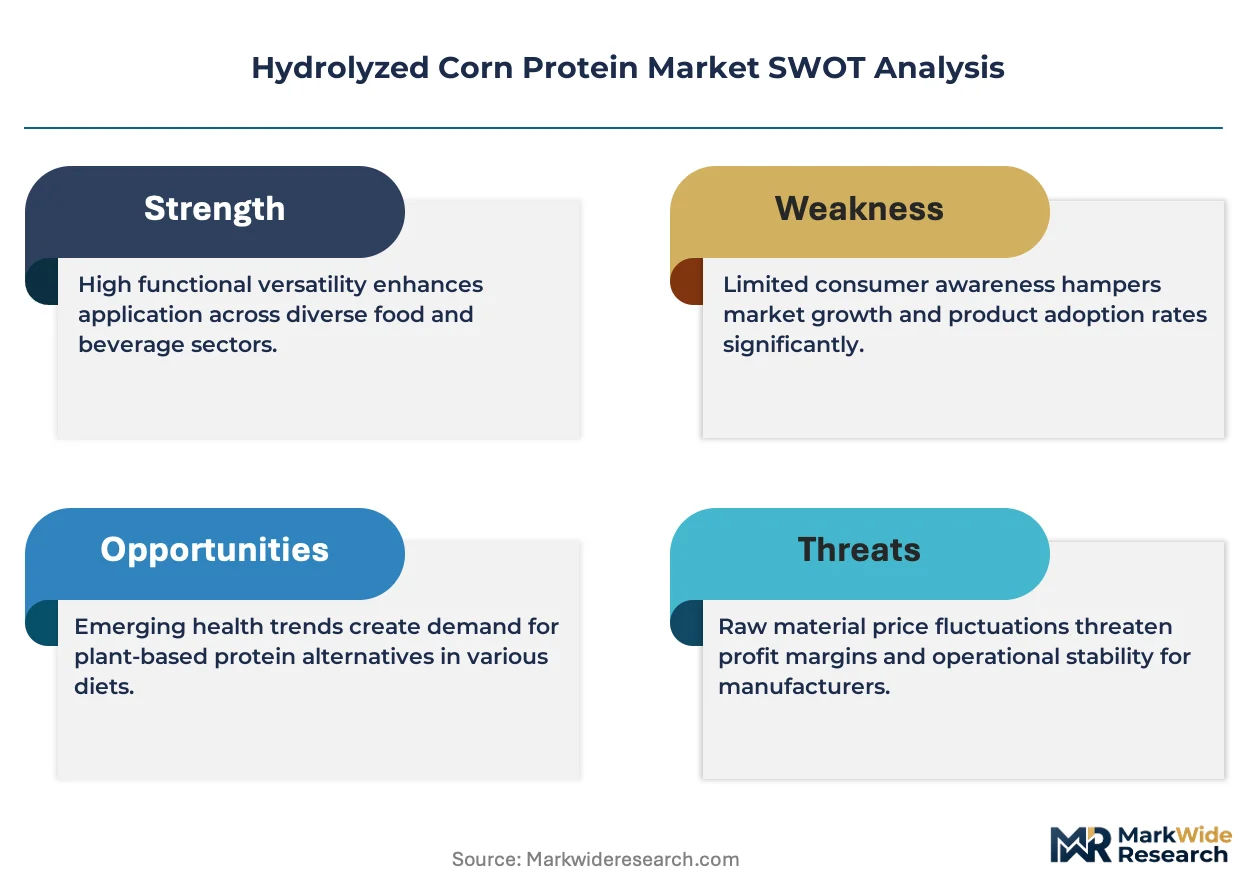
The capital-intensity divergence between integrated grain processors and specialty ingredient houses is unwinding competitive dynamics across the hydrolyzed corn protein landscape. Cargill, Incorporated leverages its captive corn supply and wet-milling infrastructure to dominate upstream hydrolysate production. Archer Daniels Midland Company anchors its position through enzymatic hydrolysis R&D platforms that yield peptide fractions for nutritional applications. Roquette Frères differentiates via non-GMO and organic-certified hydrolyzed corn protein lines targeting European clean-label markets.
Hydrolyzed corn protein consists of corn gluten meal or corn steep liquor subjected to controlled enzymatic or acid hydrolysis, yielding soluble peptides and free amino acids with molecular weights typically ranging from 200 to 10,000 Daltons. This ingredient functions primarily as a flavor precursor, emulsifier, and nutritional fortifier across food, feed, and cosmetic formulations. The powder form segment leads volume throughput due to superior shelf stability and ease of incorporation into dry blends, while the peptides sub-category within product type captures expanding margin pools from sports nutrition and clinical nutrition applications. Animal feed applications remain structurally mature with price-competitive dynamics, whereas personal care brands are driving fastest uptake as hydrolyzed corn protein displaces animal-derived keratin in hair and skin formulations.
The FDA governs hydrolyzed corn protein labeling under Food Allergen Labeling and Consumer Protection Act provisions, while the USDA oversees its use in meat and poultry product formulations through FSIS ingredient approval processes. EPA regulations on corn wet-milling effluent discharge shape production economics for Midwest processors. Stakeholders must monitor evolving enzyme patent expirations and carbon intensity scoring methodologies for fermented proteins to secure feedstock and processing advantages.
Market Dynamics
The FDA's updated guidance on fermented protein labeling is compressing formulation timelines and forcing ingredient houses to accelerate clean-label certification cycles. Midwest corn processing clusters now compete on carbon intensity scoring rather than scale alone.
Growth Catalysts
- Clean-label meat alternatives:Plant-based formulators in the United States are expanding hydrolyzed corn protein procurement as a binder and umami precursor. The USDA's FSIS ingredient approval process for meat analogs has streamlined for enzymatically hydrolyzed proteins.
- REACH-compliant cosmetic ingredients:European personal care brands are displacing animal-derived keratin with hydrolyzed corn protein peptides. ECHA's stricter animal testing bans accelerate botanical hydrolysate substitution.
- Enzyme patent expirations:Expiring protease patents are democratizing access to controlled hydrolysis technology. Specialty ingredient houses in Germany and the Netherlands are deploying open-source enzymatic platforms.
Market Restraints
- Feedstock concentration risk:Over two-thirds of merchant hydrolysate supply originates from integrated Iowa and Illinois wet-milling complexes. A single-season drought in the Corn Belt disrupts global peptide availability.
- Acid hydrolysis regulatory friction:The EPA's effluent discharge limits on acid-catalyzed processes impose compliance costs that enzymatic competitors avoid. Smaller Midwest processors face capital constraints for wastewater retrofit.
- Soy protein substitution threat:Isolated soy protein maintains price parity and established GRAS status in nutritional applications. Sports nutrition brands retain soy peptide formulations despite corn's cleaner allergen profile.
Strategic Opportunities
- Underpenetrated clinical nutrition:Japanese medical food manufacturers are formulating hydrolyzed corn protein for renal and hepatic disease patients. METI's functional food labeling system rewards peptide-based hypoallergenic formulations.
- Carbon intensity scoring tailwind:The EU Green Deal's farm-to-fork carbon accounting favors corn-derived proteins over energy-intensive fermentation alternatives. Dutch and Danish ingredient traders are building low-carbon hydrolysate certification tiers.
- Direct-to-brand distribution:E-commerce ingredient platforms are disintermediating traditional distributor networks. Clean-label cosmetic startups in California and New York procure hydrolysates through specialized B2B marketplaces.
Industry Challenges
- Peptide characterization skill gap:Analytical chemists capable of molecular weight distribution profiling and bioactivity validation remain scarce. Contract laboratories in the United States and Germany command premium rates for hydrolysate testing.
- Organic certification timeline compression:USDA Organic and EU Organic dual certification requires 18-24 month supply chain audits. Non-GMO identity preservation adds traceability infrastructure costs that erode margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrolyzed Corn Protein Market |
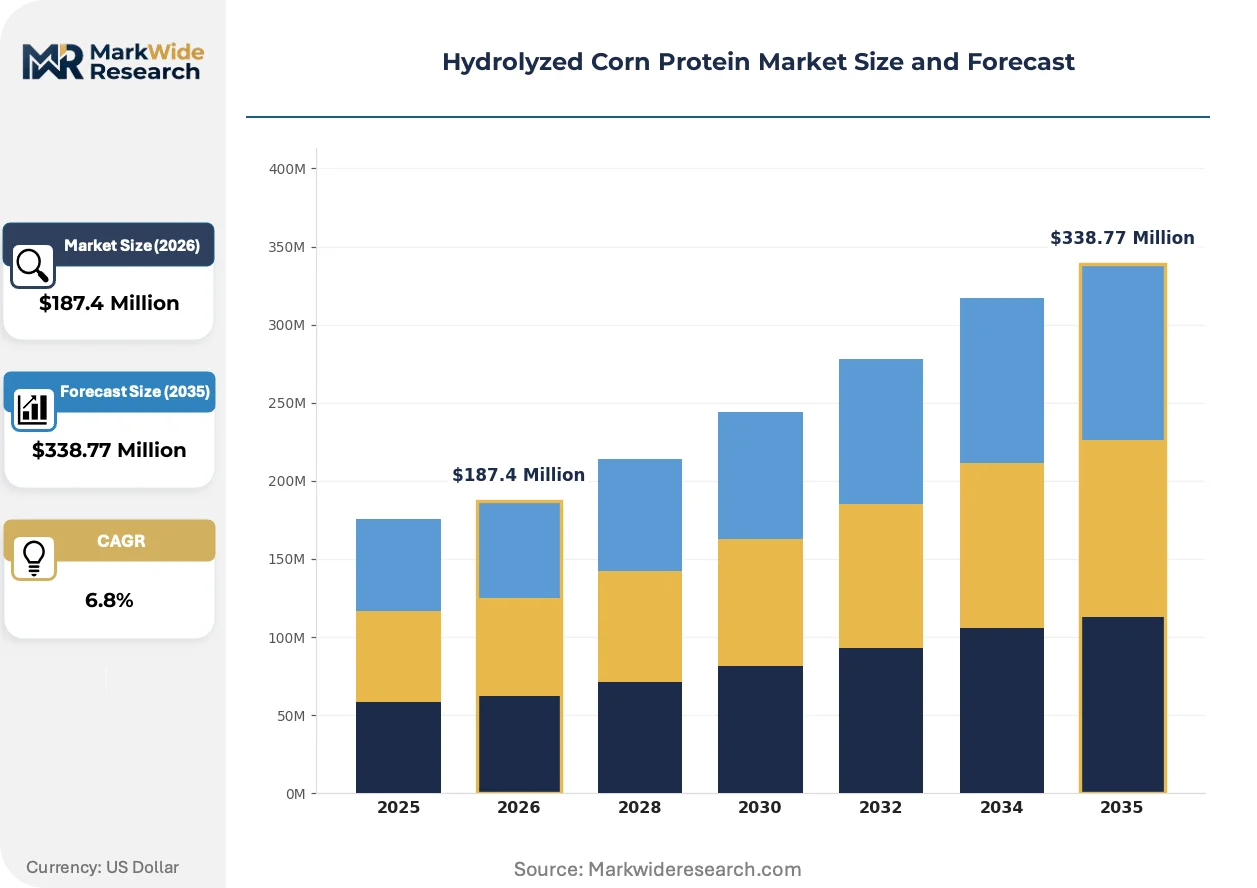
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolysate, Peptides, Concentrate, Isolate Application: Food & Beverages, Animal Feed, Nutritional Supplements, Personal Care Form: Powder, Liquid, Granules, Crystal End User: Food Manufacturers, Feed Producers, Pharmaceuticals, Personal Care Brands |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle PLC, Roquette Frères, Kerry Group plc, Sensient Technologies Corporation, ADEKA Corporation, Döhler GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrolyzed Corn Protein Market Shifts & Advancements
Enzymatic hydrolysis platforms are rewriting process economics while regulatory carbon accounting reshapes procurement priorities. Formulation science advances are unlocking peptide functionality previously reserved for animal proteins.
Controlled enzymatic hydrolysis using fungal proteases and bacterial neutral proteases is displacing acid-catalyzed processes in high-margin applications. Cosmetic peptide manufacturers in France and Switzerland are adopting enzymatic platforms to meet ECHA sustainability thresholds. The shift is compressing acid-hydrolysis capacity utilization rates among legacy Midwest processors.
The FDA's updated Food Allergen Labeling and Consumer Protection Act guidance on hydrolyzed protein declarations is forcing ingredient houses to reformulate for shorter, transparent labels. Manufacturers must now disclose hydrolysis method and starting material concentration rather than generic "natural flavor" designations. Clean-label meat alternative brands in the United States are accelerating supplier audits to verify enzymatic process claims.
Buyers are consolidating hydrolysate procurement around certified low-carbon suppliers with verified Scope 3 emissions data. European personal care conglomerates now require supplier-specific carbon intensity scores alongside peptide specifications. Dutch and German formulators are penalizing hydrolysate lots exceeding 2.5 kg CO2-eq per kilogram protein in tender evaluations.
Hydrolyzed Corn Protein Market Segmentation
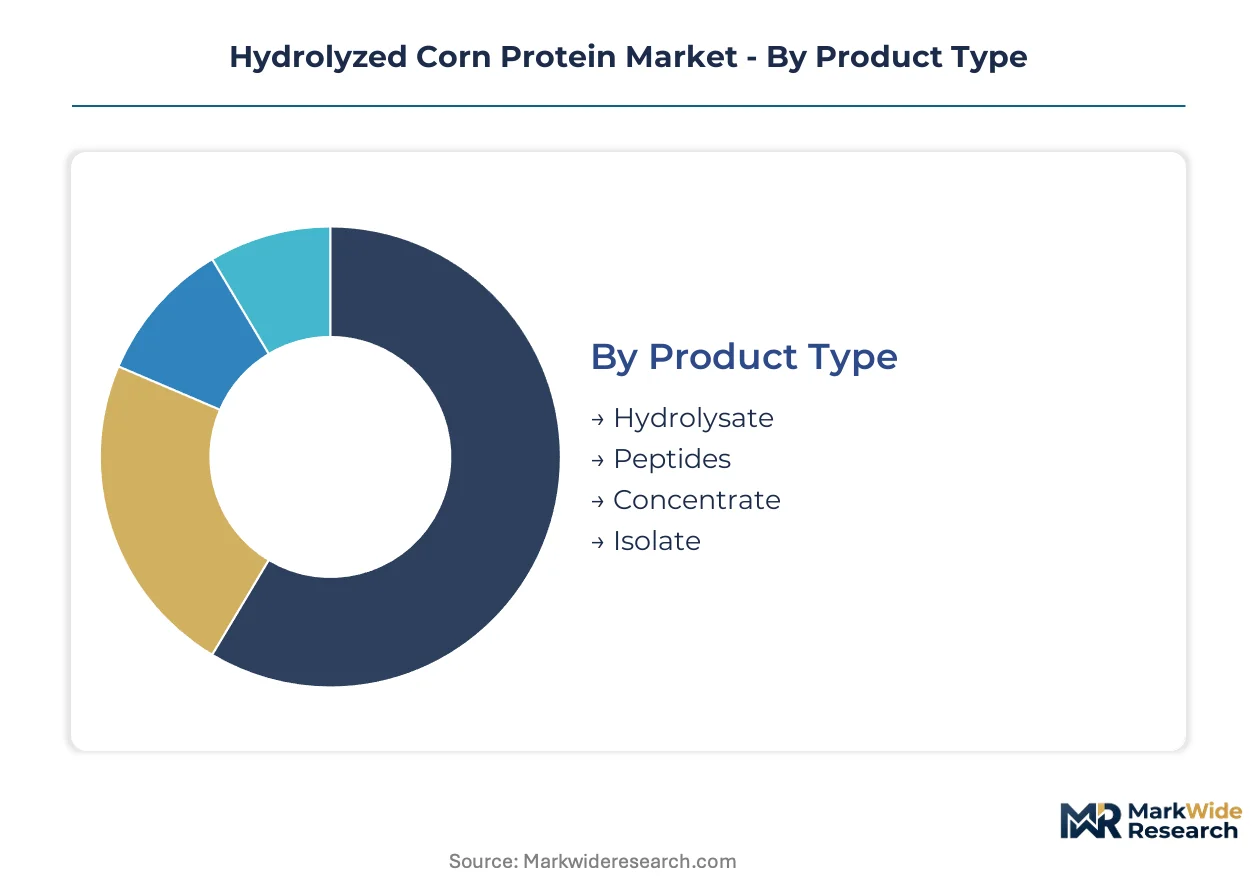
Segmentation in the hydrolyzed corn protein market reveals divergent margin structures across enzymatic versus acid-hydrolyzed product lines. Formulators face distinct substitution threats from soy and pea proteins depending on application certification requirements.
Product Type:
Substitution pressure concentrates in commodity-grade hydrolysates where soy protein maintains price parity, while peptide fractions defend margin through clinical nutrition exclusivity.
- Hydrolysate:Acid-catalyzed or enzymatically processed corn gluten yielding soluble amino acid mixtures with molecular weights spanning 200 to 10,000 Daltons. Midwest wet-milling complexes in Iowa and Illinois supply integrated processors who dominate merchant availability through captive corn streams.
- Peptides:Fractionated low-molecular-weight sequences below 1,000 Daltons optimized for bioactive functionality. Japanese medical food manufacturers under METI's functional food labeling system drive procurement for renal and hepatic disease formulations.
- Concentrate:Partially purified protein streams retaining higher carbohydrate fractions than isolates. Animal feed compounders in the United States leverage concentrates for cost-sensitive ruminant nutrition.
- Isolate:Highly purified fractions exceeding 90% protein content with minimal residual starch. Sports nutrition brands specify isolates for clean-label powder formulations despite premium positioning against soy alternatives.
Hydrolysate anchors the volume base while peptides gain share at the steepest rate.
Application:
Cost tier stratification separates premium-positioned personal care applications from price-competitive feed segments.
- Food & Beverages:Clean-label meat alternative formulators deploy hydrolyzed corn protein as umami precursors and binders. The USDA's FSIS streamlined approval process for enzymatically hydrolyzed proteins accelerates plant-based procurement timelines.
- Animal Feed:Structurally mature segment where price competition from soy meal and distiller's grains constrains margin expansion. Iowa and Illinois feed mills integrate wet-milling byproduct streams directly.
- Nutritional Supplements:Hypoallergenic peptide formulations targeting sports and clinical nutrition applications. German and Dutch specialty ingredient houses compete on carbon intensity certification tiers under EU Green Deal accounting.
- Personal Care:European cosmetic manufacturers displace animal-derived keratin with corn peptides. ECHA's animal testing bans accelerate botanical hydrolysate substitution in hair and skin formulations.
Animal feed retains the largest volume footprint while personal care demonstrates the most rapid expansion trajectory.
Form:
Supply concentration in powder processing reflects Midwest dry-blending infrastructure advantages over liquid handling networks.
- Powder:Spray-dried hydrolysates with superior shelf stability and flow characteristics for dry blend incorporation. United States ingredient distributors prioritize powder inventories for just-in-time delivery to food manufacturers.
- Liquid:Unconcentrated hydrolysate solutions requiring refrigerated logistics chains. Personal care formulators in France and Switzerland specify liquid peptides for cold-process cosmetic manufacturing.
- Granules:Agglomerated particles engineered for controlled dissolution in feed pelleting operations. Midwest feed producers favor granules for uniform distribution in bulk rations.
- Crystal:Highly purified amino acid crystallization products for pharmaceutical-grade applications. Japanese and German clinical nutrition manufacturers specify crystals for precise dosing formulations.
Powder commands the dominant share while liquid formats climb fastest among cosmetic peptide buyers.
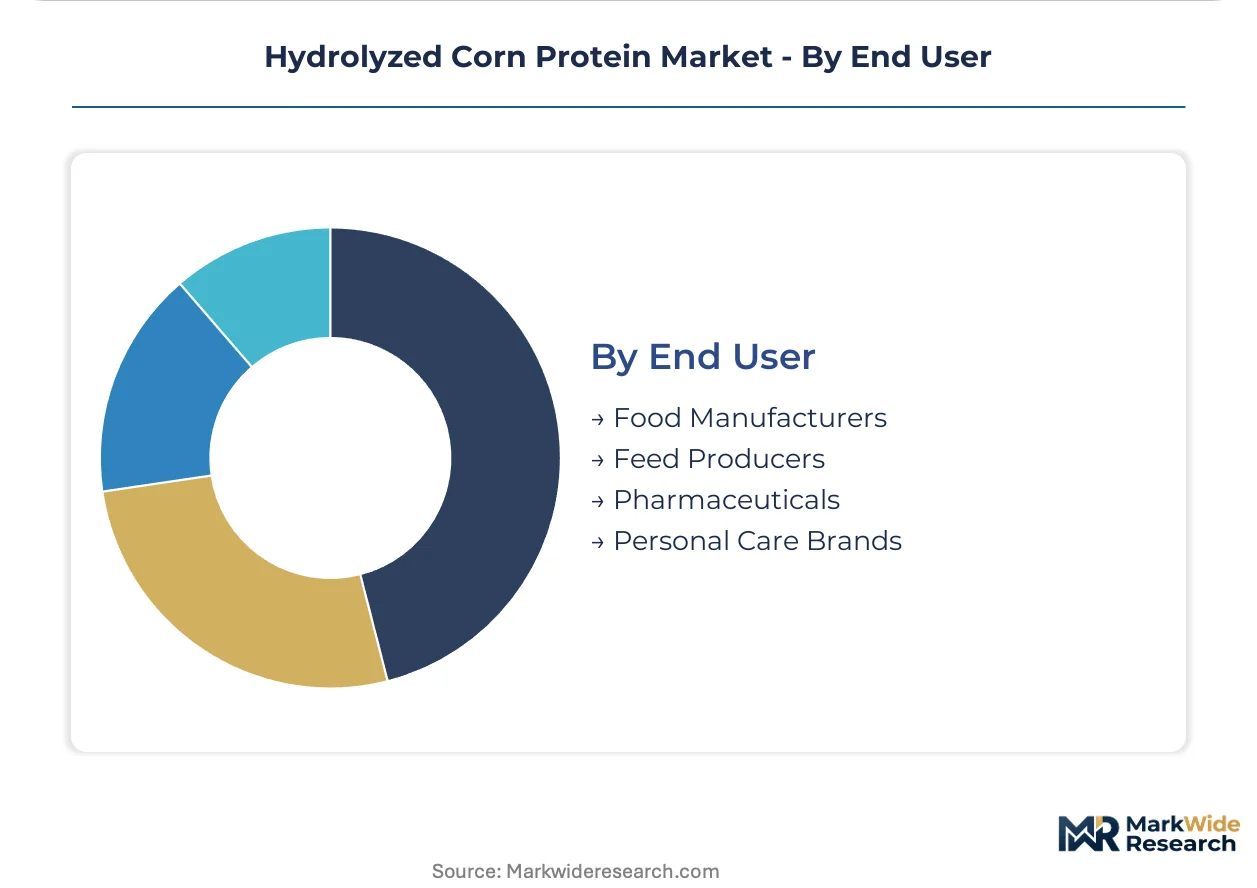
End User:
Customer type differentiation separates integrated processors with captive supply from merchant-dependent formulators facing feedstock volatility.
- Food Manufacturers:Plant-based meat producers in California and New York procure through specialized B2B marketplaces. Clean-label certification requirements drive supplier audit intensity for enzymatic process verification.
- Feed Producers:Midwest integrated operations source directly from wet-milling complexes, while coastal compounders rely on distributor networks exposed to Corn Belt drought risk.
- Pharmaceuticals:Medical food manufacturers in Japan formulate peptide-specific products for metabolic disease management. METI's functional food labeling rewards hypoallergenic protein sourcing.
- Personal Care Brands:European conglomerates mandate supplier-specific carbon intensity scores alongside peptide specifications. Dutch and Danish formulators penalize hydrolysate lots exceeding 2.5 kg CO2-eq per kilogram protein.
Food manufacturers represent the largest demand block while personal care brands expand procurement most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hydrolyzed corn protein trade flows reflect a pronounced export concentration from North American grain belts toward European and Asian formulation hubs. Import-dependent regions face feedstock vulnerability during Corn Belt harvest disruptions.
United States
Midwest wet-milling complexes in Iowa and Illinois supply over two-thirds of global merchant hydrolysate volumes. The EPA's effluent discharge regulations on acid-catalyzed processes push processors toward enzymatic retrofit investments. Chicago-area ingredient distributors coordinate just-in-time powder deliveries to coastal food manufacturers.
Germany
Specialty ingredient houses in Hamburg and Frankfurt deploy open-source enzymatic platforms following protease patent expirations. REACH compliance mandates drive substitution of animal-derived keratin with botanical hydrolysates in cosmetic applications. Bavarian contract laboratories command premium rates for peptide characterization and bioactivity validation services.
Japan
Medical food manufacturers in Tokyo and Osaka formulate hypoallergenic corn peptides for renal and hepatic disease patient populations. METI's functional food labeling system rewards peptide-based nutritional interventions with streamlined approval pathways. Kansai-region pharmaceutical compounders source crystalline amino acids for precise-dosing clinical nutrition products.
Netherlands
Ingredient traders in Rotterdam and Amsterdam construct low-carbon hydrolysate certification tiers under EU Green Deal farm-to-fork carbon accounting protocols. Dutch formulators penalize supplier lots exceeding 2.5 kg CO2-eq per kilogram protein in tender evaluations. Wageningen-area research clusters advance enzymatic hydrolysis efficiency for cosmetic peptide production.
France
Personal care conglomerates in Paris and Lyon mandate supplier-specific carbon intensity scores alongside peptide quality specifications. ECHA's animal testing bans accelerate botanical hydrolysate substitution in hair and skin formulations. Alsace-based cosmetic peptide manufacturers adopt fungal protease platforms to meet sustainability thresholds.
Hydrolyzed Corn Protein Market Competitive Landscape
Concentration sits with integrated grain processors who leverage captive corn supply and wet-milling infrastructure to dominate upstream hydrolysate production. Specialty ingredient houses compete through enzymatic hydrolysis R&D platforms and clean-label certification tiers. Three archetypes define competitive positioning: Midwest-based integrated processors with backward supply control, European specialists in non-GMO and organic-certified lines, and Asian medical-nutrition formulators. Dominant competitive moves include capacity expansion in low-carbon enzymatic processing and strategic partnerships with direct-to-brand e-commerce ingredient platforms.
Within the integrated processor tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify the Midwest-based archetype with upstream supply control. Roquette Frères occupies a specialist position among European clean-label ingredient houses. These three anchors represent divergent strategic vectors: captive grain supply versus enzymatic R&D platforms versus certification-driven market segmentation.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Roquette Frères |
| Kerry Group plc |
| Sensient Technologies Corporation |
| ADEKA Corporation |
| Döhler GmbH |
| Others |
Supply & Pricing Matrix
Midwest wet-milling capacity utilization above 85% anchors price floors for merchant hydrolysate while compressing margins for acid-catalyzed processors facing EPA effluent retrofit costs. This scale concentration grants integrated Iowa and Illinois operators disproportionate leverage over spot pricing, forcing specialty ingredient houses toward enzymatic premiums to escape commodity tier compression.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with quarterly adjustment clauses tied to corn futures. Price differentiation hinges on enzymatic certification grade and carbon intensity scoring tiers, with Dutch and Danish formulators penalizing lots exceeding 2.5 kg CO2-eq per kilogram protein. Cost compression in acid-hydrolyzed grades is intensifying because EPA compliance investments erode margin without quality offset. Feed compounders exhibit highest price sensitivity, while personal care brands absorb premiums for REACH-compliant peptide fractions.
Supply Chain Analysis
Just-in-time powder inventories dominate United States food manufacturer procurement, while European cosmetic formulators maintain strategic stockpiles of liquid peptides against Corn Belt harvest volatility. Geographic supply concentrates in the United States, Germany, and Japan, with raw material dependencies on corn gluten meal, fungal proteases, and crystallization solvents. Single-source vulnerability runs through Iowa and Illinois wet-milling complexes exposed to drought risk. Distribution runs through Chicago-area distributors for domestic reach and Rotterdam traders for EU carbon-certified tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soy protein substitution threatens incumbents across nutritional applications, demanding defensive repositioning around enzymatic process differentiation and carbon accounting advantages.
For Market Incumbents: Compound enzymatic R&D platforms with carbon intensity certification to defend margin against soy price parity. Secure backward integration into non-GMO corn streams to offset organic audit timeline compression. Prioritize EPA-compliant process retrofit ahead of effluent rule tightening. For New Entrants and Emerging Players: Anchor in Japanese clinical nutrition white space where METI functional food labeling rewards hypoallergenic peptide formulations. Target direct-to-brand e-commerce channels for California and New York cosmetic startups seeking REACH-compliant keratin substitutes. Lead with carbon accounting transparency as procurement differentiator. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty ingredient houses with enzymatic platform scale and dual USDA-EU organic certification capability. Long-term viability rests on peptide characterization infrastructure and contract laboratory access. Watch enzyme patent expiration velocity as inflection signal for process cost democratization.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Platform Scale-Up | EPA effluent rules favor enzymatic processors with lower compliance capital burden. |
| Carbon Intensity Certification | EU Green Deal accounting rewards verified Scope 3 emissions data in tender evaluations. |
| Direct-to-Brand Distribution | E-commerce ingredient platforms disintermediate legacy distributor networks for cosmetic startups. |
| Clinical Nutrition Partnership | Japanese medical food manufacturers seek hypoallergenic peptide supply under METI labeling. |
| Non-GMO Supply Integration | Identity preservation infrastructure defends margin against commodity corn price volatility. |
Research Methodology
The analysis maps enzymatic versus acid-hydrolyzed process tiers, each validated through procurement directors at plant-based meat formulators, cosmetic peptide buyers, feed compounders, and clinical nutrition manufacturers. Primary interview insights combined with secondary validation from FDA guidance documents, EPA effluent discharge records, ECHA REACH registrations, and METI functional food labeling databases. Bottom-up volume modeling and top-down value triangulation cross-checked against customs trade flows and wet-milling capacity disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include hydrolysis method, molecular weight fraction, application certification requirement, and regional carbon accounting framework. CAGRs derived from trend extrapolation of enzymatic adoption curves and feedstock cost trajectories. Industry-specific forecast inputs incorporate enzyme patent expiration schedules and EU farm-to-fork carbon scoring implementation timelines.
Underlying assumptions cover corn yield stability, regulatory enforcement continuity, and alternative protein substitution rates, with deviation risk concentrated in Corn Belt climate events and REACH amendment timelines. Forecasts reflect these documented conditions with sensitivity analysis for drought-induced feedstock disruption scenarios. Revision becomes warranted when enzymatic process cost parity crosses acid-catalyzed thresholds or when carbon intensity scoring mandates expand beyond EU borders.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Bangladesh Mustard Oil Market
Ingredients
Pea Hull Fiber Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
Collagen Casings Market
Ingredients
USA Yeast Extracts Market
Ingredients
Hydrolyzed Oat Protein Market
Ingredients
Canada Soy Protein Market
Ingredients
North America Dairy Ingredients Market
Ingredients
Europe Malt Extract Market
Ingredients
Smoke Ingredients for Food Market
Ingredients
Drum to Hopper Blends Market
Ingredients
Global Gelatin Market
Ingredients
North America Rice Protein Ingredients Market
Ingredients
Sodium Caseinate Market
Ingredients
Corn Gluten Meal Market
Ingredients
Hydrogenated Palm Oil Market