
 Potassium Zirconium Fluoride Market | 2026-2036
Potassium Zirconium Fluoride Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Zirconium Fluoride Market Analytics
China's expanding fluoride chemical capacity is rewriting regional supply dynamics for potassium zirconium fluoride. H.C. Starck GmbH leverages its tungsten and refractory metals heritage to anchor European specialty fluoride distribution. American Elements sustains North American availability through in-house synthesis of high-purity inorganic salts. OCI Company Ltd. competes on integrated fluorine chemistry platforms that extend from raw ore to refined potassium zirconium fluoride.
Potassium zirconium fluoride is a white crystalline inorganic salt with the formula K2ZrF6, typically synthesized via reaction of zirconium oxide with hydrofluoric acid and potassium fluoride at controlled temperatures to yield purities exceeding 99%. The compound serves primarily as a fluxing agent in aluminum brazing, a precursor for zirconium dioxide coatings, and a surface treatment modifier in glass and ceramics manufacturing. Powder and granule grades dominate current volume flows, with crystal formulations commanding premium positioning in electronics-grade applications. Aerospace end-use channels represent the fastest-expanding demand pool, while automotive coatings applications remain structurally mature with stable offtake patterns.
EPA oversight of fluoride emissions shapes US manufacturing site requirements, while REACH registration obligations govern European market access for imported potassium zirconium fluoride. China's MEE enforces wastewater discharge limits that raise compliance costs for domestic producers. Stakeholders must monitor how carbon border adjustment mechanisms and evolving fluorine chemical restrictions reshape competitive access across major demand centers.
Market Dynamics
China's MIIT dual carbon goals are tightening emissions standards for inorganic fluoride production, forcing European ceramic producers to restructure supply chain sourcing and accelerating the search for lower-carbon precursor alternatives.
Growth Catalysts
- Aerospace coatings demand:Fluorinated zirconium compounds replace conventional surface treatments in turbine blade and airframe applications, with Germany's industrial ceramics corridor driving specification upgrades.
- REACH registration compliance:European market access requirements favor established producers with full dossier submissions, consolidating procurement around certified supply channels.
- Electronics-grade crystal formulations:Semiconductor packaging and precision glass manufacturers specify ultra-high purity grades, creating premium positioning for specialized synthesis capabilities.
Market Restraints
- Hydrofluoric acid feedstock volatility:Input costs fluctuate with fluorite ore availability and Chinese export quota administration, compressing margin stability for non-integrated producers.
- Supply concentration in Shandong and Henan provinces:Domestic Chinese capacity controls 60% of global refined output, exposing buyers to single-geography disruption risk.
- Technical limitation in aqueous process efficiency:Wet synthesis routes generate fluoride-rich wastewater requiring MEE-compliant treatment infrastructure, raising capital intensity for new entrants.
Strategic Opportunities
- Underpenetrated Indian aluminum brazing market:Domestic HVAC and automotive radiator production expansion under PLI scheme incentives creates demand for fluxing agent supply localization.
- EU Green Deal fluorine chemical restrictions:Phasedown of high-GWP alternatives redirects coating formulation R&D toward stable inorganic fluorides with lower lifecycle emissions profiles.
- Direct-to-mill procurement platforms:Specialty chemical distributors are building digital channels linking German precision glass manufacturers to qualified potassium zirconium fluoride stockists.
Industry Challenges
- Fluorine chemist talent scarcity:Specialized expertise in HF handling and zirconium separation is concentrating at legacy tungsten and refractory metals producers, constraining new facility staffing.
- Multi-jurisdiction certification timelines:Simultaneous EPA pre-manufacture notification and REACH registration processes extend market entry lead times to 18-24 months for novel synthesis routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Zirconium Fluoride Market |
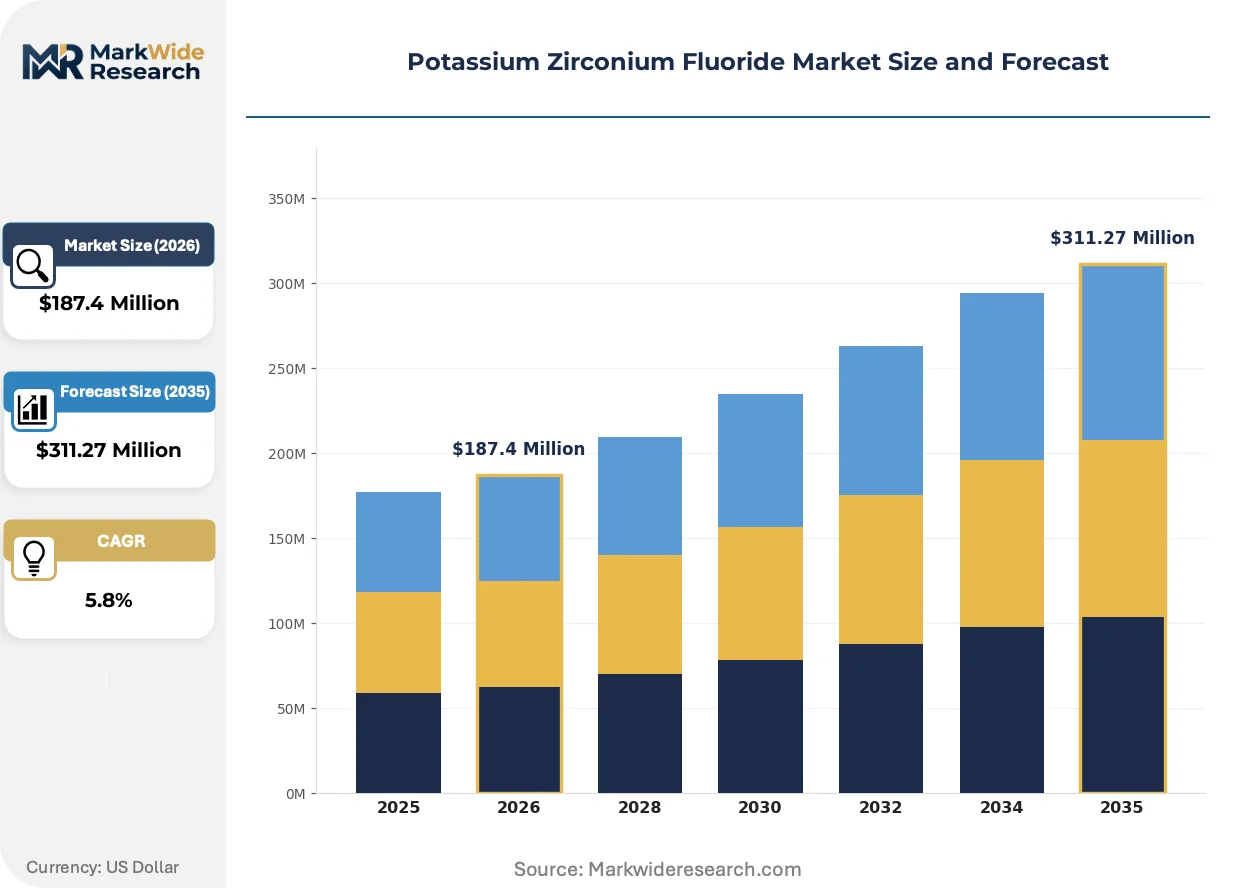
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Crystals, Solution Application: Ceramics, Glass, Electronics, Coatings End User: Aerospace, Automotive, Consumer Goods, Pharmaceuticals Distribution Channel: Online, Retail, Distributors, Direct Sales |
| Companies Covered | American Elements, Ambinter SARL, abcr GmbH, Alfa Chemistry, Fluorochem Ltd., ArrakisTek Inc., H.C. Starck GmbH, OCI Company Ltd., KJ Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Zirconium Fluoride Market Evolving Landscape
Process control technologies and regulatory compliance automation are reshaping how potassium zirconium fluoride is synthesized, certified, and delivered to end-use channels across aerospace and electronics verticals.
Closed-loop fluoride recovery systems are digitizing waste stream management in Chinese production facilities. MIIT-monitored enterprises deploy real-time effluent sensors to maintain MEE discharge compliance. This technology compression is enabling continuous operation permits that batch-process competitors cannot secure.
The EU F-Gas Regulation phase-down is redirecting coating formulation portfolios toward inorganic fluoride alternatives. Industrial ceramics manufacturers now specify potassium zirconium fluoride in surface treatment protocols previously dependent on fluorinated gases. German precision glass clusters are fastest to adapt procurement specifications to these revised compliance baselines.
Specification-driven purchasing is consolidating buyer decision authority at technical directors rather than procurement generalists. Electronics-grade crystal formulations now require certificate of analysis documentation with every lot, displacing spot-market spot-checking. This pattern is most visible in Japan's semiconductor packaging supply base, where METI-guided quality frameworks enforce supplier qualification rigor.
Potassium Zirconium Fluoride Market Segmentation
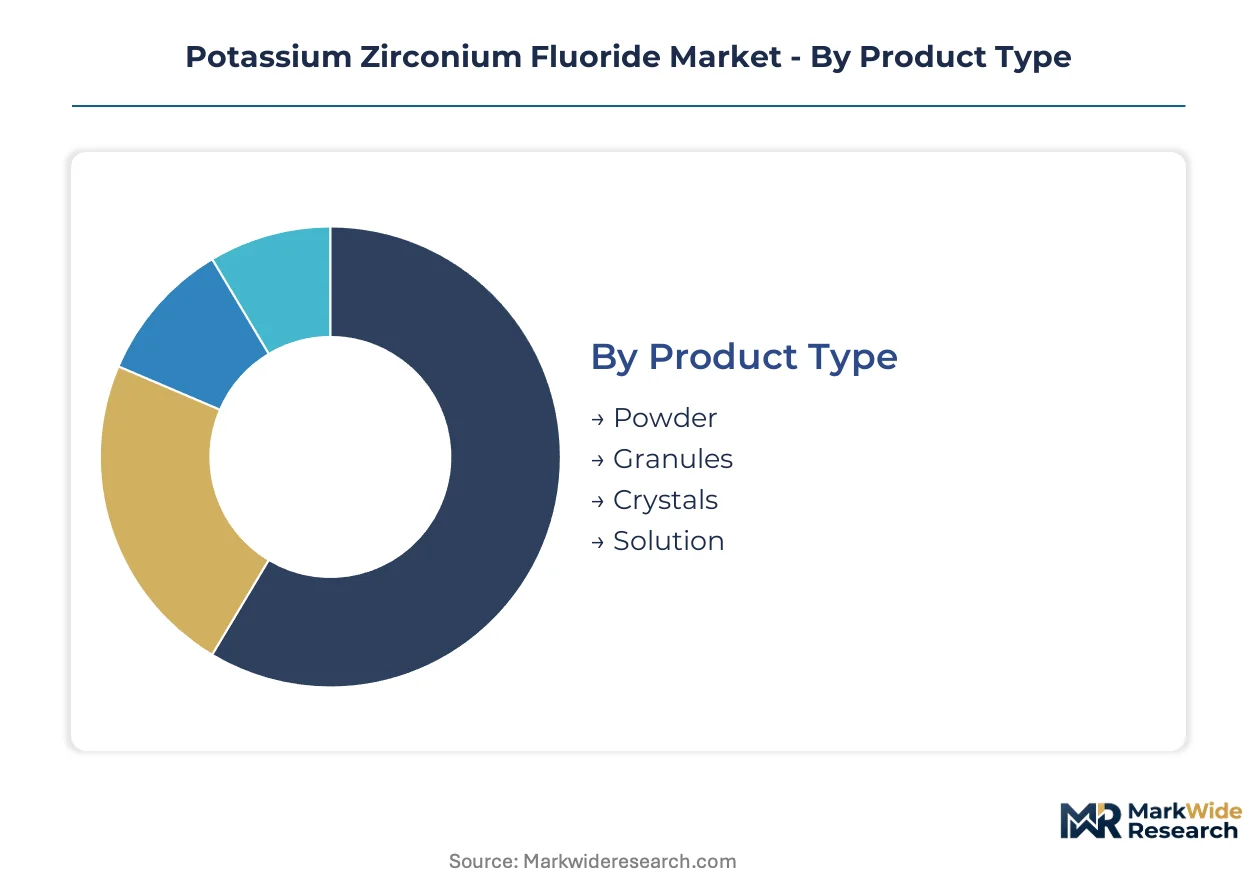
Segmentation in potassium zirconium fluoride markets reveals how specification grades align with distinct procurement channels and end-use certifications. Powder and crystal grades diverge sharply in pricing logic and supplier qualification requirements. Aerospace and electronics verticals impose purity thresholds that reshape competitive positioning across product categories.
Product Type:
Mature powder and granule formats dominate volume flows, while crystal formulations occupy an emerging premium tier driven by semiconductor packaging specifications.
- Powder:Fine particulate grades serve aluminum brazing flux applications where surface area drives reactivity. Demand concentrates in German industrial ceramics corridors, with REACH registration compliance filtering supplier pools to certified European distributors.
- Crystals:Electronics-grade formulations exceed 99% purity specifications for precision glass and semiconductor packaging. Japan's METI-guided quality frameworks enforce lot-level certificate of analysis documentation, displacing spot-market procurement patterns.
- Granules:Intermediate sizing optimizes handling characteristics for automated brazing line feed systems.
- Solution:Aqueous preparations target specialized coating deposition processes requiring controlled viscosity.
Powder retains volume leadership; crystals hold the steepest expansion curve.
Application:
Cost tier differentiation separates commodity fluxing applications from specification-driven surface treatment protocols.
- Ceramics:Fluxing agent demand in precision ceramic manufacturing ties directly to aluminum metallization processes. China's MIIT emissions standards are restructuring supply chain sourcing for European producers seeking lower-carbon precursor alternatives.
- Electronics:Semiconductor packaging and precision glass manufacturers specify ultra-high purity grades. German precision glass clusters adapted procurement specifications fastest to EU F-Gas Regulation phase-down compliance baselines.
- Glass:Surface treatment modifiers improve optical clarity and thermal shock resistance in specialty glass production.
- Coatings:Aerospace turbine blade and airframe applications favor fluorinated zirconium compounds replacing conventional surface treatments.
Ceramics commands procurement volume; electronics generates the highest margin realization per kilogram.
End User:
Customer type segmentation maps directly to certification burden and contract structure complexity.
- Aerospace:Turbine blade coating specifications demand full REACH dossier submissions and lot traceability. Germany's industrial ceramics corridor drives specification upgrades as fluorinated zirconium compounds displace legacy surface treatments.
- Automotive:Radiator brazing applications represent a structurally mature demand pool with stable offtake patterns and price-sensitive procurement.
- Consumer Goods:Decorative glass and ceramic applications tolerate broader purity tolerances than industrial specifications.
- Pharmaceuticals:Packaging glass requirements impose pharmacopeial compliance standards on raw material qualification.
Automotive anchors baseline volume; aerospace climbs the fastest on specification premium capture.
Distribution Channel:
Supply concentration shapes channel strategy, with qualified stockist networks controlling access to certified grades.
- Distributors:Specialized chemical distributors anchor European supply, with H.C. Starck GmbH leveraging tungsten and refractory metals heritage to control specialty fluoride distribution. Digital procurement platforms now link German precision glass manufacturers directly to qualified stockists.
- Direct Sales:Large-volume aerospace and electronics manufacturers negotiate frame contracts with integrated producers. American Elements sustains North American availability through in-house synthesis capabilities.
- Online:Spot-market platforms serve research quantities and non-certified industrial applications.
- Retail:Limited to small-scale laboratory and educational supply channels.
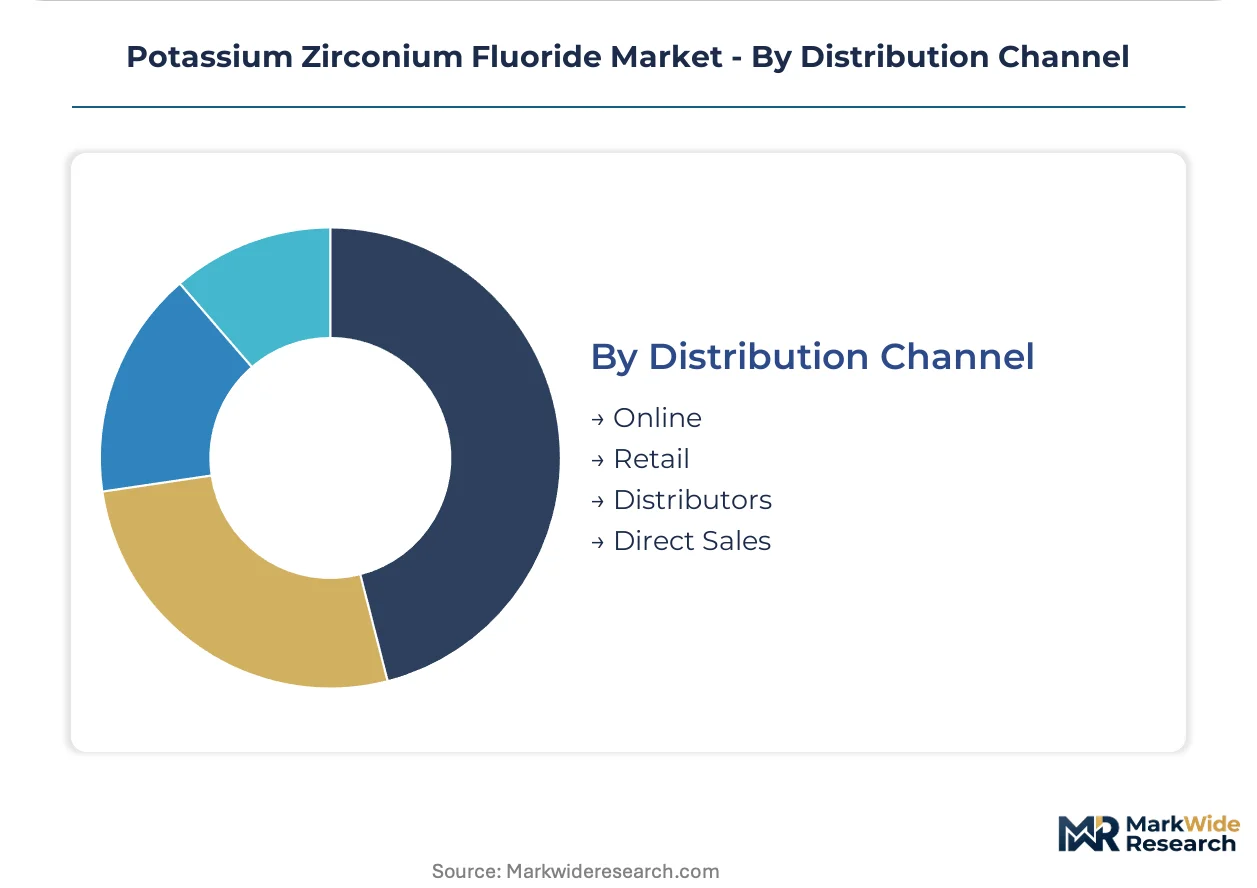
Distributors retain channel leadership; direct sales gains share fastest on aerospace contract consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites European specialty fluoride distribution, while China's high-speed rail network connects Shandong and Henan production basins to coastal export terminals.
China
Shandong and Henan provinces host concentrated inorganic fluoride refining capacity serving aluminum brazing and ceramics applications. MIIT dual carbon goals enforce emissions caps that raise compliance costs for domestic producers. Qingdao's port facilities handle bulk export flows to German industrial ceramics corridors.
Germany
Precision glass and electronics manufacturers in Bavaria and Baden-Württemberg drive specification-grade demand for crystal formulations. REACH registration obligations filter supplier pools to certified European distributors. The Rhine-Main industrial cluster anchors specialty chemical procurement for aerospace coating applications.
United States
EPA pre-manufacture notification requirements shape site selection for fluoride chemical processing. Aerospace manufacturers in the Pacific Northwest and Southeast source through direct sales channels with integrated producers. Texas Gulf Coast petrochemical infrastructure supports hydrofluoric acid feedstock availability.
Japan
Semiconductor packaging manufacturers in the Kanto region enforce METI-guided quality frameworks requiring lot-level certification. Electronics-grade crystal formulations command premium positioning over powder grades. Osaka-based precision glass clusters adapted procurement specifications fastest to EU F-Gas Regulation compliance baselines.
India
PLI scheme incentives expand domestic HVAC and automotive radiator production, creating demand for aluminum brazing flux localization. CDSCO import regulations govern pharmaceutical-grade packaging glass raw material qualification. Gujarat's chemical processing zones attract specialty fluoride distribution investments.
Potassium Zirconium Fluoride Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The vendor base organizes around three strategic archetypes: integrated fluorine chemistry platforms extending from raw ore to refined salt, specialty chemical distributors leveraging heritage in refractory metals, and in-house synthesis operations sustaining regional availability. Competitive moves concentrate on backward integration into hydrofluoric acid supply and geographic expansion through qualified stockist networks.
Among Germany-based fabricators, H.C. Starck GmbH anchors European specialty fluoride distribution through its tungsten and refractory metals heritage. American Elements exemplifies the in-house synthesis archetype, sustaining North American availability of high-purity inorganic salts. OCI Company Ltd. represents the integrated platform model, with Korean operations spanning fluorine chemistry from raw material processing through refined potassium zirconium fluoride output.
| Leading Market Players |
|---|
| American Elements |
| Ambinter SARL |
| abcr GmbH |
| Alfa Chemistry |
| Fluorochem Ltd. |
| ArrakisTek Inc. |
| H.C. Starck GmbH |
| OCI Company Ltd. |
| KJ Chemicals |
| Others |
Value Network & Pricing Analysis
Shandong and Henan province production clusters anchor global refined output capacity, concentrating pricing power among integrated fluorine chemistry platforms while exposing downstream buyers to single-geography disruption premiums. Crystal formulations for semiconductor packaging command substantial markups over powder grades used in aluminum brazing, with electronics-grade purity thresholds filtering supplier pools to certified channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates electronics-grade crystal formulations from industrial powder grades and commodity granule formats. Price differentiation hinges on certification grade and volume scale, with REACH-registered lots commanding premiums over non-certified alternatives. Pricing pressure stems from hydrofluoric acid feedstock volatility tied to Chinese fluorite ore export quotas. Automotive radiator brazing applications exhibit highest price sensitivity, while aerospace coating specifications tolerate premium capture for lot traceability.
Supply Chain Analysis
Fluorite ore availability from Chinese mining operations and hydrofluoric acid processing capacity in Shandong province feed into refined potassium zirconium fluoride output. Supply concentrates in China, with secondary capacity in Germany and the United States serving specification-grade demand. Single-source vulnerability runs through Shandong-Henan production basins controlling sixty percent of global refined output. Distribution runs through specialized chemical distributors in European industrial ceramics corridors, with direct sales channels gaining share among large-volume aerospace manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against organic fluorinated gas alternatives displaced by EU F-Gas Regulation phase-down, as coating formulators redirect R&D toward stable inorganic fluorides with favorable lifecycle emissions profiles.
For Market Incumbents: Build certification moats through simultaneous EPA pre-manufacture notification and REACH dossier submissions to extend lead times for novel synthesis competitors. Anchor procurement relationships with German precision glass clusters adapting specifications fastest to EU F-Gas Regulation compliance baselines. Prioritize backward integration into hydrofluoric acid supply to buffer margin compression from fluorite ore quota volatility.
For New Entrants and Emerging Players: India's underpenetrated aluminum brazing market offers white-space expansion as PLI scheme incentives expand domestic HVAC and automotive radiator production. Target Gujarat chemical processing zones for distribution infrastructure investments serving localized flux demand. Pursue direct-to-mill digital procurement platforms linking qualified stockists to precision glass manufacturers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated fluorine chemistry platforms with captive ore-to-salt processing capabilities and long-term aerospace frame contracts. Five-to-ten year viability favors producers with MEE-compliant wastewater treatment infrastructure securing continuous operation permits. Monitor CDSCO import regulation evolution for pharmaceutical-grade packaging glass raw material qualification as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HF Supply | Captive hydrofluoric acid production buffers margin compression from Chinese fluorite export quotas. |
| REACH Dossier Completion | Full registration submissions filter European supplier pools to certified channels. |
| Electronics-Grade Crystal Capacity | Ultra-high purity synthesis capabilities capture premium positioning in semiconductor packaging. |
| Indian Distribution Localization | Gujarat chemical zone investments serve PLI-scheme-driven aluminum brazing demand expansion. |
| Closed-Loop Fluoride Recovery | MEE-compliant waste stream management secures continuous operation permits in Chinese facilities. |
Research Methodology
A spread of perspectives from fluorine chemistry plant managers, procurement leads at aerospace OEMs, specialty chemical distribution partners, and technical R&D directors converged on the working assumptions. Primary interview insights combined with secondary validation from customs trade data, ACC industry reports, SEC 10-K filings, and MIIT emissions disclosure records. Bottom-up volume estimates triangulated against top-down demand aggregation across end-use applications.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeling across grade tier, end-use industry, and regional production hub dimensions. CAGRs derived from trend extrapolation adjusted for regulatory inflection points and feedstock cost trajectories. Forecast inputs incorporated MEE wastewater compliance cost curves and EU F-Gas Regulation phase-down timelines.
Macroeconomic conditions sit as an overlay; deviation in Chinese industrial production indices and aerospace capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding fluorite ore availability and REACH registration enforcement intensity. Cross-checking against EIA industrial chemical production benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Asia-Pacific Methyl Acrylate Market
Chemicals
Global Cysteine Market
Chemicals
Benzhydrol Market
Chemicals
Global N-Butanol Market
Chemicals
Global Amines Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Diethylenetriamine (DETA) Market
Chemicals
Fluorine Derivatives Market
Chemicals
Hypophosphorous Acid Market
Chemicals
Menadione Market
Chemicals
Sulfur Chemicals Market
Chemicals
Europe Calcium Peroxide Market
Chemicals
Trichlorosilane Market
Chemicals
Isopropanolamine Market
Chemicals
Global Wood Preservative Chemicals and Coatings Active Ingredients Market
Chemicals
Hexafluorosilicic Acid Market