
 Zirconium Market | 2026-2036
Zirconium Market Size, Share, and Industry Trends Forecast 2026-2036
Zirconium Market Intelligence
Long-term supply contracting is rebalancing buyer choice away from spot purchases toward bundled multi-year agreements with technical service attachments. Iluka Resources leverages its integrated mineral sands portfolio to secure feedstock for zirconium chemical production. Tronox Holdings anchors its position through Ti-Zr co-production economics at Australian and South African operations. Rio Tinto competes via vertical integration from mining through refined zirconium chemicals.
Zirconium is a lustrous, grey-white transition metal with atomic number 40, extracted primarily from zircon sand through chlorination or alkali fusion processes yielding zirconium tetrachloride or zirconium oxide; its exceptional corrosion resistance and low neutron absorption cross-section make it indispensable for nuclear fuel cladding and structural components. Zirconium oxide commands the largest product-type position due to its dominance in ceramic refractories and oxygen sensors, while zirconium metal captures premium margins from nuclear and aerospace specifications. Nuclear reactors represent the most structurally defended application segment given regulatory certification barriers and multi-decade qualification protocols.
The United States Nuclear Regulatory Commission enforces 10 CFR Part 50 appendices governing zirconium alloy composition and corrosion performance in light water reactors, while China's National Nuclear Safety Administration implements GB standards for indigenous reactor designs. ASTM International and ISO maintain mechanical testing and chemical assay protocols that define market access thresholds. Stakeholders must monitor regulatory divergence between Western and Chinese nuclear qualification pathways when allocating R&D and certification budgets.
Market Dynamics
Nuclear reactor construction programs across China and India are compressing qualification timelines for zirconium alloy suppliers while simultaneously tightening purity specifications under divergent regulatory pathways.
Growth Catalysts
- Pressurized heavy water reactor expansion:India's indigenous PHWR program is accelerating procurement of zirconium-niobium alloys for pressure tubes and calandria tubes.
- China's National Nuclear Safety Administration GB standards:Domestic reactor certification requirements are mandating localized zirconium supply chains for indigenous Hualong One designs.
- Chlorination process advances:Improved zirconium tetrachloride reduction yields are lowering production costs for nuclear-grade sponge.
Market Restraints
- Mineral sands concentration:Over 80% of zircon feedstock originates from Australian and South African heavy mineral sand operations, creating geographic supply vulnerability.
- Alkali fusion energy intensity:Zirconium oxide production requires sustained high-temperature processing, exposing margins to natural gas and electricity price volatility.
- Ceramic refractory substitution:Alumina-magnesia spinels and yttria-stabilized alternatives are displacing zirconia in select high-temperature insulation applications.
Strategic Opportunities
- Small modular reactor qualification:US NRC 10 CFR Part 53 framework is creating streamlined certification pathways for advanced zirconium alloy cladding in microreactor designs.
- Biomedical oxygen sensor penetration:Zirconia-based electrochemical sensors for continuous glucose monitoring represent underdeveloped demand in wearable health technology.
- EU Green Deal critical raw materials list:Zirconium's inclusion is triggering strategic stockpiling mandates and domestic processing incentives across European member states.
Industry Challenges
- Nuclear-grade certification timelines:Multi-decade qualification protocols for new alloy compositions delay commercialization and tie up R&D capital.
- Neutron cross-section metrology:Specialized testing infrastructure for hafnium content verification creates bottlenecks in quality assurance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zirconium Market |
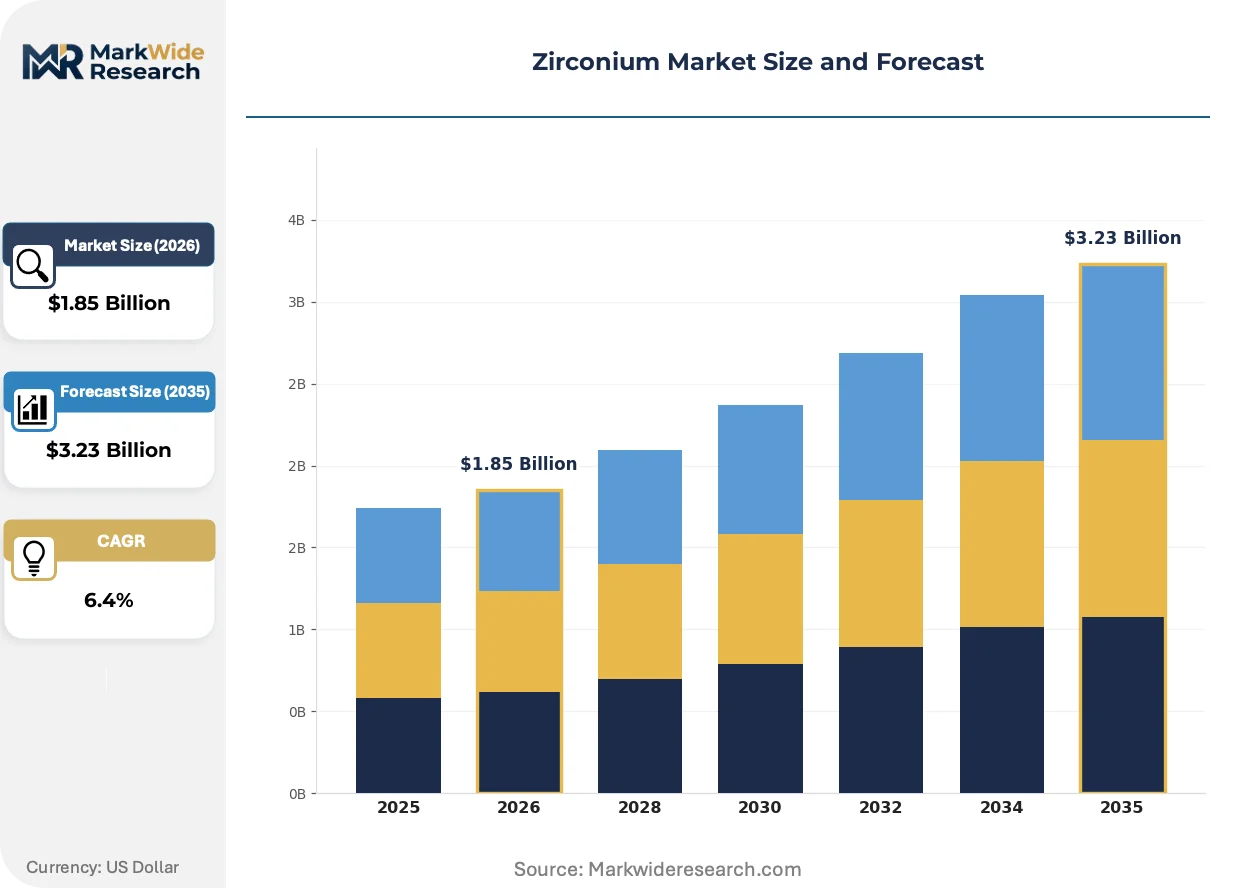
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zirconium Oxide, Zirconium Ferroalloy, Zirconium Powder, Zirconium Metal Application: Nuclear Reactors, Aerospace Components, Medical Devices, Chemical Processing End User: Aerospace Industry, Healthcare Sector, Industrial Manufacturing, Electronics Form: Ingots, Wires, Sheets, Powders |
| Companies Covered | Iluka Resources Limited, Tronox Holdings plc, Rio Tinto Group, Kenmare Resources plc, Australian Strategic Materials Ltd, Base Resources Limited, Eramet SA, Saint-Gobain ZirPro, Iwatani Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zirconium Market Strategic Shifts & Innovations
Electrochemical processing advances and regulatory divergence between Western and Chinese nuclear pathways are fragmenting technical standards while opening parallel commercialization tracks.
Additive manufacturing of zirconium alloy components is decentralizing production of complex reactor hardware. Westinghouse and Framatome are qualifying laser powder bed fusion for fuel spacer grid fabrication. Distributed manufacturing is compressing lead times for replacement parts while reducing inventory carrying costs at reactor sites.
REACH compliance in Europe is tightening purity specifications for hafnium separation in nuclear-grade zirconium. ECHA substance evaluation protocols are mandating enhanced traceability from mineral sand through sponge reduction. European fuel fabricators are responding by consolidating supplier audits and demanding batch-level isotopic certification.
Long-term contracting is displacing spot purchasing across nuclear fuel supply chains. Utilities in France, South Korea, and Canada are bundling multi-year zirconium alloy procurement with technical service agreements for in-core corrosion monitoring. This behavior is most visible in markets with state-backed reactor fleets where procurement centralization enables volume aggregation.
Zirconium Market Segmentation
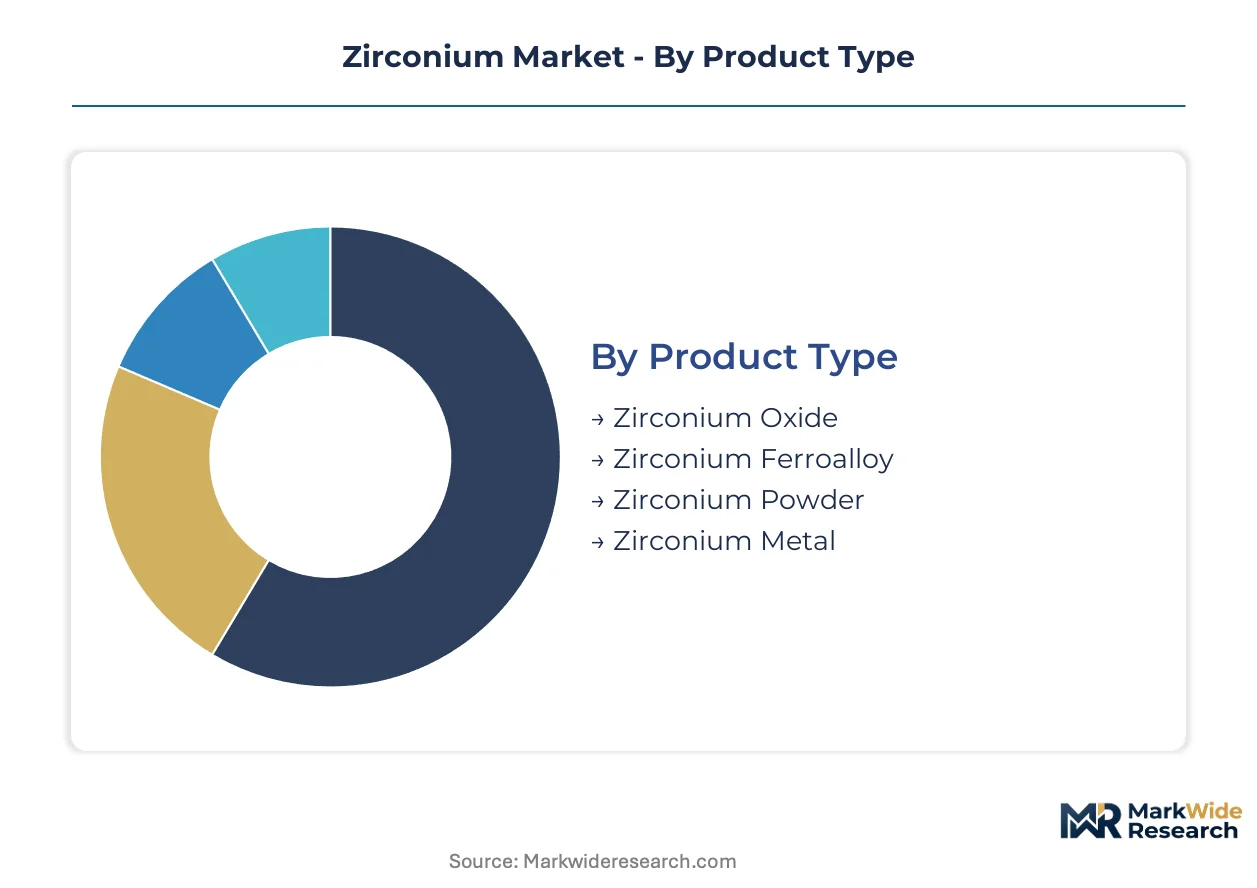
Zirconium's nuclear certification requirements fragment supply chains by purity tier, with reactor-grade specifications commanding dedicated production lines and multi-year qualification timelines. Segmentation in this market directly maps to regulatory burden intensity, creating divergent margin structures across product categories.
Product Type:
Nuclear-grade certification under NRC 10 CFR Part 50 and China's GB standards applies differentially across these product categories, with sponge and metal facing the steepest compliance barriers.
- Zirconium Oxide:Ceramic-grade zirconia dominates refractory and oxygen sensor applications with less stringent hafnium separation requirements. Demand concentrates in China's construction ceramics sector and EU automotive sensor mandates under F-Gas Regulation compliance timelines.
- Zirconium Metal:Reactor-grade sponge requires hafnium content below 100ppm and multi-decade alloy qualification protocols. Procurement is accelerating for India's PHWR pressure tube program and China's Hualong One fuel cladding specifications.
- Zirconium Ferroalloy:Steel deoxidation applications in industrial manufacturing require minimal purification, sourcing from mineral sand co-product streams without nuclear certification overhead.
- Zirconium Powder:Additive manufacturing feedstock for aerospace and medical implants is gaining traction under ASTM F2924 qualification pathways, with laser powder bed fusion adoption at Westinghouse and Framatome driving specification development.
Leading the category by volume: Zirconium Oxide. Growing fastest: Zirconium Metal.
Application:
End-use segmentation reveals a stark cost-tier split between nuclear applications absorbing certification premiums and industrial uses competing on commodity economics.
- Nuclear Reactors:Fuel cladding and structural components command the highest purity specifications with hafnium separation adding 30-50% to base material costs. China's National Nuclear Safety Administration GB standards and US NRC 10 CFR Part 50 create divergent qualification pathways that fragment supplier access.
- Aerospace Components:Turbine blade coatings and structural alloys leverage zirconium's corrosion resistance without neutron cross-section constraints, accessing faster commercialization timelines than nuclear grades.
- Medical Devices:Orthopedic implants and dental ceramics operate under FDA 510(k) and EU MDR pathways, with zirconia femoral heads representing mature demand in Japan's aging demographic.
- Chemical Processing:Heat exchangers and reactor vessels exploit acid resistance in sulfuric acid production environments, competing against titanium and tantalum on total installed cost.
Volume concentration: Nuclear Reactors. Steepest expansion trajectory: Aerospace Components.
End User:
Customer-type segmentation tracks procurement centralization, with state-backed nuclear utilities aggregating volume against fragmented industrial buyers.
- Aerospace Industry:Tier-1 engine manufacturers source superalloy master melts containing zirconium through long-term offtake agreements with integrated miners, with Rolls-Royce and Pratt & Whitney driving specification harmonization.
- Healthcare Sector:Dental laboratories and orthopedic device firms purchase zirconia blanks through distributor networks, with CAD/CAM milling center proliferation decentralizing demand geographically.
- Industrial Manufacturing:Refractory consumers in steel and glass production exhibit price-sensitive spot purchasing behavior, with Chinese construction ceramics dominating regional consumption patterns.
- Electronics:Solid oxide fuel cell manufacturers and oxygen sensor producers require high-purity stabilized zirconia, with Bosch and Continental automotive sensor programs representing concentrated demand nodes.
Dominant buyer type by spend: Aerospace Industry. Expanding most quickly: Electronics.
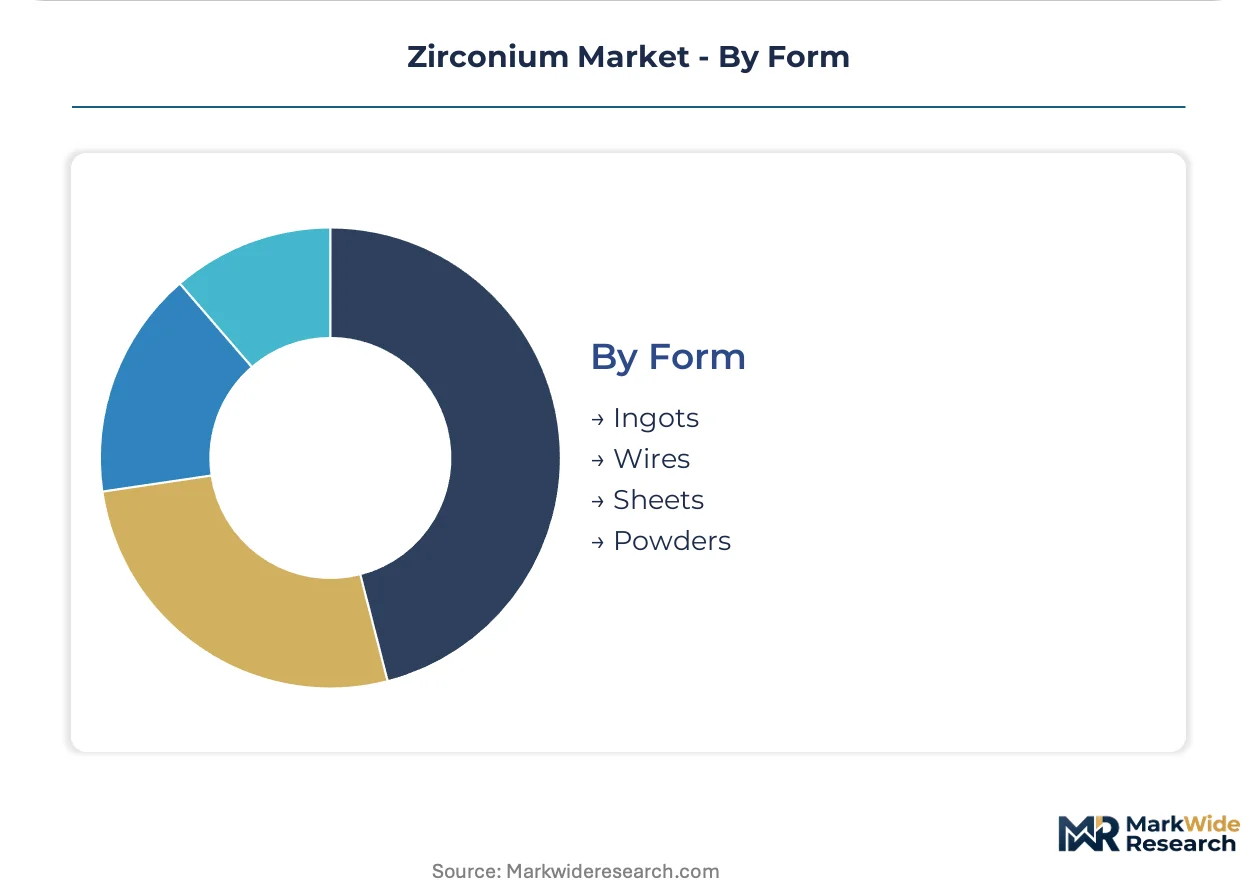
Form:
Physical form segmentation aligns with downstream processing economics, with melt-based forms capturing value-add margin and powders enabling distributed manufacturing.
- Ingots:Vacuum arc remelted nuclear-grade ingots supply tube-reduction mills at Framatome and Westinghouse fuel fabrication facilities, with ASTM B350 and ISO 10263 governing dimensional and chemical tolerances.
- Wires:Fine-diameter welding wire serves aerospace MRO applications and chemical equipment repair, with spool packaging formats optimized for robotic welding cell integration.
- Sheets:Cold-rolled plate and strip support heat exchanger fabrication for sulfuric acid service, with gauge thickness correlating to pressure rating requirements in ASME Boiler and Pressure Vessel Code compliance.
- Powders:Gas-atomized spherical powder enables laser powder bed fusion of complex fuel spacer grids, with particle size distribution specifications tightening as additive manufacturing matures for nuclear component qualification.
Highest volume form: Ingots. Gaining share fastest: Powders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia and South Africa dominate zircon sand production, while China and India absorb the bulk of nuclear-grade refined output. This geographic split between upstream mining and downstream fabrication shapes trade flows and regulatory alignment challenges.
China
China's reactor construction pipeline drives procurement of zirconium-niobium alloys for Hualong One fuel cladding. The National Nuclear Safety Administration enforces GB standards mandating localized supply chains for indigenous reactor designs. Shanghai and Sichuan host sponge reduction and tube fabrication facilities serving CNNC and CGN reactor programs.
India
India's PHWR expansion accelerates demand for zirconium-niobium pressure tubes and calandria tubes. The Atomic Energy Regulatory Board oversees indigenous qualification protocols for Nuclear Fuel Complex suppliers. Hyderabad anchors domestic zirconium alloy production through NFC's integrated fabrication complex.
United States
US utilities source nuclear-grade zirconium through long-term contracts with Western fuel fabricators. The NRC enforces 10 CFR Part 50 appendices governing alloy composition and corrosion performance. Western Pennsylvania and South Carolina concentrate tube-reduction mills serving Westinghouse and Framatome fuel facilities.
France
France's reactor fleet sustains demand for zirconium alloy cladding through state-backed procurement by EDF. ECHA REACH protocols tighten hafnium separation requirements and traceability mandates. The Rhône-Alpes region hosts Framatome's fuel fabrication and research infrastructure.
Australia
Australia supplies over 40% of global zircon feedstock from heavy mineral sand operations in Western Australia. The country's critical minerals strategy prioritizes downstream processing incentives for zirconium chemicals. Perth and the Eucla Basin concentrate mining and initial concentration infrastructure.
Zirconium Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the zirconium value chain. The market structure reflects upstream consolidation in mineral sands against downstream fragmentation in nuclear-grade refining. Three archetypes dominate: integrated mineral sands miners with co-production economics, dedicated zirconium chemical refiners, and nuclear-qualified alloy fabricators. Capacity expansion and long-term offtake contracting represent the primary competitive moves as utilities seek supply security.
Among integrated miners, Iluka Resources Limited and Tronox Holdings plc exemplify the Ti-Zr co-production model that anchors feedstock economics. Rio Tinto Group occupies a position spanning mining through refined chemicals. These three companies represent the upstream concentration that supplies downstream nuclear and industrial fabricators.
| Leading Market Players |
|---|
| Iluka Resources Limited |
| Tronox Holdings plc |
| Rio Tinto Group |
| Kenmare Resources plc |
| Australian Strategic Materials Ltd |
| Base Resources Limited |
| Eramet SA |
| Saint-Gobain ZirPro |
| Iwatani Corporation |
| Others |
Cost & Logistics Intelligence
Captive sponge reduction at Australian and South African mineral sands operations anchors both supply security and pricing power for integrated producers serving nuclear fuel fabricators. This backward integration into chlorination and reduction stages insulates margin structures from feedstock volatility while creating tiered access barriers for non-integrated competitors.
Pricing Analysis
Margin tightening in nuclear-grade sponge reflects hafnium separation energy costs and multi-decade qualification overhead. Pricing stratifies across reactor-certified, aerospace-grade, and industrial-ceramic tiers with certification level and volume scale as primary differentiation drivers. Cost compression in ceramic-grade zirconia accelerates because Chinese construction ceramics buyers negotiate spot purchasing terms. Industrial refractory consumers exhibit highest price sensitivity while nuclear utilities absorb certification premiums through long-term offtake structures.
Supply Chain Analysis
Certification gating through NRC 10 CFR Part 50 and China's GB standards fragments supplier access across Western and Chinese nuclear fleets. Raw material draws from Australian heavy mineral sands, South African co-product streams, and Indian beach deposits with zircon sand, chlorine gas, and metallurgical coke as critical inputs. Single-source vulnerability concentrates in hafnium separation capacity with neutron cross-section metrology creating quality assurance bottlenecks. Distribution runs through direct mill-to-fabricator contracts for nuclear grades and distributor networks for industrial chemicals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained with nuclear-grade sponge capacity lagging reactor construction timelines across China and India. Qualification protocol duration props pricing power for incumbent certified suppliers.
For Market Incumbents: Anchor long-term contracting positions by bundling technical service agreements with alloy procurement for state-backed utilities facing localization mandates. Defend against emerging additive manufacturing feedstock competitors by locking powder specification development with Westinghouse and Framatome qualification programs. Prioritize backward integration into mineral sands where Ti-Zr co-production economics sustain feedstock cost advantage. For New Entrants and Emerging Players: Direct-to-fuel-fabricator digital procurement platforms offer white-space entry around spot purchasing friction in industrial zirconia grades. Target India's Nuclear Fuel Complex supplier qualification pipeline as the most penetrable nuclear tier given indigenous PHWR expansion and localization requirements. Pursue biomedical oxygen sensor partnerships with Bosch and Continental automotive programs as faster commercialization pathway than nuclear certification. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated mineral sands majors seeking downstream nuclear qualification assets. Long-term viability hinges on positioning within Chinese or Western regulatory certification clusters as divergence deepens. Watch small modular reactor NRC Part 53 qualification timelines as inflection signal for demand acceleration outside traditional light water reactor programs.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | EDF and CNNC procurement centralization rewards multi-year zirconium alloy contracting with technical service attachments. |
| Backward Integration | Iluka Resources' mineral sands-to-sponge pipeline captures margin from zircon sand through nuclear-grade reduction. |
| Capacity Expansion | Shanghai and Sichuan sponge facilities respond to Hualong One construction timelines with localized supply mandates. |
| Joint Venture | Framatome-Western partnerships on laser powder bed fusion accelerate fuel spacer grid additive manufacturing qualification. |
| Green Manufacturing Transition | EU Green Deal critical raw materials list triggers strategic stockpiling and processing incentives for European zirconium chemicals. |
Research Approach
Trade databases, SEC 10-K filings, and nuclear regulatory submission records formed the secondary backbone for this analysis. Primary interviews with fuel fabrication procurement directors, mineral sands operations managers, and nuclear quality assurance engineers validated supply chain structures and qualification timelines. Bottom-up and top-down triangulation cross-checked volume estimates against customs data and reactor construction pipeline disclosures.
Bottom-up modeling aggregated individual reactor unit demand for zirconium-niobium alloys across China and India construction programs. Top-down analysis calibrated total addressable market against mineral sands production capacity and zircon-to-sponge conversion ratios. Segmentation dimensions included product grade tier, end-use application, and regional regulatory cluster. CAGRs derived from regression against reactor deployment schedules and industrial ceramics demand elasticity.
Inputs from EIA nuclear generation forecasts and IEA critical minerals assessments were available through the study window; gaps in Chinese GB standard implementation timelines introduce uncertainty bands around localization assumptions. Forecasts reflect documented assumptions on qualification protocol duration and hafnium separation capacity expansion. A model refresh is warranted upon material change in small modular reactor certification pathways or REACH hafnium purity mandate revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Silver Nitrate Market
Metals
Global Titanium Metal Market
Metals
Motor Lamination Material Market
Metals
Steel Casting Market
Metals
Stainless Steel Panels Market
Metals
Transition Metals Market
Metals
Global Copper Sputtering Target Market
Metals
Japan Aluminium Powder Market
Metals
Pump Casing Materials Market
Metals
Silver Enamel Market
Metals
Base Metals Market
Metals
HSLA Steel Plate Market
Metals
Aluminum Tubes Market
Metals
Aluminum Welding Market
Metals
Magnesium Metal Market
Metals
Middle-East and Africa Metal Finishing Market