
 Hexafluorosilicic Acid Market | 2026-2036
Hexafluorosilicic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Hexafluorosilicic Acid Market Intelligence
The hexafluorosilicic acid market is recalibrating around a widening split between pharmaceutical-grade purity standards and commodity industrial volumes. Technical-grade material now trades on fundamentally different margin structures than food-grade or pharmaceutical-grade variants, with specification thresholds diverging by orders of magnitude. The Mosaic Company leverages its captive phosphate rock supply to anchor downstream fluorosilicic acid output. Honeywell International competes through integrated fluorine chemistry platforms that extend into specialty derivatives. Solvay differentiates via controlled manufacturing protocols for higher-purity grades serving regulated end uses.
Hexafluorosilicic acid, also known as fluorosilicic acid or silicofluoric acid, is an inorganic compound with the formula H₂SiF₆ typically supplied as a 20-35% aqueous solution generated as a byproduct of phosphate fertilizer manufacturing through the reaction of silica with hydrogen fluoride. It functions primarily as a fluoridating agent in municipal water treatment, a metal surface conditioner, and a precursor in aluminum fluoride and cryolite synthesis. Industrial-grade material dominates volume throughput due to its role in fertilizer production and bulk water treatment, while pharmaceutical-grade commands premium positioning driven by compounding pharmacy and dental applications. Water treatment applications sustain the largest demand footprint, though metal surface treatment for automotive and aerospace components is gaining specification intensity.
The EPA regulates fluoridation additives under NSF/ANSI Standard 60, while the FDA oversees food-grade and pharmaceutical-grade classifications through indirect food additive and drug substance frameworks. REACH in Europe imposes registration and hazard communication requirements that constrain import pathways and formulation transparency. OSHA's permissible exposure limits shape workplace handling protocols and drum packaging specifications. Stakeholders must monitor evolving state-level fluoridation mandates and purity certifications as regulatory fragmentation between jurisdictions intensifies qualification burdens.
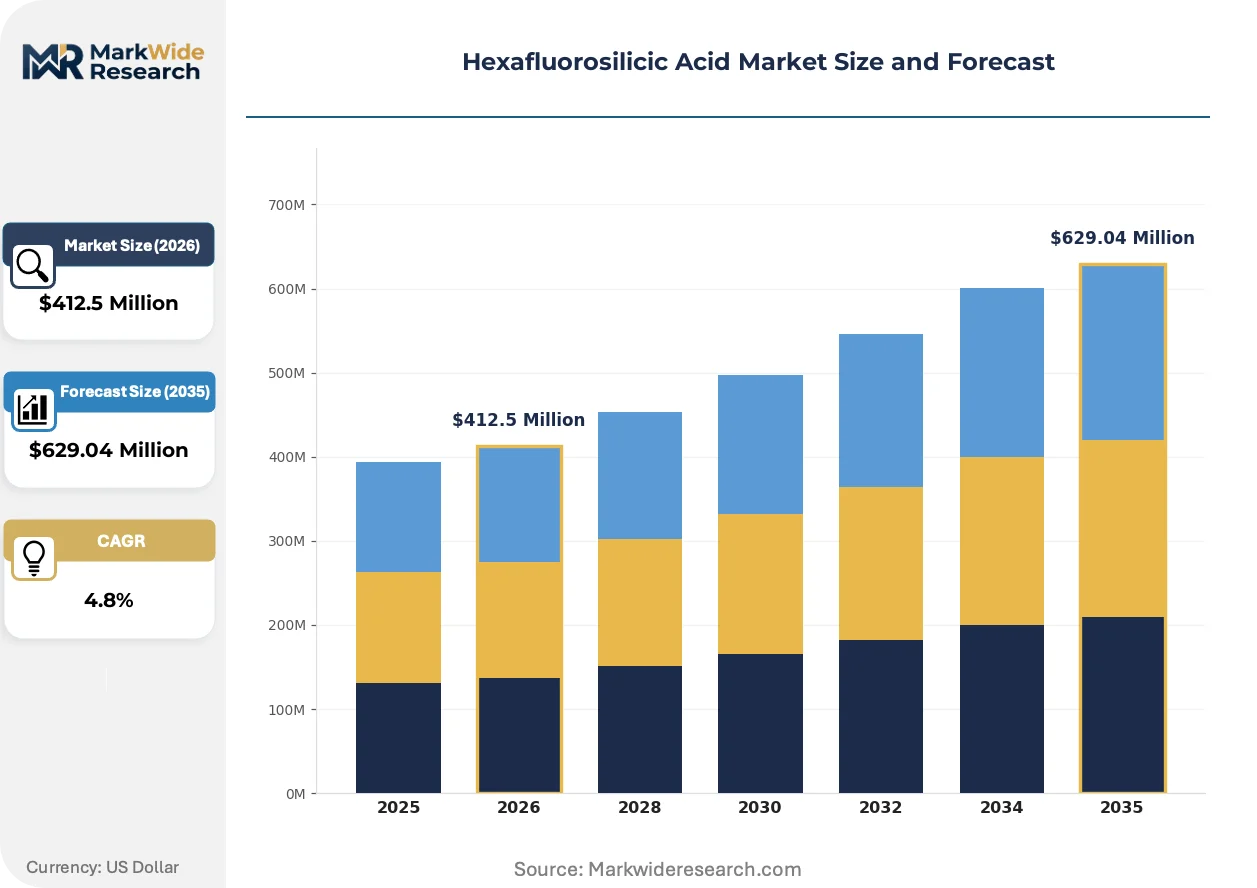
Market Dynamics
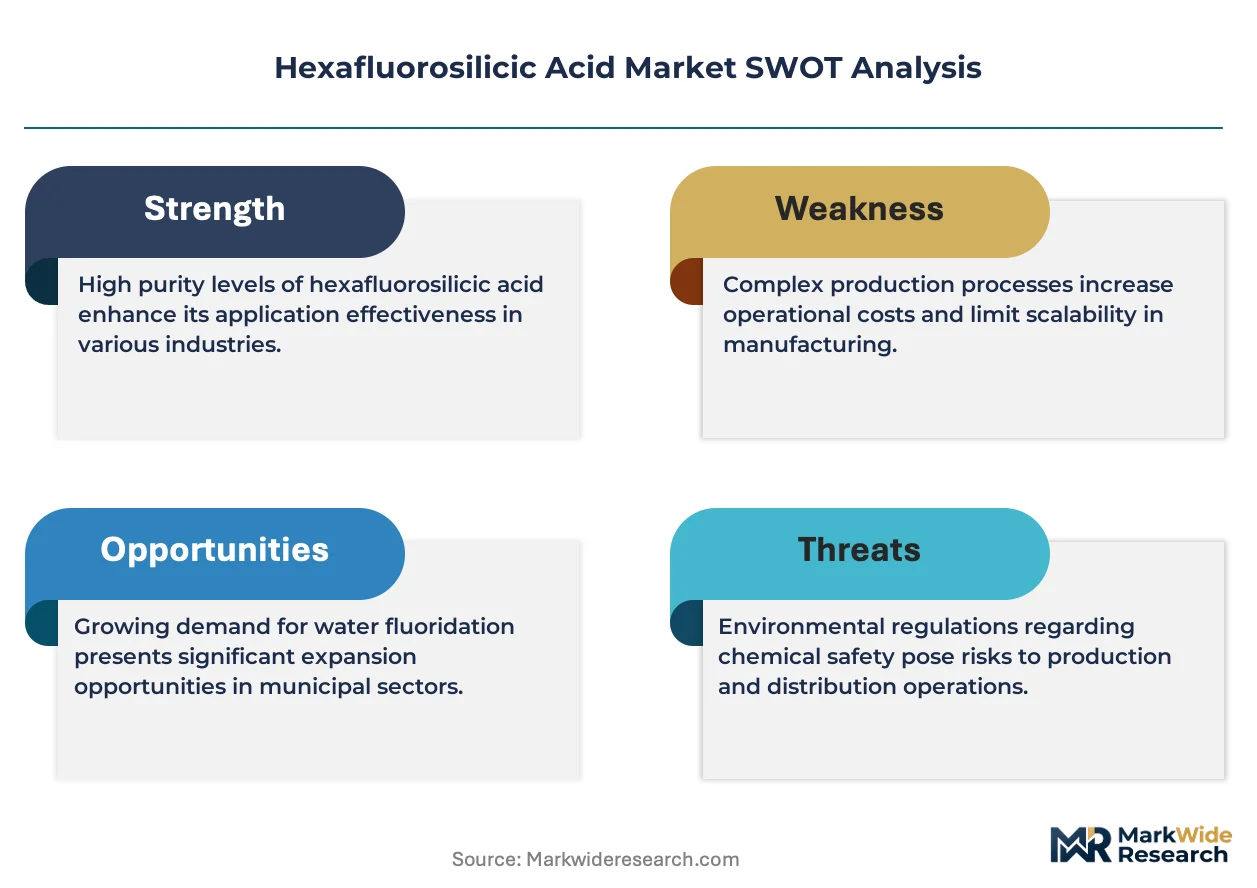
The hexafluorosilicic acid market is being pulled apart by diverging purity requirements across end-use segments, with municipal water treatment demanding technical-grade volumes while pharmaceutical compounding and dental applications impose specification thresholds that strain conventional production economics.
Growth Catalysts
- NSF/ANSI Standard 60:EPA enforcement of this drinking water additive standard is tightening purity benchmarks across US municipal procurement, forcing upgrades that favor qualified suppliers with verified analytical capabilities.
- Phosphate fertilizer co-production:Captive supply integration from phosphate rock processing is expanding fluorosilicic acid availability as a byproduct stream, particularly in regions with concentrated fertilizer manufacturing.
- Aluminum fluoride precursor demand:Primary aluminum smelters are absorbing larger fluorosilicic acid volumes for cryolite synthesis as energy-intensive aluminum production shifts toward regions with integrated chemical supply chains.
Market Restraints
- Phosphate rock supply concentration:Four countries control over 80% of mineable phosphate reserves, creating geopolitical chokepoints that transmit directly to fluorosilicic acid availability and pricing volatility.
- Hydrogen fluoride cost pass-through:Raw material exposure to HF pricing—tied to fluorspar mining and Chinese export quotas—compresses margins for non-integrated producers without captive acid streams.
- REACH registration burdens:European importers face escalating compliance costs for hazard communication and substance registration, constraining formulation transparency and favoring domestic manufacturing.
Strategic Opportunities
- Pharmaceutical-grade certification:USP-grade material commands 3-5x technical-grade pricing; facilities achieving FDA drug substance validation can access compounding pharmacy and dental therapeutic markets.
- Metal surface treatment expansion:Automotive lightweighting and aerospace component finishing are absorbing higher-purity fluorosilicic acid for titanium and aluminum conditioning prior to coating.
- State-level fluoridation mandates:Subnational policy divergence in the United States is creating procurement windows in jurisdictions expanding public water fluoridation coverage.
Industry Challenges
- Analytical chemistry talent scarcity:Facilities require ICP-MS and ion chromatography specialists to maintain pharmaceutical-grade certification, with qualified personnel concentrated in established chemical manufacturing regions.
- Legacy infrastructure retrofit costs:Converting technical-grade production lines to food-grade or pharmaceutical-grade standards demands capital-intensive containment, cleaning validation, and quality system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hexafluorosilicic Acid Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Grade: Technical Grade, Food Grade, Pharmaceutical Grade, Industrial Grade Application Area: Water Treatment, Metal Surface Treatment, Fertilizer Production, Chemical Synthesis, Pulp & Paper Processing End User Industry: Manufacturing Plants, Agriculture Sector, Chemical Manufacturers, Water Utilities, Paper Mills Packaging Type: Drums, IBC Containers, Bulk Tankers, Cylinders |
| Companies Covered | The Mosaic Company, American Elements, Honeywell International, Gelest, IXOM, Solvay, Hydrite Chemical, Napco Chemical Company, KMG Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hexafluorosilicic Acid Market Strategic Shifts & Innovations
Continuous processing technology and automated quality assurance systems are compressing batch cycle times while tightening specification control, enabling producers to serve multiple grade tiers from shared assets without cross-contamination risk.
Closed-loop membrane filtration is automating impurity removal in hexafluorosilicic acid concentration steps, replacing manual sampling and offline adjustment with real-time conductivity and density feedback. Municipal water treatment utilities in the southeastern United States are adopting these systems fastest, driven by procurement specifications that now reward demonstrated process control. The technology is automating labor-intensive quality assurance steps that previously required dedicated analytical staff, reducing headcount intensity in high-volume production facilities.
REACH authorization requirements for substances of very high concern are tightening disclosure obligations for fluorosilicic acid importers into the European Union, forcing reformulation transparency and supply chain documentation that many commodity traders cannot provide. Industrial-grade consumers are responding by consolidating purchases with registrants holding full dossiers, while food-grade buyers are accelerating qualification of European-based manufacturing alternatives. The regulation is fragmenting import pathways and favoring producers with in-house regulatory affairs capabilities.
Specification-driven procurement is consolidating municipal water treatment purchasing around qualified suppliers with verified NSF/ANSI Standard 60 certification, displacing spot-market sourcing that dominated historical procurement patterns. Large water utilities in Texas, California, and Florida are unbundling chemical supply from equipment service contracts, creating direct procurement relationships with chemical manufacturers rather than distributors. This behavioral shift is most visible in states with centralized utility structures and formal fluoridation mandates, where procurement departments now prioritize analytical traceability over price minimization.
Hexafluorosilicic Acid Market Segmentation
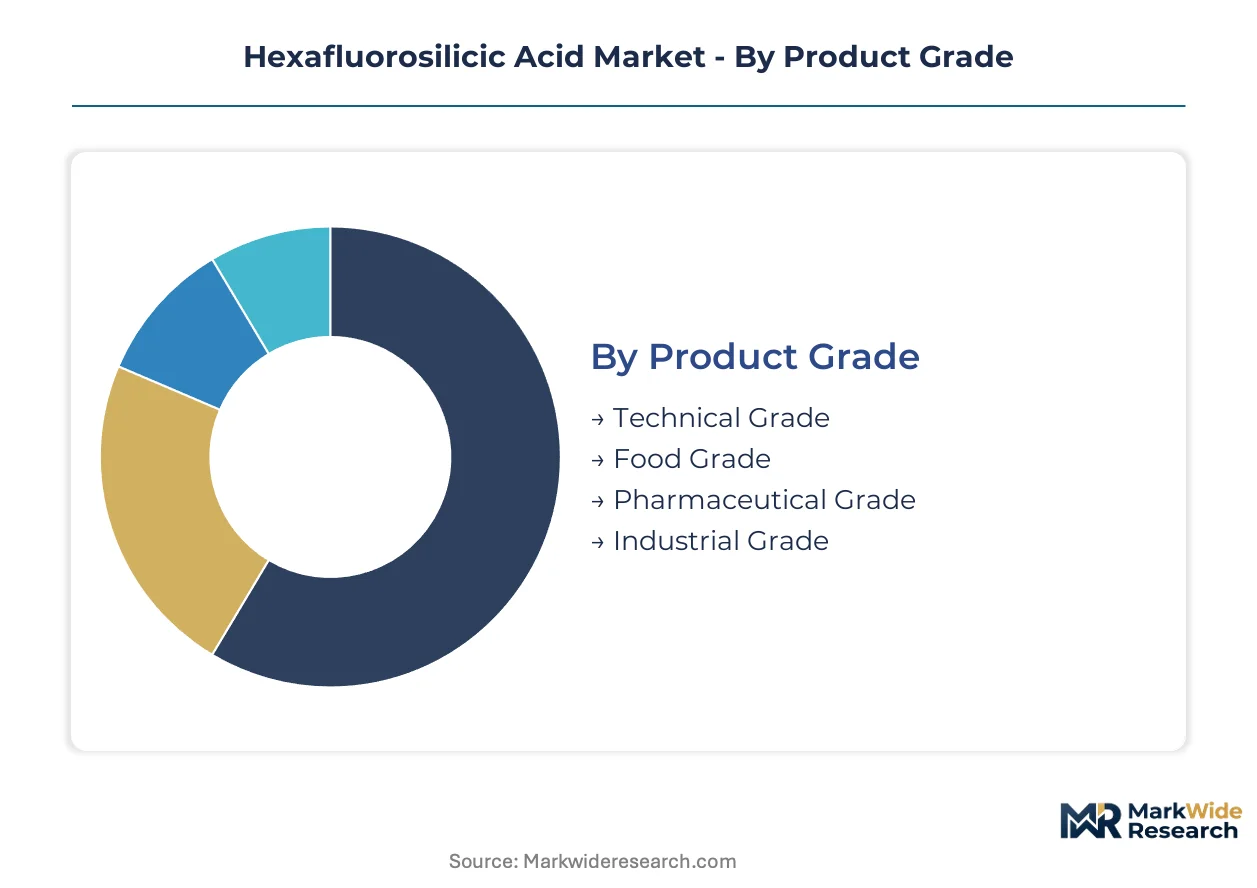
Hexafluorosilicic acid procurement splits sharply across purity tiers and containment requirements, with municipal buyers prioritizing NSF/ANSI certification while industrial consumers optimize for volume scale and logistics efficiency.
Product Grade:
Purity thresholds determine pricing multiples and regulatory qualification burdens across buyer segments.
- Technical Grade:Supplied as 20-35% aqueous solution with baseline fluoride content for municipal fluoridation and bulk industrial applications. Demand concentrates in US water utilities upgrading to NSF/ANSI Standard 60 compliance as EPA enforcement tightens analytical documentation requirements.
- Pharmaceutical Grade:Manufactured under USP monograph specifications with validated impurity profiles below 10 ppm for heavy metals. Compounding pharmacies and dental therapeutic manufacturers in the United States absorb this material despite 3-5x technical-grade pricing premiums.
- Food Grade:Meets FDA indirect food additive specifications for equipment sanitization and processing aids. Beverage bottling facilities and food processing plants require this certification for regulatory audit readiness.
- Industrial Grade:Unpurified byproduct stream from phosphate fertilizer manufacturing with variable silica content. Aluminum smelters and cryolite synthesis operations purchase this grade for captive chemical integration.
Volume sits with Technical Grade; growth tilts toward Pharmaceutical Grade.
Application Area:
End-use specifications fragment demand across contamination-sensitive and volume-driven consumption patterns.
- Water Treatment:Municipal fluoridation programs consume the largest absolute volumes, with procurement specifications now mandating real-time process control documentation. Texas and Florida utilities are consolidating purchases around qualified suppliers with verified analytical capabilities.
- Metal Surface Treatment:Aerospace and automotive component finishing requires higher-purity material for titanium and aluminum conditioning prior to coating. Lightweighting mandates in transportation manufacturing are expanding specification intensity for this segment.
- Fertilizer Production:Captive consumption within integrated phosphate rock processing operations. Mosaic and similar producers utilize this stream internally rather than merchant sales.
- Chemical Synthesis:Precursor demand for aluminum fluoride and cryolite manufacturing in primary aluminum smelting. Energy-intensive smelter relocations toward integrated chemical supply regions are reshaping geographic demand.
- Pulp & Paper Processing:Equipment cleaning and wood pulp bleaching applications with moderate purity requirements. Mills prioritize drum packaging for handling efficiency.
Water Treatment commands current volume leadership; Metal Surface Treatment is climbing the fastest as specification thresholds rise.
End User Industry:
Customer scale and regulatory exposure determine procurement sophistication and contract structures.
- Water Utilities:Large municipal systems in California, Texas, and Florida unbundle chemical supply from equipment service contracts. Centralized procurement departments now prioritize analytical traceability over distributor relationships.
- Chemical Manufacturers:Integrated fluorine chemistry operations purchase technical-grade material for downstream derivative synthesis. Honeywell and Solvay operate captive consumption models with minimal merchant market exposure.
- Manufacturing Plants:Automotive and aerospace finishing operations with batch-process consumption patterns. These buyers require IBC container delivery for just-in-time inventory management.
- Agriculture Sector:Phosphate fertilizer producers generate hexafluorosilicic acid as byproduct rather than purchasing merchant supply. Geographic concentration of phosphate rock mining shapes regional availability.
- Paper Mills:Moderate-volume consumers with standardized drum packaging requirements. Procurement emphasizes handling safety protocols over purity certification.
Water Utilities anchor contract value; Chemical Manufacturers are expanding most quickly through backward integration.
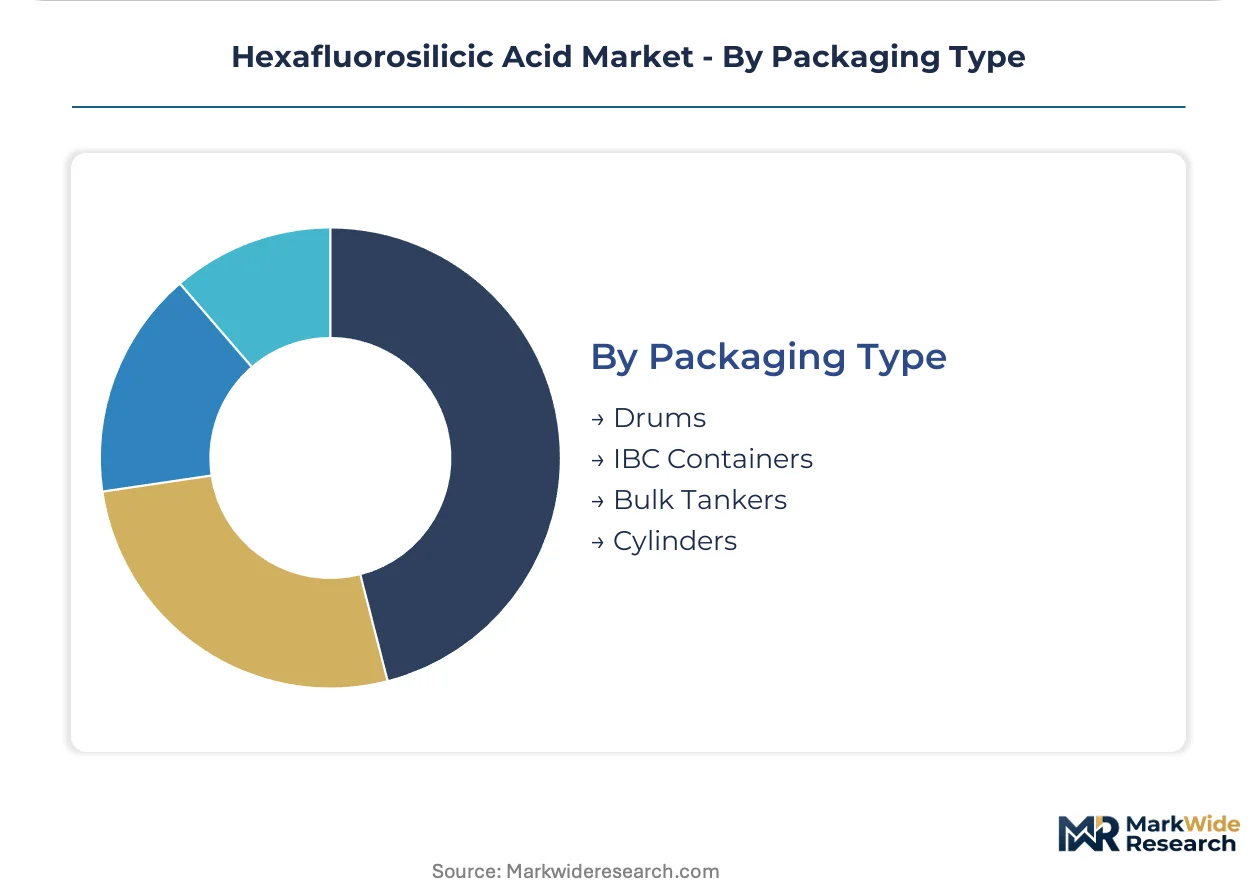
Packaging Type:
Containment selection balances handling safety, transportation economics, and contamination risk.
- Bulk Tankers:Dedicated fleet delivery for high-volume municipal water treatment facilities with on-site storage infrastructure. Southeastern US utilities specify tanker delivery for fluoridation programs serving populations above 100,000.
- IBC Containers:Intermediate bulk packaging for manufacturing plants with moderate consumption rates and space-constrained storage. Automotive surface treatment facilities prefer this format for forklift maneuverability.
- Drums:Standard 55-gallon steel packaging for smaller water utilities and paper mills with limited storage capacity. OSHA handling protocols shape drum specification and labeling requirements.
- Cylinders:Pressurized containment for specialized pharmaceutical-grade delivery with inert gas overlay. Compounding pharmacies and dental manufacturers require this format for oxidation-sensitive formulations.
Bulk Tankers dominate tonnage movement; Cylinders are gaining share fastest as pharmaceutical-grade demand steepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida's municipal water utilities anchor North American fluoridation chemical demand, with Tampa Bay and Miami-Dade systems driving specification intensity for NSF/ANSI Standard 60 certified supply.
United States
Texas and California water utilities are consolidating procurement around qualified suppliers with verified analytical capabilities. EPA enforcement of Safe Drinking Water Act amendments tightens purity documentation requirements. Large municipal systems in Houston and Los Angeles unbundle chemical supply from equipment service contracts.
China
Phosphate fertilizer manufacturing in Guizhou and Yunnan provinces generates substantial fluorosilicic acid byproduct streams. MIIT standards for industrial chemical purity shape domestic quality thresholds. Aluminum smelters in Shandong province absorb technical-grade volumes for cryolite synthesis.
Germany
REACH registration obligations constrain import pathways for fluorosilicic acid distributors serving chemical synthesis operations. ECHA authorization requirements for substances of very high concern tighten disclosure obligations. Industrial consumers in the Ruhr region consolidate purchases with registrants holding full dossiers.
Brazil
Phosphate mining concentration in Minas Gerais state underpins captive fluorosilicic acid availability for fertilizer producers. ANVISA oversight of food-grade chemical classifications shapes import qualification burdens. São Paulo-based water treatment operators navigate state-level fluoridation policy divergence.
Australia
Water utilities in New South Wales and Victoria specify bulk tanker delivery for fluoridation programs serving populations above 100,000. TGA frameworks for therapeutic goods manufacturing influence pharmaceutical-grade import standards. Melbourne's municipal procurement departments prioritize analytical traceability over price minimization.
Hexafluorosilicic Acid Market Key Industry Players
Premium-margin players sit above commodity-margin players across purity certification tiers, with pharmaceutical-grade specialists commanding 3-5x technical-grade pricing multiples. The market structure consolidates around integrated phosphate fertilizer producers, diversified fluorine chemistry platforms, and specialty chemical registrants with regulatory affairs capabilities. Three archetypes dominate: captive byproduct generators, backward-integrated fluorine specialists, and certification-focused pharmaceutical-grade suppliers. Competitive moves center on capacity expansion in high-purity production lines and strategic partnerships with municipal procurement departments.
Within the integrated phosphate producer tier, The Mosaic Company exemplifies captive supply architecture, while Honeywell International occupies a position among diversified fluorine chemistry platforms extending into specialty derivatives. Solvay anchors the pharmaceutical-grade certification vector, representing controlled manufacturing protocols for regulated end uses.
| Leading Market Players |
|---|
| The Mosaic Company |
| American Elements |
| Honeywell International |
| Gelest |
| IXOM |
| Solvay |
| Hydrite Chemical |
| Napco Chemical Company |
| KMG Chemicals |
| Others |
Cost & Logistics Intelligence
ICP-MS and ion chromatography specialists concentrated in the US Gulf Coast and German chemical corridors command wage premiums that compress margins for pharmaceutical-grade producers while widening spreads against technical-grade commodity pricing. Labor-cost differentials between certified analytical talent and standard production staff directly map onto the 3-5x pricing multiples separating USP-grade from municipal-grade material.
Pricing Analysis
NSF/ANSI Standard 60 certification outcomes anchor value-based pricing for municipal water treatment contracts, with utilities paying verified analytical documentation premiums over spot-market alternatives. Price differentiation separates pharmaceutical-grade USP monograph material from technical-grade municipal supply, with brand certification and geographic delivery cost layering additional premiums. Cost compression in technical-grade volumes is intensifying because phosphate rock supply concentration transmits volatility through captive byproduct streams. Municipal procurement departments show highest price sensitivity, while compounding pharmacies absorb premiums for validated impurity profiles.
Supply Chain Analysis
Empty drum return and container refurbishment flows from municipal water utilities back to Gulf Coast production facilities reduce packaging cost intensity for high-volume technical-grade supply. Geographic supply concentration centers on the United States, China, and Morocco, with phosphate fertilizer co-production in Florida and North Africa feeding downstream fluorosilicic acid availability. Raw material dependencies rest on phosphate rock mining, hydrogen fluoride availability, and fluorspar processing economics. Single-source vulnerability runs through concentrated phosphate reserve ownership across four dominant countries. Distribution feeds from integrated fertilizer producers through qualified chemical distributors to municipal procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification-capable producers as EPA enforcement of NSF/ANSI Standard 60 documentation requirements forces commodity traders without analytical capabilities toward exit.
For Market Incumbents: Deepen captive phosphate rock integration to secure byproduct acid streams against hydrogen fluoride cost volatility, while expanding ICP-MS analytical capacity to defend pharmaceutical-grade positioning against emerging USP-certified entrants. Capacity addition in Texas and Florida municipal corridors anchors contract renewal rates. For New Entrants and Emerging Players: NSF/ANSI Standard 60 in the United States opens a window for regional blending and certification facilities serving southeastern utilities consolidating procurement around qualified suppliers. White-space targets include pharmaceutical-grade compounding pharmacy supply and automotive metal surface treatment specifications. Go-to-market positioning should emphasize real-time process control documentation exceeding municipal procurement thresholds. For Investors and Strategic Acquirers: Re-rating potential sits with USP-certified pharmaceutical-grade specialists given FDA drug substance validation requirements tightening qualification barriers. Long-term viability favors producers with backward-integrated phosphate supply and in-house regulatory affairs capabilities spanning REACH and EPA frameworks. Signal to monitor: state-level fluoridation mandate expansions in Texas, California, and Florida as procurement volume inflection triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Investment | FDA USP monograph validation unlocks 3-5x pricing premiums in compounding pharmacy supply. |
| Backward Integration into Phosphate Rock | Mosaic-style captive supply anchors margin stability against hydrogen fluoride volatility. |
| Real-Time Process Control Deployment | Closed-loop membrane filtration meets Texas and Florida municipal procurement specifications. |
| REACH Registration Dossier Completion | Full ECHA substance registration preserves European import pathways against trader displacement. |
| Long-Term Municipal Supply Agreements | Direct procurement relationships with Houston and Los Angeles utilities displace distributor intermediaries. |
Research Approach
Trade data from USITC and Eurostat, SEC 10-K filings from integrated phosphate producers, and ECHA registration dossiers formed the secondary backbone for supply-side calibration. Primary interviews with municipal water utility procurement directors, ICP-MS analytical laboratory managers, phosphate fertilizer plant operations heads, and fluorosilicic acid distribution channel partners provided demand-side validation. Bottom-up triangulation across grade-tier production volumes and top-down cross-checks against aluminum fluoride precursor consumption anchored market sizing.
Bottom-up modeling segmented volume and value across pharmaceutical-grade, technical-grade, food-grade, and industrial-grade tiers, with water treatment, metal surface treatment, and chemical synthesis applications tracked separately. CAGRs were derived from regression analysis against phosphate fertilizer production forecasts and municipal fluoridation program expansion rates. Packaging format splits between bulk tankers, IBC containers, and cylinders incorporated logistics cost modeling for municipal versus pharmaceutical delivery modes.
The model assumes a particular technology adoption path for closed-loop membrane filtration concentration; alternative pathways for batch processing with manual quality assurance would alter the outlook for labor cost structures and certification timelines. Forecasts reflect assumptions about EPA enforcement continuity and phosphate rock supply stability. Practitioners should monitor state-level fluoridation mandate legislation and REACH authorization list updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
3-Fluoro-5-Nitrotoluene Market
Chemicals
Global Glycol Ether Market
Chemicals
Superplasticizer Market
Chemicals
Potassium Iodide Market
Chemicals
Aluminium Chloride Market
Chemicals
Triethanolamine Market
Chemicals
6 Hexanediol Market
Chemicals
Power Plant Chemicals Market
Chemicals
Europe Hydrazine Market
Chemicals
Photographic Chemicals Market
Chemicals
Hydrogenated Dimer Acid Market
Chemicals
Fatty Alcohol Market
Chemicals
Hydrazine Hydrate Market
Chemicals
Hydroxyzine Imine Market
Chemicals
Asia-Pacific Fluorosilicic Acid Market