
 Europe Calcium Peroxide Market | 2026-2036
Europe Calcium Peroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Calcium Peroxide Market Foresight
Modular packaging configurations for calcium peroxide is expanding buyer flexibility across European water treatment and agriculture sectors. Solvay SA leverages its integrated peroxide platform to sustain supply security for industrial-grade formulations across Benelux and France. Evonik Industries AG anchors its position through specialized pharmaceutical-grade production serving regulated medical markets. Carus Group Inc. competes on geographic reach, with distribution networks penetrating Central and Eastern European industrial zones.
Calcium peroxide is an inorganic compound with the formula CaO₂, typically manufactured through the reaction of calcium salts with hydrogen peroxide under controlled alkaline conditions, yielding a white or yellowish solid that releases oxygen upon contact with water. Its primary industrial purpose centers on controlled oxygen release for groundwater remediation, soil decontamination, and as a slow-acting bleaching agent in food processing applications. Industrial grade formulations dominate volume throughput due to established demand from municipal and industrial water treatment operators, while food grade segments command premium positioning tied to EU purity standards for direct-contact applications. Pharmaceutical grade represents a concentrated margin pool despite smaller volumes, reflecting stringent certification barriers and specialized synthesis requirements.
REACH registration mandates administered by ECHA govern substance authorization and restrict hazardous impurities in calcium peroxide destined for consumer-facing applications. The EU Green Deal's chemical sustainability targets are accelerating substitution away from more aggressive oxidants toward controlled-release peroxygen compounds in soil and water remediation. Food processors must navigate EFSA additive regulations alongside national implementations of the EU F-Gas Regulation where calcium peroxide serves as an alternative treatment pathway. Stakeholders should monitor evolving biodegradability criteria under the EU Chemicals Strategy for Sustainability and assess backward integration into hydrogen peroxide feedstock supply as a structural hedge against raw material volatility.
Market Dynamics
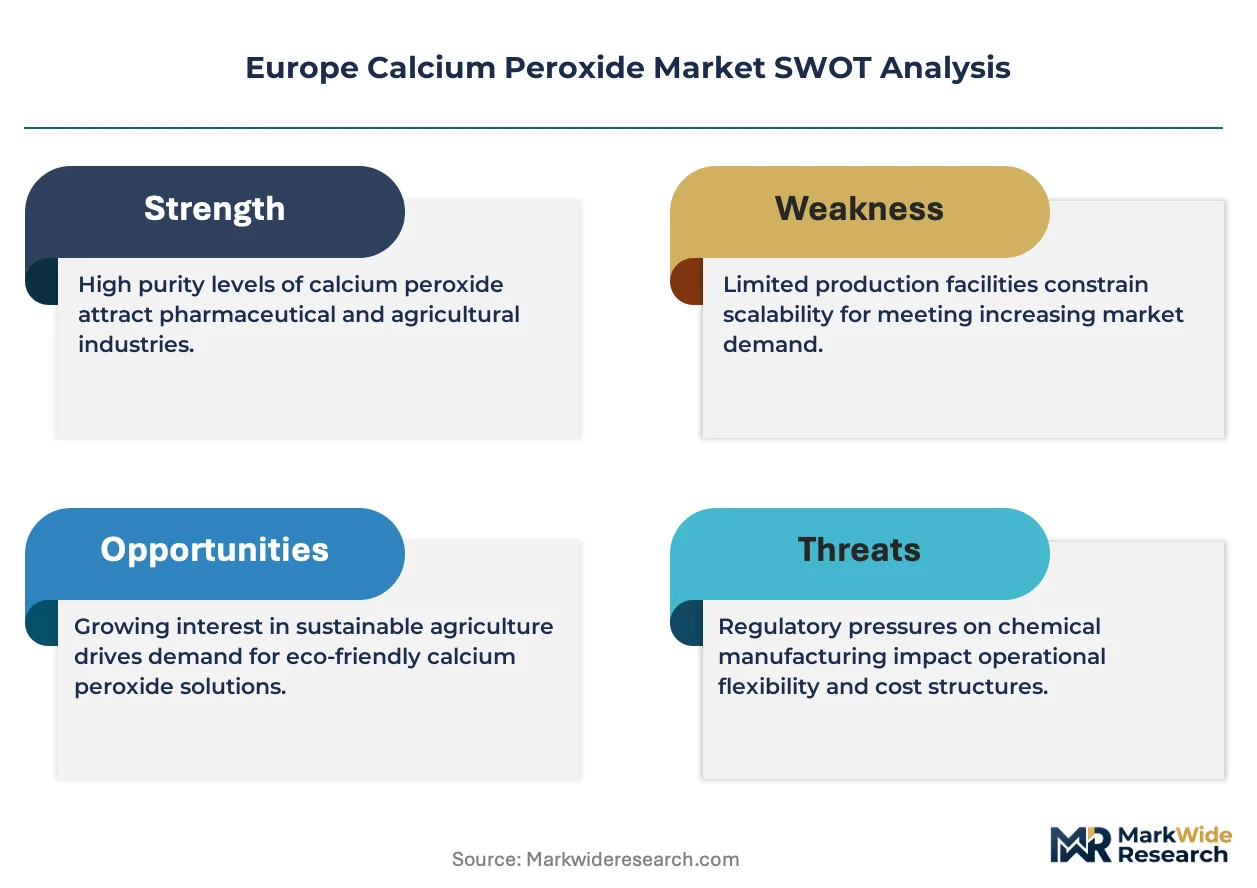
REACH compliance mandates from ECHA are compressing supplier qualification timelines and elevating purity specifications across European calcium peroxide procurement channels, forcing reformulation investments and selective distributor partnerships.
Growth Catalysts
- Aerobic bioremediation protocols:Water treatment utilities across Germany and France are expanding controlled oxygen release systems for contaminated groundwater sites, driving volume demand for industrial-grade formulations.
- EU Green Deal substitution mandates:The chemical sustainability framework is accelerating displacement of aggressive chlorinated oxidants toward controlled-release peroxygen compounds in soil remediation applications.
- Rhine-Ruhr manufacturing corridor concentration:Industrial cluster density around Düsseldorf and Essen creates localized demand pull for high-volume calcium peroxide supply contracts.
Market Restraints
- Hydrogen peroxide feedstock volatility:Raw material price swings for the primary calcium peroxide input compress margin stability and complicate long-term contracting.
- Eastern European supply concentration risk:Production capacity clustering in select Polish and Czech facilities creates vulnerability to regional logistics disruptions.
- Slow-release kinetics limitation:Calcium peroxide's controlled oxygen release rate restricts applicability in time-sensitive emergency remediation scenarios where faster-acting alternatives prevail.
Strategic Opportunities
- Portuguese and Spanish agricultural penetration:Underdeveloped adoption in Iberian soil conditioning and crop oxygenation applications offers expansion runway for technical grade formulations.
- EFSA food additive regulatory tailwind:Expanding approved applications for calcium peroxide as a flour treatment agent and food processing bleaching compound opens premium food-grade volume channels.
- Modular packaging-digital procurement convergence:Flexible container sizing combined with B2B platform purchasing is reducing minimum order friction for mid-sized water treatment operators.
Industry Challenges
- REACH registration timeline compression:Extended ECHA substance evaluation periods delay market entry for modified formulations and derivative compounds.
- Pharmaceutical-grade synthesis capex intensity:Specialized production equipment for medical oxygen generation applications demands significant capital deployment with elongated payback horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Calcium Peroxide Market |
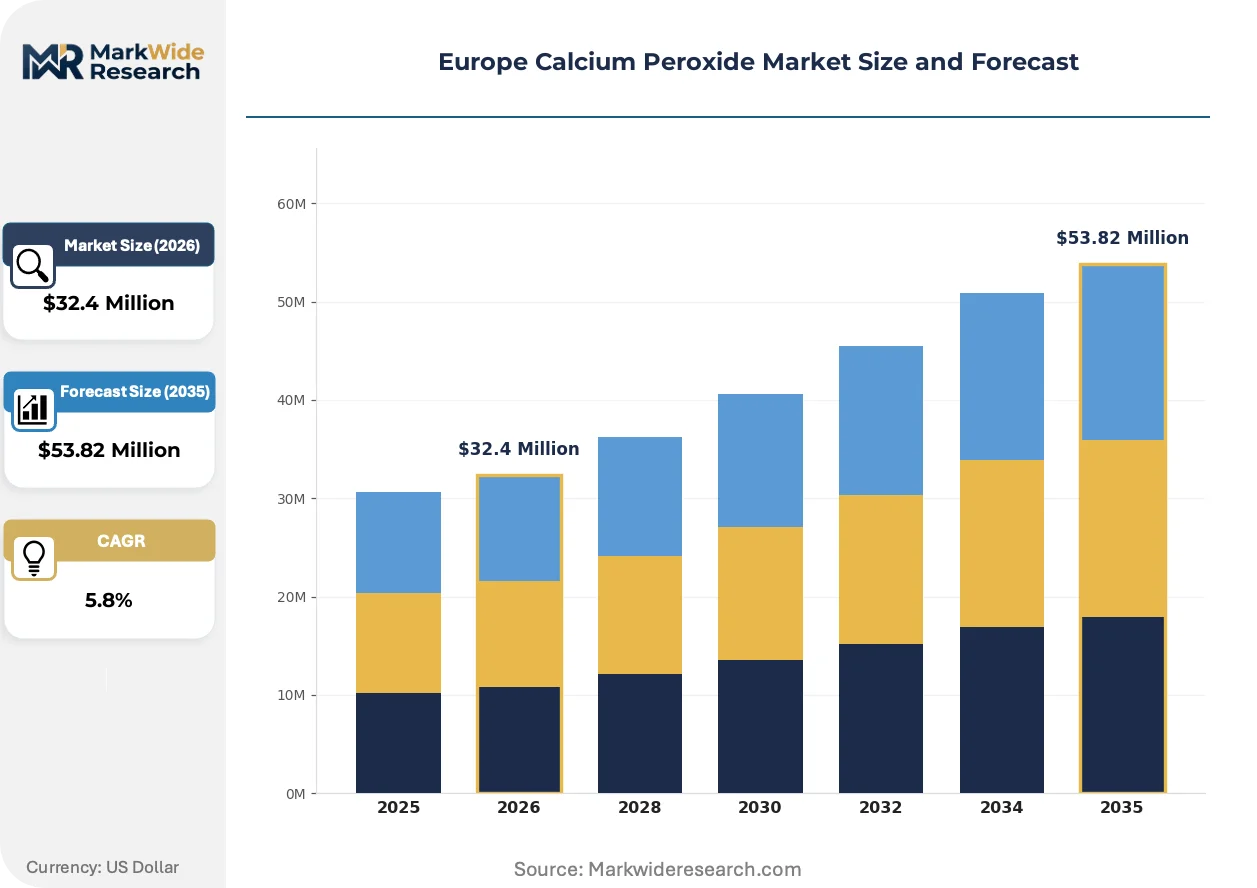
| Market Size in 2026 | $32.4 Million |
| Market Size in 2035 | $53.82 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Agricultural Grade Application: Water Treatment, Soil Treatment, Organic Agriculture, Food Preservation End User: Manufacturers, Distributors, Farmers, Food Processors Packaging Type: Bags, Drums, Bulk Containers, Custom Packaging |
| Companies Covered | PeroxyChem LLC, Carus Group Inc., Solvay SA, Calmags GmBH, Merck KGaA, Evonik Industries AG, American Elements, Nikunj Chemicals, Arkema Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Calcium Peroxide Market Shifts & Advancements
Electrochemical synthesis pathways and modular reactor designs are reshaping production economics, while regulatory tightening on chemical oxidants accelerates formulation innovation across European manufacturing.
Encapsulated calcium peroxide granules with polymer coating technology are electrifying controlled-release performance in groundwater remediation applications. German environmental engineering firms are adopting these formulations for deep aquifer oxygenation projects. The technology is electrifying competitive positioning by enabling longer-duration treatment cycles that reduce site visit frequency and labor costs.
REACH authorization requirements for Substances of Very High Concern are tightening impurity thresholds for calcium peroxide destined for consumer-facing applications. Industrial chemical distributors must now maintain enhanced documentation chains and third-party testing protocols. Food-grade and pharmaceutical-grade segments are responding with dedicated batch tracking systems and segregated storage infrastructure to maintain compliance eligibility.
Water treatment procurement teams are consolidating supplier relationships and demanding technical service bundling alongside commodity chemical supply. Municipal utilities in northern Italy are replacing fragmented multi-vendor purchasing with single-source framework agreements covering formulation supply, dosing equipment, and performance monitoring. This concentration pattern is most visible in the Po Valley industrial zone where integrated service contracts now dominate tender specifications.
Europe Calcium Peroxide Market Segmentation
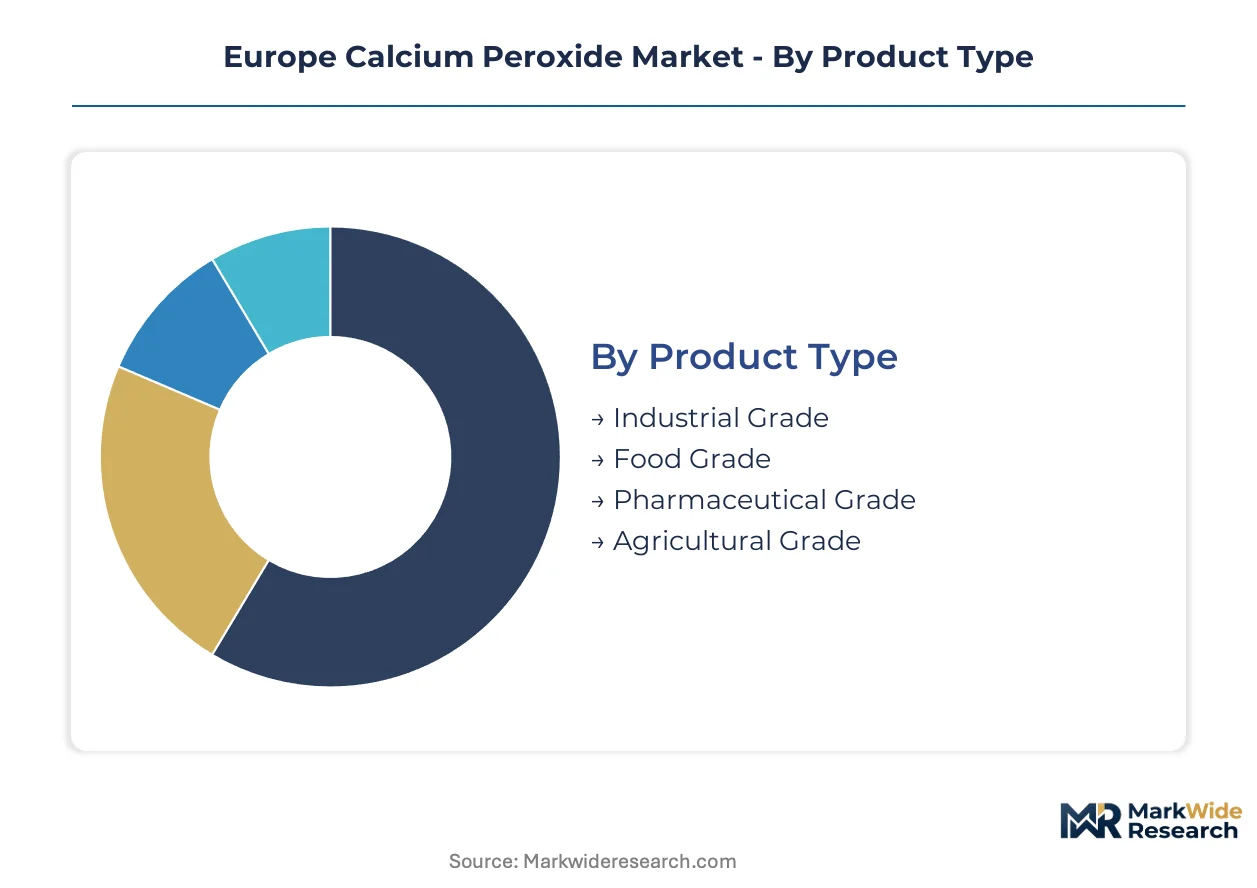
Segmentation in the European calcium peroxide market reflects divergent certification burdens and end-use specifications. Product grade distinctions determine REACH registration complexity and EFSA approval requirements, while application focus shapes regional demand concentration and procurement channel structure.
Product Type:
REACH compliance intensity escalates sharply from industrial through pharmaceutical grades, with ECHA substance evaluation timelines and purity thresholds creating tiered market entry barriers.
- Industrial Grade:Formulations typically contain 50-75% active CaO₂ with stabilizers for controlled oxygen release in groundwater remediation. Municipal utilities across Germany's Rhine-Ruhr corridor anchor volume demand through aerobic bioremediation contracts for contaminated aquifers.
- Food Grade:Refined to meet EFSA additive specifications for flour treatment and processing bleaching, requiring segregated production lines and enhanced impurity documentation. Northern Italian food processors drive premium positioning through direct-contact application approvals.
- Pharmaceutical Grade:Ultra-pure synthesis for medical oxygen generation meets EMA GMP standards with batch-level traceability.
- Agricultural Grade:Technical formulations for soil oxygenation and seed priming operate under national fertilizer regulations with lighter ECHA scrutiny.
Leading the category by volume: Industrial Grade. Growing fastest: Food Grade.
Application:
Application focus determines procurement scale, with municipal tenders dominating water treatment and fragmented farm-level purchasing characterizing organic agriculture.
- Water Treatment:Controlled oxygen release systems for groundwater bioremediation command the largest contract values. French environmental engineering firms deploy calcium peroxide for deep aquifer oxygenation at industrial legacy sites.
- Soil Treatment:Decontamination of hydrocarbon-impacted soils through slow-release oxidation. Benelux remediation contractors favor encapsulated granules for extended treatment cycles.
- Organic Agriculture:Crop oxygenation and root zone conditioning in certified organic operations. Iberian adoption remains underdeveloped relative to Central European intensity.
- Food Preservation:Bleaching and dough conditioning applications require EFSA-listed additive status. Premium positioning reflects compliance documentation burdens.
Water Treatment generates the largest absolute volumes. Organic Agriculture is climbing the fastest as EU Green Deal subsidies expand.
End User:
End-user type structures pricing power and technical service requirements, with manufacturers capturing formulation value and distributors managing logistics complexity.
- Manufacturers:Integrated peroxide producers supply industrial-grade formulations direct to large water treatment operators. Solvay SA and Evonik Industries AG dominate this channel through captive hydrogen peroxide feedstock.
- Distributors:Chemical distributors aggregate fragmented demand from mid-sized remediation contractors and agricultural cooperatives. Carus Group Inc. penetrates Central and Eastern European zones through specialized logistics networks.
- Farmers:Direct procurement of agricultural-grade material for soil conditioning remains limited by technical advisory gaps.
- Food Processors:Mill operators and baking facilities source food-grade calcium peroxide through approved additive suppliers with EFSA certification chains.
Manufacturers command the highest margin capture. Distributors are expanding most quickly through integrated service bundling.
Packaging Type:
Packaging configuration aligns with customer scale and handling infrastructure, from bulk rail deliveries to small-lot flexible containers.
- Bags:25-50kg multi-layer paper or polyethylene sacks for agricultural and small industrial users. Portuguese and Spanish distributors favor bagged formats for fragmented farm delivery.
- Drums:Steel or fiber drums containing 100-250kg for medium-volume water treatment operators. Northern Italian utilities specify drum formats for dosing system compatibility.
- Bulk Containers:Intermediate bulk containers and tanker deliveries for large municipal remediation projects. Rhine-Ruhr manufacturing clusters generate concentrated bulk demand.
- Custom Packaging:Modular sizing and private labeling for specialized pharmaceutical and food-grade applications.
Bulk Containers lead by tonnage moved. Custom Packaging shows the steepest expansion trajectory as digital procurement platforms reduce minimum order friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Central European chemical clusters while consumption pulls toward Western European remediation hotspots and Mediterranean agricultural zones. This spatial mismatch shapes logistics networks and distributor economics across the continent.
Germany
Rhine-Ruhr municipalities deploy calcium peroxide for deep aquifer oxygenation at legacy industrial sites. REACH registration mandates from ECHA compress supplier qualification timelines for water treatment contractors. Düsseldorf and Essen anchor concentrated demand through framework agreements covering formulation supply and dosing equipment.
France
Environmental engineering firms favor encapsulated granules for extended hydrocarbon remediation cycles in northern industrial zones. EFSA additive regulations govern expanding flour treatment applications in food processing. The Paris Basin and Lyon corridor generate premium-tier demand for pharmaceutical-grade synthesis serving medical oxygen generation.
Italy
Po Valley utilities consolidate fragmented procurement into single-source contracts with technical service bundling. National implementations of the EU F-Gas Regulation drive substitution toward peroxygen compounds in soil treatment. Northern chemical processing zones around Milan and Turin concentrate food-grade volume for direct-contact applications.
Spain
Iberian agricultural adoption remains underdeveloped relative to Central European intensity in soil oxygenation and seed priming. National fertilizer regulations apply lighter ECHA scrutiny to technical formulations for farm use. Andalusian and Valencian cooperatives represent expansion targets for modular packaging configurations reducing minimum order friction.
Poland
Production capacity clustering in Czech and Polish facilities creates vulnerability to regional logistics disruptions for Western European buyers. The country's national chemical regulator enforces REACH-aligned purity specifications for cross-border shipments. Silesian industrial zones supply industrial-grade formulations to Benelux remediation contractors.
Europe Calcium Peroxide Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation grades and geographic coverage zones. Market structure tilts toward consolidation at the industrial-grade volume tier while fragmenting across specialized pharmaceutical and food-grade niches. Three archetypes dominate: integrated peroxide producers with captive hydrogen peroxide feedstock, regional distributors with logistics networks penetrating underserved zones, and pharmaceutical-grade specialists with EMA GMP certification infrastructure. Capacity expansion and strategic partnerships represent the dominant competitive moves reshaping supply security.
Among integrated chemical conglomerates, Solvay SA and Evonik Industries AG occupy positions exemplifying backward integration into hydrogen peroxide feedstock supply. Carus Group Inc. represents the distributor archetype with geographic reach extending into Central and Eastern European industrial zones. These three anchors illustrate how competitive positioning stratifies across production control, regulatory certification depth, and logistics network density.
| Leading Market Players |
|---|
| PeroxyChem LLC |
| Carus Group Inc. |
| Solvay SA |
| Calmags GmBH |
| Merck KGaA |
| Evonik Industries AG |
| American Elements |
| Nikunj Chemicals |
| Arkema Group |
| Others |
Supply & Pricing Matrix
Encapsulated granule manufacturing is compressing unit economics for premium formulations while concentrating production control among German and Czech facilities with polymer-coating capabilities. REACH compliance investments and hydrogen peroxide feedstock volatility are simultaneously reshaping cost structures and supplier qualification barriers across European procurement channels.
Pricing Analysis
Margin tightening in food-grade tiers reflects EFSA certification documentation burdens and segregated production line requirements. Three-tier pricing structure across pharmaceutical, food, and industrial grades tracks purity thresholds and REACH registration intensity. Pricing pressure intensifies in industrial formulations as municipal utilities consolidate procurement into framework agreements with technical service bundling. Mid-sized water treatment operators show highest price sensitivity due to limited volume leverage, while pharmaceutical-grade buyers absorb premiums for EMA GMP batch traceability.
Supply Chain Analysis
Freight cost differentials between Polish production clusters and Iberian agricultural end-users are widening distributor margin capture opportunities for regional logistics specialists. Supply concentrates in Czech and Polish manufacturing facilities serving Western European demand, with hydrogen peroxide, calcium salt precursors, and polymer coating materials as critical inputs. Single-source vulnerability from Eastern European production clustering creates exposure to regional logistics disruptions. Distribution runs through integrated chemical conglomerates for large municipal contracts and specialized distributors for fragmented agricultural demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration timeline compression and hydrogen peroxide feedstock volatility are forcing selective exits among undercapitalized formulation specialists, creating consolidation opportunities for integrated producers with captive raw material supply.
For Market Incumbents: Lock in supply security through backward integration into hydrogen peroxide feedstock or long-term offtake agreements with Central European producers. Secure REACH registration asset bases ahead of ECHA substance evaluation period extensions. Prioritize certification depth in pharmaceutical-grade synthesis to defend margin pools against emerging Polish and Czech competitors with lower compliance infrastructure.
For New Entrants and Emerging Players: B2B platform procurement channels offer lower customer acquisition friction for modular packaging configurations targeting mid-sized water treatment operators in Iberia and southern Italy. Agricultural-grade soil oxygenation in Spain and Portugal presents the most penetrable white-space opportunity given underdeveloped adoption intensity. Lead with technical advisory services bundled with product supply to overcome farmer-level technical knowledge gaps.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated peroxide conglomerates seeking REACH registration assets and geographic footprint expansion. Five-to-ten-year viability hinges on regulatory compliance infrastructure depth rather than commodity scale. Monitor ECHA authorization timeline announcements for Substances of Very High Concern as inflection indicators for formulation substitution demand and asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogen Peroxide Feedstock | Captive supply from Solvay and Evonik insulates margin stability against raw material volatility. |
| REACH Registration Asset Acquisition | Pre-approved substance dossiers compress market entry timelines for modified formulations. |
| Encapsulated Granule Capacity Expansion | Polymer-coating capabilities extend treatment cycle duration for German groundwater remediation contractors. |
| Modular Packaging-Digital Platform Convergence | Flexible container sizing reduces minimum order friction for Portuguese and Spanish agricultural cooperatives. |
| EFSA Food Additive Regulatory Expansion | Approved flour treatment applications unlock premium volume channels in northern Italian food processing zones. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with water treatment procurement managers, environmental engineering directors, agricultural cooperative supply heads, chemical distributor logistics specialists, and ECHA regulatory affairs consultants. Cefic sector reports, ECHA registration databases, Eurostat trade flows, and SEC filings from listed chemical conglomerates provided demand-side validation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the European chemicals sector.
Reconciliation of production capacity disclosures, import-export flows, and end-use consumption surveys informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, application focus, end-user channel structure, and regional production hub. CAGRs derived from trend extrapolation of volume demand drivers and price trajectory assumptions, with hydrogen peroxide feedstock cost curves and REACH compliance investment cycles as industry-specific forecast inputs.
The model holds under stable ECHA regulatory enforcement and continued EU Green Deal implementation; deviation in authorization timeline extensions or raw material supply disruptions would shift volume and value trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Europe Hydrazine Market
Chemicals
Europe Fluorosilicic Acid Market
Chemicals
Phosphorus Pentasulfide (P2S5) Market
Chemicals
Linear Mercaptans Market
Chemicals
China Methanol Market
Chemicals
Global Benzalkonium Chloride Market
Chemicals
Europe Textile Chemicals Market
Chemicals
Cupric Chloride Market
Chemicals
Trimethylamine Market
Chemicals
Acetophenone Market
Chemicals
Guaiazulene Market
Chemicals
Gas Sweetening Chemicals Market
Chemicals
Global Inorganic Fluorides Market
Chemicals
Lead Tetracetate Market
Chemicals
Roofing Chemical Market
Chemicals
Middle East and Africa Methyl Acrylate Market