
 Asia-Pacific Methyl Acrylate Market | 2026-2036
Asia-Pacific Methyl Acrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Methyl Acrylate Market Outlook
The Asia-Pacific methyl acrylate supply base is consolidating around two distinct tiers: large-scale producers with captive acrylic acid supply and smaller emulsion specialists competing on formulation flexibility. Dow Chemical Company leverages its integrated acrylic acid-methyl acrylate chain across multiple production sites in the region. BASF anchors its position through advanced emulsion polymerization technology serving coatings and adhesives makers. Shanghai Huayi Acrylic Acid Co., Ltd dominates domestic Chinese supply with backward integration into propylene oxidation.
Methyl acrylate is an acrylate ester produced via esterification of acrylic acid with methanol, featuring a molecular weight of approximately 86.09 g/mol and a glass transition temperature near 10°C when homopolymerized; it functions primarily as a reactive monomer in polymer systems requiring hardness, clarity, and UV resistance. Coatings applications lead volume consumption due to architectural and industrial protective demand across Southeast Asian construction markets. Emulsion process technology commands expanding share as water-based formulations displace solvent systems under environmental compliance pressure. Adhesives and sealants represent the fastest-growing product category, driven by automotive lightweighting and electronics assembly requirements in South Korea and Japan.
China's MIIT enforces GB standards for volatile organic compound emissions in industrial coatings, directly restricting solvent-based methyl acrylate formulations and redirecting demand toward emulsion grades. Japan's METI chemical substance regulations and South Korea's MFDS industrial chemical frameworks impose registration and hazard communication requirements that raise compliance costs for imported material. India's BIS certification mandates for acrylic esters create additional testing barriers for non-domestic suppliers. Stakeholders must monitor evolving national chemical inventories across the region, as diverging registration timelines threaten to fragment supply access and force localized formulation strategies.
Market Dynamics
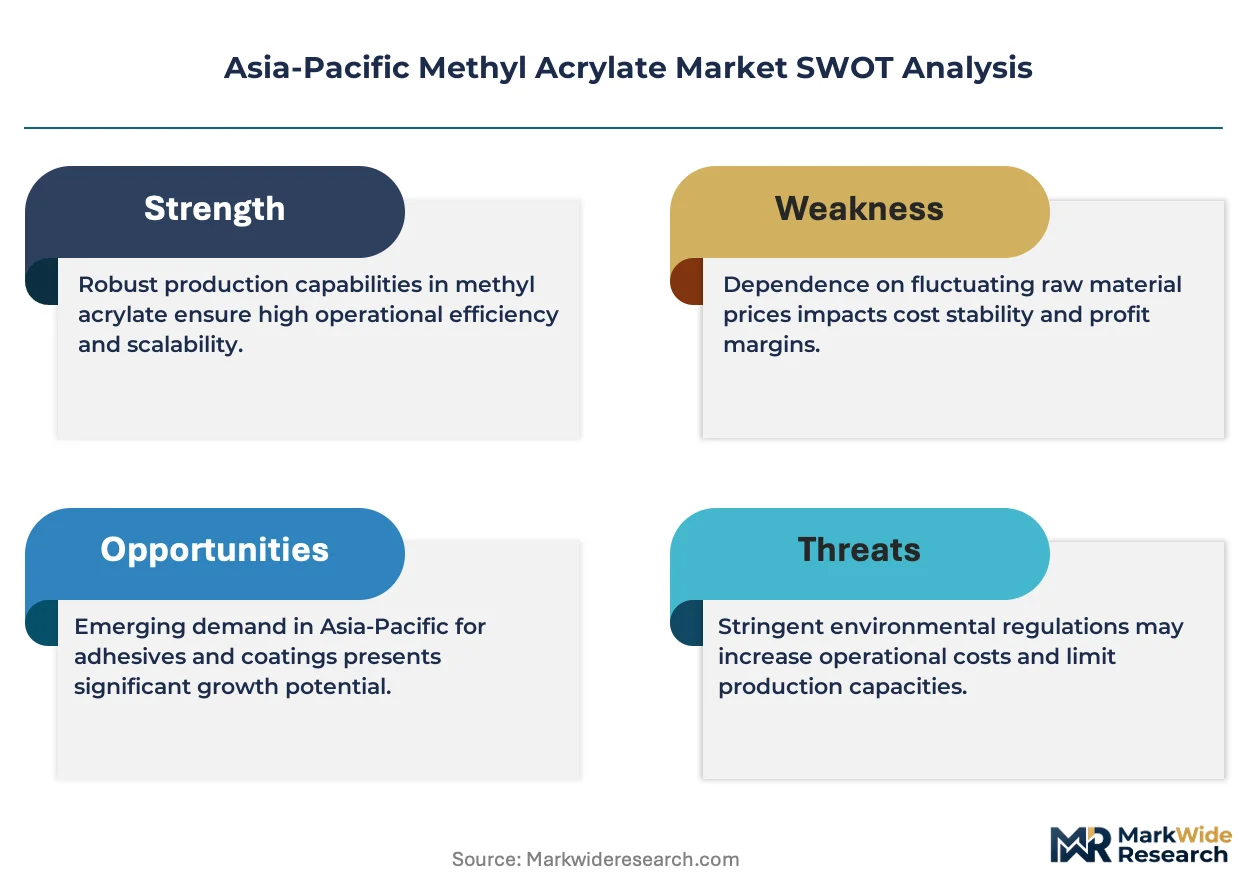
Water-based formulation mandates across Asia-Pacific are compressing solvent-based methyl acrylate demand while expanding emulsion-grade procurement, forcing manufacturers to reconfigure production lines and raw material sourcing strategies within compressed compliance timelines.
Growth Catalysts
- GB Standard VOC Limits:China's MIIT enforcement of industrial coating emissions rules redirects methyl acrylate consumption toward low-VOC emulsion grades, expanding addressable market for compliant formulations.
- Automotive Lightweighting:Adhesive applications in South Korean and Japanese vehicle assembly plants are consuming specialized methyl acrylate grades for structural bonding of composite components.
- Eastern China Chemical Corridor:Acrylic acid derivative clusters in Jiangsu and Zhejiang provinces concentrate downstream coatings and adhesive producers, creating localized demand density that reduces logistics costs for methyl acrylate suppliers.
Market Restraints
- Propylene Feedstock Volatility:Methyl acrylate production costs track naphtha-cracker propylene output, exposing margin compression when olefin markets tighten.
- Captive Supply Concentration:Large-scale producers with backward-integrated acrylic acid capacity control pricing power, limiting market entry for non-integrated emulsion specialists.
- BIS Certification Barriers:India's mandatory testing and registration requirements for acrylic ester imports create timeline friction that disadvantages smaller international suppliers.
Strategic Opportunities
- Vietnam Industrial Coatings:Manufacturing relocation from China into northern Vietnamese provinces is creating greenfield demand for architectural and protective coatings using methyl acrylate-based emulsions.
- Electronics Assembly Adhesives:Semiconductor packaging and display bonding applications in South Korea require ultra-pure methyl acrylate grades with specialized purity specifications.
- Japan METI Substance Framework:Chemical registration requirements favor established suppliers with documented hazard profiles, creating competitive moats against unregistered imports.
Industry Challenges
- Emulsion Polymerization Expertise Gap:Formulation chemists capable of optimizing water-based acrylic systems remain concentrated at major producers, constraining mid-tier manufacturer technical capabilities.
- Dual Inventory Compliance:Divergent national chemical inventories across China, Japan, South Korea, and India force suppliers to maintain separate registration dossiers and formulation variants, multiplying administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Methyl Acrylate Market |
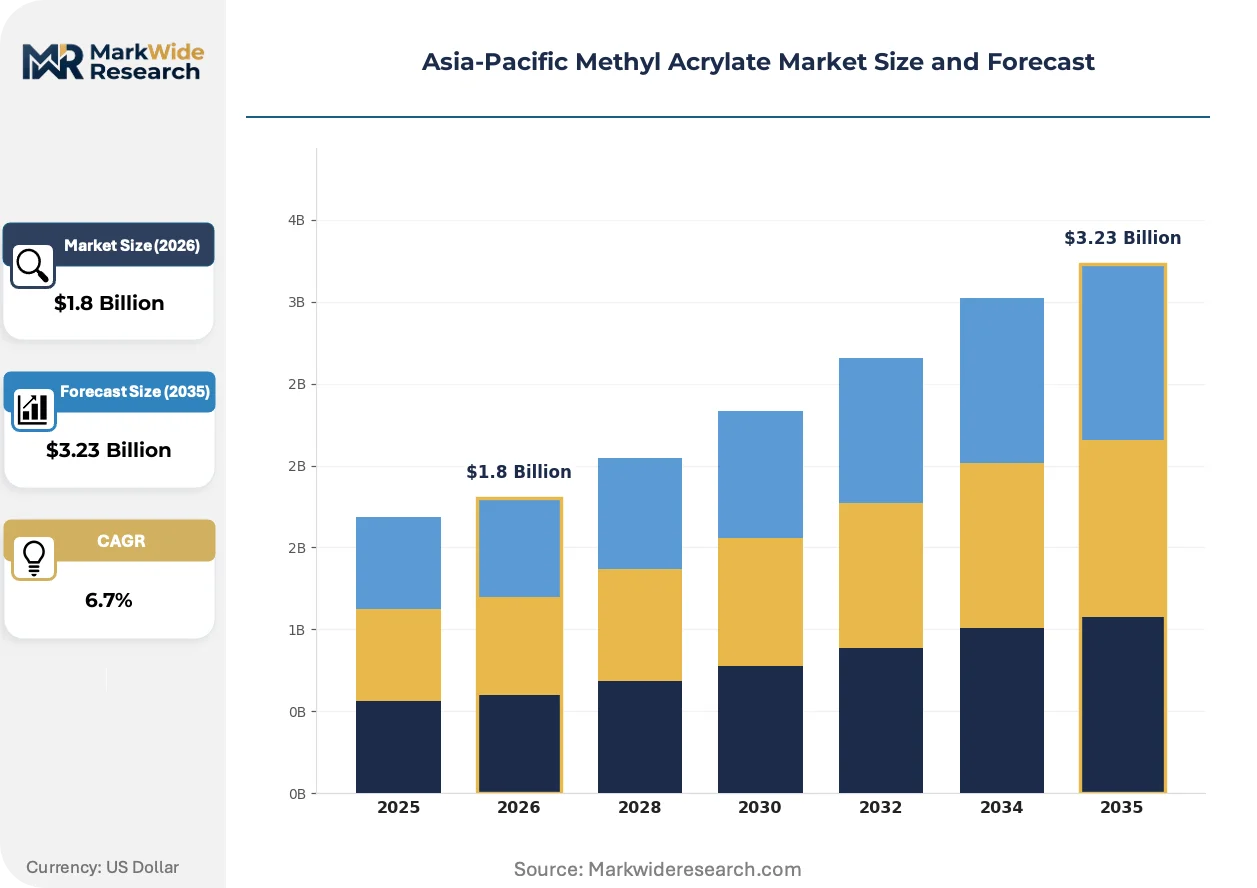
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Adhesives, Sealants, Inks Application: Construction, Automotive, Electronics, Textiles End User: Manufacturers, Distributors, Retailers, OEMs Technology: Polymerization, Emulsion Process, Suspension Process, Solution Process |
| Companies Covered | Dow Chemical Company, BASF, Evonik Industries AG, Arkema S.A., LG Chem Ltd., Shanghai Huayi Acrylic Acid Co., Ltd, DuPont, Sibur Holding, ISU Chemical, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Methyl Acrylate Market Strategic Shifts
Continuous reactor technology and closed-loop solvent recovery systems are redefining methyl acrylate production economics, while regulatory pressure on volatile organic compounds accelerates formulation chemistry shifts across coatings and adhesive end-uses.
Continuous stirred-tank reactor systems with inline analytics are automating esterification process control, reducing acrylic acid conversion variance from batch methods. Major Chinese producers are retrofitting Jiangsu-based facilities with these systems to capture yield improvements. The technology is automating quality assurance steps that previously required manual sampling and laboratory verification, compressing batch release cycles.
China's GB 30981-2020 standard for industrial protective coatings mandates VOC content thresholds that exclude high-solvent methyl acrylate formulations from state-funded infrastructure projects. Coatings manufacturers in Shandong and Guangdong provinces are reformulating product lines to meet these specifications. Architectural coatings for government and commercial construction now specify emulsion-grade raw materials exclusively, redirecting procurement specifications.
Specification-driven procurement by multinational coatings formulators is consolidating supplier relationships around certified emulsion-grade producers with documented carbon footprints. Tier-one buyers in Japan and South Korea now require lifecycle assessment data as a standard tender component. This pattern concentrates methyl acrylate sourcing decisions at headquarters technical teams rather than regional purchasing functions, extending qualification timelines but locking in multi-year supply commitments.
Asia-Pacific Methyl Acrylate Market Segmentation
Methyl acrylate procurement patterns diverge sharply across formulation chemistries and end-use specifications, forcing suppliers to maintain parallel production configurations. Segmentation clarity enables manufacturers to align reactor technology choices with margin profiles across coatings, adhesives, and specialty applications.
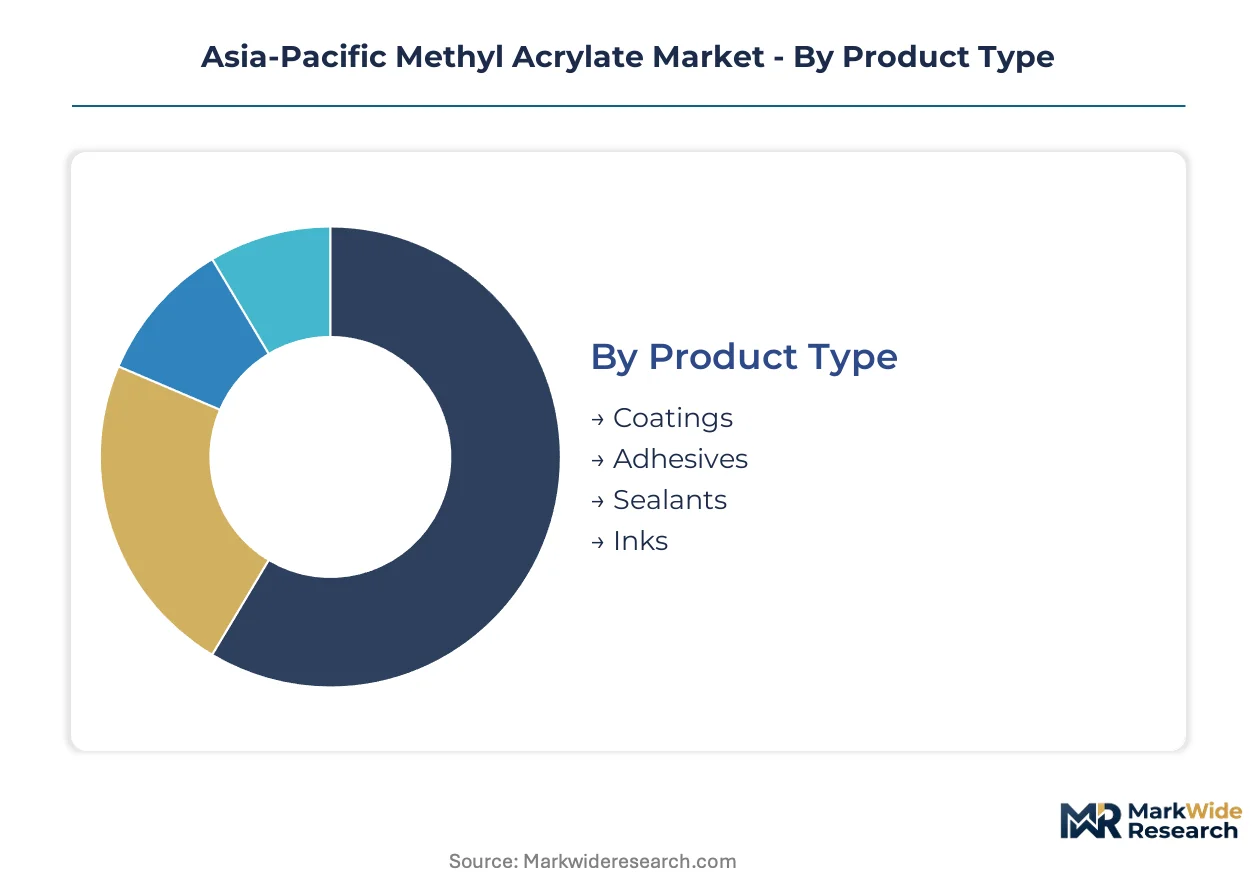
Product Type:
Standardization dominates commodity coatings grades, while adhesives and sealants command customized purity protocols and tailored glass transition specifications.
- Coatings:Architectural and industrial protective formulations consume the majority of emulsion-grade methyl acrylate, with procurement specifications tightening around China's GB 30981-2020 VOC thresholds. Water-based acrylic emulsions for construction exteriors and automotive refinish drive volume concentration in Jiangsu and Shandong province manufacturing clusters.
- Adhesives:Structural bonding applications require specialized monomer grades with controlled residual acid content below 0.05 percent for automotive lightweighting and electronics assembly. South Korean vehicle manufacturers and Japanese semiconductor packaging operations specify ultra-purity certifications that command premium positioning over standard industrial grades.
- Sealants:Construction joint compounds and automotive seam sealers utilize medium-viscosity methyl acrylate copolymers with flexibility modifiers.
- Inks:UV-curable and solvent-based printing formulations employ high-clarity monomer grades for packaging and publication applications.
Leading the category by volume: Coatings. Expanding most quickly: Adhesives.
Application:
Construction absorbs standardized bulk volumes, whereas automotive and electronics segments demand application-engineered specifications with tighter certification requirements.
- Construction:Architectural coatings for residential and commercial buildings represent the foundational demand base, with procurement centralized through state-funded infrastructure tenders in China that mandate emulsion-grade compliance. Protective coatings for bridges, pipelines, and industrial facilities in India and Southeast Asia follow specification patterns established by Chinese GB standards.
- Automotive:Structural adhesives for composite body-in-white assembly and interior bonding applications consume specialty grades with rapid cure profiles and thermal stability above 120°C. Japanese and South Korean OEM qualification protocols extend supplier approval timelines but lock in multi-year contract structures.
- Electronics:Display bonding and semiconductor encapsulation require sub-ppm impurity specifications with documented ionic content.
- Textiles:Fabric finishing and nonwoven binders utilize conventional emulsion polymerization grades with soft hand modifiers.
Construction maintains the largest volume share. Electronics climbs fastest on purity-premium expansion.
End User:
Direct manufacturer relationships concentrate technical specification control, while distributor and retail channels fragment procurement across smaller formulation operations.
- Manufacturers:Integrated coatings and adhesives producers with captive emulsion polymerization capability purchase methyl acrylate in bulk quantities, negotiating long-term supply agreements tied to propylene price indices. Dow Chemical Company and BASF anchor procurement through backward-integrated supply chains, while Chinese domestic formulators in Zhejiang province rely on spot market flexibility.
- Distributors:Regional chemical distributors serve mid-tier formulators lacking direct producer relationships, consolidating smaller volume orders across multiple end-use categories.
- Retailers:Specialty chemical retailers reach small-scale coating shops and repair operations with packaged quantities.
- OEMs:Automotive and electronics original equipment manufacturers specify qualified supplier lists that restrict sourcing to pre-certified methyl acrylate producers with documented hazard communication dossiers.
Manufacturers dominate procurement volume. OEMs gain fastest on specification-driven consolidation.
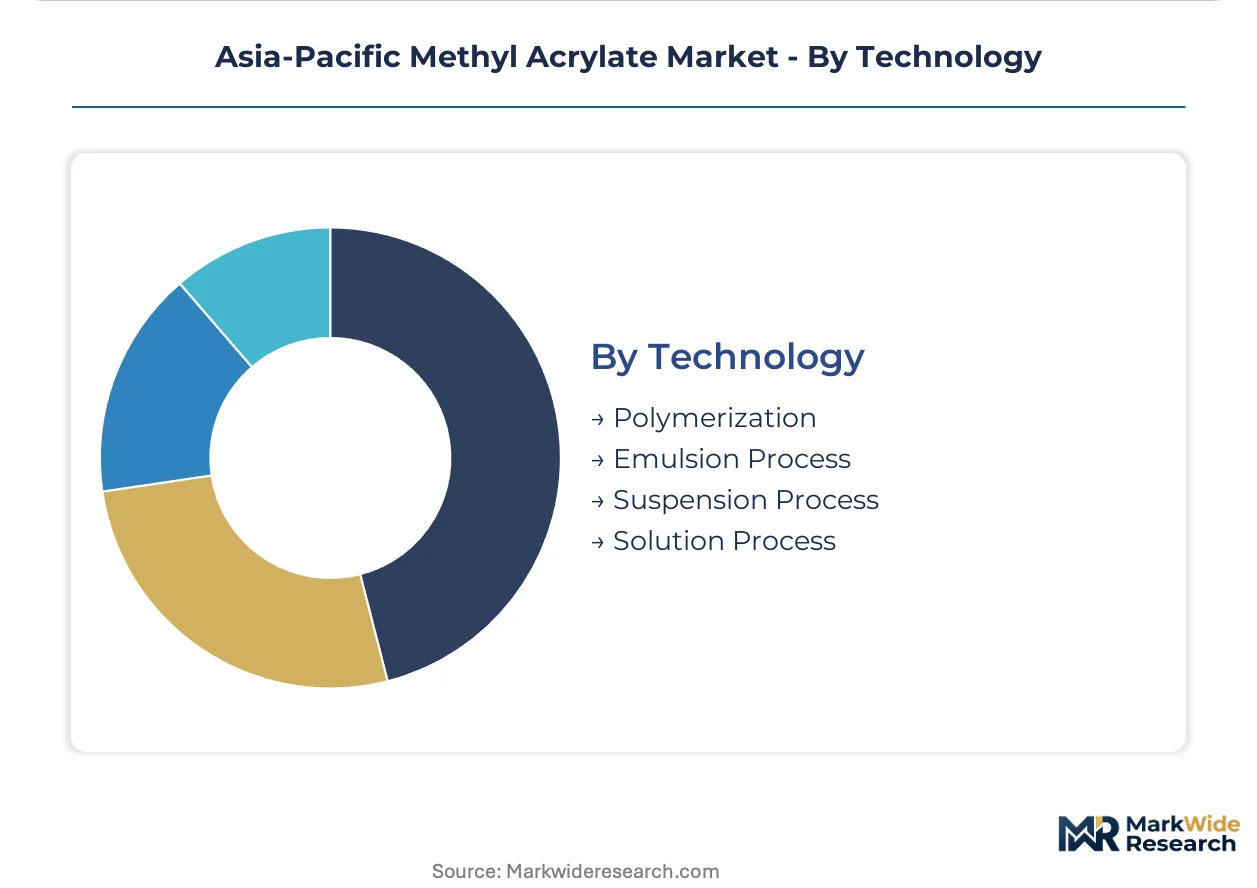
Technology:
Emulsion and solution processes split the market between environmental compliance leaders and legacy solvent-system holdouts facing regulatory compression.
- Polymerization:Bulk and solution polymerization systems produce high-molecular-weight copolymers for specialty adhesive applications requiring precise molecular architecture control.
- Emulsion Process:Water-based emulsion polymerization commands expanding share as China's MIIT VOC enforcement and India's BIS certification redirect formulation investments away from solvent systems. Continuous stirred-tank reactor retrofits in Jiangsu province automate quality control and compress batch release cycles for compliant coatings production.
- Suspension Process:Bead polymerization generates solid resin grades for powder coatings and thermoplastic applications.
- Solution Process:Solvent-based systems retain niche positions in high-performance automotive refinish and industrial maintenance coatings where waterborne alternatives lack durability benchmarks, though regulatory pressure from Japan's METI substance framework and South Korea's MFDS registration requirements erode long-term viability.
Emulsion process leads by volume. Polymerization gains fastest on specialty adhesive demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor methyl acrylate demand through their acrylic acid derivative clusters serving coatings and adhesive manufacturers. Eastern China's chemical manufacturing corridor concentrates downstream formulators within tight logistics radiuses of propylene oxidation facilities. Divergent national chemical inventories across the region force suppliers to maintain parallel registration dossiers and formulation variants.
China
Architectural coatings procurement for state-funded infrastructure projects drives bulk methyl acrylate consumption through centralized tenders. MIIT enforcement of GB 30981-2020 VOC thresholds mandates emulsion-grade raw materials for government construction contracts. Shandong and Guangdong province manufacturers are reformulating product lines to meet these specifications, redirecting procurement away from solvent-based systems.
India
Industrial protective coatings for bridges and pipelines absorb standardized methyl acrylate volumes following specification patterns established by Chinese GB standards. BIS certification requirements for acrylic ester imports create testing barriers that disadvantage smaller international suppliers. Maharashtra and Gujarat chemical manufacturing zones concentrate domestic formulators seeking spot market flexibility for emulsion polymerization feedstock.
Japan
Semiconductor packaging and display bonding applications demand ultra-pure methyl acrylate grades with sub-ppm impurity specifications. METI chemical substance registration requirements favor established suppliers with documented hazard communication dossiers. Kansai region electronics assemblers specify qualified supplier lists that restrict sourcing to pre-certified producers with multi-year contract structures.
South Korea
Automotive lightweighting initiatives consume specialized methyl acrylate grades for structural bonding of composite body-in-white components. MFDS industrial chemical frameworks impose registration and hazard communication requirements that raise compliance costs for imported material. Busan-Ulsan manufacturing corridor hosts vehicle assembly plants with extended supplier qualification protocols locking in multi-year supply commitments.
Vietnam
Manufacturing relocation from China into northern Vietnamese provinces generates greenfield demand for architectural and protective coatings. Provincial industrial zones attract coatings formulators seeking lower-cost emulsion polymerization capacity. Hai Phong and Bac Ninh manufacturing clusters concentrate new entrants requiring methyl acrylate feedstock for water-based formulation lines.
Asia-Pacific Methyl Acrylate Market Competitive Environment
Capital-heavy producers with captive acrylic acid supply compete with asset-light emulsion specialists on formulation flexibility. The supply base consolidates around two distinct tiers: large-scale integrated producers controlling pricing power and smaller regional players competing on technical service. Strategic archetypes include backward-integrated petrochemical conglomerates, advanced emulsion technology licensors, and domestic Chinese propylene oxidation specialists. Dominant competitive moves encompass continuous reactor retrofits for yield improvement and multi-year supply agreements tied to propylene price indices.
Within the integrated petrochemical tier, Dow Chemical Company and BASF exemplify multinational producers leveraging regional production networks. Shanghai Huayi Acrylic Acid Co., Ltd occupies a position among domestic Chinese manufacturers with propylene oxidation capabilities. These three entities represent contrasting archetypes: multinational technology licensors, regional integrated producers, and specialized domestic suppliers serving eastern China chemical corridor demand.
| Leading Market Players |
|---|
| Dow Chemical Company |
| BASF |
| Evonik Industries AG |
| Arkema S.A. |
| LG Chem Ltd. |
| Shanghai Huayi Acrylic Acid Co., Ltd |
| DuPont |
| Sibur Holding |
| ISU Chemical |
| Others |
Value Chain & Pricing Dynamics
Backward integration into propylene oxidation anchors both supply security and pricing leverage for Asia-Pacific methyl acrylate producers. Captive acrylic acid output insulates integrated players from olefin market volatility while compressing margins for non-integrated emulsion specialists competing on formulation flexibility.
Pricing Analysis
Yield-based pricing anchors methyl acrylate contracts to downstream coatings throughput and adhesive production efficiency. Three-tier pricing structure across premium, standard, and economy levels separates ultra-purity semiconductor grades from industrial coatings feedstock and commodity construction emulsions. Cost compression in standard grades intensifies because propylene feedstock volatility transmits directly to spot market quotations. Small-scale formulators in Vietnam and India exhibit highest price sensitivity, while Japanese electronics assemblers accept premium positioning for documented impurity profiles.
Supply Chain Analysis
Freight cost differentials favor producers located within the Jiangsu-Zhejiang chemical corridor serving eastern China coatings clusters. Supply concentrates in China, South Korea, and Japan, with propylene, methanol, and catalyst systems feeding from regional petrochemical complexes. Single-source vulnerability runs through concentrated acrylic acid derivative capacity in Jiangsu province. Distribution runs through direct manufacturer relationships for bulk volumes and regional chemical distributors for mid-tier formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific methyl acrylate market functions as a vertical-integration race where upstream propylene control and downstream emulsion formulation capability determine competitive endurance. Players are pursuing captive acrylic acid supply as the decisive lever for margin defense and volume security.
For Market Incumbents: Anchor pricing power through continuous reactor retrofits that compress batch release cycles and automate quality assurance. Deepen captive propylene supply through long-term offtake agreements with naphtha crackers in South Korea and eastern China. Defend against emulsion-grade commoditization by locking multi-year supply commitments with Japanese electronics assemblers requiring ultra-purity certification. For New Entrants and Emerging Players: GB 30981-2020 in China opens a window for specialized emulsion-grade producers serving Shandong and Guangdong reformulation demand. Target Vietnam's northern industrial zones where manufacturing relocation generates greenfield coatings capacity without incumbent supplier relationships. Lead with technical service capabilities that compensate for lack of backward integration, emphasizing formulation optimization support for water-based system transitions. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated petrochemical conglomerates seeking Asia-Pacific emulsion technology platforms. Long-term viability favors producers with demonstrated compliance across China's MIIT, Japan's METI, and South Korea's MFDS regulatory frameworks. Monitor BIS certification timeline acceleration in India as the inflection signal for supply access fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive propylene oxidation capacity insulates margin structures from olefin market volatility in Jiangsu province. |
| Continuous Reactor Retrofit | Inline analytics automation reduces acrylic acid conversion variance and compresses batch release cycles for emulsion grades. |
| Multi-year Supply Agreement | Propylene-indexed contracts lock volume commitments with Japanese automotive OEMs and Korean electronics assemblers. |
| Regulatory Certification Investment | Documented hazard communication dossiers satisfy METI, MFDS, and BIS requirements that fragment supply access. |
| Geographic Capacity Expansion | Greenfield emulsion polymerization facilities in Vietnam capture manufacturing relocation demand from Chinese coatings producers. |
Study Parameters
Independent corroboration across plant managers at Jiangsu-based production facilities, procurement leads at downstream coatings OEMs, and distribution channel partners underwrites the qualitative findings in this study. Technical R&D directors at emulsion polymerization operations provided primary perspective on formulation shift dynamics. Secondary validation drew from customs and trade data, ACC and Cefic regional reports, and SEC 10-K disclosures from multinational chemical producers. Bottom-up volume estimates triangulated against top-down demand modeling across application segments.
Rate-of-change decomposition separates volume growth into construction coatings absorption, automotive adhesive substitution, and electronics purity-premium expansion across the analysis window. Segmentation dimensions encompass grade tier, end-use industry, and regional production hub configuration. CAGRs were derived from iterative convergence of demand-side uptake curves and supply-side capacity addition schedules. Forecast inputs incorporated propylene price index trajectories and VOC regulatory enforcement intensity by national jurisdiction.
The model assumes a particular technology adoption path; alternative pathways for continuous stirred-tank reactor diffusion would alter the outlook for yield improvement and quality variance reduction. Forecasts reflect documented assumptions regarding MIIT enforcement consistency and BIS certification timeline adherence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Mercuric Chloride Market
Chemicals
Diethylenetriamine (DETA) Market
Chemicals
Global Construction Chemical Market
Chemicals
Photographic Chemicals Market
Chemicals
Chromium Trioxide Market
Chemicals
Coal Tar Market
Chemicals
Catechol Market
Chemicals
Allyl Chloride Market
Chemicals
Photographic Film Processing Chemicals Market
Chemicals
Isooctyl Alcohol Market
Chemicals
Morpholine Market
Chemicals
Cold Phosphating Chemicals Market
Chemicals
India Ethoxylates Market
Chemicals
Global Amines Market
Chemicals
Ethylenediamine (EDA) Market
Chemicals
Pentanedione Market