
 Menadione Market | 2026-2036
Menadione Market Size, Share, and Industry Trends Forecast 2026-2036
Menadione Market Foresight
Technical-grade specification and purity certification services is realigning how menadione suppliers monetize output beyond base chemical sales. Brother Enterprises Holding Co Ltd leverages captive fermentation capacity to anchor vitamin K3 derivative supply chains. Haining Huawei Chemical Co Ltd specializes in powder-grade menadione for pharmaceutical intermediates. Oxyvit Kimya San Ve Tic A Fi competes through Turkish production positioning between Asian supply and European demand.
Menadione, a synthetic naphthoquinone compound designated vitamin K3, functions as a procoagulant precursor and animal feed fortificant, typically manufactured via oxidation of 2-methylnaphthalene with chromic acid or air oxidation processes yielding 96-98% purity grades. Powder formulations dominate pharmaceutical and nutraceutical channels where precise dosing and extended shelf stability command premium positioning, while liquid and oil variants anchor animal feed blending operations where homogenization with fat carriers simplifies incorporation. Granule formats represent the fastest-growing structural category as premix manufacturers seek dust-free handling and reduced segregation during bulk transport.
China's SAMR enforces GB 1903.43 feed additive standards that mandate heavy metal limits and assay specifications for menadione sodium bisulfite variants used in livestock rations. The EU REACH framework and EFSA feed additive evaluations constrain market access for non-registered producers seeking European animal nutrition channels. India's FSSAI and BIS certification requirements shape import quality benchmarks for nutraceutical applications. Stakeholders must monitor evolving residue tolerance thresholds in major protein-exporting jurisdictions where veterinary drug regulation directly constrains vitamin K3 inclusion rates.
Market Dynamics
Feed-grade menadione producers face mounting pressure from China's GB 1903.43 standard revisions and EFSA's tightened residue thresholds, forcing reformulation investments that favor integrated chromic acid oxidation operators over toll manufacturers.
Growth Catalysts
- Livestock protein demand:Poultry and swine operations in Vietnam and Indonesia are scaling vitamin K3 premix inclusion to reduce hemorrhagic disorders in high-density farming systems.
- REACH registration completion:ECHA's 2023 menadione sodium bisulfite dossier acceptance opened EU feed compounder channels previously restricted to European-sourced material.
- Continuous oxidation reactor deployment:Jiangsu-based producers are replacing batch chromic acid systems with air-oxidation loops that cut solvent recovery costs.
Market Restraints
- Chromic acid supply concentration:Kazakhstan and South African chromium ore processing dominates precursor availability, exposing formulators to volatile hexavalent chromium pricing.
- EFSA evaluation timelines:Pending reauthorization of menadione sodium bisulfite as a feed additive creates inventory hesitation among Dutch and Danish premix manufacturers.
- Phylloquinone substitution:Natural vitamin K1 from alfalfa extraction is capturing pharmaceutical applications where synthetic provenance faces consumer scrutiny.
Strategic Opportunities
- Brazilian aquaculture expansion:ANVISA's pending feed additive harmonization with Codex Alimentarius standards positions menadione for shrimp and tilapia ration fortification.
- Granule format premix integration:Dust-free menadione bisulfite granules are penetrating Brazilian and Mexican poultry operations seeking automated blending compatibility.
- India PLI scheme alignment:FSSAI's nutraceutical ingredient localization incentives attract investment for pharmaceutical-grade menadione diacetate production.
Industry Challenges
- Assay validation bottlenecks:Third-party certification of 96-98% purity grades against evolving GB and EP monographs extends batch release timelines.
- Cross-contamination protocols:Multi-product fermentation facilities must segregate menadione bisulfite from other vitamin K derivatives to prevent mislabeling violations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Menadione Market |
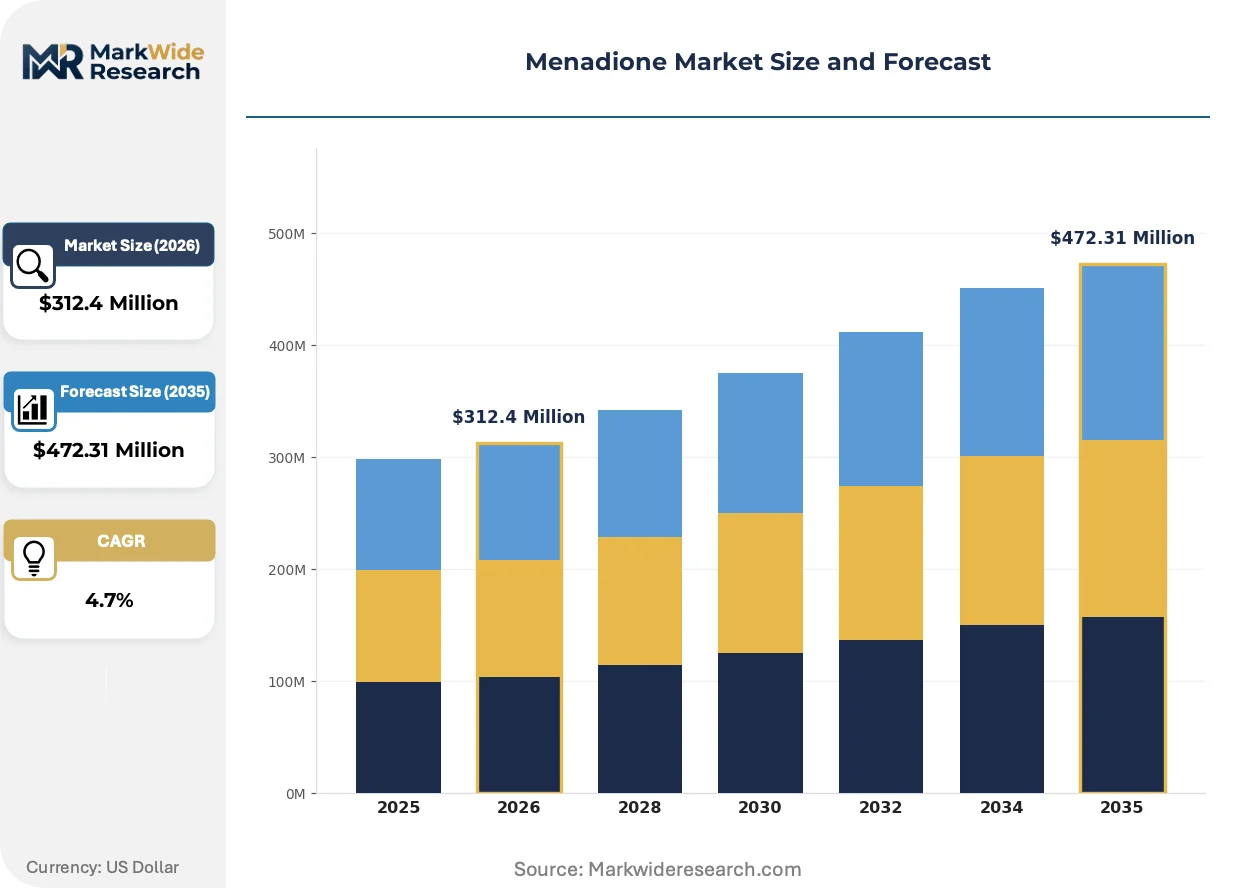
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granules, Oil Application: Animal Feed, Pharmaceuticals, Cosmetics, Nutraceuticals End User: Agriculture, Healthcare, Personal Care, Food Industry Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | Oxyvit Kimya San Ve Tic A Fi, Dirox SA, Haining Huawei Chemical Co Ltd, Lier Chemical Co Ltd, Xiangshui Huasheng Chemical Co Ltd, Brother Enterprises Holding Co Ltd, Vishnu Chemicals Limited, Sigma-Aldrich Corporation, Foodchem International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Menadione Market Shifts & Advancements
Process intensification and regulatory data requirements are compressing the viable producer base while creating openings for specification-differentiated suppliers.
Continuous flow oxidation technology is expanding into menadione production as Zhejiang and Shandong chemical parks retrofit air-oxidation reactors to replace legacy chromic acid batch vessels. Feed compounders in Thailand and the Philippines are qualifying this output for premium premix contracts. The technology is expanding into cost structures that previously favored toll manufacturing, enabling captive integration by mid-scale fermentation operators.
EFSA's 2024 updated guidance on vitamin K3 residue monitoring in animal tissues is tightening analytical method requirements for liver and kidney testing. Dutch and Spanish premix manufacturers are upgrading HPLC-MS capabilities to demonstrate compliance. The regulation is expanding into documentation burdens that favor producers with established EU regulatory affairs functions over Asian exporters relying on distributor registration.
Compound feed mills are consolidating procurement through integrated vitamin premix suppliers rather than direct menadione bisulfite sourcing. Large Brazilian and Vietnamese poultry integrators are negotiating multi-year supply agreements with DSM and Adisseo for complete vitamin K premixes. The shift is expanding into margin compression for standalone menadione merchants unable to offer formulation services or stability guarantees.
Menadione Market Segmentation
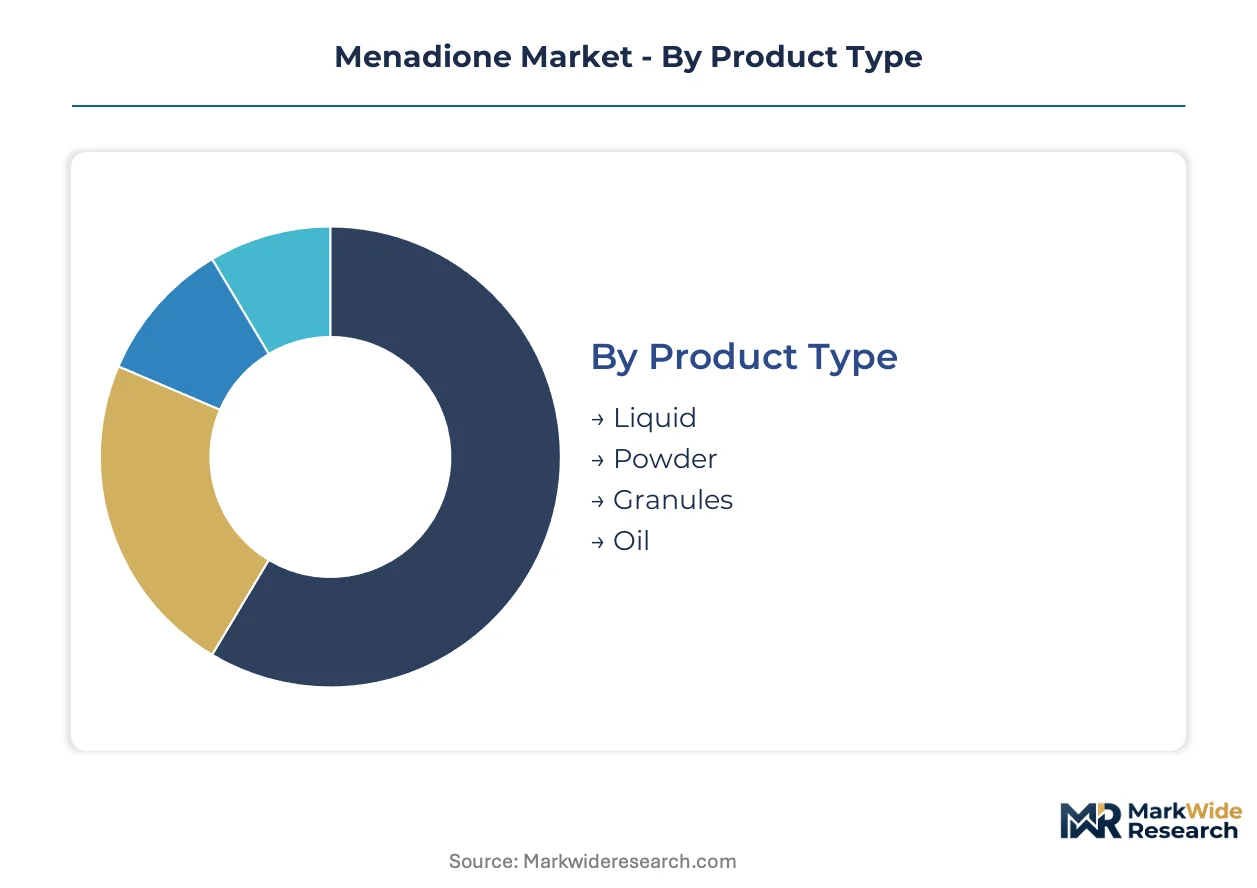
Menadione market segmentation reveals how formulation chemistry and regulatory compliance requirements fragment value capture across supply chains. Distinct purity grades, application protocols, and channel economics create specialized competitive arenas where specification expertise determines margin retention.
Product Type:
Chromic acid oxidation and air-oxidation reactor outputs concentrate differently across physical formats, with handling properties and stability profiles dictating facility investment patterns.
- Powder:Crystalline menadione sodium bisulfite at 96-98% assay specification serves pharmaceutical intermediate synthesis and precise nutraceutical dosing where extended shelf stability commands premium positioning. Jiangsu and Zhejiang province producers dominate this grade, supplying DSM and Adisseo for premix formulation.
- Granules:Dust-free bisulfite granules manufactured through fluidized bed agglomeration enable automated blending compatibility in Brazilian and Mexican poultry operations while reducing segregation during bulk transport. Premix manufacturers in Thailand and the Philippines are qualifying this output for multi-year supply contracts.
- Liquid:Aqueous solutions of menadione sodium bisulfite simplify incorporation into aqueous feed slurries for aquaculture applications.
- Oil:Fat-soluble menadione formulations homogenize with lipid carriers for direct feed blending without premix intermediation.
Powder absorbs the bulk of installed capacity; granules are expanding most quickly as automated feed mill investment accelerates across Southeast Asia and Latin America.
Application:
Regulatory residue thresholds and end-use certification requirements stratify demand intensity, with veterinary drug oversight creating divergent compliance burdens across segments.
- Animal Feed:Vitamin K3 fortification of poultry and swine rations addresses hemorrhagic disorders in high-density farming systems across Vietnam and Indonesia. China's GB 1903.43 standard and EFSA feed additive evaluations constrain formulation flexibility, favoring integrated producers with established regulatory affairs functions.
- Pharmaceuticals:Menadione serves as procoagulant precursor in synthetic vitamin K manufacturing where pharmacopeial compliance against EP and USP monographs mandates validated assay protocols. Indian pharmaceutical manufacturers under CDSCO oversight are expanding diacetate derivative production for injectable formulations.
- Nutraceuticals:Dietary supplement applications face substitution pressure from natural phylloquinone extracted from alfalfa, constraining synthetic menadione penetration in consumer-facing channels.
- Cosmetics:Topical formulations leverage menadione derivatives for claimed skin-brightening properties in Asian personal care markets.
Animal feed absorbs the bulk of installed capacity; pharmaceuticals are gaining share fastest as Indian and Chinese API manufacturers deepen backward integration into vitamin K3 intermediates.
End User:
Procurement scale and technical specification sophistication vary sharply across customer categories, with integrated livestock operations and pharmaceutical manufacturers exerting contrasting bargaining leverage.
- Agriculture:Compound feed mills and poultry integrators in Brazil and Vietnam consolidate procurement through DSM and Adisseo for complete vitamin K premixes, compressing margins for standalone menadione merchants lacking formulation services.
- Healthcare:Hospital and clinical settings utilize menadione derivatives for neonatal hemorrhagic disease prophylaxis and anticoagulant reversal where regulatory dossier completeness determines supplier qualification.
- Personal Care:Cosmetic formulators in South Korea and Japan specify menadione derivatives for topical applications with stability testing protocols exceeding feed-grade requirements.
- Food Industry:Food fortification applications remain limited by consumer preference for natural vitamin K sources and stringent FSSAI and FDA labeling requirements.
Agriculture commands the dominant share of volume throughput; healthcare is climbing the fastest as Indian PLI scheme incentives attract pharmaceutical-grade investment.
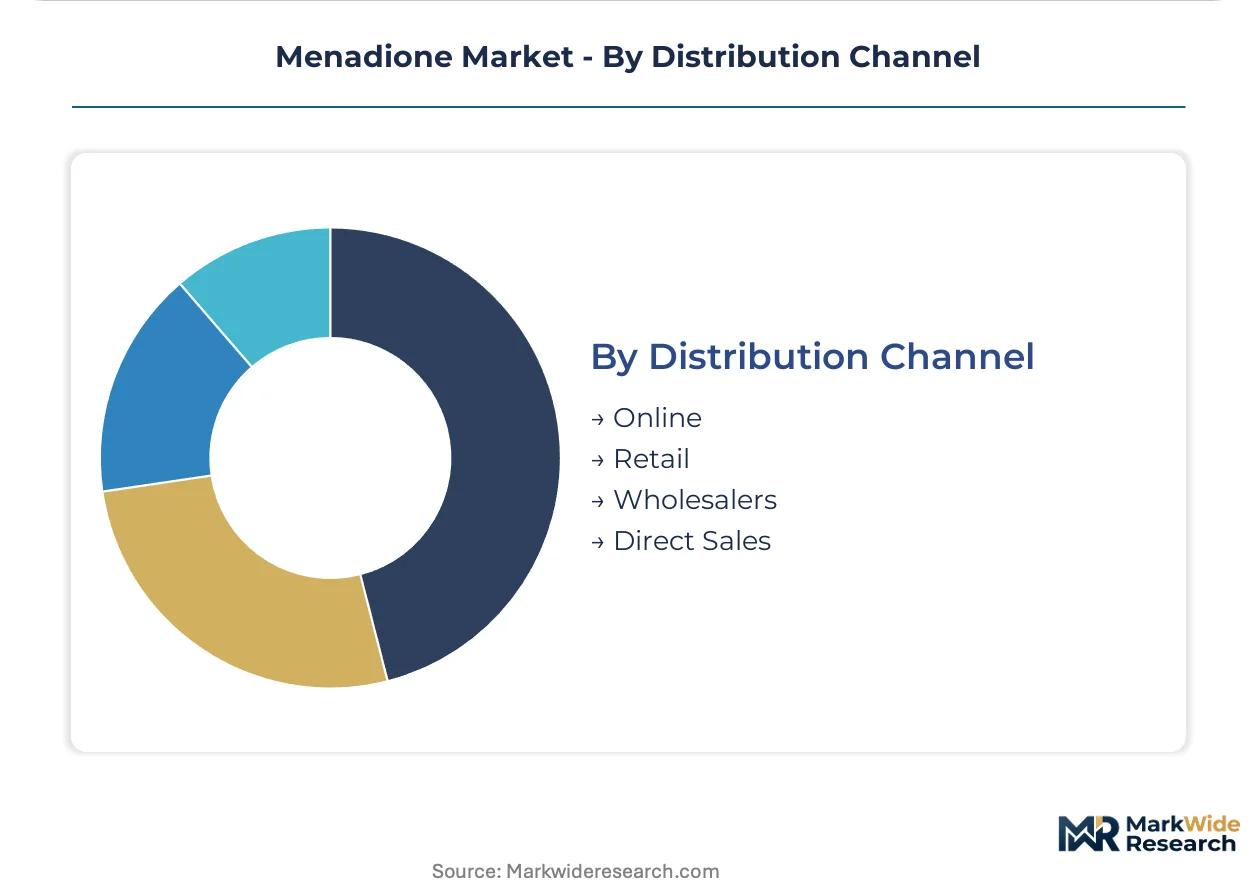
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and geographic proximity to manufacturing clusters, with direct relationships consolidating among large-volume buyers.
- Direct Sales:Long-term supply agreements between Jiangsu producers and multinational premix formulators eliminate intermediary margins while enabling customized stability guarantees and joint regulatory dossier preparation for EFSA and SAMR submissions.
- Wholesalers:Regional distributors serve mid-scale feed compounders in secondary Vietnamese and Indonesian markets where lot size minimums and technical support requirements fall below direct sales thresholds.
- Online:E-commerce platforms facilitate spot procurement for small-scale nutraceutical manufacturers and research institutions requiring kilogram-scale quantities with rapid delivery.
- Retail:Pharmacy and veterinary supply channels distribute finished menadione formulations for clinical and on-farm applications.
Direct sales capture the dominant share of value; online channels are expanding most quickly as small-batch nutraceutical manufacturers proliferate across India and Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in East Asian chemical parks while consumption spreads across protein-exporting economies. Chromic acid oxidation and air-oxidation reactor deployment concentrates in Jiangsu and Zhejiang provinces. Regulatory divergence between SAMR's GB standards and EFSA residue thresholds fragments compliance requirements.
China
Poultry integrators in Shandong and Henan provinces drive feed-grade menadione consumption for hemorrhagic disease prevention in high-density operations. SAMR's GB 1903.43 standard mandates heavy metal limits and assay specifications that favor integrated producers with captive chromic acid oxidation capacity. Jiangsu province hosts the dominant synthesis cluster where continuous air-oxidation reactor retrofits are displacing legacy batch vessels.
Brazil
Broiler and swine operations in São Paulo and Paraná states scale vitamin K3 premix inclusion to meet export certification requirements for EU and Middle Eastern protein markets. ANVISA's pending feed additive harmonization with Codex Alimentarius standards positions menadione for aquaculture expansion in shrimp and tilapia rations. Compound feed mills in the South Region consolidate procurement through multinational premix suppliers.
India
Pharmaceutical API manufacturers in Gujarat and Maharashtra deepen backward integration into menadione diacetate production for injectable formulations under CDSCO oversight. FSSAI nutraceutical certification requirements shape import quality benchmarks while PLI scheme incentives attract pharmaceutical-grade investment. Hyderabad and Ahmedabad clusters specialize in pharmacopeial-grade synthesis for domestic and export markets.
Germany
Premix formulators in Lower Saxony and North Rhine-Westphalia upgrade HPLC-MS capabilities to meet EFSA's 2024 residue monitoring guidance for liver and kidney testing. REACH registration completion for menadione sodium bisulfite opened channels previously restricted to European-sourced material. Dutch and Danish compounders leverage German distributors for EFSA dossier preparation and regulatory affairs support.
United States
Specialty chemical distributors serve research institutions and small-batch nutraceutical manufacturers requiring kilogram-scale quantities with rapid delivery. FDA oversight of feed additive labeling constrains direct incorporation by mid-scale livestock operations. Texas and Iowa compound feed mills rely on imported premix formulations rather than standalone menadione bisulfite sourcing.
Menadione Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across a bifurcated structure. Chromic acid oxidation operators with captive fermentation capacity anchor supply security for multinational premix formulators. Toll manufacturers face margin compression as continuous reactor deployment enables mid-scale captivity. Three archetypes dominate: integrated chemical conglomerates with backward chromium ore access, specialized naphthoquinone synthesis houses, and regional distributors with regulatory dossier capabilities. Competitive moves concentrate on EFSA/REACH registration completion and granule format premix integration partnerships.
Among Chinese synthesis specialists, Brother Enterprises Holding Co Ltd and Haining Huawei Chemical Co Ltd exemplify the integrated production archetype with Zhejiang province positioning. Oxyvit Kimya San Ve Tic A Fi occupies a bridging position between Asian supply clusters and European demand channels. These three represent distinct geographic and functional specializations without overlapping strategic positioning.
| Leading Market Players |
|---|
| Oxyvit Kimya San Ve Tic A Fi |
| Dirox SA |
| Haining Huawei Chemical Co Ltd |
| Lier Chemical Co Ltd |
| Xiangshui Huasheng Chemical Co Ltd |
| Brother Enterprises Holding Co Ltd |
| Vishnu Chemicals Limited |
| Sigma-Aldrich Corporation |
| Foodchem International Corporation |
| Others |
Supply & Pricing Matrix
Specialized oxidation chemists concentrated in Jiangsu and Zhejiang provinces anchor menadione production economics, with labor-cost differentials between coastal China and inland chemical parks driving spreads between pharmaceutical-grade and feed-grade pricing tiers. This workforce concentration enables integrated producers to capture margin premiums through captive chromic acid handling capabilities that toll manufacturers cannot replicate.
Pricing Analysis
Margin tightening in feed-grade menadione reflects chromic acid feedstock volatility and EFSA compliance documentation burdens. Three-tier pricing structure across pharmaceutical-grade, feed-premium, and economy feed grades separates assay-validated output from standard 96-98% material. Price differentiation hinges on GB 1903.43 certification completeness and REACH registration status. Poultry integrators in Brazil and Vietnam exhibit highest price sensitivity, while Indian API manufacturers prioritize pharmacopeial compliance over unit cost.
Supply Chain Analysis
Chromic acid supply rests on Kazakhstan and South African chromium ore processing, with hexavalent chromium precursor availability constraining formulator output planning. Menadione synthesis draws from 2-methylnaphthalene naphtha derivatives and sulfur dioxide for bisulfite conversion. Single-source vulnerability in chromic acid exposes producers to raw material disruption. Distribution runs through multinational premix formulators consolidating procurement for Brazilian and Vietnamese poultry operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
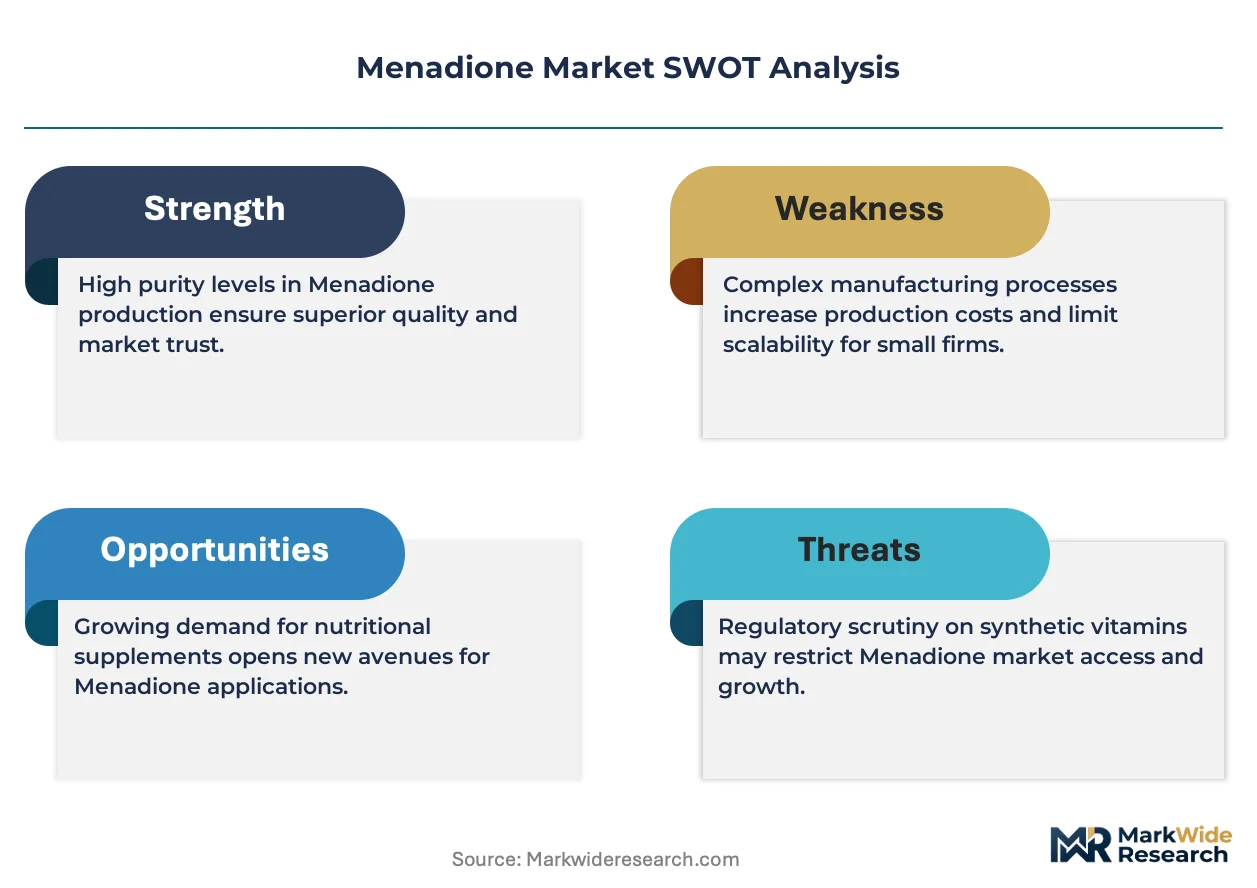
Menadione market participation functions as a cost-of-compliance story where SAMR's GB 1903.43 standard and EFSA feed additive reauthorization create regulatory moats favoring incumbent producers with established dossier capabilities.
For Market Incumbents: Deepen backward integration into chromic acid oxidation capacity to neutralize precursor supply volatility threatening margin stability. Secure multi-year premix supply agreements with DSM and Adisseo channel partners in Brazil and Vietnam. Prioritize continuous air-oxidation reactor deployment in Jiangsu chemical parks to displace legacy batch systems and capture cost-down advantages. For New Entrants and Emerging Players: Continuous flow oxidation technology offers a technology-first wedge against incumbent batch-process economics. Target Indian pharmaceutical-grade menadione diacetate production under PLI scheme incentives as the most penetrable white-space opportunity. Pursue FSSAI nutraceutical certification as the qualifying go-to-market pathway for domestic API manufacturer partnerships. For Investors and Strategic Acquirers: Re-rating potential sits with integrated Chinese synthesis houses possessing captive fermentation capacity and completed REACH dossiers given EFSA's tightened residue monitoring requirements. Long-term viability favors producers with demonstrated regulatory affairs functions spanning SAMR, EFSA, and FDA submission experience. Watch ANVISA's Codex Alimentarius harmonization timeline as the inflection signal for Brazilian aquaculture expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Oxidation Reactor Deployment | Jiangsu producers retrofit air-oxidation loops to cut solvent recovery costs and displace chromic acid batch vessels. |
| EFSA Dossier Completion | REACH registration for menadione sodium bisulfite opens EU feed compounder channels previously restricted to European material. |
| Granule Format Premix Integration | Dust-free bisulfite granules penetrate Brazilian and Mexican poultry operations seeking automated blending compatibility. |
| Backward Integration into Chromic Acid | Captive oxidation capacity insulates formulators from Kazakhstan and South African chromium ore supply volatility. |
| Indian PLI Scheme Alignment | FSSAI nutraceutical localization incentives attract pharmaceutical-grade menadione diacetate investment for injectable formulations. |
Research Methodology
Trade databases, chemical industry association publications, and regulatory filing repositories formed the secondary backbone, cross-referenced with primary interviews spanning plant managers at Jiangsu and Zhejiang synthesis facilities, procurement leads at Brazilian and Vietnamese poultry integrators, regulatory affairs directors navigating EFSA and SAMR submission pathways, and distribution channel partners in European feed compounder markets. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across the analysis window.
Bottom-up modeling anchored on installed oxidation reactor capacity, operating rates, and grade-specific yield assumptions, while top-down validation referenced animal feed production volumes and vitamin K3 inclusion rate norms. Segmentation dimensions spanned physical format, application protocol, purity grade tier, and regional regulatory cluster. CAGRs derived from trend extrapolation of livestock protein demand, premix manufacturer procurement patterns, and pharmaceutical API backward integration rates.
Several conditions sit outside the modeled scope, including potential phylloquinone substitution acceleration in pharmaceutical applications, unforeseen chromic acid supply disruptions from Kazakhstan or South Africa, and EFSA reauthorization delays extending inventory hesitation among Dutch and Danish premix manufacturers. Forecasts reflect documented assumptions regarding regulatory timeline adherence and feed additive inclusion rate stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Syringaldehyde Market
Chemicals
North America Construction Chemicals Market
Chemicals
US Methanol Market
Chemicals
Global Methylene Chloride Market
Chemicals
Global Calcium Hypochlorite Market
Chemicals
Stimulation Materials Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Myclobutanil Market
Chemicals
Schneider's Insect Medium Market
Chemicals
Middle East and Africa Methyl Acrylate Market
Chemicals
Aluminum Phosphide Market
Chemicals
Superplasticizer Market
Chemicals
Hypophosphorous Acid Market
Chemicals
Solder Flux Market
Chemicals
Hydroxyethyl Methyl Cellulose Market
Chemicals
Ferric Phosphate Market