
 Isopropanolamine Market | 2026-2036
Isopropanolamine Market Size, Share, and Industry Trends Forecast 2026-2036
Isopropanolamine Market Intelligence
Monoethanolamine is shifting toward partial displacement by isopropanolamine in glyphosate-salt formulations, as the secondary amine delivers superior solubility and lower aquatic toxicity profiles. Dow Chemical leverages backward integration into propylene oxide feedstock to control cost volatility across its amine portfolio. BASF sustains European manufacturing scale through dedicated alkoxylation trains at its Ludwigshafen complex. Huntsman Corporation anchors North American supply through its Conroe, Texas facility, which serves agricultural chemical blenders across the Corn Belt.
Isopropanolamine refers to the family of alkanolamines synthesized from propylene oxide and ammonia, existing as mono-, di-, and tri-isopropanolamine isomers with molecular weights ranging from 75 to 191 g/mol, functioning primarily as neutralizing agents, emulsifiers, and pH buffers in industrial formulations. Liquid Isopropanolamine dominates volume shipments due to ease of handling in automated dosing systems, though Solid Isopropanolamine commands premium pricing from pharmaceutical customers requiring precise stoichiometric control. Cleaning Agents represents the most mature application segment with stable replacement demand, while Agricultural Chemicals generates the fastest growth as salt-formulation patents expire and generic herbicide producers seek cost-optimized amine alternatives.
EPA registration requirements under FIFRA govern isopropanolamine use in pesticide formulations, mandating specific impurity thresholds that filter out non-specialty suppliers. REACH compliance in Europe, administered by ECHA, imposes full substance dossiers on importers above one-tonne annual volumes, raising fixed compliance costs for smaller traders. China's MEE enforces dual carbon goals that pressure coal-based propylene oxide producers to adopt cleaner hydrogen peroxide-to-propylene oxide routes. Stakeholders must monitor feedstock propylene oxide capacity expansions in Asia and regulatory divergence on amine classification between EPA and ECHA frameworks.
Market Dynamics
Propylene oxide feedstock concentration in Asia is compressing margin structures for Western isopropanolamine manufacturers while accelerating localization of agricultural chemical formulation supply chains. Chinese hydrogen peroxide-to-propylene oxide capacity expansions are resetting regional cost baselines.
Growth Catalysts
- EPA FIFRA Registration Thresholds:Impurity mandates for pesticide-grade amines are filtering out commodity suppliers and consolidating demand among specialty-certified producers in the United States.
- Glyphosate Salt Patent Expirations:Generic herbicide manufacturers are substituting monoethanolamine with isopropanolamine to achieve superior aquatic toxicity profiles and solubility performance.
- China's Dual Carbon Goals:MEE enforcement is pressuring coal-based propylene oxide plants toward cleaner HPPO routes, improving feedstock sustainability credentials for downstream amine derivatives.
Market Restraints
- Propylene Oxide Volatility:Feedstock price swings tied to Asian petrochemical cycles compress formulation margins for agricultural chemical blenders.
- REACH Compliance Burden:ECHA substance dossier requirements above one-tonne volumes raise fixed costs that disadvantage smaller European traders and importers.
- Ethanolamine Substitution:Established monoethanolamine and diethanolamine supply chains in mature cleaning applications resist displacement despite isopropanolamine's technical advantages.
Strategic Opportunities
- Pharmaceutical Solid Grades:Precise stoichiometric control requirements in drug synthesis command premium pricing for crystalline isopropanolamine formats.
- EU Green Deal Alignment:Bio-based propylene oxide pilot programs create regulatory tailwinds for low-carbon amine derivatives in European personal care formulations.
- Automated Dosing Systems:Liquid isopropanolamine compatibility with precision agriculture equipment opens channel innovation in Brazil and Argentina farming cooperatives.
Industry Challenges
- Alkoxylation Train Certification:Multi-year validation timelines for pharmaceutical-grade production lines delay capacity monetization for new market entrants.
- Cross-Regulatory Divergence:EPA and ECHA classification inconsistencies on amine hazard categories complicate global formulation registrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isopropanolamine Market |
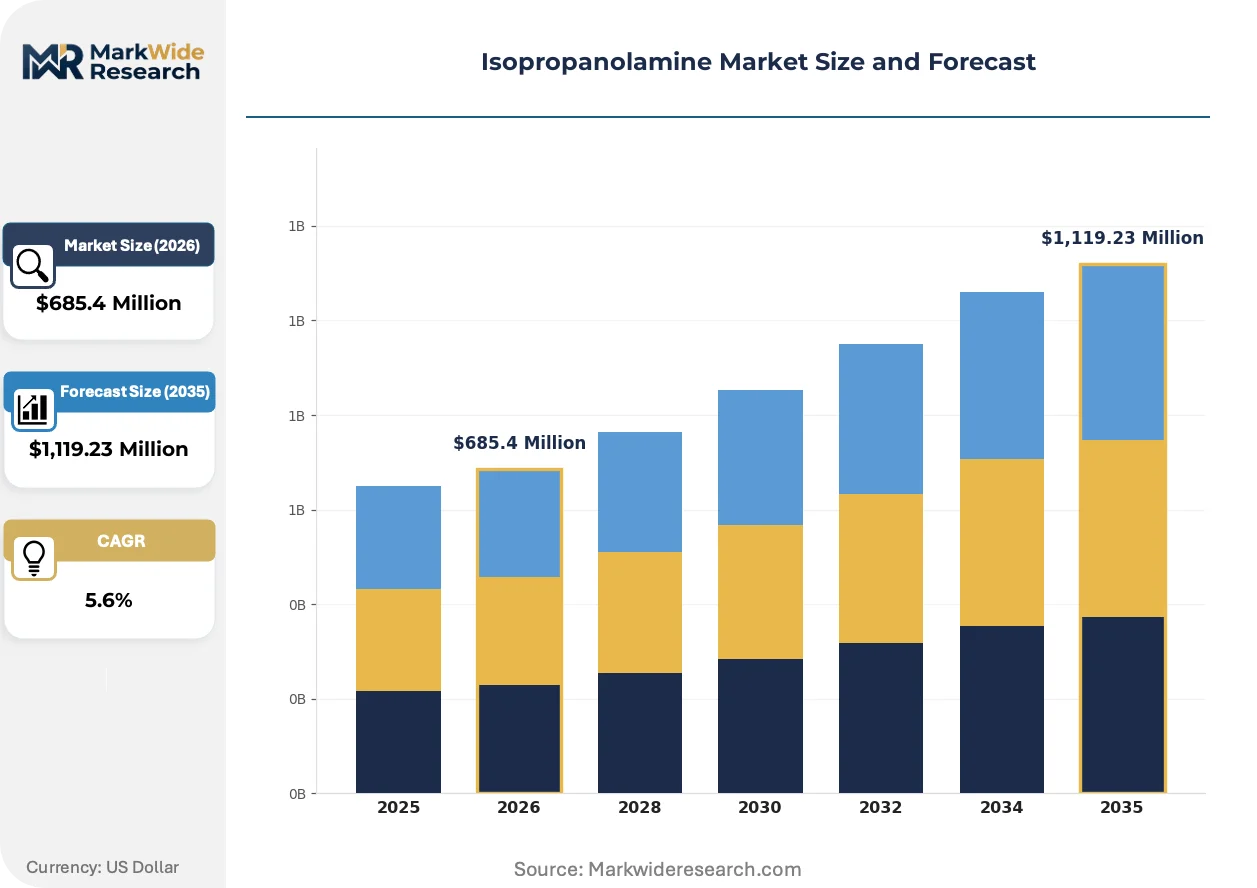
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,119.23 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Isopropanolamine, Solid Isopropanolamine, Aqueous Solutions, Blends Application: Cleaning Agents, Agricultural Chemicals, Personal Care Products, Disinfectants End User: Pharmaceuticals, Agriculture, Cosmetics, Industrial Cleaning Distribution Channel: Online Sales, Direct Sales, Distributors, Retail |
| Companies Covered | Dow Chemical, BASF, Huntsman Corporation, AkzoNobel, Hongbaoli Group, Neo Chemical, Siddhi Chem, Nanjing HBL, China National Bluestar Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isopropanolamine Market Strategic Shifts & Innovations
Continuous processing technology is replacing batch alkoxylation in amine manufacturing, compressing cycle times and tightening impurity control. This shift is redrawing competitive positioning between integrated petrochemical majors and standalone specialty amine producers.
Membrane separation technology for isopropanolamine purification is integrating into new production facilities, enabling single-digit ppm water specifications required by pharmaceutical customers. Agricultural chemical blenders in the US Corn Belt are adopting these higher-purity grades to preempt EPA registration rejections. The technology is integrating quality assurance directly into continuous flow architectures, collapsing the traditional gap between production and certification testing.
REACH registration requirements under ECHA oversight are tightening substance dossier standards for surfactant-grade amines entering European Union markets. Full toxicological profiling now extends to trace impurity metabolites, extending compliance timelines for non-integrated importers. Specialty manufacturers with captive analytical capabilities are capturing formulation business from traders lacking in-house regulatory affairs functions.
Long-term supply agreements are displacing spot purchasing for agricultural chemical formulators seeking price predictability amid propylene oxide volatility. Major herbicide producers in China are locking three-to-five-year offtake contracts with domestic isopropanolamine plants. This pattern is most visible in Shandong and Jiangsu provinces, where integrated agrochemical clusters are internalizing amine supply to match backward-integrated Western competitors.
Isopropanolamine Market Segmentation
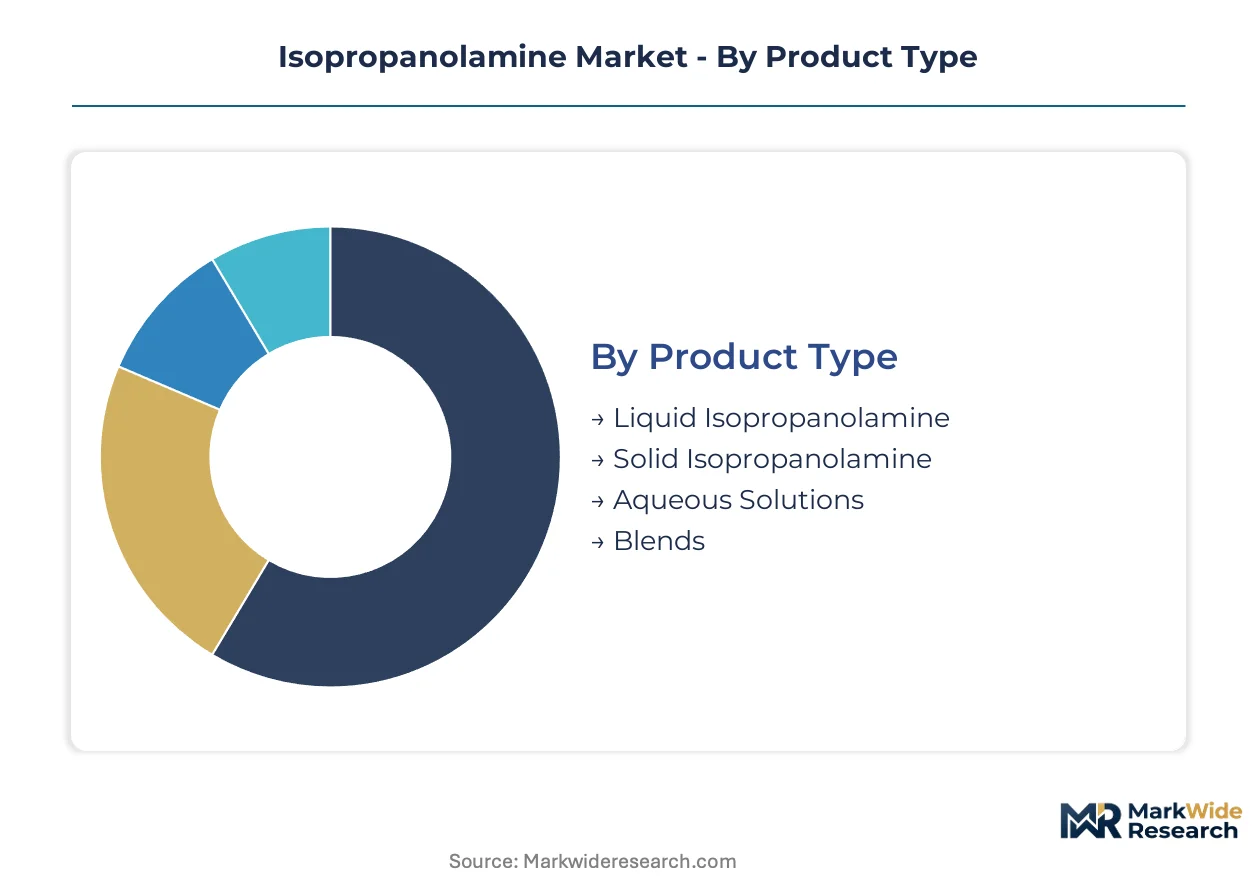
Isopropanolamine procurement patterns diverge sharply across product formats and end-use certifications. EPA FIFRA registration requirements for agricultural applications create tiered compliance burdens that reshape segment economics and supplier selection criteria.
Product Type:
Certification intensity varies by physical state: liquid grades face routine surfactant testing, while solid formats trigger pharmaceutical-grade validation protocols including USP monograph compliance and ICH Q3D elemental impurity screening.
- Liquid Isopropanolamine:Dominates volume shipments through automated dosing compatibility in agricultural chemical blending operations. Demand concentrates among glyphosate-salt formulators across the US Corn Belt and Shandong Province agrochemical clusters, driven by solubility advantages over monoethanolamine alternatives.
- Solid Isopropanolamine:Crystalline format with precise stoichiometric control for pharmaceutical synthesis and laboratory reagent applications. Procurement centers on FDA-registered API manufacturers and contract research organizations requiring USP-grade documentation, constrained by multi-year alkoxylation train certification timelines.
- Aqueous Solutions:Pre-diluted concentrates for industrial cleaning compounders seeking handling efficiency.
- Blends:Custom isomer ratios tailored to specific pH buffering requirements in personal care formulations.
Leading the category by volume: Liquid Isopropanolamine. Growing fastest: Solid Isopropanolamine.
Application:
Margin structures align with regulatory exposure: agricultural chemicals carry EPA registration overhead, while cleaning agents operate under lighter OSHA hazard communication standards.
- Agricultural Chemicals:Herbicide salt formulations represent the steepest expansion trajectory as generic glyphosate patents expire and formulators substitute isopropanolamine for ethanolamines to achieve superior aquatic toxicity profiles. Procurement is concentrating in China, where domestic manufacturers displace imported ethanolamines with local isopropanolamine derivatives.
- Cleaning Agents:Mature segment with stable replacement demand from institutional and industrial maintenance operations. Volume concentrates in North American and European facility management supply chains, constrained by established monoethanolamine infrastructure that resists displacement despite technical advantages.
- Personal Care Products:pH buffering in hair and skin formulations, subject to EU Cosmetics Regulation (EC) No 1223/2009 safety assessments.
- Disinfectants:Neutralizing agent for quaternary ammonium compound formulations in healthcare surface sanitation.
Highest margin capture: Agricultural Chemicals. Most price-sensitive: Cleaning Agents.
End User:
Customer scale determines contract structure: pharmaceutical buyers negotiate multi-year quality agreements, while industrial cleaning purchasers rely on spot markets.
- Pharmaceuticals:Solid-grade isopropanolamine for active pharmaceutical ingredient synthesis and excipient applications. Procurement centers on FDA-registered manufacturers requiring complete impurity profiling and ICH Q7 GMP compliance, commanding premium pricing for crystalline formats with single-digit ppm water specifications.
- Agriculture:Herbicide formulators and generic crop protection producers seeking cost-optimized amine alternatives. Demand clusters in Brazil, Argentina, and the US Midwest farming cooperatives adopting precision agriculture equipment compatible with liquid dosing systems.
- Cosmetics:Personal care compounders sourcing surfactant-grade material for pH adjustment in rinse-off products.
- Industrial Cleaning:Maintenance chemical blenders serving manufacturing facilities and transportation fleets.
Most stringent specification requirements: Pharmaceuticals. Fastest contract renewal cycles: Agriculture.
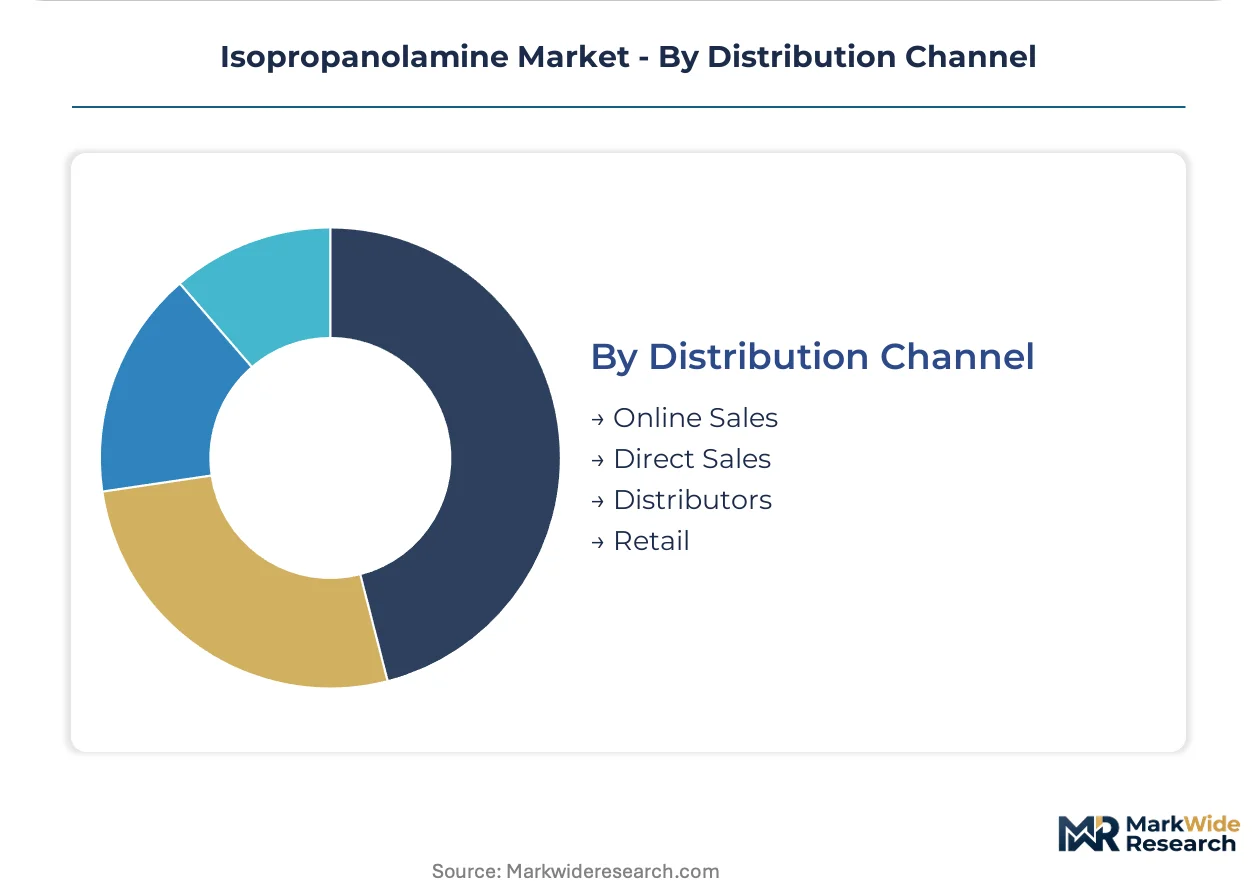
Distribution Channel:
Channel selection reflects purchase scale and technical support needs: bulk agricultural buyers bypass intermediaries, while fragmented personal care formulators depend on distributor technical service.
- Direct Sales:Long-term offtake agreements between isopropanolamine producers and agricultural chemical manufacturers. Three-to-five-year contracts are displacing spot purchasing among major herbicide producers in China seeking price predictability amid propylene oxide volatility.
- Distributors:Technical service intermediaries serving mid-size cleaning compounders and personal care formulators requiring formulation support and smaller lot sizes.
- Online Sales:Laboratory-scale quantities for research institutions and specialty chemical traders.
- Retail:Consumer-packaged cleaning products containing isopropanolamine derivatives.
Dominant by contract value: Direct Sales. Expanding service intensity: Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese agrochemical manufacturers account for the steepest demand acceleration as domestic formulators substitute imported ethanolamines with locally produced isopropanolamine derivatives. Procurement concentration clusters in Shandong and Jiangsu provinces, where integrated herbicide production complexes internalize amine supply chains.
United States
Glyphosate-salt formulators across the Corn Belt drive agricultural chemical demand, seeking EPA FIFRA-compliant amine grades for generic herbicide production. The EPA mandates specific impurity thresholds that filter out non-specialty suppliers, consolidating procurement among certified producers. Huntsman Corporation anchors North American supply through its Conroe, Texas facility serving regional agricultural chemical blenders.
China
Domestic manufacturers displace imported ethanolamines with local isopropanolamine derivatives as generic herbicide patents expire. The MEE enforces dual carbon goals pressuring coal-based propylene oxide plants toward cleaner HPPO routes. Shandong and Jiangsu provinces host three-to-five-year offtake contracts between major herbicide producers and domestic amine plants.
Germany
BASF sustains European manufacturing scale through dedicated alkoxylation trains at its Ludwigshafen complex, serving personal care and agricultural formulations. REACH compliance administered by ECHA imposes full substance dossiers on importers above one-tonne annual volumes. The Ludwigshafen industrial cluster represents the continent's most integrated amine production hub.
Brazil
Farming cooperatives adopt precision agriculture equipment compatible with liquid isopropanolamine dosing systems for herbicide application. ANVISA registration requirements parallel EPA frameworks for pesticide-grade amine imports. São Paulo state anchors formulation demand as Brazilian agribusiness expands generic crop protection manufacturing.
India
Institutional cleaning compounders source surfactant-grade material for industrial maintenance operations across manufacturing corridors. BIS quality standards govern technical-grade amine specifications for domestic chemical blenders. Gujarat and Maharashtra industrial clusters concentrate import-dependent supply chains serving regional formulators.
Isopropanolamine Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical majors commanding agricultural chemical volumes while standalone producers serve pharmaceutical and personal care niches. Market structure tilts toward consolidation among propylene oxide-integrated players capable of absorbing feedstock volatility. Three archetypes dominate: backward-integrated chemical majors with captive feedstock, regional specialists with alkoxylation train certifications, and import-dependent traders serving fragmented cleaning segments. Competitive moves center on long-term offtake contracting and alkoxylation capacity expansion.
Among North American integrated producers, Dow Chemical and Huntsman Corporation exemplify the backward-integrated archetype with upstream control over propylene oxide feedstock. BASF represents the European specialist model with dedicated production infrastructure at Ludwigshafen. Hongbaoli Group anchors Chinese domestic supply as regional formulators localize procurement. These three occupy positions across distinct geographic demand centers rather than competing directly for shared accounts.
| Leading Market Players |
|---|
| Dow Chemical |
| BASF |
| Huntsman Corporation |
| AkzoNobel |
| Hongbaoli Group |
| Neo Chemical |
| Siddhi Chem |
| Nanjing HBL |
| China National Bluestar Group |
| Others |
Cost & Logistics Intelligence
Propylene oxide price indices cascading from Asian petrochemical benchmarks compress margin structures for Western isopropanolamine manufacturers while amplifying pricing power for integrated Chinese producers. This feedstock volatility propagates through three distinct pricing tiers—pharmaceutical solid grades, agricultural chemical liquid grades, and industrial cleaning aqueous solutions—each tethered to different certification burdens and volume scales.
Pricing Analysis
Volume shipments of liquid agricultural grades trade at compressed margins against premium-capture solid pharmaceutical formats. Pricing stratifies across EPA FIFRA-certified, REACH-registered, and technical industrial tiers, with certification level and volume scale as the primary differentiation drivers. Cost compression in agricultural chemical segments is intensifying because Chinese domestic producers are undercutting import parity. Industrial cleaning compounders exhibit the highest price sensitivity due to established monoethanolamine substitution alternatives, while pharmaceutical API manufacturers show minimal elasticity given USP monograph compliance requirements.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Shanghai anchor hub-and-spoke patterns for liquid isopropanolamine shipments to agricultural chemical blenders. Manufacturing concentrates in China, the United States, and Germany, with feedstock propylene oxide sourcing from hydrogen peroxide-to-propylene oxide routes in Shandong Province and traditional chlorohydrin processes along the US Gulf Coast. Single-source vulnerability looms over pharmaceutical-grade supply chains due to multi-year alkoxylation train certification timelines that constrain qualified supplier pools. Distribution runs through direct sales channels for bulk agricultural offtake and technical service distributors for fragmented personal care formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The isopropanolamine market functions as a cost-of-compliance arena where EPA FIFRA registration thresholds erect formidable barrier-to-entry moats. Only specialty-certified producers capable of absorbing multi-year validation timelines and captive analytical capabilities capture sustainable formulation business.
For Market Incumbents: Hedge against propylene oxide volatility through backward integration into feedstock or long-term offtake contracting with HPPO-route Chinese suppliers. Capacity addition in Shandong Province agrochemical clusters defends position against emerging domestic Chinese competitors. Certification investment in pharmaceutical-grade alkoxylation trains captures premium pricing from FDA-registered API manufacturers.
For New Entrants and Emerging Players: E-commerce channels for laboratory-scale solid isopropanolamine offer the most penetrable entry vector. Target contract research organizations and mid-size pharmaceutical developers in India and Southeast Asia seeking USP-grade documentation without minimum order constraints. A technical service-heavy distributor partnership model bypasses direct competition with integrated majors in agricultural chemical volumes.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with alkoxylation train certifications in European personal care corridors. Long-term viability hinges on exposure to agricultural chemical demand in Brazil and Argentina farming cooperatives adopting precision dosing equipment. Watch HPPO capacity expansion announcements in China as the inflection signal for feedstock cost competitiveness shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Dow Chemical's captive feedstock control insulates margin structures from Asian petrochemical cycles. |
| Pharmaceutical-Grade Alkoxylation Certification | BASF's Ludwigshafen trains command premium pricing through USP monograph compliance capabilities. |
| Long-Term Supply Agreement | Chinese herbicide producers in Shandong Province lock three-to-five-year offtake contracts for price predictability. |
| HPPO Route Transition | MEE dual carbon enforcement pressures coal-based propylene oxide plants toward cleaner hydrogen peroxide processes. |
| Precision Agriculture Channel Development | Liquid isopropanolamine compatibility with automated dosing systems opens Brazilian farming cooperative procurement. |
Research Approach
Independent corroboration across plant managers at alkoxylation facilities, procurement leads at agricultural chemical blenders, and distribution channel partners underwrites the qualitative findings. Primary interviews with technical R&D directors at specialty amine producers and regulatory affairs specialists navigating EPA FIFRA submissions combined with secondary validation from customs/trade data, ACC/Cefic chemical industry reports, and SEC 10-K filings for integrated petrochemical majors. Bottom-up segmentation modeling and top-down macroeconomic anchoring triangulate volume and value estimates.
Rate-of-change decomposition separates feedstock propylene oxide price movements from value-added processing margins across the analysis window. Segmentation dimensions include physical state (liquid, solid, aqueous), application certification tier (EPA FIFRA, REACH-registered, technical), and regional production hub concentration. CAGRs derive from elasticity-adjusted demand projections and capacity expansion pipelines. Industry-specific forecast inputs incorporate glyphosate salt formulation patent expiration schedules and MEE enforcement intensity on dual carbon goals.
The model holds under stable regulatory enforcement intensity and continued HPPO capacity commissioning in China; deviation in EPA-ECHA classification harmonization or propylene oxide supply disruptions would shift trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Phosphorus Trichloride Market
Chemicals
Calcium Methoxide Market
Chemicals
North America Ethylene Dichloride (EDC) Market
Chemicals
Aluminium Chloride Market
Chemicals
Global Syringaldehyde Market
Chemicals
Schneider's Insect Medium Market
Chemicals
6 Hexanediol Market
Chemicals
Cummene Derivatives Market
Chemicals
RO Membrane Chemicals Market
Chemicals
Saudi Arabia Construction Chemicals Market
Chemicals
Resorcinol Market
Chemicals
Fluorine Derivatives Market
Chemicals
Canada Methanol Market
Chemicals
Naturally Derived Fatty Alcohol Market
Chemicals
Amine Oxide Market
Chemicals
Middle East and Africa Methyl Acrylate Market