
 Trichlorosilane Market | 2026-2036
Trichlorosilane Market Size, Share, and Industry Trends Forecast 2026-2036
Trichlorosilane Market Intelligence
The trichlorosilane market is pivoting on a widening split between semiconductor-grade purity specifications and commodity technical-grade volumes. Hemlock Semiconductor Operations leverages captive chlorosilane production to sustain polysilicon cost leadership in Michigan. Wacker Chemie AG anchors European supply through integrated silane chemistry at its Burghausen complex. Shin-Etsu Chemical dominates ultra-high-purity segments for epitaxial silicon wafers.
Trichlorosilane is a chlorinated silicon compound with the formula SiHCl3, produced via the reaction of metallurgical-grade silicon with hydrogen chloride at elevated temperatures; it serves as the principal precursor for high-purity polysilicon used in photovoltaic cells and semiconductor devices. Semiconductor grade commands premium pricing due to parts-per-billion impurity thresholds, while solar cell applications drive volume absorption across technical and reagent grades. Specialty grade segments occupy narrow but high-margin niches in advanced coatings and silicon carbide precursor markets.
China's MEE enforces emissions caps on chlorosilane facilities under dual carbon mandates, while REACH in Europe governs chemical registration and downstream use restrictions. The EPA in the United States monitors hazardous air pollutant thresholds for chlorosilane manufacturing under the Clean Air Act. Stakeholders must monitor evolving purity certifications and carbon-border adjustment mechanisms to secure long-term offtake agreements.
Market Dynamics
The trichlorosilane market is bifurcating around purity-grade stratification, with semiconductor-grade specifications tightening under China's GB standards while solar-grade volumes absorb technical-grade output from Xinjiang's integrated polysilicon complexes.
Growth Catalysts
- Dual carbon mandates:China's MEE emissions caps are accelerating facility upgrades toward closed-loop chlorosilane recovery, tightening supply discipline and favoring scaled producers with carbon capture integration.
- Photovoltaic deployment:Polysilicon ingot pulling for PERC and TOPCon cell architectures is absorbing technical-grade trichlorosilane at volumes that sustain reactor utilization across East Asian manufacturing clusters.
- Silicon carbide precursor demand:Wide-bandgap semiconductor fabrication is opening specialty-grade niches for ultra-low-boron trichlorosilane in chemical vapor deposition of SiC epitaxial layers.
Market Restraints
- Hydrochloric acid cost volatility:Metallurgical-grade silicon chlorination depends on HCl feedstock pricing tied to chlor-alkali co-production economics, creating margin compression during energy price spikes.
- Xinjiang supply concentration:Four integrated producers control over two-thirds of China's technical-grade output, concentrating disruption risk from logistics bottlenecks or regional regulatory enforcement.
- Siemens process substitution:Fluidized bed reactor technology using silane is displacing trichlorosilane-based polysilicon deposition in select new capacity, threatening long-term volume absorption.
Strategic Opportunities
- Indian polysilicon incubation:The country's PLI scheme for solar module manufacturing is attracting trichlorosilane import demand as domestic ingot pulling capacity scales under CEA grid-interconnection mandates.
- Semiconductor reshoring incentives:The US IRA advanced manufacturing tax credits are stimulating polysilicon purification investments that require semiconductor-grade chlorosilane supply security.
- Digital twin integration:AI-driven distillation optimization is converging with IoT sensor networks to yield real-time purity monitoring that reduces off-spec batches and reprocessing costs.
Industry Challenges
- High-purity distillation expertise:Fractional distillation to parts-per-billion boron and phosphorus specifications requires process engineers with specialized chlorosilane handling experience that remains scarce outside established East Asian clusters.
- Multi-grade certification timelines:Qualification for SEMI standard semiconductor-grade supply takes 18-24 months of customer-specific validation, locking working capital in inventory before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trichlorosilane Market |
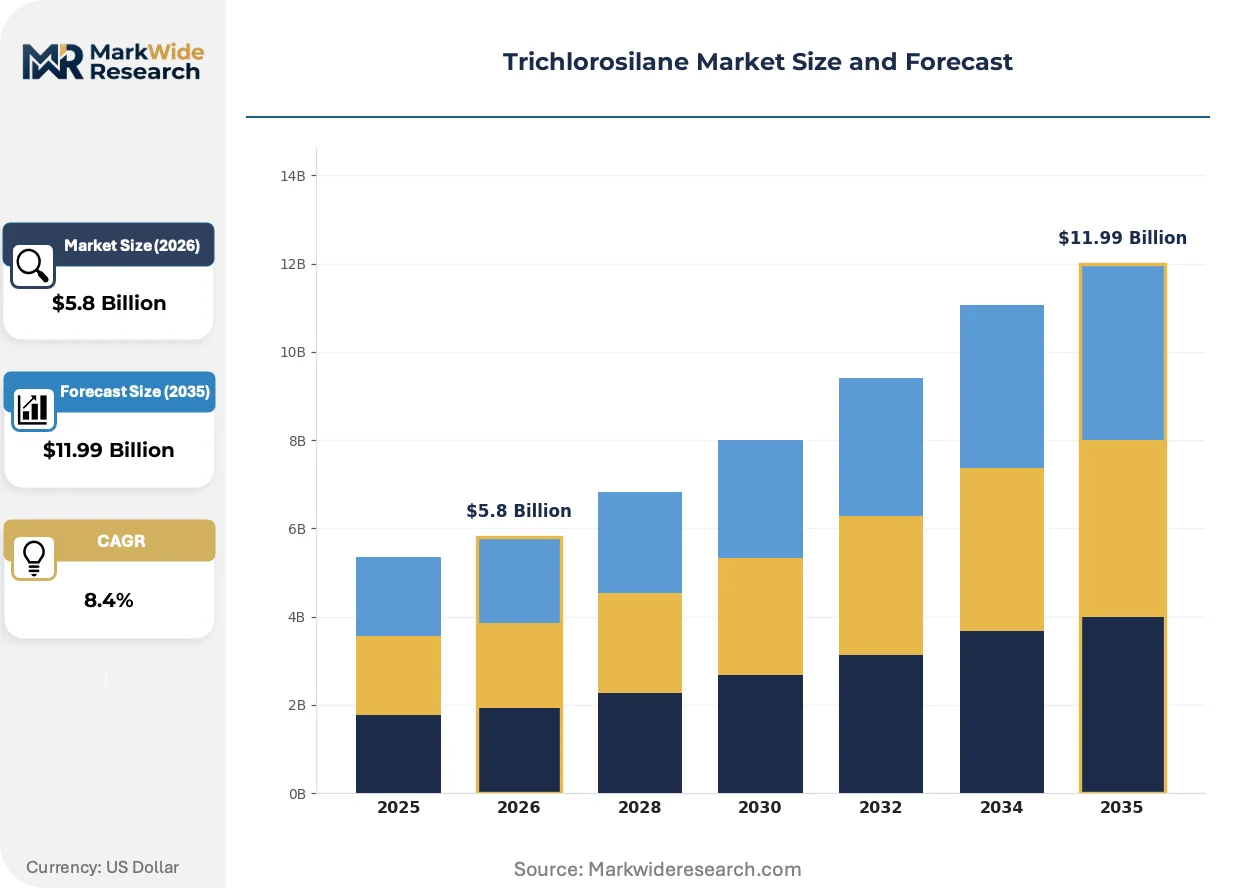
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagent Grade, Technical Grade, Semiconductor Grade, Specialty Grade Application: Solar Cells, Semiconductor Manufacturing, Coatings, Silicones End User: Electronics, Chemical Industry, Energy Sector, Automotive Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail Stores |
| Companies Covered | Hemlock Semiconductor Operations, Evonik Industries, Wacker Chemie AG, REC Silicon, Shin-Etsu Chemical, GCL-Poly Energy Holdings, Tokuyama Corporation, Linde, OCI Company Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trichlorosilane Market Strategic Shifts & Innovations
Trichlorosilane production technology is fragmenting into modular, purity-optimized configurations that separate semiconductor and solar supply chains, while regulatory carbon accounting and buyer consolidation reshape competitive requirements.
Advanced distillation skids with integrated online mass spectrometry are modularizing quality control into discrete processing stages. Polysilicon producers in Jiangsu and Sichuan are adopting these units to bypass centralized analytical bottlenecks. This modularizing architecture compresses batch release cycles from days to hours, enabling just-in-time delivery contracts with wafer manufacturers.
REACH registration requirements for chlorosilane downstream uses are tightening substance volume tracking across European polysilicon importers. ECHA's 2023 updated guidance on intermediates classification is forcing re-evaluation of toll manufacturing arrangements. German and Norwegian solar-grade buyers are responding by demanding full supply chain substance flow documentation from Asian suppliers.
Long-term offtake contracting is displacing spot market transactions as the dominant procurement mechanism for semiconductor-grade volumes. Tier-one wafer manufacturers in Japan and South Korea are locking five-year supply agreements with fixed purity escalation clauses. This concentration is most visible in Shin-Etsu's supply base, where three buyers now contract over half of ultra-high-purity Japanese output.
Trichlorosilane Market Segmentation
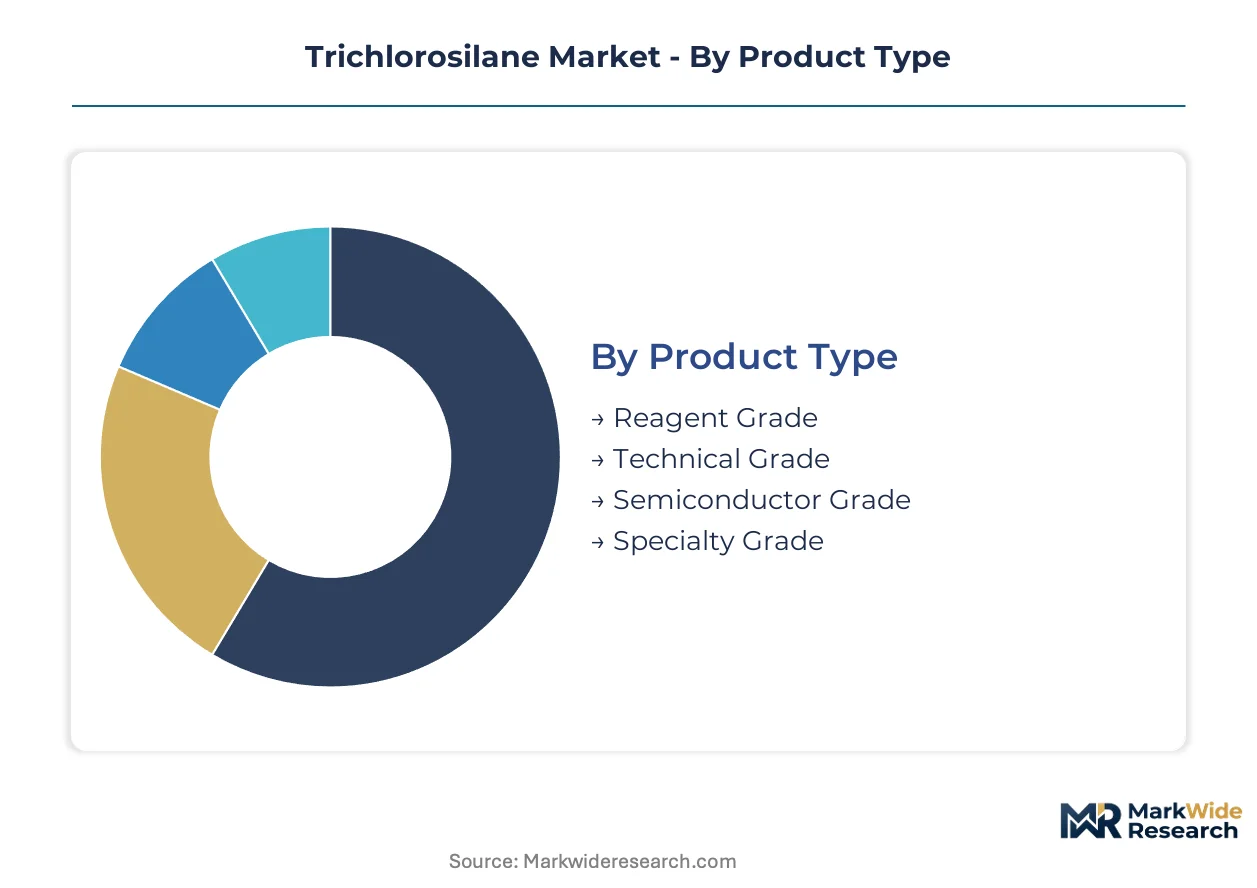
Trichlorosilane purity grades command radically different pricing architectures and qualification timelines, while application splits reveal diverging growth trajectories between photovoltaic volume absorption and semiconductor premium capture. Segment boundaries are hardening as solar-grade producers pursue commodity scale and electronics-grade suppliers defend certification moats.
Product Type:
Integration depth varies sharply across grades, with semiconductor and specialty grades embedding directly into customer specification systems while technical and reagent grades flow through standardized procurement channels.
- Semiconductor Grade:Parts-per-billion purity thresholds for boron and phosphorus define this segment, requiring fractional distillation trains with online mass spectrometry validation. Demand concentrates in Japanese and South Korean wafer manufacturers under long-term offtake agreements with fixed purity escalation clauses. China's GB standards tightening is extending qualification timelines to 18-24 months.
- Technical Grade:Solar photovoltaic polysilicon production absorbs the bulk of technical-grade volumes through Siemens process deposition. Xinjiang and Jiangsu province clusters in China consume the majority of output, with four integrated producers controlling over two-thirds of domestic supply. MEE emissions caps are accelerating facility upgrades toward closed-loop chlorosilane recovery.
- Reagent Grade:Laboratory and analytical applications drive smaller-batch procurement with less stringent purity requirements than semiconductor specifications.
- Specialty Grade:Ultra-low-boron formulations serve silicon carbide chemical vapor deposition for wide-bandgap semiconductor fabrication.
Volume placements concentrate in Technical Grade; the faster expansion belongs to Semiconductor Grade.
Application:
Cost tier stratification separates high-volume solar deposition from premium semiconductor epitaxy, with coatings and silicones occupying intermediate value positions.
- Solar Cells:Polysilicon ingot pulling for PERC and TOPCon architectures absorbs technical-grade trichlorosilane at scales that sustain reactor utilization across East Asian manufacturing bases. India's PLI scheme for solar module manufacturing is attracting import demand as domestic ingot capacity scales.
- Semiconductor Manufacturing:Epitaxial silicon wafer fabrication requires ultra-high-purity chlorosilane with documented impurity pedigrees. US IRA advanced manufacturing tax credits are stimulating domestic polysilicon purification investments that require supply security guarantees.
- Coatings:Advanced surface treatment applications utilize specialty-grade formulations for chemical vapor deposition processes.
- Silicones:Intermediate chemical synthesis consumes reagent-grade volumes for silicone polymer production.
Cost absorption runs deepest in Solar Cells; margin capture peaks in Semiconductor Manufacturing.
End User:
Customer type concentration shapes contracting structures, with electronics buyers demanding specification lock-in and energy sector purchasers prioritizing volume flexibility.
- Electronics:Tier-one wafer manufacturers in Japan and South Korea dominate semiconductor-grade offtake through five-year supply agreements. Three buyers now contract over half of ultra-high-purity Japanese output.
- Energy Sector:Solar photovoltaic developers and polysilicon producers drive technical-grade procurement through spot and short-term contracts.
- Chemical Industry:Silicone and chlorosilane derivative manufacturers source reagent and technical grades for downstream synthesis.
- Automotive:Silicon carbide power electronics for electric vehicle inverters is emerging as a demand source for ultra-low-boron specialty grades.
Contract duration extends furthest in Electronics; procurement flexibility matters most in Energy Sector.
Distribution Channel:
Supply concentration determines channel selection, with direct relationships dominating high-purity segments and intermediaries handling commodity flows.
- Direct Sales:Semiconductor-grade volumes move through bilateral negotiations with integrated polysilicon producers and wafer manufacturers.
- Distributors:Technical and reagent grades flow through chemical distribution networks serving fragmented solar and silicone customer bases.
- Online Platforms:Small-batch reagent-grade procurement is migrating to digital channels for laboratory and research customers.
- Retail Stores:Minimal penetration limited to consumer-facing silicone sealant and coating applications.
Relationship intensity peaks in Direct Sales; transaction velocity runs highest in Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xinjiang's integrated polysilicon corridor commands the largest technical-grade trichlorosilane absorption capacity globally, with four producers consolidating over two-thirds of China's domestic output under tightening MEE emissions enforcement.
China
Jiangsu and Sichuan province clusters are deploying modular distillation skids with online mass spectrometry to compress batch release cycles. GB standards tightening under SAMR supervision is extending semiconductor-grade qualification timelines to 18-24 months. Xinjiang's four integrated producers dominate technical-grade supply, concentrating disruption risk from regional logistics or regulatory enforcement actions.
United States
Advanced manufacturing tax credits under the IRA are stimulating polysilicon purification investments requiring semiconductor-grade chlorosilane supply security. EPA hazardous air pollutant monitoring under the Clean Air Act shapes facility compliance costs. Michigan-based captive chlorosilane production sustains cost leadership in polysilicon deposition for domestic wafer manufacturing.
Germany
Burghausen complex operations anchor European supply through integrated silane chemistry serving wafer manufacturers. REACH registration requirements and ECHA's 2023 updated intermediates classification are forcing re-evaluation of toll manufacturing arrangements. German solar-grade buyers are demanding full supply chain substance flow documentation from Asian suppliers under CSRD-aligned carbon accounting.
Japan
Tier-one wafer manufacturers under METI industrial policy guidance dominate ultra-high-purity semiconductor-grade offtake through five-year supply agreements with fixed purity escalation clauses. Three buyers now contract over half of domestic ultra-high-purity output. Nagoya and Kyushu manufacturing clusters concentrate epitaxial silicon wafer fabrication requiring documented impurity pedigrees.
India
The PLI scheme for solar module manufacturing is attracting trichlorosilane import demand as domestic ingot pulling capacity scales under CEA grid-interconnection mandates. Maharashtra and Gujarat industrial corridors are incubating polysilicon purification investments. BIS certification requirements for imported chlorosilane are tightening quality documentation standards for technical-grade procurement.
Trichlorosilane Market Key Industry Players
Premium-margin players sit above commodity-margin players across purity-grade stratification, with semiconductor-grade specifications commanding 18-24 month qualification timelines that lock working capital before revenue recognition. The vendor base organizes into three archetypes: integrated polysilicon producers with captive chlorosilane supply, standalone specialty chemical manufacturers serving electronics-grade demand, and diversified industrial gas suppliers leveraging distribution infrastructure. Capacity expansion and backward integration into metallurgical-grade silicon chlorination represent the dominant competitive moves, with carbon capture integration emerging as a compliance differentiator under tightening emissions regimes.
Among German chemical conglomerates, Wacker Chemie AG exemplifies integrated silane chemistry positioning, while Evonik Industries occupies a specialty-grade tier serving narrow high-margin niches. Japanese materials specialists Shin-Etsu Chemical and Tokuyama Corporation anchor ultra-high-purity supply for epitaxial wafer fabrication, representing the premium-tier archetype with long-term offtake lock-in. Hemlock Semiconductor Operations demonstrates captive chlorosilane production economics, while REC Silicon and OCI Company Ltd. illustrate diversified positioning across solar and electronics-grade segments. GCL-Poly Energy Holdings represents scale-driven technical-grade concentration within China's Xinjiang corridor.
| Leading Market Players |
|---|
| Hemlock Semiconductor Operations |
| Evonik Industries |
| Wacker Chemie AG |
| REC Silicon |
| Shin-Etsu Chemical |
| GCL-Poly Energy Holdings |
| Tokuyama Corporation |
| Linde |
| OCI Company Ltd. |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracting by Japanese and South Korean wafer manufacturers is compressing spot market liquidity and forcing technical-grade suppliers toward fixed-escalation agreements that lock in margin structures years ahead of delivery.
Pricing Analysis
Yield-guaranteed pricing for semiconductor-grade trichlorosilane anchors value capture at the wafer-fabrication outcome, with purity-escalation clauses indexing contract values to boron and phosphorus threshold achievements. Three-tier pricing structure across semiconductor, technical, and reagent grades reflects 18-24 month qualification timelines versus commodity spot availability. Cost compression in technical-grade volumes is intensifying because Xinjiang's four integrated producers leverage captive chlorosilane supply to undercut standalone merchants. Solar polysilicon buyers exhibit acute price sensitivity; epitaxial wafer manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
GB standards tightening under SAMR supervision is gating supply chain access for semiconductor-grade qualification, extending certification timelines and concentrating viable sources among established East Asian producers. Manufacturing concentrates in China, Japan, and Germany, with Xinjiang and Jiangsu province clusters absorbing technical-grade volumes and Burghausen and Nagoya anchoring ultra-high-purity output. Feedstock draws from metallurgical-grade silicon chlorination and hydrogen chloride supply tied to chlor-alkali economics. Single-source vulnerability runs through Xinjiang's logistics corridors under MEE emissions enforcement. Distribution runs through direct bilateral negotiations for semiconductor grades and chemical distribution networks for technical volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Emissions-capped operating permits under China's dual carbon mandates are squeezing sub-scale chlorosilane facilities, consolidating viable supply among carbon-integrated producers with closed-loop recovery systems.
For Market Incumbents: Anchor semiconductor-grade supply security through five-year offtake lock-in with tier-one wafer manufacturers, while accelerating backward integration into metallurgical-grade silicon chlorination to insulate margins from HCl feedstock volatility. Fluidized bed reactor substitution using silane threatens long-term technical-grade absorption; defend position by modularizing distillation skids with online mass spectrometry to compress batch release cycles below competitor turnaround times. For New Entrants and Emerging Players: The IRA advanced manufacturing tax credits in the United States open a window for polysilicon purification investments requiring semiconductor-grade chlorosilane supply partnerships. Target India's PLI-scheme solar module corridor as technical-grade import demand scales under CEA grid-interconnection mandates. Pursue toll manufacturing arrangements with established German or Japanese distributors to bypass 18-24 month direct qualification timelines. For Investors and Strategic Acquirers: The window for entry favors specialty-grade producers with ultra-low-boron formulation capabilities serving silicon carbide epitaxy for automotive power electronics. Acquisition targets should exhibit captive chlorosilane production or modular distillation technology integration. Watch fluidized bed reactor deployment rates as the inflection signal for trichlorosilane displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallurgical-Grade Silicon | Hemlock Semiconductor Operations demonstrates captive chlorosilane economics insulating margin from HCl volatility. |
| Modular Distillation Skid Deployment | Jiangsu and Sichuan producers compress batch release cycles from days to hours via online mass spectrometry integration. |
| Long-term Supply Agreement Structuring | Shin-Etsu Chemical locks five-year offtake with fixed purity escalation clauses defending semiconductor-grade pricing power. |
| Carbon Capture Integration | Closed-loop chlorosilane recovery under MEE emissions caps differentiates compliant producers from stranded capacity. |
| Joint Venture for Regional Market Access | Indian PLI scheme incubation attracts foreign technical-grade suppliers partnering with domestic ingot pullers under CEA mandates. |
Research Approach
Document review covered trade flow databases, SEC and ECHA regulatory filings, and polysilicon producer sustainability disclosures, complemented by interviews with plant managers at chlorosilane facilities, procurement leads at wafer manufacturers, and distribution channel partners serving solar and electronics sectors. Bottom-up triangulation against top-down purity-grade demand modeling validated volume estimates across technical and semiconductor segments.
Output projections span purity-grade stratification, end-use absorption by solar versus semiconductor applications, and regional production hub concentration without specifying discrete annual milestones. CAGRs derive from reactor utilization rates, qualification timeline compression, and substitution elasticity for silane-based fluidized bed alternatives. Forecast inputs incorporate MEE emissions cap enforcement trajectories and IRA tax credit uptake assumptions.
The model assumes a particular technology adoption path; alternative pathways for silane-based polysilicon deposition would alter the outlook for trichlorosilane volume absorption. Forecasts reflect assumptions around GB standards enforcement intensity and Xinjiang logistics corridor stability. A model refresh is warranted upon material change in fluidized bed reactor commercialization rates or carbon-border adjustment mechanism implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
Benzenoid Market
Chemicals
Global Methylene Chloride Market
Chemicals
LAMEA Dimethyl Phosphate Market
Chemicals
North America Methanol Market
Chemicals
Polyphosphoric Acid (PPA) Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
Industrial Odor Management Market
Chemicals
Non PVC Plasticizers Market
Chemicals
Mercury (I) Sulphate Market
Chemicals
Methylamines Market
Chemicals
Global Photoresist Chemicals Market
Chemicals
Amine Oxide Market
Chemicals
Insect Repellent Active Ingredients Market
Chemicals
Formalin Vials Market
Chemicals
South America Surface Treatment Chemicals Market