
 Diethylenetriamine (DETA) Market | 2026-2036
Diethylenetriamine (DETA) Market Size, Share, and Industry Trends Forecast 2026-2036
Diethylenetriamine (DETA) Market Analysis
Polymer-grade purification technology is fragmenting the traditional ethyleneamine production hierarchy, forcing producers to choose between commodity scale and specialty purity. Huntsman Corporation leverages its integrated amines portfolio to sustain cost positions across multiple DETA derivatives. Tosoh Corporation anchors its Asian supply network through captive ethylene dichloride access and downstream epoxy hardener specialization.
Diethylenetriamine is a linear aliphatic polyamine with the formula H₂N(CH₂)₂NH(CH₂)₂NH₂, produced primarily via ethylene dichloride ammonolysis or reductive amination of monoethanolamine, functioning as a reactive intermediate for chelating agents, surfactants, and epoxy curing systems. Industrial-grade material dominates volume flows into corrosion inhibitors and asphalt additives where specification tolerance permits broader amine distribution. Pharmaceutical-grade DETA commands premium positioning through CDMO partnerships, while chemical intermediates for chelating agents represent the fastest-growing application vector as water treatment standards tighten globally.
EPA oversight under the Toxic Substances Control Act shapes manufacturing disclosures and emission thresholds for U.S.-based ethyleneamine facilities. REACH registration through ECHA mandates comprehensive toxicological dossiers for DETA import and production above one tonne annually within the European Economic Area. China's MEE enforces GB standard compliance for wastewater discharge from amine production corridors along the Yangtze River basin. Stakeholders must monitor regulatory divergence between jurisdictions where purity classifications and handling protocols increasingly determine market access rather than price alone.
Market Dynamics
Polymer-grade purification technology is fragmenting the traditional ethyleneamine production hierarchy, forcing producers to choose between commodity scale and specialty purity. Wind turbine blade manufacturers exceeding 100-meter lengths now specify ultra-high-purity DETA for epoxy curing systems, creating a bifurcation between industrial-grade and pharmaceutical-grade supply tiers.
Growth Catalysts
- REACH Registration Requirements:ECHA-mandated toxicological dossiers for DETA above one tonne annually are filtering out marginal European producers and consolidating supply among compliant manufacturers.
- Wind Energy Expansion:Epoxy curing agent demand from turbine blade fabricators is accelerating as blade architectures require longer carbon fiber-reinforced structures.
- China's Yangtze River Clusters:Ethyleneamine production corridors concentrated in Jiangsu and Zhejiang provinces serve domestic coatings and adhesive formulators with integrated raw material access.
Market Restraints
- Ethylene Dichloride Feedstock Volatility:DETA production costs track EDC pricing, which fluctuates with chlor-alkali plant operating rates and ethylene supply disruptions.
- Purity Specification Divergence:EPA emission thresholds under TSCA and MEE wastewater GB standards impose conflicting compliance architectures on multinational producers.
- Monoethanolamine Reductive Amination:Alternative DETA synthesis routes using MEA feedstock threaten EDC-based producers when natural gas prices compress ammonia economics.
Strategic Opportunities
- CDMO Pharmaceutical Partnerships:Pharmaceutical-grade DETA for chelating agent precursors commands premium positioning through contract development and manufacturing organization relationships.
- Water Treatment Mandates:Tightening effluent standards across industrial zones are expanding demand for DETA-derived chelating agents in heavy metal sequestration applications.
- MEA-to-DETA Process Convergence:Integration of reductive amination technology with bio-based ethanolamine feedstocks offers carbon intensity reduction pathways for specialty chemical producers.
Industry Challenges
- Polyamine Separation Expertise Scarcity:Fractional distillation of ethyleneamine mixtures to polymer-grade specifications requires specialized process engineering talent concentrated at legacy production sites.
- Multi-Jurisdiction Registration Timelines:Parallel EPA TSCA disclosures, ECHA REACH dossiers, and NMPA chemical registrations create extended product qualification cycles for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diethylenetriamine (DETA) Market |
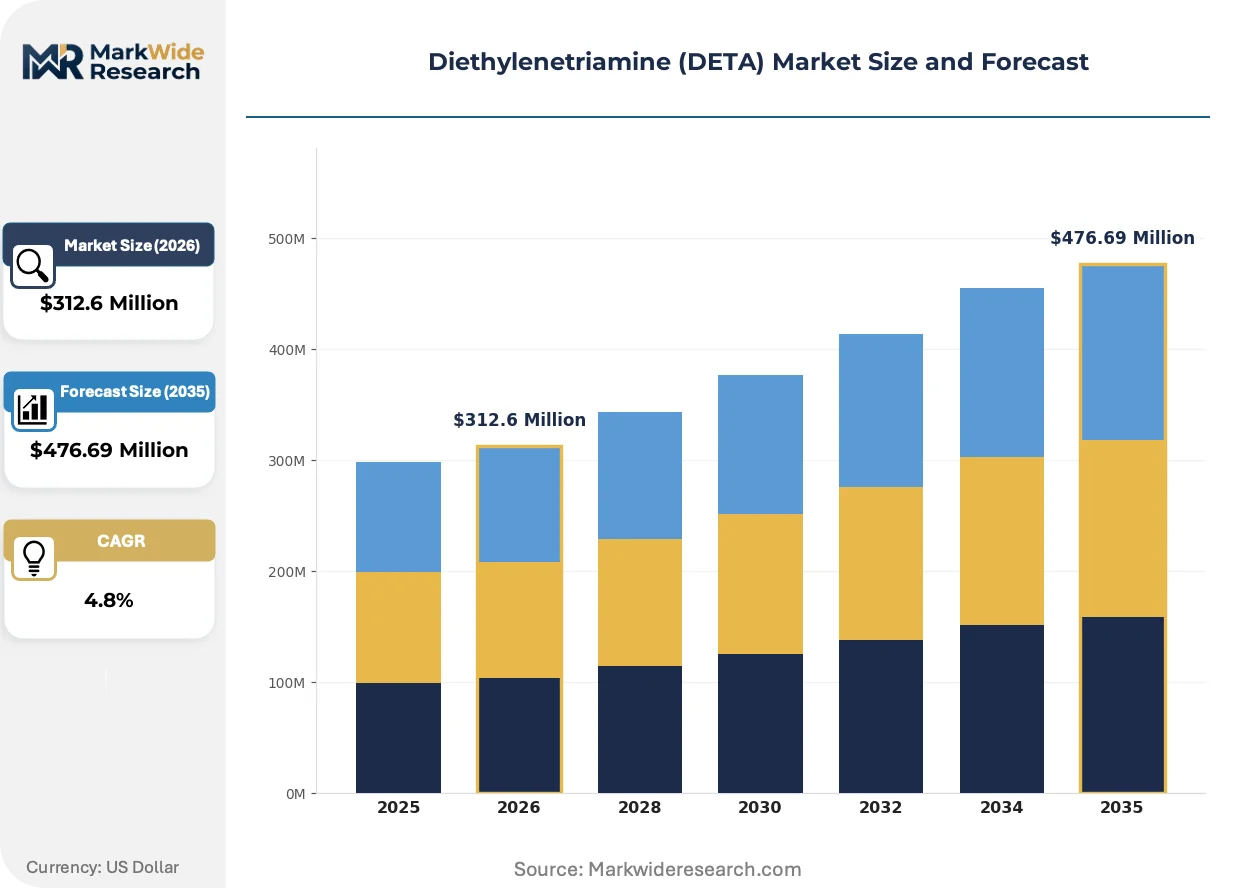
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $476.69 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Agricultural Grade, Research Grade End User: Chemical Manufacturers, Pharmaceutical Companies, Agricultural Sector, Research Institutions Application: Adhesives, Coatings, Corrosion Inhibitors, Chemical Intermediates Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | The Dow Chemical Company, Tosoh Corporation, BASF SE, Delamine B.V., Nouryon, Huntsman Corporation, AkzoNobel N.V., Arabian Amines Company, Diamines and Chemicals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diethylenetriamine (DETA) Market Emerging Trajectories
Manufacturing technology and regulatory architecture are converging to reshape competitive positioning in ethyleneamine derivatives. Three developments are restructuring how DETA purity grades are produced, certified, and deployed across end-use verticals.
Continuous reactive distillation systems for ethyleneamine purification are migrating from batch processing architectures toward integrated continuous manufacturing platforms. Specialty chemical producers in Germany and Japan are retrofitting legacy ammonolysis trains with in-line analytical control systems. This technology is migrating from pharmaceutical-grade applications into industrial-grade production, compressing capital recovery timelines and enabling real-time purity adjustment.
REACH registration dossiers under ECHA Article 10 are mandating extended one-generation reproductive toxicity studies for DETA classifications above 100 tonnes annually. Industrial-grade importers into the European Economic Area face compliance cost escalation that favors established registrants with existing toxicological data packages. Pharmaceutical-grade suppliers with prior CDMO toxicology investments are absorbing registration burdens more efficiently than commodity traders.
Wind turbine blade fabricators are consolidating epoxy hardener procurement around qualified supplier lists with locked purity specifications and certified carbon footprints. OEMs like Vestas and Siemens Gamesa now require supply chain disclosure through the EU Green Deal taxonomy. This buyer concentration is most visible in Denmark and northern Germany, where blade manufacturing clusters have displaced spot-market DETA purchasing with multi-year framework agreements tied to renewable energy project financing cycles.
Diethylenetriamine (DETA) Market Segmentation
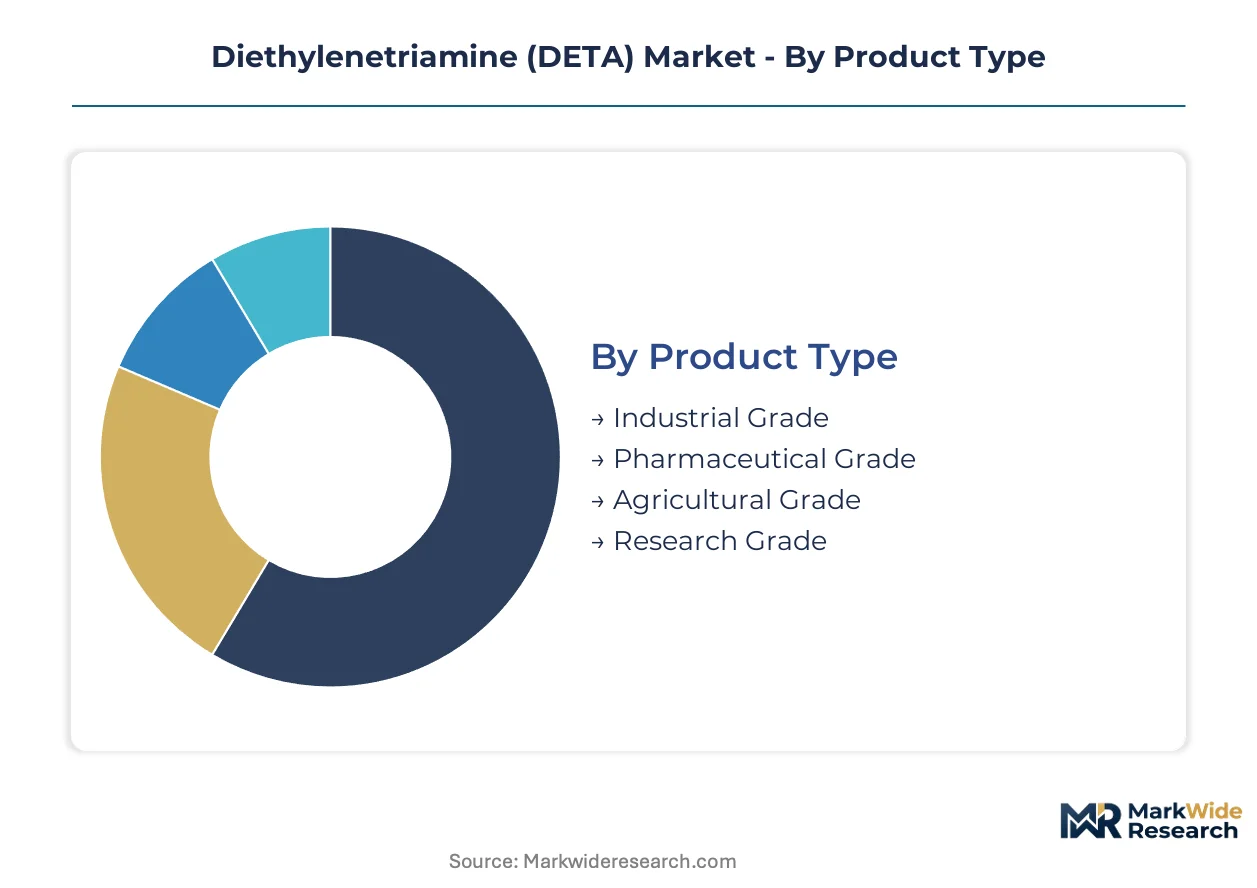
Purity specifications and regulatory compliance create distinct value tiers in DETA supply chains. Each segment carries different qualification timelines, margin structures, and customer concentration patterns that reshape competitive positioning across the ethyleneamine derivatives landscape.
Product Type:
Inventory cycles vary dramatically across purity grades, with pharmaceutical-grade material requiring extended stability testing and industrial-grade turning on chlor-alkali operating schedules.
- Industrial Grade:Broad amine distribution tolerances characterize this specification for corrosion inhibitors and asphalt additives. Demand concentrates in China's Yangtze River manufacturing corridors where ethyleneamine producers serve domestic coatings formulators with integrated EDC access.
- Pharmaceutical Grade:Stringent impurity limits below 0.1% define this tier for chelating agent precursors and active pharmaceutical ingredient synthesis. CDMO partnerships in Germany and Switzerland anchor demand as ECHA REACH dossier requirements filter out marginal suppliers.
- Agricultural Grade:Intermediate purity specifications serve agrochemical intermediate production with seasonal procurement patterns tied to planting cycles.
- Research Grade:Small-batch, high-specification material supports academic and commercial R&D with extended lead times and premium positioning.
Industrial grade anchors the volume base while pharmaceutical grade gains share at the steepest rate.
End User:
Customer technical capabilities determine specification complexity and contract structures across the value chain.
- Chemical Manufacturers:Integrated amines producers like Huntsman Corporation leverage captive DETA for downstream epoxy hardener and surfactant synthesis. Procurement cycles align with ethylene dichloride contract pricing and chlor-alkali plant utilization rates.
- Pharmaceutical Companies:CDMO networks in Basel and Boston drive pharmaceutical-grade demand with locked purity certificates and multi-year supply agreements. EPA TSCA disclosure requirements and ECHA Article 10 registrations create qualification barriers for new entrants.
- Agricultural Sector:Seasonal buying patterns from agrochemical formulators concentrate in Brazil and India during pre-planting procurement windows.
- Research Institutions:Fragmented, small-volume demand from university and government laboratories with spot-market purchasing behavior.
Chemical manufacturers dominate absolute offtake while pharmaceutical companies expand most quickly.
Application:
Performance requirements and certification burdens segment demand by technical intensity and regulatory exposure.
- Adhesives:Epoxy curing systems for wind turbine blade fabrication require ultra-high-purity DETA as blade architectures exceed 100 meters. Vestas and Siemens Gamesa procurement teams in Denmark enforce qualified supplier lists with carbon footprint disclosure under EU Green Deal taxonomy.
- Coatings:Industrial protective and marine coatings consume volume-grade material with specification tolerance for broader amine distribution. China's Jiangsu province coating clusters source from captive ethyleneamine production corridors.
- Corrosion Inhibitors:Oilfield and refinery applications in the US Gulf Coast and Middle East drive demand for metal-chelating formulations with EPA emission threshold compliance.
- Chemical Intermediates:Fastest-expanding application vector as water treatment mandates tighten effluent standards for heavy metal sequestration across industrial zones.
Coatings anchor the volume base while chemical intermediates climb the fastest.
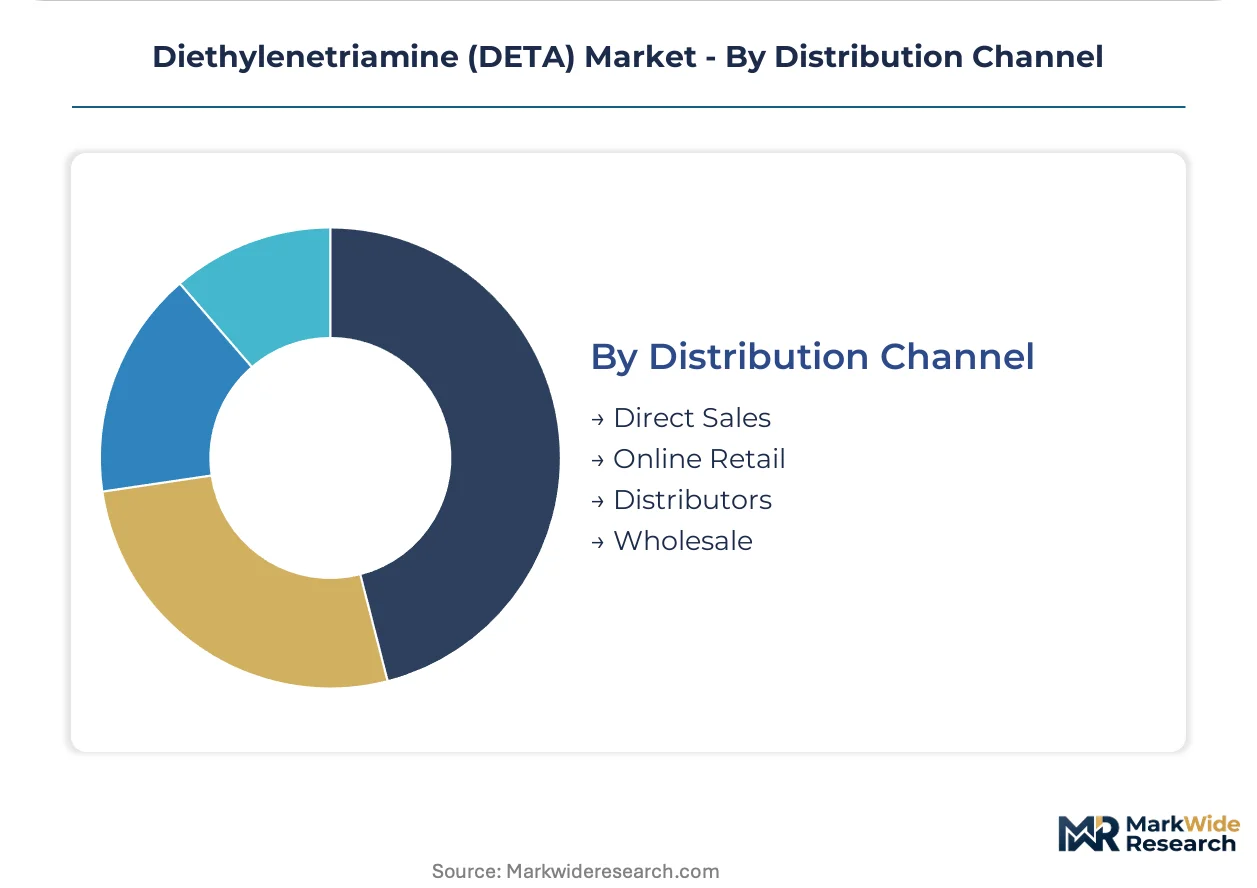
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and geographic concentration of demand.
- Direct Sales:Multi-year framework agreements with wind turbine OEMs and pharmaceutical CDMOs lock in purity specifications and certified carbon footprints. Tosoh Corporation anchors Asian supply networks through direct relationships with epoxy hardener specialists.
- Distributors:Regional chemical distributors serve fragmented coatings and adhesive formulators with technical service and just-in-time delivery capabilities.
- Wholesale:Bulk volume movements into industrial-grade applications with price-sensitive procurement and minimal technical support requirements.
- Online Retail:Small-package sales to research institutions and specialty formulators with credit card purchasing and rapid fulfillment expectations.
Direct sales command the premium tier while distributors capture expanding share in mid-market coatings segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wind turbine blade fabricators and pharmaceutical CDMOs concentrate procurement in specific industrial corridors where epoxy hardener specialization and REACH-compliant supply chains intersect. Regulatory divergence between EPA emission thresholds and ECHA registration requirements fragments supplier qualification across Atlantic markets. Ethyleneamine production clusters in China's Yangtze River basin serve domestic coatings formulators with captive ethylene dichloride access.
United States
EPA oversight under the Toxic Substances Control Act shapes manufacturing disclosures for Gulf Coast ethyleneamine facilities serving oilfield corrosion inhibitor demand. Emission thresholds for chlor-alkali co-product streams tighten compliance burdens on Texas and Louisiana production sites. Houston-area chemical manufacturers procure industrial-grade material for refinery and petrochemical applications.
Germany
REACH registration dossiers under ECHA Article 10 mandate extended toxicological studies for DETA classifications above 100 tonnes annually. Industrial-grade importers face compliance cost escalation that favors established registrants with existing data packages. The Rhine-Ruhr chemical corridor anchors epoxy hardener production for Vestas and Siemens Gamesa blade fabrication supply chains.
China
MEE enforcement of GB wastewater standards along the Yangtze River basin shapes production economics for Jiangsu and Zhejiang ethyleneamine corridors. Domestic coatings formulators source from integrated producers with captive EDC access and downstream surfactant capabilities. NMPA chemical registration timelines create extended qualification cycles for pharmaceutical-grade imports.
Japan
METI industrial standards and PMDA pharmaceutical regulations bifurcate DETA supply tiers between industrial chelating agents and active pharmaceutical ingredient precursors. Chubu region chemical producers leverage reductive amination technology with bio-based ethanolamine feedstock integration. Nagoya-area epoxy hardener specialists serve wind turbine component fabricators with ultra-high-purity specifications.
Saudi Arabia
Downstream petrochemical integration creates feedstock advantages for Arabian Gulf ethyleneamine producers serving regional corrosion inhibitor demand. Industrial-grade material flows into Middle East refinery and oilfield applications with specification tolerance for broader amine distribution. Jubail Industrial City clusters anchor production corridors with chlor-alkali integration and access to European export markets.
Diethylenetriamine (DETA) Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply architectures where direct sales to wind turbine OEMs and pharmaceutical CDMOs lock in multi-year framework agreements. The vendor base stratifies between integrated amines producers with captive ethylene dichloride access and downstream epoxy hardener specialists. Three archetypes dominate: multinational chemical conglomerates with diversified ethyleneamine portfolios, regional production specialists with Yangtze River basin integration, and pharmaceutical-grade purification houses with CDMO certification. Competitive moves center on REACH registration consolidation and continuous reactive distillation retrofitting.
Among integrated chemical producers, Huntsman Corporation and Tosoh Corporation exemplify archetypes with differentiated geographic anchoring. Huntsman leverages North American chlor-alkali integration for industrial-grade scale positions. Tosoh anchors Asian supply networks through direct relationships with epoxy hardener specialists. BASF SE occupies a position spanning both commodity and specialty tiers with European registration advantages. Delamine B.V. represents the purification-specialist archetype with CDMO-facing capabilities.
| Leading Market Players |
|---|
| The Dow Chemical Company |
| Tosoh Corporation |
| BASF SE |
| Delamine B.V. |
| Nouryon |
| Huntsman Corporation |
| AkzoNobel N.V. |
| Arabian Amines Company |
| Diamines and Chemicals Ltd. |
| Others |
Supply Flow & Price Mechanics
Ethylene dichloride feedstock volatility determines both pricing tier spreads and supply chain shape, compressing margins for EDC-based producers when chlor-alkali operating rates fluctuate while rewarding reductive amination specialists with MEA feedstock flexibility. Pharmaceutical-grade purification investments widen spreads between industrial-grade spot pricing and CDMO-contracted premium tiers.
Pricing Analysis
Cost-plus contracts indexed to ethylene dichloride and ammonia benchmarks dominate industrial-grade procurement, with Huntsman Corporation and Tosoh Corporation leveraging captive chlor-alkali integration to stabilize input costs. Price differentiation separates pharmaceutical-grade CDMO agreements with locked purity certificates from spot-market industrial-grade movements. Pricing pressure stems from MEA-to-DETA process convergence threatening EDC-based economics during natural gas price compression. Chemical manufacturers exhibit highest price sensitivity due to volume procurement and specification tolerance, while pharmaceutical CDMOs accept premium positioning for registration-compliant supply security.
Supply Chain Analysis
Tariff exposure between the United States and China fragments ethyleneamine trade flows, forcing European and Middle Eastern producers to capture displaced volume. Supply concentrates in China's Jiangsu and Zhejiang provinces, Germany's Rhine-Ruhr corridor, and Saudi Arabia's Jubail Industrial City, with each hub drawing from captive EDC or integrated MEA feedstock. Raw material dependencies include ethylene dichloride, monoethanolamine, and ammonia. Distribution runs through direct sales to wind turbine OEMs and pharmaceutical CDMOs, with regional distributors serving fragmented coatings formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA, ECHA, and MEE jurisdictions creates niche positioning opportunities for purity-grade specialists and regional registration holders. Wind blade scaling beyond 100 meters concentrates procurement power among qualified suppliers.
For Market Incumbents: Harden REACH registration moats by consolidating toxicological dossier investments across Article 10 classifications above 100 tonnes annually. Defend against MEA-based process convergence by locking long-term EDC supply agreements with Gulf Coast chlor-alkali operators. Prioritize continuous reactive distillation retrofits to compress pharmaceutical-grade capital recovery timelines. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical-grade purification serving Basel and Boston CDMO networks, where ECHA registration barriers filter commodity competition. Target water treatment chelating agent intermediates as the fastest-expanding application vector with tightening effluent mandates. Pursue bio-based ethanolamine feedstock integration to differentiate carbon intensity credentials under EU Green Deal taxonomy. For Investors and Strategic Acquirers: REACH Article 10 enforcement reshapes the acquisition landscape toward established registrants with existing toxicological data packages. Five-to-ten-year viability favors purification-specialist archetypes with CDMO certification and locked multi-year framework agreements. Monitor wind turbine OEM qualified supplier list consolidation as the inflection signal for epoxy hardener supply chain control.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EDC Supply | Huntsman Corporation secures Gulf Coast chlor-alkali co-product streams against feedstock volatility. |
| Continuous Reactive Distillation Retrofit | German and Japanese producers compress pharmaceutical-grade capital recovery through real-time purity adjustment. |
| CDMO Partnership Certification | Delamine B.V. anchors premium positioning through locked multi-year supply agreements with Basel networks. |
| Bio-Based MEA Feedstock Integration | Chubu region producers differentiate carbon intensity under METI industrial standards and EU Green Deal. |
| Wind Turbine OEM Qualified Supplier Listing | Vestas and Siemens Gamesa procurement teams displace spot-market purchasing with carbon-disclosed framework agreements. |
Methodological Framework
Desk research of customs trade data, SEC 10-K filings, and ECHA registration databases preceded structured interviews with ethyleneamine plant managers, epoxy hardener procurement leads at wind turbine OEMs, pharmaceutical CDMO technical directors, and coatings formulator supply planners. Secondary validation drew from ACC and Cefic industry reports, chlor-alkali operating rate disclosures, and wind energy project development databases. Bottom-up volume triangulation across purity grades and end-use applications converged with top-down market sizing.
Forecast assumptions held fixed regulatory enforcement timelines and wind blade scaling trajectories while varying ethylene dichloride pricing scenarios and MEA process adoption rates across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use industry, application technical intensity, and regional production hub clustering. CAGRs derived from slope-intercept analysis of historical volume movements and elasticity-adjusted demand projections, with wind turbine blade length specifications and water treatment mandate tightening as primary industry-specific inputs.
Sensitivities concentrate around chlor-alkali plant operating rate disruptions, REACH registration timeline accelerations, and MEA-to-DETA process economics shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Guanidine Carbonate Market
Chemicals
Cold Phosphating Chemicals Market
Chemicals
Lanthanum Nitrate Market
Chemicals
Household Insecticides Market
Chemicals
India Metal Treatment Chemical Market
Chemicals
Sulfuric Acid Market
Chemicals
Global Cysteine Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Global Oxo Alcohols Market
Chemicals
Betaine Market
Chemicals
Chlorosilane Market
Chemicals
Isoamyl Acetate Market
Chemicals
Paraphenylenediamine (PPD) Market
Chemicals
Malonic Acid Market
Chemicals
Global Commodity Chemicals Market
Chemicals
Trifluoroacetic Acid (TFA) Market