
 Global Wood Preservative Chemicals and Coatings Active Ingredients Market | 2026-2036
Global Wood Preservative Chemicals and Coatings Active Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wood Preservative Chemicals and Coatings Active Ingredients Market Foresight
Market Context with Strategic Players
Alkaline copper quaternary is shifting economics away from traditional chromated copper arsenate across residential and commercial construction. LANXESS anchors European supply through its borate and copper compound portfolios, while Koppers Performance Chemicals dominates North American railroad tie and utility pole treatment. Viance differentiates through waterborne preservative systems that compete directly with solvent-based alternatives in decking applications.
Technical Definition and Structural Segments
Wood preservative chemicals and coatings active ingredients comprise biocidal compounds, water-repellent polymers, and stabilizing agents formulated to inhibit fungal decay, insect infestation, and moisture-induced degradation in dimensional lumber and engineered wood products, typically applied via pressure-vacuum impregnation or surface coating at retention levels measured in pounds per cubic foot. Copper compounds command the largest share of the product type landscape due to proven efficacy against brown-rot and white-rot fungi in above-ground and ground-contact applications, while nanocoatings within coating technology represent the fastest-expanding segment as manufacturers pursue thinner-film performance with lower volatile organic compound emissions. Construction firms absorb the dominant volume within end user industry demand, though marine contractors generate disproportionate margin pools through specification-grade fluorochemical and zinc naphthenate treatments for piling and bulkhead exposure.
Regulatory Frame and Forward-Looking Close
EPA registration requirements under the Federal Insecticide, Fungicide, and Rodenticide Act govern active ingredient approval and label claims in the United States, while REACH and the EU Biocidal Products Regulation constrain copper emission thresholds and mandate environmental risk assessments for preservative leachate across European member states. China's MEE enforces GB standards for treated-wood import and domestic manufacturing discharge that elevate compliance costs for boron-based formulations. Stakeholders must monitor pending restrictions on creosote railway applications in Germany and France, as these rulings will redirect volume toward copper azole and micronized copper systems within the next regulatory cycle.
Market Dynamics
Alkaline copper quaternary is displacing chromated copper arsenate as the dominant preservative chemistry across residential construction, driven by EPA FIFRA restrictions on arsenic-containing formulations and builder liability concerns in ground-contact lumber applications.
Growth Catalysts
- REACH copper emission thresholds:European ECHA mandates are accelerating borate and copper azole adoption in above-ground decking, redirecting formulation R&D toward waterborne systems with lower leachate profiles.
- Railroad tie replacement cycles:North American Class I railways are expanding creosote-alternative programs for crossties and bridge timbers, pulling micronized copper volumes into an historically creosote-captive segment.
- Nanocoating film-thickness reduction:Sol-gel and silica-based nanocoatings are penetrating marine piling specifications in Japan and Australia, enabling thinner protective layers with equivalent fungal resistance.
Market Restraints
- Copper price volatility:Copper carbonate and copper oxide feedstocks expose formulators to London Metal Exchange fluctuations that compress margin predictability in fixed-price municipal contracts.
- Supply concentration in borate mining:Turkish and California borate deposits control roughly two-thirds of global refined supply, creating geographic chokepoints for borate-based preservative manufacturers.
- Ground-contact efficacy gaps:Organic biocides lack the decades-long performance data of copper systems, limiting specification in critical infrastructure such as highway guardrails and transmission poles.
Strategic Opportunities
- India treated-wood infrastructure:BIS certification requirements for railway sleepers and utility poles are expanding addressable volume as the country electrifies rural distribution networks.
- GB standard export compliance:China's MEE discharge rules for treated-wood manufacturing are creating a two-tier market where ISO-certified producers capture premium export slots to Southeast Asian construction markets.
- Biocide-polymer convergence:Pressure-vacuum impregnation lines are integrating in-line moisture-barrier coatings, enabling single-process treatment that reduces capital intensity for mid-scale sawmills.
Industry Challenges
- Preservative retention calibration:Ground-contact specifications require precise pounds-per-cubic-foot dosing that varies by wood species density, demanding skilled technicians that sawmills struggle to retain.
- EPA label amendment timelines:New active ingredient registrations under FIFRA Section 3 face 18-36 month review cycles that delay commercial launch and compress patent-protected revenue windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wood Preservative Chemicals and Coatings Active Ingredients Market |
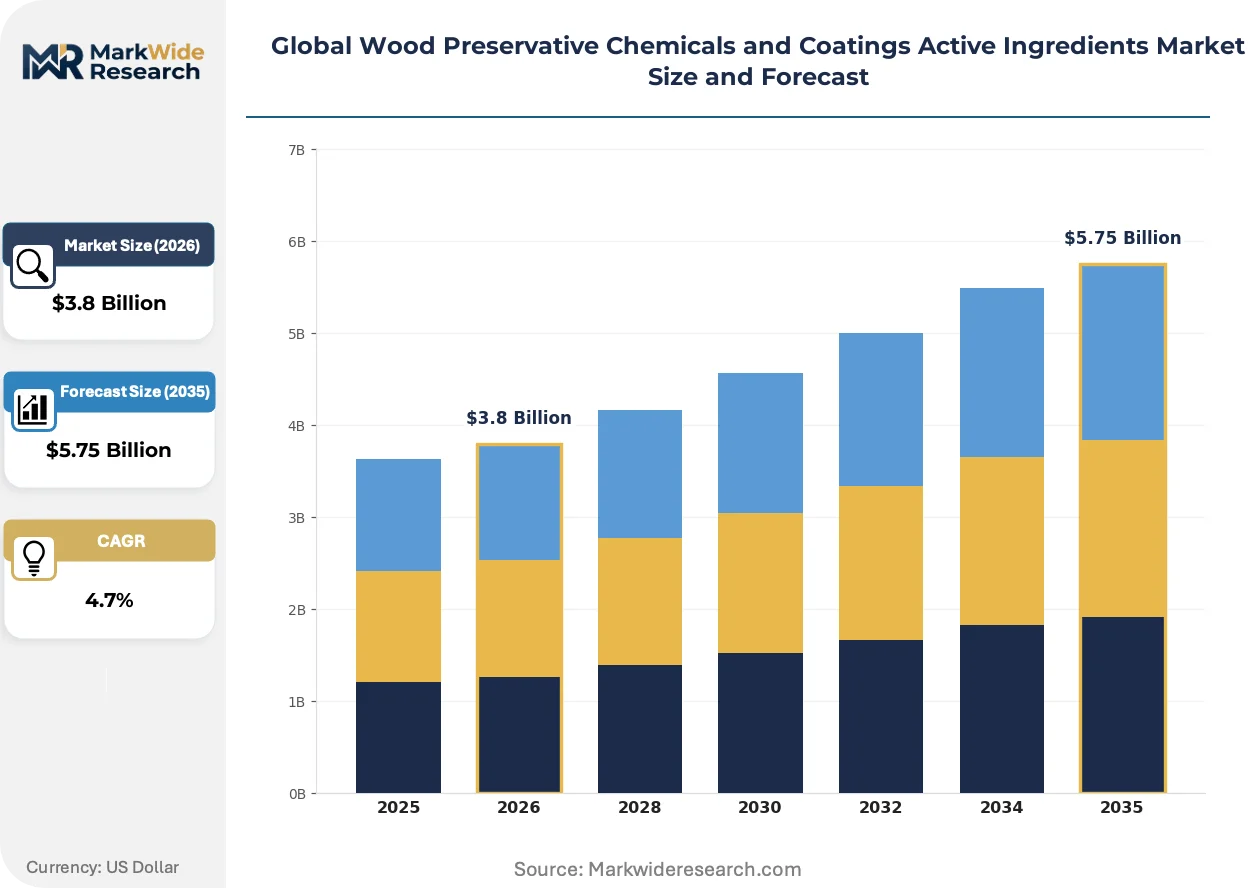
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Compounds, Borates, Organic Solvents, Synthetic Polymers, Zinc Naphthenate, Fluorochemicals Application: Roofing, Decking, Fencing, Outdoor Furniture, Marine Structures, Agricultural Tools End User Industry: Construction Firms, Furniture Manufacturers, Marine Contractors, Agricultural Equipment Producers, Packaging Plants, Infrastructure Developers Coating Technology: Waterborne, Solvent-Based, Thermal Modification, Nanocoatings, UV-Curable, Powder Coatings |
| Companies Covered | Kop-Coat, Kurt Obermeier GmbH & Co. KG, LANXESS, Remmers Group AG, Arxada, Koppers Performance Chemicals, Viance, Troy Corporation, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wood Preservative Chemicals and Coatings Active Ingredients Market Shifts & Advancements
Micronized copper systems are fragmenting the preservative landscape by enabling dry-formulation handling that eliminates liquid waste streams, while regulatory pressure on volatile organic compounds compresses solvent-based coating margins.
Micronized copper carbonate is rewriting treatment economics by eliminating the slurry-handling infrastructure required for soluble copper systems. Residential decking manufacturers in the United States are retrofitting pressure plants for dry-chemical delivery at a pace that is compressing capital barriers for regional treaters. This technology is rewriting the geographic distribution of treater capacity by enabling smaller-batch, higher-flexibility operations closer to lumber sources.
REACH authorization requirements for creosote are forcing railway operators across Germany and France to accelerate copper azole and borate evaluation programs for crosstie replacement. The industrial consequence is a specification-grade volume migration that copper-based suppliers are capturing through dedicated rail-sector technical service teams. Bridge timber and switch tie applications in Central Europe are most affected, with Austrian and Swiss operators now requiring environmental product declarations for all preservative systems.
Direct mill-treater relationships are displacing distributor-mediated chemical procurement in North American dimensional lumber. Large sawmill groups are negotiating multi-year active ingredient supply agreements that bundle technical service and retention testing, compressing independent chemical distributor margins. British Columbia and the US Pacific Northwest show this pattern most visibly, where vertically integrated forest products companies are bringing treatment operations in-house.
Global Wood Preservative Chemicals and Coatings Active Ingredients Market Segmentation
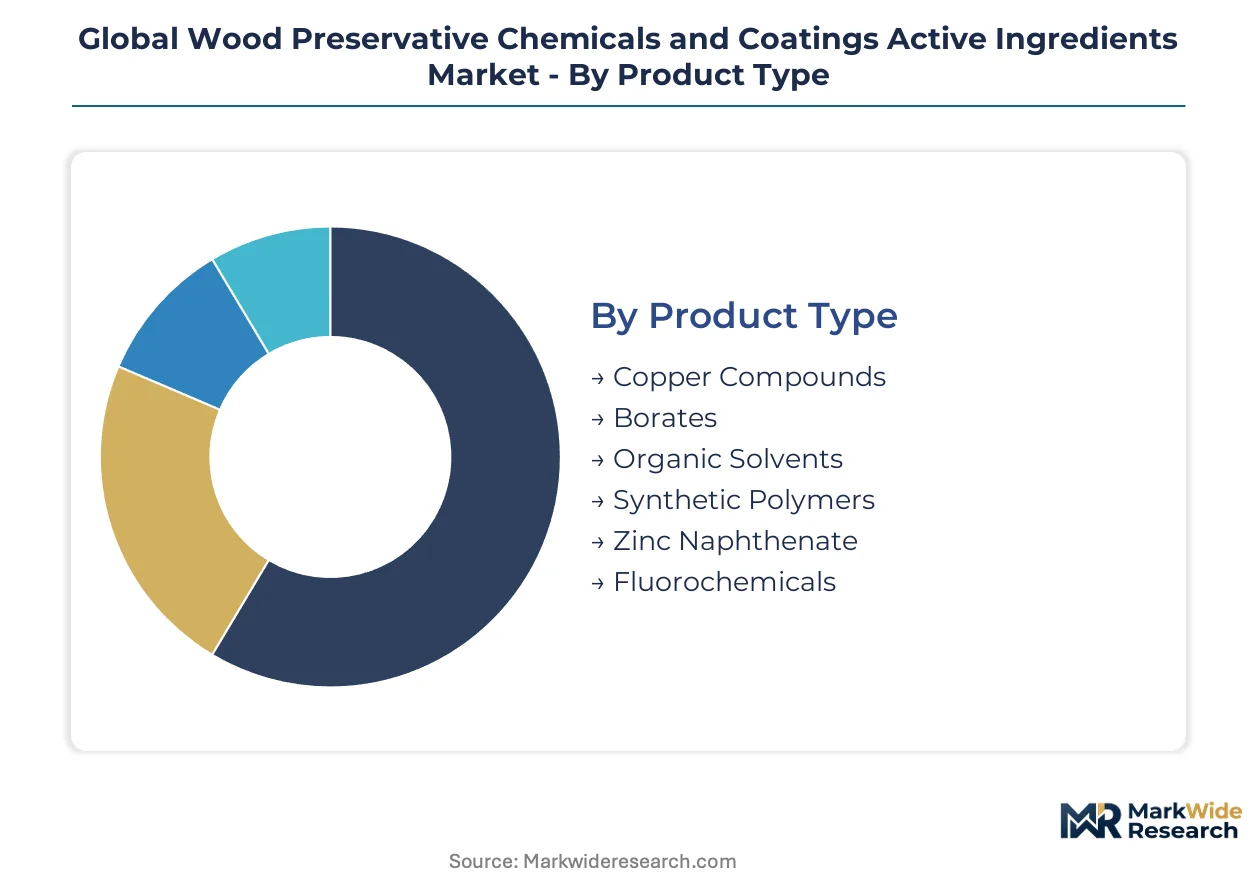
Wood preservative chemistry fragments across active ingredient families, application exposures, and coating delivery systems that each carry distinct regulatory burdens and performance specifications. Treatment selection hinges on decay hazard classifications, end-use environmental exposure, and regional chemical approval status rather than commodity pricing alone.
Product Type:
Copper-based systems anchor efficacy benchmarks across ground-contact and above-ground specifications, while alternative chemistries compete on leachate profiles and handling safety.
- Copper Compounds:Alkaline copper quaternary and copper azole formulations deliver broad-spectrum protection against brown-rot and white-rot fungi through controlled release of cupric ions. Demand concentrates in United States residential decking and German railway tie replacement programs, where decades of field performance data support specification in critical infrastructure.
- Borates:Disodium octaborate tetrahydrate and related boron compounds penetrate deep into wood cell walls via diffusion, offering protection against insects and decay organisms with low mammalian toxicity. Above-ground applications in Australian and New Zealand framing dominate volume, though European REACH emission thresholds are redirecting R&D toward encapsulation technologies that reduce leaching.
- Organic Solvents:Petroleum-derived carriers dissolve lipophilic biocides for deep penetration into refractory wood species.
- Synthetic Polymers:Acrylic and polyurethane film-forming systems create surface barriers against moisture ingress.
- Zinc Naphthenate:Organometallic complexes provide mold and mildew resistance in above-ground exposures with lower copper content.
- Fluorochemicals:Perfluorinated compounds repel water and oils in premium exterior applications.
Mature deployment sits with Copper Compounds. Newer deployment is concentrated in Borates.
Application:
Exposure severity and replacement economics drive specification tiers, with ground-contact applications demanding higher retention levels and more frequent re-treatment cycles.
- Decking:Horizontal surfaces in residential and commercial construction face intense UV degradation, moisture cycling, and foot traffic abrasion that accelerate coating failure. North American treated-wood producers specify micronized copper systems at elevated retentions for United States and Canadian building codes, while Japanese architects increasingly specify nanocoating overlays for premium cedar installations.
- Marine Structures:Piling, bulkheads, and dock components endure continuous saltwater immersion, marine borer attack, and tidal wet-dry cycling that exceed terrestrial decay hazards. Australian and Japanese port authorities specify dual-treatment protocols combining copper azole impregnation with fluorochemical or zinc naphthenate surface coatings.
- Roofing:Shingles and shakes require fire-retardant and moisture-resistant treatments.
- Fencing:Post-in-ground and board exposures split between ground-contact and above-ground specifications.
- Outdoor Furniture:Appearance-critical applications favor clear or tinted coatings with UV stabilizers.
- Agricultural Tools:High-durability handles and posts face soil contact and chemical exposure.
Volume concentrates in Decking. Margin expansion is steepest in Marine Structures.
End User Industry:
Procurement scale and technical sophistication vary sharply, with infrastructure operators demanding certified retention testing and furniture makers prioritizing aesthetic compatibility.
- Construction Firms:Large-scale residential and commercial builders drive standardized treated-lumber volume through prescriptive building code compliance. United States national homebuilders specify third-party inspected retention levels for ground-contact framing, while German and Austrian timber-frame contractors require environmental product declarations documenting copper emission profiles.
- Infrastructure Developers:Highway authorities, railway operators, and utility companies purchase treated wood through multi-year municipal contracts with fixed-price escalation clauses. Indian railway electrification programs under BIS certification are expanding sleeper treatment volume, while French and German rail operators evaluate copper azole alternatives to creosote under REACH authorization pressure.
- Furniture Manufacturers:Outdoor seating and table producers balance durability with surface appearance requirements.
- Marine Contractors:Port and waterfront specialists specify high-retention treatments with extended service life guarantees.
- Agricultural Equipment Producers:Tractor component and vineyard post manufacturers seek cost-optimized protection.
- Packaging Plants:Pallet and crate producers use lighter-duty treatments for temporary exposure.
Construction Firms absorb dominant volume. Infrastructure Developers generate the steepest expansion trajectory.
Coating Technology:
Application method and volatile organic compound regulations determine technology selection, with waterborne systems displacing solvent carriers in environmentally constrained markets.
- Waterborne:Acrylic and polyurethane dispersions deliver film-forming protection with low solvent emissions, enabling compliance with EPA and MEE discharge regulations. European decking manufacturers in Germany and France have converted pressure-treatment lines to waterborne finishing systems, while Chinese export-oriented sawmills adopt waterborne coatings to meet GB standard import requirements in Southeast Asian markets.
- Nanocoatings:Sol-gel silica and metal oxide nanoparticles create ultra-thin hydrophobic barriers with minimal volatile organic compound content. Japanese marine piling specifications and Australian waterfront infrastructure projects are piloting nanocoating systems that reduce film thickness while maintaining fungal resistance.
- Solvent-Based:Traditional alkyd and oil-modified urethane systems persist in industrial applications.
- Thermal Modification:Heat-treated wood chemistry eliminates chemical preservatives through pyrolytic cell wall alteration.
- UV-Curable:Electron-beam and ultraviolet-initiated polymerization enables rapid line speeds in industrial finishing.
- Powder Coatings:Thermoset resin powders provide thick, durable films for metal-wood hybrid components.
Waterborne systems command installed base. Nanocoatings are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential construction intensity and treated-wood infrastructure replacement cycles concentrate demand in the United States, Germany, and China. Regulatory divergence on copper emissions and creosote authorization is fragmenting formulation standards across these markets.
United States
Class I railway operators are expanding creosote-alternative programs for crossties and bridge timbers, pulling micronized copper volumes into historically creosote-captive segments. EPA FIFRA restrictions on arsenic-containing formulations continue to redirect residential construction toward alkaline copper quaternary and copper azole systems. The Pacific Northwest and British Columbia sawmill corridor exhibits the most visible pattern of direct mill-treater relationships displacing distributor-mediated chemical procurement.
Germany
Railway operators are accelerating copper azole and borate evaluation programs for crosstie replacement under REACH authorization pressure for creosote. ECHA copper emission thresholds are redirecting above-ground decking formulation R&D toward waterborne systems with lower leachate profiles. Bridge timber and switch tie applications in Central Europe are most affected, with Austrian and Swiss operators now requiring environmental product declarations for all preservative systems.
China
MEE discharge rules for treated-wood manufacturing are creating a two-tier market where ISO-certified producers capture premium export slots to Southeast Asian construction markets. GB standards for treated-wood import and domestic manufacturing discharge elevate compliance costs for boron-based formulations. Yangtze River Delta export-oriented sawmills are adopting waterborne coatings to meet import requirements in Vietnam and Thailand.
India
BIS certification requirements for railway sleepers and utility poles are expanding addressable volume as the country electrifies rural distribution networks. Indian railway electrification programs under BIS certification are expanding sleeper treatment volume. Maharashtra and Gujarat industrial corridors are witnessing early-phase treated-wood infrastructure investment as highway authorities pilot preservative specifications for guardrails and sign posts.
Australia
Port authorities are specifying dual-treatment protocols combining copper azole impregnation with fluorochemical or zinc naphthenate surface coatings for marine piling. Sol-gel silica nanocoatings are penetrating waterfront infrastructure projects, enabling thinner protective layers with equivalent fungal resistance. New South Wales and Queensland marine contractors generate disproportionate margin pools through specification-grade treatments for piling and bulkhead exposure.
Global Wood Preservative Chemicals and Coatings Active Ingredients Market Competitive Landscape
Capacity expansion dominates the current landscape as regional treaters retrofit pressure plants for dry-chemical delivery. The vendor base organizes around three strategic archetypes: integrated chemical-solutions conglomerates with borate and copper compound portfolios, specialized wood-treatment technology providers focused on waterborne systems, and regional preservative distributors with technical service capabilities. M&A activity and backward integration into active ingredient synthesis represent the two dominant competitive moves, with sawmill groups negotiating multi-year supply agreements that bundle retention testing and technical support.
Among European-based chemical conglomerates, LANXESS anchors supply through its borate and copper compound portfolios, while Remmers Group AG exemplifies the specialized coating technology archetype. Kurt Obermeier GmbH & Co. KG occupies a position within the regional technical service tier, representing the distributor-centric model that direct mill-treater relationships are progressively displacing in North American markets.
| Leading Market Players |
|---|
| Kop-Coat |
| Kurt Obermeier GmbH & Co. KG |
| LANXESS |
| Remmers Group AG |
| Arxada |
| Koppers Performance Chemicals |
| Viance |
| Troy Corporation |
| Lonza Group |
| Others |
Supply & Pricing Matrix
Class I railway operators and national homebuilder procurement programs concentrate buying power across North American and European preservative markets, anchoring contract-based long-term offtake pricing that compresses spot-market premiums for copper compound and borate formulations.
Pricing Analysis
Volume concentrates in fixed-price municipal contracts for railway ties and utility poles, while margins expand in specification-grade marine treatments. Three-tier pricing structure across premium, standard, and economy levels separates ISO-certified export-grade copper azole from domestic construction-grade alkaline copper quaternary and unbranded borate commodity formulations. Price differentiation hinges on certification tier and volume scale, with EPA-registered label claims commanding premiums. Cost compression in standard-tier residential decking is intensifying because London Metal Exchange copper volatility exposes formulators to margin erosion. Infrastructure developers show lowest price sensitivity due to multi-year replacement cycles, while packaging plants and agricultural equipment producers drive spot-market discounting.
Supply Chain Analysis
Copper carbonate and copper oxide feedstock supply rests on Chilean mining operations, Turkish and Californian borate deposits, and German specialty chemical synthesis. Refined boron compound production draws from Turkish state-controlled and California desert operations that together anchor two-thirds of global capacity. Sol-gel silica nanoparticles for marine coatings hinge on Japanese and Australian materials science suppliers. Single-source vulnerability in borate mining creates geographic chokepoints for waterborne preservative manufacturers. Distribution runs through direct mill-treater relationships in British Columbia and the US Pacific Northwest, compressing independent chemical distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around backward-integrated sawmill groups and multi-year supply agreements, with EPA FIFRA registration timelines and copper price volatility forcing independent regional treaters toward acquisition or exit.
For Market Incumbents: Anchor market position through captive borate sourcing agreements with Turkish or Californian deposit operators, insulating margin predictability from London Metal Exchange swings. Deepen technical service capabilities for railway tie replacement programs in Germany and France, where REACH creosote authorization pressure is accelerating copper azole specification. Defend against micronized copper dry-formulation entrants by retrofitting pressure plants for flexible batch sizes closer to lumber sources. For New Entrants and Emerging Players: Launch via waterborne coating specialization targeting Yangtze River Delta export-oriented sawmills seeking GB standard compliance for Southeast Asian construction markets. Penetrate India's BIS-certified railway sleeper and utility pole segments as rural electrification expands addressable volume. White-space exists in nanocoating marine piling specifications for Australian and Japanese port authorities piloting thinner-film performance. For Investors and Strategic Acquirers: The window for entry favors mid-scale treaters with ISO-certified production capacity and established mill relationships in export-corridor geographies. Long-term viability rests on captive access to compliant active ingredient supply chains as MEE discharge rules and REACH emission thresholds elevate regulatory barriers. Acquisition targets should demonstrate technical service teams capable of retention calibration across wood species density variations. Watch pending creosote railway restrictions in Central Europe as inflection indicator for copper azole volume migration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borate Mining | Turkish and Californian deposit control secures supply continuity against geographic chokepoints. |
| Pressure Plant Retrofit for Dry-Formulation Delivery | Micronized copper carbonate handling eliminates slurry infrastructure and enables smaller-batch operations. |
| Railway Sector Technical Service Expansion | German and French REACH authorization pressure accelerates copper azole crosstie replacement evaluation. |
| Waterborne Coating Line Conversion | European decking manufacturers adopt low-leachate systems to meet ECHA copper emission thresholds. |
| ISO Certification for Export Market Access | China's MEE discharge rules create two-tier market favoring certified producers for Southeast Asian slots. |
Research Methodology
Independent corroboration across pressure-treatment plant managers, procurement leads at North American Class I railways, European railway operator technical directors, and marine contractor specification engineers underwrites the qualitative findings. Primary interviews with sawmill group chemical procurement officers and distribution channel partners in British Columbia, the US Pacific Northwest, and Germany were cross-referenced against customs and trade data, SEC 10-K filings of integrated forest products companies, and ECHA authorization documentation. Bottom-up volume estimates from retention-level specifications by application exposure were reconciled with top-down chemical production capacity assessments.
Across the analysis window, forecasts were anchored to historical railway tie replacement cycles, residential construction permit trends, and treated-wood infrastructure investment patterns in India and China. Segmentation modeling incorporated active ingredient chemistry family, decay hazard classification, coating delivery technology, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion announcements. Forecast inputs included London Metal Exchange copper price scenarios and REACH authorization timelines for creosote alternatives.
The model assumes a particular technology adoption path; alternative pathways for micronized copper dry-formulation or sol-gel nanocoating penetration would alter the outlook. Forecasts reflect assumptions regarding EPA FIFRA registration continuity, borate mining license renewals, and railway operator specification inertia. A small set of triggers—pending German and French creosote restrictions, Indian BIS certification enforcement, and Chinese MEE discharge rule expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Diphenyl Sulfone Market
Chemicals
Saudi Arabia Construction Chemicals Market
Chemicals
Silicone Textile Softeners Market
Chemicals
Global Methyl Methacrylate (MMA) Monomer Market
Chemicals
Ferric Fluoride Market
Chemicals
India Methanol Market
Chemicals
Hypophosphorous Acid Market
Chemicals
Aircraft Cleaning Chemicals Market
Chemicals
(S)-(+)-2-Amino-1-Propanol Market
Chemicals
Rocket Propellant Chemicals Market
Chemicals
Automotive Appearance Chemicals Market
Chemicals
Hexafluorosilicic Acid Market
Chemicals
Wood Preservation Chemicals Market
Chemicals
Laboratory Chemical Reagents Market
Chemicals
Carbon Tetrachloride Market
Chemicals
Mercuric Chloride Market