
 Sulfur Chemicals Market | 2026-2036
Sulfur Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Sulfur Chemicals Market Analysis
The EU Green Deal is decoupling sulfur chemical demand from carbon-intensive production pathways across European manufacturing clusters. Shell plc leverages its integrated refining-chemicals footprint to sustain captive sulfur recovery operations in the Netherlands and Germany. Georgia Gulf Sulfur Corporation anchors North American supply through specialized elemental sulfur processing and distribution infrastructure. Eastman Chemical Company differentiates via sulfur derivative specialization serving pharmaceutical and agrochemical synthesis requirements.
Sulfur chemicals encompass sulfuric acid, sulfur dioxide, elemental sulfur, and thiol compounds produced through Claus process recovery, contact process oxidation, or petroleum refining extraction, with purity grades and concentration levels determining suitability for industrial synthesis, metal processing, or agricultural nutrient delivery. Sulfuric acid dominates product type volume due to its irreplaceable role in phosphate fertilizer manufacturing and base metal leaching operations. Thiol compounds represent the fastest-expanding product category as pharmaceutical manufacturers expand mercaptan-based active ingredient synthesis and rubber processors adopt specialized vulcanization accelerators.
EPA enforcement of the Clean Air Act shapes sulfur recovery technology mandates for U.S. refiners and chemical manufacturers, while REACH registration requirements govern thiol compound commercialization across EU member states. China's MEE administers dual carbon goals that tighten sulfur dioxide emission limits for industrial facilities in Shandong and Jiangsu provinces. Stakeholders must monitor regulatory divergence between emission trading systems and command-and-control standards as jurisdictions compete for sulfur-intensive industrial investment.
Market Dynamics
The EU F-Gas Regulation is compressing sulfur dioxide handling margins across European chemical clusters, forcing capital reallocation toward recovery system upgrades and emission trading compliance infrastructure.
Growth Catalysts
- Phosphate fertilizer expansion:Brazilian processors are scaling sulfuric acid offtake as domestic phosphate capacity adds new trains. Agricultural modernization programs in India are accelerating sulfur-based nutrient consumption through subsidized distribution networks.
- REACH registration pathways:Thiol compound commercialization across EU member states is streamlining as ECHA dossier requirements clarify mercaptan-based active ingredient categories for pharmaceutical synthesis.
- Dual carbon enforcement:China's MEE is tightening sulfur dioxide emission limits in Shandong and Jiangsu provinces, creating replacement demand for Claus process recovery upgrades in petroleum refining complexes.
Market Restraints
- Feedstock volatility:Elemental sulfur pricing tracks natural gas processing economics, exposing derivative producers to Henry Hub fluctuations without pass-through mechanisms in contract structures.
- Supply concentration:Claus process capacity clusters around integrated refining-chemicals complexes in the US Gulf Coast and Rotterdam-Antwerp corridor, creating geographic vulnerability to hurricane or regulatory shutdowns.
- Substitution pressure:Bio-based acid catalysts and enzymatic processes are displacing sulfuric acid in select pharmaceutical intermediate synthesis, though phosphate fertilizer applications remain technically locked.
Strategic Opportunities
- Battery materials synthesis:Lithium-sulfur battery cathode manufacturing is creating demand for ultra-high-purity sulfur compounds, with South Korean and Japanese cathode producers qualifying new supply sources.
- Carbon border adjustment:The EU CBAM is creating competitive advantage for sulfur recovery operations with verified low-carbon intensity, favoring facilities with integrated hydrogen production or renewable power sourcing.
- Specialty thiol channels:Direct procurement relationships between mercaptan producers and rubber vulcanization accelerator formulators are bypassing traditional distributor networks, capturing margin through technical service integration.
Industry Challenges
- Process safety certification:Sulfur dioxide handling permits require continuous emissions monitoring system validation that extends project commissioning timelines by 8-14 months in jurisdictions with backlogged environmental review queues.
- Claus catalyst replacement cycles:Alumina-based catalyst deactivation in sour gas processing demands scheduled turnaround coordination that conflicts with refinery maintenance windows, compressing available contractor capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulfur Chemicals Market |
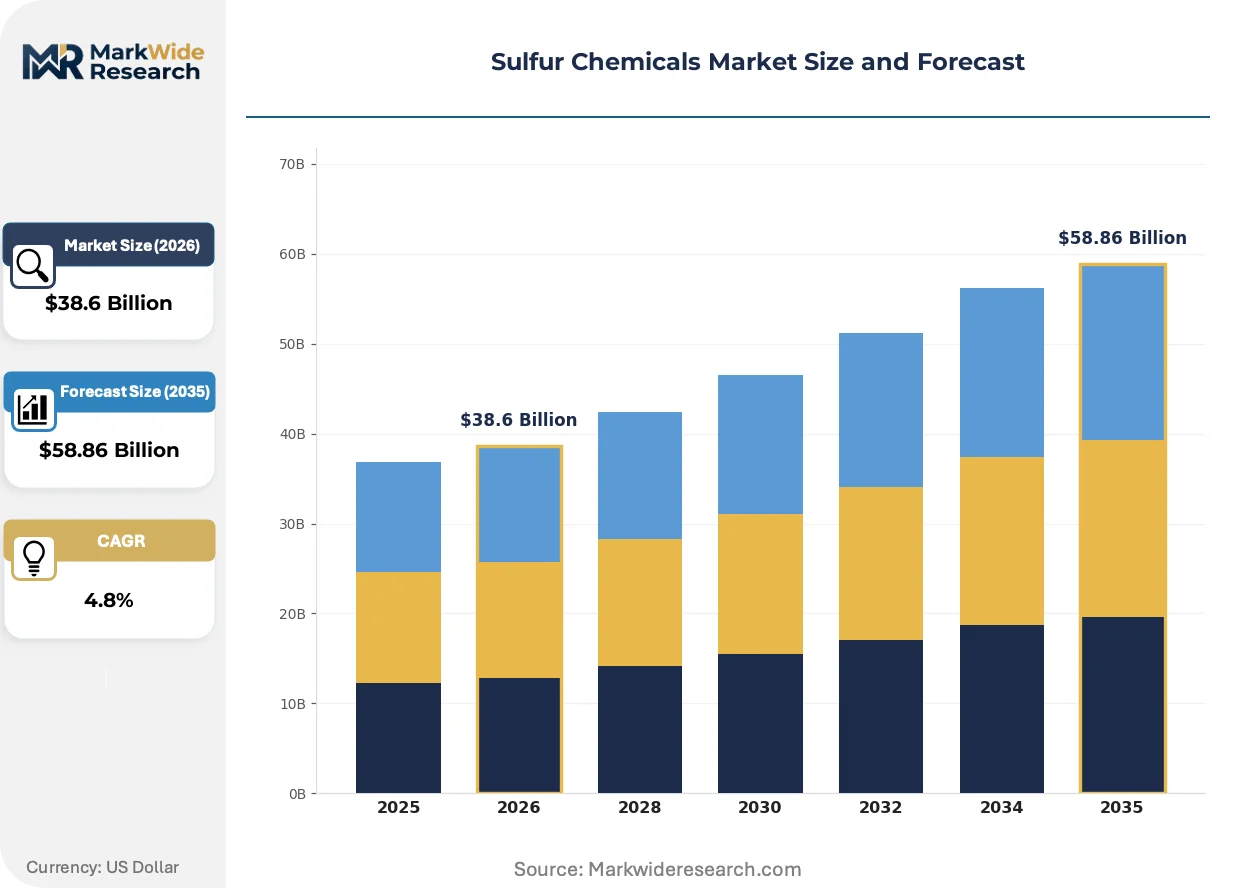
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sulfuric Acid, Sulfur Dioxide, Elemental Sulfur, Thiol Compounds End Use Industry: Agriculture, Pharmaceuticals, Chemical Manufacturing, Textile Application: Fertilizers, Pesticides, Water Treatment, Rubber Processing Delivery Mode: Bulk Shipment, Packaged Supply, On-site Generation, Local Distribution |
| Companies Covered | Saudi Arabian Oil Company, Shell plc, Abu Dhabi National Oil Company, Valero Marketing and Supply Company, China Petroleum & Chemical Corporation (Sinopec), Georgia Gulf Sulfur Corporation, Enersul Limited Partnership, The Dow Chemical Company, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulfur Chemicals Market Emerging Trajectories
Process intensification and emission containment technologies are restructuring capital deployment patterns across sulfur chemical value chains, with digital monitoring systems and modular recovery units displacing conventional centralized infrastructure.
Membrane contactor technology for sulfur dioxide recovery is modularizing acid gas treatment workflows in mid-scale chemical manufacturing. Pharmaceutical and fine chemical producers in Switzerland and the Netherlands are piloting skid-mounted units that bypass fixed-bed absorber construction. This approach is compressing project timelines from 24 months to 8-12 months while enabling relocation between production sites.
The EU F-Gas Regulation is tightening containment and recovery mandates for sulfur dioxide used as process refrigerant and reaction medium. Chemical manufacturers in Germany and Belgium are retrofitting closed-loop handling systems to meet 2027 phase-down targets. Thiol compound processors with fumigation applications face the steepest compliance costs, driving consolidation among smaller formulators unable to fund infrastructure replacement.
Specification-driven procurement is fragmenting sulfuric acid supply relationships in North American metal processing. Copper and rare earth leaching operators are qualifying multiple regional producers against identical purity benchmarks rather than relying on single-source rail delivery. This pattern is most visible in Arizona and Nevada mining corridors, where spot market purchases now supplement term contracts during processing campaign peaks.
Sulfur Chemicals Market Segmentation
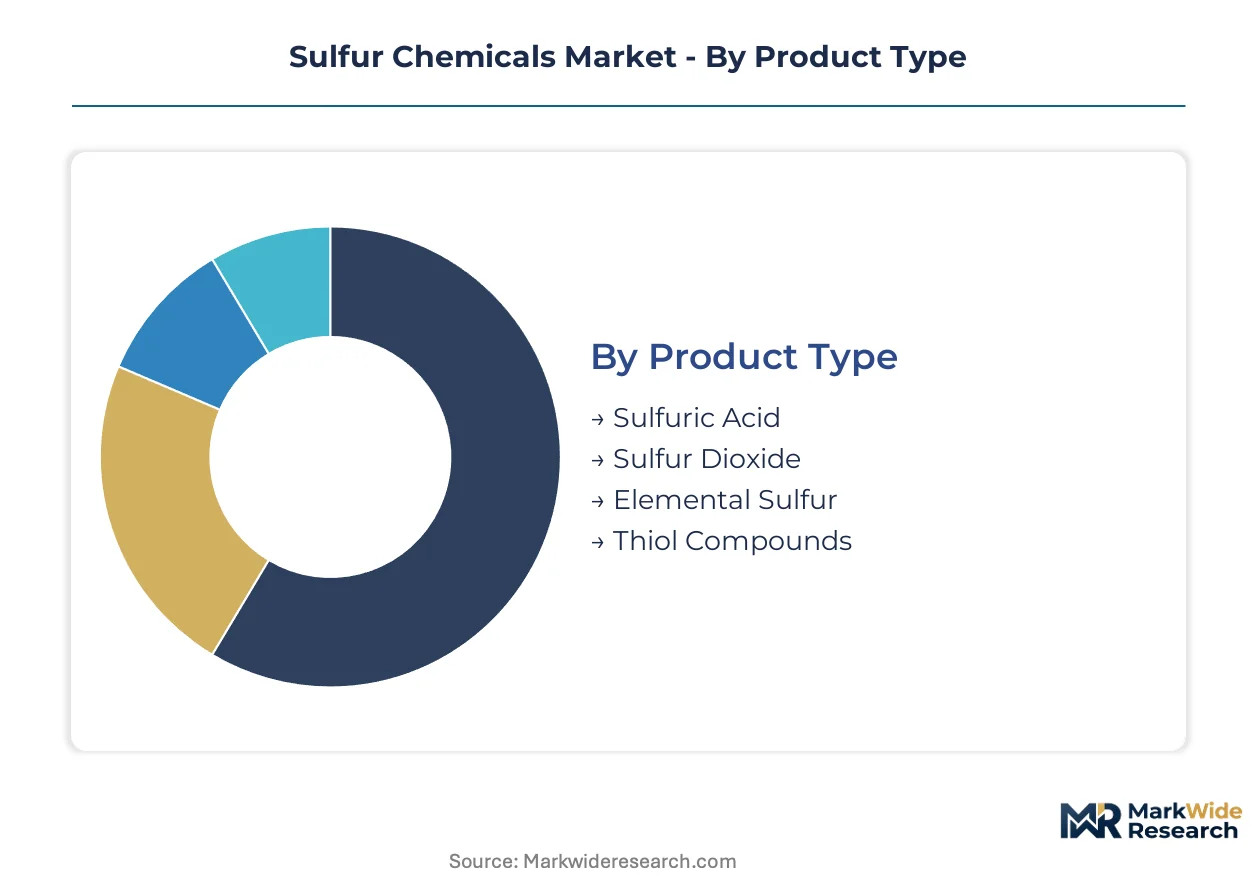
Sulfur chemical procurement patterns diverge sharply across product purity grades and delivery logistics. End-use specifications in phosphate processing versus pharmaceutical synthesis create fundamentally different sourcing relationships and contract structures.
Product Type:
Upgrade cycles and catalyst replacement schedules determine competitive positioning across sulfur chemical categories. Claus process recovery economics and contact process oxidation yields shape relative margin profiles.
- Sulfuric Acid:Contact process oxidation produces concentrations from 93% to 98% for phosphate fertilizer manufacturing and base metal leaching. Brazilian processors are scaling offtake as domestic phosphate capacity expands, while Indian agricultural modernization programs accelerate consumption through subsidized distribution networks.
- Thiol Compounds:Mercaptan-based molecules serve pharmaceutical active ingredient synthesis and specialized rubber vulcanization accelerators. Pharmaceutical manufacturers in Switzerland and the Netherlands are expanding mercaptan-based synthesis capacity, with South Korean and Japanese cathode producers qualifying ultra-high-purity sulfur sources for lithium-sulfur battery manufacturing.
- Sulfur Dioxide:Process refrigerant and reaction medium applications face tightening EU F-Gas Regulation containment mandates.
- Elemental Sulfur:Claus process recovery from petroleum refining and natural gas processing supplies fertilizer and chemical manufacturing feedstock.
Volume placements concentrate in Sulfuric Acid; the faster expansion belongs to Thiol Compounds.
End Use Industry:
Application-specific purity requirements fragment procurement relationships across customer categories. Certification burdens and technical service demands scale with end-use complexity.
- Agriculture:Phosphate fertilizer manufacturing consumes the majority of sulfuric acid volume globally. Brazilian and Indian agricultural modernization programs are driving sulfur-based nutrient consumption through expanding domestic processing capacity and subsidized distribution infrastructure.
- Pharmaceuticals:Mercaptan-based active ingredient synthesis and thiol compound intermediates demand ultra-high-purity specifications. REACH registration pathways through ECHA are streamlining commercialization across EU member states for mercaptan-based therapeutic categories.
- Chemical Manufacturing:Intermediate synthesis and process reagent applications span sulfuric acid, sulfur dioxide, and thiol derivatives.
- Textile:Specialty dye intermediates and fiber processing chemicals utilize controlled sulfur compound formulations.
Procurement volume clusters in Agriculture; margin capture concentrates in Pharmaceuticals.
Application:
Process integration depth varies dramatically across application categories. On-site generation economics and logistics constraints shape competitive boundaries.
- Fertilizers:Phosphate rock acidulation requires 93-98% sulfuric acid at massive scale. Brazilian processors are adding new phosphate processing trains, accelerating sulfuric acid offtake from integrated refining-chemicals complexes.
- Rubber Processing:Vulcanization accelerators and specialty modifiers utilize thiol compounds and sulfur derivatives. Direct procurement relationships between mercaptan producers and rubber formulators are bypassing traditional distributor networks through technical service integration.
- Pesticides:Sulfur-based active ingredients and intermediates serve agricultural protection chemistry.
- Water Treatment:pH adjustment and disinfection byproduct management utilize controlled sulfur dioxide dosing.
Shipment volumes dominate in Fertilizers; technical differentiation concentrates in Rubber Processing.
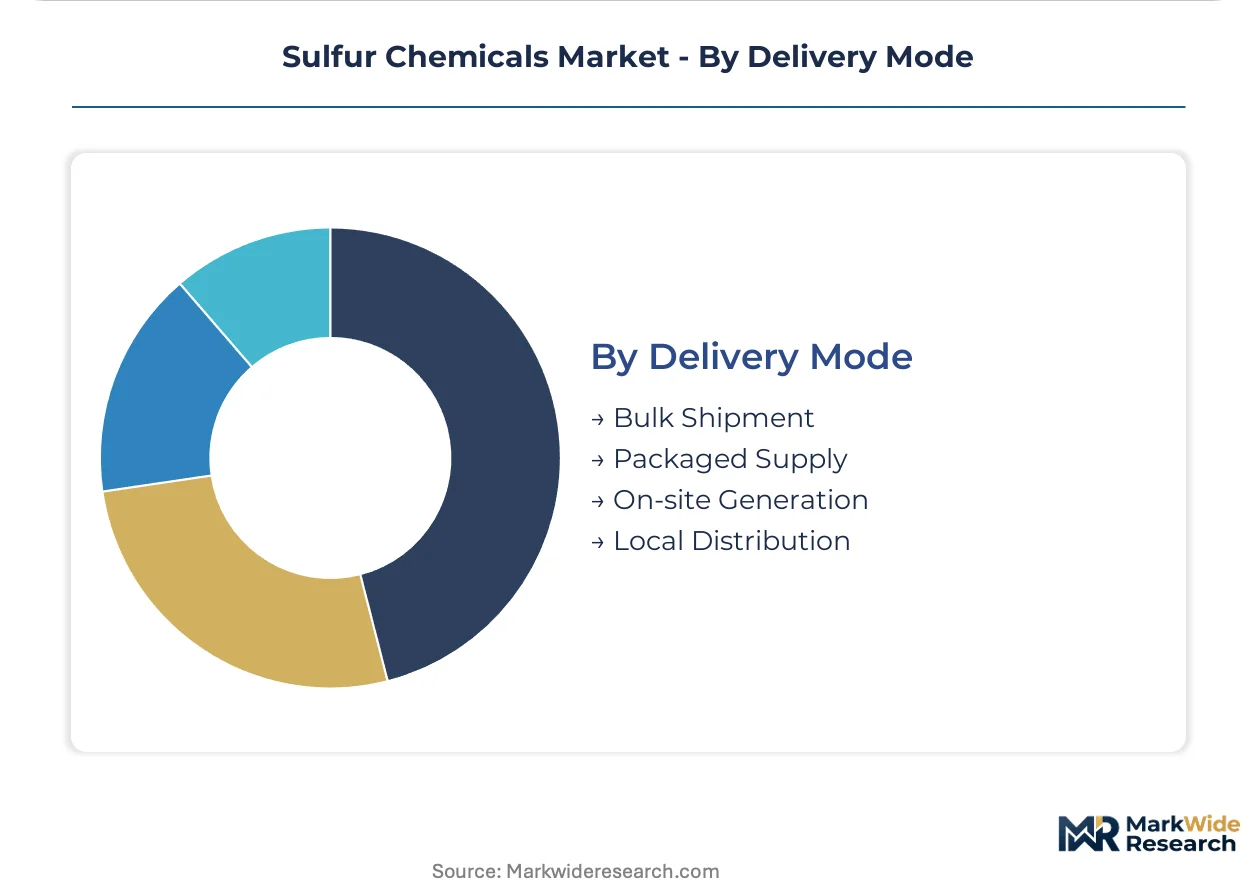
Delivery Mode:
Capital intensity and customer scale requirements stratify competitive participation across logistics configurations. Rail, barge, and pipeline economics favor incumbent infrastructure holders.
- Bulk Shipment:Rail, barge, and dedicated pipeline delivery serves phosphate fertilizer complexes and base metal leaching operations. Arizona and Nevada mining corridors now supplement term contracts with spot market purchases during processing campaign peaks.
- On-site Generation:Sulfuric acid plants integrated with phosphate processing or petroleum refining complexes eliminate transport costs. China's MEE dual carbon enforcement is tightening sulfur dioxide emission limits, creating replacement demand for Claus process recovery upgrades in Shandong and Jiangsu province refining complexes.
- Packaged Supply:Drum and tote delivery serves pharmaceutical and fine chemical producers with lower volume requirements.
- Local Distribution:Regional warehousing and just-in-time delivery supports textile and specialty chemical formulators.
Contract value concentrates in Bulk Shipment; growth momentum favors On-site Generation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in petroleum refining corridors supply consumption centers in phosphate processing and specialty chemical manufacturing. The geographic divide between sulfur recovery capacity and derivative demand shapes trade flows and investment patterns across national boundaries.
United States
Phosphate fertilizer processors in Florida and the Gulf Coast sustain sulfuric acid offtake from integrated refining complexes. EPA Clean Air Act enforcement tightens sulfur dioxide emission limits for Texas and Louisiana facilities. The US Gulf Coast corridor concentrates Claus process capacity, with hurricane exposure creating periodic supply vulnerability.
Brazil
Agricultural modernization programs accelerate sulfur-based nutrient consumption through subsidized distribution networks. ANVISA registration requirements govern thiol compound commercialization for agrochemical synthesis. São Paulo and Minas Gerais host expanding phosphate processing trains that scale sulfuric acid procurement from domestic and import sources.
China
Shandong and Jiangsu province refining complexes face MEE dual carbon enforcement tightening sulfur dioxide emission limits. The Yangtze River Delta concentrates contact process oxidation capacity for domestic fertilizer and metal leaching demand. Replacement investment in Claus process recovery upgrades dominates capital allocation in eastern manufacturing clusters.
Germany
Chemical manufacturers in the Rhine-Ruhr and Ludwigshafen corridors retrofit closed-loop sulfur dioxide handling systems to meet EU F-Gas Regulation 2027 phase-down targets. REACH registration through ECHA streamlines thiol compound commercialization for pharmaceutical synthesis. The Rotterdam-Antwerp pipeline corridor feeds German processing capacity with refinery-sourced feedstock.
India
Subsidized fertilizer distribution infrastructure accelerates sulfur-based nutrient consumption in agricultural modernization programs. BIS certification requirements govern sulfuric acid purity grades for domestic phosphate processing. Gujarat and Maharashtra host expanding phosphate capacity that draws sulfur supplies from Middle East import sources and domestic refining.
Sulfur Chemicals Market Vendor Landscape
The competitive structure tilts toward integrated petroleum refining operators with captive sulfur recovery capacity. National oil companies and multinational energy majors dominate upstream supply positions through Claus process economics. Three archetypes prevail: integrated refining-chemicals conglomerates with backward integration into sour gas processing, specialized elemental sulfur processors focused on distribution logistics, and diversified chemical manufacturers with sulfur derivative specialization. Capacity expansion and emission compliance infrastructure represent the dominant competitive moves as regulatory tightening accelerates capital deployment.
Within the integrated refining tier, Saudi Arabian Oil Company and Abu Dhabi National Oil Company anchor Middle East supply positions through petroleum extraction scale. Shell plc exemplifies the European integrated model with refining-chemicals footprint in the Netherlands and Germany. Georgia Gulf Sulfur Corporation occupies the specialized North American distribution archetype, while Eastman Chemical Company represents diversified chemical manufacturers with sulfur derivative focus. These entities collectively illustrate how geographic proximity to feedstock sources and regulatory jurisdiction shape competitive positioning across the value chain.
| Leading Market Players |
|---|
| Saudi Arabian Oil Company |
| Shell plc |
| Abu Dhabi National Oil Company |
| Valero Marketing and Supply Company |
| China Petroleum & Chemical Corporation (Sinopec) |
| Georgia Gulf Sulfur Corporation |
| Enersul Limited Partnership |
| The Dow Chemical Company |
| Eastman Chemical Company |
| Others |
Supply Flow & Price Mechanics
Henry Hub natural gas pricing cascades through sulfur chemical value chains into contract structures that stratify across fertilizer-grade bulk deliveries and pharmaceutical-grade specialty shipments. Feedstock volatility at the extraction layer compresses margins for derivative producers lacking pass-through mechanisms, while integrated refiners with captive Claus process capacity capture pricing power through backward control over sour gas processing economics.
Pricing Analysis
Yield-guaranteed pricing for phosphate fertilizer processors anchors contract structures, with Brazilian and Indian offtake agreements tying sulfuric acid tariffs to phosphate rock throughput volumes rather than spot commodity indices. Price differentiation separates technical-grade bulk shipments from battery-material purity tiers certified by cathode producer qualification protocols. Cost compression in standard fertilizer-grade supply is intensifying because specification-driven procurement in North American metal leaching fragments historical single-source relationships. Phosphate processors exhibit highest price sensitivity due to thin acidulation margins, while lithium-sulfur battery cathode producers absorb premium pricing for ultra-high-purity sulfur compounds without volume negotiation.
Supply Chain Analysis
Regional distribution centers in the US Gulf Coast and Rotterdam-Antwerp corridor warehouse elemental sulfur for just-in-time delivery to phosphate processing complexes. Geographic supply concentration clusters in the United States, Saudi Arabia, and the Netherlands through integrated refining-chemicals infrastructure. Raw material dependencies rest on sour natural gas processing economics, alumina-based Claus catalyst replacement cycles, and petroleum refining throughput volumes. Single-source vulnerability from hurricane exposure along the US Gulf Coast creates periodic supply disruption risk. Distribution runs through dedicated pipeline corridors, rail bulk shipment contracts, and barge logistics serving coastal processing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane contactor technology for sulfur dioxide recovery is displacing fixed-bed absorber infrastructure, compressing project timelines from twenty-four months to eight-to-twelve months and enabling modular relocation between production sites.
For Market Incumbents: Anchor competitive position through captive sulfur recovery capacity expansion in Shandong and Jiangsu province refining corridors where China's MEE dual carbon enforcement tightens emission limits. Prioritize backward integration into sour gas processing infrastructure to insulate margin structures from Henry Hub volatility. Defend against membrane contactor substitution by embedding continuous emissions monitoring certification into technical service offerings for pharmaceutical and fine chemical customers. For New Entrants and Emerging Players: The premium-to-economy price gap in thiol compound supply creates entry opportunity for mercaptan producers capable of bypassing traditional distributor networks through direct procurement relationships with rubber vulcanization accelerator formulators. Target battery materials synthesis segments in South Korea and Japan where cathode producers actively qualify new ultra-high-purity sulfur sources. Pursue technical service integration as the primary go-to-market angle, capturing margin through formulation support rather than commodity volume plays. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized elemental sulfur processors with distribution logistics infrastructure in North American corridors where EPA Clean Air Act enforcement accelerates consolidation among smaller formulators unable to fund closed-loop handling system retrofits. Long-term viability across the analysis window hinges on positioning for EU CBAM competitive advantage through verified low-carbon intensity sulfur recovery operations. Monitor lithium-sulfur battery cathode manufacturer qualification timelines as the critical inflection signal for specialty sulfur compound demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sour Gas Processing | Captive Claus process capacity insulates margin structures from Henry Hub feedstock volatility for integrated operators. |
| Membrane Contactor Technology Deployment | Modular skid-mounted units compress project timelines and enable relocation between Swiss and Dutch pharmaceutical production sites. |
| EU F-Gas Regulation Compliance Infrastructure | Closed-loop sulfur dioxide handling retrofits in Germany and Belgium secure operating permits through 2027 phase-down targets. |
| Battery Materials Synthesis Qualification | Ultra-high-purity sulfur compound certification with South Korean and Japanese cathode producers opens premium pricing tiers. |
| Specification-Driven Procurement Relationships | Direct technical service contracts with Arizona and Nevada copper leaching operators fragment historical single-source rail dependencies. |
Methodological Framework
Independent corroboration across plant managers at integrated refining-chemicals complexes, procurement leads at Brazilian phosphate fertilizer processors, distribution channel partners in the Rotterdam-Antwerp corridor, and technical R&D directors at mercaptan specialty manufacturers underwrites the qualitative findings in this study. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from disclosed sulfur chemical operations, and EPA enforcement action records. Bottom-up capacity and consumption estimates were triangulated against top-down macroeconomic indicators across the analysis window.
Rate-of-change decomposition across sulfuric acid grade tiers, thiol compound purity specifications, end-use industry concentration, and regional production hub economics structured the analytical framework. CAGRs were derived from segmented volume trajectory modeling incorporating phosphate fertilizer capacity expansion timelines, lithium-sulfur battery cathode commercialization curves, and EU F-Gas Regulation compliance investment cycles. Forecast inputs included Claus process recovery upgrade schedules in Chinese refining complexes and REACH registration pathway progressions for mercaptan-based pharmaceutical categories.
Inputs from plant-level interviews and regulatory filing databases were available through the study window; gaps in real-time inventory positioning data from private sulfur trading operations introduce uncertainty bands around short-term price trajectory assumptions. Forecasts reflect documented assumptions regarding emission limit enforcement intensity and battery materials synthesis scale-up velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
1, 4 Butanediol Market
Chemicals
Ferric Phosphate Market
Chemicals
Inorganic Chemicals Market
Chemicals
Sodium Azide Market
Chemicals
Cumene Market
Chemicals
Europe Textile Chemicals Market
Chemicals
Africa Sodium Cyanide Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Xanthates Market
Chemicals
North America Methanol Market
Chemicals
Europe Biguanide Market
Chemicals
North America Construction Chemicals Market
Chemicals
Aromatic Polyamine Market
Chemicals
Bronopol Market
Chemicals
Formalin Vials Market
Chemicals
Betaine Market