
 Hypophosphorous Acid Market | 2026-2036
Hypophosphorous Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Hypophosphorous Acid Market Analysis
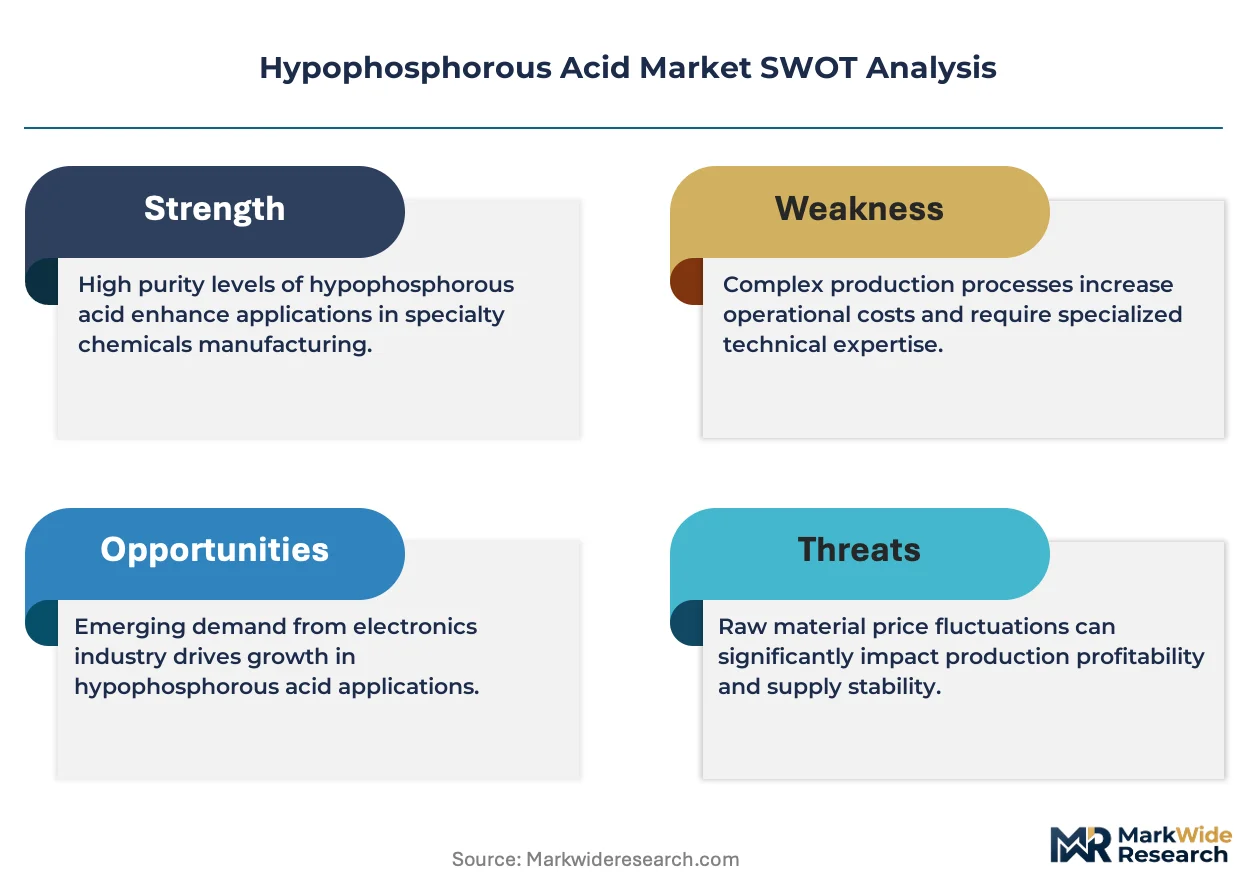
ISO 9001 certification timelines for specialty chemical producers is collapsing, compressing the window for new entrants to establish credible supply relationships. Arkema sustains European market presence through backward integration into phosphorus raw material sourcing. Hubei Lianxing Chemical dominates Chinese production capacity with integrated manufacturing from yellow phosphorus through finished acid derivatives.
Hypophosphorous acid (HPA, H₃PO₂) functions as a powerful reducing agent with a phosphorus oxidation state of +1, manufactured primarily via phosphorus trichloride hydrolysis or direct oxidation of white phosphorus. Industrial grade material serves electroplating baths as a stabilizer for nickel deposition, while reagent grade supplies pharmaceutical and laboratory synthesis requiring sub-ppm metallic impurity thresholds. Electroplating applications anchor volume demand through electronics sector procurement, whereas pharmaceutical grade commands premium positioning due to stringent USP and EP monograph compliance. Chemical synthesis pathways for agrochemical intermediates represent the fastest-expanding application segment as phosphorus-based crop protection chemistry diversifies.
EPA hazardous substance reporting under TSCA Section 8 shapes domestic manufacturing transparency requirements for phosphorus compound handlers. REACH registration obligations in Europe restrict non-compliant import volumes, while China's MEE enforces wastewater discharge standards that elevate treatment capital for HPA producers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate compliance cost asymmetries that will reshape competitive sourcing decisions.
Market Dynamics
Semiconductor fabrication expansion is redrawing procurement patterns for high-purity reducing agents, compressing certification timelines and concentrating qualified supplier relationships around electroplating chemical specialists with proven sub-ppm impurity control.
Growth Catalysts
- Electronics electroplating:Semiconductor foundries in Taiwan, South Korea, and the United States are expanding nickel-phosphorus deposition capacity for advanced packaging substrates, pulling industrial-grade HPA volumes upward.
- REACH registration:European ECHA compliance requirements for phosphorus derivative importers are filtering out non-certified suppliers, tightening supply qualification windows for compliant producers.
- Agrochemical intermediates:Phosphorus-based crop protection chemistry diversification is opening new synthesis pathways requiring HPA as a selective reducing agent for organophosphorus building blocks.
Market Restraints
- Yellow phosphorus input volatility:Thermal process electricity requirements and Chinese environmental enforcement at MEE create feedstock cost instability that propagates through derivative pricing.
- Jiangsu-Gujarat production concentration:Over two-thirds of global merchant capacity sits in two provincial clusters, exposing buyers to localized disruption risks from environmental shutdowns or logistics bottlenecks.
- Sodium hypophosphite substitution:Some electroplating formulations are migrating to solid salt derivatives for handling convenience, capping HPA volume growth in mature nickel bath applications.
Strategic Opportunities
- Indian pharmaceutical grade:CDSCO-aligned USP monograph compliance among domestic producers remains limited, creating white space for import substitution as Gujarat manufacturing clusters upgrade analytical capabilities.
- EPA TSCA Section 8 transparency:Domestic hazardous substance reporting requirements are incentivizing onshore production investment to bypass import documentation complexity and accelerate customer qualification.
- Direct oxidation process convergence:White phosphorus-to-acid continuous flow technologies are reducing PCl₃ intermediate handling, enabling capital-efficient capacity additions at smaller scale.
Industry Challenges
- ISO 9001 certification compression:Specialty chemical buyer qualification cycles have shortened from eighteen months to under nine months, straining documentation and audit resources for new market entrants.
- Multi-jurisdictional compliance stacking:Producers serving both EPA TSCA and REACH-registered customers must maintain parallel analytical protocols and divergent impurity specifications, elevating quality system costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypophosphorous Acid Market |
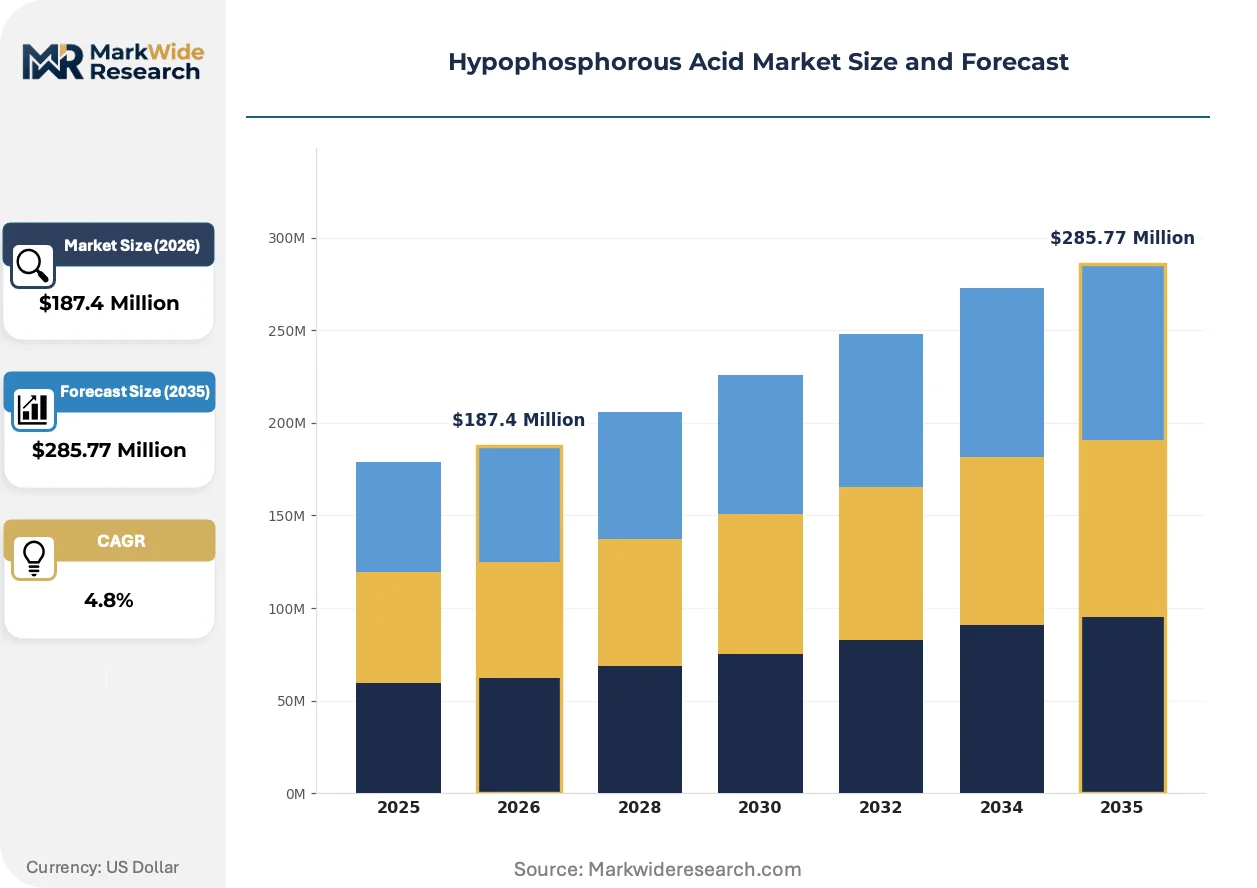
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Reagent Grade, Food Grade, Pharmaceutical Grade Application: Electroplating, Chemical Synthesis, Additive Manufacturing, Pharmaceuticals End User: Electronics, Healthcare, Agriculture, Textiles Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Hubei Lianxing Chemical, Arkema, Richman Chemical Inc, Nacalai Tesque Inc., Honeywell, Merck, Wego Chemical Group Inc, Qingyuan RGDC Chemicals, Solvay SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypophosphorous Acid Market Emerging Trajectories
Process intensification and regulatory transparency mandates are reshaping how HPA is manufactured, tested, and procured, with implications for scale economics and supplier qualification timelines.
Continuous flow white phosphorus oxidation is displacing batch PCl₃ hydrolysis as the dominant production architecture. Taiwanese semiconductor chemical suppliers are adopting this technology for on-site acid generation, eliminating intermediate storage and transportation hazards. The shift is compressing the merchant market for packaged industrial-grade material while elevating technical service requirements around process integration.
REACH Article 33 supply chain communication obligations are forcing downstream electroplating chemical formulators to document HPA provenance through sub-supplier tiers. European ECHA enforcement actions against incomplete registration dossiers are accelerating supplier consolidation among phosphorus derivative traders. Battery and electronics OEMs with EU manufacturing footprints are now mandating full SVHC disclosure from their plating chemical vendors.
Direct mill-to-foundry chemical management contracts are replacing distributor-mediated procurement for high-volume semiconductor electroplating operations. Korean and Japanese electronics manufacturers are consolidating qualified supplier lists to single-source arrangements with technical service integration, bypassing traditional regional chemical distributors. This pattern is most pronounced in Pyeongtaek and Kumamoto semiconductor clusters where bath chemistry optimization is bundled into equipment service agreements.
Hypophosphorous Acid Market Segmentation
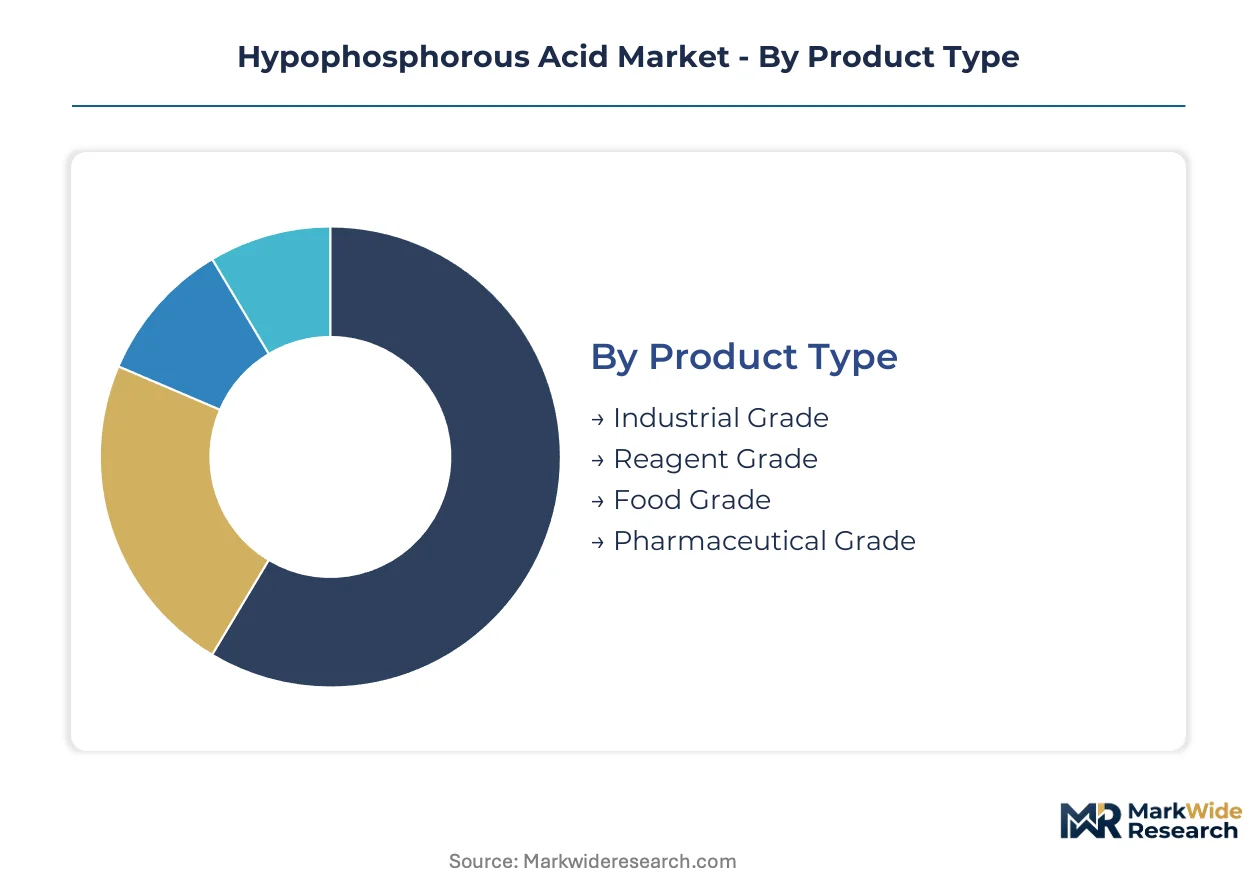
Segmentation in hypophosphorous acid reveals how purity grades, application requirements, and procurement channels create distinct commercial pathways. Each dimension shapes pricing power, qualification timelines, and supplier relationships differently.
Product Type:
Industrial-grade material moves primarily through direct sales to electroplating chemical formulators, while pharmaceutical-grade volumes route through specialized distributors with cold-chain and documentation capabilities.
- Industrial Grade:Contains 30-50% H₃PO₂ with controlled chloride and sulfate levels for nickel bath stabilization. Semiconductor foundries in Taiwan and South Korea pull volumes through mill-to-foundry contracts that bundle technical service with chemical supply.
- Reagent Grade:Achieves 50% concentration with sub-ppm metallic impurities for laboratory synthesis and analytical applications. University procurement consortia and research institute tenders concentrate demand in Germany and Japan where funding cycles drive batch purchasing patterns.
- Food Grade:Meets FCC monograph specifications for antioxidant applications in edible oils and fats. Food additive distributors in the United States and European Union handle regulatory filing support for end-user compliance.
- Pharmaceutical Grade:Complies with USP and EP monographs for API synthesis and excipient functions. CDSCO-registered Indian manufacturers are upgrading analytical capabilities to capture import substitution opportunities in domestic generic drug production.
By volume, Industrial Grade leads. By growth pace, Pharmaceutical Grade is expanding most quickly.
Application:
Cost tier stratification separates commodity electroplating from premium synthesis applications where impurity thresholds justify 3-5x pricing multiples.
- Electroplating:Nickel-phosphorus deposition baths consume industrial-grade HPA as a reducing agent and bath stabilizer. Taiwan Semiconductor Manufacturing and Samsung Foundry procurement teams negotiate multi-year supply agreements with integrated chemical service providers.
- Chemical Synthesis:Agrochemical intermediate production requires selective reduction of phosphorus halides to organophosphorus building blocks. Gujarat-based crop protection manufacturers are expanding captive HPA consumption for glyphosate and phosphonate herbicide diversification.
- Additive Manufacturing:Metal powder reduction and surface treatment applications in aerospace component printing. Powder bed fusion service bureaus in Germany and the United States source through specialized metal powder suppliers rather than direct chemical procurement.
- Pharmaceuticals:Reductive amination and deoxygenation steps in active pharmaceutical ingredient synthesis. Contract development and manufacturing organizations in Switzerland and Singapore qualify suppliers against ICH Q3D elemental impurity guidelines.
Electroplating commands absolute volume share. Pharmaceuticals generates the steepest margin expansion trajectory.
End User:
Customer type determines whether procurement emphasizes technical service integration or transactional price efficiency.
- Electronics:Semiconductor and printed circuit board manufacturers require sub-ppm metallic impurity guarantees with lot-level Certificates of Analysis. Korean chaebol electronics groups consolidate qualified supplier lists to single-source arrangements with embedded process engineering support.
- Healthcare:Pharmaceutical manufacturers and medical device electroplating operations demand USP-grade material with complete supply chain documentation for regulatory audits. European ECHA Article 33 obligations force full SVHC disclosure through sub-supplier tiers.
- Agriculture:Crop protection chemical producers utilize HPA for phosphorus-based herbicide and fungicide intermediate synthesis. Chinese environmental enforcement at MEE is pushing agrochemical manufacturing toward Jiangsu province clusters with integrated wastewater treatment infrastructure.
- Textiles:Flame retardant finishing and dye reduction processes consume lower-purity grades through regional chemical distributors. South Asian garment manufacturing hubs in Bangladesh and Vietnam source through trading companies with limited technical service capabilities.
Electronics procurement concentrates spend among the fewest suppliers. Healthcare qualification cycles run longest but lock in highest switching costs.
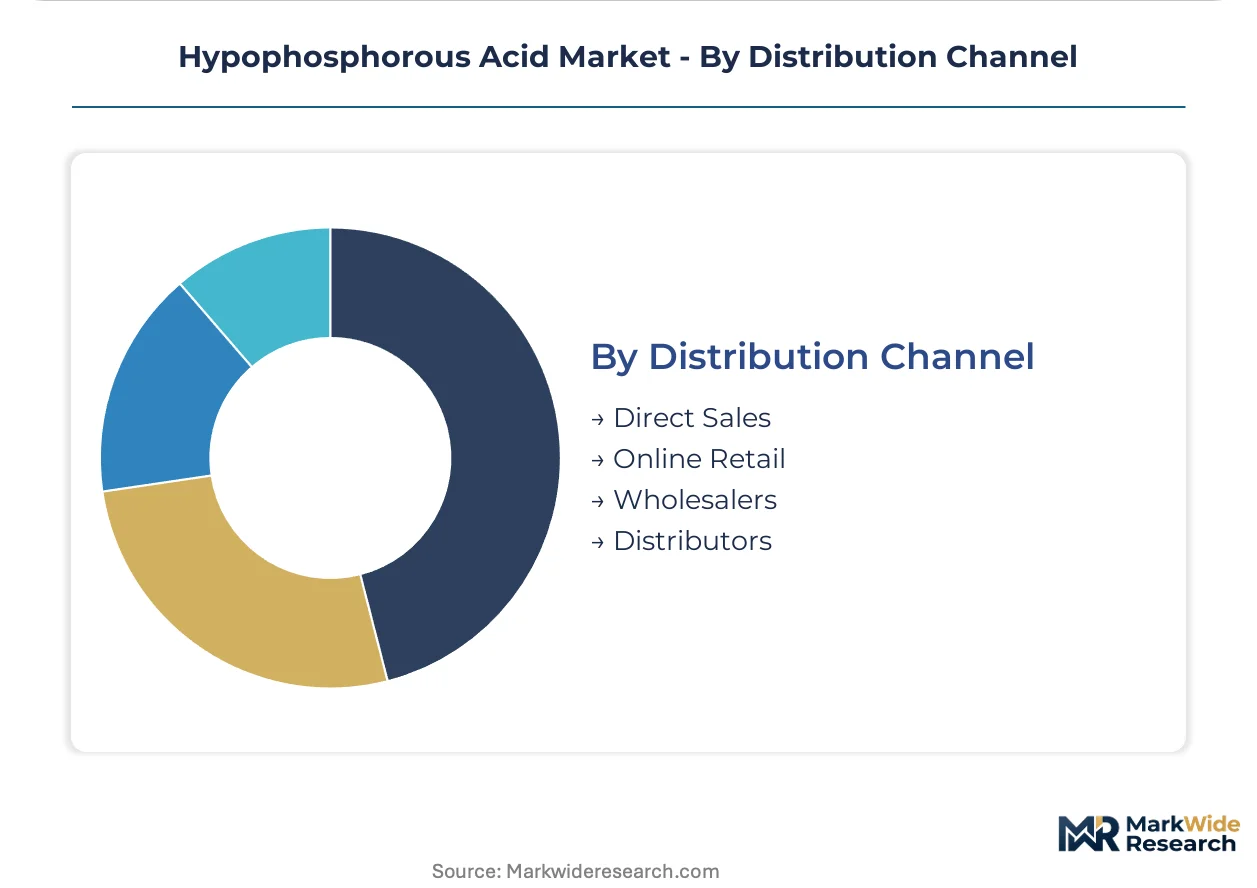
Distribution Channel:
Supply concentration in Jiangsu and Gujarat provinces shapes which channels can reliably source material across geographic markets.
- Direct Sales:High-volume electroplating chemical formulators and semiconductor foundries negotiate mill-direct contracts with fixed pricing and dedicated technical account management. Arkema and Hubei Lianxing Chemical maintain direct sales organizations for top-tier accounts.
- Online Retail:Laboratory-scale reagent grade volumes move through specialty chemical e-commerce platforms with credit card purchasing and next-day delivery. Academic and small R&D customers in the United States and Europe dominate this channel.
- Wholesalers:Regional chemical traders aggregate industrial-grade volumes for resale to smaller electroplating shops and metal finishing operations. Indian wholesale networks in Maharashtra and Tamil Nadu serve fragmented automotive component suppliers.
- Distributors:Full-service chemical distributors provide regulatory documentation, inventory management, and local technical support for pharmaceutical and food-grade applications. European distributors face ECHA registration compliance requirements that filter non-certified traders from the market.
Direct Sales captures the largest contract values. Online Retail is gaining share fastest among new market entrants with limited procurement staff.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor foundries and pharmaceutical manufacturers concentrate procurement power across five national markets where electroplating chemistry and API synthesis drive HPA consumption patterns. Each geography presents distinct regulatory compliance architectures and industrial clustering dynamics.
United States
Domestic semiconductor packaging expansion in Arizona and Texas pulls industrial-grade volumes for nickel-phosphorus deposition baths. EPA TSCA Section 8 hazardous substance reporting mandates transparency from phosphorus compound handlers, elevating documentation burdens on importers. Onshore production investment accelerates near Houston chemical corridors to bypass import complexity.
China
Jiangsu province hosts over half of global merchant capacity with integrated manufacturing from yellow phosphorus through finished derivatives. MEE wastewater discharge enforcement elevates treatment capital requirements for producers in Xuzhou and Nanjing clusters. Environmental shutdowns at MEE discretion expose buyers to localized supply disruption risks.
Germany
Specialty chemical distributors serve pharmaceutical manufacturers in Ludwigshafen and Leverkusen with REACH-registered material requiring full SVHC disclosure. ECHA Article 33 supply chain communication obligations filter non-compliant traders from electroplating chemical procurement channels. BASF-adjacent service providers dominate technical account management for nickel bath formulators.
India
Gujarat manufacturing clusters in Ankleshwar and Vadodara attract agrochemical intermediate producers expanding phosphorus-based crop protection chemistry. CDSCO-aligned USP monograph compliance remains limited among domestic pharmaceutical-grade suppliers, creating import substitution white space. Captive consumption grows for glyphosate and phosphonate herbicide diversification pathways.
South Korea
Pyeongtaek semiconductor foundries consolidate qualified supplier lists to single-source arrangements bundling bath chemistry optimization with equipment service agreements. MFDS pharmaceutical-grade import requirements parallel ICH Q3D elemental impurity guidelines for API synthesis applications. Samsung and SK hynix procurement teams negotiate multi-year technical service contracts with integrated chemical providers.
Hypophosphorous Acid Market Vendor Landscape
Player mix skews toward integrated phosphorus derivative specialists with backward control over yellow phosphorus feedstock. Market structure concentrates around three tiers: multinational chemical conglomerates with REACH-registered European distribution, Chinese provincial champions with captive energy and phosphorus ore access, and regional reagent distributors serving laboratory-scale demand. Dominant competitive moves include direct mill-to-foundry contract consolidation bypassing traditional distributors, and continuous flow process licensing for on-site acid generation at semiconductor clusters.
Within the integrated manufacturing tier, Hubei Lianxing Chemical represents Chinese provincial champion positioning with Xiangyang-based production architecture spanning yellow phosphorus through finished acid derivatives. Arkema exemplifies European multinational structure with phosphorus raw material sourcing integration sustaining REACH-compliant supply relationships. Among laboratory reagent specialists, Nacalai Tesque Inc. and Merck occupy positions serving sub-ppm impurity requirements for pharmaceutical synthesis and analytical applications.
| Leading Market Players |
|---|
| Hubei Lianxing Chemical |
| Arkema |
| Richman Chemical Inc |
| Nacalai Tesque Inc. |
| Honeywell |
| Merck |
| Wego Chemical Group Inc |
| Qingyuan RGDC Chemicals |
| Solvay SA |
| Others |
Supply Flow & Price Mechanics
REACH registration dossiers gate both supplier qualification and price differentiation in European hypophosphorous acid procurement, compressing the compliant supplier pool while elevating premium positioning for ECHA-registered producers serving pharmaceutical and electronics electroplating customers.
Pricing Analysis
Cost-plus contracts with yellow phosphorus indexation dominate industrial-grade procurement for nickel bath formulators, linking quarterly price adjustments to thermal process electricity and feedstock benchmarks. Three-tier pricing structure across pharmaceutical, reagent, and industrial grades separates USP-monograph compliance from standard electroplating specifications. Pricing pressure stems from sodium hypophosphite substitution in mature nickel bath applications. Electronics semiconductor foundries exhibit lowest price sensitivity due to bundled technical service requirements, while textile flame retardant processors in South Asia remain most cost-conscious.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for European electroplating chemical formulators sourcing from Jiangsu province clusters. Merchant capacity concentrates in China, India, and Germany, with over two-thirds of global supply originating in Xuzhou and Ankleshwar manufacturing zones. Raw material dependencies center on yellow phosphorus, thermal process electricity, and chlorine gas for PCl₃ intermediate production. Single-source vulnerability from MEE environmental enforcement actions in Jiangsu threatens supply continuity. Distribution runs through direct mill-to-foundry contracts for high-volume semiconductor customers, bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hypophosphorous acid procurement fragmentation creates niche opportunities as semiconductor packaging diversification and pharmaceutical import substitution reshape qualified supplier requirements across multiple geographies.
For Market Incumbents: Secure backward integration into yellow phosphorus sourcing to buffer feedstock volatility from Chinese MEE enforcement actions. Expand REACH-registered capacity in European chemical corridors to capture electroplating chemical formulators fleeing documentation complexity. Lock in multi-year technical service contracts with Korean and Taiwanese semiconductor foundries before direct oxidation on-site generation displaces packaged acid demand. For New Entrants and Emerging Players: CDSCO fast-track certification for USP-grade production opens white space in Indian pharmaceutical API synthesis supply chains currently dependent on European imports. Target Gujarat agrochemical intermediate producers expanding phosphorus-based herbicide manufacturing with captive HPA consumption models. Pursue continuous flow process licensing agreements with semiconductor chemical suppliers seeking on-site acid generation partnerships. For Investors and Strategic Acquirers: EPA TSCA Section 8 enforcement reshapes the acquisition landscape toward domestic onshore production assets with established hazardous substance reporting infrastructure. Mid-cap phosphorus derivative specialists with integrated manufacturing from ore through finished acid offer strongest five-to-ten-year viability profiles. Monitor ECHA registration renewal deadlines as inflection indicators for supplier consolidation velocity among European traders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Arkema's phosphorus ore sourcing secures REACH-compliant supply independence from Chinese feedstock volatility. |
| Continuous Flow Process Licensing | Taiwanese semiconductor chemical suppliers adopt white phosphorus oxidation to eliminate intermediate storage hazards. |
| CDSCO Certification Investment | Gujarat manufacturers upgrade analytical capabilities to capture domestic pharmaceutical-grade import substitution demand. |
| Direct Mill-to-Foundry Contracts | Samsung Foundry procurement consolidates qualified suppliers to single-source arrangements with embedded process engineering. |
| Long-term Supply Agreement | Electroplating chemical formulators lock in fixed pricing with yellow phosphorus indexation to manage MEE enforcement risk. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with phosphorus derivative plant managers, electroplating chemical procurement leads at semiconductor foundries, REACH registration consultants, and Indian agrochemical R&D directors; and secondary validation through customs trade data, ECHA registration dossiers, SEC chemical sector filings, and Chinese MEE wastewater discharge records. Bottom-up capacity modeling triangulated against top-down demand segmentation across electronics, pharmaceutical, and agrochemical end-uses.
Across the analysis window, forecasts deployed grade-tier, end-use industry, and regional production hub segmentation with CAGRs derived from historical phosphorus derivative demand elasticity and forward capacity addition announcements. Semiconductor fabrication capital expenditure cycles and pharmaceutical API outsourcing trends served as industry-specific demand drivers. Volume and value outputs reflect cross-referencing of merchant capacity utilization rates with electroplating bath chemistry consumption coefficients.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor packaging expansion, stable Chinese environmental enforcement intensity, or continued REACH registration compliance would require recalibration. Forecasts reflect documented assumptions around yellow phosphorus feedstock availability and electroplating formulation substitution rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
Tin Chemicals Market
Chemicals
Potassium Fluoride Market
Chemicals
Copper Oxychloride Market
Chemicals
Bronopol Market
Chemicals
Detergent Alcohols Market
Chemicals
Spirodiclofen Market
Chemicals
Benzoyl Alcohol Market
Chemicals
Diphenylamine (DPA) Market
Chemicals
Latin America Construction Chemicals Market
Chemicals
Global P-Phenylenediamine Market
Chemicals
Thiourea Market
Chemicals
Global Bleaching Agents Market
Chemicals
3-Iodoaniline Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Carbon Tetrabromide Market