
 Potassium Thiosulfate Fertilizer Market | 2026-2036
Potassium Thiosulfate Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Thiosulfate Fertilizer Market Insights
Agricultural cooperatives and direct-to-farm supply chains is reconfiguring how potassium thiosulfate reaches end users in North America. Tessenderlo Group leverages its integrated sulfur chemistry platform to control raw material flows from European production hubs. Mears Fertilizer anchors its position through specialized liquid blending capacity serving the Midwest corn-soy rotation. Hydrite Chemical differentiates via technical service bundling that ties formulation advice to bulk delivery contracts.
Potassium thiosulfate is a crystalline salt with the formula K₂S₂O₃, typically supplied as a clear liquid concentrate containing 25% K₂O and 17% sulfur, manufactured through the reaction of potassium hydroxide with sulfur dioxide and elemental sulfur. Its primary commercial purpose is to deliver dual nutrient availability without chloride or nitrate loading, making it compatible with sensitive high-value crops and fertigation systems where salinity management is critical. Liquid formulations command the dominant volume position due to seamless compatibility with drip irrigation and center-pivot injection equipment, while granular variants occupy niche applications in bulk blending operations where dry spreader compatibility matters. Foliar spray and fertigation application methods are expanding fastest as precision agriculture platforms advance sensor-guided nutrient timing.
EPA fertilizer labeling requirements and state-level nutrient management regulations in Iowa and Florida shape product registration pathways and application rate documentation for potassium thiosulfate suppliers. REACH registration obligations in Europe and China's GB fertilizer standards create divergent compliance burdens that favor producers with multi-jurisdictional regulatory affairs capacity. Stakeholders must monitor how carbon intensity scoring in agricultural supply chains redirects procurement criteria toward low-emission sulfur extraction and processing pathways.
Market Dynamics
Precision agriculture platforms and sensor-guided nutrient timing are compressing application windows and forcing suppliers to integrate real-time agronomic advice with physical delivery infrastructure.
Growth Catalysts
- EPA Fertilizer Runoff Standards:Tightened nutrient management protocols in Iowa and Florida are mandating documented application rates and timing, creating compliance-driven demand for chloride-free potassium sources that integrate with precision systems.
- Fertigation Expansion:Brazil's Mato Grosso soybean belt dominates adoption where center-pivot and drip irrigation systems require liquid-compatible, low-salinity nutrient inputs.
- Foliar Spray Programs:Specialty crop producers in California's Central Valley are expanding canopy-level nutrient delivery to bypass soil fixation losses and target reproductive growth stages.
Market Restraints
- Elemental Sulfur Volatility:Potassium thiosulfate production depends on sulfur dioxide and elemental sulfur feedstocks whose prices fluctuate with oil refining rates and phosphate fertilizer co-production economics.
- REACH Registration Burden:European producers face divergent compliance obligations under ECHA's substance evaluation protocols that favor multi-jurisdictional regulatory affairs capacity.
- Potassium Chloride Substitution:Standard KCl remains entrenched in bulk commodity grain operations where chloride tolerance and cost minimization override specialty nutrient premiums.
Strategic Opportunities
- Carbon Intensity Scoring:Agricultural supply chain procurement criteria are redirecting toward low-emission sulfur extraction pathways, rewarding producers with integrated sulfur chemistry platforms.
- Direct-to-Farm Channels:Agricultural cooperatives are disintermediating traditional distributor networks, creating openings for suppliers with localized liquid blending and technical service bundling.
- Sensor-Guided Timing:Variable-rate application technology convergence with drone-mounted spraying equipment is opening precision foliar segments in high-value perennial crops.
Industry Challenges
- Liquid Blending Capacity Constraints:Regional shortages of specialized storage and batching infrastructure limit rapid scaling in the Midwest corn-soy rotation where demand concentrates.
- Multi-Jurisdictional Registration Timelines:Divergent fertilizer standards across China's GB framework, India's BIS protocols, and Brazil's MAPA requirements stretch product commercialization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Thiosulfate Fertilizer Market |
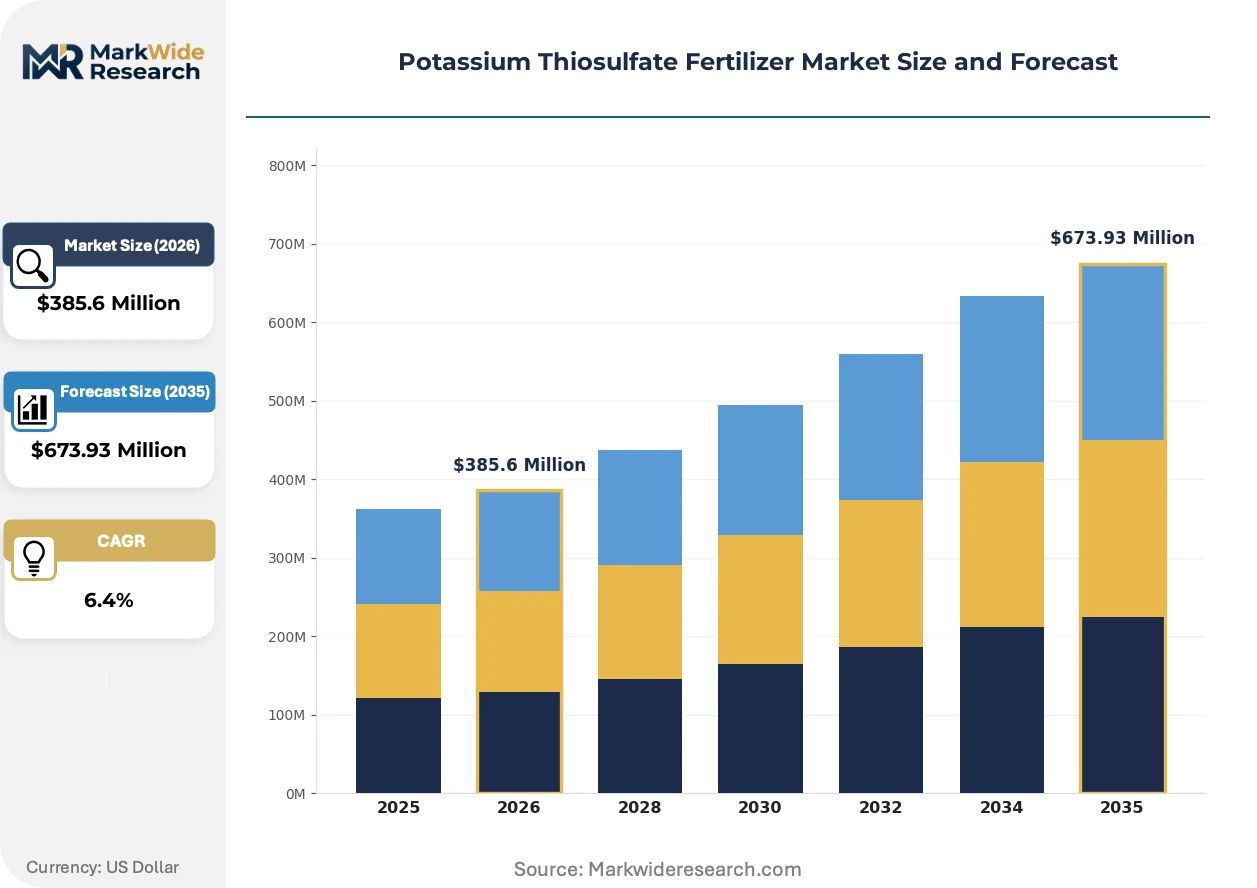
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Granular, Powder, Suspension End Use Industry: Agriculture, Horticulture, Landscaping, Turf Management Application Method: Soil Application, Foliar Spray, Fertigation, Drip Irrigation Distribution Channel: Wholesale, Online, Retail, Agro Dealers |
| Companies Covered | Tessenderlo Group, Mears Fertilizer, Hydrite Chemical, Thatcher Company, Plant Food Company, TIB Chemicals, Omnia Specialities, Nufarm, Spraygro Liquid Fertilizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Thiosulfate Fertilizer Market Trends and Innovations
Real-time soil and tissue analytics are compressing decision cycles from seasonal to weekly intervals, forcing nutrient suppliers to embed data services within physical product relationships.
Variable-rate fertigation controllers equipped with EC and pH sensors are digitizing nutrient delivery in California's Central Valley almond orchards and Florida's citrus groves. Large-scale specialty crop operators are retrofitting existing drip infrastructure with automated injection skids that adjust potassium thiosulfate flow based on continuous sap flow and soil moisture telemetry. This precision layer is digitizing the traditional calendar-based fertilization calendar into responsive, event-triggered protocols that minimize leaching losses.
REACH registration obligations under ECHA's 2023 updated evaluation criteria are tightening documentary requirements for sulfur-containing fertilizer intermediates entering European customs territories. The industrial consequence is a bifurcation between integrated producers with in-house regulatory affairs teams and traders dependent on third-party registration holders. Specialty liquid blenders in the Netherlands and Germany are responding by consolidating formulation activities within vertically controlled facilities to maintain substance volume tracking.
Buyer concentration among agricultural cooperatives is consolidating procurement decisions previously fragmented across independent retail agronomists. The channel being disrupted is the traditional three-step distributor-dealer-grower hierarchy, replaced by direct contracting between cooperative supply managers and bulk liquid terminals. This disintermediation is most visible in the US Corn Belt where regional cooperatives now operate captive rail receiving and on-farm delivery fleets, compressing supplier margins while demanding embedded technical advisory services.
Potassium Thiosulfate Fertilizer Market Segmentation
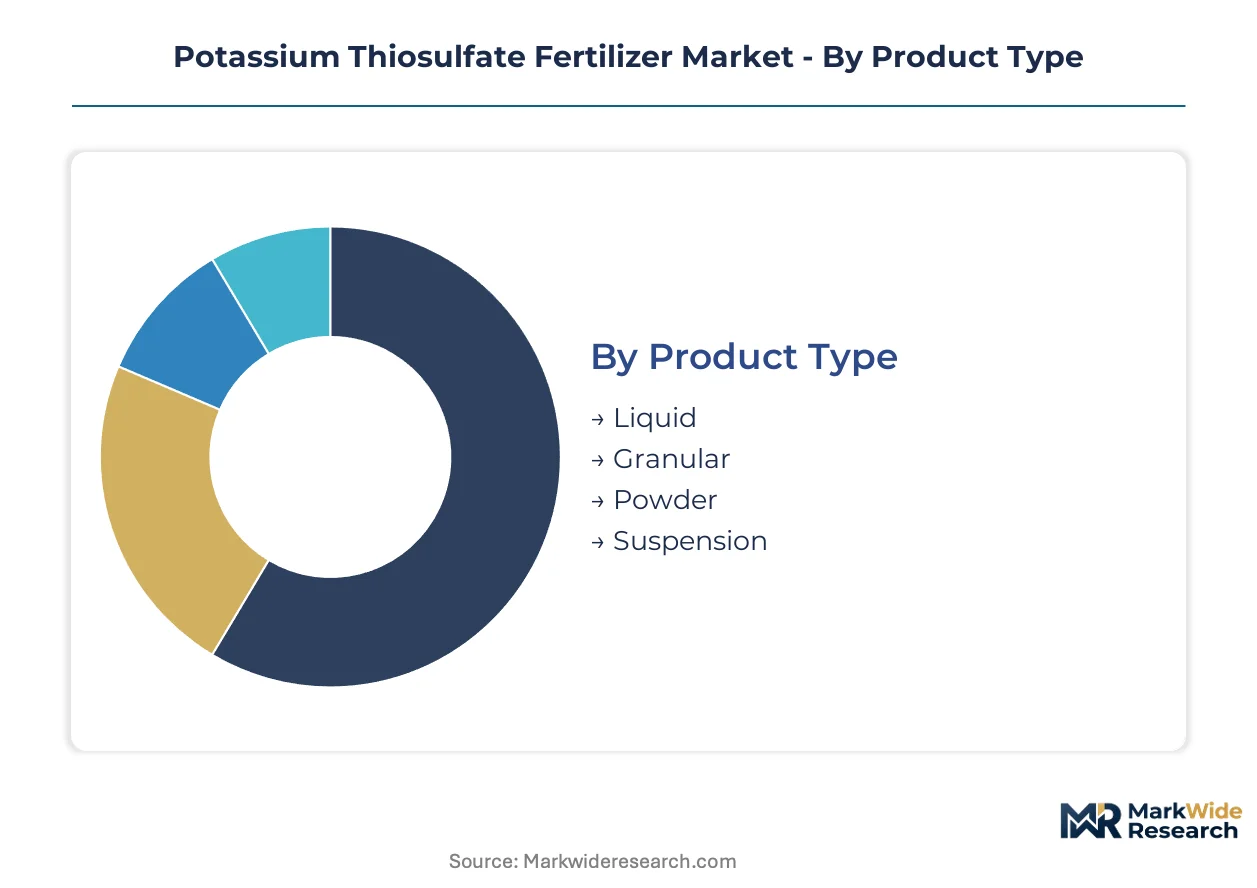
Potassium thiosulfate formulations diverge sharply across physical states and delivery modes, with each segment demanding distinct manufacturing assets and logistics infrastructure. Understanding these divides clarifies why liquid concentrates dominate fertigation while dry forms persist in bulk blending.
Product Type:
The use-case spectrum spans from precision drip systems requiring pumpable solutions to dry spreader equipment demanding free-flowing granules.
- Liquid:Clear concentrates containing 25% K₂O and 17% sulfur integrate seamlessly with center-pivot injection and drip irrigation equipment. Demand concentrates in Brazil's Mato Grosso soybean belt where fertigation systems require chloride-free, low-salinity nutrient inputs compatible with automated injection skids.
- Granular:Crystalline salt formulations engineered for dry spreader compatibility serve bulk blending operations in the Midwest corn-soy rotation. Regional shortages of specialized liquid storage infrastructure reinforce granular persistence where dry fertilizer terminals dominate supply chains.
- Powder:Fine-particle variants target specialized foliar spray formulations requiring rapid dissolution in tank-mix applications.
- Suspension:Concentrated slurries bridge liquid handling convenience with higher nutrient density for high-volume agricultural cooperatives.
Established volume favors Liquid; emerging adoption favors Suspension.
End Use Industry:
Customer sophistication varies from commodity grain operations to sensor-guided perennial crop management.
- Agriculture:Broadacre grain and oilseed production drives baseline demand through fertigation and soil application methods. Brazil's soybean belt and the US Corn Belt anchor volume where potassium chloride substitution faces chloride sensitivity constraints.
- Horticulture:High-value fruit and vegetable operations in California's Central Valley deploy foliar spray programs to bypass soil fixation losses during reproductive growth stages.
- Landscaping:Turf establishment and ornamental maintenance applications favor granular formulations compatible with broadcast spreaders.
- Turf Management:Golf courses and sports fields demand chloride-free potassium sources where salinity stress compromises turf quality.
Revenue concentration sits with Agriculture; margin expansion favors Horticulture.
Application Method:
Precision agriculture platforms are compressing application windows and forcing method-specific formulation engineering.
- Fertigation:Nutrient injection through irrigation systems demands liquid compatibility and precise EC control. Variable-rate controllers equipped with pH sensors are digitizing delivery in California almond orchards and Florida citrus groves.
- Foliar Spray:Canopy-level nutrient delivery targets reproductive growth stages with rapid uptake timing. Specialty crop producers are expanding programs as drone-mounted spraying equipment opens precision segments.
- Soil Application:Traditional broadcast or banded placement persists in commodity grain operations where cost minimization overrides specialty nutrient premiums.
- Drip Irrigation:Micro-irrigation compatibility requires filtered, low-precipitate formulations to prevent emitter clogging in high-frequency delivery systems.
Technology investment flows toward Fertigation; biological efficacy advantages favor Foliar Spray.
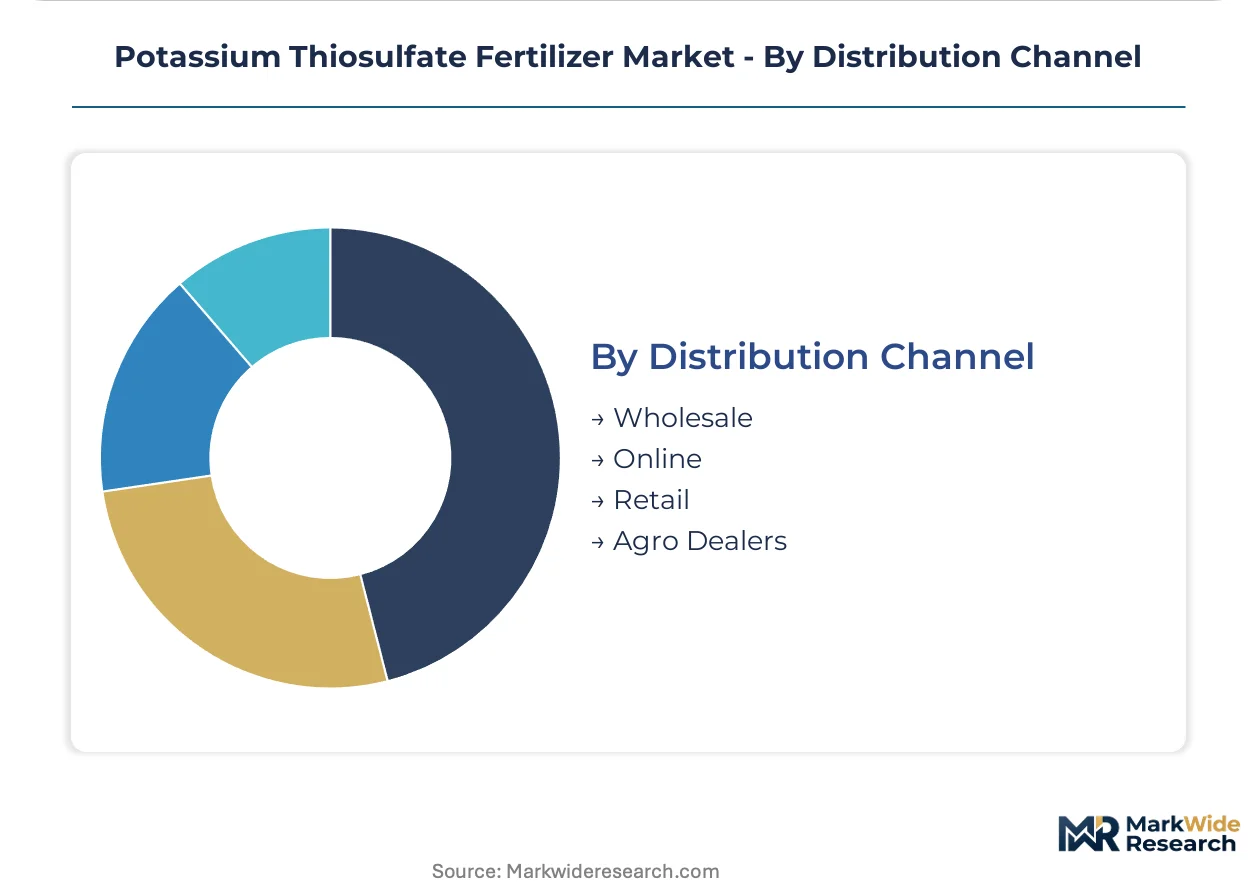
Distribution Channel:
Channel power is shifting from independent retail networks to consolidated cooperative procurement.
- Agro Dealers:Traditional agronomy-led retail maintains penetration through embedded soil testing and recommendation services.
- Wholesale:Bulk liquid terminals serve cooperative supply managers with captive rail receiving and on-farm delivery fleets.
- Online:Digital procurement platforms gain traction among smaller specialty crop operators seeking transparent pricing and technical documentation.
- Retail:Garden center and farm supply stores address landscaping and turf management segments with smaller package sizes.
Procurement consolidation strengthens Wholesale; service differentiation preserves Agro Dealers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River barge network and Gulf Coast port terminals enable liquid fertilizer flows into the US Corn Belt, while Brazil's Santos-Itaquí grain corridor anchors South American distribution.
United States
EPA fertilizer labeling requirements and Iowa's nutrient management regulations mandate documented application rates for chloride-free potassium sources. The Midwest corn-soy rotation concentrates demand where agricultural cooperatives operate captive rail receiving terminals. Mears Fertilizer anchors liquid blending capacity across Illinois and Indiana.
Brazil
MAPA fertilizer registration protocols govern import and commercialization of specialty liquid nutrients. The Mato Grosso soybean belt dominates adoption where center-pivot irrigation requires low-salinity inputs compatible with automated injection systems. Regional cooperatives retrofit existing drip infrastructure with variable-rate controllers.
China
GB fertilizer standards and the Ministry of Agriculture's zero-growth chemical fertilizer use policy shape product registration pathways. Shandong Peninsula chemical clusters manufacture sulfur-derived intermediates for domestic formulation. Provincial agricultural bureaus promote fertigation in the Yangtze River Delta vegetable production zones.
Germany
ECHA REACH registration obligations and the EU Green Deal's Farm to Fork Strategy tighten documentary requirements for sulfur-containing fertilizer intermediates. The Rhine-Ruhr industrial corridor hosts integrated sulfur chemistry platforms with captive regulatory affairs capacity. Dutch-German border liquid terminals consolidate formulation activities for cross-border distribution.
Australia
TGA-equivalent agricultural chemical registration and state-level fertilizer quality codes govern import and blending operations. Murray-Darling Basin irrigated horticulture drives demand for chloride-free potassium in almond and citrus orchards. Melbourne-based liquid fertilizer terminals serve southeastern broadacre grain regions.
Potassium Thiosulfate Fertilizer Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The supplier base organizes around three functional layers: integrated sulfur chemistry producers with captive raw material control, regional liquid blenders with specialized storage infrastructure, and technical service bundlers linking formulation advice to delivery contracts. Consolidation pressures concentrate among mid-scale blenders lacking regulatory affairs capacity or backward integration into sulfur feedstocks. Dominant competitive moves include cooperative procurement disintermediation and carbon intensity scoring integration into supply agreements.
Within the integrated chemistry tier, Tessenderlo Group exemplifies European producers with multi-jurisdictional regulatory capacity. Mears Fertilizer occupies a position among North American regional specialists anchored in Midwest liquid blending infrastructure. Hydrite Chemical represents the technical service archetype, bundling formulation advisory with bulk delivery relationships. These three patterns illustrate how geographic concentration, regulatory competence, and service integration separate viable suppliers from margin-compressed commodity traders.
| Leading Market Players |
|---|
| Tessenderlo Group |
| Mears Fertilizer |
| Hydrite Chemical |
| Thatcher Company |
| Plant Food Company |
| TIB Chemicals |
| Omnia Specialities |
| Nufarm |
| Spraygro Liquid Fertilizer |
| Others |
Pricing and Supply Chain Analysis
The Mississippi River barge network's seasonal freight rate volatility compresses margins for liquid fertilizer terminals serving the Midwest corn-soy rotation, concentrating pricing power among suppliers with captive rail infrastructure while forcing smaller blenders toward granular formulations to avoid waterborne logistics exposure.
Pricing Analysis
Three-tier pricing structure across premium certified, standard commercial, and economy bulk levels separates agricultural cooperatives with captive storage from independent retailers and spot-market traders. Price differentiation hinges on EPA compliance documentation and volume-scale procurement commitments. Cost compression in the economy tier is intensifying because agricultural cooperatives consolidate procurement decisions and demand embedded technical services. Commodity grain operations exhibit highest price sensitivity, while California specialty crop producers prioritize chloride-free certification over unit economics.
Supply Chain Analysis
Extended payment terms from agricultural cooperatives and supply-chain finance facilities from integrated sulfur chemistry producers are reshaping working capital requirements for regional blenders. Manufacturing concentrates in Belgium, Germany, and China's Shandong Peninsula, drawing from elemental sulfur, potassium hydroxide, and sulfur dioxide feedstocks. Single-source vulnerability sits with phosphate fertilizer co-production economics that govern sulfur dioxide availability. Distribution runs through cooperative-operated rail receiving terminals and captive on-farm delivery fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Potassium thiosulfate demand tracks the agricultural input cycle, with recovery signals emerging from Brazil's Mato Grosso irrigation expansion and California's almond orchard replanting programs.
For Market Incumbents: Insulate margin position through backward integration into sulfur feedstocks and captive regulatory affairs capacity spanning EPA, REACH, and MAPA protocols. Tessenderlo Group's integrated sulfur chemistry platform exemplifies this defensive posture against commodity traders lacking multi-jurisdictional registration teams. Capacity addition in Brazil's Santos-Itaquí corridor anchors South American supply security. For New Entrants and Emerging Players: Establish a beachhead in drone-mounted foliar spray services for California Central Valley perennial crops, where sensor-guided nutrient timing creates technical service bundling opportunities absent from commodity grain channels. White-space targets include automated injection skid retrofitting for existing drip infrastructure and carbon intensity scoring certification for European supply agreements. Direct contracting with agricultural cooperatives bypasses traditional distributor-dealer hierarchies. For Investors and Strategic Acquirers: Regional liquid blenders with specialized storage infrastructure and EPA registration pathways represent the priority acquisition archetype, particularly those anchored in Illinois and Indiana rail corridors. Long-term viability rests on consolidation of mid-scale blenders lacking backward integration or regulatory capacity. Watch for carbon intensity scoring integration into cooperative procurement criteria as an inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Feedstocks | Captive supply of elemental sulfur insulates margin from phosphate fertilizer co-production volatility. |
| Multi-Jurisdictional Regulatory Affairs Investment | EPA, REACH, and MAPA registration capacity accelerates product commercialization cycles across North America and Europe. |
| Automated Injection Skid Retrofitting | Variable-rate fertigation controllers digitize nutrient delivery for California almond and Florida citrus operations. |
| Carbon Intensity Certification Program | EU Green Deal procurement criteria redirect supply agreements toward low-emission sulfur extraction pathways. |
| Direct-to-Farm Technical Service Bundling | Agricultural cooperative disintermediation demands embedded agronomic advisory with bulk liquid contracts. |
Research Methodology
Desk research of customs trade data, EPA fertilizer registration databases, and ECHA REACH submission records preceded structured interviews with liquid fertilizer terminal managers, agricultural cooperative supply directors, sulfur chemistry plant engineers, and specialty crop agronomists. Primary fieldwork across Brazil's Mato Grosso, California's Central Valley, and the US Corn Belt was cross-validated against secondary sources including MAPA import statistics and Iowa nutrient management compliance reports. Bottom-up volume modeling triangulated with top-down value estimates across product type, end use, and application method segments.
Assumptions held fixed include EPA fertilizer runoff standards enforcement intensity, Brazil's center-pivot irrigation expansion trajectory, and elemental sulfur price correlation with oil refining rates. Variables stress-tested across the projection horizon encompass REACH registration timeline extensions, agricultural cooperative procurement consolidation velocity, and drone-mounted spraying equipment adoption curves. Segmentation dimensions modeled include physical formulation state, crop category sensitivity to chloride loading, and distribution channel control structure. CAGRs derived from logistic diffusion curves fitted to fertigation system penetration data and foliar spray program expansion rates.
Stress conditions across sulfur dioxide feedstock availability, MAPA registration approval delays, and cooperative payment term extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and boundary conditions. Macroeconomic commodity cycles, regulatory protocol revisions, or precision agriculture technology disruption would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
United States Micronutrient Fertilizer Market
Fertilizers
Argentina Fertilizer Market
Fertilizers
Catalyst Fertilizers Market
Fertilizers
Fertilizer Applicators Market
Fertilizers
Global Complex Fertilizers Market
Fertilizers
China Micronutrient Fertilizer Market
Fertilizers
Humate Fertilizer Market
Fertilizers
Neem-Based Fertilizers Market
Fertilizers
Sulfur Fertilizer Market
Fertilizers
Russia Micronutrient Fertilizer Market
Fertilizers
Southeast Asia Fertilizer Market
Fertilizers
Blue-Green Algae Fertilizer Market
Fertilizers
Indonesia Fertilizer Market
Fertilizers
Europe Specialty Fertilizer Market
Fertilizers
Crop Micronutrients Market
Fertilizers
Phosphate Fertilizers Market