
 Indonesia Fertilizer Market | 2026-2036
Indonesia Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Fertilizer Market Outlook
Smallholder cooperative consolidation across Java and Sumatra is recalibrating volume negotiations and payment terms for domestic suppliers. PT Pupuk Indonesia (Persero) anchors national distribution through its archipelago-wide terminal network. PT Petrokimia Gresik leverages its integrated phosphate complex to sustain cost leadership in NPK blending. Yara International ASA competes through precision agriculture advisory bundled with premium coated formulations.
Indonesia fertilizer encompasses nitrogen, phosphorus, and potassium compounds formulated to replenish soil macronutrients for commercial crop production, typically manufactured via Haber-Bosch ammonia synthesis, phosphate rock acidulation, or potash refining with granulation to 2-4 millimeter particle size for mechanized spreading. Urea dominates tonnage due to subsidized pricing and established import infrastructure, though coated slow-release variants capture widening margin pools from horticultural exporters. Liquid formulations gain traction in plantation estates where fertigation systems reduce labor intensity, while granular NPK maintains its lock on rice paddy applications through government procurement channels.
Indonesia's Ministry of Agriculture sets subsidized price ceilings and product registration requirements through its fertilizer distribution directives, while BIS-equivalent national standards enforce nutrient content labeling and heavy metal limits. The country's central environmental regulator mandates emission controls on ammonia plants, tightening capital requirements for brownfield urea expansions. Stakeholders must weigh import dependency for potash against domestic natural gas feedstock costs when committing to capacity additions.
Market Dynamics
Indonesia's fertilizer sector is restructuring around smallholder cooperative consolidation, which is compressing supplier margins while redirecting procurement volumes toward integrated distributors capable of offering credit terms and technical advisory bundled with product delivery.
Growth Catalysts
- Ministry of Agriculture Subsidization Policy:Certified organic input subsidies are pulling manufacturer portfolios toward specialty grades with higher margin profiles than commodity urea.
- Sugarcane Belt Intensification:East Java's plantation estates are expanding fertigation infrastructure, creating pull-through demand for liquid formulations and soluble NPK compounds.
- Natural Gas Feedstock Availability:Domestic gas pricing agreements are sustaining cost competitiveness for ammonia synthesis relative to import-dependent regional peers.
Market Restraints
- Potash Import Dependency:Indonesia lacks domestic potash reserves, exposing blenders to Baltic-Canadian supply chain volatility and currency fluctuation risk.
- Environmental Emission Controls:The central environmental regulator's ammonia plant emission mandates are tightening capital requirements for brownfield urea capacity expansions.
- Soil Acidification from Sulfur Deficiency:Intensive cropping without micronutrient replenishment is degrading long-term yield potential in Kalimantan's expanding oil palm frontier.
Strategic Opportunities
- Sulawesi and Papua Frontier Estates:Underpenetrated plantation development in eastern Indonesia offers first-mover positioning for integrated fertilizer-logistics operators.
- Coated Slow-Release Convergence:Polymer coating technology paired with precision agriculture advisory is opening premium segments among horticultural exporters.
- Digital Procurement Platforms:Mobile-enabled cooperative aggregation tools are emerging as a channel innovation to bypass traditional distributor layers.
Industry Challenges
- Agronomist Talent Scarcity:Field advisory capacity lags behind cooperative demand for soil testing and prescription blending services.
- Product Registration Timelines:Ministry of Agriculture certification delays for new formulations extend commercialization cycles beyond planting season windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Fertilizer Market |
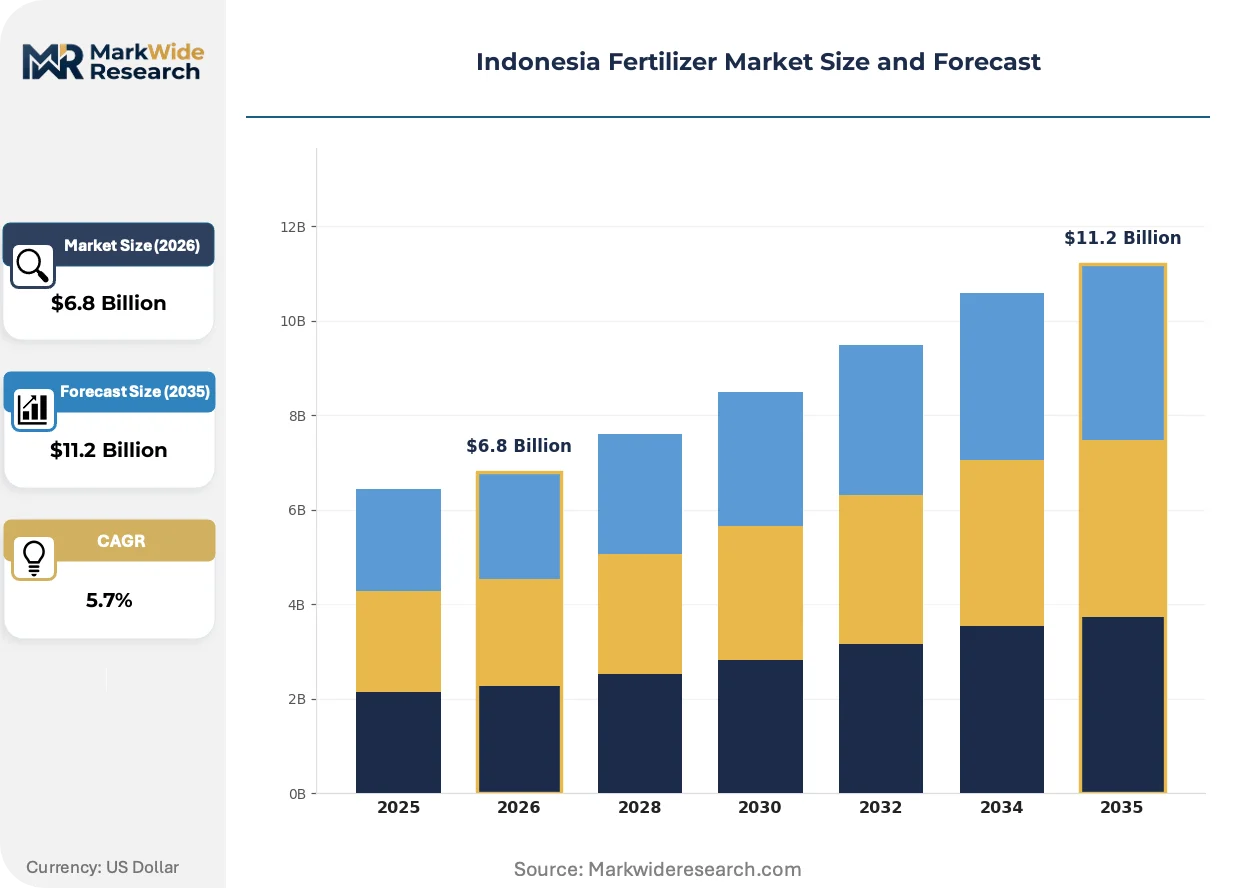
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, NPK, Ammonium Sulfate, Potash Formulation: Granular, Liquid, Powder, Coated End User: Agriculture, Horticulture, Turf, Landscaping Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | PT Pupuk Indonesia (Persero), PT Pupuk Kalimantan Timur, PT Pupuk Kujang, PT Petrokimia Gresik, PT Pupuk Sriwidjaja Palembang, PT Saraswanti Anugerah Makmur Tbk, PT Jadi Mas, Wilmar International Limited, Yara International ASA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Fertilizer Market Strategic Shifts
Technology adoption across Indonesia's fertilizer value chain is compressing traditional distribution layers while pulling precision agriculture tools into smallholder-facing service models previously reserved for plantation estates.
Controlled-release urea with polymer or sulfur coatings is consolidating market share in high-value horticultural segments. Bali's dragon fruit and chili exporters are adopting these formulations to reduce nitrogen leaching and labor application frequency. The technology is consolidating margin pools away from commodity urea traders toward integrated manufacturers with coating capabilities.
Indonesia's Ministry of Agriculture fertilizer distribution directives are tightening product registration and subsidized price ceiling enforcement. Domestic manufacturers must now navigate dual compliance tracks for commercial and subsidized channel qualification. Specialty grade producers are responding by segregating product lines to isolate registration risk from premium portfolio expansion.
Cooperative-led procurement aggregation is displacing individual smallholder purchases through village-level buying committees. Java's rice paddy districts and Sumatra's oil palm corridors are seeing buying power concentrate into fewer negotiation points. North Sumatra's cooperative federations are now the dominant channel gatekeepers for NPK volume allocation.
Indonesia Fertilizer Market Segmentation
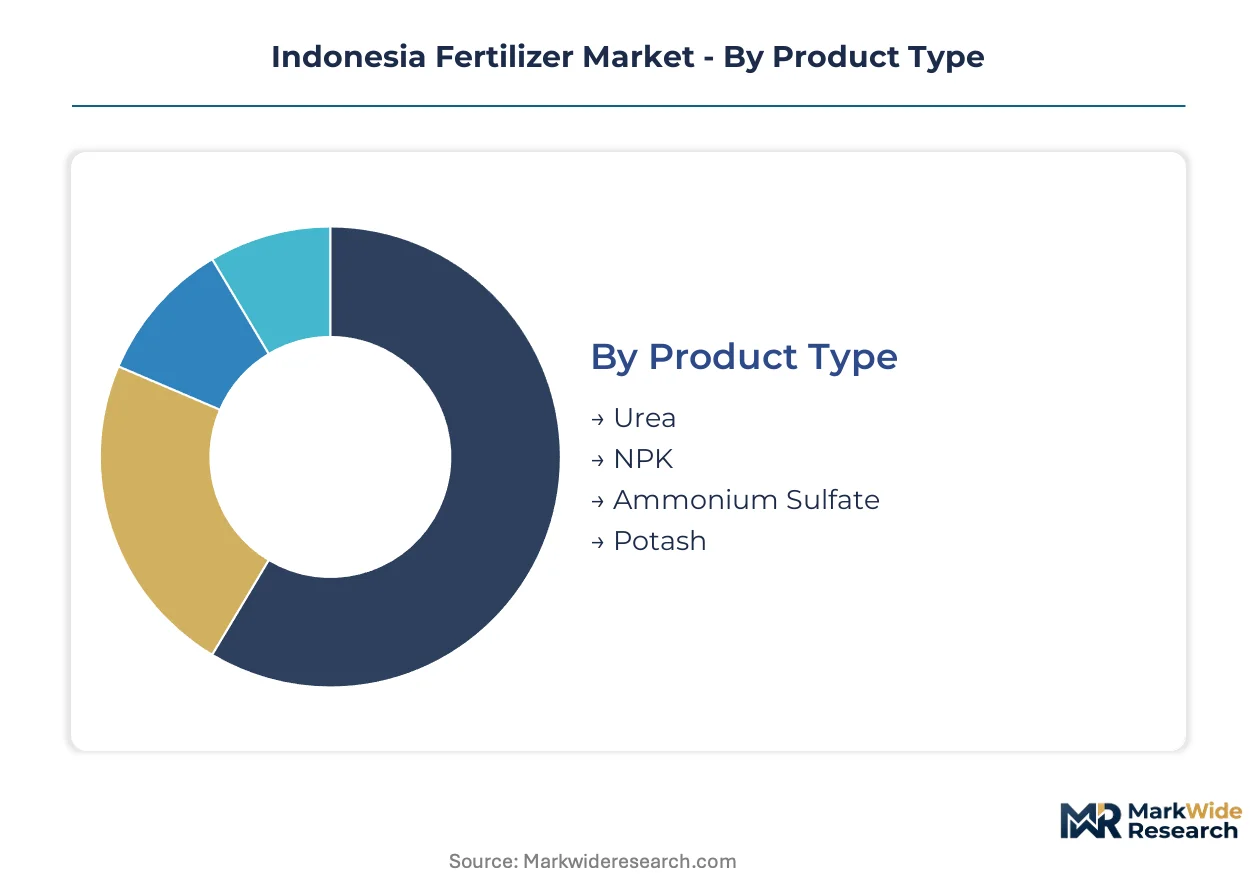
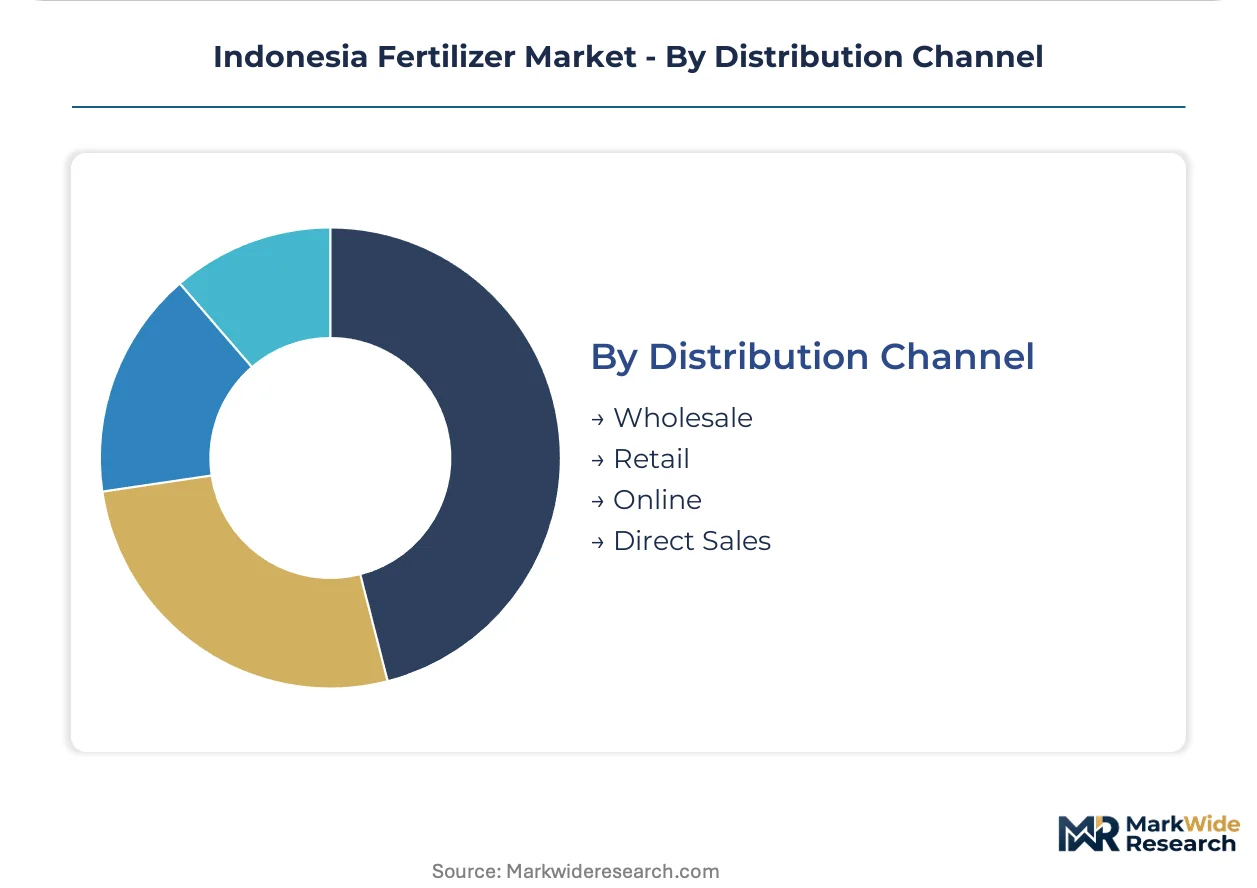
Segmentation in Indonesia's fertilizer market reveals how procurement patterns diverge between subsidized commodity channels and premium specialty tiers. Understanding these splits enables suppliers to align product registration strategies with distinct margin and volume profiles across Java's rice belts and Sumatra's plantation corridors.
Product Type:
Customization versus standardization tension runs deepest here, with commodity grades locked into government price ceilings while specialty formulations command open-market premiums.
- Urea:The dominant nitrogen source synthesized via Haber-Bosch ammonia processes, typically prilled to 2-4 millimeter particles for mechanized spreading. Demand concentrates in East Java's sugarcane belt and Central Java's rice paddy districts, where subsidized pricing through Ministry of Agriculture channels sustains volume throughput despite thinning margins.
- NPK:Compound fertilizers blending nitrogen, phosphorus, and potassium in ratios tailored to crop-specific requirements. North Sumatra's oil palm cooperative federations are redirecting procurement volumes toward integrated blenders capable of offering credit terms and technical advisory bundled with product delivery.
- Ammonium Sulfate:Dual-nutrient source supplying nitrogen and sulfur, valued in sulfur-deficient Kalimantan soils where intensive oil palm cropping has depleted micronutrient reserves.
- Potash:Potassium chloride and sulfate variants imported entirely from Baltic and Canadian sources, exposing blenders to currency fluctuation risk and maritime supply chain volatility.
Leading the category by volume: Urea. Growing fastest: NPK compound grades.
Formulation:
Physical form determines application economics, with labor-scarce plantation estates favoring capital-intensive delivery systems while smallholders prioritize low-unit-cost granular products.
- Granular:The established standard for rice paddy applications, manufactured through drum or pan granulation to achieve uniform particle size for broadcast spreading. Government procurement channels maintain this format's lock on Java's cooperative-led distribution.
- Liquid:Soluble concentrates and suspensions designed for fertigation infrastructure. East Java's plantation estates are expanding drip and pivot systems, creating pull-through demand that bypasses traditional granular distributor layers.
- Powder:Fine-ground formulations for high-value horticultural foliar feeding, particularly among Bali's dragon fruit and chili exporters seeking rapid nutrient uptake.
- Coated:Polymer or sulfur-encapsulated controlled-release variants capturing widening margin pools through reduced application frequency and leaching mitigation.
Granular formulations dominate tonnage. Liquid products are climbing the fastest as plantation automation spreads.
End User:
Customer archetypes split between price-sensitive subsistence operators and yield-optimizing commercial enterprises with divergent soil testing and advisory service requirements.
- Agriculture:Broadacre cereal and fiber crop production encompassing rice, corn, and sugarcane across Java and Sumatra. Smallholder cooperative consolidation is compressing supplier margins while concentrating negotiation leverage into fewer village-level buying committees.
- Horticulture:Intensive fruit and vegetable cultivation for domestic and export markets. Bali's dragon fruit growers and Malang's apple orchards are adopting precision agriculture tools previously reserved for plantation estates.
- Turf:Golf course and sports field maintenance, a narrow segment concentrated in Jakarta's satellite developments and resort zones.
- Landscaping:Urban greening and commercial property maintenance, primarily serving Jakarta, Surabaya, and Bandung metropolitan demand.
Agriculture commands absolute volume share. Horticulture shows the steepest expansion trajectory as export quality standards tighten.
Distribution Channel:
Channel structure reflects the archipelago's logistics constraints, with physical infrastructure dominance giving way to digital intermediation in cooperative-heavy regions.
- Wholesale:Bulk volume aggregation through PT Pupuk Indonesia's terminal network and regional distributor depots. This layer handles subsidized product allocation under Ministry of Agriculture distribution directives.
- Retail:Village-level kiosks and agricultural supply shops serving individual smallholders. Cooperative procurement aggregation is displacing this channel's relevance in Java's rice districts.
- Online:Mobile-enabled cooperative aggregation tools and B2B procurement platforms emerging as channel innovations to bypass traditional distributor markups.
- Direct Sales:Manufacturer-to-plantation relationships for liquid formulation and specialty grade delivery, particularly in North Sumatra's oil palm corridor.
Wholesale channels move the greatest tonnage. Online platforms are gaining share fastest where cooperative digitization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in East Java's sugarcane belt and North Sumatra's oil palm corridor, where cooperative consolidation is redirecting procurement volumes toward integrated distributors capable of offering bundled advisory services.
Java
East Java's plantation estates are expanding fertigation infrastructure for sugarcane intensification, creating pull-through demand for liquid formulations. The Ministry of Agriculture subsidization policy for certified organic inputs is redirecting manufacturer portfolios toward specialty grades. Surabaya and Malang anchor blending and distribution capacity for the island's rice paddy districts.
Sumatra
North Sumatra's oil palm cooperative federations are the dominant channel gatekeepers for NPK volume allocation, compressing supplier margins while concentrating negotiation leverage. BIS-equivalent national standards enforce nutrient content labeling and heavy metal limits across product registration requirements. Medan serves as the logistics hub for potash imports destined for Kalimantan's expanding plantation frontier.
Kalimantan
Intensive oil palm cropping without micronutrient replenishment is degrading long-term yield potential through soil acidification and sulfur deficiency. The central environmental regulator mandates emission controls on ammonia plants, tightening capital requirements for brownfield urea expansions. Pontianak and Samarinda are emerging as procurement aggregation points for frontier estate development.
Sulawesi
Underpenetrated plantation development in eastern Indonesia offers first-mover positioning for integrated fertilizer-logistics operators. Domestic natural gas feedstock availability sustains cost competitiveness for ammonia synthesis relative to import-dependent regional peers. Makassar anchors distribution infrastructure for nickel-corridor agricultural expansion.
Papua
Frontier estate development remains underpenetrated, creating strategic opportunities for operators capable of overcoming archipelago logistics constraints. Mobile-enabled cooperative aggregation tools are emerging as channel innovations to bypass traditional distributor layers. Jayapura and Merauke represent nascent demand concentrations for specialty grade penetration.
Indonesia Fertilizer Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue precision agriculture advisory and coated formulation premiumization. The vendor base clusters around state-linked ammonia synthesis complexes, integrated phosphate blenders, and international specialty grade suppliers. Three archetypes dominate: domestic gas-fed urea manufacturers, NPK compound blenders with coastal terminal access, and precision agriculture service bundlers. Capacity expansion and cooperative procurement aggregation represent the dominant competitive moves reshaping channel control.
Among domestic state-linked producers, PT Pupuk Indonesia (Persero) and PT Petrokimia Gresik exemplify the integrated infrastructure archetype, anchoring national distribution through archipelago-wide terminal networks. Yara International ASA occupies a position representing the international precision agriculture bundler archetype. These three entities collectively illustrate how competitive positioning stratifies across commodity volume, integrated blending, and premium advisory service tiers.
| Leading Market Players |
|---|
| PT Pupuk Indonesia (Persero) |
| PT Pupuk Kalimantan Timur |
| PT Pupuk Kujang |
| PT Petrokimia Gresik |
| PT Pupuk Sriwidjaja Palembang |
| PT Saraswanti Anugerah Makmur Tbk |
| PT Jadi Mas |
| Wilmar International Limited |
| Yara International ASA |
| Others |
Value Chain & Pricing Dynamics
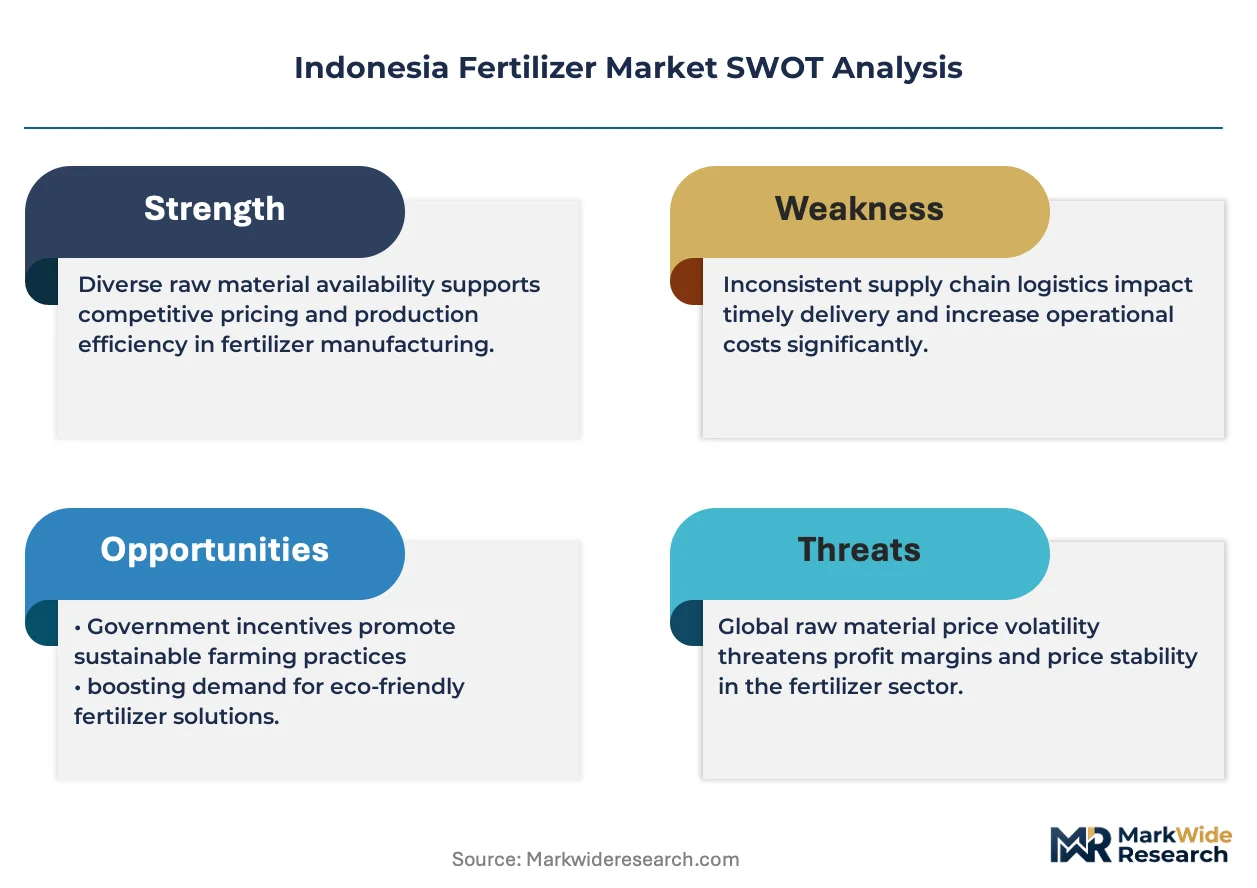
Polymer coating technology adoption is simultaneously elevating production costs for controlled-release formulations and concentrating margin capture among integrated manufacturers with in-house sulfur or polymer encapsulation capabilities, compressing commodity traders into thinner spreads.
Pricing Analysis
Volume concentrates in subsidized urea channels where Ministry of Agriculture price ceilings compress returns, while margin pools migrate toward specialty coated grades and liquid formulations for plantation estates. Price differentiation rests on certification tier and bundled advisory services rather than base nutrient content alone. Pricing pressure intensifies in granular NPK segments as cooperative procurement aggregation concentrates buyer leverage. Smallholder cooperatives exhibit highest price sensitivity, whereas horticultural exporters prioritize yield optimization over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from North Sumatra's oil palm cooperative federations require blenders to qualify multiple potash suppliers across Canada and Baltic states to mitigate maritime disruption risk. Ammonia synthesis draws from domestic natural gas fields in East Java and Kalimantan, while phosphate rock acidulation rests on imported Moroccan and Jordanian feedstock. Single-source vulnerability concentrates in potash import channels exposed to currency fluctuation and Red Sea routing alternatives. Distribution runs through PT Pupuk Indonesia's archipelago-wide terminal network, with direct sales bypassing wholesale layers for liquid formulation plantation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-release coating technology is displacing commodity urea in high-value horticultural segments, creating a portfolio-transition imperative for legacy ammonia producers.
For Market Incumbents: Acquire precision agriculture advisory capabilities to defend against Yara International ASA's bundled service model. Integrate backward into sulfur or polymer coating inputs to capture margin migration from commodity traders. Secure terminal access in Sulawesi and Papua before frontier estate development accelerates cooperative procurement aggregation. For New Entrants and Emerging Players: The premium-economy price gap in coated slow-release formulations offers white-space positioning for mid-tier blenders with coating technology partnerships. Target Sulawesi's underpenetrated plantation corridor where integrated logistics operators remain scarce. Pursue digital procurement platform partnerships with Java's village-level buying committees to bypass entrenched wholesale distributor layers. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated fertilizer-logistics operators with eastern Indonesia terminal networks. Long-term viability hinges on natural gas feedstock access and coating technology licensing rather than pure ammonia capacity scale. Watch for Ministry of Agriculture subsidy redirection toward certified organic inputs as inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Inputs | Captures margin pools migrating from commodity traders toward integrated manufacturers with sulfur or polymer encapsulation capabilities. |
| Precision Agriculture Advisory Service Launch | Defends positioning against Yara International ASA's bundled model among Bali dragon fruit and Malang apple exporters. |
| Terminal Network Expansion in Eastern Indonesia | Secures first-mover logistics control over Sulawesi and Papua frontier estate development corridors. |
| Digital Cooperative Procurement Platform | Bypasses traditional wholesale distributor markups in Java's village-level buying committee channels. |
| Specialty Grade Product Registration Segregation | Isolates subsidized channel compliance risk from premium portfolio expansion under Ministry of Agriculture directives. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across cooperative procurement managers, plantation estate agronomists, blending facility technical directors, and Ministry of Agriculture distribution officers. Secondary sources included Indonesian fertilizer import statistics, BIS-equivalent national standards documentation, and environmental regulator emission compliance disclosures. Bottom-up volume estimates from terminal throughput data reconciled with top-down market sizing from agricultural census planting area projections.
Data-stream reconciliation combined production capacity utilization rates with cooperative procurement volume aggregation trends across the projection horizon. Segmentation modeling incorporated product type, formulation, end-use, and distribution channel dimensions alongside regional plantation development intensity. CAGRs derived from trend extrapolation of subsidized allocation volumes and premium grade adoption curves, calibrated against natural gas pricing agreement stability and potash import cost volatility assumptions.
Inputs from Ministry of Agriculture distribution directives and central environmental regulator filings were available through the study window; gaps in real-time cooperative procurement transaction data introduce uncertainty bands around volume concentration estimates. Deviation in subsidy policy redirection timing or natural gas feedstock pricing renegotiation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Italy Foliar Fertilizer Market
Fertilizers
Potash Market
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
Catalyst Fertilizers Market
Fertilizers
Global Green Fertilizers Market
Fertilizers
Asia-Pacific Organic Fertilizer Market
Fertilizers
Italy Water Soluble Fertilizer Market
Fertilizers
Vietnam Biofertilizer Market
Fertilizers
Chelate Fertilizer Market
Fertilizers
Crop Micronutrients Market
Fertilizers
Polymer Coated Urea Market
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
Neem-Based Fertilizers Market
Fertilizers
Polymer Coated Fertilizer Market
Fertilizers
China Organic Fertilizers Market
Fertilizers
Middle East and Africa Specialty Fertilizer Market