
 Global Complex Fertilizers Market | 2026-2036
Global Complex Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Complex Fertilizers Market Analysis
Specialty crop agriculture is expanding its share of complex fertilizer consumption as high-value horticulture displaces commodity grain applications in key growing regions. Nutrien Ltd. leverages its integrated retail network to control distribution channels across North American farm belts. Yara International ASA anchors its position through deep R&D intensity in precision agriculture technologies. The Mosaic Company competes on manufacturing scale in phosphate-based NPK production.
Complex fertilizers are multi-nutrient formulations containing two or more primary macronutrients—nitrogen, phosphorus, and potassium—in homogeneous granules or liquid suspensions, typically manufactured through ammoniation-granulation or bulk blending processes to achieve specified N-P-K ratios for targeted crop nutrition. Granular formulations dominate volume due to established handling infrastructure and mechanical spreading compatibility, while controlled-release variants capture expanding margin pools through improved nutrient use efficiency and reduced application frequency. NPK fertilizers lead formulation demand across broadacre cropping systems, though specialty fertilizers gain traction in greenhouse and protected agriculture where micronutrient customization commands price premiums.
The EPA regulates nutrient management practices under the Clean Water Act, restricting phosphorus runoff from fertilizer applications in watersheds with impaired water quality. REACH and the EU F-Gas Regulation govern ammonia emissions and fluorinated greenhouse gas releases from nitrogen fertilizer production facilities across European manufacturing bases. India's FSSAI and CEA set quality benchmarks for fertilizer imports and domestic blending operations. Stakeholders must monitor tightening environmental performance standards that increasingly determine production licensing and market access eligibility.

Market Dynamics
Controlled-release coating technologies are fragmenting demand patterns as precision agriculture displaces commodity-grade bulk blends across high-value cropping systems. This structural shift concentrates margin capture among formulation specialists while compressing volumes for standardized NPK producers.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases from ammonia production facilities is accelerating capital redeployment into low-emission nitric acid plants across German and Polish manufacturing corridors.
- Brazil's Cerrado expansion:Large-scale soybean and corn operations in Mato Grosso and Goiás are displacing commodity-grade fertilizers with customized NPK formulations tailored to cerrado soil acidity profiles.
- Polymer-coated urea:Sulfur-polymer hybrid coatings are displacing conventional uncoated nitrogen in specialty horticulture applications through improved nitrogen use efficiency and reduced leaching losses.
Market Restraints
- Natural gas price volatility:Ammonia synthesis consumes 70-80% of production costs in nitrogen fertilizer manufacturing, exposing margins to Henry Hub and TTF benchmark fluctuations.
- Phosphate rock concentration:Moroccan and Chinese state-controlled miners control roughly two-thirds of exportable phosphate rock reserves, creating supply security vulnerabilities for non-integrated NPK blenders.
- REACH registration burdens:The European Chemicals Agency's substance evaluation protocols impose multi-year compliance timelines and testing costs that disproportionately burden small-scale specialty fertilizer importers.
Strategic Opportunities
- India's PM-KISAN-linked soil health card scheme:The government's micronutrient deficiency mapping initiative creates a regulatory tailwind for customized complex fertilizer formulations targeting zinc, boron, and sulfur gaps in Punjab and Haryana wheat belts.
- Drone-based variable-rate application:The convergence of multispectral imaging with granulated controlled-release products enables prescription-grade fertility management in Australian broadacre cotton operations.
- Direct-to-farm digital platforms:Mobile-enabled procurement networks are bypassing traditional cooperative distribution structures in Kenya and Nigeria, capturing farmer data for tailored nutrient recommendation engines.
Industry Challenges
- Soil science specialization shortage:Precision agriculture deployment requires agronomists trained in GIS-based fertility mapping, a skill set concentrated in university extension programs with limited commercial training pipelines.
- Controlled-release certification timelines:OECD 305 biodegradability testing and EU fertilizer product regulation (FPR) conformity assessments extend product launch cycles by 18-24 months for novel coating chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Complex Fertilizers Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Water-Soluble, Controlled-Release Application: Agricultural Crops, Horticultural Crops, Turf, Ornamental Plants End User: Farmers, Distributors, Retailers, Agricultural Cooperatives Formulation: NP Fertilizers, NPK Fertilizers, Basic Fertilizers, Specialty Fertilizers |
| Companies Covered | Nutrien Ltd., Yara International ASA, The Mosaic Company, CF Industries Holdings, Inc., ICL Group, OCP Group, K+S Aktiengesellschaft, BASF, EuroChem Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Complex Fertilizers Market Emerging Trajectories
Digital soil sensing and automated blending systems are compressing the gap between laboratory analysis and field application, enabling real-time formulation adjustments that were previously confined to research station trials.
Encapsulated nutrient technologies using biodegradable polymer matrices are decentralizing fertilizer manufacturing by enabling distributed blending operations to produce site-specific NPK grades without centralized ammoniation plants. Mid-scale cooperatives in the US Corn Belt and Australian wheat-sheep zones are adopting containerized coating units at twice the pace of conventional brownfield expansions. This diffusion pattern is compressing the historical economies-of-scale advantage held by integrated nitrogen producers.
REACH authorization requirements for cadmium limits in phosphate fertilizers are forcing reformulation of traditional DAP and MAP products across EU member state import channels. The industrial consequence is a sourcing pivot toward low-cadmium igneous phosphate deposits in Russia and South Africa, displacing sedimentary rock from North African suppliers. Specialty fertilizer distributors in the Netherlands and Denmark are responding by securing multi-year offtake agreements with alternative rock producers.
Consolidated procurement by large-scale farming enterprises is displacing fragmented dealer networks across Brazilian soybean operations and US Plains wheat production. Input purchasing cooperatives in Rio Grande do Sul and Kansas are centralizing fertilizer tendering through digital platforms that aggregate volume across thousands of hectares, extracting price concessions previously captured by independent retailers. This concentration is most visible in Mato Grosso's sorriso cotton belt and western Kansas irrigated corn corridors.
Global Complex Fertilizers Market Segmentation

Complex fertilizer segmentation tracks the divergence between commodity-scale NPK production and precision-formulation technologies. Each axis reveals distinct margin pools, regulatory exposure, and capital intensity requirements that reshape competitive positioning across the value chain.
Product Type:
Physical form determines handling infrastructure compatibility, application precision, and nutrient release kinetics across divergent farm scales and crop systems.
- Granular:Homogeneous pellets manufactured through ammoniation-granulation processes dominate volume due to mechanical spreading compatibility with existing farm equipment. Demand concentrates in Brazilian soybean operations across Mato Grosso and Goiás, where bulk handling infrastructure favors solid formulations over liquid alternatives.
- Controlled-Release:Polymer-coated or sulfur-encapsulated granules enable synchronized nutrient release matching crop uptake curves. Specialty horticulture in Spain's Almería greenhouse belt and California's Central Valley vegetable operations drives adoption, with premium pricing justified through reduced application frequency and leaching mitigation.
- Liquid:Suspension concentrates suit fertigation systems and aerial application in Australian broadacre cotton.
- Water-Soluble:Fully dissolvable crystalline formulations serve protected agriculture and hydroponic systems in the Netherlands.
Granular leads on scale; controlled-release leads on momentum.
Application:
Crop category segmentation maps fertilizer value capture against input intensity, price elasticity, and technical advisory requirements.
- Agricultural Crops:Broadacre cereals, oilseeds, and fiber crops consume standardized NPK formulations at maximum volume scale. Corn-soybean rotations in Iowa and Illinois anchor demand for high-analysis phosphate and potash blends, with procurement centralized through cooperative purchasing pools.
- Horticultural Crops:High-value fruits, vegetables, and nuts require customized micronutrient packages and pH-adjusted formulations. Mexico's Sinaloa tomato belt and Morocco's Souss-Massa citrus groves drive specialty complex fertilizer consumption, with growers paying premiums for zinc, boron, and sulfur enrichment.
- Turf:Golf courses and sports fields demand slow-release nitrogen for aesthetic maintenance with minimal growth surges.
- Ornamental Plants:Nursery and floriculture operations in Colombia's Bogotá savanna use precision-blended starter solutions.
Agricultural crops anchor volume; horticultural crops command margin.
End User:
Channel structure determines price realization, technical service bundling, and working capital requirements across the distribution network.
- Farmers:Direct procurement by large-scale enterprises bypasses traditional dealer markups through digital tendering platforms. Kansas wheat cooperatives and Rio Grande do Sul soybean producers aggregate hectares to extract volume pricing previously captured by independent retailers.
- Distributors:Regional wholesalers manage inventory risk and credit extension across fragmented farm bases. Indian state-level fertilizer distributors in Punjab and Haryana navigate FSSAI quality benchmarks while handling subsidized product flows under PM-KISAN-linked schemes.
- Retailers:Local ag-input shops provide last-mile delivery and agronomic advice in Nigeria's northern cereal belt.
- Agricultural Cooperatives:Member-owned purchasing entities centralize procurement across thousands of smallholders in Kenya's Rift Valley.
Farmers drive channel disintermediation; distributors retain working capital dominance.
Formulation:
Nutrient composition segmentation reflects the technical sophistication gradient from commodity macronutrient supply to customized plant nutrition solutions.
- NPK Fertilizers:Ternary blends containing nitrogen, phosphorus, and potassium in specified ratios constitute the volume foundation of complex fertilizer manufacturing. REACH cadmium limits are forcing EU importers to pivot from Moroccan sedimentary phosphate toward Russian and South African igneous rock sources.
- Specialty Fertilizers:Micronutrient-enriched and pH-optimized formulations target specific soil deficiencies and crop physiological stages. India's soil health card scheme identifies zinc, boron, and sulfur gaps across Punjab wheat belts, creating regulatory tailwinds for customized production.
- NP Fertilizers:Nitrogen-phosphorus binary blends serve sulfur-deficient soils in Australian wheat-sheep zones.
- Basic Fertilizers:Standardized commodity grades without micronutrient augmentation fill price-sensitive segments in Indonesian palm oil estates.
NPK formulations dominate tonnage; specialty fertilizers capture expanding margin pools.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Cerrado agricultural frontier concentrates the most dynamic demand expansion for customized NPK formulations. Regulatory pressure on ammonia emissions and phosphate sourcing is fragmenting supply chains across multiple manufacturing corridors.
Brazil
Mato Grosso and Goiás soybean operations drive consumption of acidity-tailored NPK blends for cerrado soils. ANVISA and environmental licensing protocols govern fertilizer import quality and storage facility standards. The Sorriso cotton belt in western Mato Grosso anchors procurement centralization through digital cooperative platforms.
United States
Iowa and Illinois corn-soybean rotations anchor volume demand for high-analysis phosphate and potash formulations. The EPA regulates nutrient management under the Clean Water Act, restricting phosphorus runoff in impaired watersheds. The US Corn Belt sees mid-scale cooperatives adopting containerized coating units for distributed NPK blending.
Germany
Precision agriculture adoption in Lower Saxony and Bavaria drives controlled-release fertilizer integration. The EU F-Gas Regulation and REACH cadmium limits force reformulation of traditional DAP and MAP products. German manufacturing corridors are redeploying capital into low-emission nitric acid plants to meet phasedown requirements.
India
Punjab and Haryana wheat belts generate regulatory tailwinds for customized formulations targeting zinc, boron, and sulfur deficiencies. The FSSAI and CEA set quality benchmarks for fertilizer imports and domestic blending operations under PM-KISAN-linked soil health card schemes. State-level distributors navigate subsidized product flows while managing inventory risk.
Australia
Broadacre cotton operations in Queensland and New South Wales adopt drone-based variable-rate application with controlled-release granules. The country's national environmental regulator oversees water quality protection in Murray-Darling Basin fertilizer applications. Australian wheat-sheep zones compress the gap between laboratory analysis and field application through automated blending systems.
Global Complex Fertilizers Market Vendor Landscape
Capacity expansion dominates the current landscape as integrated nitrogen producers redeploy capital into low-emission manufacturing corridors. The vendor base organizes around three tiers: global diversified majors with captive raw material positions, regional formulation specialists with coating technology capabilities, and commodity blenders competing on logistics proximity. Strategic archetypes include backward-integrated phosphate miners controlling rock supply, precision agriculture technology bundlers, and distributed blending cooperatives. M&A activity and technology licensing partnerships represent the primary competitive moves as players secure alternative phosphate rock sources and coating intellectual property.
Within the diversified-major tier, Nutrien Ltd. and Yara International ASA exemplify contrasting strategic positions. Nutrien leverages its integrated retail network across North American farm belts to control distribution channels and capture farmer data. Yara anchors its positioning through precision agriculture technology intensity and European manufacturing base adaptation to F-Gas Regulation compliance. The Mosaic Company occupies a scale-driven position in phosphate-based NPK production, representing the captive-resource archetype with exposure to REACH-driven cadmium reformulation pressures.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| Yara International ASA |
| The Mosaic Company |
| CF Industries Holdings, Inc. |
| ICL Group |
| OCP Group |
| K+S Aktiengesellschaft |
| BASF |
| EuroChem Group |
| Others |
Supply Flow & Price Mechanics
Natural gas feedstock costs cascade through ammonia synthesis into three distinct pricing tiers for nitrogen-based complex fertilizers, with Henry Hub and TTF benchmark volatility compressing margins at the commodity end while polymer-coated specialty grades retain pricing power through micronutrient customization.
Pricing Analysis
Distributor markups widen for controlled-release formulations carrying REACH cadmium compliance certification, while bulk NPK blends face compression from cooperative tendering platforms in Brazil and the US Corn Belt. Price differentiation separates sulfur-polymer hybrid coatings from conventional granules based on nitrogen use efficiency guarantees. Pricing pressure stems from phosphate rock sourcing pivots forced by EU cadmium limits. Smallholder cooperatives in Kenya and Nigeria exhibit highest price sensitivity; greenhouse operators in Spain's Almería belt show lowest.
Supply Chain Analysis
Phosphate rock supply rests on Moroccan and Chinese state-controlled miners holding roughly two-thirds of exportable reserves, creating single-source vulnerability for non-integrated NPK blenders. Ammonia synthesis feeds from natural gas corridors in Russia, Qatar, and the US Gulf Coast. Sulfur and polymer coating chemicals draw from petrochemical complexes in Germany and South Korea. Tariff exposure concentrates at EU import channels facing REACH substance evaluation protocols. Distribution runs through regional wholesalers managing inventory risk and credit extension across fragmented farm bases.
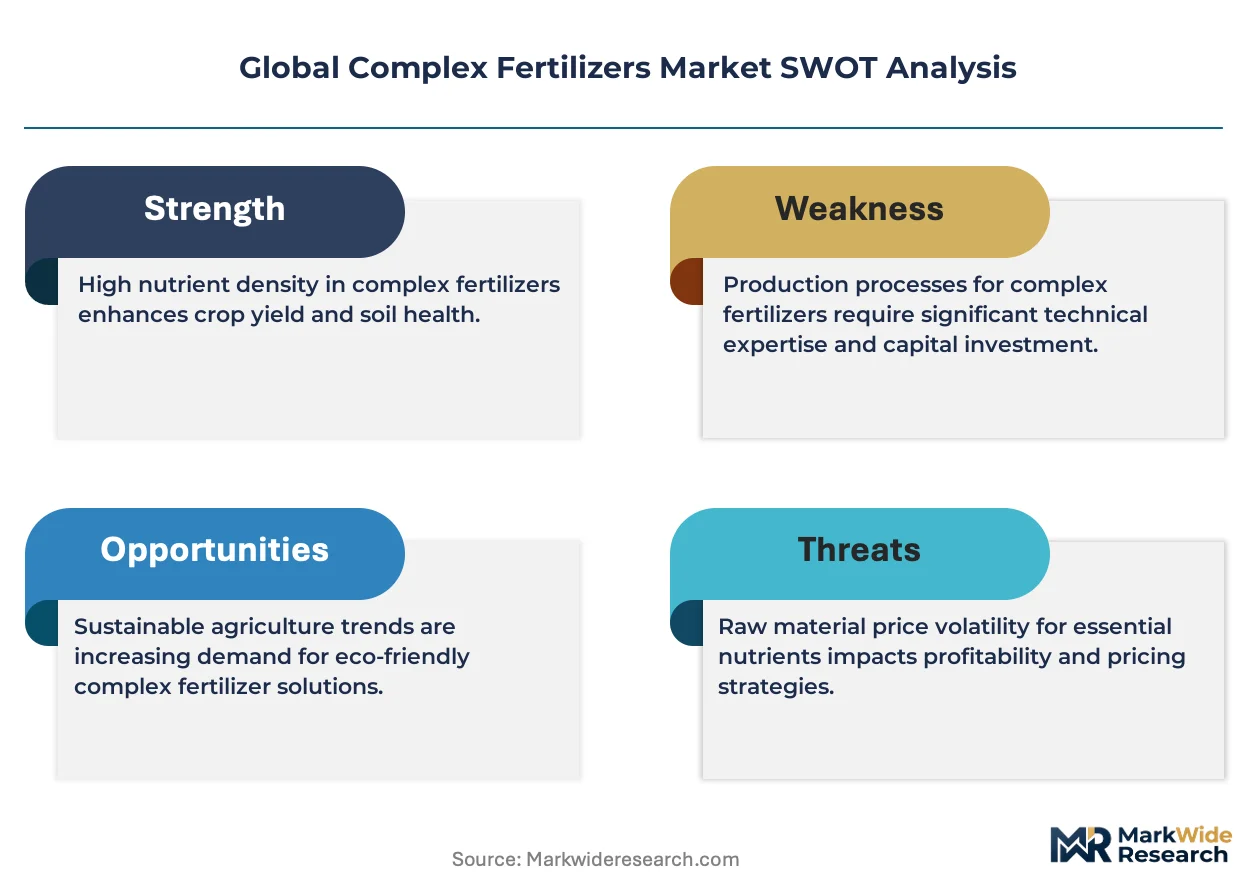
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in controlled-release coating technologies and precision agriculture bundling, with polymer-encapsulated formulations capturing value from nitrogen use efficiency premiums while commodity-grade bulk blends face procurement centralization pressure.
For Market Incumbents: Lock in alternative phosphate rock offtake agreements with Russian and South African igneous deposit operators before REACH cadmium limits fully displace Moroccan sedimentary sources. Secure coating technology licensing partnerships to defend formulation margins against mid-scale cooperative adoption of containerized blending units. Capacity addition in low-emission nitric acid plants across German and Polish manufacturing corridors addresses EU F-Gas Regulation compliance exposure. For New Entrants and Emerging Players: Drone-based variable-rate application platforms offer a technology-first wedge into Australian broadacre cotton and Brazilian Cerrado soybean operations where precision agriculture penetration remains below greenhouse horticulture levels. Target India's PM-KISAN-linked soil health card scheme implementation zones in Punjab and Haryana for customized micronutrient formulations. Direct-to-farm digital procurement networks bypass traditional cooperative structures while capturing farmer data for recommendation engines. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration burdens and F-Gas compliance costs disproportionately burden small-scale specialty fertilizer importers lacking capital for multi-year testing timelines. Long-term viability favors formulation specialists with captive coating intellectual property over commodity blenders exposed to phosphate rock concentration. Watch drone-based application adoption rates in Australian broadacre operations as inflection indicator for precision agriculture platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock | Captive supply of low-cadmium igneous deposits secures EU market access against REACH-driven sourcing pivots. |
| Coating Technology Licensing | Polymer-encapsulation IP partnerships enable mid-scale cooperatives to produce site-specific NPK grades without centralized plants. |
| Direct-to-Farm Digital Platform | Mobile procurement networks in Kenya and Nigeria bypass dealer markups while capturing farmer data for nutrient recommendations. |
| Low-Emission Nitric Acid Capacity | Capital redeployment into German and Polish manufacturing corridors meets EU F-Gas Regulation phasedown requirements. |
| Drone-Based Variable-Rate Partnership | Multispectral imaging integration with controlled-release granules enables prescription-grade fertility management in Australian cotton. |
Methodological Framework
Bottom-up crop-specific demand modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with fertilizer plant managers, procurement leads at agricultural cooperatives, distribution channel partners, and precision agriculture technology directors combined with secondary validation from customs and trade data, FAO fertilizer consumption statistics, SEC filings of integrated nitrogen producers, and EPA nutrient management enforcement records. Triangulation across these sources ensures segment-level granularity without distortion from single-source reporting.
Historical trendline analysis of NPK consumption patterns by crop type and regional regulatory cluster informed the projection framework across the analysis window. Segmentation dimensions modeled include physical form, nutrient composition tier, application crop category, and end-user channel structure. CAGRs derived from fitted growth curves adjusted for regulatory phase-in timelines and technology adoption S-curves. Forecast inputs incorporated natural gas price scenario bands and phosphate rock trade flow reconfigurations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU F-Gas Regulation implementation pace and Brazilian Cerrado expansion rates. Projections reflect assumptions around REACH cadmium limit enforcement consistency and drone-based application technology cost curves. A small set of named triggers—ammonia plant closure announcements, soil health card scheme budget allocations, and polymer coating patent expirations—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Urea Fertilizers Market
Fertilizers
China Fertilizers Market
Fertilizers
Russia Micronutrient Fertilizer Market
Fertilizers
Ammonium Sulfate Fertilizer Market
Fertilizers
Brazil Organic Fertilizer Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
Global Urea Market
Fertilizers
Global Fertilizers Market
Fertilizers
Polymer Coated Fertilizer Market
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
Global Liquid Fertilizer Market
Fertilizers
Saudi Arabia Fertilizer Market
Fertilizers
Global NPK Fertilizer Market
Fertilizers
Potassium Thiosulfate Fertilizer Market
Fertilizers
Global Controlled Release Fertilizer Market
Fertilizers
Thailand Fertilizers Market