
 Vietnam Recycling Market | 2026-2036
Vietnam Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Recycling Market Insights
Multi-source feedstock aggregation from informal collectors to formal processors is shifting how Vietnam's recycling sector secures raw material. DUYTAN Recycling Corporation leverages its proximity to central Vietnam's manufacturing belt to secure consistent PET bottle flows. VietCycle Corporation anchors the northern region through partnerships with municipal waste operators including Urenco. GreenHub Vietnam differentiates by embedding digital tracking across collection routes that previously operated without documentation.
Vietnam recycling encompasses the collection, sorting, cleaning, and reprocessing of discarded materials into feedstock for new products, with mechanical shredding and extrusion representing the dominant processing pathway for plastics and metals. The sector serves manufacturing supply chains seeking lower-cost raw material alternatives to virgin commodities. Plastics recycling commands the largest volume share due to packaging waste generation across food and beverage industries, while chemical and pyrolysis technologies represent the fastest-expanding processing category as investors target mixed-film streams that mechanical methods cannot handle. Paper recycling maintains mature, margin-compressed operations centered on Dong Tien Paper Mill and comparable integrated producers.
The Ministry of Natural Resources and Environment implements extended producer responsibility frameworks that obligate manufacturers to finance collection infrastructure, while the country's national standards body sets recycled content thresholds for select packaging categories. These regulations reshape market access by requiring formal documentation chains that informal collectors historically lacked. Stakeholders must monitor enforcement consistency across provincial environmental departments and assess whether chemical recycling investments align with emerging emission controls.
Market Dynamics
Extended producer responsibility enforcement by Vietnam's Ministry of Natural Resources and Environment is forcing packaging manufacturers to finance formal collection infrastructure, collapsing the historical reliance on unregistered informal collectors and triggering capital flows into documented feedstock chains.
Growth Catalysts
- Regulatory mandate escalation:Tightened extended producer responsibility rules obligate manufacturers to fund collection networks, creating guaranteed revenue streams for formal processors.
- Mechanical reprocessing demand:Ho Chi Minh City's industrial zones concentrate appetite for shredded and extruded plastic feedstock, drawing investment from domestic collectors and regional equipment providers.
- Chemical recycling advancement:Pyrolysis technologies unlock value from mixed-film waste streams that mechanical methods cannot process, expanding addressable feedstock volumes.
Market Restraints
- Feedstock cost volatility:Post-consumer plastic prices fluctuate with virgin resin benchmarks, compressing margins when oil prices drop.
- Collection infrastructure gaps:Northern provinces outside Hanoi lack dense collection networks, forcing processors to absorb elevated logistics costs.
- Technical contamination limits:Multi-layer packaging and adhesive labels degrade reprocessed pellet quality, restricting end-use applications.
Strategic Opportunities
- Central Vietnam manufacturing belt:Da Nang and surrounding provinces host underdeveloped recycling capacity relative to their industrial waste generation.
- Digital tracking integration:Blockchain-enabled provenance systems create premium pricing for documented recycled content sought by export-oriented brands.
- Chemical recycling convergence:Partnerships between pyrolysis operators and petrochemical complexes enable circular feedstock integration.
Industry Challenges
- Sorting automation deficit:Near-infrared and robotics expertise remains scarce, forcing reliance on manual labor with inconsistent throughput.
- Certification timeline compression:Recycled content verification schemes require 12-18 month accreditation cycles that delay contract execution.
- Legacy informal collector integration:Decades of undocumented collection practice creates resistance to formal documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Recycling Market |
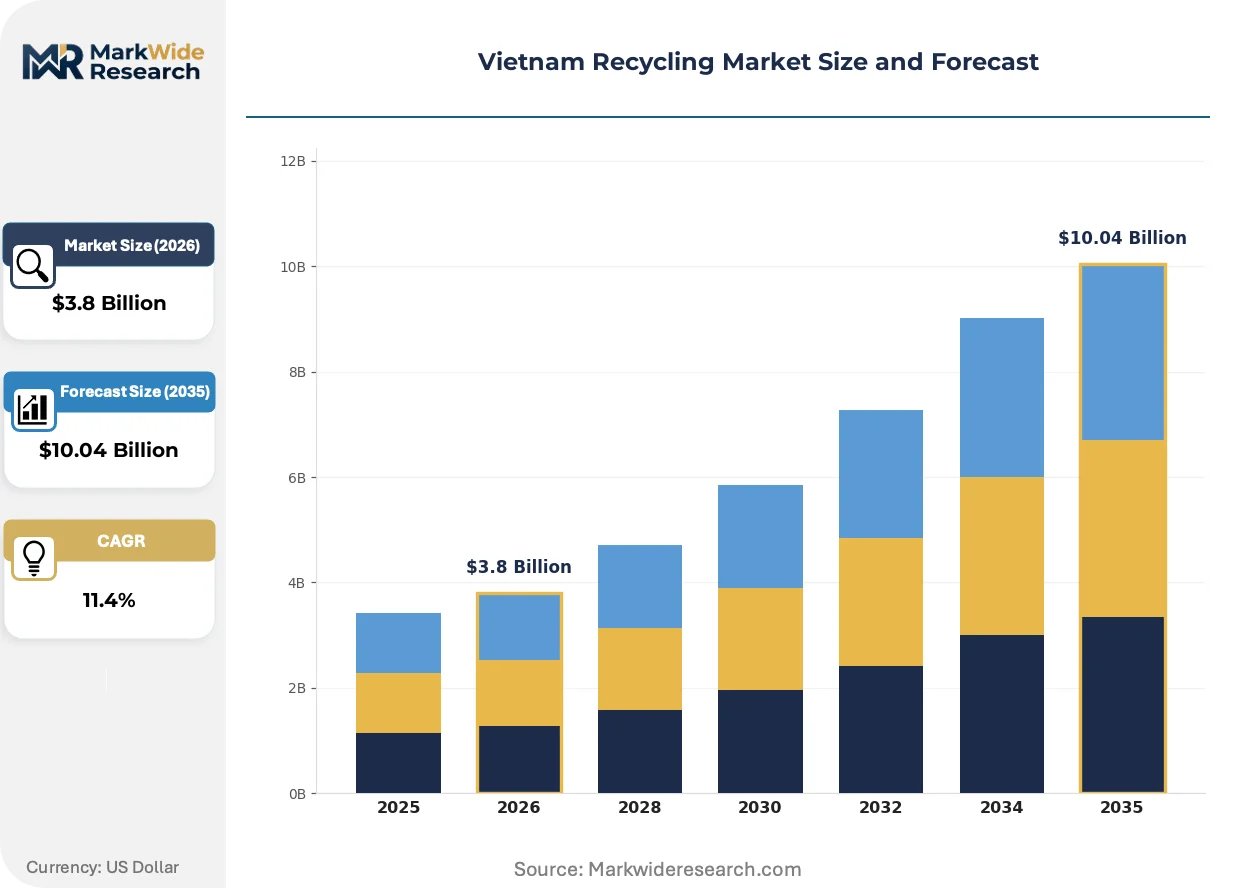
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastics, Metals, Paper, Glass Collection Method: Curbside, Drop-off Centers, Buy-back Centers, Street Collection Processing Technology: Mechanical, Chemical, Pyrolysis, Biochemical End User Sector: Manufacturing, Construction, Agriculture, Energy |
| Companies Covered | DUYTAN Recycling Corporation, VietCycle Corporation, Urenco (Hanoi Urban Environment Co.), GreenHub Vietnam, Dong Tien Paper Mill, AnPhat Holdings, Hiep Thanh Plastic, CMC Copper, Hoang Ha Copper, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Recycling Market Trends and Innovations
Technology providers and waste operators are converging on digitized traceability and advanced reprocessing methods that reshape how Vietnamese recyclers secure competitive position and access premium offtake contracts.
Pyrolysis-based chemical recycling is expanding into mixed plastic waste streams that mechanical shredding cannot valorize. Food and beverage packaging manufacturers with rigid sustainability targets are piloting offtake agreements at small commercial scale. This technology is expanding into the addressable feedstock base by unlocking value from contaminated films and multi-layer structures previously destined for landfill or incineration.
Extended producer responsibility implementation by Vietnam's Ministry of Natural Resources and Environment mandates manufacturer financing of collection infrastructure. The regulation forces brand owners to contract directly with formal processors rather than anonymous traders. Southern provinces with denser industrial presence are responding faster than northern regions due to proximity to Ho Chi Minh City's processor concentration.
Buyer procurement now favors long-term feedstock contracts with documented chain-of-custody over spot market purchases. Export-oriented electronics and apparel brands are disintermediating traders to secure verified recycled content. This pattern is most visible in Dong Nai and Binh Duong provinces where manufacturing clusters face direct pressure from EU and US customers requiring supply chain transparency.
Vietnam Recycling Market Segmentation
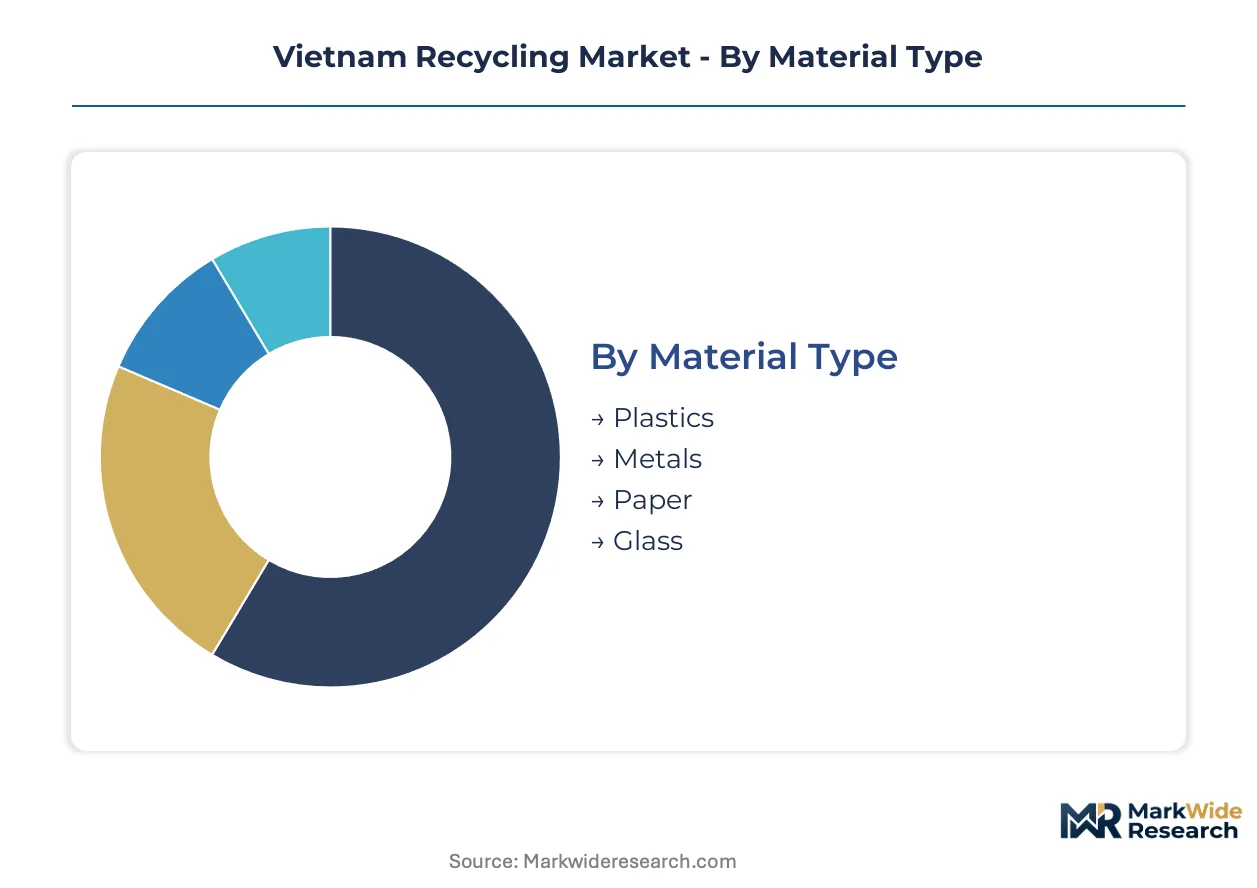
Segmentation reveals how Vietnam's recycling sector fragments across material chemistry, collection logistics, and processing sophistication. Understanding these axes clarifies where capital deployment and regulatory pressure concentrate most intensely.
Material Type:
Material chemistry determines processing infrastructure requirements and end-market pricing power across Vietnam's industrial zones.
- Plastics:PET, HDPE, and PP streams dominate volume flows from Ho Chi Minh City's beverage and packaging manufacturers. Mechanical reprocessing capacity concentrates in Dong Nai and Binh Duong provinces where food-grade pellet demand from export-oriented brands commands premium pricing.
- Metals:Aluminum and steel recovery from manufacturing scrap and post-consumer sources feeds central Vietnam's construction and electronics sectors. Da Nang's industrial belt generates consistent ferrous waste streams that bypass collection infrastructure gaps plaguing northern provinces.
- Paper:OCC and mixed paper grades serve integrated mills with captive pulping capacity. Dong Tien Paper Mill anchors demand though margin compression limits processor expansion.
- Glass:Container recovery operates at smaller scale with limited local reprocessing; cullet typically feeds construction aggregate or exports.
Plastics lead on scale; chemical recycling investments targeting mixed-film waste are gaining share fastest.
Collection Method:
Collection modality shapes feedstock documentation quality and compliance with extended producer responsibility mandates.
- Curbside:Municipal programs in Hanoi and Ho Chi Minh City generate volume but suffer contamination rates that degrade mechanical reprocessing yields. Urenco partnerships in the north are formalizing documentation chains that satisfy manufacturer compliance requirements.
- Drop-off Centers:Fixed collection points in industrial zones capture cleaner commercial waste streams from manufacturing facilities. These centers anchor formal feedstock contracts with processors seeking verified chain-of-custody documentation.
- Buy-back Centers:Transaction-based collection incentivizes high-value material recovery; PET bottle aggregation dominates though price volatility with virgin resin benchmarks compresses margins.
- Street Collection:Informal networks historically supplied majority feedstock volume; Ministry of Natural Resources and Environment documentation rules are forcing integration into formal systems or displacement.
Street collection retains volume dominance; drop-off centers are expanding most quickly under regulatory pressure.
Processing Technology:
Technology selection determines which feedstock streams become economically recoverable and emission compliance exposure.
- Mechanical:Shredding, washing, and extrusion equipment dominates installed capacity across southern provinces. Ho Chi Minh City's processor concentration attracts regional equipment providers and technical service networks.
- Chemical:Pyrolysis and depolymerization unlock mixed-film and multi-layer packaging waste previously destined for landfill. Petrochemical complex partnerships enable circular feedstock integration into virgin production.
- Pyrolysis:Thermal cracking of plastic waste into synthetic crude or monomer feedstocks represents the steepest expansion trajectory as investors target contamination-heavy streams mechanical methods cannot valorize.
- Biochemical:Enzymatic and fermentation-based processing remains pre-commercial in Vietnam; limited pilot scale operations focus on agricultural residue streams.
Mechanical processing anchors current capacity; pyrolysis commands the steepest investment trajectory.
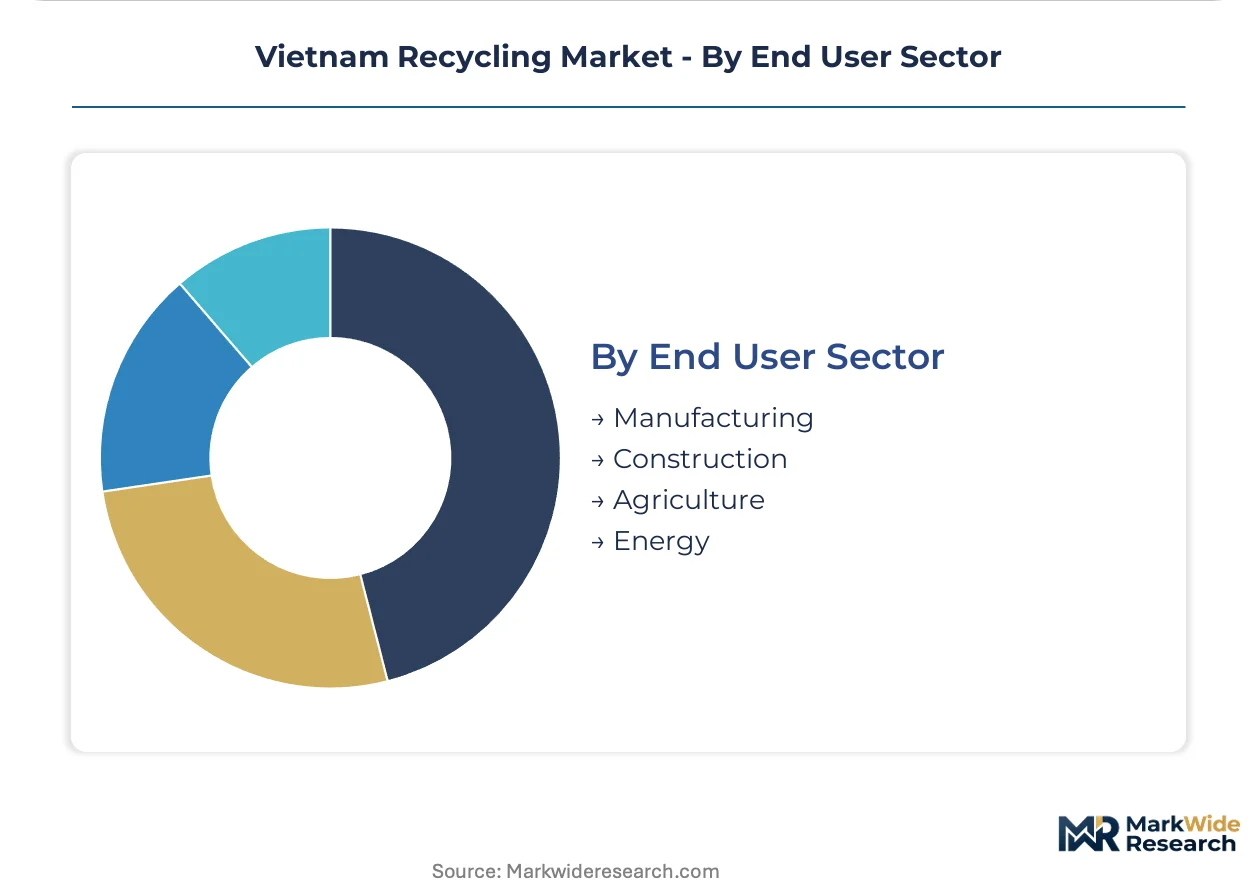
End User Sector:
Demand concentration by end-use sector determines regional processor location and recycled content specification stringency.
- Manufacturing:Electronics and apparel brands in Dong Nai and Binh Duong provinces drive demand for documented recycled content meeting EU and US supply chain transparency requirements. These buyers are disintermediating traders to secure verified feedstock contracts.
- Construction:Aggregate substitution and rebar feedstock applications absorb lower-grade recycled output; technical contamination limits restrict higher-value applications.
- Agriculture:Mulch films and irrigation component manufacturing generates plastic waste streams that loop back into recycling networks; limited chemical recycling pilots target this closed-loop potential.
- Energy:Waste-to-fuel and refuse-derived fuel applications absorb non-recyclable fractions; emission control alignment with Ministry of Natural Resources and Environment standards remains uncertain.
Manufacturing commands premium pricing power; construction absorbs volume at compressed margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ho Chi Minh City's industrial corridor anchors Vietnam's recycling demand concentration, with mechanical reprocessing capacity clustering across Dong Nai and Binh Duong provinces where export-oriented manufacturers face direct supply chain transparency pressure from EU and US buyers.
Red River Delta
Hanoi generates substantial municipal waste volumes through Urenco-operated collection networks, yet contamination rates degrade mechanical reprocessing yields. The Ministry of Natural Resources and Environment's extended producer responsibility framework mandates formal documentation chains that informal collectors in this region struggle to satisfy. Bac Ninh and Hai Duong industrial zones concentrate electronics manufacturing scrap flows requiring verified recycled content certification.
Southeast Region
Dong Nai and Binh Duong provinces host the densest processor concentration, with food-grade pellet demand from apparel and electronics brands commanding premium pricing. Buy-back centers and drop-off facilities capture cleaner commercial waste streams than municipal curbside programs. Binh Duong's manufacturing clusters drive disintermediation as brands contract directly with formal processors for documented chain-of-custody.
Central Coast
Da Nang and surrounding provinces generate industrial waste volumes that exceed local recycling capacity, creating logistics cost burdens for processors sourcing from this belt. DUYTAN Recycling Corporation leverages proximity to central Vietnam's manufacturing base to secure consistent PET bottle flows. The region's underdeveloped reprocessing infrastructure relative to waste generation presents expansion opportunities for mechanical and chemical recycling investors.
Mekong Delta
Agricultural plastic waste from mulch films and irrigation components generates feedstock streams with closed-loop potential, though collection infrastructure remains sparse outside Can Tho. The Ministry of Natural Resources and Environment's enforcement consistency varies across provincial environmental departments in this southern region. Limited chemical recycling pilots target agricultural residue valorization where mechanical methods face technical contamination limits.
Northern Midlands and Mountains
Provinces outside Hanoi lack dense collection networks, forcing processors to absorb elevated logistics costs when sourcing from this territory. VietCycle Corporation anchors northern region feedstock security through municipal waste operator partnerships. The gap between regulatory documentation requirements and informal collector capabilities creates operational friction for formal processors expanding into these peripheral markets.
Vietnam Recycling Market Competitive Landscape
Global equipment providers compete with regional champions across technology provision and feedstock aggregation, while domestic collectors battle formal processors for control of documented supply chains. Market structure fragments across three tiers: multinational machinery suppliers, integrated Vietnamese processors with municipal partnerships, and informal collector networks facing regulatory displacement. Strategic archetypes include EPR compliance specialists, pyrolysis technology pioneers, and digital traceability integrators. Capacity expansion and backward integration into collection infrastructure represent the dominant competitive moves as formal documentation requirements tighten.
Among Vietnamese-anchored processors, DUYTAN Recycling Corporation and VietCycle Corporation exemplify the municipal-partnership archetype, while GreenHub Vietnam occupies a position within the digital traceability tier. Dong Tien Paper Mill represents integrated pulp-and-paper operations with captive demand absorption. These entities illustrate how geographic positioning and regulatory relationship depth determine competitive standing under Vietnam's evolving extended producer responsibility regime.
| Leading Market Players |
|---|
| DUYTAN Recycling Corporation |
| VietCycle Corporation |
| Urenco (Hanoi Urban Environment Co.) |
| GreenHub Vietnam |
| Dong Tien Paper Mill |
| AnPhat Holdings |
| Hiep Thanh Plastic |
| CMC Copper |
| Hoang Ha Copper |
| Others |
Pricing and Supply Chain Analysis
Export-oriented apparel and electronics manufacturers in Dong Nai and Binh Duong provinces command pricing leverage through long-term offtake contracts with documented chain-of-custody requirements, compressing spot-market processors into commodity-grade margins while premium-tier feedstock secures volume commitments.
Pricing Analysis
Input-cost pass-through from virgin resin benchmarks governs post-consumer plastic pricing, with mechanical reprocessors absorbing volatility when oil prices drop. Three-tier pricing structure across food-grade certified, industrial-grade, and aggregate-grade pellets reflects contamination tolerance and end-use specification. Pricing pressure stems from informal collector displacement costs under Ministry of Natural Resources and Environment documentation mandates. Small-scale collectors exhibit highest price sensitivity; multinational brands with EPR compliance obligations show lowest.
Supply Chain Analysis
Feedstock supply rests on informal collector networks across Vietnam's northern provinces, mechanical equipment from China and Taiwan, and pyrolysis technology licensors from South Korea and Japan. Raw material dependencies include post-consumer PET bottles, mixed-film agricultural waste, and manufacturing scrap from electronics assembly. Single-source vulnerability concentrates in imported near-infrared sorting equipment. Distribution runs through formal processor gates in Ho Chi Minh City's industrial corridor before reaching export-oriented manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
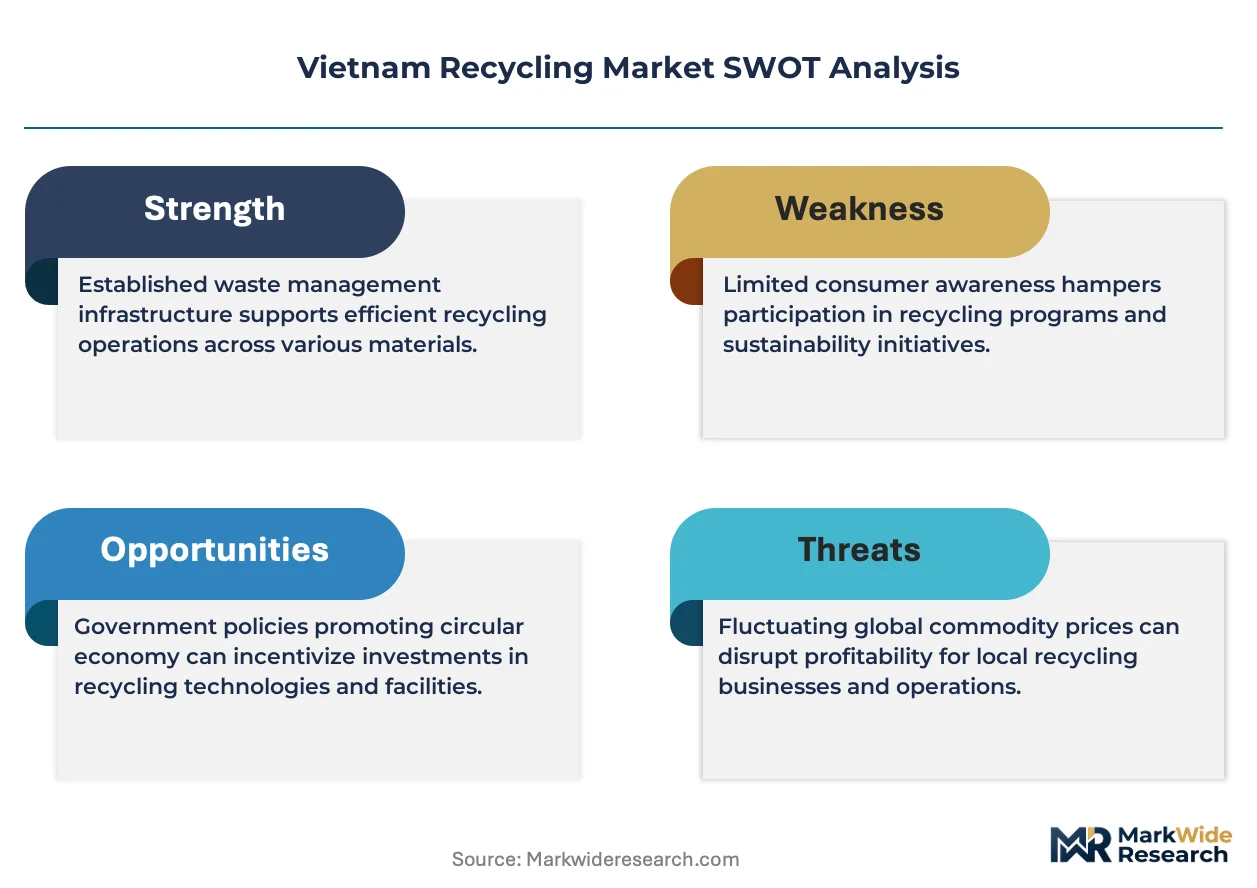
Vietnam's recycling sector offers margin expansion through chemical recycling yield improvements and premium-tier feedstock certification that commands documented chain-of-custody pricing.
For Market Incumbents: Lock in municipal waste operator partnerships before Urenco and comparable entities exhaust exclusive contracting windows in Hanoi and surrounding northern provinces. Pyrolysis technology entrants threaten mechanical reprocessing margins; backward integration into collection infrastructure secures feedstock volume against displacement. For New Entrants and Emerging Players: Begin with Da Nang and central Vietnam's manufacturing belt where reprocessing capacity lags industrial waste generation. Agricultural plastic waste from Mekong Delta mulch films presents underdeveloped feedstock streams with closed-loop potential. Digital tracking integration creates differentiation against informal collector competition. For Investors and Strategic Acquirers: Petrochemical conglomerates seeking circular feedstock integration represent the most active acquirer in this space. Five-to-ten year viability hinges on Ministry of Natural Resources and Environment enforcement consistency across provincial environmental departments. Acquisition targets should demonstrate formal documentation chains and municipal partnerships. Watch for pyrolysis offtake agreement announcements from food and beverage packaging manufacturers as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | Secures feedstock volume against informal collector displacement under EPR rules. |
| Pyrolysis Technology Licensing | Unlocks mixed-film waste streams that mechanical methods cannot valorize. |
| Municipal Waste Operator Partnership | Establishes formal documentation chains required by Dong Nai manufacturers. |
| Digital Tracking Platform Deployment | Enables premium pricing from EU and US brands demanding supply chain transparency. |
| Food-Grade Pellet Certification Investment | Accesses export-oriented apparel and electronics manufacturer contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered waste collection operators, mechanical reprocessing plant managers, pyrolysis technology providers, municipal environmental department officials, and procurement leads at export-oriented manufacturers. Secondary validation drew from Ministry of Natural Resources and Environment regulatory filings, Vietnam Environment Administration waste generation statistics, customs trade data on recycling equipment imports, and extended producer responsibility implementation circulars. Bottom-up feedstock flow modeling and top-down manufacturing demand estimation provided triangulation.
Segment-weighting across material type, collection method, processing technology, and end-user sector shaped volume and value outputs across the projection horizon. Material chemistry splits modeled PET, HDPE, PP, and mixed-film streams separately. Processing technology segmentation captured mechanical, pyrolysis, and emerging biochemical pathways. CAGRs derived from historical capacity expansion rates, regulatory implementation timelines, and manufacturing sector recycled content adoption curves. Forecast inputs included virgin resin price volatility assumptions and provincial EPR enforcement differential.
Several conditions sit outside the modeled scope, including potential emission control tightening on pyrolysis operations and informal collector resistance duration. Forecasts reflect assumptions about Ministry of Natural Resources and Environment enforcement consistency and petrochemical complex partnership appetite. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
Plastic Ignition Holders Market
Recycled Plastics
Recycled Leather Market
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
North America Plastic Waste Management Market
Recycled Plastics
Waste Plastic Bricks Market
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market
Recycled Plastics
Global Post-Consumer Recycled Plastics Market
Recycled Plastics
US Plastics Market
Recycled Plastics
North America BPA Free Plastic Market
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
Recycled Carbon Fiber Market
Recycled Plastics
Europe Recycled Plastics Market
Recycled Plastics
Recyclability-Optimized Impact Modifiers for Polyolefins Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
US Recycled Plastics Market