
 Global Recycled Base Oil Market | 2026-2036
Global Recycled Base Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Recycled Base Oil Market Intelligence
European capacity expansion in re-refining is fragmenting the supplier landscape, which was previously dominated by regional collectors. Clean Harbors leverages its extensive hazardous waste collection network in North America to secure a consistent feedstock supply. PURAGLOBE differentiates through its advanced UOP HyLube hydrotreating technology to produce high-quality Group III base oils. Avista Oil Deutschland GmbH sustains a strong position within the German and Central European markets through its integrated collection and re-refining model.
Recycled base oil is a lubricant feedstock derived from used oils through multi-stage re-refining. This process utilizes techniques like thin-film evaporation and hydrotreating to remove contaminants and restore the oil's chemical properties. Its primary purpose is to displace virgin crude-derived base oils in new lubricant blends for sustainability and cost reasons. While re-refined base oil forms the core product segment, applications in industrial lubricants and metalworking fluids are creating new margin opportunities beyond the high-volume automotive engine oil sector.
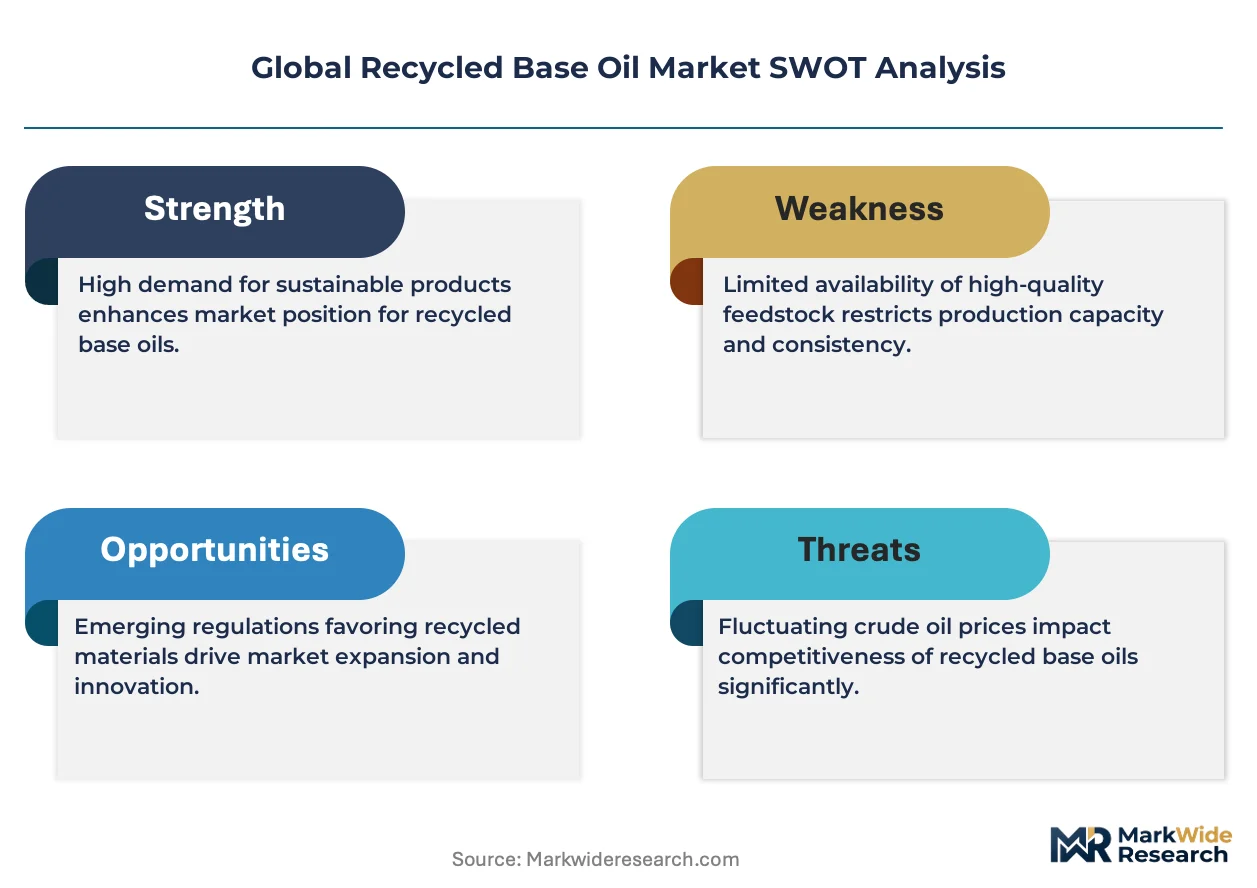
Regulatory frameworks such as the US EPA's used oil management program and the EU's Waste Framework Directive are critical to market structure. These policies mandate or encourage the collection and proper recycling of used oils, creating a reliable feedstock supply for re-refiners. China's dual carbon goals also support the expansion of its domestic recycling capacity. Future competitiveness will depend on a firm's ability to upgrade re-refining processes to produce Group II and Group III equivalent base oils consistently.
Market Dynamics
The central force shaping the market is the global regulatory pivot towards circular economy models. Mandates and incentives, such as the European Union's Green Deal, are compelling industries to treat used oil as a valuable feedstock rather than waste, structuring the entire supply chain.
Growth Catalysts
- Corporate Sustainability Mandates:Large transportation and industrial firms are adopting recycled lubricants to meet internal ESG targets and reduce their carbon footprint, creating consistent demand for engine and hydraulic oils with re-refined content.
- Regulatory Frameworks:Policies like the US EPA's used oil management program and the EU's Waste Framework Directive create a structured and reliable feedstock supply by encouraging or mandating used oil collection and recycling.
- Cost Competitiveness:Recycled base oils offer a cost-effective alternative to virgin base oils, providing lubricant blenders with a hedge against volatile crude oil prices and improving formulation cost stability.
Market Restraints
- Feedstock Quality Variability:Inconsistent quality and high levels of contamination in collected used oil increase processing complexity and cost for re-refiners, impacting final product yield and profitability.
- Competition from Virgin Oils:Periods of low crude oil prices can diminish the economic advantage of using recycled base oils, slowing adoption by cost-sensitive lubricant blenders who may revert to virgin feedstocks.
- Technical Upgrading Hurdles:Significant capital investment and technical expertise are required to upgrade re-refining facilities to consistently produce high-purity Group II and Group III base oils that can compete with top-tier virgin products.
Strategic Opportunities
- Expansion into Industrial Applications:Developing specialized recycled base oil grades for industrial lubricants, greases, and metalworking fluids offers a path to higher margins and diversification beyond the high-volume automotive sector.
- Emerging Market Capacity Building:Policy support for circular economies in nations like China under its dual carbon goals presents an opportunity for investment in new collection infrastructure and advanced re-refining plants.
- Advanced Separation Technologies:The adoption of solvent extraction and advanced membrane filtration technologies prior to hydrotreating can improve feedstock quality, boost efficiency, and lower the overall cost of producing high-grade base oils.
Industry Challenges
- Capital-Intensive Technology:The high upfront cost of constructing facilities with advanced hydrotreating and thin-film evaporation units creates a significant barrier to entry and limits the pace of capacity expansion for smaller operators.
- Logistical Network Complexity:Managing fragmented and geographically dispersed used oil collection networks to ensure a steady, predictable, and uncontaminated feedstock supply remains a major operational challenge for re-refiners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Recycled Base Oil Market |
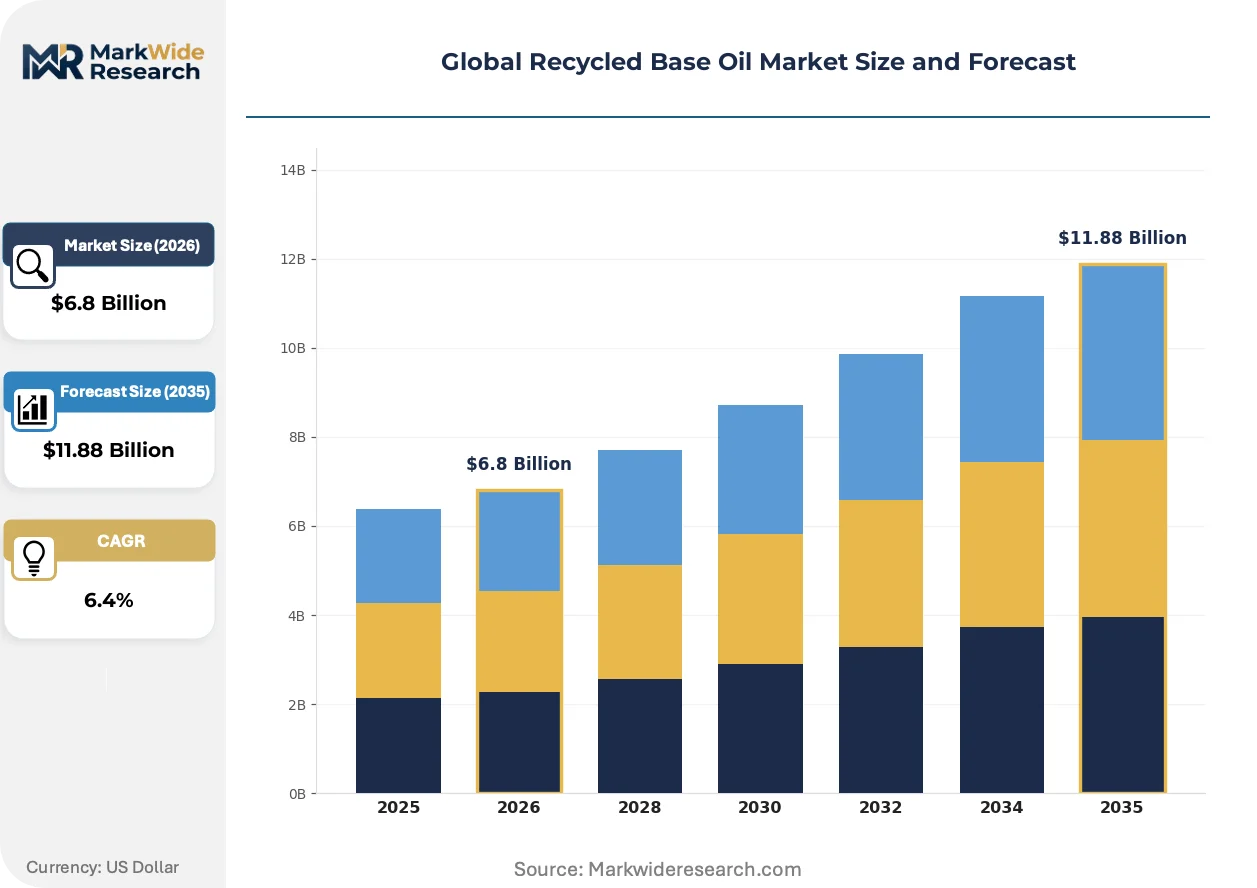
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Premium Base Oil, Group III Base Oil, Re-refined Base Oil, Synthetic Base Oil, Blend Base Oil Application: Industrial Lubricants, Metalworking Fluids, Automotive Engine Oil, Hydraulic Fluids, Marine Lubricants End User: Manufacturing Plants, Transportation Fleets, Agricultural Equipment, Construction Machinery, Power Generation Units Distribution Channel: Direct Sales, Distributors, Wholesalers, Online Retailers, Exporters |
| Companies Covered | Clean Harbors, Inc., Valvoline LLC, PURAGLOBE, Crystal Clean, Inc., Avista Oil Deutschland GmbH, NexLube, Hering VPT, Terrapure BR Ltd., Gulf Basin Petroleum Recycling Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Recycled Base Oil Market Strategic Shifts & Innovations
A fundamental evolution is underway as the industry shifts from basic oil recycling to the sophisticated production of high-performance feedstocks. This transition is driven by technological advancements in purification and regulatory pressures for higher quality, making recycled oils functionally equivalent to virgin products.
Advanced hydrotreating is a catalytic process that uses hydrogen to remove impurities and stabilize molecules in used oil. Lubricant blenders are increasingly specifying re-refined oils produced with this method to ensure performance in modern engine oil formulations. This technology is virtualizing the performance gap between premium recycled base oils and their virgin Group II and Group III counterparts, making them interchangeable.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a significant policy shift with indirect market consequences. It compels large companies to disclose the environmental impact of their supply chains, including lubricant procurement. This affects lubricant blenders and their industrial customers, who now face increased pressure to use and document the percentage of recycled content in their products to meet reporting requirements.
Corporate purchasing behavior is changing to prioritize supply chain transparency and documented sustainability metrics. This disrupts traditional, price-centric procurement by forcing lubricant suppliers to validate the recycled content and carbon footprint of their products. The trend is most pronounced in the automotive and heavy-duty fleet sectors in North America and Europe, where ESG reporting is becoming standard practice.
Global Recycled Base Oil Market Segmentation
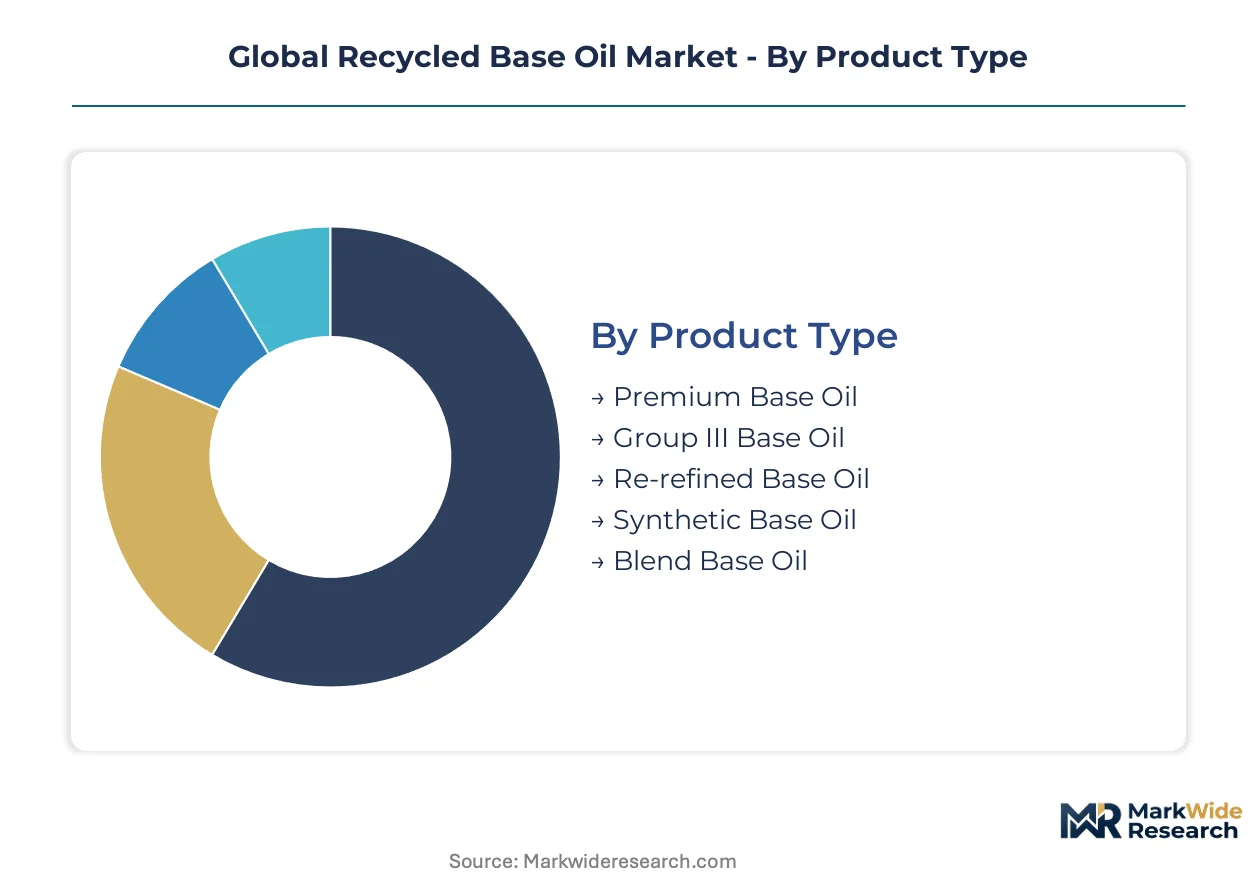
The segmentation analysis for the Global Recycled Base Oil Market illustrates the diverse product forms, end-use applications, and operational models driving demand. Understanding these distinct segments helps identify specific growth pockets and competitive arenas within the re-refining industry. This granular view is essential for strategic market positioning.
Product Type:
The product type segmentation reveals the use-case spectrum for recycled base oils, ranging from foundational re-refined products to advanced synthetic equivalents.
- Group III Base Oil:These highly refined base oils undergo extensive hydrocracking and hydroisomerization, possessing excellent viscosity index and low volatility. Demand concentrates in high-performance automotive engine oil formulations in Europe due to stringent emissions standards.
- Re-refined Base Oil:This core segment encompasses base oils produced from used oils through processes like thin-film evaporation and hydrotreating. Its demand is sustained by cost-conscious lubricant blenders seeking sustainable alternatives in North America.
- Premium Base Oil:These high-quality base oils, often Group II or Group III equivalent, suit demanding lubricant applications.
- Synthetic Base Oil:These chemically engineered base oils, like PAOs and Esters, offer superior performance in extreme conditions.
- Blend Base Oil:This refers to a mixture of base oils, including recycled content, for specific lubricant performance.
Established volume favors Re-refined Base Oil; emerging adoption favors Group III Base Oil.
Application:
The application focus highlights where recycled base oils are integrated into diverse lubricant formulations across various industrial and transportation sectors.
- Automotive Engine Oil:This segment represents the largest application for recycled base oils, used in passenger vehicles and heavy-duty fleets. Demand is driven by corporate sustainability mandates from large fleet operators in the United States and Germany.
- Industrial Lubricants:Recycled base oils find use in a broad range of industrial applications, including gear and compressor oils. New margin opportunities emerge as manufacturing plants in Europe seek to reduce their environmental footprint.
- Metalworking Fluids:These fluids, crucial for machining, utilize recycled base oils for their lubricating and cooling properties.
- Hydraulic Fluids:Recycled base oils are formulated into hydraulic systems for power transmission and equipment operation.
- Marine Lubricants:This application involves lubricants for marine engines and auxiliary equipment, where sustainability mandates gain traction.
Automotive Engine Oil currently dominates consumption, while Industrial Lubricants are expanding most quickly as new opportunities emerge.
End User:
The end-user segmentation classifies the primary customer types that procure lubricants containing recycled base oils for their operational needs.
- Transportation Fleets:This segment includes commercial trucking companies, public transport, and logistics firms using significant engine and hydraulic oils. Corporate sustainability mandates within these large fleets in North America drive consistent demand for recycled content.
- Manufacturing Plants:Industrial facilities across sectors, from automotive to chemicals, consume lubricants for machinery, processing, and maintenance. Demand for sustainable industrial lubricants increases within these facilities in Germany and the US.
- Agricultural Equipment:Farmers and agricultural businesses use lubricants for tractors, harvesters, and heavy machinery.
- Construction Machinery:This segment covers heavy equipment like excavators and bulldozers, requiring robust hydraulic and engine oils.
- Power Generation Units:Power plants utilize specialized lubricants for turbines, generators, and auxiliary equipment, often under demanding conditions.
Transportation Fleets represent a significant volume consumer, while Manufacturing Plants are increasingly prioritizing sustainable lubricant procurement.
Distribution Channel:
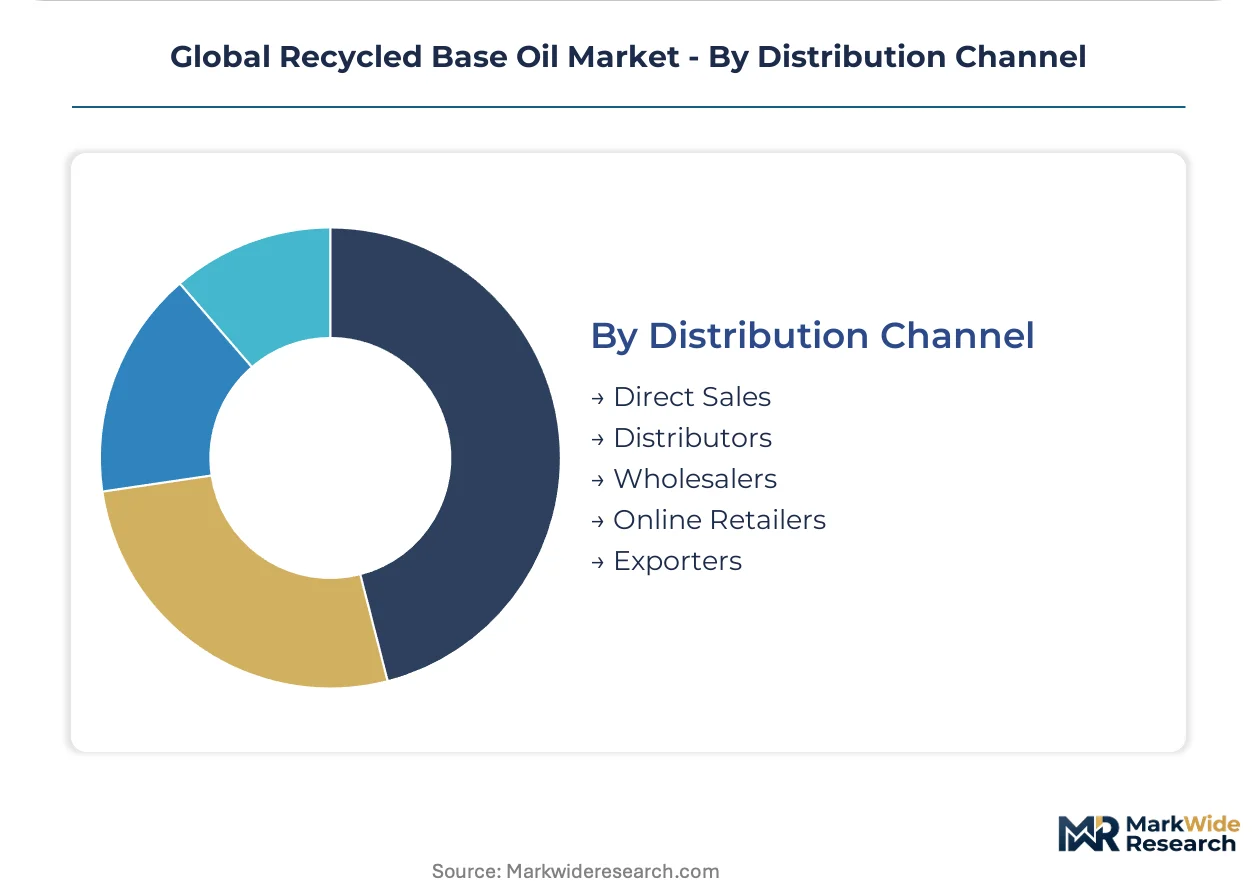
The distribution channel segmentation outlines various market reach strategies employed by recycled base oil producers and lubricant blenders to deliver products to end-users.
- Direct Sales:Producers sell directly to large industrial clients or lubricant blenders, facilitating customized solutions and stronger relationships. This channel is preferred for high-volume contracts with major transportation fleets.
- Distributors:Independent distributors handle sales, logistics, and technical support, providing market access to smaller lubricant blenders and end-users. This channel is crucial for reaching fragmented industrial sectors in Europe.
- Wholesalers:These entities purchase in bulk from producers and resell to smaller distributors or retailers, serving as a supply chain intermediary.
- Online Retailers:E-commerce platforms offer a growing channel for specialized lubricants and smaller purchases, enhancing market accessibility.
- Exporters:Companies engaged in international trade of recycled base oils, supplying markets beyond domestic production capabilities.
Direct Sales offers tailored engagement for large customers, whereas Distributors provide extensive market penetration across diverse regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global recycled base oil market exhibits varying consumption mixes across regions. While North America focuses on cost-effectiveness, Europe prioritizes high-performance Group III base oils driven by stringent environmental standards. Demand concentration in specific countries reflects established collection infrastructure and strong regulatory support for circular economy models.
United States
Demand for recycled base oils in the United States stems from large transportation fleets meeting corporate sustainability mandates. The US EPA's used oil management program provides a structured framework for feedstock collection. California, a key region, supports strong regulatory backing and established collection infrastructure.
Germany
Germany demonstrates strong demand for recycled base oils, particularly in its manufacturing plants and automotive sector. The EU's Waste Framework Directive encourages used oil recycling across the nation. Avista Oil Deutschland GmbH sustains its strong position within the German market through integrated collection and re-refining.
China
China's recycled base oil market is expanding due to its dual carbon goals and increasing industrial lubricant applications. The national government actively supports the expansion of domestic recycling capacity. Major industrial hubs like the Yangtze River Delta are seeing investments in new collection infrastructure and advanced re-refining plants.
France
French industrial sectors and transportation fleets are increasingly adopting recycled base oils to meet European sustainability targets. The European Union's Green Deal incentivizes circular economy models, including used oil re-refining. Paris and its surrounding industrial regions are witnessing growing interest in sustainable lubricant procurement.
United Kingdom
The United Kingdom's industrial and automotive sectors are driving demand for sustainable lubricant solutions containing recycled base oils. UK environmental regulations, aligned with broader European directives, promote used oil collection and recycling efforts. Industrial clusters around Birmingham and Manchester are actively integrating re-refined content into their operational lubricants.
Global Recycled Base Oil Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the global recycled base oil market. The market structure exhibits a tiered consolidation, with established players leveraging extensive collection networks and advanced processing technologies. Strategic archetypes include integrated re-refiners, specialized technology providers focusing on high-grade outputs, and large waste management firms securing feedstock. Dominant competitive moves involve significant capital investment in capacity expansion and strategic partnerships for feedstock security and market access.
Within the integrated re-refiner archetype, Avista Oil Deutschland GmbH sustains a strong position in German and Central European markets through its comprehensive collection and processing model. This approach ensures a stable supply chain for its re-refined products. Clean Harbors, Inc. exemplifies a large North American waste management firm, leveraging its extensive hazardous waste collection network to secure consistent feedstock supply for its recycling operations. PURAGLOBE differentiates through its advanced UOP HyLube hydrotreating technology, allowing it to produce high-quality Group III base oils and representing a specialized technology provider focused on premium product segments globally.
| Leading Market Players |
|---|
| Clean Harbors, Inc. |
| Valvoline LLC |
| PURAGLOBE |
| Crystal Clean, Inc. |
| Avista Oil Deutschland GmbH |
| NexLube |
| Hering VPT |
| Terrapure BR Ltd. |
| Gulf Basin Petroleum Recycling Co. |
| Others |
Cost & Logistics Intelligence
Crude oil price volatility determines both pricing tier spreads and the overall supply chain shape for recycled base oils. This dynamic forces lubricant blenders to balance cost savings from recycled content against the stability of virgin crude-derived feedstocks.
Pricing Analysis
Geographic price spreads for recycled base oils show Europe often commands a premium for Group III products compared to North America's broader re-refined base oil market. The dominant pricing model involves contract-based long-term offtake agreements for large volumes, supplemented by commodity spot pricing for smaller or opportunistic purchases. Price differentiation stems from the quality grade, particularly Group II and Group III equivalence, and the volume scale of the transaction. Pricing softness reflects competition from virgin oils when crude oil prices are low. Cost-sensitive lubricant blenders, especially those serving general industrial applications, exhibit the highest price sensitivity.
Supply Chain Analysis
Upstream feedstock sourcing for re-refiners relies heavily on established used oil collection networks. Geographic supply concentration centers in Germany, U.S. California, and China, driven by robust regulatory frameworks and infrastructure. The supply chain draws from a consistent stream of used oils, with hydrotreating catalysts representing a critical processing input. Feedstock quality variability presents a primary structural risk, impacting processing costs and final product yield. Downstream distribution runs through direct sales channels for major lubricant blenders and large transportation fleets, while independent distributors serve fragmented industrial sectors across Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat story, justified by significant regulatory entrenchment that mandates and incentivizes used oil recycling.
For Market Incumbents: Build regulatory entrenchment by actively participating in policy development for circular economy models. Expand collection infrastructure in key growth regions like China and upgrade re-refining facilities to consistently produce Group II and Group III equivalent base oils. This defends against virgin oil price volatility by securing premium product positioning. Invest in advanced hydrotreating technology to meet stringent performance specifications, a critical lever against emerging substitute technologies.
For New Entrants and Emerging Players: Establish a beachhead in specialized industrial lubricants and metalworking fluids applications. These segments offer higher margin opportunities and are less saturated than the automotive engine oil sector. Target emerging markets like China, where policy support for domestic recycling capacity creates a favorable environment. The most penetrable segment involves offering advanced separation technologies to improve feedstock quality, providing a distinct go-to-market angle.
For Investors and Strategic Acquirers: The EU Green Deal reshapes the acquisition landscape, favoring companies with proven sustainability credentials and advanced re-refining capabilities. Long-term viability rests on firms capable of consistently producing high-quality Group II and Group III base oils from used oils, driven by global sustainability mandates. Integrated re-refiners with extensive collection networks or proprietary advanced processing technologies represent attractive acquisition archetypes. Consistency in Group III output from re-refiners serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding re-refining capacity in emerging markets like China meets growing regional demand and leverages policy support. |
| Backward Integration | Integrating into used oil collection networks secures consistent feedstock supply and enhances operational control for re-refiners. |
| Green Manufacturing Transition | Adopting advanced hydrotreating technologies ensures the production of high-quality Group II and Group III base oils. |
| Long-term Supply Agreement | Securing long-term contracts with large transportation fleets guarantees stable demand for recycled lubricant content. |
| Joint Venture | Forming joint ventures for advanced separation technologies improves feedstock quality and processing efficiency for re-refiners. |
Research Approach
Initial hypotheses were tested against primary input from re-refinery plant managers, lubricant blenders, waste management executives, and fleet procurement officers, and refined through iterative feedback. This approach combined in-depth primary interviews with comprehensive secondary validation. Secondary data sources included US EPA reports, EU Waste Framework Directive documents, industry association publications, and corporate sustainability reports, all triangulated through bottom-up and top-down analyses.
Demand-supply balance formed the core of the analytical framework across the projection horizon. The quantitative model segmented the market by product type, application, end-user, distribution channel, and re-refining technology tier. Compound annual growth rates were derived from historical trends, identified market drivers, and projected policy impacts. Used oil collection rates and regulatory mandates for recycled content served as critical industry-specific forecast inputs.
Stress conditions across crude prices and regulatory enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological advancements and sustained policy support. Geopolitical instability affecting crude prices or rapid technological shifts in virgin oil production represent specific risk factors. Cross-checking against industry benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Recycled PET Flakes Market
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
Non-Ferrous Scrap Recycling Market
Recycled Plastics
Vietnam Plastics Market
Recycled Plastics
Recycled Leather Market
Recycled Plastics
Plastic Lumber Market
Recycled Plastics
Post-Consumer Recycled Plastics in Consumer Electronics Market
Recycled Plastics
Polyvinyl Chloride (PVC) Market
Recycled Plastics
North America Recycled Plastics Market
Recycled Plastics
Global Recycled Asphalt Market
Recycled Plastics
BPA Free Plastic Market
Recycled Plastics
Myanmar Plastics Market
Recycled Plastics
Recycled Thermoplastic Market
Recycled Plastics
South-East Asia (SEA) Plastics Market
Recycled Plastics
US Plastics Market
Recycled Plastics
Modified Polypropylene Market