
 USA Plastic-To-Fuel Market | 2026-2036
USA Plastic-To-Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
USA Plastic-To-Fuel Market Analytics
The pricing and performance gap between ASTM-certified pyrolysis oils and unrefined commodity outputs is realigning procurement patterns across downstream buyers. Brightmark Energy leverages its Indiana facility to sustain continuous production of drop-in diesel substitutes. Agilyx Corporation anchors Pacific Northwest operations with specialized polystyrene-to-styrene oil conversion. Plastic2Oil, Inc. competes on modular system deployment for smaller waste streams.
Plastic-to-fuel technology converts non-recyclable polymers into hydrocarbon liquids through thermal decomposition in oxygen-limited environments, typically operating between 400°C and 800°C to crack long-chain polymers into shorter fuel-range molecules. Pyrolysis oil dominates current output volumes while synthetic gas from mixed plastics feedstock shows the fastest capacity expansion. Thermochemical processes lead installed capacity but catalytic upgrading commands premium pricing through higher yields of gasoline-range hydrocarbons.
EPA fuel registration requirements under 40 CFR Part 79, state-level renewable fuel standards in California and Oregon, and OSHA process safety management rules collectively shape facility permitting timelines and product qualification pathways. The Department of Energy's plastics upcycling grants are accelerating pilot-scale catalytic systems toward commercial validation. Stakeholders must monitor how LCFS credit values and pyrolysis oil pathway approvals interact to determine project economics.
Market Dynamics
The EPA's 40 CFR Part 79 fuel registration pathway and state-level extended producer responsibility mandates are compressing project development timelines while cement plants and industrial boilers absorb off-spec pyrolysis oils at rising volumes.
Growth Catalysts
- Extended Producer Responsibility Laws:California, Oregon, and Maine impose waste diversion mandates that redirect non-recyclable polymer streams toward pyrolysis facilities.
- Cement Kiln Co-Processing:Cement plants in Texas and Ohio substitute pyrolysis oil for petroleum coke in clinker production, cutting fuel costs and emissions simultaneously.
- Catalytic Upgrading Systems:Pilot-scale reactors at Department of Energy-funded sites yield gasoline-range hydrocarbons at premium pricing versus unrefined pyrolysis oil.
Market Restraints
- Feedstock Cost Volatility:Mixed plastic bale prices fluctuate with resin commodity cycles and export ban disruptions, squeezing facility margins.
- Permitting Friction:OSHA process safety management compliance and state air quality permits extend facility commissioning by 18-36 months in most jurisdictions.
- Fossil Fuel Substitution:Abundant shale-derived naphtha and natural gas liquids in the Gulf Coast region undercut pyrolysis oil pricing for refinery blendstock applications.
Strategic Opportunities
- Polystyrene-to-Styrene Monomer:Specialized depolymerization systems unlock circular chemical pathways for food-service packaging waste streams currently landfilled.
- Low Carbon Fuel Standard Credits:California LCFS and Oregon CFP credit stacking with federal incentives improves project returns for ASTM-certified fuel outputs.
- Modular Distributed Systems:Containerized pyrolysis units address rural and island waste streams where landfill capacity constraints and transport costs concentrate.
Industry Challenges
- ASTM Certification Timelines:Fuel pathway approvals for pyrolysis-derived diesel substitutes require 24-48 months of engine testing and emissions validation.
- Pyrolysis Oil Stability:Acid content and oxygenate levels in unrefined outputs complicate storage, transport, and co-processing agreements with conventional refiners.
- Skilled Technician Scarcity:Thermal processing and catalytic reactor operations demand cross-trained operators familiar with both petrochemical and waste management protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Plastic-To-Fuel Market |
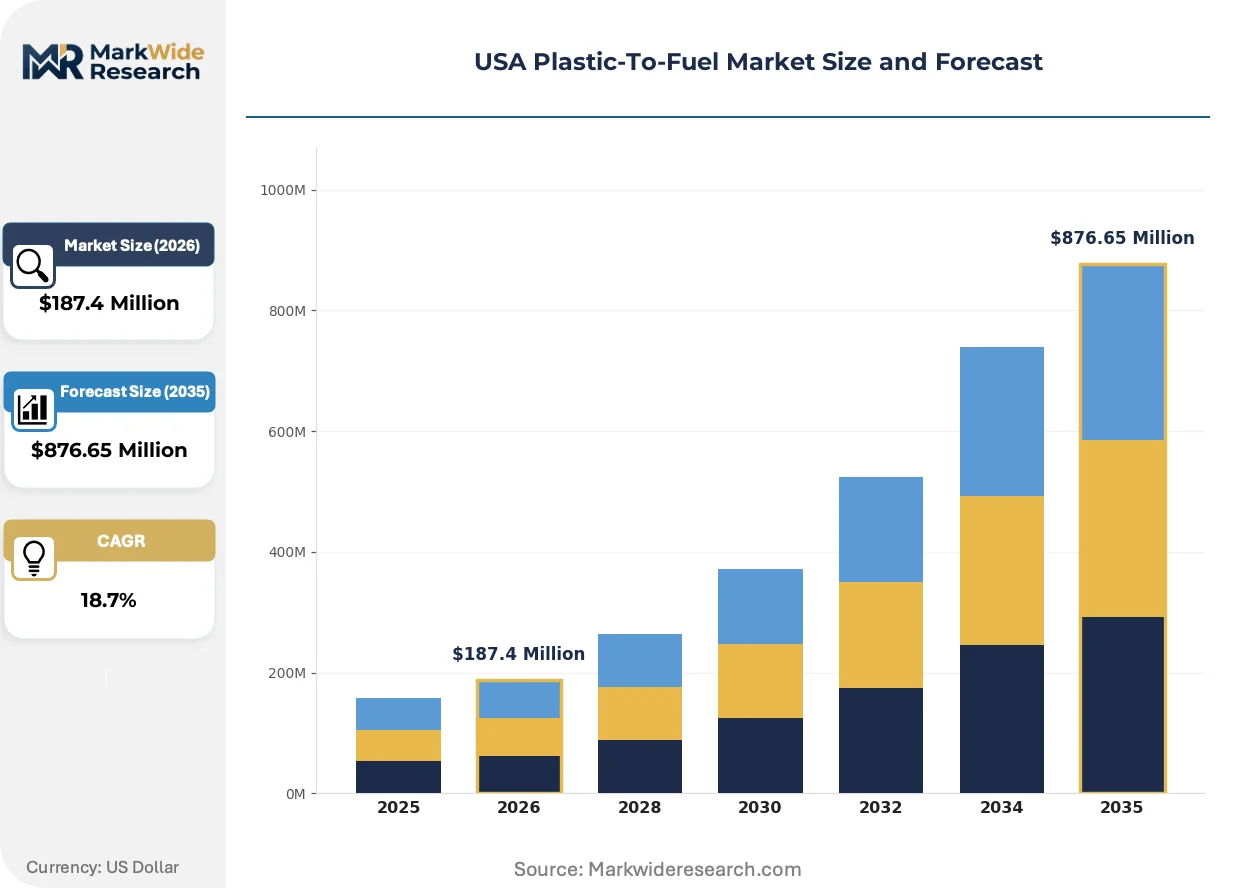
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pyrolysis Oil, Synthetic Gas, Diesel, Gasoline Technology: Thermochemical, Biochemical, Catalytic, Advanced Oxidation Feedstock: Polyethylene, Polypropylene, Polystyrene, Mixed Plastics End User: Energy Sector, Transportation, Industrial, Refineries |
| Companies Covered | Agilyx Corporation, Brightmark Energy, Plastic2Oil, Inc., Renewlogy, RES Polyflow, Vadxx Energy, Alterra Energy, Cynar Plc, Green Envirotec Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Plastic-To-Fuel Market Evolving Landscape
Thermochemical conversion platforms are absorbing capital and engineering talent as refiners and waste processors race to qualify pyrolysis-derived streams for existing fuel infrastructure.
Catalytic fast pyrolysis with zeolite upgrading is absorbing investment from cement and steel sector offtakers seeking drop-in fuel replacements. Brightmark Energy's Indiana facility demonstrates continuous production at scale. ASTM D7544 certification for pyrolysis liquid fuels is compressing qualification timelines for refinery co-processing agreements.
The EPA's refined fuel standards under 40 CFR Part 79 and state-level renewable portfolio standards are tightening product qualification pathways. California Air Resources Board LCFS methodology updates for waste-to-fuel pathways determine credit generation rates. Facility developers in Texas and Ohio align engineering designs with anticipated pathway approvals.
Industrial offtakers now specify ASTM-certified pyrolysis oil in procurement contracts, displacing spot-market purchases of unrefined commodity outputs. Cement plants in the Midwest and Southeast embed fuel quality specifications in multi-year supply agreements. This certification-driven preference shift concentrates procurement among producers with in-house upgrading capability.
USA Plastic-To-Fuel Market Segmentation
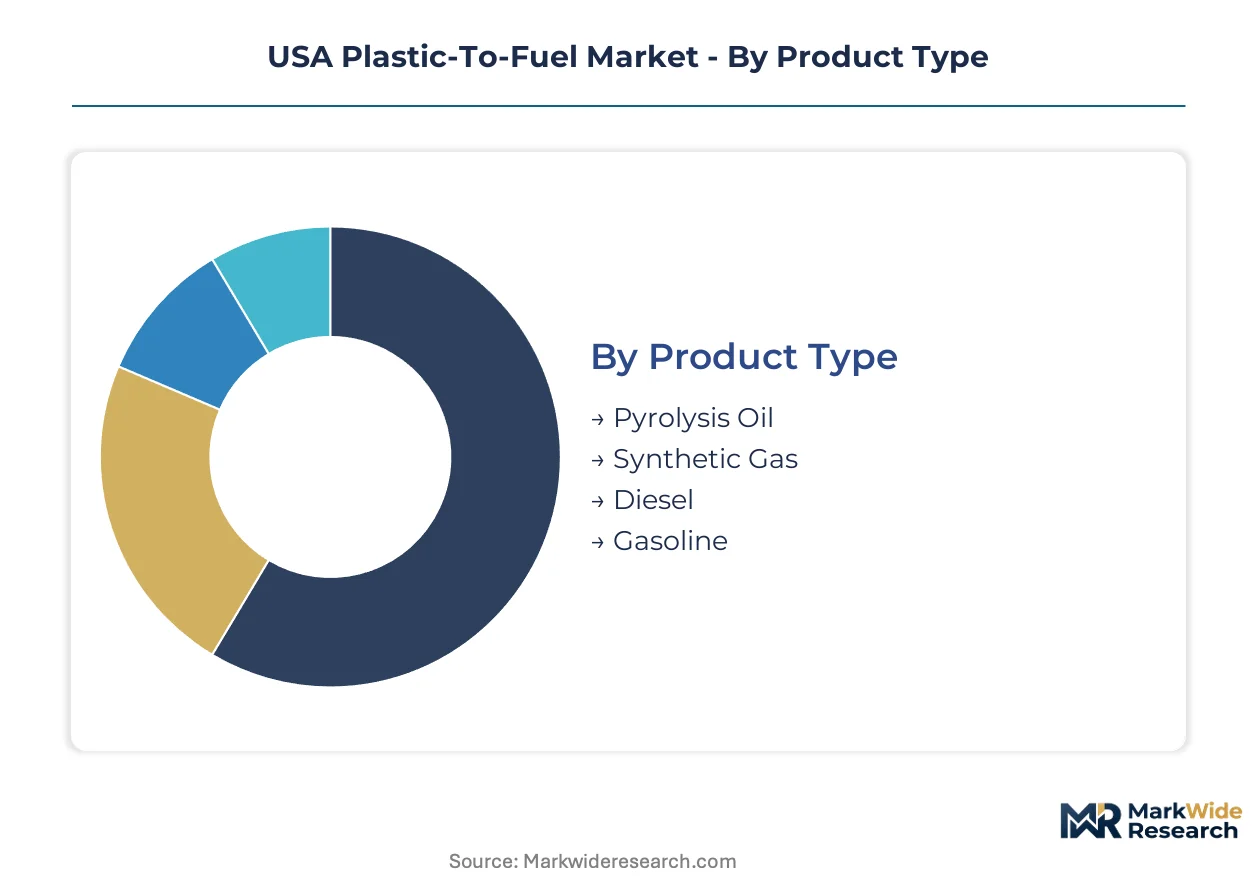
Segmentation reveals how technology choices and feedstock access dictate facility economics across the USA Plastic-To-Fuel Market. Product certification tiers and end-user specifications create divergent margin structures that reshape competitive positioning.
Product Type:
Supply concentration in Texas and Ohio petrochemical corridors determines which outputs achieve commercial scale first.
- Pyrolysis Oil:Unrefined thermochemical output with high acid and oxygenate content dominates current production volumes. Cement plants in Ohio and industrial boilers across the Midwest absorb off-spec streams for co-processing, though storage instability complicates long-haul transport economics.
- Synthetic Gas:Mixed plastics feedstock yields syngas through gasification routes operating above 800°C. Texas Gulf Coast refineries pilot this pathway for circular hydrogen production, attracted by integration with existing steam methane reforming infrastructure.
- Diesel:ASTM D975-certified drop-in substitutes command premium pricing from California fleet operators seeking LCFS credit stacking.
- Gasoline:Catalytic upgrading to gasoline-range hydrocarbons remains pilot-scale, constrained by octane specification compliance costs.
Pyrolysis Oil absorbs the bulk of installed capacity; Synthetic Gas is expanding most quickly.
Technology:
Cost tier separation between commodity thermochemical outputs and premium catalytic systems widens as ASTM certification becomes a procurement gate.
- Thermochemical:Pyrolysis and gasification platforms operating at 400-800°C represent the mature installed base. Brightmark Energy's Indiana facility demonstrates continuous production at commercial scale, though product quality variability limits refinery offtake agreements.
- Catalytic:Zeolite upgrading and hydroprocessing units yield gasoline and diesel fractions meeting ASTM specifications. Department of Energy-funded pilots in the Pacific Northwest target 24-48 month pathway approvals for fuel registration under 40 CFR Part 79.
- Biochemical:Enzymatic depolymerization approaches remain pre-commercial, constrained by polymer crystallinity challenges and enzyme cost structures.
- Advanced Oxidation:Plasma-assisted and supercritical water systems occupy niche research positions with limited operational track records.
Thermochemical systems anchor current revenue; Catalytic routes are gaining share fastest.
Feedstock:
Geography of waste generation and sorting infrastructure determines feedstock cost structures and contamination risk profiles.
- Polyethylene:HDPE and LDPE streams from packaging and film waste deliver consistent paraffinic yields with minimal heteroatom contamination. Texas material recovery facilities concentrate supply for Gulf Coast processors.
- Polypropylene:Automotive and durable goods waste streams face collection fragmentation but offer favorable propylene recovery economics through specialized depolymerization.
- Polystyrene:Food-service packaging diverted from California landfills feeds Agilyx Corporation's Oregon operations for styrene monomer recovery.
- Mixed Plastics:Post-consumer bales with resin codes 3-7 dominate volume availability but require preprocessing investments that erode facility margins.
Polyethylene commands the deepest processor relationships; Polystyrene is climbing the fastest as circular chemical pathways mature.
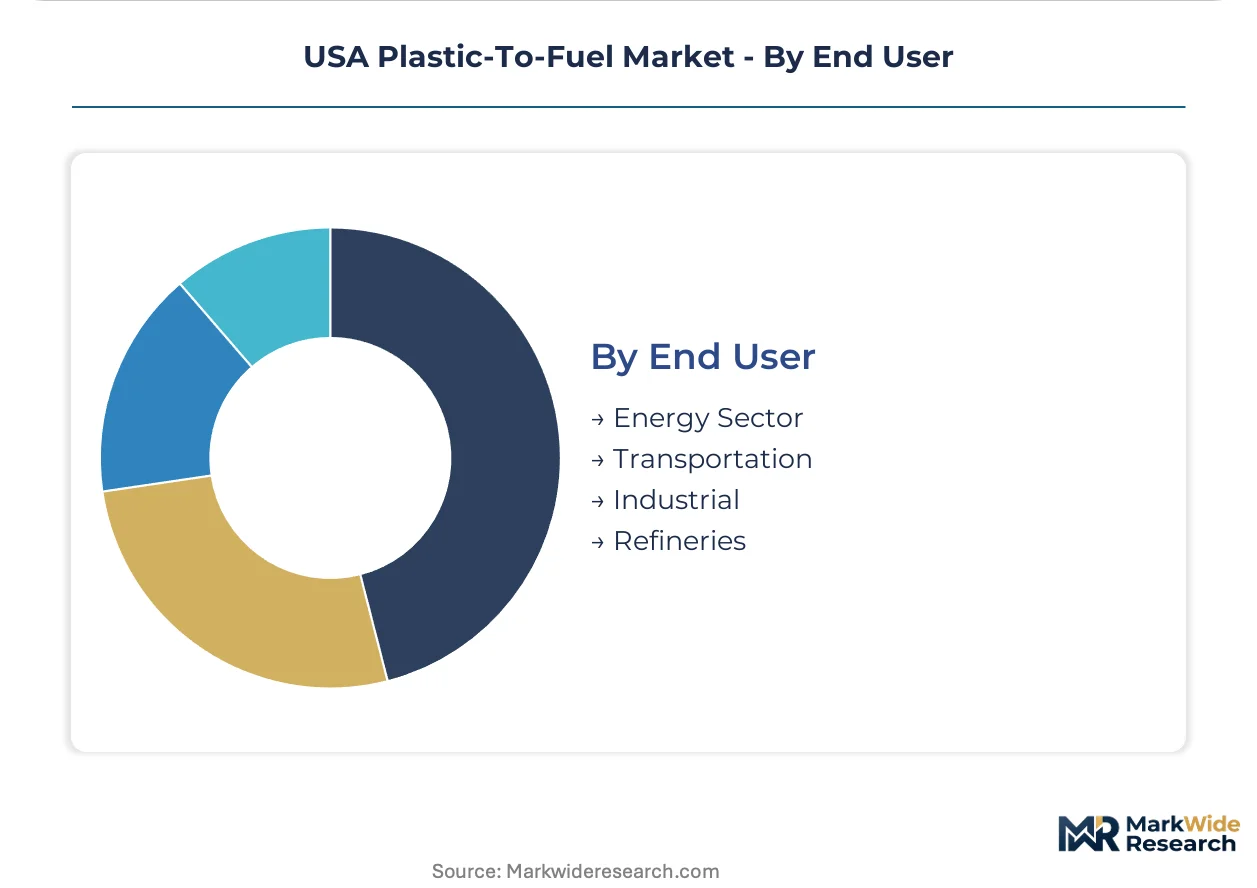
End User:
Customer type segmentation exposes divergent specification tolerances and contract duration preferences across downstream buyers.
- Energy Sector:Power generators and industrial thermal users purchase off-spec pyrolysis oil under spot arrangements with minimal quality guarantees.
- Transportation:California and Oregon fleet operators demand ASTM-certified diesel substitutes with full LCFS credit documentation, compressing supplier qualification timelines.
- Industrial:Cement kilns in Texas and Ohio embed multi-year fuel supply agreements with embedded quality specifications, displacing petroleum coke consumption.
- Refineries:Gulf Coast and Midwest refiners pilot co-processing of upgraded pyrolysis streams, though shale-derived naphtha pricing undercuts circular feedstock economics.
Industrial offtakers lock in the longest contract tenors; Transportation applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel anchors North American pyrolysis oil production capacity, drawing mixed plastic feedstock from Gulf Coast material recovery facilities and Texas petrochemical complexes seeking circular feedstock alternatives.
Texas
Texas concentrates the deepest pyrolysis infrastructure investments, with Gulf Coast refineries piloting co-processing agreements for upgraded plastic-derived streams. EPA Region 6 air quality permits govern facility commissioning timelines, while OSHA process safety management compliance shapes operational protocols. The Houston-The Woodlands-Sugar Land metro area hosts multiple thermochemical conversion facilities supplying cement kilns and industrial boilers across the state.
California
California's SB 54 extended producer responsibility mandates divert non-recyclable polymers from landfills toward conversion facilities. California Air Resources Board LCFS methodology updates determine credit generation rates for ASTM-certified fuel outputs, with pathway approvals requiring 24-48 month validation cycles. The Los Angeles-Long Beach-Anaheim corridor concentrates demand from fleet operators seeking diesel substitutes with full LCFS documentation.
Ohio
Ohio cement plants absorb off-spec pyrolysis oil volumes for clinker production, displacing petroleum coke consumption under multi-year supply agreements. Ohio EPA Division of Air Quality permits govern facility emissions, while state-level waste diversion goals redirect post-industrial plastic streams. The Cleveland-Elyria metro area anchors Midwest pyrolysis oil demand from industrial thermal users.
Indiana
Indiana hosts continuous commercial-scale thermochemical production demonstrating sustained output of drop-in diesel substitutes. Indiana Department of Environmental Management permits and federal EPA fuel registration under 40 CFR Part 79 shape product qualification pathways. The Indianapolis-Carmel-Anderson region serves as a distribution hub for ASTM-certified outputs to transportation fleet operators.
Oregon
Oregon's Clean Fuels Program credit stacking improves project economics for specialized polystyrene-to-styrene oil conversion operations. Oregon Department of Environmental Quality rules govern waste-to-fuel facility siting, while Pacific Northwest polymer waste streams feed circular chemical pathways. The Portland-Vancouver-Hillsboro metro area concentrates food-service packaging diversion infrastructure.
USA Plastic-To-Fuel Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with ASTM D7544-qualified outputs commanding supply contract premiums over unrefined pyrolysis oil. The vendor base stratifies between integrated thermochemical operators with captive upgrading capability and modular system deployers serving distributed waste streams. Three archetypes dominate: continuous commercial-scale producers, specialized feedstock processors, and containerized unit fabricators. Capacity expansion and strategic partnerships represent the dominant competitive vectors as offtakers lock in multi-year supply agreements.
Within the continuous production tier, Brightmark Energy and Agilyx Corporation exemplify divergent strategic positions—Brightmark Energy anchors Midwest operations with sustained diesel substitute output, while Agilyx Corporation occupies specialized polystyrene conversion in the Pacific Northwest. Plastic2Oil, Inc. sits within the modular deployment archetype, addressing rural and island waste streams where transport economics favor distributed processing. These three companies represent the operational spectrum from centralized commercial scale to distributed containerized systems.
| Leading Market Players |
|---|
| Agilyx Corporation |
| Brightmark Energy |
| Plastic2Oil, Inc. |
| Renewlogy |
| RES Polyflow |
| Vadxx Energy |
| Alterra Energy |
| Cynar Plc |
| Green Envirotec Holdings |
| Others |
Value Network & Pricing Analysis
California's SB 54 extended producer responsibility mandate gates both qualified supply and premium-tier pricing access, as facilities demonstrating ASTM D7544 certification capture multi-year offtake agreements while uncertified producers compete for spot-market cement kiln volumes.
Pricing Analysis
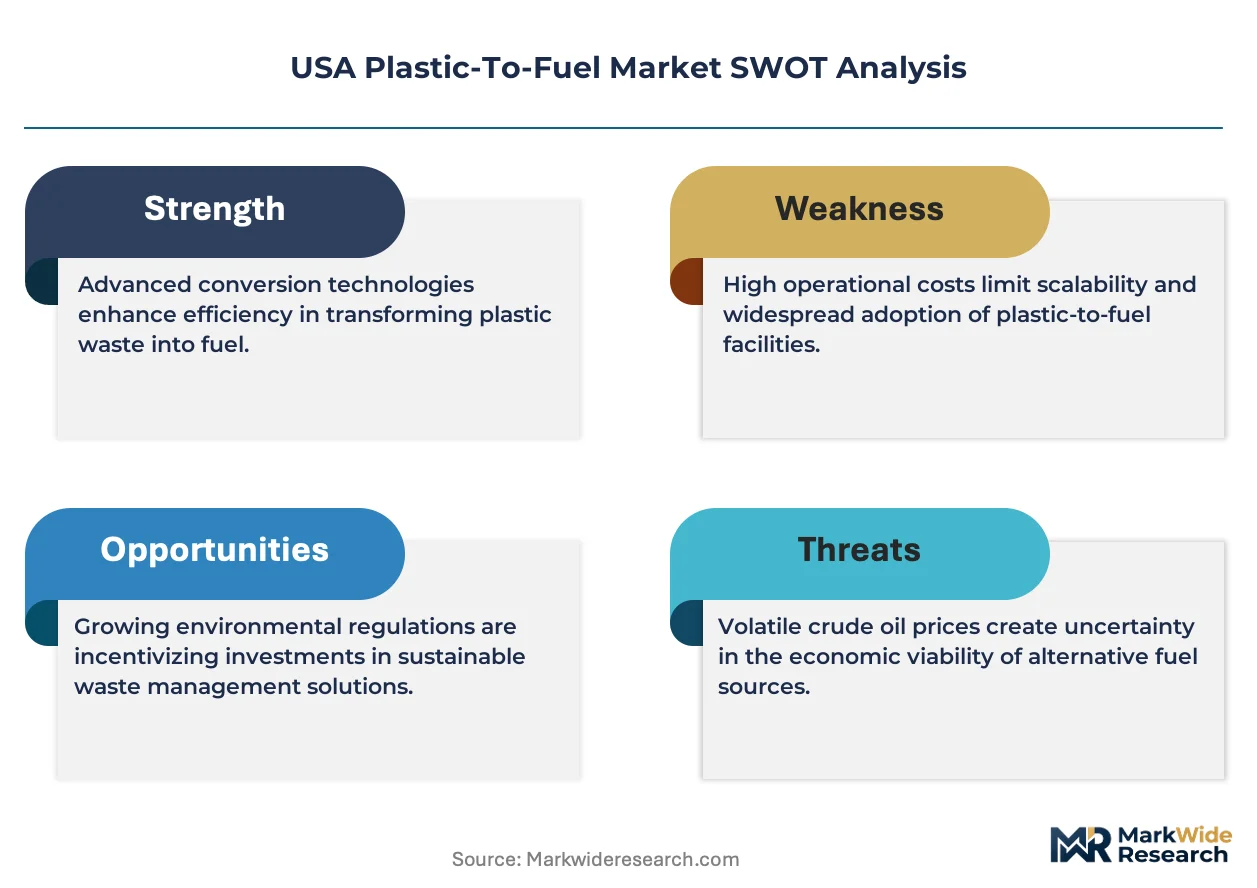
ASTM certification status anchors value-based pricing, with D7544-qualified pyrolysis oil commanding contract premiums over unrefined commodity outputs. Price differentiation rests on fuel pathway approval tier and LCFS credit documentation completeness. Cost compression in the unrefined tier is intensifying because abundant Gulf Coast shale-derived naphtha undercuts circular feedstock economics. Cement plants and industrial boilers show highest price sensitivity; California fleet operators seeking LCFS credit stacking demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements from Midwest cement plants and California refineries mandate multi-supplier qualification for ASTM-certified streams. Feedstock supply concentrates in Texas, Ohio, and California material recovery facilities. Raw material dependencies include mixed plastic bales, post-industrial polystyrene streams, and preprocessing equipment. Single-source vulnerability runs through specialized catalytic reactor fabricators. Distribution feeds from thermochemical conversion hubs via rail and tanker truck to industrial offtakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive feedstock preprocessing is reshaping competitive positioning, as facilities securing direct municipal contracts insulate margin structures from resin commodity cycle volatility.
For Market Incumbents: Hedge against shale-derived naphtha pricing pressure by securing multi-year municipal feedstock agreements in landfill-constrained geographies. Defend ASTM certification moats through accelerated pathway investment under 40 CFR Part 79, as uncertified commodity producers face displacement from refinery co-processing agreements. Capacity addition in Indiana and Ohio petrochemical corridors reinforces supply security. For New Entrants and Emerging Players: Begin with modular containerized deployment targeting rural and island waste streams where transport economics favor distributed processing. Pacific Northwest polystyrene-to-styrene conversion and Appalachian mixed-plastics preprocessing represent penetrable white-space. Go-to-market leverage rests on Oregon Clean Fuels Program credit stacking documentation. For Investors and Strategic Acquirers: EPA pathway approval acceleration is the leading indicator that catalytic upgrading platforms will capture premium-tier pricing expansion. Five-to-ten year viability favors integrated thermochemical operators with captive upgrading capability over pure-play commodity producers. Acquisition targets include specialized polystyrene depolymerization assets and containerized system fabricators with operational track records.| Strategic Initiative | Industry Significance |
|---|---|
| ASTM Certification Investment | 40 CFR Part 79 fuel registration unlocks refinery co-processing agreements and LCFS credit stacking. |
| Feedstock Preprocessing Integration | Captive mixed-plastics sorting reduces contamination risk and stabilizes input cost structures. |
| Catalytic Upgrading Scale-Up | Zeolite reactor deployment yields gasoline-range hydrocarbons at premium pricing versus unrefined pyrolysis oil. |
| Multi-Year Industrial Offtake Agreements | Cement kiln supply contracts in Texas and Ohio displace petroleum coke consumption with volume commitments. |
| Modular System Fabrication | Containerized units address rural waste streams where landfill capacity constraints and transport costs concentrate. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across plant managers at thermochemical conversion facilities, procurement leads at cement and industrial boiler operators, EPA regulatory affairs specialists, and waste haulage contract managers. Secondary validation drew from EPA 40 CFR Part 79 registration databases, California Air Resources Board LCFS pathway approvals, state-level extended producer responsibility implementation reports, and OSHA process safety management audit disclosures. Bottom-up facility capacity modeling triangulated against top-down waste stream generation estimates.
Granularity-level modeling operated at technology-platform, feedstock-resin, and end-user-segment resolution across the projection horizon. Segmentation dimensions included product certification tier, thermochemical versus catalytic conversion route, polyethylene versus polystyrene versus mixed-plastics feedstock, and cement kiln versus refinery versus transportation fleet offtake. CAGRs derived from installed capacity buildout curves, feedstock cost trajectory assumptions, and LCFS credit value sensitivity analysis. Industry-specific inputs encompassed pyrolysis oil stability parameters and ASTM D7544 qualification timelines.
Underlying measurement precision varies by segment; ASTM-certified diesel substitute volumes carry tighter precision than unrefined pyrolysis oil spot-market estimates. Forecasts reflect assumptions regarding EPA pathway approval velocity, state EPR implementation pace, and shale naphtha pricing persistence. A model refresh is warranted upon material change in LCFS methodology updates or federal plastics upcycling grant allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Recycled Thermoplastic Market
Recycled Plastics
China Plastics Market
Recycled Plastics
Malaysia Plastics Market
Recycled Plastics
Global Recycled Asphalt Market
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Modified Polypropylene Market
Recycled Plastics
United States Non-Ferrous Scrap Recycling Market
Recycled Plastics
Plastic Lumber Market
Recycled Plastics
Indonesia Plastics Market
Recycled Plastics
Microplastic Recycling Market
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
Global Recycled Plastics Market
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
Plastic Compounds Market
Recycled Plastics
Asia-Pacific Plastic Waste Management Market