
 Global Recycled Asphalt Market | 2026-2036
Global Recycled Asphalt Market Size, Share, and Industry Trends Forecast 2026-2036
Global Recycled Asphalt Market Foresight
The gap between conventional hot mix production and in-place recycling throughput is narrowing as sensor-guided thermal profiling and foamed binder injection reach commercial scale. Astec Industries leverages its drum mix plant retrofit architecture to capture contractor upgrade cycles across North American highway programs. CRH sustains vertical integration from aggregate quarrying through asphalt terminal operations, locking in feedstock quality for reclaimed binder streams. Eurovia anchors European demand through its molecular rejuvenator partnerships with public works authorities in France and the United Kingdom.
Recycled asphalt comprises processed reclaimed asphalt pavement combined with virgin aggregate and rejuvenating agents to restore binder rheology for new pavement layers, typically achieving binder replacement ratios between 15% and 50% depending on mix design and agency specifications. Its primary purpose is to reduce virgin bitumen consumption while maintaining Marshall stability and rutting resistance comparable to conventional mixes. Hot mix asphalt dominates current volume due to entrenched agency specifications and contractor familiarity, though warm mix asphalt represents the fastest-expanding category as foaming and chemical additive technologies lower production temperatures and extend paving seasons. Reclaimed asphalt pavement as a standalone input stream commands attention from government agencies seeking lifecycle cost reductions on federally aided projects.
The US Federal Highway Administration and state DOTs including Texas DOT and Caltrans shape demand through binder replacement ratio caps and performance-graded mix approval protocols, while the EU Green Deal and national green public procurement rules in France and Germany mandate minimum recycled content thresholds for road contracts. The US EPA industrial materials recycling program and ECHA REACH compliance for rejuvenator chemicals further constrain formulation choices and supplier qualification. Stakeholders must monitor whether agency spec writers relax binder replacement ceilings or instead tighten performance testing regimes as recycled content thresholds rise.
Market Dynamics
Warm mix asphalt specifications are rewriting procurement protocols across OECD highway agencies, compressing the cost gap with conventional hot mix while foamed binder injection systems reach commercial scale. This thermal efficiency pivot is collapsing contractor upgrade cycles and reshaping equipment vendor order books.
Growth Catalysts
- EU Green Deal circular-economy mandates:Municipal highway departments in France and Germany now enforce minimum recycled content thresholds for public road contracts, locking in reclaimed asphalt pavement offtake.
- Sensor-guided thermal profiling:Real-time infrared monitoring of in-place recycling operations is extending pavement service life predictions and reducing performance variance on high-traffic corridors.
- Texas DOT binder replacement ratio expansion:The state transportation agency permits higher reclaimed binder substitution in surface course mixes, directly lifting regional reclaimed asphalt pavement consumption.
Market Restraints
- Rejuvenator chemical cost volatility:Bio-based and petroleum-derived binder restoration agents face feedstock price swings that compress blending margin at independent mix plants.
- Performance-graded mix approval bottlenecks:State DOT laboratory validation timelines for high-recycled-content designs extend project award cycles and freeze contractor inventory decisions.
- Portland cement concrete substitution:Full-depth reclamation with cement stabilization competes for the same distressed pavement feedstock in municipal maintenance budgets.
Strategic Opportunities
- India national highway expansion:The country's road building program under its infrastructure investment pipeline presents untapped reclaimed asphalt pavement specification adoption potential.
- Performance-based asphalt contracts:Agency procurement shifting from unit-price to lifecycle-cost models rewards contractors delivering higher recycled content with extended warranty terms.
- Cold recycling emulsion chemistry:Bitumen emulsion and foamed bitumen convergence for cold in-place recycling opens seasonal paving windows in temperate climates previously restricted to warm mix.
Industry Challenges
- Rheological testing skill scarcity:Binder restoration laboratories face shortages of technicians trained in dynamic shear rheometer and bending beam rheometer protocols for aged binder characterization.
- Legacy plant retrofit capex burdens:Drum mix and batch plant modifications for higher reclaimed asphalt pavement throughput require capital deployment that strains mid-tier contractor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Recycled Asphalt Market |
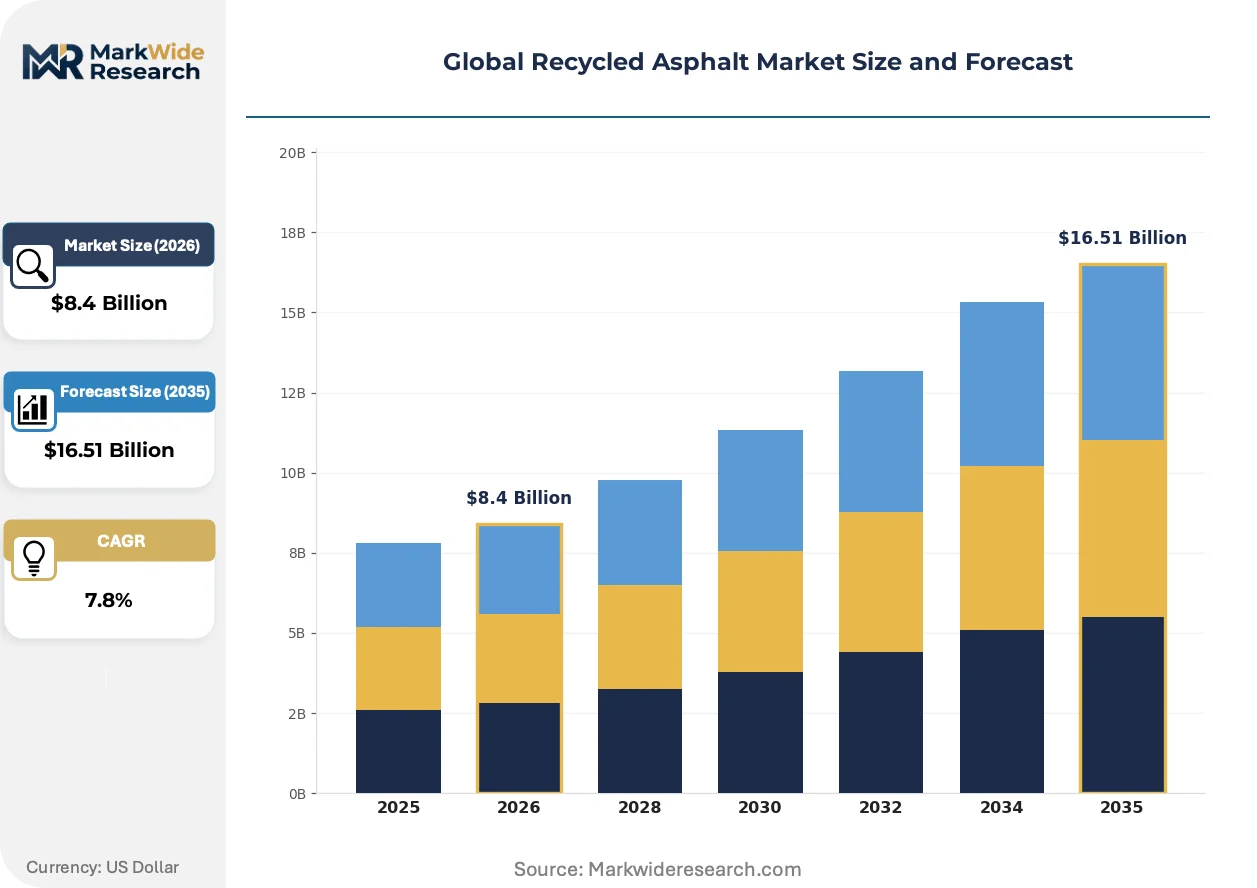
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reclaimed Asphalt Pavement, Hot Mix Asphalt, Cold Mix Asphalt, Warm Mix Asphalt Technology: Batch Plant, Drum Mix Plant, Molecular Rejuvenators, Polymer Modification Application: Highways, Urban Roads, Airport Runways, Parking Lots, Rural Roads End User: Construction Contractors, Road Maintenance Companies, Government Agencies, Private Developers |
| Companies Covered | Astec Industries, Colas, CRH, WIRTGEN Group, Eurovia, Granite Construction, CEMEX, Vulcan Materials Company, Bodean Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Recycled Asphalt Market Shifts & Advancements
Foamed asphalt production systems are crossing the threshold from pilot to mainstream deployment, altering the economics of in-place recycling relative to conventional mill-and-fill operations. This thermal process innovation is compressing project timelines and reshaping contractor equipment investment priorities.
Low-temperature asphalt production is collapsing the energy cost differential between recycled and virgin mix categories. Foamed bitumen and chemical additive systems now enable production at 30-40°C below conventional hot mix thresholds. European contractors led by French and German highway specialists are capturing extended paving season windows and reduced emissions profiles that satisfy EU Green Deal procurement scoring.
REACH compliance for rejuvenator formulations is tightening chemical supplier qualification requirements across European reclaimed asphalt pavement value chains. ECHA registration obligations for novel bio-based binder restoration agents are extending product commercialization timelines. Formulators are responding by pre-qualifying molecular rejuvenator candidates through parallel toxicology and performance testing tracks before full-scale field trials.
Lifecycle cost procurement models are displacing traditional unit-price bidding on federally aided highway projects. State DOTs in the US Sun Belt are weighting recycled content and extended pavement performance warranties in contractor selection scoring. Texas and California transportation agencies now rank reclaimed asphalt pavement utilization rates alongside conventional price submissions in competitive bid evaluations.
Global Recycled Asphalt Market Segmentation
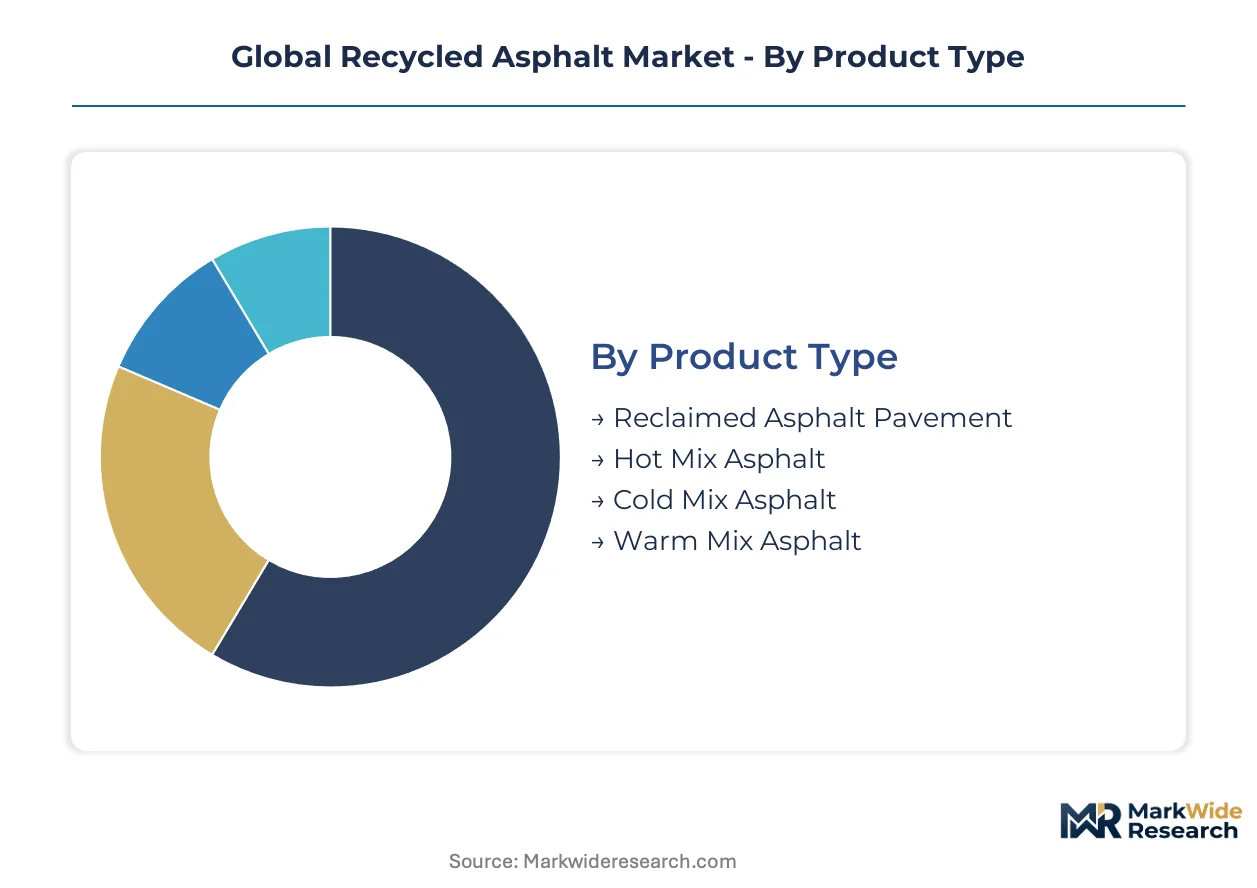
Segmentation in recycled asphalt reveals how technology maturity, procurement channels, and agency specifications fragment demand across distinct product categories. Each dimension carries implications for equipment investment, formulation chemistry, and contractor qualification requirements.
Product Type:
Mature hot mix formats dominate current procurement volumes while emerging low-temperature technologies reshape specification trajectories across OECD highway agencies.
- Hot Mix Asphalt:Conventional production at 150-180°C delivers established Marshall stability and rutting resistance metrics that state DOTs recognize without supplemental testing. Texas DOT and Caltrans specifications cement its position on federally aided projects where binder replacement ratios remain capped below performance thresholds.
- Warm Mix Asphalt:Foamed binder injection and chemical additive systems reduce production temperatures 30-40°C below conventional thresholds. French and German municipal highway departments under EU Green Deal mandates now weight warm mix procurement scoring, collapsing the cost gap with hot mix while extending paving seasons in temperate climates.
- Reclaimed Asphalt Pavement:Processed milled pavement combined with virgin aggregate and rejuvenators achieves 15-50% binder replacement depending on mix design. Government agencies seeking lifecycle cost reductions on highway rehabilitation contracts drive specification adoption.
- Cold Mix Asphalt:Bitumen emulsion formulations enable stockpiling and seasonal deployment without continuous heating infrastructure. Rural road maintenance programs with intermittent paving schedules concentrate demand in municipal budgets with limited hot plant access.
Hot Mix Asphalt handles the majority of throughput; Warm Mix Asphalt is gaining share fastest as EU procurement rules harden.
Technology:
Cost tier differentiation separates capital-intensive plant infrastructure from additive chemistry approaches that independent mix plants can adopt without equipment retrofit.
- Drum Mix Plant:Continuous production architecture accommodates higher reclaimed asphalt pavement feed rates through drum retrofit modifications. Astec Industries and comparable vendors capture North American contractor upgrade cycles as state DOTs relax binder replacement ceilings.
- Molecular Rejuvenators:Bio-based and petroleum-derived binder restoration agents reverse age-hardening in reclaimed binder streams. Eurovia's partnerships with French and United Kingdom public works authorities anchor European demand, though ECHA REACH compliance extends commercialization timelines for novel formulations.
- Batch Plant:Discontinuous production permits precise virgin-to-reclaimed aggregate proportioning for specialized surface course designs. Higher capital and operating costs limit penetration to large-scale highway contractors with dedicated quality control laboratories.
- Polymer Modification:Styrene-butadiene-styrene and similar elastomers enhance high-temperature performance grade in high-recycled-content mixes. Specification adoption concentrates in US Sun Belt states where rutting resistance requirements exceed standard binder grades.
Drum Mix Plant technology commands the largest installed base; Molecular Rejuvenators are climbing the fastest as REACH-compliant bio-based candidates reach field validation.
Application:
Volume concentration tracks federal funding allocation patterns, with performance-graded specifications most stringent on high-traffic corridors where lifecycle cost models dominate procurement.
- Highways:Federally aided interstate and arterial routes subject to FHWA performance-graded mix protocols. Texas DOT and Caltrans binder replacement ratio expansions directly lift reclaimed asphalt pavement consumption on these corridors.
- Urban Roads:Municipal street networks with utility conflict and access constraints favor in-place recycling methods over conventional mill-and-fill. Sensor-guided thermal profiling technologies reduce performance variance in high-traffic urban corridors.
- Airport Runways:Federal Aviation Administration specifications impose stringent stability and skid resistance requirements that historically constrained recycled content. Emerging field trials with enhanced rejuvenator chemistry test binder replacement feasibility.
- Parking Lots:Private developer and commercial property maintenance budgets prioritize initial cost over lifecycle performance. Cold mix and stockpile-friendly formulations capture seasonal repair contracts.
- Rural Roads:County and township maintenance programs with limited hot plant proximity rely on cold mix emulsion products. Cement stabilization and full-depth reclamation compete for the same distressed pavement feedstock.
Highways absorb the dominant share of reclaimed asphalt pavement tonnage; Urban Roads represent the steepest expansion trajectory as in-place recycling technologies displace conventional rehabilitation methods.
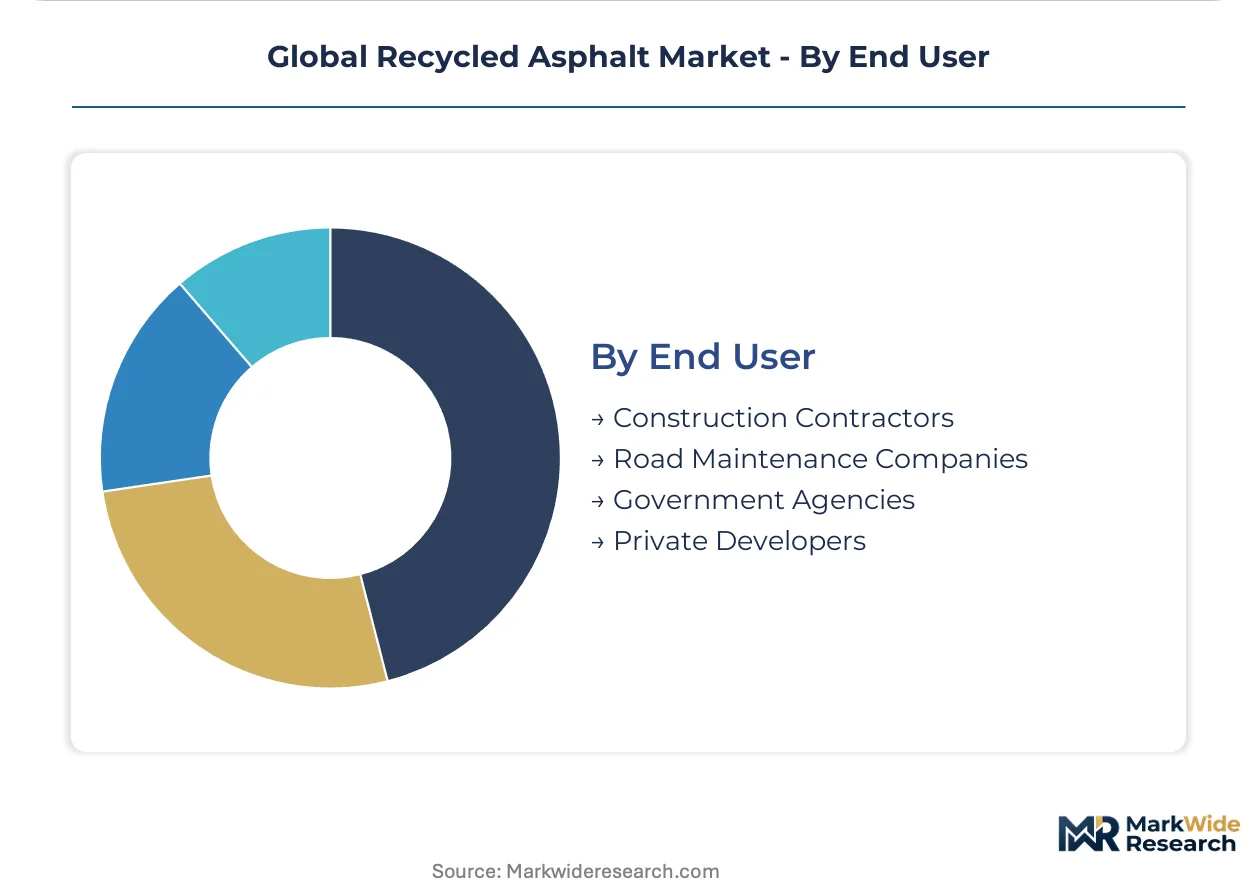
End User:
Customer type determines specification influence, with government agencies setting recycled content thresholds that cascade through contractor and developer procurement decisions.
- Government Agencies:Federal Highway Administration, state DOTs, and municipal highway departments establish binder replacement caps and performance-graded approval protocols. EU Green Deal circular-economy mandates and US Sun Belt specification expansions shape demand concentration.
- Construction Contractors:Tier-one highway specialists with in-house drum mix plants and quality control laboratories capture performance-based contract awards. Equipment vendor relationships and rejuvenator supplier partnerships lock in formulation choices.
- Road Maintenance Companies:Seasonal paving operations and municipal service contracts drive demand for cold mix and warm mix products with extended stockpile life. Mid-tier balance sheets strain under legacy plant retrofit capital requirements.
- Private Developers:Commercial and residential paving specifications typically defer to municipal standards with lower recycled content thresholds. Initial cost sensitivity limits adoption of premium rejuvenator formulations.
Government Agencies set the specification boundary conditions; Construction Contractors represent the fastest-moving segment as performance-based procurement models displace unit-price bidding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German rejuvenator chemistry exports supply French and British highway contractors under EU Green Deal procurement mandates. Cross-border reclaimed asphalt pavement trade flows concentrate in the Rhine corridor connecting Dutch terminals to Belgian and German mixing plants.
United States
Texas DOT specifications now permit higher binder replacement ratios in surface course mixes, lifting regional reclaimed asphalt pavement consumption. The Federal Highway Administration performance-graded protocols govern interstate highway contracts. Dallas-Fort Worth contractors deploy sensor-guided thermal profiling on high-traffic urban corridors.
Germany
Municipal highway departments enforce minimum recycled content thresholds under EU Green Deal circular-economy mandates. The KBA road construction standards integrate warm mix asphalt specifications into federal procurement rules. The Rhine-Main industrial cluster hosts drum mix plant retrofit specialists serving cross-border Dutch and Belgian markets.
France
Eurovia anchors European demand through molecular rejuvenator partnerships with public works authorities. ANSM and national green public procurement rules mandate recycled asphalt utilization in road maintenance budgets. The Lyon-Grenoble corridor concentrates warm mix technology validation trials for alpine climate conditions.
India
National highway expansion under the infrastructure investment pipeline presents reclaimed asphalt pavement specification adoption potential. The Ministry of Road Transport and Highways evaluates performance-based contracting models for federal aid projects. The Delhi-Mumbai Industrial Corridor contractors pilot cold recycling emulsion chemistry for seasonal paving windows.
United Kingdom
Highways England procurement scoring now weights recycled content in lifecycle cost models for arterial route maintenance. ECHA REACH compliance requirements govern rejuvenator chemical imports from continental suppliers. The Midlands quarrying belt integrates reclaimed asphalt pavement processing with aggregate terminal operations.
Global Recycled Asphalt Market Competitive Landscape
Channel-controlling players compete with product-specialist players across equipment, materials, and contracting verticals. The market structure consolidates around integrated construction-materials conglomerates with captive aggregate supply and independent mixing-plant operators dependent on merchant feedstock. Three archetypes dominate: full-line equipment vendors with retrofit capabilities, vertically integrated materials producers controlling quarry-to-pavement value chains, and specialized rejuvenator formulators with regulatory pre-qualification advantages. Competitive moves center on strategic partnerships between equipment vendors and state DOT specification committees, plus backward integration by contractors into aggregate quarrying to lock in reclaimed asphalt pavement quality.
Within the integrated-materials tier, CRH and CEMEX exemplify the quarry-to-pavement archetype with captive supply chain control over reclaimed binder streams. Astec Industries occupies a position as the equipment-specialist anchor, representing the drum mix plant retrofit category that captures North American contractor upgrade cycles. These three companies sit within distinct competitive vectors—materials integration, equipment technology, and formulation chemistry—without overlapping core capabilities.
| Leading Market Players |
|---|
| Astec Industries |
| Colas |
| CRH |
| WIRTGEN Group |
| Eurovia |
| Granite Construction |
| CEMEX |
| Vulcan Materials Company |
| Bodean Company |
| Others |
Supply & Pricing Matrix
The Rhine corridor freight network links Dutch reclaimed asphalt pavement terminals to Belgian and German mixing plants, with barge transport costs compressing blending margins at independent facilities while integrated quarry-to-pavement operators capture price premiums through captive feedstock quality.
Pricing Analysis
Cost-plus contracts with bitumen indexation dominate highway agency procurement, tying mix prices to Platts Singapore or Rotterdam marker fluctuations. Price differentiation rests on rejuvenator chemistry grade and state DOT performance-graded certification tier, with bio-based molecular formulations commanding premiums over petroleum-derived alternatives. Pricing pressure stems from rejuvenator feedstock volatility squeezing independent plant margins. Municipal maintenance budgets exhibit highest price sensitivity, while tier-one contractors with in-house drum plants absorb cost swings through vertical integration.
Supply Chain Analysis
Drum mix plant manufacturing concentrates in the United States, Germany, and China, with Astec Industries and WIRTGEN Group anchoring North American and European equipment supply. Reclaimed asphalt pavement processing draws from aged pavement stockpiles, virgin aggregate quarries, and bio-based rejuvenator feedstocks. Single-source vulnerability runs through specialized molecular rejuvenator formulators facing ECHA REACH registration delays. Distribution runs through asphalt terminal networks integrated with aggregate handling facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as EU Green Deal procurement mandates accelerate specification adoption beyond legacy hot mix baselines.
For Market Incumbents: Entrench specification influence through state DOT laboratory partnerships and drum mix plant retrofit financing programs. Cement stabilization technologies threaten reclaimed asphalt pavement feedstock access on municipal maintenance contracts; counter by locking multi-year reclaimed pavement offtake agreements with county highway departments. Backward integration into aggregate quarrying secures binder stream quality consistency. For New Entrants and Emerging Players: Build out cold recycling emulsion chemistry capabilities for India's national highway expansion, where performance-based contracting models remain underdeveloped and specification adoption lags OECD benchmarks. Target state DOTs relaxing binder replacement ceilings in the US Sun Belt. Lead with sensor-guided thermal profiling equipment-as-a-service models to bypass capital-intensive plant ownership barriers. For Investors and Strategic Acquirers: Rejuvenator-specialist formulators with ECHA REACH pre-qualification represent the most defensible acquisition archetype in a market tightening chemical supplier requirements. Long-term viability hinges on agency spec writers elevating recycled content thresholds above current performance-grade caps. Watch for Texas DOT and Caltrans laboratory validation timeline compression as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Drum Mix Plant Retrofit Program | Captures North American contractor upgrade cycles as state DOTs relax binder replacement ceilings. |
| Molecular Rejuvenator Partnership | Eurovia's French and United Kingdom public works alliances anchor EU Green Deal specification adoption. |
| Cold Recycling Emulsion Pilot | Opens seasonal paving windows in India's Delhi-Mumbai Industrial Corridor temperate zones. |
| Sensor-Guided Thermal Profiling Deployment | Dallas-Fort Worth contractors reduce performance variance on high-traffic urban corridors. |
| Aggregate Quarry Backward Integration | CRH and CEMEX lock reclaimed binder stream quality through captive supply chain control. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with asphalt plant managers, state DOT specification engineers, rejuvenator formulator R&D directors, and tier-one highway contractor procurement leads; and secondary validation through FHWA performance-graded mix protocols, EU Green Deal procurement rule filings, ECHA REACH registration databases, and customs trade data on bitumen emulsion imports. Bottom-up reclaimed asphalt pavement tonnage estimates triangulated against top-down highway construction expenditure forecasts.
Forecast inputs considered product type segmentation across hot mix, warm mix, and cold recycling formats; technology differentiation between drum mix plant infrastructure and molecular rejuvenator chemistry; and application concentration across highways, urban roads, and rural maintenance programs. CAGRs were derived from agency specification adoption curves and contractor equipment investment cycles. Industry-specific inputs included state DOT binder replacement ratio expansion timelines and EU national green public procurement threshold implementations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cement stabilization technology providers or bio-based rejuvenator startups would shift outcomes beyond modeled ranges. Quarterly review of Texas DOT and Caltrans laboratory validation backlogs, plus ECHA REACH novel substance registration progress, is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Germany Plastics Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
Non-Ferrous Scrap Recycling Market
Recycled Plastics
Plastic Lumber Market
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
Europe Recycled Plastics Market
Recycled Plastics
Polyvinyl Chloride (PVC) Market
Recycled Plastics
North America Plastic Recycling Market
Recycled Plastics
Plastic Color Sorter Market
Recycled Plastics
Asia-Pacific Plastic Waste Management Market
Recycled Plastics
Plastic Recycling Market
Recycled Plastics
Plastic Waste Management Market
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
North America Plastic Waste Management Market
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
Circular Plastic Feedstock Traceability Market