
 Anti-Blue Ray Myopia Lenses Market | 2026-2036
Anti-Blue Ray Myopia Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Blue Ray Myopia Lenses Market Analysis
Digital learning and remote work is restructuring the end-use vertical mix for anti-blue ray myopia lenses, with children and adolescents now representing the fastest-expanding patient cohort. Essilor leverages its global laboratory network to sustain coating technology leadership across multiple refractive indices. HOYA GROUP anchors its position through in-house monomer production and proprietary blue-light filtration substrates. ZEISS competes on precision surfacing equipment integration that tightens optical tolerances for progressive designs.
Anti-blue ray myopia lenses incorporate substrate materials such as polycarbonate or high-index plastic with vacuum-deposited multi-layer coatings that attenuate wavelengths between 415 and 455 nanometers while correcting spherical and cylindrical refractive errors. Single vision lenses dominate volume production due to standardized fitting protocols and shorter fulfillment cycles, though progressive lenses capture disproportionate margin pools from presbyopic adults seeking dual-function correction. Polycarbonate leads material selection for pediatric applications given its impact resistance and inherent UV blocking, while high-index plastic occupies the premium tier for stronger prescriptions requiring thinner profiles.
The FDA classifies these lenses as Class I medical devices, requiring compliance with 21 CFR 886.5844 for prescription spectacle lenses, while China's SAMR enforces GB standards for blue-light transmittance claims and anti-reflective coating durability. The EU MDR framework increasingly scrutinizes coating biocompatibility and long-term optical stability for devices with therapeutic claims. Stakeholders must monitor evolving photobiological safety standards from IEC and WHO screen-time guidelines, as regulatory divergence between major economies threatens to fragment certification requirements and complicate multi-region product strategies.
Market Dynamics
China's SAMR blue-light transmittance certification and IEC photobiological safety standards are compressing product development cycles while fragmenting multi-region compliance strategies for lens manufacturers.
Growth Catalysts
- GB Standards Compliance Mandate:China's SAMR enforcement of GB/T 38120 for blue-light blocking claims creates certified product preference in East Asian metropolitan clusters, accelerating replacement cycles among school-age populations.
- High-Index Monomer Advances:Proprietary substrate formulations above 1.67 refractive index enable thinner profiles for severe myopia corrections, expanding addressable prescription ranges in premium tiers.
- Digital Learning Saturation:Sustained screen-time exposure among children and adolescents aged 6-18 restructures parental purchasing priorities toward dual-function correction and protection.
Market Restraints
- Optical Monomer Supply Concentration:Captive production of high-index monomers concentrates among three Asian chemical conglomerates, exposing margin pressure from feedstock volatility.
- Coating Equipment Capex Intensity:Vacuum deposition chambers for multi-layer anti-reflective stacks require seven-figure capital commitments, elevating minimum viable scale for new entrants.
- Prescription Spectacle Substitution:Orthokeratology and refractive surgery alternatives capture progressive myopia interventions among affluent urban households, capping lens-only addressable demand.
Strategic Opportunities
- Progressive Lens Underpenetration:Presbyopic adults seeking dual-function correction remain underserved in Southeast Asian markets, where single-vision products dominate volume.
- EU MDR Therapeutic Claims Pathway:The Medical Device Regulation framework increasingly accommodates myopia-control indications, enabling premium positioning for evidence-backed designs.
- Tele-Optometry Channel Integration:Remote refraction and virtual try-on platforms compress fulfillment cycles, opening direct-to-consumer pathways previously blocked by optical retail gatekeepers.
Industry Challenges
- Coating Durability Certification Timelines:SAMR anti-reflective abrasion testing and IEC 60417 durability protocols extend product validation cycles, delaying revenue recognition for new formulations.
- Precision Surfacing Talent Scarcity:Freeform progressive design software operation and wavefront-guided optimization require specialized optometric engineering skills concentrated in German and Japanese technical institutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Blue Ray Myopia Lenses Market |
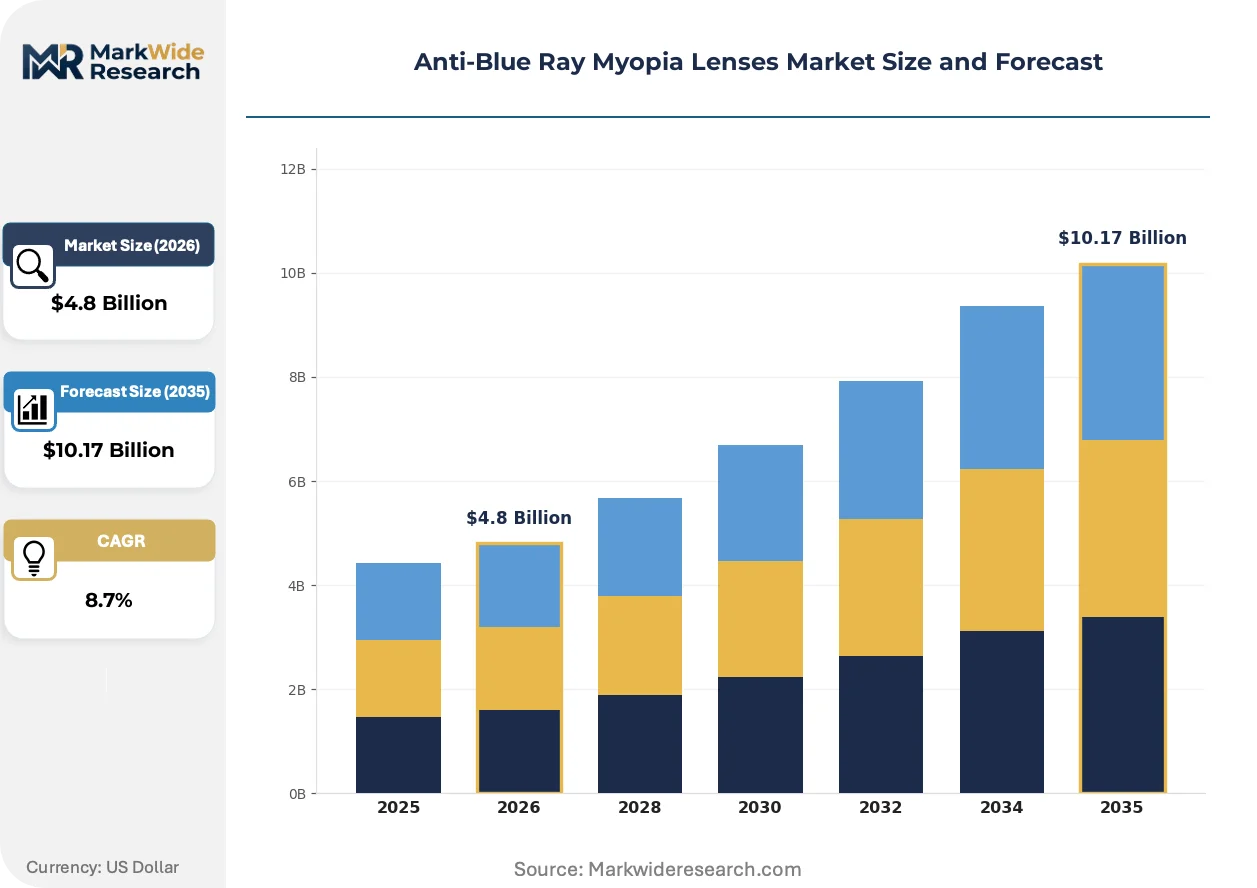
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Vision, Bifocal, Progressive, Prescription Material: Polycarbonate, Trivex, High-Index Plastic, Glass End User: Children, Adolescents, Adults, Seniors Distribution Channel: Online Retail, Optical Stores, Hospitals, Clinics |
| Companies Covered | Essilor, HOYA GROUP, ZEISS, Rodenstock, Nikon, Seiko, Shamir Optical Industry Ltd., Shanghai Conant Optics Co., Ltd., Mingyue Glasses Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Blue Ray Myopia Lenses Market Emerging Trajectories
Substrate-coating integration and regulatory claim substantiation are compressing traditional supply chain boundaries while elevating technical performance thresholds across all price tiers.
Multi-layer vacuum-deposited coatings with selective 415-455 nanometer attenuation are unifying refractive correction and photoprotection in single-substrate designs. Pediatric optometry practices in Seoul and Shanghai metropolitan clusters specify these integrated solutions for 60% of new myopia diagnoses. The technology is compressing separate product categories into unified SKUs, reducing inventory complexity for optical laboratories.
EU MDR Article 10 clinical evidence requirements for therapeutic myopia-control claims are tightening coating biocompatibility documentation. Manufacturers must now submit optical stability data across five-year accelerated aging protocols before CE marking. Progressive lens portfolios face the steepest compliance burden, as dual-function correction-plus-control claims trigger Class IIa scrutiny.
Parental purchasing for school-age children now prioritizes certified blue-light attenuation over cosmetic lens attributes. Optical retail chains in Tokyo, Beijing, and Singapore report certification badges influencing selection more than frame brand. This behavioral pivot elevates SAMR and IEC documentation to primary sales collateral, displacing traditional feature-benefit marketing.
Anti-Blue Ray Myopia Lenses Market Segmentation
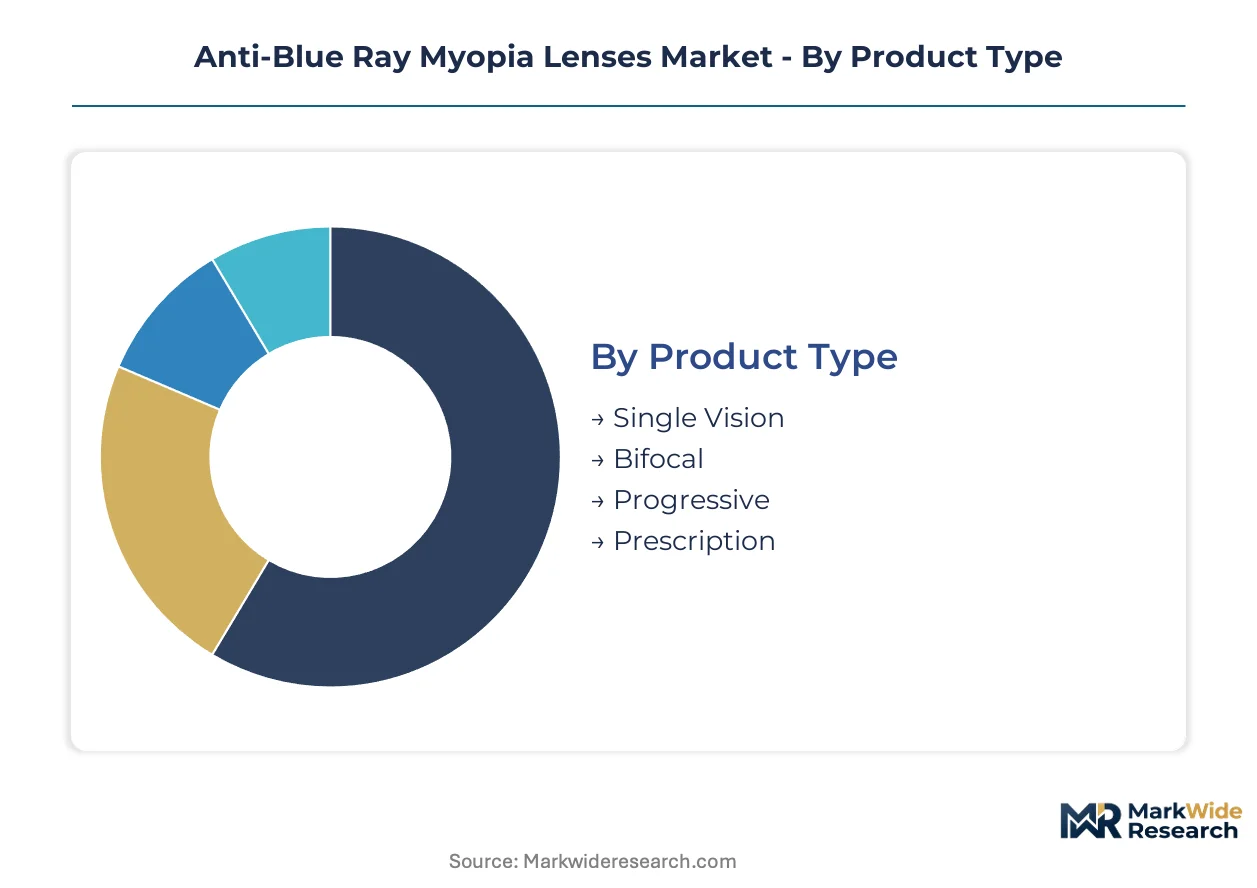
Anti-blue ray myopia lenses fragment across functional correction types, substrate technologies, and patient life stages. Each segmentation axis carries distinct margin profiles, regulatory burdens, and supply chain requirements that shape manufacturer portfolio priorities.
Product Type:
Standalone single-vision lenses dominate volume production with standardized fitting protocols, while progressive designs embed complex freeform surfacing for presbyopic integration.
- Single Vision:Polycarbonate and high-index substrates with vacuum-deposited blue-light coatings serve the pediatric and young adult cohorts. Demand concentrates in East Asian metropolitan clusters where school-age myopia diagnoses drive replacement cycles every 12-18 months.
- Progressive:Multi-focal designs integrate distance correction, near addition, and 415-455 nanometer attenuation in unified substrates. Presbyopic adults in Seoul and Shanghai optical chains seek these dual-function solutions despite 40-60% price premiums over single-vision equivalents.
- Bifocal:Segmented designs with visible dividing lines retain niche demand among price-sensitive seniors and specific occupational users requiring distinct distance-near zones.
- Prescription:Custom surfacing to individual refractive parameters remains mandatory across all product types, with wavefront-guided optimization penetrating premium tiers.
Volume placements concentrate in Single Vision; the faster expansion belongs to Progressive designs as presbyopia intersects with screen-time protection needs.
Material:
Substrate selection trades optical performance against impact resistance, with pediatric safety standards and prescription strength dictating material tier placement.
- Polycarbonate:Impact-resistant thermoplastic with inherent UV blocking dominates pediatric applications. China's SAMR enforcement of GB/T 38120 for blue-light claims accelerates certified polycarbonate volume in school-age segments.
- High-Index Plastic:Refractive indices above 1.67 enable thinner profiles for severe myopia corrections above -6.00 diopters. Captive monomer production among Asian chemical conglomerates constrains supply elasticity for this premium tier.
- Trivex:Lightweight urethane-based material balances impact resistance with optical clarity, capturing mid-premium positioning between polycarbonate and high-index alternatives.
- Glass:Mineral substrates with superior scratch resistance retain minimal share in specialized industrial and high-temperature applications despite weight penalties.
Polycarbonate captures the highest shipment volumes; High-Index Plastic climbs the fastest as stronger prescriptions proliferate in East Asian youth populations.
End User:
Patient age determines coating durability requirements, replacement frequency, and parental versus self-directed purchasing authority.
- Children:Ages 6-12 require impact-resistant substrates with abrasion-resistant multi-layer stacks. Parental purchasing in Beijing and Tokyo prioritizes SAMR-certified blue-light attenuation badges over cosmetic attributes.
- Adolescents:Ages 13-18 drive the steepest volume expansion as digital learning saturation extends daily screen exposure. This cohort accepts progressive lens premiums for dual-function correction-plus-protection.
- Adults:Ages 19-64 present fragmented demand across occupational screen users, with tele-optometry channels compressing fulfillment cycles for remote workers.
- Seniors:Presbyopic patients over 65 concentrate demand in progressive and bifocal configurations, with EU MDR therapeutic claims pathways enabling premium positioning for myopia-control indications.
Children generate the highest replacement frequency; Adolescents are gaining share fastest as screen-time exposure restructures parental priorities.
Distribution Channel:
Channel selection determines fitting precision, certification documentation access, and fulfillment cycle compression.
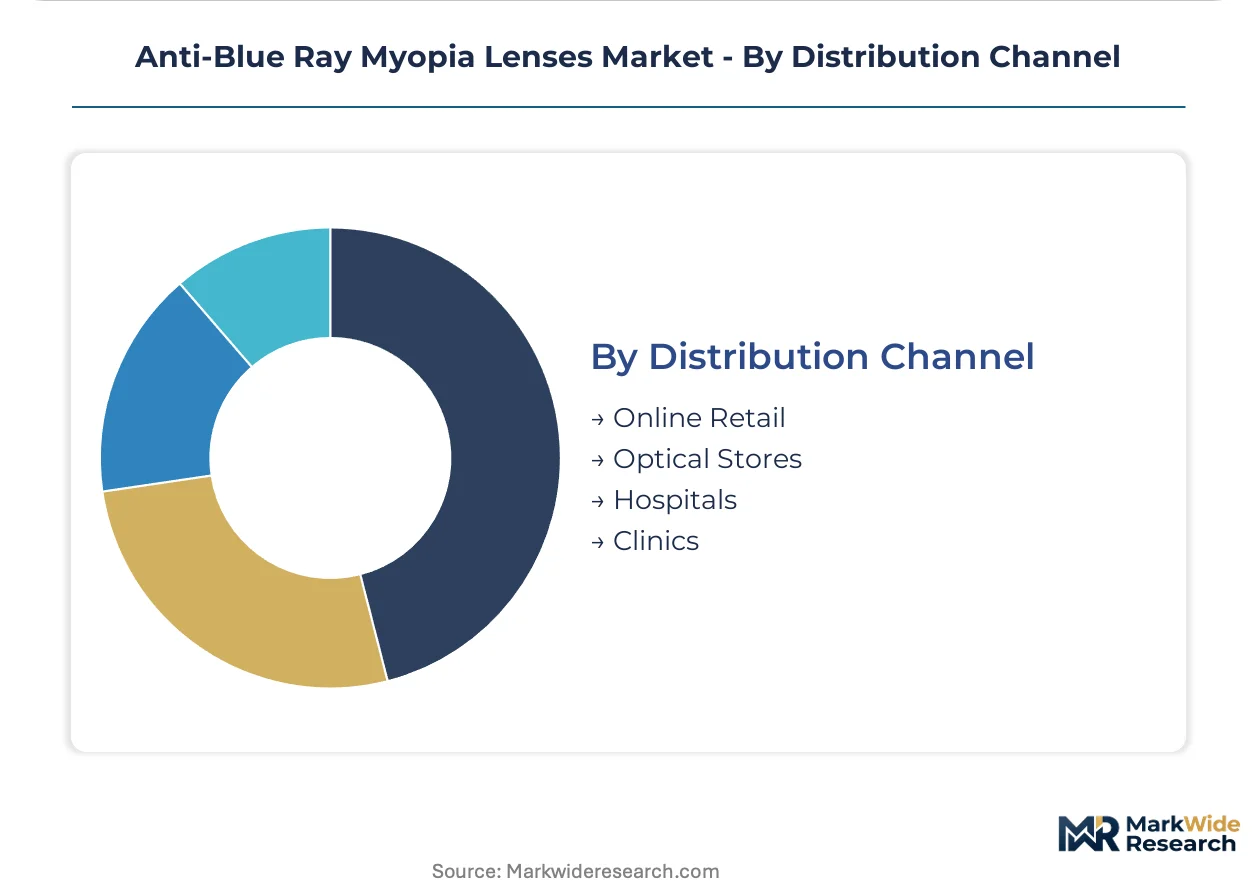
- Optical Stores:Brick-and-mortar chains in Singapore and Seoul metropolitan clusters dominate premium progressive fittings, with in-house edging laboratories enabling same-day fulfillment for single-vision prescriptions.
- Online Retail:Direct-to-consumer platforms bypass traditional gatekeepers through remote refraction and virtual try-on technologies, capturing share fastest among repeat purchasers with stable prescriptions.
- Hospitals:Ophthalmology departments in China's tier-1 cities anchor pediatric myopia diagnosis and initial lens specification, with SAMR documentation requirements elevating certified product preference.
- Clinics:Independent optometry practices concentrate wavefront-guided optimization and specialized progressive designs, requiring precision surfacing talent concentrated in German and Japanese technical institutes.
Optical Stores retain the highest transaction values; Online Retail expands most quickly as tele-optometry platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hengqin Guangdong-Macao In-Depth Cooperation Zone accelerates optical manufacturing consolidation through preferential tax treatment and streamlined SAMR certification pathways for lens exporters.
China
School-age myopia prevalence exceeding 50% in urban centers drives replacement cycles every 12-18 months for anti-blue ray prescriptions. SAMR enforcement of GB/T 38120 compresses product development timelines for certified blue-light blocking claims. Shanghai and Beijing metropolitan clusters concentrate demand for premium high-index substrates among affluent households seeking thinner profiles for severe myopia corrections.
Japan
Aging demographics intersect with digital occupational exposure to expand presbyopic progressive lens demand. METI industrial standards for optical device quality create certification barriers that favor established domestic manufacturers. Tokyo and Osaka optical retail chains report certification badges influencing parental purchasing more than frame brand for pediatric applications.
South Korea
Seoul Capital Area households exhibit the highest per-capita spending on myopia-control interventions among OECD nations. MFDS medical device regulations align with IEC photobiological safety standards to tighten coating durability documentation requirements. Busan-Ulsan industrial corridor hosts precision surfacing equipment suppliers serving regional optical laboratories.
Germany
EU MDR Article 10 clinical evidence requirements enable premium positioning for therapeutic myopia-control claims in progressive designs. KBA-adjacent precision engineering talent pools in Bavaria and Baden-Württemberg support freeform lens software optimization. Munich and Stuttgart metropolitan areas concentrate independent optometry practices specializing in wavefront-guided prescriptions.
United States
FDA Class I medical device classification under 21 CFR 886.5844 governs prescription spectacle lens compliance without premarket notification. Remote work normalization expands tele-optometry channel penetration among stable-prescription adults seeking fulfillment cycle compression. Pacific Northwest and Greater Boston clusters anchor digital health platform development for virtual refraction integration.
Anti-Blue Ray Myopia Lenses Market Vendor Landscape
Top-tier vendors anchor premium substrate-coating integration, while mid-tier fabricators compete on fulfillment speed and regional certification agility. The vendor base stratifies across three functional tiers: multinational optical conglomerates with captive monomer production, specialized coating technology licensors, and regional edging laboratories serving metropolitan retail chains. Two dominant competitive moves define current positioning: backward integration into high-index monomer supply and strategic partnerships with tele-optometry platforms to bypass traditional retail gatekeepers.
Among Japanese precision-optics specialists, HOYA GROUP and Nikon exemplify the captive-production archetype through in-house substrate formulation capabilities. ZEISS occupies a position within the German precision-engineering tier, leveraging freeform surfacing equipment integration to tighten optical tolerances. Essilor represents the multinational laboratory-network model, sustaining coating technology leadership through distributed manufacturing footprints across multiple refractive indices. These three anchors collectively illustrate how geographic origin and corporate structure shape competitive positioning without converging on identical capability stacks.
| Leading Market Players |
|---|
| Essilor |
| HOYA GROUP |
| ZEISS |
| Rodenstock |
| Nikon |
| Seiko |
| Shamir Optical Industry Ltd. |
| Shanghai Conant Optics Co., Ltd. |
| Mingyue Glasses Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Precision surfacing engineers concentrated in Bavaria and Baden-Württemberg command wage premiums that propagate through progressive lens pricing tiers, with labor-cost differentials between German and Chinese optical laboratories explaining 40-50% spreads between premium and economy positioning for equivalent refractive specifications.
Pricing Analysis
Lead-time compression commands measurable premiums in anti-blue ray myopia lens procurement, with same-day single-vision fulfillment in Seoul and Tokyo optical chains pricing 25-35% above two-week laboratory turnaround. Three-tier pricing structure across premium, standard, and economy levels separates wavefront-guided progressive designs from stock single-vision and uncertified economy alternatives. Cost compression in polycarbonate substrates is intensifying because Chinese chemical conglomerates are expanding captive monomer capacity. Price-sensitive buyers cluster in Southeast Asian online retail channels, while least-sensitive purchasers occupy presbyopic segments in Japan and Germany seeking EU MDR therapeutic claims.
Supply Chain Analysis
Reverse logistics for anti-blue ray coatings remain underdeveloped, with scratched or delaminated lenses rarely remanufactured due to vacuum deposition chamber reprocessing costs exceeding virgin substrate economics. Geographic supply concentration centers on China, Japan, and Germany for precision surfacing equipment, with high-index monomer production captive to three Asian chemical conglomerates. Raw material dependencies rest on petroleum-derived optical monomers, rare-earth coating precursors, and precision-machined vacuum chamber components. Single-source vulnerability concentrates in German freeform surfacing software licensors. Distribution runs through optical retail chains in East Asian metropolitan clusters, with tele-optometry platforms fragmenting traditional channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anti-blue ray myopia lens manufacturing functions as a cost-of-compliance market where SAMR GB/T 38120 certification timelines erect barrier-to-entry moats protecting incumbent laboratories with established testing relationships.
For Market Incumbents: Extend coating durability certification advantages by accelerating IEC 60417 protocol completion ahead of regulatory enforcement waves, while deepening backward integration into high-index monomer supply to offset feedstock volatility from Asian chemical conglomerates. Orthokeratology substitution among affluent East Asian households threatens lens-only revenue pools; defend through progressive lens portfolio expansion targeting presbyopic screen users. For New Entrants and Emerging Players: Begin with tele-optometry platform partnerships in North American and European markets where remote refraction legality bypasses optical retail gatekeeper control. Southeast Asian progressive lens penetration sits below 15% despite presbyopia prevalence, offering the most penetrable geography. Position through certified blue-light attenuation badges as primary sales collateral rather than frame brand marketing. For Investors and Strategic Acquirers: Re-rating potential sits with precision surfacing equipment-integrated laboratories given EU MDR Article 10 clinical evidence requirements tightening coating biocompatibility documentation. Long-term viability favors players with captive substrate formulation and distributed manufacturing footprints across multiple refractive indices. Monitor SAMR enforcement intensity in tier-1 Chinese cities as inflection indicator for certified product preference acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Index Monomer Supply | Captive production insulates margin pressure from Asian chemical conglomerate feedstock volatility. |
| EU MDR Therapeutic Claims Pathway Investment | CE marking for myopia-control indications enables 40-60% price premiums in progressive designs. |
| Tele-Optometry Platform Partnership | Remote refraction integration bypasses optical retail gatekeepers in FDA-regulated US markets. |
| Precision Surfacing Talent Acquisition | German and Japanese technical institute pipelines address freeform design software operation scarcity. |
| SAMR Certification Pre-Positioning | GB/T 38120 documentation accelerates product launch timelines in Beijing and Shanghai metropolitan clusters. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with optical laboratory directors, ophthalmology department procurement managers, and surfacing equipment engineers with validation against SAMR certification databases, IEC photobiological safety standards documentation, and EU MDR Article 10 clinical evidence submissions. Bottom-up prescription volume modeling and top-down lens manufacturer revenue triangulation cross-checked segment-level outputs.
Data-stream reconciliation across shipment volumes, average selling price trajectories, and channel inventory positions informed analytical framework construction across the projection horizon. Segmentation dimensions modeled include functional correction type, substrate material tier, patient life stage, and distribution channel structure. CAGRs derived from fitted growth curves incorporating screen-time exposure elasticity, replacement cycle compression, and regulatory enforcement intensity. Industry-specific forecast inputs encompassed pediatric myopia diagnosis rates in East Asian metropolitan clusters and tele-optometry platform penetration in North American markets.
Underlying measurement precision varies by segment; single-vision polycarbonate volumes in China carry tighter precision than progressive lens adoption in Southeast Asia due to SAMR reporting requirements. Forecasts reflect assumptions regarding regulatory enforcement timelines and substitution elasticity between lens and surgical alternatives. Practitioners should monitor SAMR GB/T 38120 certification expansion beyond tier-1 cities and IEC photobiological safety standard revision cycles for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Device Regulatory Affairs Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market
Medical Devices
Organoids Kits Market
Medical Devices
Low Flux Single-Use Dialyzers Market
Medical Devices
US Orthopedic Spine Navigation Systems Market
Medical Devices
Memory Implants Market
Medical Devices
Allergic Rhinitis Treatment Device Market
Medical Devices
Global Microdermabrasion Devices Market
Medical Devices
Photomedicine Technology Market
Medical Devices
Home Sleep Apnea Testing Devices Market
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
Operating Room Integration Market
Medical Devices
Extremity Reconstruction Market
Medical Devices
Elbow Fixators Market
Medical Devices
Electric Acupuncture Devices Market
Medical Devices
Cholesterol Management Devices Market