
 Global Implantable Cardioverter Defibrillators (ICD) Market | 2026-2036
Global Implantable Cardioverter Defibrillators (ICD) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Implantable Cardioverter Defibrillators (ICD) Market Foresight
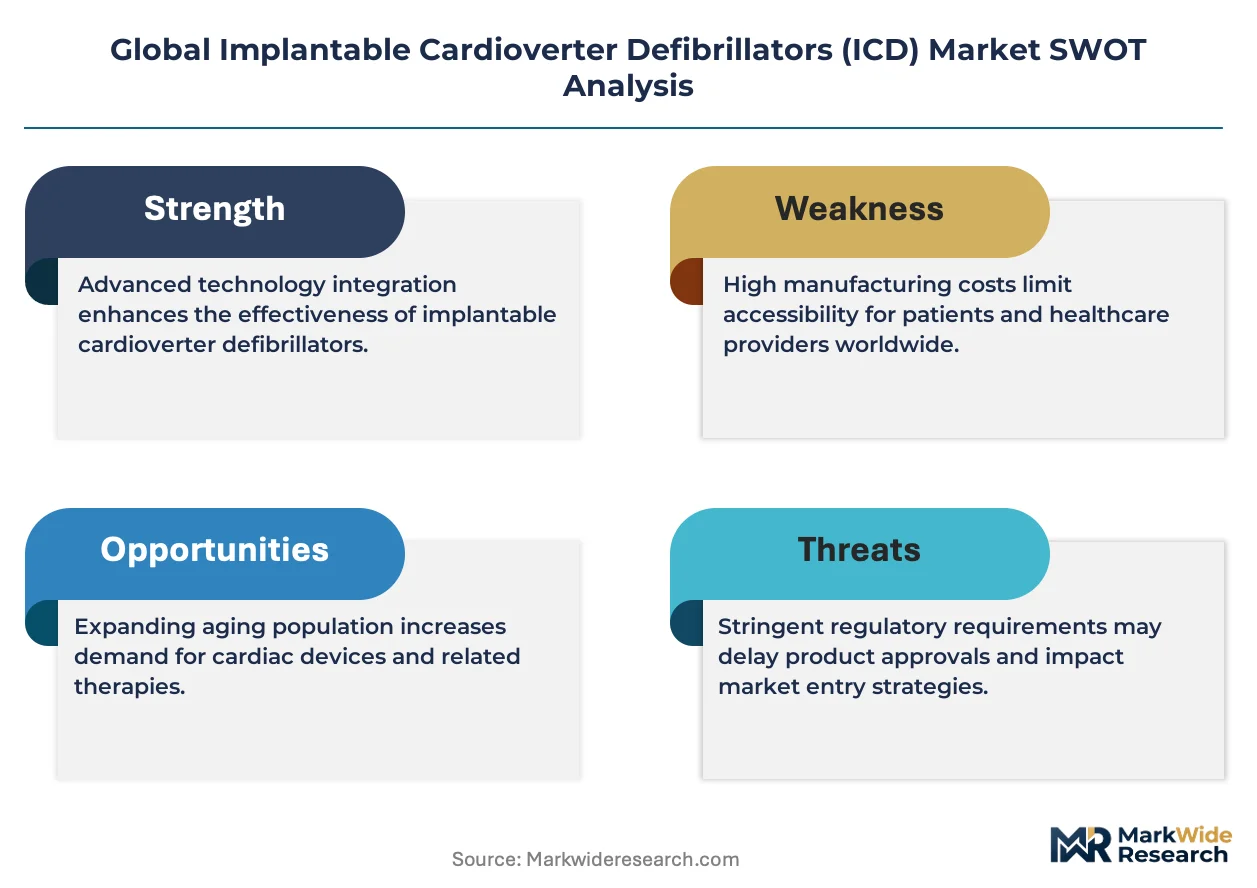
Magnetic resonance-conditional device certification is redrawing competitive boundaries in the implantable defibrillator sector. Medtronic leverages its integrated manufacturing footprint to sustain supply continuity across dual-chamber and leadless platforms. Abbott differentiates through catheter-based delivery systems that reduce implantation complexity in electrophysiology labs. Boston Scientific Corporation anchors its position with extended longevity batteries that lower replacement procedure frequency.
An implantable cardioverter defibrillator is a battery-powered pulse generator with transvenous or subcutaneous leads that monitors cardiac rhythm and delivers high-voltage shocks or antitachycardia pacing to terminate life-threatening ventricular arrhythmias. The device incorporates titanium housings, lithium silver vanadium oxide cells, and programmable detection algorithms with zone-based therapy stratification. Dual chamber ICD systems command premium positioning due to atrial-synchronized ventricular pacing capabilities and superior discrimination of supraventricular tachycardia. Subcutaneous ICD configurations are gaining structural momentum among younger patients with channelopathies who require long-term rhythm protection without transvenous lead complications. Wearable cardioverter defibrillator demand concentrates in temporary bridge-to-transplant or bridge-to-decision scenarios at heart failure units.
FDA premarket approval pathways and CE marking under the EU Medical Device Regulation impose stringent clinical evidence requirements for novel ICD platforms, extending development timelines but elevating barriers to commoditized competition. Japan's PMDA and China's NMPA maintain distinct approval frameworks that favor multinational sponsors with established local regulatory affairs infrastructure. Stakeholders must monitor evolving reimbursement thresholds for leadless and extravascular systems as health technology assessment bodies in Germany, France, and England recalibrate cost-effectiveness benchmarks.
Market Dynamics
Leadless ICD platforms are fragmenting the traditional transvenous device hierarchy by eliminating lead-related complications, forcing manufacturers to reallocate R&D expenditure toward catheter-based delivery systems and extravascular electrode configurations.
Growth Catalysts
- EU Medical Device Regulation:MDR's stricter clinical evidence requirements for legacy device recertification are accelerating hospital procurement of next-generation MRI-conditional systems to preempt compliance gaps.
- Electrophysiology lab expansion:Specialized cardiac centers in Germany and Japan are installing dedicated implant suites that streamline same-day discharge protocols for subcutaneous ICD recipients.
- Lithium silver vanadium oxide cells:Extended battery chemistry is compressing replacement intervals, reducing lifetime procedure burden for pediatric channelopathy patients.
Market Restraints
- Titanium housing supply:Aerospace and defense procurement is constraining medical-grade titanium sheet availability, elevating raw material cost volatility for device enclosures.
- Transvenous lead extraction:Specialized laser sheath and mechanical dilator supply concentrates among single-source vendors, creating procedural bottleneck risk for device upgrades.
- CE marking timeline:Notified body capacity constraints under MDR are extending leadless system certification cycles by 18-24 months versus pre-2021 benchmarks.
Strategic Opportunities
- India's CDSCO pathway:Streamlined import license frameworks for Class C cardiac devices are opening access to 1.4 billion patient population with underpenetrated electrophysiology infrastructure.
- Wearable-to-implantable bridge:Temporary cardioverter defibrillator demand at heart failure units is creating channel for longitudinal patient capture into permanent device ecosystems.
- Extravascular pacing convergence:Integration of subcutaneous ICD platforms with leadless pacemaker technology is enabling single-device rhythm management for brady-tachy syndrome patients.
Industry Challenges
- Electrophysiologist training bandwidth:Steep learning curves for extravascular implant techniques are constraining procedure throughput at mid-volume cardiac centers.
- Legacy device interoperability:Proprietary telemetry protocols between manufacturer-specific programmers and home monitoring systems are fragmenting remote patient management workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Implantable Cardioverter Defibrillators (ICD) Market |
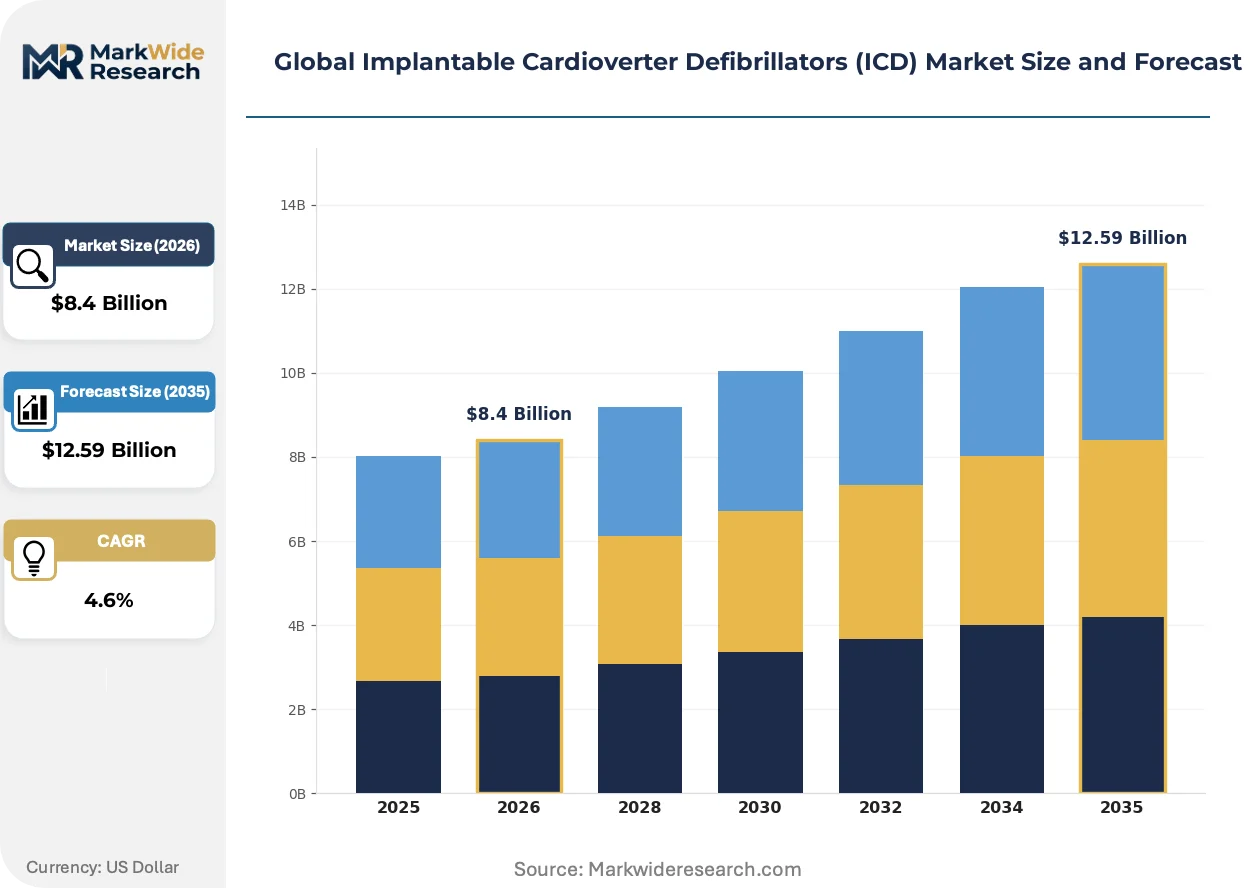
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Chamber ICD, Dual Chamber ICD, Subcutaneous ICD, Wearable Cardioverter Defibrillator Therapy Area: Ventricular Tachycardia, Atrial Fibrillation, Ventricular Fibrillation, Sudden Cardiac Arrest End User: Cardiology Clinics, Specialized Cardiac Centers, Electrophysiology Labs, Heart Failure Units Deployment: Hospital-Based Implantation, Ambulatory Care, Outpatient Surgery Centers, Cardiac Rehabilitation Facilities |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott, Biotronik, LivaNova, MicroPort Scientific Corporation, Koninklijke Philips, Cardiac Science Corporation, Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Implantable Cardioverter Defibrillators (ICD) Market Shifts & Advancements
Algorithmic detection refinement and battery chemistry advances are compressing the functional gap between premium dual-chamber systems and streamlined single-chamber alternatives, reshaping procurement tiering across hospital systems.
Subcutaneous ICD electrode technology is fragmenting the implantable defibrillator landscape by enabling entirely extravascular rhythm monitoring and therapy delivery. Younger patients with inherited channelopathies are adopting these systems at accelerating pace to avoid decades of transvenous lead burden. This shift is compressing addressable market scope for traditional dual-coil lead systems while expanding serviceable indications.
EU MDR's post-market surveillance requirements are mandating systematic device registry participation and real-world evidence generation for all active implantable cardiac devices. Manufacturers must now maintain continuous clinical follow-up infrastructure across distributed patient populations. Subcutaneous and leadless platforms face disproportionate compliance burden due to limited long-term outcome datasets.
Hospital procurement committees are consolidating cardiac rhythm management vendor relationships to capture volume-based service contracts spanning devices, programmers, and remote monitoring subscriptions. Integrated delivery networks in the United States are displacing fragmented point-of-purchase arrangements with multi-year enterprise agreements. Germany's university hospital clusters exhibit earliest concentration of this consolidated sourcing model.
Global Implantable Cardioverter Defibrillators (ICD) Market Segmentation
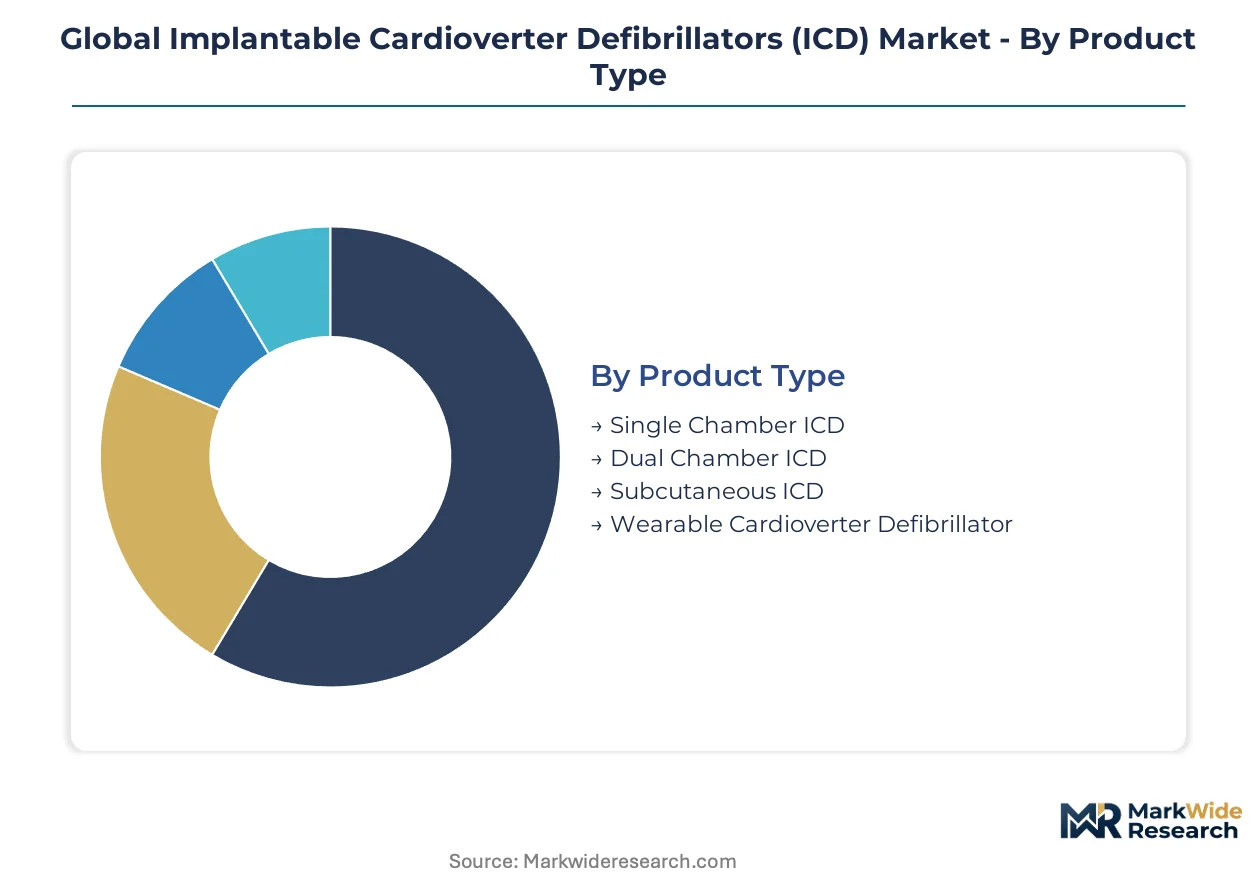
Device configuration and therapy specificity determine reimbursement tiers, regulatory approval pathways, and procurement committee evaluation criteria across cardiac rhythm management portfolios. Segmentation clarity enables stakeholders to align manufacturing capacity with procedure volume concentration in electrophysiology infrastructure.
Product Type:
FDA premarket approval timelines and CE marking under MDR create divergent market access trajectories across device configurations, with MRI-conditional certifications now table stakes for hospital procurement.
- Dual Chamber ICD:Titanium-encased pulse generator with atrial and ventricular sensing channels enables synchronized pacing and superior supraventricular tachycardia discrimination. Demand concentrates in Germany's university hospital clusters where electrophysiologists prioritize rhythm discrimination accuracy for complex arrhythmia patients. PMDA approval requirements in Japan favor established dual-chamber platforms with extensive Japanese clinical datasets.
- Subcutaneous ICD:Entirely extravascular system with subcutaneous electrode array eliminates transvenous lead complications. Adoption accelerates among pediatric channelopathy patients in United States specialized centers seeking decades of therapy without lead extraction risks. Battery longevity limitations constrain replacement intervals versus transvenous alternatives.
- Single Chamber ICD:Streamlined ventricular-only sensing reduces implantation complexity and device cost for standard indications.
- Wearable Cardioverter Defibrillator:External garment-based system provides temporary bridge-to-decision coverage at heart failure units awaiting transplant eligibility determination.
Dual Chamber ICD handles the majority of throughput; Subcutaneous ICD is expanding most quickly on share.
Therapy Area:
Clinical indication specificity drives device programming requirements, detection algorithm sophistication, and electrophysiologist training investment.
- Ventricular Fibrillation:Chaotic electrical activity requiring immediate high-voltage defibrillation represents the core lifesaving indication for all ICD platforms. Procedure volume concentrates in United States emergency cardiac centers with 24-hour electrophysiology coverage. Detection algorithm sensitivity thresholds directly impact battery consumption and longevity.
- Sudden Cardiac Arrest:Catastrophic circulatory collapse event creates preventive implant demand among high-risk post-infarction patients. Germany's statutory health insurance funds mandate risk stratification protocols before reimbursement authorization. Secondary prevention indications dominate volume in established markets.
- Ventricular Tachycardia:Organized rapid ventricular rhythm amenable to antitachycardia pacing reduces shock burden.
- Atrial Fibrillation:Supraventricular arrhythmia with stroke risk drives dual-chamber device preference for combined rhythm management.
Ventricular Fibrillation anchors installed base volumes; Sudden Cardiac Arrest prevention is gaining share fastest in prophylactic implant segments.
End User:
Facility specialization level determines procedure complexity handled, reimbursement capture rates, and device portfolio breadth stocked.
- Electrophysiology Labs:Dedicated catheterization suites with 3D mapping integration handle complex device implants and lead extractions. Japan's expanding specialized cardiac center network prioritizes same-day discharge protocols for subcutaneous ICD recipients. Capital equipment requirements create high barriers to entry for new facility establishment.
- Specialized Cardiac Centers:Comprehensive rhythm management programs combine implantation, follow-up, and remote monitoring services. United States integrated delivery networks consolidate purchasing across multi-site cardiac service lines. Volume-based contracting favors centers with procedure throughput above institutional thresholds.
- Cardiology Clinics:Outpatient-focused practices handle routine device follow-up and generator replacements.
- Heart Failure Units:Bridge-to-transplant centers generate temporary wearable defibrillator demand with longitudinal patient capture potential.
Electrophysiology Labs command premium procedure margins; Specialized Cardiac Centers are scaling fastest through network consolidation.
Deployment:
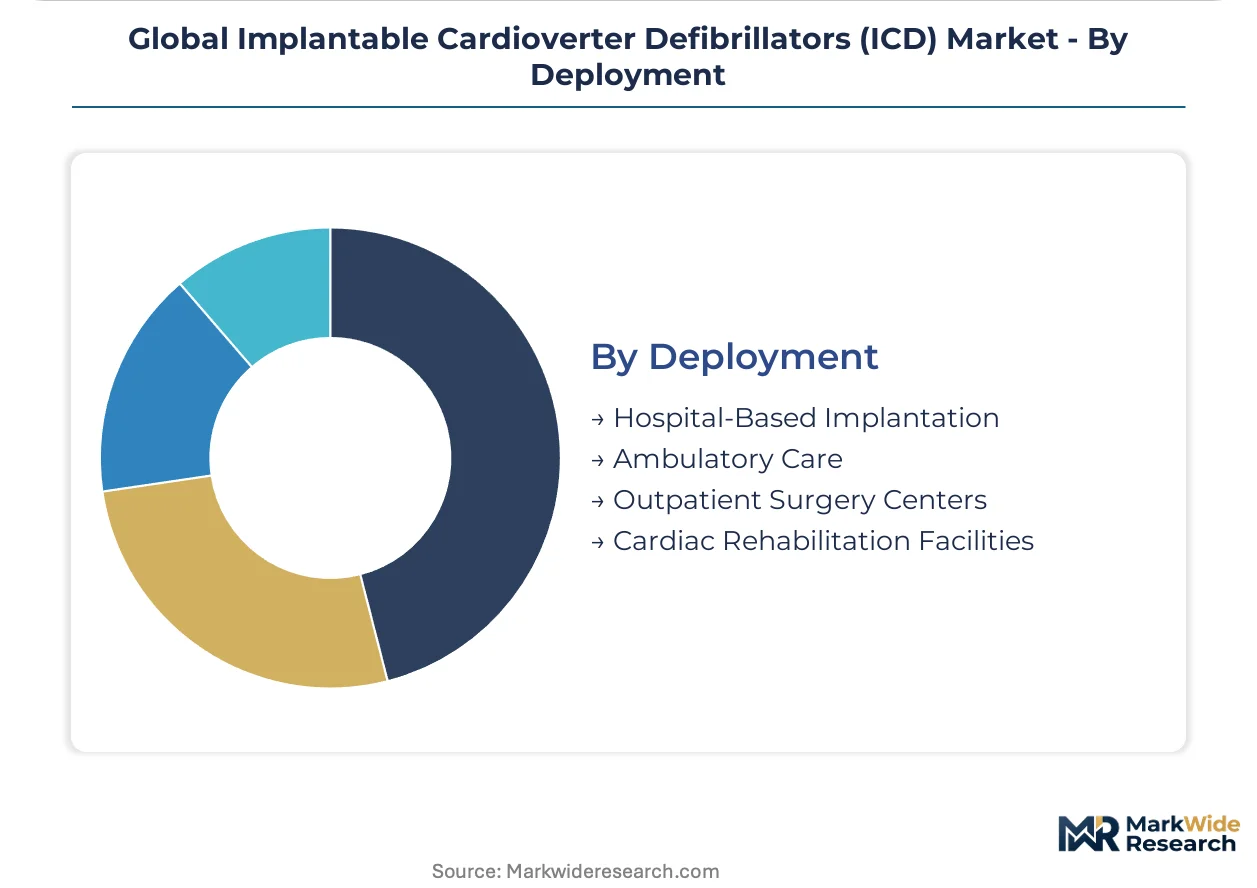
Care setting determines regulatory oversight intensity, reimbursement coding specificity, and patient acuity thresholds.
- Hospital-Based Implantation:Inpatient surgical suites with cardiac surgery backup manage high-risk patients and complex lead revisions. Germany's diagnosis-related group reimbursement system incentivizes same-admission discharge for uncomplicated subcutaneous ICD procedures. Overnight observation requirements vary by national healthcare system.
- Ambulatory Care:Standalone surgical facilities with streamlined protocols target low-risk primary implants. United States Medicare site-of-service differentials create pricing pressure on hospital outpatient departments. Accreditation requirements for conscious sedation administration constrain facility eligibility.
- Outpatient Surgery Centers:Focused procedural environments optimize throughput for generator replacements.
- Cardiac Rehabilitation Facilities:Post-implant recovery sites manage exercise tolerance testing and device parameter optimization.
Hospital-Based Implantation retains the dominant share; Ambulatory Care is climbing the fastest as payers push site-of-service migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade titanium sourcing and electrophysiology infrastructure investment concentrate device manufacturing and procedural capacity across five national markets. FDA, CE marking under MDR, and PMDA frameworks create divergent compliance burdens that reshape competitive positioning in each geography.
United States
Specialized cardiac centers in Cleveland Clinic and Mayo Clinic networks drive subcutaneous ICD adoption among pediatric channelopathy patients. FDA premarket approval pathways for leadless systems extend development timelines but elevate barriers to entry. Electrophysiology lab expansion concentrates in Texas Medical Center and Boston's Longwood Medical Area.
Germany
University hospital clusters in Berlin and Munich prioritize MRI-conditional dual-chamber systems for complex arrhythmia discrimination. Statutory health insurance funds mandate risk stratification protocols before sudden cardiac arrest prevention reimbursement. Same-day discharge protocols for subcutaneous ICD recipients streamline throughput in Heidelberg and Hamburg facilities.
Japan
PMDA approval requirements favor established platforms with extensive domestic clinical datasets, constraining novel leadless system entry. Specialized cardiac center networks in Tokyo and Osaka expand implant suite capacity for extravascular configurations. METI funding for electrophysiology infrastructure accelerates procedural volume growth in Kansai region.
China
NMPA maintains distinct approval frameworks that favor multinational sponsors with established local regulatory affairs infrastructure in Shanghai and Beijing. Domestic manufacturers in Shenzhen and Suzhou develop cost-optimized single-chamber alternatives for tier-two hospital penetration. Reimbursement recalibration for advanced rhythm management therapies proceeds province-by-province.
India
CDSCO streamlined import license frameworks for Class C cardiac devices open access to underpenetrated electrophysiology infrastructure. Mumbai and Delhi cardiac centers install dedicated implant suites targeting bridge-to-transplant wearable defibrillator demand. Pediatric channelopathy diagnosis rates remain low outside major metropolitan hospital networks.
Global Implantable Cardioverter Defibrillators (ICD) Market Competitive Landscape
Concentration sits with diversified cardiovascular device conglomerates possessing integrated manufacturing footprints and established regulatory affairs infrastructure across FDA, CE marking, and PMDA jurisdictions. The vendor base structures across three tiers: premium dual-chamber and leadless platform specialists, mid-market single-chamber standard bearers, and regional cost-optimized alternatives. Dominant competitive moves include strategic partnerships for catheter-based delivery system development and geographic expansion into India's CDSCO pathway.
Among diversified cardiovascular technology conglomerates, Medtronic, Boston Scientific Corporation, and Abbott exemplify archetypes spanning integrated manufacturing scale, extended longevity battery specialization, and catheter-based delivery system innovation respectively. Medtronic anchors supply continuity across dual-chamber and leadless platforms. Boston Scientific Corporation occupies a position emphasizing battery chemistry advances that compress replacement intervals. Abbott sits within the catheter-based delivery system specialization tier, reducing implantation complexity in electrophysiology labs.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| Biotronik |
| LivaNova |
| MicroPort Scientific Corporation |
| Koninklijke Philips |
| Cardiac Science Corporation |
| Asahi Kasei Corporation |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four-month CE marking cycles under EU MDR compress inventory buffers for leadless system manufacturers while concentrating pricing power among sponsors with established notified body relationships and parallel FDA submission tracks.
Pricing Analysis
CE marking under EU MDR dictates the pricing tier structure across implantable defibrillator portfolios. MRI-conditional dual-chamber systems command premium positioning against standard single-chamber alternatives due to extended clinical evidence requirements and superior rhythm discrimination capabilities. Price differentiation hinges on battery longevity specifications and atrial sensing channel sophistication. Cost compression in subcutaneous ICD tiers is intensifying because titanium housing procurement competes with aerospace and defense demand. Heart failure units exhibit highest price sensitivity due to bridge-to-transplant reimbursement constraints, while specialized cardiac centers prioritize clinical performance over acquisition cost.
Supply Chain Analysis
Medical-grade titanium sheet inventory cycles of ninety to one hundred twenty days expose device enclosures to aerospace procurement volatility and spot-market price swings. Manufacturing concentrates in the United States, Germany, and Switzerland for pulse generator assembly, with lithium silver vanadium oxide cell production anchored in Japan and South Korea. Raw material dependencies span titanium sponge, medical-grade lithium compounds, and biocompatible polymers for catheter-based delivery systems. Single-source vulnerability concentrates in laser sheath supply for transvenous lead extraction procedures. Distribution runs through integrated delivery networks in the United States and university hospital clusters in Germany, displacing fragmented point-of-purchase arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The implantable defibrillator market enters a cyclical recovery phase as electrophysiology lab expansion and leadless platform maturation converge, with procedural volume growth in specialized cardiac centers providing the cyclical anchor.
For Market Incumbents: Secure catheter-based delivery system capabilities through targeted R&D allocation or strategic technology access agreements to defend against leadless platform fragmentation. Lock in multi-year titanium supply contracts with aerospace-grade specification waivers to mitigate raw material cost volatility. Fortify notified body relationships across EU MDR jurisdictions to compress certification cycle differentials versus emerging competitors. For New Entrants and Emerging Players: Lead with India's CDSCO pathway for Class C cardiac device import licenses, targeting Mumbai and Delhi cardiac centers with bridge-to-transplant wearable defibrillator offerings. Exploit underpenetrated pediatric channelopathy diagnosis networks outside major metropolitan clusters. Position through electrophysiology infrastructure partnerships rather than direct hospital sales force buildout. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified cardiovascular conglomerates seeking to rationalize non-core rhythm management assets amid portfolio consolidation pressures. Five-to-ten-year viability hinges on extravascular pacing convergence capabilities and remote monitoring platform integration. Watch FDA premarket approval pathway timelines for leadless systems as inflection indicator for competitive repositioning velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Leadless Platforms | Premarket approval pathways elevate barriers to commoditized competition in the United States. |
| CE Marking Pathway Under EU MDR | Stricter clinical evidence requirements accelerate hospital procurement of MRI-conditional systems. |
| Hospital System Partnership | Integrated delivery networks consolidate cardiac rhythm management vendor relationships. |
| Software Companion Development | Proprietary telemetry protocols fragment remote patient management workflows. |
| Reimbursement Strategy | Germany's statutory health insurance funds mandate risk stratification protocols before authorization. |
Research Methodology
A standing panel of electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA filings, CE marking databases under EU MDR, hospital procurement registries, and CMS Medicare reimbursement data. Primary interviews with regulatory affairs specialists at multinational sponsors and notified body representatives in Germany and the Netherlands anchored market access timeline assessments. Bottom-up procedure volume modeling across electrophysiology labs and top-down manufacturer shipment analysis triangulated market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by device configuration, therapy indication, end-user facility type, and deployment setting. CAGRs derived from procedural volume trajectories in specialized cardiac centers and replacement cycle compression from battery chemistry advances. Industry-specific forecast inputs incorporated PMDA approval timeline differentials and India's CDSCO import license processing rates.
The analysis sits within stated boundaries; outcomes outside sustained electrophysiology infrastructure investment or stable titanium supply conditions would require recalibration. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory pathway continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Infant Radiant Warmer Market
Medical Devices
Hospital and Pre-Hospital External Defibrillator Market
Medical Devices
Global Portable Oxygen Concentrators Market
Medical Devices
Intracranial Pressure Monitors Market
Medical Devices
Meniscus Repair Systems Market
Medical Devices
Oxygen Conservers Market
Medical Devices
Veterinary Anesthesia Equipment Market
Medical Devices
Global Automated Dispensing Machines Market
Medical Devices
Cervical Retractors Market
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
Internal Trauma Fixation Device Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
North America Invisible Orthodontics Market
Medical Devices
Global Smart Implants Market
Medical Devices
Italy Ultrasound Devices Market
Medical Devices
High Flow Ventilators Market